
 Plastic Toy Storage Market | 2026-2036
Plastic Toy Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Toy Storage Market Insights
Injection molding automation is tilting production economics toward high-volume, precision-tooled bin architectures. Sterilite Corporation leverages captive resin compounding to sustain margin control across its stackable box lines. Rubbermaid anchors commercial-grade durability standards that dominate the daycare and institutional procurement channel. Inter IKEA Systems B.V. differentiates through flat-pack logistics that compress last-mile distribution costs for modular bin systems.
Plastic toy storage denotes injection-molded or thermoformed containment systems fabricated from polypropylene, polystyrene, or high-density polyethylene, typically ranging from 15 to 75 liters in capacity, engineered to organize, protect, and transport play items in residential or institutional settings. Stackable boxes command the largest volume share due to closet and under-bed compatibility, while modular bins capture the fastest growth trajectory as open-concept playroom designs proliferate in new residential construction. Drawer organizers retain stable replacement demand but face margin compression from private-label competition at home improvement centers.
The EPA regulates phthalate thresholds under the Consumer Product Safety Improvement Act, compelling reformulation toward polypropylene and high-density polyethylene resins. The FDA's indirect food contact guidelines for storage materials used in educational lunch programs create additional compliance layers for institutional suppliers. ASTM F963 toy safety standards, enforced by the CPSC, mandate structural integrity testing that elevates tooling investments for chest box and rolling container categories. Stakeholders must monitor state-level extended producer responsibility legislation as it migrates from packaging toward durable plastic goods.
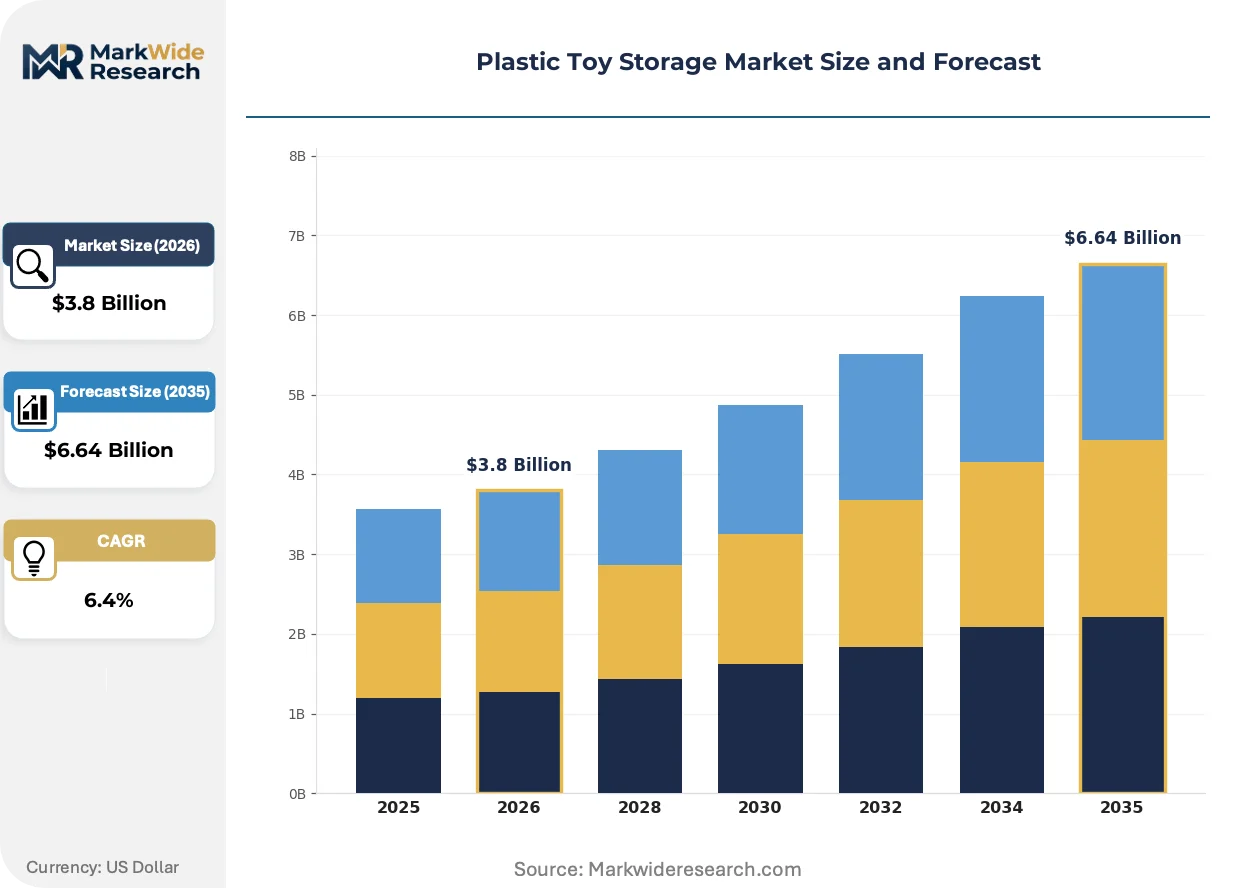
Market Dynamics
Injection molding automation is compressing unit economics for precision-tooled bin architectures while EPA phthalate thresholds force resin reformulation toward polypropylene alternatives. Daycare procurement is consolidating around modular systems as enrollment climbs.
Growth Catalysts
- Modular storage systems:Daycare centers are expanding procurement of stackable configurations as enrollment rises, prioritizing space efficiency and sanitization protocols.
- REACH compliance migration:European manufacturers are accelerating polypropylene adoption to meet evolving substance restrictions, creating competitive differentiation in export markets.
- Suburban household formation:United States markets with elevated birth rates and multi-child households are driving replacement cycles for under-bed and closet-compatible units.
Market Restraints
- Petrochemical input volatility:Polypropylene and high-density polyethylene resin costs fluctuate with crude oil benchmarks, squeezing margin stability for injection molders.
- Tooling capital intensity:ASTM F963 structural integrity mandates for chest boxes and rolling containers require six-figure mold investments that deter mid-scale entrants.
- Extended producer responsibility migration:State-level EPR legislation moving from packaging toward durable goods threatens end-of-life cost absorption for manufacturers.
Strategic Opportunities
- Flat-pack logistics innovation:Compression of last-mile distribution costs through knock-down modular designs opens direct-to-consumer channels previously dominated by retail intermediaries.
- Institutional lunch program integration:FDA indirect food contact guidelines create compliance-layer differentiation for suppliers serving educational settings with dual-use storage.
- Open-concept residential construction:New home builds featuring dedicated playroom spaces favor visible modular bin systems over concealed closet storage.
Industry Challenges
- Multi-jurisdiction compliance layering:Manufacturers must reconcile EPA phthalate limits, FDA food contact standards, and ASTM structural requirements across product lines.
- Automation workforce transition:Injection molding facilities require technicians capable of programming and maintaining robotic cell integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Toy Storage Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
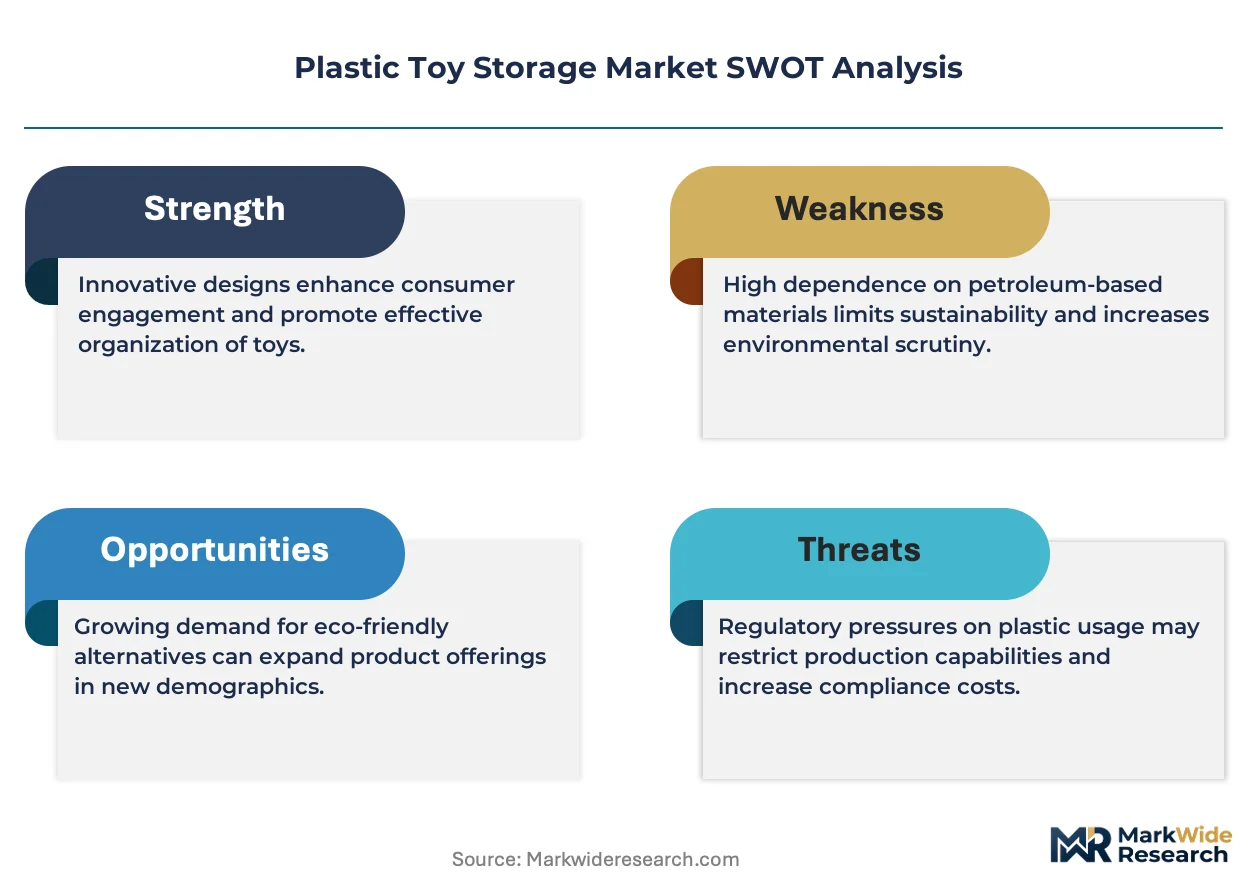
| Segmentation | Product Type: Stackable Boxes, Drawer Organizers, Chest Boxes, Rolling Containers, Modular Bins Material: Polypropylene, Polystyrene, High-Density Polyethylene, Acrylonitrile Butadiene Styrene, Polycarbonate Application: Residential Playrooms, Educational Institutions, Daycare Centers, Toy Retailers, Hobbyist Workshops Distribution Channel: Online Retailers, Specialty Stores, Supermarkets, Toy Chain Stores, Home Improvement Centers |
| Companies Covered | Sterilite Corporation, Rubbermaid, Inter IKEA Systems B.V., Honey-Can-Do International, LLC, Seville Classics, Inc., South Shore Industries, Badger Basket, KidKraft, Crate & Barrel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Toy Storage Market Trends and Innovations
Digital design tools and automated production systems are compressing development cycles for specialized storage configurations. Three convergent developments are restructuring competitive positioning.
Thin-wall injection molding with in-mold labeling is rendering obsolete conventional decorated surfaces that peel or chip in institutional sanitization cycles. Daycare procurement teams are specifying these finishes for durability compliance. The technology is compressing price premiums previously commanded by premium-brand surface treatments.
REACH substance restrictions are accelerating substitution of legacy plasticizers in vinyl-based storage alternatives. European manufacturers face reformulation deadlines that North American exporters must match for market access. The regulatory friction is elevating polypropylene's cost-competitiveness against incumbent materials.
Direct-to-institution procurement platforms are displacing traditional distributor relationships for volume daycare and school district accounts. Digital catalog interfaces with specification filtering are capturing specification authority previously held by regional supply houses. The channel shift is most visible in United States suburban districts with consolidated purchasing authority.
Plastic Toy Storage Market Segmentation
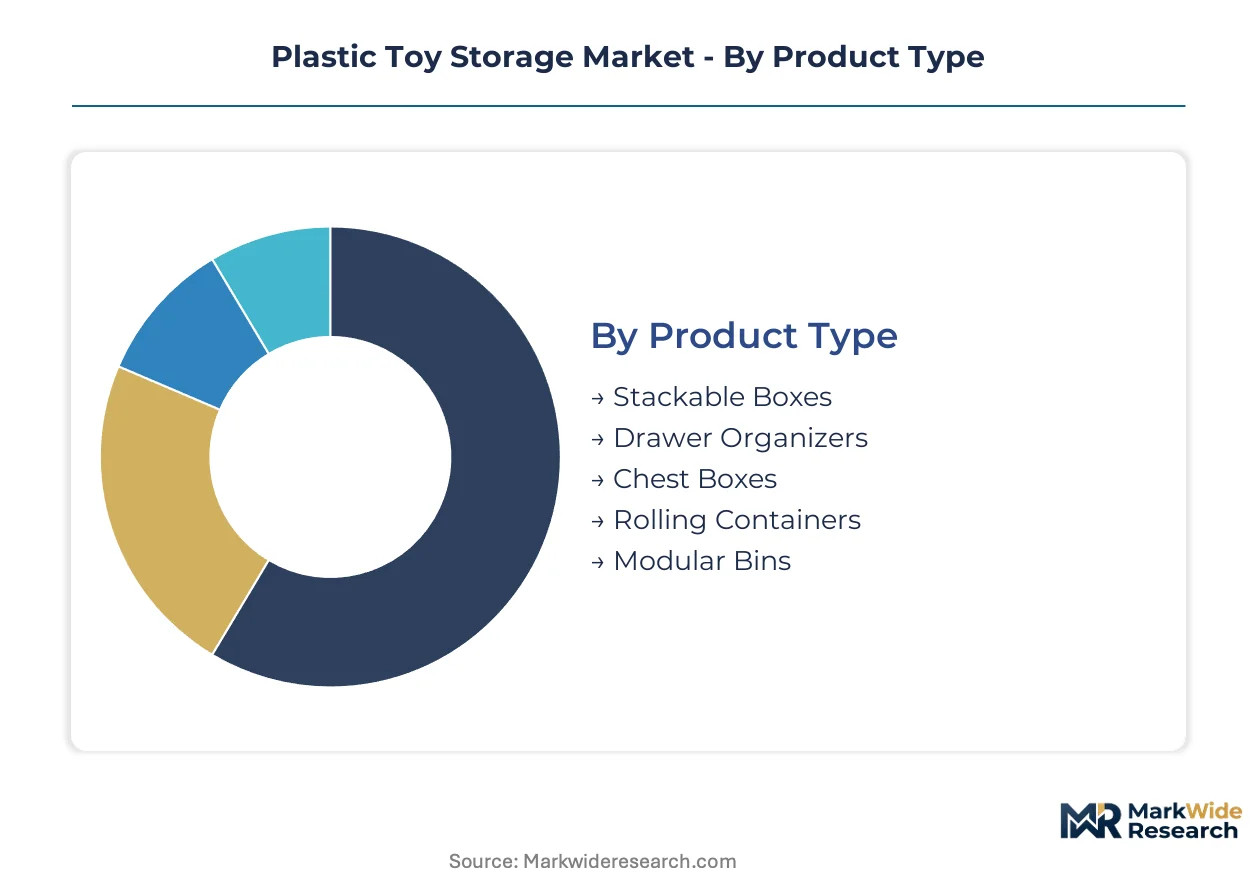
Segmentation in plastic toy storage reveals divergent durability requirements and procurement rhythms across residential and institutional buyers. Material selection and product architecture determine replacement cycles, with some configurations turning over annually while others persist for years.
Product Type:
Replacement cycles vary dramatically across product architectures, from closet-compatible boxes refreshed every 3-5 years to institutional modular systems designed for decade-long service lives.
- Stackable Boxes:Injection-molded rectangular containers with interlocking lid mechanisms, typically 15-50 liter capacity, fabricated from high-density polyethylene for closet and under-bed deployment. United States suburban households with multiple children drive steady replacement demand as configurations adapt to changing toy inventories and bedroom layouts.
- Modular Bins:Open-top rectangular units with standardized footprint dimensions enabling vertical and horizontal reconfiguration, injection-molded in polypropylene for sanitization compatibility. Daycare centers are consolidating procurement around these systems as enrollment expansion forces rapid space reconfiguration.
- Drawer Organizers:Shallow compartmentalized trays for small-item sorting, typically polystyrene construction.
- Chest Boxes:Large-volume hinged-lid containers, 50-75 liter range, requiring ASTM F963 structural integrity certification.
- Rolling Containers:Castor-mounted mobile units for heavy-load transport, commanding premium tooling investments.
Stackable boxes anchor the volume base while modular bins gain share at the steepest rate.
Material:
Cost tiers stratify sharply, with commodity polypropylene dominating institutional procurement while engineering-grade polycarbonate captures premium hobbyist applications.
- Polypropylene:Semi-crystalline thermoplastic with superior chemical resistance and autoclave compatibility, now the default for daycare and educational procurement. EPA phthalate thresholds under the Consumer Product Safety Improvement Act have accelerated migration from vinyl alternatives, with polypropylene capturing institutional specification authority previously held by legacy materials.
- High-Density Polyethylene:Linear polymer with excellent impact strength and low-temperature performance, preferred for stackable box applications requiring durability under mechanical stress. United States residential buyers favor this material for under-bed storage where weight-bearing capacity determines satisfaction.
- Polystyrene:Amorphous thermoplastic for drawer organizer applications where cost minimization outweighs structural demands.
- Acrylonitrile Butadiene Styrene:Terpolymer balancing rigidity and processability, common in decorative chest box applications.
- Polycarbonate:High-performance engineering resin for transparent hobbyist workshop storage requiring optical clarity.
Polypropylene commands the largest procurement volumes while high-density polyethylene retains the broadest residential penetration.
Application:
Customer type determines specification complexity, with hobbyist workshops demanding precision tolerances while residential buyers prioritize aesthetic coordination.
- Daycare Centers:Institutional facilities requiring sanitization-compatible modular systems with rounded corners and drain holes for wash-down protocols. Enrollment expansion across United States suburban markets is forcing rapid capacity additions, with procurement teams specifying polypropylene architectures that withstand commercial-grade disinfectant cycles.
- Residential Playrooms:Home environments where open-concept new construction favors visible modular storage over concealed closet solutions. United States multi-child households in high-birth-rate suburban counties are driving replacement cycles as families reconfigure spaces for age-appropriate toy access.
- Educational Institutions:K-12 settings requiring FDA indirect food contact compliance for dual-use lunch and storage applications.
- Toy Retailers:Commercial display and back-of-house inventory management with branding surface requirements.
- Hobbyist Workshops:Enthusiast segments demanding transparent polycarbonate visibility and precise compartmentalization for small parts.
Residential playrooms generate the highest unit volumes while daycare centers show the most rapid procurement expansion.
Distribution Channel:
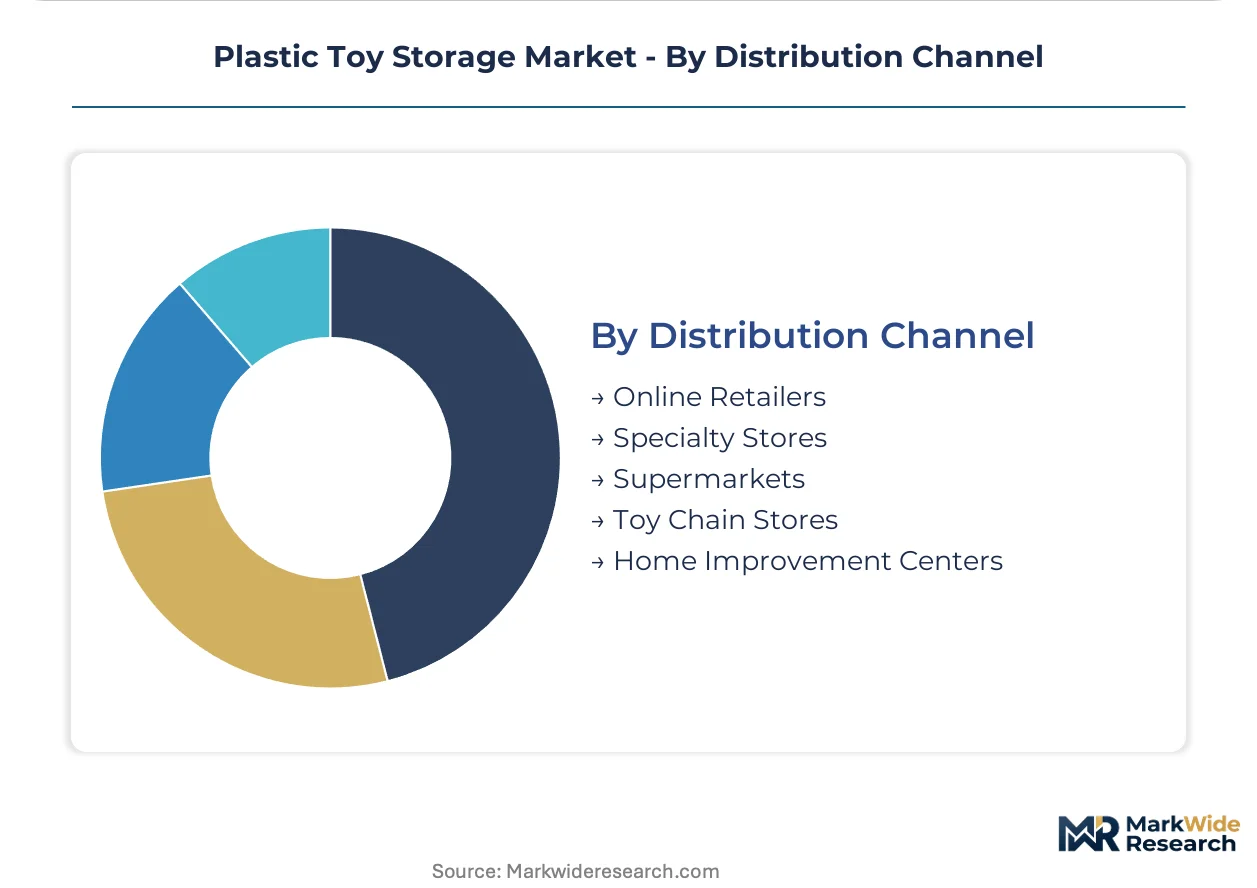
Volume concentration versus margin capture splits across channel types, with home improvement centers extracting terms while direct digital platforms retain specification authority.
- Online Retailers:Digital platforms enabling direct-to-consumer flat-pack logistics that compress last-mile distribution costs for modular bin systems. Specification filtering interfaces are capturing procurement authority from regional distributors, particularly for United States suburban households researching dimensions and capacity before purchase.
- Home Improvement Centers:Big-box retail networks with private-label compression power, driving margin pressure on stackable box and drawer organizer categories. These channels dominate replacement demand for residential closet and garage organization projects.
- Specialty Stores:Curated retail environments with premium positioning and consultative selling.
- Supermarkets:Mass-market impulse and seasonal toy storage with high volume, low margin economics.
- Toy Chain Stores:Coordinated merchandising with toy product lifecycles, capturing gift-oriented purchases.
Home improvement centers anchor volume throughput while online retailers expand share most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports injection-molded modular bins to United States suburban markets through consolidated Pacific shipping lanes. German manufacturers supply REACH-compliant polypropylene systems to European daycare networks. Indian fabricators serve domestic institutional procurement with cost-optimized stackable configurations.
United States
Suburban counties with elevated birth rates drive replacement cycles for under-bed and closet-compatible storage. The EPA's Consumer Product Safety Improvement Act enforces phthalate thresholds that accelerate polypropylene adoption. Injection molders in Ohio and Michigan supply big-box retail channels with high-density polyethylene stackable boxes.
Germany
REACH substance restrictions compel reformulation away from legacy plasticizers toward polypropylene alternatives. ECHA registration requirements create compliance barriers for non-European exporters. Manufacturers in North Rhine-Westphalia dominate institutional procurement for sanitization-compatible modular systems serving daycare networks across Central Europe.
China
Domestic toy retail expansion and export manufacturing concentration sustain dual demand channels. GB standards for plastic products in child-contact applications establish baseline safety protocols. Yangtze River Delta molders supply flat-pack modular configurations to direct-to-consumer platforms targeting United States and European markets.
India
Rising enrollment in urban daycare centers generates procurement demand for space-efficient storage architectures. BIS certification requirements for plastic products in educational settings create quality differentiation. Gujarat-based injection molding clusters serve institutional buyers in Maharashtra and Delhi-NCR with cost-competitive polypropylene bins.
Plastic Toy Storage Market Competitive Landscape
On the supply side, the industry is structured around three distinct competitive tiers. Captive resin compounders with in-house polymer formulation capabilities occupy the integrated tier. Specialized molders serving institutional procurement channels form the mid-tier. Private-label fabricators supplying home improvement centers populate the price-competitive tier. Dominant competitive moves include backward integration into resin compounding and flat-pack logistics optimization for direct digital channels.
Among North American manufacturers, Sterilite Corporation exemplifies the integrated archetype through captive supply of formulated resins. Rubbermaid anchors the institutional durability segment with commercial-grade specification authority. Inter IKEA Systems B.V. occupies a distinctive position through compressed last-mile distribution economics for knock-down modular systems.
| Leading Market Players |
|---|
| Sterilite Corporation |
| Rubbermaid |
| Inter IKEA Systems B.V. |
| Honey-Can-Do International, LLC |
| Seville Classics, Inc. |
| South Shore Industries |
| Badger Basket |
| KidKraft |
| Crate & Barrel |
| Others |
Pricing and Supply Chain Analysis
Pacific shipping lane rate volatility compresses margin buffers for Yangtze River Delta exporters while simultaneously amplifying price differentiation between flat-pack modular systems and fully assembled units destined for United States suburban retail channels.
Pricing Analysis
Thin-wall injection molding with in-mold labeling commands premium positioning against conventional decorated surfaces that degrade under institutional sanitization cycles. Pricing stratifies across premium, standard, and economy tiers based on ASTM F963 certification grade and captive resin compounding capability. Cost compression in the stackable box segment intensifies because private-label competition at home improvement centers extracts supplier concessions. Residential buyers in multi-child households exhibit highest price sensitivity for closet-compatible units, while daycare procurement teams prioritize sanitization durability over unit cost.
Supply Chain Analysis
Consumer Product Safety Improvement Act phthalate thresholds restrict resin formulation flows toward polypropylene alternatives, reshaping raw material sourcing patterns. Manufacturing gravity centers on China, the United States, and Germany, with injection molding clusters drawing from polypropylene, high-density polyethylene, and polystyrene feedstocks. Single-source vulnerability concentrates in Yangtze River Delta mold dependencies for precision-tooled bin architectures. Distribution runs through consolidated big-box retail networks and direct-to-consumer digital platforms with flat-pack logistics optimization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as United States suburban school districts consolidate procurement authority through digital catalog platforms, fragmenting traditional distributor relationships and extracting specification compliance concessions from manufacturers.
For Market Incumbents: Harden ASTM F963 certification depth across chest box and rolling container lines to deter mid-scale entrants lacking six-figure mold capital. Deepen backward integration into captive resin compounding to insulate margin control from petrochemical input volatility. Channel control through direct-to-institution procurement platforms defends against distributor disintermediation threatening specification authority.
For New Entrants and Emerging Players: Establish a beachhead in modular bin systems for United States daycare enrollment expansion corridors where sanitization compatibility creates specification barriers for undifferentiated competitors. Target REACH-compliant polypropylene architectures for European export access where ECHA registration requirements filter non-compliant suppliers. Flat-pack logistics innovation enables direct digital channel entry with compressed last-mile economics.
For Investors and Strategic Acquirers: EPA phthalate threshold evolution reshapes the acquisition landscape toward polypropylene-dominant manufacturers with institutional procurement relationships. Five-to-ten year viability favors integrated compounder-molders with daycare channel penetration over pure-play fabricators exposed to home improvement center margin compression. Monitor state-level extended producer responsibility legislation migration as the signal for end-of-life cost absorption inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Sterilite Corporation's captive formulation capability sustains margin control against petrochemical volatility. |
| Flat-Pack Logistics Optimization | Inter IKEA Systems B.V. compresses last-mile distribution costs for knock-down modular bin systems. |
| ASTM F963 Certification Investment | Rubbermaid anchors commercial-grade durability standards that dominate daycare procurement channels. |
| Direct-to-Institution Digital Platform | Specification filtering interfaces capture procurement authority from regional supply houses in suburban districts. |
| REACH Compliance Migration | European manufacturers accelerate polypropylene adoption to meet ECHA substance restriction deadlines. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across injection molding facilities, daycare procurement teams, and home improvement center category buyers. Primary fieldwork captured specification requirements from institutional buyers in United States suburban markets and residential purchasing patterns in high-birth-rate counties. Secondary validation drew from EPA Consumer Product Safety Improvement Act filings, ASTM F963 test documentation, customs trade data for injection-molded plastic articles, and SEC disclosures from resin compounders. Bottom-up demand modeling triangulated against top-down production capacity assessments across Yangtze River Delta and Ohio-Michigan manufacturing clusters.
Calibration anchored volume projections to enrollment-driven daycare capacity expansion and residential household formation patterns across the analysis window. Segmentation dimensions encompassed product architecture, material grade tier, application setting, and distribution channel structure. CAGRs derived from compound growth mechanics applied to baseline consumption estimates, with cross-checks against resin consumption forecasts and injection molding equipment installation trends. Industry-specific inputs included phthalate regulatory compliance timelines and flat-pack logistics adoption rates in direct digital channels.
Macroeconomic conditions sit as an overlay; deviation in crude oil benchmarks and Pacific shipping lane rates would shift the trajectory. Forecasts reflect documented assumptions regarding EPA enforcement consistency and REACH implementation timelines. Material shifts in extended producer responsibility legislation scope or ASTM F963 structural testing requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Toys and Games
LAMEA Action Figure Toys Market
Toys and Games
Board Games and Puzzles Market
Toys and Games
Kids Recreational Services Market
Toys and Games
Sustainable Toys Market
Toys and Games
Toys and Games Market
Toys and Games
China Playing Cards & Board Games Market
Toys and Games
Bubble Blower Market
Toys and Games
Playing Cards and Board Games Market
Toys and Games
Bounce House Market
Toys and Games
United States Toys Market
Toys and Games
Ferret Toys Market
Toys and Games
Global Educational Toy Market
Toys and Games
Indoor Bumper Cars Market
Toys and Games
Arcade Games Machine Market
Toys and Games
Die-Cast Toys Market
Toys and Games
Global Blind Boxes Market