
 Quality Warranty Management Market | 2026-2036
Quality Warranty Management Market Size, Share, and Industry Trends Forecast 2026-2036
Quality Warranty Management Market Outlook
Multi-source vendor consolidation is realigning how enterprises procure warranty management infrastructure. SAP leverages its ERP backbone to anchor integrated claims-to-manufacturing workflows across automotive clients. Oracle Corporation competes through database-native analytics that unify quality assurance data across distributed supplier networks. Salesforce extends its CRM dominance into warranty lifecycle engagement, positioning service portals as retention tools for consumer goods brands.
Quality warranty management encompasses software platforms and services that administer product guarantee programs, track failure modes, and automate claim adjudication through rule-based engines processing structured and unstructured data. Its primary commercial purpose is to reduce warranty reserve volatility while capturing field intelligence for engineering feedback loops. Cloud-based deployment leads adoption as manufacturers seek elastic infrastructure for seasonal claim surges, while warranty analytics represents the fastest-expanding service type due to predictive maintenance integration. The aerospace vertical sustains premium pricing for on-premise configurations given ITAR and airworthiness traceability mandates.
ISO 9001 quality management standards, FDA 21 CFR Part 820 for medical device quality systems, and EU Product Liability Directive frameworks collectively elevate warranty documentation rigor across regulated verticals. These standards compel manufacturers to invest in auditable claim trails and root-cause analysis capabilities that satisfy both customer protection and regulatory inspection requirements. Stakeholders must evaluate whether hybrid deployment architectures can reconcile cloud agility with sector-specific data sovereignty constraints.
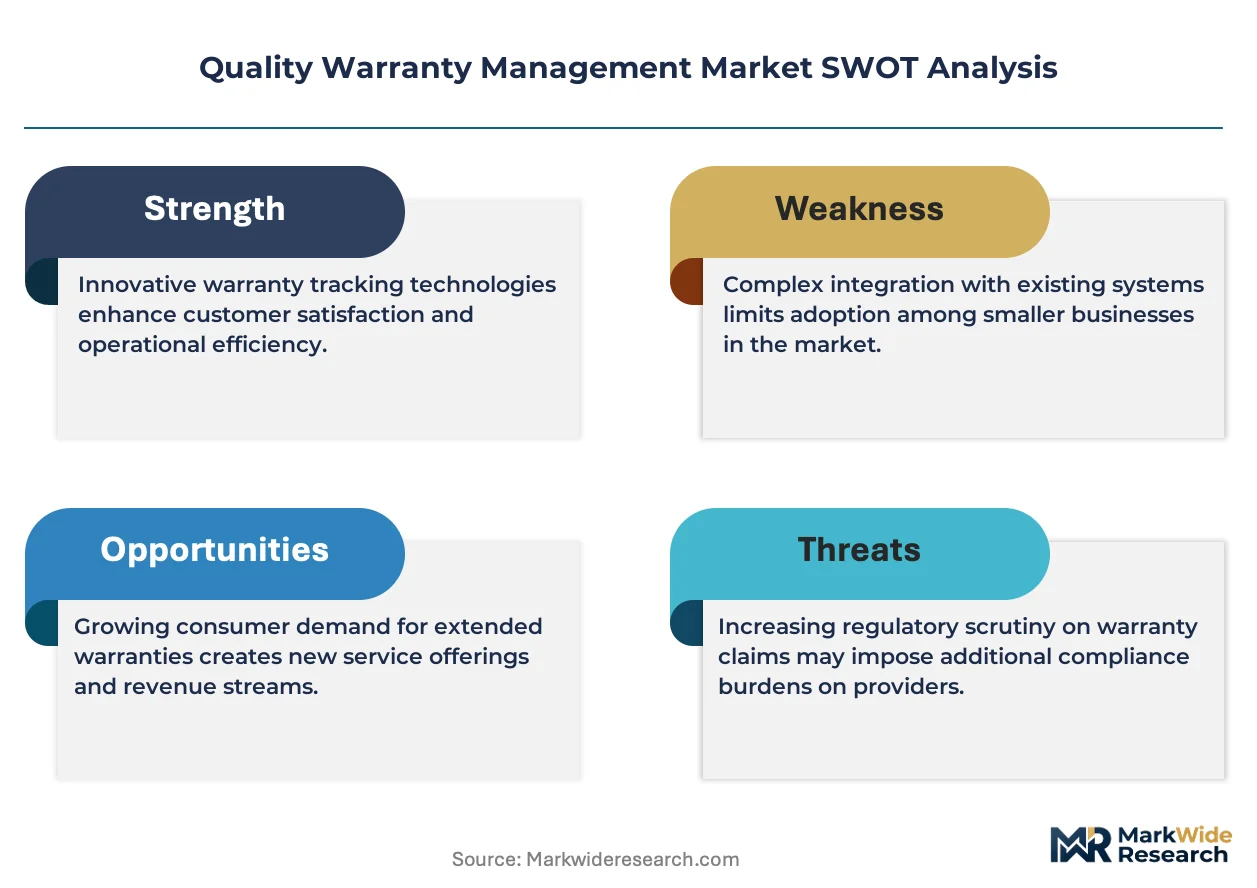
Market Dynamics
Cloud-native warranty platforms are compressing deployment timelines from months to weeks, forcing incumbent vendors to rearchitect legacy stacks around microservices and API-first data exchange.
Growth Catalysts
- Predictive maintenance integration:Automotive OEMs embed sensor telemetry into warranty analytics to flag component failures before customer claims materialize, reducing reserve volatility.
- EU Product Liability Directive:Strict documentation mandates compel manufacturers to deploy auditable claim trails and root-cause analysis engines across distributed supplier networks.
- ISO 9001:2015 revisions:Updated quality management standards require documented corrective action workflows, accelerating platform upgrades among medical device and aerospace suppliers.
Market Restraints
- ITAR compliance costs:Aerospace and defense contractors face prohibitive data sovereignty requirements that block pure-cloud deployments, sustaining expensive on-premise infrastructure.
- Legacy ERP entrenchment:Deep integration with SAP and Oracle systems creates switching friction that extends procurement cycles and inflates total cost of ownership.
- Fragmented supplier data standards:Tier-2 and Tier-3 component manufacturers lack standardized failure-mode taxonomies, forcing costly data normalization projects.
Strategic Opportunities
- India manufacturing expansion:PLI scheme incentives for electronics and automotive production create first-mover advantage for warranty platforms supporting BIS quality certification workflows.
- Connected device telemetry:Convergence of IoT sensor streams with AI-driven anomaly detection enables proactive warranty interventions before product failure.
- Outcome-based service contracts:Industrial equipment vendors bundle warranty management with uptime guarantees, creating recurring revenue streams that displace transactional claim processing.
Industry Challenges
- Data engineering talent scarcity:Warranty analytics platforms require specialists fluent in both manufacturing domain knowledge and machine learning pipeline architecture.
- Multi-cloud integration complexity:Hybrid deployments spanning AWS, Azure, and private data centers demand sophisticated orchestration that most manufacturers lack in-house.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Quality Warranty Management Market |
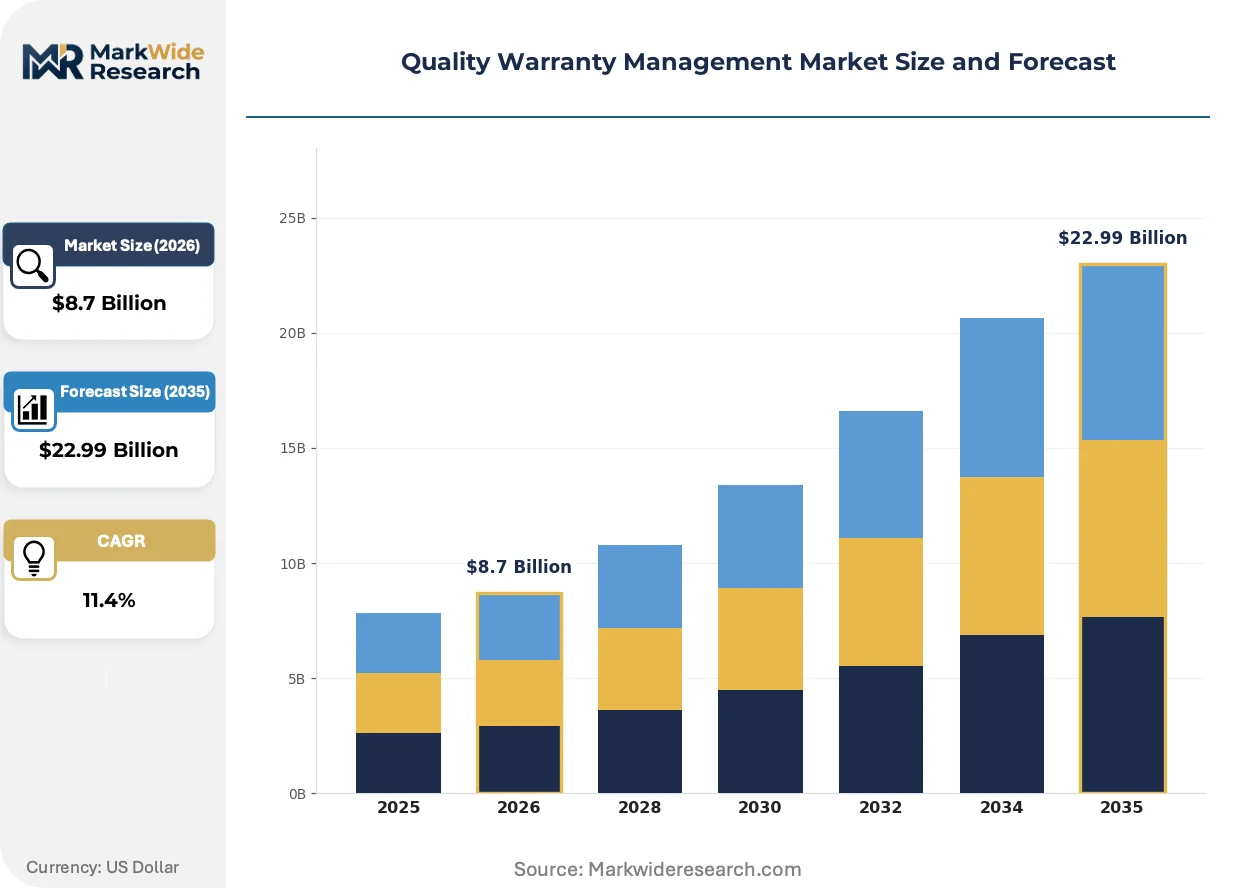
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Claims Management, Warranty Analytics, Quality Assurance, Reporting Tools End User: Manufacturers, Retailers, Distributors, Service Providers Deployment: On-Premise, Cloud-Based, Hybrid, SaaS Industry Vertical: Automotive, Electronics, Consumer Goods, Aerospace |
| Companies Covered | IBM Corporation, SAP, Oracle Corporation, Pegasystems Inc., Tavant Technologies, PTC, Wipro Limited, IFS, Salesforce, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Quality Warranty Management Market Strategic Shifts
Artificial intelligence and embedded connectivity are transforming warranty management from reactive cost centers into predictive engineering intelligence systems that shape product design cycles.
Machine learning models trained on historical failure patterns and real-time operational telemetry are automating claim adjudication decisions that previously required human engineering review. Automotive manufacturers in Germany and the United States deploy these systems to process high-volume powertrain claims with sub-second resolution. The compression of adjudication cycles is automating reserve calculations and accelerating feedback loops between field performance and design engineering.
EU Medical Device Regulation (MDR) mandates unique device identification and post-market surveillance documentation that exceeds legacy quality system capabilities. Manufacturers must now maintain traceable complaint records across distributed supply chains with audit-ready retrieval timelines. European medical device producers are responding by consolidating warranty and vigilance workflows into unified quality management platforms.
Industrial buyers now demand performance-based contracts that transfer operational risk to equipment vendors rather than traditional warranty term sheets. Mining and energy sector procurement teams in Australia and Canada unbundle hardware acquisition from lifecycle service commitments. This behavioral shift compresses vendor selection criteria around demonstrated mean-time-between-failure data rather than warranty duration alone.
Quality Warranty Management Market Segmentation
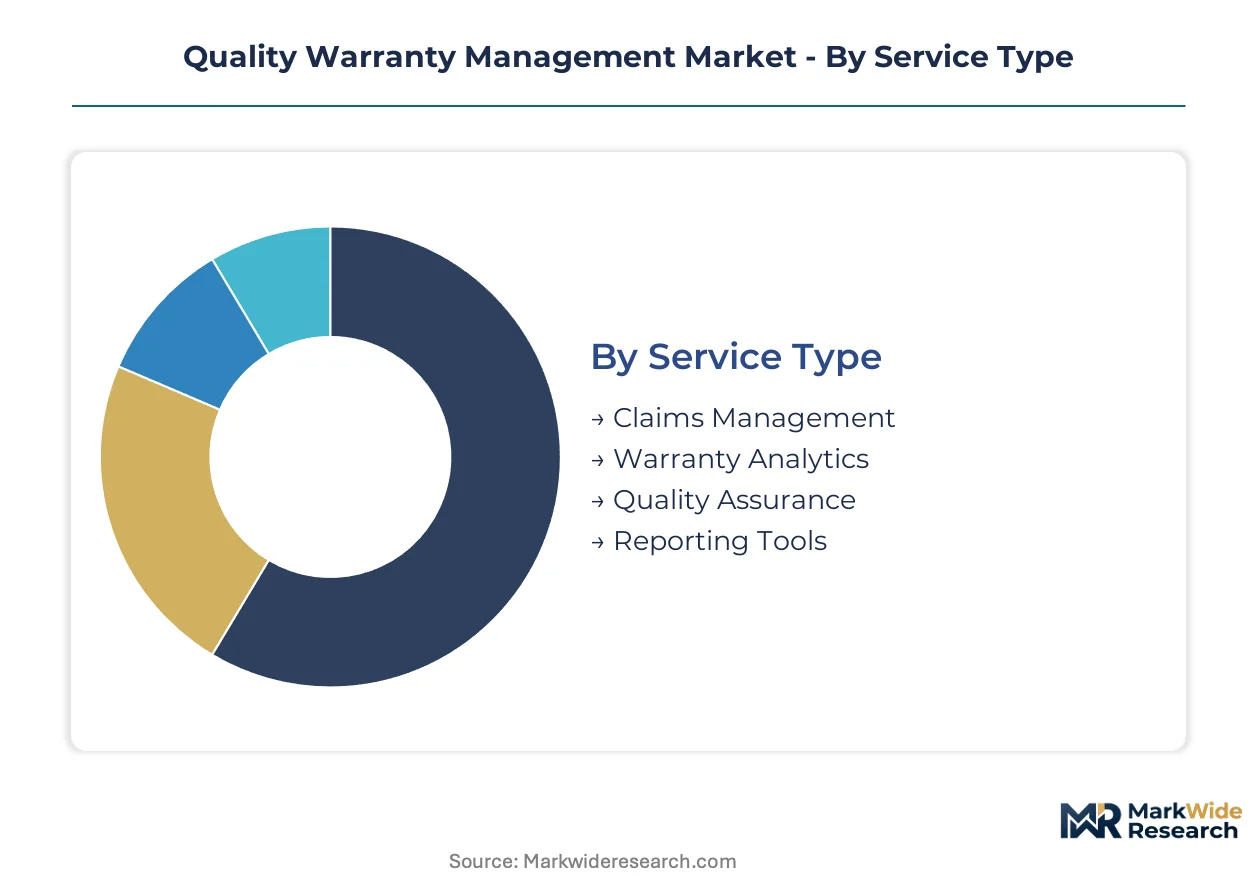
Warranty management platforms serve heterogeneous operational requirements across manufacturing ecosystems. Segmentation reveals where predictive capabilities command premium pricing versus where transactional processing dominates procurement decisions.
Service Type:
Volume concentration sits in claims processing automation, while premium pricing attaches to predictive intelligence layers.
- Claims Management:Rule-based engines adjudicate warranty requests through structured workflows that validate eligibility, calculate reserves, and trigger supplier chargebacks. Automotive OEMs in Germany and the United States deploy these systems to process high-volume powertrain claims with sub-second resolution.
- Warranty Analytics:Machine learning pipelines ingest sensor telemetry and historical failure patterns to flag component degradation before customer claims materialize. This segment commands the steepest expansion trajectory as manufacturers embed predictive maintenance into quality feedback loops.
- Quality Assurance:Auditable documentation trails satisfy ISO 9001 corrective action mandates across medical device and aerospace supplier networks.
- Reporting Tools:Dashboard interfaces consolidate claim metrics for reserve volatility management and executive risk reporting.
Mature deployment sits with Claims Management. Newer deployment is concentrated in Warranty Analytics.
End User:
Procurement authority shifts upstream as manufacturers internalize warranty costs that previously flowed to channel partners.
- Manufacturers:Automotive and electronics producers deploy end-to-end platforms integrating engineering, quality, and finance functions. These buyers demand API-native architectures that federate data across Tier-1 through Tier-3 supplier hierarchies.
- Service Providers:Authorized repair networks require mobile-enabled claim submission and real-time parts availability verification. This segment is gaining share fastest as outcome-based service contracts proliferate in industrial equipment sectors.
- Retailers:Extended warranty program administrators seek white-label customer portals with embedded fraud detection.
- Distributors:Inventory-heavy intermediaries prioritize supplier chargeback automation and reverse logistics coordination.
Platform sophistication peaks with Manufacturers. Deployment simplicity dominates among Distributors.
Deployment:
Elastic infrastructure demands separate from data sovereignty constraints create bifurcated procurement patterns.
- Cloud-Based:AWS and Azure-hosted configurations deliver seasonal capacity scaling for consumer goods manufacturers facing holiday claim surges. Elastic infrastructure eliminates capital-intensive on-premise provisioning.
- Hybrid:Sensitive quality data resides in private data centers while customer-facing portals leverage public cloud elasticity. Aerospace contractors facing ITAR mandates favor this architecture for airworthiness traceability.
- On-Premise:Defense and medical device producers maintain fully captive infrastructure to satisfy FDA 21 CFR Part 820 and ITAR documentation requirements.
- SaaS:Subscription pricing lowers entry barriers for mid-market electronics assemblers lacking dedicated IT engineering resources.
Regulatory complexity sustains On-Premise. Cost pressure accelerates SaaS.
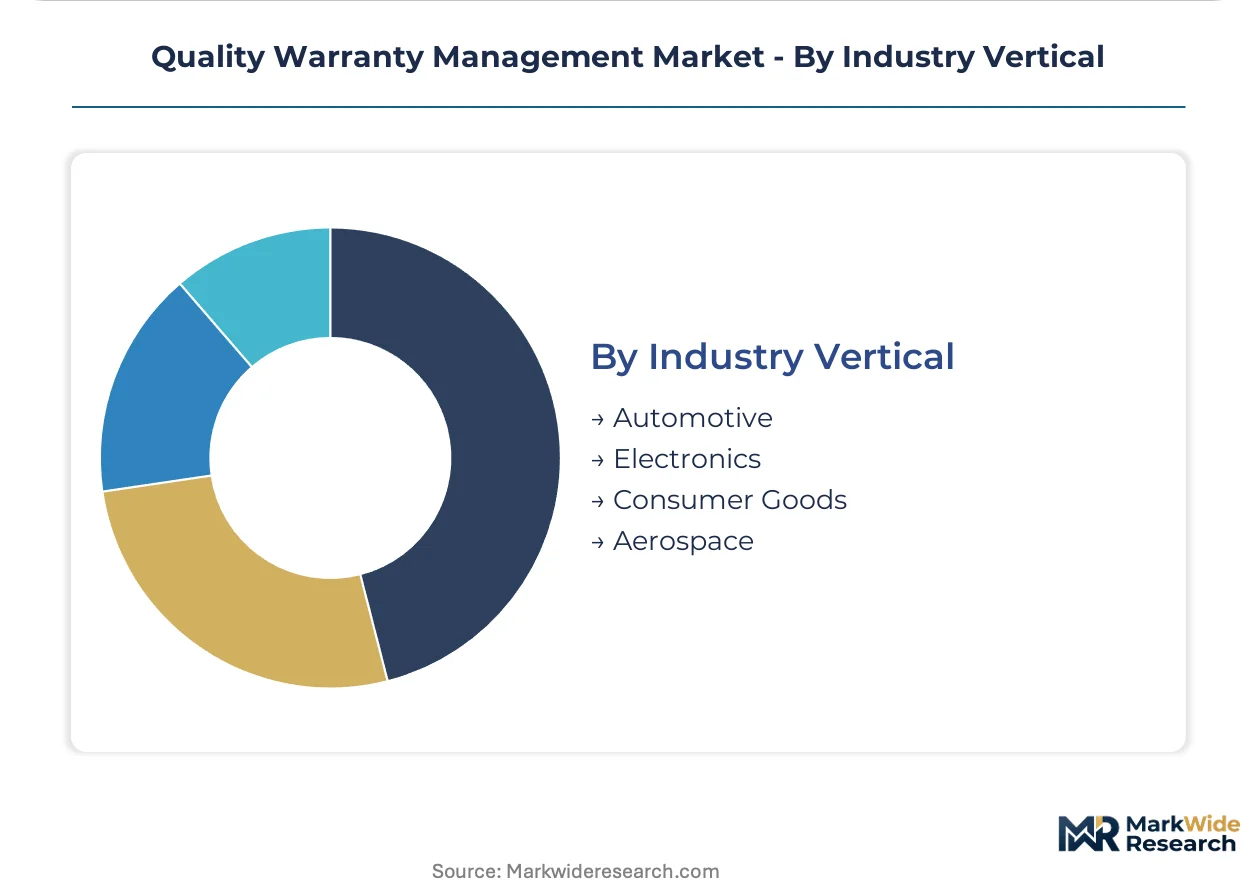
Industry Vertical:
Failure-mode criticality and liability exposure determine platform investment intensity across sectors.
- Automotive:Powertrain warranty reserves represent material balance sheet exposures, driving investment in predictive analytics and supplier recovery automation. NHTSA recall coordination requirements mandate auditable claim trails.
- Aerospace:FAA airworthiness directives and ITAR compliance sustain premium pricing for on-premise configurations with complete engineering traceability. This vertical maintains the most stringent documentation standards.
- Electronics:Rapid product cycles and distributed Asian manufacturing footprints prioritize cloud-native platforms with multi-language supplier interfaces.
- Consumer Goods:Brand reputation sensitivity drives investment in customer-facing warranty portals that double as retention tools.
Compliance rigor peaks in Aerospace. Volume scale concentrates in Automotive.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for quality warranty management platforms concentrates in industrialized manufacturing economies with stringent product liability enforcement. The United States, Germany, and China together absorb the majority of enterprise procurement as automotive, aerospace, and electronics producers invest in predictive analytics infrastructure.
United States
Automotive OEMs in Michigan and Ohio deploy warranty analytics to reduce powertrain reserve volatility. NHTSA recall coordination mandates drive investment in auditable claim trails across Tier-1 supplier networks. Detroit-area manufacturers lead adoption of cloud-native platforms integrating sensor telemetry with machine learning adjudication engines.
Germany
Bavarian automotive clusters prioritize predictive maintenance integration to flag component failures before customer claims materialize. EU Product Liability Directive documentation requirements compel manufacturers to maintain root-cause analysis capabilities. Stuttgart and Munich industrial corridors sustain premium pricing for platforms with complete engineering traceability.
China
Electronics assemblers in the Yangtze River Delta seek elastic cloud infrastructure for seasonal claim surges. GB standards and SAMR quality enforcement accelerate platform upgrades among domestic manufacturers. Shenzhen and Shanghai production hubs drive demand for multi-language supplier interfaces across distributed Asian manufacturing footprints.
India
PLI scheme incentives for electronics and automotive production create procurement momentum for BIS-certified warranty workflows. CDSCO medical device regulations compel documented corrective action capabilities among domestic suppliers. Tamil Nadu and Gujarat manufacturing zones attract first-mover platform deployments supporting export quality certification.
Japan
Automotive and electronics producers in the Chubu region invest in warranty analytics to compress feedback loops between field performance and design engineering. METI quality management guidelines elevate documentation rigor across supplier hierarchies. Nagoya industrial clusters favor hybrid deployment architectures reconciling cloud agility with data sovereignty constraints.
Quality Warranty Management Market Competitive Environment
Platform consolidation dominates the current landscape as ERP incumbents absorb specialized warranty vendors into broader manufacturing suites. The vendor base stratifies into three tiers: enterprise software conglomerates with embedded quality modules, pure-play warranty specialists with deep industry vertical expertise, and cloud-native challengers offering API-first architectures. Strategic archetypes include ERP-anchored workflow integrators, database-native analytics providers, and CRM-extended service engagement platforms. M&A activity and cloud migration partnerships represent the dominant competitive vectors reshaping procurement patterns.
Within the ERP-anchored tier, SAP and Oracle Corporation exemplify incumbents leveraging manufacturing data backbone dominance to capture warranty workflow integration. Salesforce occupies a distinct position extending customer relationship infrastructure into post-sale service engagement. Among India-based technology services providers, Wipro Limited represents the systems integrator archetype bridging legacy ERP entrenchment with cloud-native deployment architectures for mid-market manufacturers lacking dedicated IT engineering resources.
| Leading Market Players |
|---|
| IBM Corporation |
| SAP |
| Oracle Corporation |
| Pegasystems Inc. |
| Tavant Technologies |
| PTC |
| Wipro Limited |
| IFS |
| Salesforce |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up warranty software specialists have consolidated fragmented point solutions across the United States and Germany, concentrating pricing power with platforms that command premium SaaS multiples while compressing margins for undifferentiated claims-processing vendors. This ownership pattern tightens supply-side discipline as portfolio companies enforce unified pricing architectures across acquired customer bases.
Pricing Analysis
Volume concentrates in standardized SaaS tiers while margin pools in predictive analytics modules. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-grade compliance suites from mid-market automotive bundles. Cost compression in the economy tier is intensifying because cloud-native entrants are undercutting legacy on-premise maintenance contracts. Mid-market electronics manufacturers exhibit the sharpest price sensitivity, whereas aerospace contractors absorbing ITAR compliance costs show minimal elasticity.
Supply Chain Analysis
Data engineering talent scarcity in Bengaluru and Shenzhen constrains platform development velocity for warranty analytics vendors. Supply concentrates in the United States, Germany, and India, with implementation services drawing from Eastern European delivery centers. The technology stack rests on AWS and Azure infrastructure, open-source machine learning frameworks, and specialized IoT sensor hardware. Single-source vulnerability runs through hyperscaler concentration for cloud-native deployments. Distribution runs through direct enterprise sales teams and systems integrators including Wipro Limited.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform consolidation is accelerating as cloud migration costs force sub-scale vendors toward strategic exits. ERP incumbents are capturing distressed assets to fill warranty analytics gaps.
For Market Incumbents: Extend API-native architectures to absorb adjacent quality management workflows before pure-play analytics vendors establish beachheads. SAP and Oracle should accelerate microservices rearchitecture to defend against cloud-native challengers eroding their automotive installed base. Certification investment in ISO 9001:2015 compliance modules represents the priority defensive lever.
For New Entrants and Emerging Players: EU Medical Device Regulation in Europe opens a window for unified warranty-vigilance platforms that legacy QMS vendors cannot rapidly reconfigure. Target mid-tier medical device manufacturers in Germany and France with pre-validated documentation templates. White-label partnerships with Indian systems integrators offer the fastest go-to-market angle for cost-sensitive Asian electronics assemblers.
For Investors and Strategic Acquirers: Distressed-cycle entries favor cloud-native warranty specialists with proven automotive OEM references in the United States and Germany. Long-term viability hinges on predictive maintenance integration depth rather than transactional claims volume. Monitor NHTSA recall frequency as the inflection signal indicating reserve volatility pressure that drives analytics platform procurement.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies warranty analytics with SAP ERP backbones across Tier-1 automotive supplier networks. |
| Acquisition of Specialist Firm | Fills predictive maintenance capability gaps for industrial equipment vendors in mining and energy sectors. |
| Geographic Expansion | Establishes BIS-certified delivery centers in Tamil Nadu to capture PLI-scheme manufacturing momentum. |
| Strategic Partnership | Links Salesforce service clouds with OEM dealer management systems for retention-focused warranty portals. |
| Product Launch | Introduces ITAR-compliant hybrid architectures reconciling cloud elasticity with aerospace data sovereignty mandates. |
Study Parameters
Document review covered SEC 10-K filings, ISO certification registries, and EU Medical Device Regulation guidance documents, complemented by interviews with warranty platform product managers, automotive OEM quality directors, aerospace compliance officers, and medical device regulatory affairs leads. Secondary sources included NHTSA recall databases, FAA airworthiness directives, and BIS quality certification records. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across the analysis window.
Cross-referencing historical deployment patterns with expert panel input shaped the analytical framework. Segmentation dimensions modeled include service type, deployment architecture, end-user category, and industry vertical complexity. CAGRs were derived through regression analysis of adoption curves and technology substitution rates. Forecast inputs incorporated cloud migration velocity and predictive maintenance integration maturity.
Caveats apply where NHTSA regulatory enforcement intensity or EU Product Liability Directive implementation timelines could materially shift the outlook. Forecasts reflect assumptions about ITAR compliance cost trajectories and Tier-2 supplier data standardization progress. Material deviation in hyperscaler pricing or automotive production volumes warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Risk Management and Compliance
Global Liquidity Asset Liability Management Solutions Market
Risk Management and Compliance
Risk-Based Monitoring Software Market
Risk Management and Compliance
Global Energy Trading and Risk Management (ETRM) Market
Risk Management and Compliance
Oil and Gas Risk Management Market
Risk Management and Compliance
Clinical Risk Grouping Solutions Market
Risk Management and Compliance
Global Credit Risk Rating Software Market
Risk Management and Compliance
North America Strategic Consulting Market
Risk Management and Compliance
Artificial Intelligence and Regtech Market
Risk Management and Compliance
Revenue Assurance Market
Risk Management and Compliance
Governance, Risk and Compliance Platform Market
Risk Management and Compliance
AI in Fraud Management Market
Risk Management and Compliance
Employee Benefits Strategy and Consulting Market
Risk Management and Compliance
BFSI Security Market
Risk Management and Compliance
Medical Device Cyber Risk Quantification Market
Risk Management and Compliance
Global Compliance Management Software Market
Risk Management and Compliance
Global Backstop Netting Systems Market