
 Stress Testing Solutions Market | 2026-2036
Stress Testing Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Stress Testing Solutions Market Analysis
The gap between premium enterprise platforms and commodity API testing tools is restructuring how vendors capture value across the Stress Testing Solutions landscape. IBM Corporation leverages its mainframe heritage and hybrid cloud integrations to sustain pricing power in regulated financial workloads. Oracle Corporation anchors its position through database-layer optimization that reduces latency during peak-load simulations. Micro Focus International competes by specializing in legacy system compatibility, a niche where modernization budgets often exceed greenfield deployments.
Stress testing solutions encompass software platforms and services that simulate extreme operational conditions to validate system resilience, typically processing millions of concurrent transactions through distributed load injectors to identify breaking points before production deployment. Enterprise software and cloud solutions command the deepest margin pools as financial institutions consolidate fragmented toolchains into unified resilience platforms, while SaaS and API testing tools expand fastest among software developers embedding continuous validation into CI/CD pipelines. The deployment model dimension shows hybrid architectures leading in regulated sectors where data sovereignty requirements prevent full public cloud migration, though private cloud instances are gaining share as banks seek dedicated infrastructure for regulatory submission workloads.
EU DORA mandates, Basel Committee stress testing guidelines, and SEC cybersecurity disclosure rules are elevating baseline requirements for documentation, audit trails, and third-party risk management in validation workflows. The Federal Reserve's CCAR framework and EBA stress test exercises directly shape procurement criteria, forcing vendors to pre-certify scenario libraries against supervisor templates. Stakeholders must monitor how divergent national implementations of cross-border data localization rules affect hybrid deployment strategies.
Market Dynamics
EU DORA compliance deadlines are compressing procurement cycles as European banks race to validate operational resilience before enforcement begins, forcing vendors to restructure delivery models around pre-certified scenario templates.
Growth Catalysts
- EU Digital Operational Resilience Act:Mandatory stress testing for critical IT systems across financial institutions creates baseline demand for automated validation platforms.
- Cloud migration acceleration:German banks are migrating stress testing workloads to hybrid architectures, expanding addressable infrastructure for resilience software vendors.
- Continuous integration pipelines:Software developers embed API stress testing into CI/CD workflows, broadening adoption beyond traditional financial services.
Market Restraints
- Specialized talent scarcity:Shortage of engineers fluent in both mainframe systems and cloud-native architectures limits deployment velocity at legacy institutions.
- Data sovereignty compliance:Cross-border localization rules fragment cloud infrastructure strategies, increasing operational complexity for multi-jurisdiction banks.
- Open-source load testing tools:Apache JMeter and k6 substitute for commercial platforms in non-regulated development environments, capping pricing power at the low end.
Strategic Opportunities
- Regulatory submission automation:Pre-packaged scenario libraries aligned with EBA stress test templates and Federal Reserve CCAR frameworks command premium positioning.
- AI-augmented anomaly detection:Machine learning convergence with traditional load simulation enables predictive breaking-point identification before peak-load events.
- Sector expansion beyond banking:Payment processors and insurance underwriters face emerging DORA-equivalent mandates, opening adjacent verticals.
Industry Challenges
- Legacy system integration:COBOL-era core banking platforms resist standard API connectivity, requiring costly middleware development for unified resilience testing.
- Certification timeline compression:Supervisor template updates outpace vendor recertification cycles, creating compliance lag for scenario library providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stress Testing Solutions Market |
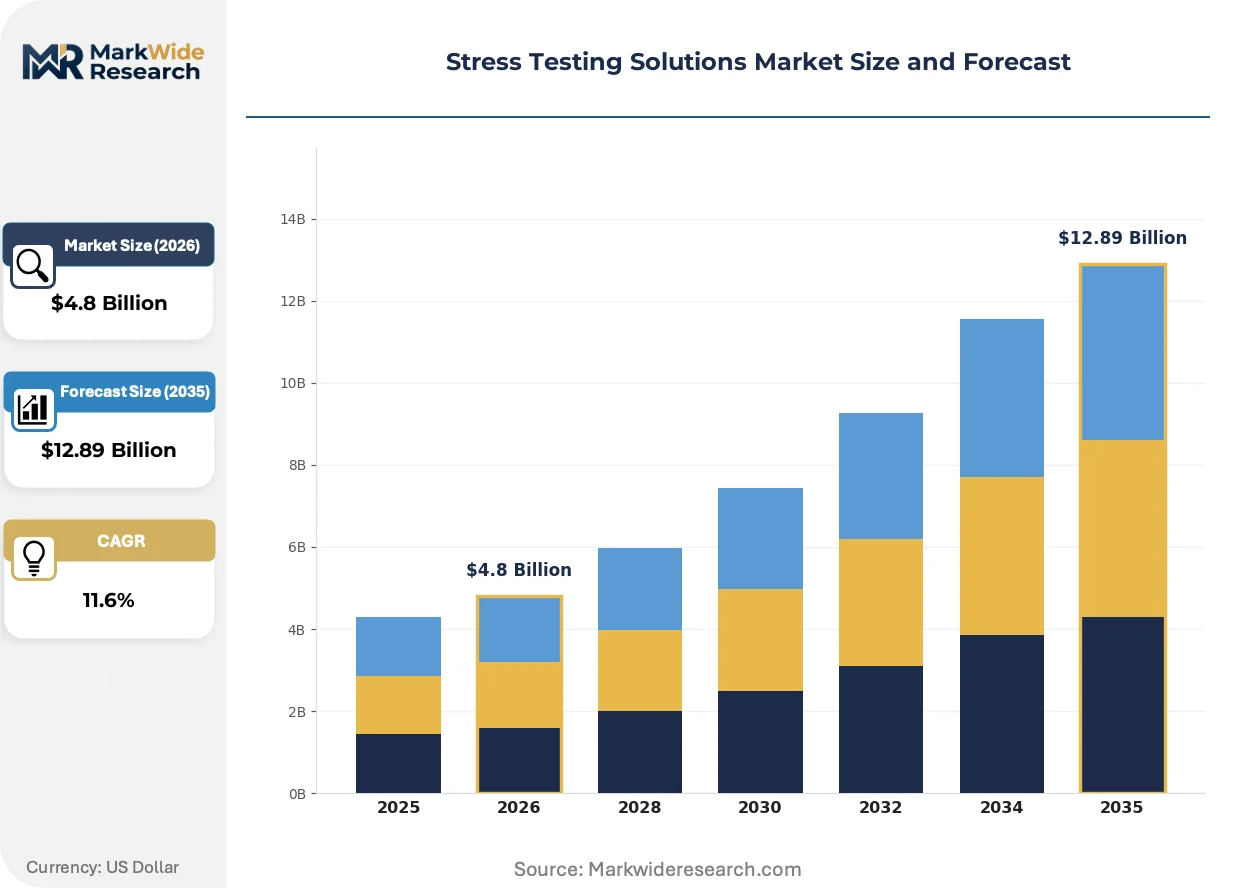
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.89 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Enterprise Software, SaaS, API Testing Tools, Cloud Solutions End User: Financial Institutions, Software Developers, Healthcare Providers, Retail Enterprises Deployment Model: On-Premises, Public Cloud, Private Cloud, Hybrid Testing Method: Load Testing, Performance Testing, Automated Testing, Manual Testing |
| Companies Covered | IBM Corporation, Oracle Corporation, Micro Focus International, Accenture, Capgemini SE, Wipro Limited, Cognizant Technology Solutions Corporation, Akamai Technologies Inc., SAS Institute Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stress Testing Solutions Market Emerging Trajectories
Automated resilience validation is migrating from batch-oriented annual exercises to continuous real-time monitoring, compressing the feedback loop between simulation and production deployment.
Distributed load injector architectures are consolidating previously fragmented point solutions into unified platforms. Tier-one banks in Frankfurt and London deploy these systems to simulate millions of concurrent transactions across hybrid infrastructure. The technology is consolidating vendor footprints by absorbing API testing, chaos engineering, and compliance reporting into single procurement decisions.
EU DORA mandates now require documented audit trails for all resilience testing activities, effective 2025. Financial institutions must demonstrate systematic validation of critical third-party dependencies. Cloud service providers serving European banks are responding by embedding compliance-grade logging directly into infrastructure-as-code templates.
Buying committees now favor subscription pricing over perpetual licenses, unbundling implementation services from software fees. Mid-tier banks in Spain and Italy lead this shift, pressuring vendors to restructure revenue recognition. Procurement teams increasingly demand usage-based tiers rather than seat-based models for development-stage testing tools.
Stress Testing Solutions Market Segmentation
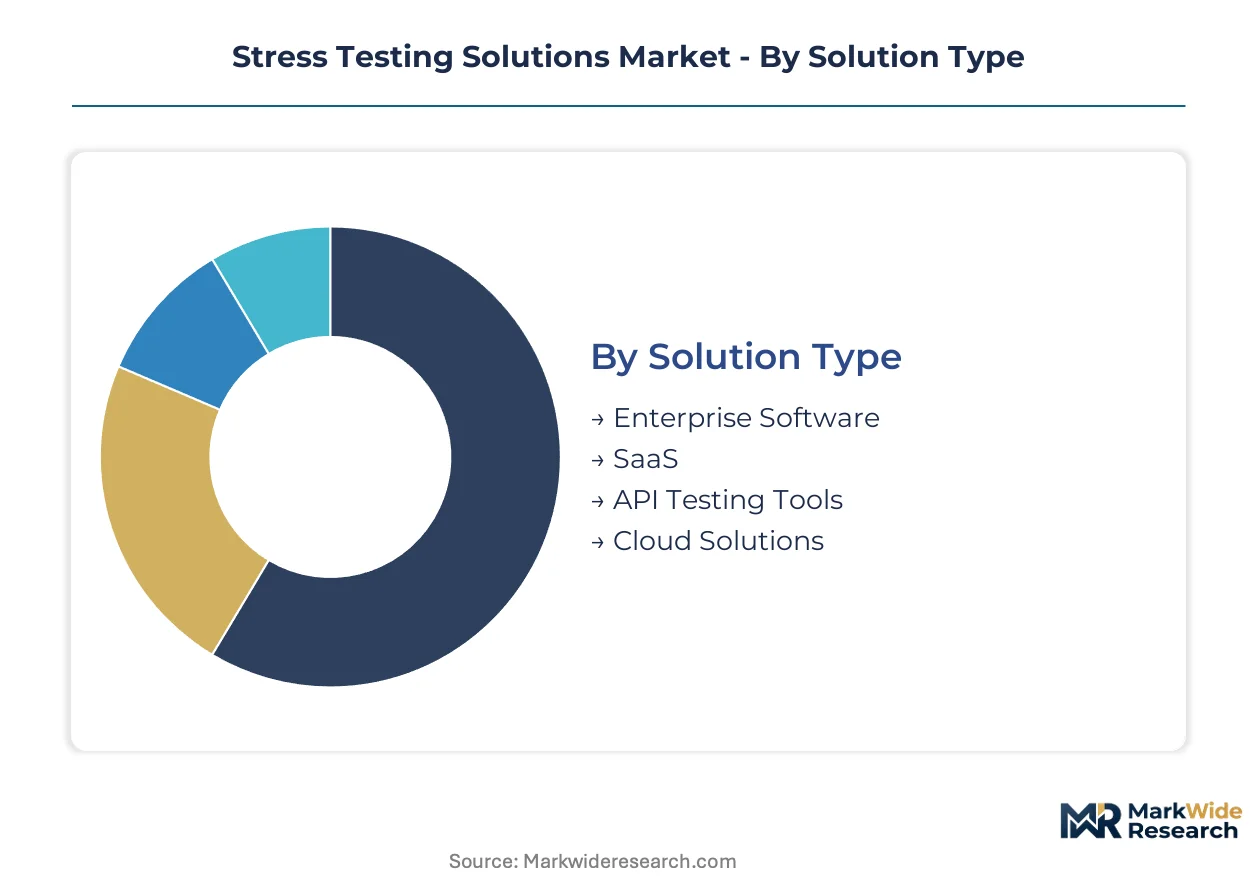
Segmentation in stress testing solutions reveals how procurement priorities diverge between regulated financial institutions seeking compliance-grade platforms and development teams prioritizing speed and integration flexibility. Understanding these divides helps vendors align feature roadmaps with buyer willingness to pay.
Solution Type:
Cost tier separates buyers most sharply in this category, with annual contract values spanning three orders of magnitude from open-source API tools to mainframe-resilient enterprise suites.
- Enterprise Software:On-premise platforms with deep customization for core banking systems and regulatory submission workflows. Tier-one banks in Germany and France anchor demand as DORA compliance deadlines compress procurement timelines for documented resilience validation.
- SaaS:Subscription-based delivery with pre-configured scenario libraries and automated reporting dashboards. Mid-tier banks in Spain and Italy favor this model for its faster deployment and lower capital commitment.
- API Testing Tools:Lightweight solutions for developer-centric continuous integration pipelines.
- Cloud Solutions:Infrastructure-as-a-service offerings with elastic load injector scaling for peak-load simulation events.
Volume sits with Enterprise Software; growth tilts toward SaaS.
End User:
Application context determines feature requirements more than budget scale, with financial services demanding audit trails that software developers consider overhead.
- Financial Institutions:Banks, insurers, and asset managers requiring Basel Committee and EBA-compliant scenario libraries with immutable logging. Frankfurt and London clusters drive premium platform adoption as hybrid cloud migration accelerates for stress testing workloads.
- Software Developers:Engineering teams embedding automated validation into CI/CD pipelines. These buyers prioritize API compatibility and speed over compliance documentation, expanding the addressable base beyond traditional financial services.
- Healthcare Providers:Emerging demand from payment processors and claims systems facing operational resilience mandates.
- Retail Enterprises:E-commerce platforms validating peak-load capacity during seasonal demand spikes.
Revenue concentrates with Financial Institutions; expansion is steepest among Software Developers.
Deployment Model:
Data sovereignty requirements and legacy system constraints fragment infrastructure choices, preventing universal cloud migration even where cost efficiency favors it.
- On-Premises:Dedicated hardware installations for institutions with strict data localization requirements. German banks maintain significant on-premise footprints for core banking stress testing where regulatory submission data cannot exit national boundaries.
- Public Cloud:Shared infrastructure with pay-per-use scaling for development and non-production workloads. Limited adoption in EU financial services due to DORA third-party risk management requirements.
- Private Cloud:Single-tenant dedicated environments combining cloud elasticity with controlled access. Gaining share among UK and French banks seeking dedicated infrastructure for regulatory submission workloads.
- Hybrid:Integrated architectures spanning on-premise core systems and cloud-based load injectors. Dominates in regulated sectors where sensitive transaction data remains on-premise while simulation compute scales elastically.
Hybrid architectures capture current deployment volume; Private Cloud is climbing the fastest as banks restructure for compliance.
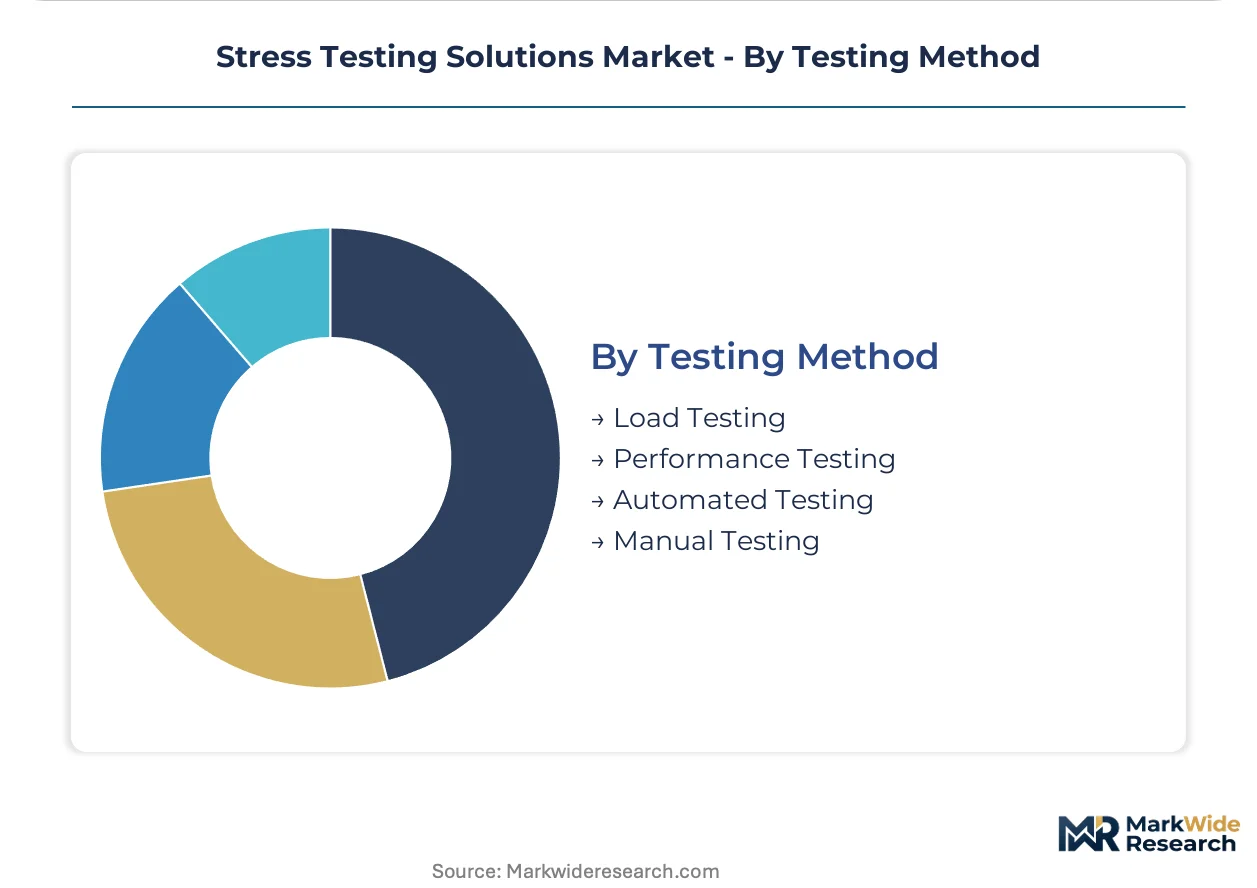
Testing Method:
Technology maturity and labor cost differentials separate automated from manual approaches, with machine learning now displacing human-tuned scenario design.
- Load Testing:Simulated transaction volumes to identify system breaking points under concurrent demand. Essential for payment processors validating capacity before product launches.
- Performance Testing:Latency and throughput measurement under varying conditions. Healthcare claims systems in Germany deploy these methods to ensure response times meet service level agreements.
- Automated Testing:Self-executing scripts with AI-augmented anomaly detection for predictive breaking-point identification. Represents the steepest expansion trajectory as machine learning converges with traditional simulation.
- Manual Testing:Human-directed exploration of edge cases and custom scenario construction. Persists for legacy COBOL-era systems where standard API connectivity remains limited.
Automated Testing is gaining share fastest; Manual Testing retains niche value for legacy integration complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt anchors European demand for stress testing infrastructure as German banks consolidate compliance workloads ahead of enforcement deadlines. Financial institutions across the continent are restructuring procurement around hybrid architectures that satisfy data sovereignty requirements while enabling elastic compute scaling.
Germany
Frankfurt's banking cluster drives premium platform adoption as DORA compliance deadlines compress implementation timelines. BaFin supervisory guidance mandates documented audit trails for all critical IT system validations. Bavarian technology vendors and North Rhine-Westphalian system integrators are expanding delivery capacity to serve accelerated procurement cycles.
United Kingdom
London's financial services concentration sustains demand for regulatory submission automation aligned with Bank of England stress test frameworks. The Prudential Regulation Authority's operational resilience requirements shape vendor certification priorities. Edinburgh and Manchester technology centers are developing specialized scenario libraries for insurance sector applications.
France
Paris-based asset managers and insurers are migrating validation workloads to private cloud instances with dedicated infrastructure for sensitive data. Autorité de Contrôle Prudentiel et de Résolution guidelines emphasize third-party risk documentation for cloud-dependent stress testing. Lyon and Toulouse emerging technology clusters are attracting mid-tier bank procurement decisions.
United States
New York's tier-one banks deploy distributed load injector architectures for Federal Reserve CCAR framework compliance. SEC cybersecurity disclosure rules elevate documentation requirements for resilience validation workflows. Chicago and San Francisco technology procurement teams are embedding continuous monitoring into development pipelines.
India
Mumbai's financial institutions are adopting SaaS delivery models for faster deployment of stress testing capabilities. Reserve Bank of India guidelines on operational resilience for systemically important banks create baseline demand. Bangalore and Hyderabad technology services clusters are expanding engineering capacity for hybrid cloud integration projects.
Stress Testing Solutions Market Vendor Landscape
Premium-margin players sit above commodity-margin players across the solution-type dimension, with enterprise software suites commanding annual contract values orders of magnitude above API testing tools. The vendor base organizes into three tiers: mainframe-heritage platforms with hybrid cloud extensions, database-centric optimization specialists, and legacy-system compatibility providers. Consolidation pressure intensifies as financial institutions seek unified platforms over fragmented point solutions. Strategic moves center on pre-certification partnerships with regulatory bodies and vertical integration into compliance-grade logging infrastructure.
Within the mainframe-heritage tier, IBM Corporation and Oracle Corporation exemplify archetypes sustaining pricing power through infrastructure-layer integration. Micro Focus International occupies a position representing legacy-system specialization where modernization budgets exceed greenfield deployment spending. These three anchors demonstrate how vendor origin stories translate into differentiated resilience validation positioning across regulated financial workloads.
| Leading Market Players |
|---|
| IBM Corporation |
| Oracle Corporation |
| Micro Focus International |
| Accenture |
| Capgemini SE |
| Wipro Limited |
| Cognizant Technology Solutions Corporation |
| Akamai Technologies Inc. |
| SAS Institute Inc. |
| Others |
Supply Flow & Price Mechanics
DORA-mandated audit trail requirements in the European Union are forcing vendors to embed compliance-grade logging infrastructure directly into platform architectures, elevating cost structures and compressing margins for providers lacking pre-certified scenario libraries.
Pricing Analysis
Outcome-based pricing anchored to regulatory submission success commands premium positioning in this market. Three-tier pricing structure across enterprise, mid-market SaaS, and developer API tiers separates buyers by compliance documentation depth and load injector scale. Cost compression in the API testing tier is intensifying because open-source substitutes erode commercial pricing power. Mid-tier banks in Southern Europe exhibit highest price sensitivity, while Frankfurt-based tier-one institutions prioritize certification grade over license cost.
Supply Chain Analysis
Engineering talent scarcity in Germany and the United Kingdom constrains deployment velocity for hybrid cloud integration projects. Software development draws from Bangalore, Hyderabad, and Dublin service clusters for load injector customization and scenario library maintenance. Supply chain risk centers on single-source vulnerability for mainframe-compatible middleware components. Distribution runs through system integrators and direct enterprise sales teams with embedded regulatory specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized engineering capacity for legacy-to-cloud integration functions as the binding constraint propping pricing power for incumbent vendors with proven mainframe expertise.
For Market Incumbents: Anticipate consolidation pressure from unified platform demands by accelerating pre-certification partnerships with BaFin and the Prudential Regulation Authority. Invest in backward integration into compliance-grade logging infrastructure to defend margin position against SaaS-native entrants lacking regulatory submission automation capabilities. For New Entrants and Emerging Players: EU DORA in Germany opens a window for mid-market SaaS providers targeting Spanish and Italian banks with faster deployment timelines and subscription pricing. Focus initial penetration on software developer segments embedding API stress testing into CI/CD pipelines, where compliance documentation requirements remain minimal and speed-to-integration drives procurement decisions. For Investors and Strategic Acquirers: The window for entry favors platform vendors with hybrid cloud deployment capabilities and established regulatory template libraries. Target acquisition archetypes include legacy-system compatibility specialists serving COBOL-era core banking platforms, where modernization budgets exceed greenfield deployment spending. Watch for supervisor template update velocity as an inflection indicator for scenario library provider compliance lag.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Pre-Certification Partnership | BaFin and PRA alignment accelerates procurement cycles for enterprise platforms. |
| Hybrid Cloud Platform Integration | Frankfurt banks demand elastic load injector scaling with on-premise data sovereignty. |
| AI-Augmented Anomaly Detection Launch | Machine learning convergence enables predictive breaking-point identification. |
| Legacy Middleware Acquisition | COBOL-era system connectivity commands premium pricing in modernization cycles. |
| Geographic Expansion to Private Cloud Hubs | Paris and London financial centers seek dedicated infrastructure for regulatory workloads. |
Methodological Framework
Document review covered regulatory filings from BaFin, the Prudential Regulation Authority, and the Federal Reserve, complemented by interviews with CTOs at tier-one banks, IT procurement officers at mid-tier institutions, platform engineers at cloud service providers, and integration specialists at system integrators. Secondary validation drew from SEC 10-K disclosures, EBA stress test documentation, and hyperscaler capex reports. Bottom-up deployment estimates and top-down market sizing were triangulated for consistency.
Segmentation outputs across solution type, end user, deployment model, and testing method were modeled throughout the forecast period. CAGRs were derived from elasticity-adjusted adoption curves and regulatory deadline impacts. Industry-specific inputs included DORA compliance timeline compression effects and mainframe modernization budget trajectories.
Caveats apply where supervisor template update velocity or cross-border data localization rule divergence could materially shift the outlook. Forecasts reflect assumptions about regulatory enforcement consistency and hybrid cloud migration pace. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Risk Management and Compliance
Risk-Based Monitoring Software Market
Risk Management and Compliance
Europe Sustainable Finance Market
Risk Management and Compliance
Treasury and Risk Management Market
Risk Management and Compliance
Operational Risk Management Consulting Services in Manufacturing Market
Risk Management and Compliance
Europe Strategy Consulting Market
Risk Management and Compliance
Crypto Compliance Software Market
Risk Management and Compliance
Compliance As a Service Market
Risk Management and Compliance
Europe Risk Management Market
Risk Management and Compliance
United States Strategic Consulting Services Market
Risk Management and Compliance
Enterprise Governance, Risk, and Compliance (Egrc) Market
Risk Management and Compliance
Legal Advisory Service Market
Risk Management and Compliance
Loan Compliance Management Software Market
Risk Management and Compliance
Treasury and Risk Management Application Market
Risk Management and Compliance
Global Regulatory Reporting and Compliance Market
Risk Management and Compliance
Asset Liability Management (ALM) Solution Market
Risk Management and Compliance
Certificates Market