
 France Disposal Tableware Market | 2026-2036
France Disposal Tableware Market Size, Share, and Industry Trends Forecast 2026-2036
France Disposal Tableware Market Foresight
Plant-based polymer formulation is rewriting material specifications across the France disposal tableware supply chain, pushing converters away from fossil-derived resins toward fermented starch and cellulose feedstocks. Guillin anchors European thermoforming capacity from its Normandy operations, sustaining long production runs for retail-ready PLA trays. FLO Europe SAS dominates institutional catering channels through direct distribution contracts with French hospital and school food service networks.
France disposal tableware encompasses single-use serving vessels and utensils engineered from molded pulp, extruded biopolymers, or pressed agricultural residues, designed to withstand temperatures between 40°C and 120°C depending on end-use, then degrade through industrial composting or anaerobic digestion. Disposable cups lead volume throughput in the product type category, driven by espresso and beverage consumption patterns in French cafés and corporate break rooms, while bagasse and bamboo materials within the material category capture expanding margin pools as brand owners seek differentiation through FSC and OK Compost certifications. Wholesale suppliers channel the majority of tonnage to food service providers, though online retailers are gaining traction among smaller event management operators seeking flexible batch sizes.
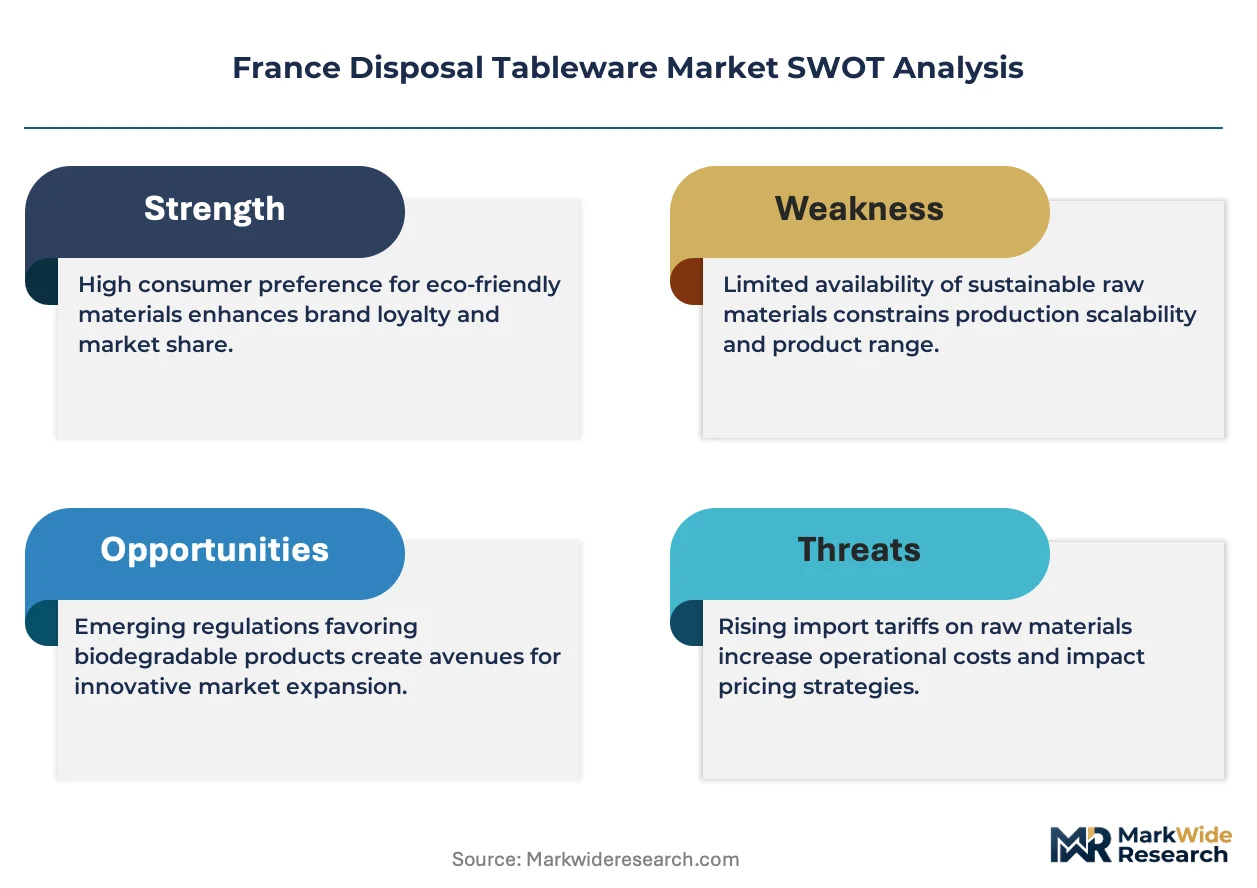
France's AGEC anti-waste legislation and the EU Single-Use Plastics Directive, enforced by the national environmental agency and DGCCRF, prohibit certain plastic items and mandate extended producer responsibility fees that reshape cost structures for importers and domestic molders alike. ANSES evaluates food contact safety for novel biopolymer compositions, adding a technical gate that filters out uncertified Asian suppliers. Stakeholders must track pending revisions to France's sorting and composting infrastructure standards, as industrial compostability claims require verified end-of-life pathways to maintain consumer trust and regulatory compliance.
Market Dynamics
France's AGEC anti-waste law and the EU Single-Use Plastics Directive are compressing the addressable market for fossil-based serviceware while redirecting procurement budgets toward certified compostable alternatives. This regulatory pressure is the dominant structural force reshaping material specifications, supplier qualification criteria, and end-of-life infrastructure investments across the French disposable tableware value chain.
Growth Catalysts
- AGEC mandate sequence:France's national anti-waste law prohibits single-use plastic plates, cups, and cutlery in stages, compelling food service operators to source bagasse and PLA alternatives. Hospital and school catering networks must comply by fixed deadlines, creating predictable replacement demand.
- Industrial composting infrastructure:Expansion of anaerobic digestion capacity in Île-de-France and Auvergne-Rhône-Alpes validates end-of-life claims for certified products. Municipal sorting rules now accept OK Compost-labeled items, closing the loop for operators seeking regulatory compliance.
- Quick-service restaurant conversion:Chains across Paris, Lyon, and Marseille are executing fleet-wide plastic-to-biopolymer transitions. These operators prioritize thermoformed PLA trays and bagasse clamshells for hot-food applications above 100°C.
Market Restraints
- Feedstock cost volatility:Corn starch and sugarcane bagasse prices fluctuate with agricultural commodity cycles, compressing margins for converters locked into fixed-price institutional contracts. This input instability disadvantages biopolymer producers against fossil-resin competitors with more hedged supply chains.
- Asian import dependency:Uncertified molded pulp and PLA injection-molded utensils from low-cost manufacturing clusters dominate spot-market supply. DGCCRF enforcement actions against non-compliant imports create supply disruption risk for distributors lacking qualified domestic alternatives.
- Performance ceiling in high-heat applications:PLA softens above 60°C without crystallization treatment, limiting penetration into soup and hot-beverage segments where polypropylene previously dominated. Technical gaps in microwave-safe biopolymer formulations constrain menu flexibility for caterers.
Strategic Opportunities
- Provence-Alpes-Côte d'Azur event catering:Festival and wedding markets in Nice and Marseille remain underserved by certified compostable suppliers. Seasonal demand spikes for premium bamboo and palm-leaf tableware create margin expansion potential for regional distributors with flexible batch capabilities.
- Extended producer responsibility fee optimization:France's Citeo eco-modulation system rewards products with verified compostability through reduced financial contributions. Manufacturers can capture fee differentials by engineering formulations that exceed baseline recycling targets.
- Digital wholesale platforms:Online procurement channels are fragmenting buyer-seller relationships historically controlled by broadline distributors. Smaller hospitality operators in secondary cities now access direct-from-converter pricing without minimum order quantity constraints.
Industry Challenges
- ANSES food contact certification timelines:Novel biopolymer compositions require 12-18 month safety evaluations before market authorization. Development pipelines stall when formulation iterations trigger re-submission protocols, delaying revenue recognition for innovative material suppliers.
- Composting facility acceptance variance:Industrial composters in different French regions apply divergent sorting criteria for bioplastic contamination thresholds. Product labeled as industrially compostable in Normandy may face rejection in Occitania, complicating national distribution strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Disposal Tableware Market |
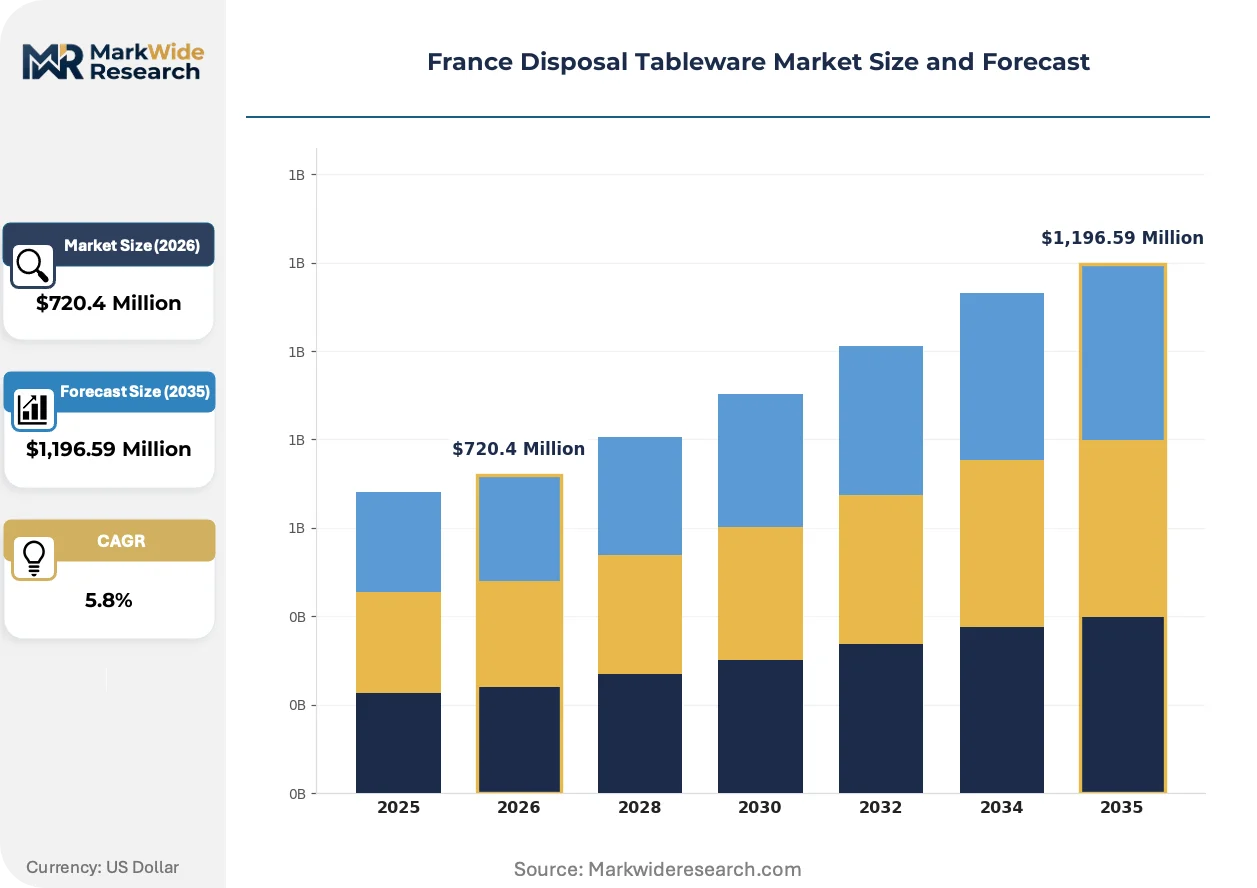
| Market Size in 2026 | $720.4 Million |
| Market Size in 2035 | $1,196.59 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable Plates, Disposable Cups, Disposable Cutlery, Disposable Bowls, Napkins Material: Plastic, Paper, Biodegradable PLA, Bamboo, Bagasse End User: Food Service Providers, Event Management, Cafeterias, Street Vendors Distribution Channel: Supermarkets, Online Retailers, Wholesale Suppliers, Specialty Stores |
| Companies Covered | Melitta France, Fetez-Moi, Guillin, Prosaveurs, Espirit Planete, Marcojea Production, FLO Europe SAS, PAPSTAR, Dart Container Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Disposal Tableware Market Shifts & Advancements
Material science breakthroughs and enforcement tightening of France's anti-waste framework are converging to redefine performance benchmarks and procurement criteria across the disposable tableware sector. These developments are compressing product development cycles and redrawing competitive boundaries between incumbent converters and specialized biopolymer formulators.
Thermoformed crystallized PLA (C-PLA) is rendering obsolete conventional amorphous PLA in hot-food applications requiring dimensional stability above 80°C. Quick-service chains in Paris and Lyon are adopting C-PLA clamshells and bowls for fried and sauced menu items previously served in expanded polystyrene. This thermal performance leap is enabling full material substitution across the temperature range of French fast-casual cuisine without menu engineering compromises.
France's AGEC law and its implementing decrees are mandating phased elimination of plastic-stemmed cotton swabs, stirrers, and cutlery with enforcement delegated to DGCCRF and regional prefectures. Penalty structures and extended producer responsibility fee modulation are accelerating compliance investments by importers and domestic molders. The institutional catering channel faces the most compressed transition timeline, driving concentrated demand for bagasse and wooden alternatives in hospital and school food service networks.
Certification-driven specification is replacing price-first procurement in French food service purchasing decisions. Buyers now require OK Compost INDUSTRIAL or HOME labels before contract award, filtering out uncertified Asian suppliers regardless of unit cost advantage. This behavioral pivot is most pronounced in corporate catering and premium event management segments where brand reputation risk from greenwashing allegations outweighs procurement savings.
France Disposal Tableware Market Segmentation
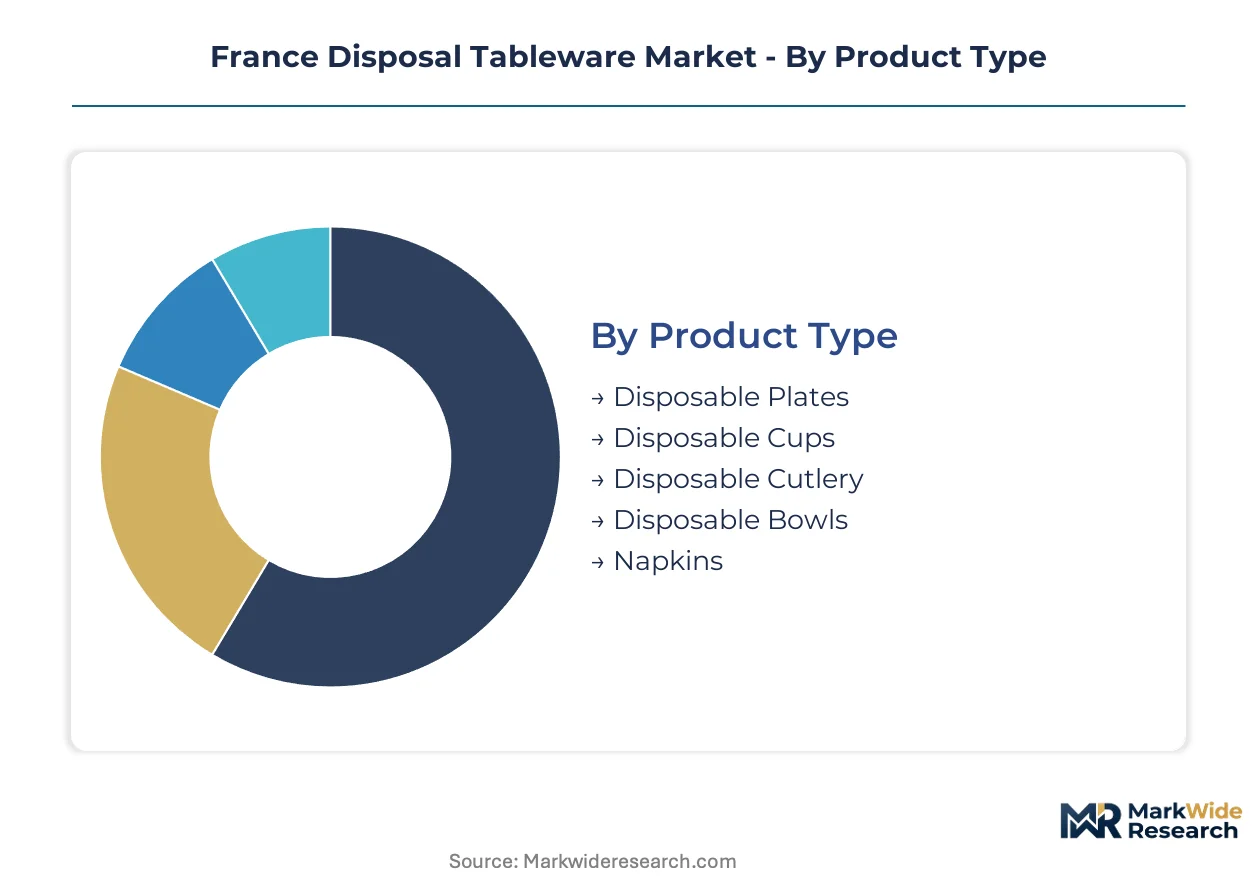
Segmentation in the France disposal tableware market reveals how regulatory pressure and end-use performance requirements split procurement behavior across material grades and distribution pathways. Buyers sort products by compostability certification, temperature tolerance, and channel accessibility rather than unit cost alone.
Product Type:
Mature formats dominate volume flows while emerging designs capture premium positioning in regulated channels.
- Disposable Cups:Engineered from extruded PLA or coated paperboard with heat-sealed rims, these vessels withstand espresso service temperatures. Parisian cafés and corporate break rooms in Île-de-France drive concentrated procurement of certified compostable variants.
- Disposable Plates:Molded pulp and bagasse compositions form the bulk of institutional catering procurement. Hospital and school food service networks under AGEC compliance deadlines specify these for hot-meal delivery.
- Disposable Cutlery:Wooden and CPLA alternatives replace banned plastic stems in quick-service applications.
- Disposable Bowls:Crystallized PLA formulations enable soup and sauced menu items above 80°C.
- Napkins:Recycled fiber grades serve high-volume event catering with minimal certification overhead.
Disposable cups retain volume leadership; disposable bowls hold the steepest expansion curve.
Material:
Cost tiers separate fossil-derived feedstocks from agricultural residue and fermented starch alternatives.
- Bagasse:Pressed sugarcane fiber delivers structural rigidity for clamshells and plates above 120°C. Quick-service chains in Lyon and Marseille specify bagasse for fried food applications requiring grease resistance and industrial compostability.
- Biodegradable PLA:Crystallized grades overcome thermal limitations of amorphous formulations. Thermoformed trays from Normandy converters serve retail-ready meal segments with verified OK Compost INDUSTRIAL certification.
- Bamboo:Premium event catering in Provence-Alpes-Côte d'Azur favors this material for aesthetic differentiation.
- Paper:Coated grades retain share in cold-beverage and limited-heat applications.
- Plastic:Declining share confined to non-regulated specialty applications and legacy inventory.
Bagasse retains volume leadership; biodegradable PLA holds the steepest expansion curve.
End User:
Customer type determines certification stringency and batch size requirements across the procurement spectrum.
- Food Service Providers:Hospital and school catering networks face compressed AGEC compliance timelines. Direct distribution contracts with converters lock in bagasse and wooden alternatives through multi-year procurement agreements.
- Event Management:Festival and wedding operators in Nice and Marseille seek flexible batch sizes with premium bamboo and palm-leaf aesthetics. Seasonal demand spikes favor distributors with digital wholesale platforms.
- Cafeterias:Corporate and institutional break rooms prioritize cost-competitive PLA cups with compostable certification.
- Street Vendors:Price-sensitive spot purchasing concentrates in unregulated segments with limited certification requirements.
Food service providers retain volume leadership; event management holds the steepest expansion curve.
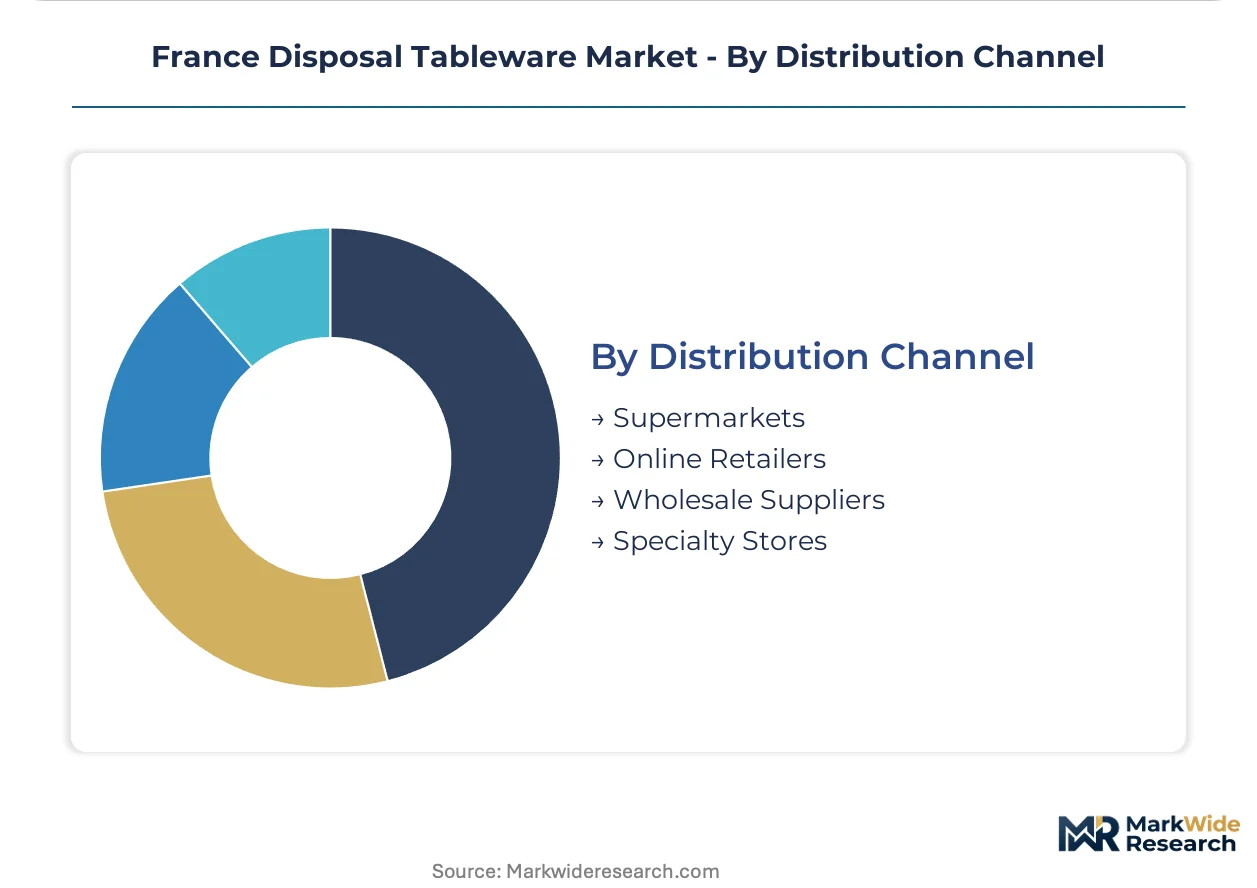
Distribution Channel:
Supply concentration varies between broadline incumbents and fragmenting digital entrants.
- Wholesale Suppliers:Broadline distributors channel majority tonnage to institutional buyers with established logistics networks. Long-term contracts with Normandy converters secure capacity for retail-ready PLA tray production runs.
- Online Retailers:Digital platforms fragment buyer-seller relationships historically controlled by distributors. Smaller hospitality operators in secondary cities access direct-from-converter pricing without minimum order quantity constraints.
- Supermarkets:Retail shelf space captures consumer-facing picnic and home entertaining segments.
- Specialty Stores:Premium compostable certifications target eco-conscious household procurement.
Wholesale suppliers retain volume leadership; online retailers hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spanish converters supply bagasse tableware to French distributors serving Mediterranean catering networks, while Belgian thermoformers export crystallized PLA trays to Parisian retail chains. This cross-border trade flow intensifies as AGEC compliance deadlines compress domestic French production capacity.
Île-de-France
Parisian quick-service chains and corporate catering networks drive concentrated procurement of certified compostable cups and trays. ANSM and DGCCRF enforcement actions against non-compliant imports filter supplier qualification. Thermoforming operations in the greater Paris basin anchor European PLA tray production for retail-ready meal segments.
Auvergne-Rhône-Alpes
Lyon's hospital and school food service networks face compressed AGEC transition timelines for plate and cutlery replacement. The region's expanding anaerobic digestion infrastructure validates OK Compost INDUSTRIAL claims for bagasse products. Industrial composting facilities in Grenoble and Saint-Étienne accept certified biowaste from institutional catering operations.
Provence-Alpes-Côte d'Azur
Festival and wedding markets in Nice and Marseille generate seasonal demand spikes for premium bamboo and palm-leaf tableware. Event management operators seek flexible batch sizes through digital wholesale platforms. The region's tourism density creates concentrated procurement pull for aesthetically differentiated compostable serviceware.
Hauts-de-France
Dunkirk and Calais logistics corridors channel imported molded pulp from Belgian and Dutch suppliers to French institutional buyers. The region's port infrastructure positions it as a distribution gateway for bagasse products entering from Asian manufacturing clusters. Municipal waste sorting rules in Lille metropolitan area enforce strict contamination thresholds for compostable claims.
Occitanie
Toulouse and Montpellier food service operators navigate divergent composting facility acceptance criteria for bioplastic contamination. The region's agricultural base supplies residual fiber feedstocks to local molded pulp converters. Industrial composters in the territory apply variable sorting protocols that complicate national distribution strategies for certified tableware.
France Disposal Tableware Market Competitive Landscape
On the supply side, the industry is structured around three distinct capability tiers. Large-scale thermoformers with integrated compounding operations occupy the top tier, serving retail and institutional channels with long production runs. Mid-sized converters specializing in agricultural residue molding sit in the middle tier, supplying bagasse and bamboo formats to event catering and quick-service segments. Import-dependent distributors without manufacturing assets form the bottom tier, competing on spot pricing for uncertified Asian supply. Consolidation pressure is accelerating through converter-processor partnerships and capacity expansion in Normandy thermoforming clusters.
Within the integrated thermoforming tier, Guillin anchors European production capacity from its Normandy operations. FLO Europe SAS occupies a position in institutional catering distribution through direct contracts with hospital and school networks. Among specialty converters, Marcojea Production exemplifies the agricultural residue molding archetype serving premium event segments. These three players represent the dominant competitive positioning vectors: scale-driven manufacturing, channel-locked distribution, and specialty material differentiation.
| Leading Market Players |
|---|
| Melitta France |
| Fetez-Moi |
| Guillin |
| Prosaveurs |
| Espirit Planete |
| Marcojea Production |
| FLO Europe SAS |
| PAPSTAR |
| Dart Container Corporation |
| Others |
Supply & Pricing Matrix
Dunkirk-Calais freight corridors channel imported molded pulp from Belgian thermoformers and Dutch bagasse converters into French institutional procurement networks, with logistics cost differentials creating three distinct pricing tiers that separate premium certified compostable products from uncertified Asian spot supply.
Pricing Analysis
Crystallized PLA commands a 40-60% premium over conventional amorphous grades due to thermal performance above 80°C, while bagasse clamshells price between these tiers based on grease resistance and OK Compost certification status. Price differentiation hinges on certification grade and volume scale, with hospital networks locking multi-year contracts at standard-tier rates while event operators pay premium for flexible batch sizes. Cost compression in the economy tier intensifies as DGCCRF enforcement actions against non-compliant imports disrupt spot-market supply. Street vendors and small caterers exhibit highest price sensitivity, whereas corporate catering buyers prioritize certification compliance over unit cost.
Supply Chain Analysis
Upstream corn starch and sugarcane bagasse feedstock supply draws from agricultural regions in Brazil, Thailand, and domestic French cereal production, with biopolymer resin compounding concentrated in Belgium and the Netherlands. Raw material dependencies include fermented starch polymers, pressed agricultural fibers, and crystallization additives for heat-resistant grades. Single-source vulnerability runs through Asian molded pulp injection capacity that dominates uncertified utensil supply. Distribution runs through broadline wholesale networks for institutional buyers, while digital platforms fragment procurement relationships for smaller hospitality operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's disposal tableware market is entering a cyclical recovery phase as AGEC compliance deadlines force replacement demand through institutional channels, with the regulatory mandate sequence acting as the primary cyclical driver compressing transition timelines for hospital and school networks.
For Market Incumbents: Build certification moats around ANSES food contact approvals and OK Compost INDUSTRIAL labeling to defend against Asian import substitution. Expand thermoforming capacity in Normandy clusters to capture retail-ready PLA tray demand from Parisian quick-service chains. Lock multi-year direct distribution contracts with institutional catering networks before AGEC deadlines concentrate buyer leverage. For New Entrants and Emerging Players: Pursue white-space opportunities in Provence-Alpes-Côte d'Azur event catering, where seasonal demand spikes for premium bamboo and palm-leaf tableware outstrip regional supply flexibility. Target festival and wedding operators in Nice and Marseille through digital wholesale platforms offering batch-size customization without minimum order constraints. Establish go-to-market partnerships with regional distributors possessing established logistics networks. For Investors and Strategic Acquirers: Carve-out targets emerge from food service distribution conglomerates seeking to divest non-core tableware trading operations amid margin compression from regulatory compliance costs. Long-term viability centers on integrated manufacturing assets with captive compounding capabilities and certified compostability credentials. Monitor DGCCRF enforcement action frequency as an inflection indicator for import substitution acceleration and domestic capacity valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Supply | Corn starch and bagasse sourcing from Brazilian and Thai agricultural networks reduces commodity price volatility exposure. |
| OK Compost INDUSTRIAL Certification Investment | TÜV Austria validation enables Citeo eco-modulation fee reductions and hospital network contract eligibility. |
| Digital Wholesale Platform Launch | Direct-to-operator channels bypass broadline distributor markups for event management and smaller hospitality buyers. |
| Crystallized PLA Capacity Expansion | |
| Regional Distribution Partnership | Collaboration with Île-de-France logistics providers secures last-mile delivery for Parisian corporate catering networks. |
Research Methodology
Initial hypotheses were tested against primary input from thermoforming plant managers, institutional catering procurement directors, DGCCRF regulatory enforcement officers, and biopolymer R&D leads, then refined through secondary validation against customs trade data, ANSES food contact safety filings, Citeo eco-modulation fee schedules, and EU Single-Use Plastics Directive implementation decrees. Bottom-up volume estimates from converter production runs were triangulated with top-down demand modeling across food service, event management, and retail channels.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon, with segmentation modeled by material grade, product format, end-user channel, and composting infrastructure availability by French region. CAGRs were derived from replacement cycle analysis of AGEC-mandated plastic phase-outs and penetration curve modeling for crystallized PLA in hot-food applications. Forecast inputs incorporated anaerobic digestion capacity expansion timelines and DGCCRF enforcement intensity assumptions.
Sensitivities concentrate around ANSES certification timeline delays, composting facility acceptance variance across French regions, and feedstock commodity price volatility. Forecasts reflect documented assumptions on regulatory enforcement consistency and infrastructure buildout schedules. Cross-checking against Citeo packaging waste recovery data and regional prefecture compliance reporting is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Foodservice Packaging
Food Service Packaging (FSP) Market
Foodservice Packaging
Compostable Food Service Packaging Market
Foodservice Packaging
Compostable Food Service Tray Market
Foodservice Packaging
Foodservice Paper Bags Market
Foodservice Packaging
United States Disposable Tableware Market
Foodservice Packaging
North America Foodservice Packaging Market
Foodservice Packaging
Foodservice Disposable Packaging Market
Foodservice Packaging
Bar and Prep Faucets Market
Foodservice Packaging
Italy Disposable Tableware Market
Foodservice Packaging
Canada Foodservice Packaging Market