
 Bar and Prep Faucets Market | 2026-2036
Bar and Prep Faucets Market Size, Share, and Industry Trends Forecast 2026-2036
Bar and Prep Faucets Market Outlook
EPA WaterSense specifications is broadening the addressable market for low-flow bar and prep faucets as builders and remodelers face tightened municipal plumbing codes. Kohler Co. leverages its captive foundry network to control stainless steel supply for pull-down configurations. Moen Incorporated anchors North American distribution through exclusive big-box retail partnerships. Grohe AG differentiates through German-engineered ceramic disc cartridge technology that extends product lifecycle ratings.
Bar and prep faucets are compact secondary sink fixtures engineered for food preparation and beverage service, typically mounting on smaller basins with spout clearances between 6 and 12 inches and flow rates calibrated to meet local water efficiency thresholds. Pull-down faucets lead residential specification due to hose-retract mechanisms that maximize utility in constrained counter spaces, while touchless installation types capture growing commercial and hospitality share where hygiene protocols drive capital planning. Stainless steel dominates material selection for its corrosion resistance in high-moisture environments, though bronze finishes command margin premiums in design-forward residential segments.
EPA WaterSense, California Energy Commission Title 20, and EU Ecodesign Directive frame compliance thresholds that manufacturers must satisfy for market access across major economies. The EU Green Deal's embedded carbon tracking requirements are beginning to shape sourcing decisions for brass and zinc alloy components. Stakeholders must monitor evolving state-level plumbing codes and building electrification mandates that could redefine installation specifications and channel priorities.
Market Dynamics
WaterSense certification mandates and comparable efficiency standards across Germany and Japan are compressing product development cycles while forcing foundry and ceramic cartridge suppliers to synchronize compliance roadmaps.
Growth Catalysts
- EPA WaterSense thresholds:Municipal plumbing code tightening in United States metropolitan markets is expanding specification volume for low-flow bar and prep configurations.
- Residential kitchen renovations:North American housing stock turnover is accelerating fixture replacement cycles in secondary sink installations.
- Stainless steel foundry capacity:Captive metal supply networks are stabilizing input costs for pull-down faucet manufacturers serving high-volume channels.
Market Restraints
- Brass and zinc alloy sourcing:EU Green Deal embedded carbon tracking requirements are elevating compliance costs for European component suppliers.
- Ceramic disc cartridge concentration:German-engineered valve technology remains concentrated among limited precision manufacturers, creating supply bottlenecks.
- California Title 20 friction:State-level efficiency mandates exceed federal baselines, fragmenting product SKUs and inventory requirements for national distributors.
Strategic Opportunities
- Japanese compact residential retrofits:Space-constrained urban housing stock is driving specification of 6-inch spout clearance configurations with integrated hose-retract mechanisms.
- Touchless technology convergence:Sensor-activated flow control is penetrating hospitality and commercial foodservice segments where hygiene protocols govern capital allocation.
- Building electrification mandates:Emerging state-level installation specifications are creating first-mover advantage for electrically compatible faucet configurations in new construction.
Industry Challenges
- WaterSense certification timelines:EPA testing and verification protocols extend product launch windows, compressing revenue recognition for seasonal product cycles.
- Multi-jurisdiction compliance engineering:Simultaneous satisfaction of EPA, EU Ecodesign, and JIS standards requires parallel development tracks, straining R&D bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bar and Prep Faucets Market |
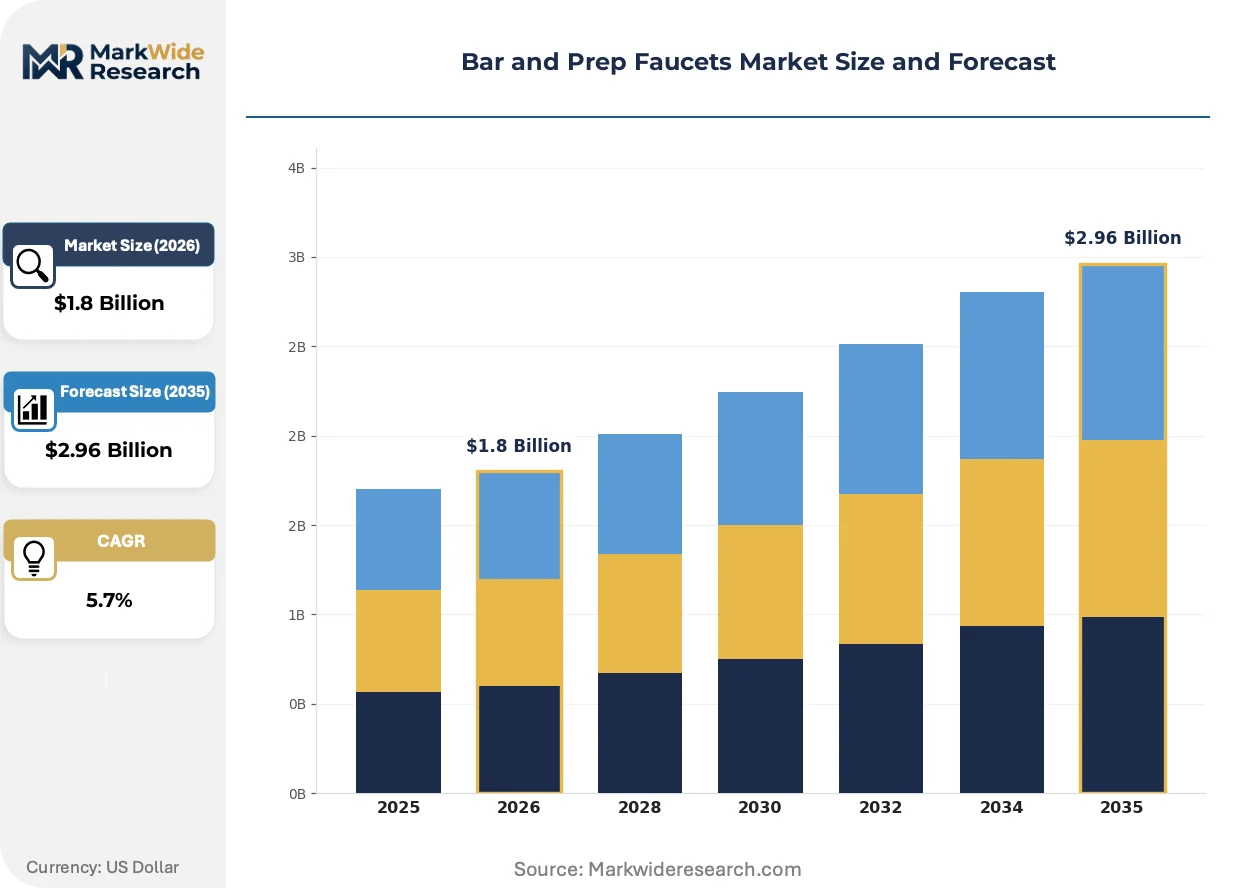
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pull-Down Faucets, Pull-Out Faucets, Wall-Mounted Faucets, Single Handle Faucets Material: Stainless Steel, Chrome, Bronze, Plastic Installation Type: Deck Mount, Wall Mount, Touchless, Countertop End User: Residential, Commercial, Industrial, Hospitality |
| Companies Covered | Kohler Co., Moen Incorporated, Delta Faucet Company, Grohe AG, Hansgrohe SE, American Standard Brands, Fortune Brands Innovations, LIXIL Group, Masco Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bar and Prep Faucets Market Strategic Shifts
Touchless sensor integration, ceramic cartridge precision engineering, and bronze finish differentiation are compressing traditional mechanical faucet architectures while opening premium positioning corridors.
Touchless flow activation is consolidating around infrared and capacitive sensor modules that eliminate manual handle contact. Hospitality operators and commercial kitchen specifiers are adopting these configurations at accelerated pace to satisfy HACCP-aligned hygiene protocols. The technology is consolidating specification authority away from traditional mechanical suppliers toward sensor-embedded system integrators.
EU Ecodesign Directive efficiency thresholds are tightening allowable flow-rate ranges for kitchen fixtures entering European markets. Manufacturers must redesign internal waterways and aerator geometries to maintain functional performance at reduced liter-per-minute outputs. German kitchen manufacturing clusters are responding fastest, leveraging existing ceramic disc valve precision to maintain user experience at mandated conservation levels.
Specification behavior is rotating toward finish-driven selection criteria as stainless steel commoditization erodes margin at volume tiers. Design-forward residential buyers are prioritizing oil-rubbed bronze and matte black PVD coatings, forcing distributors to expand SKU breadth and inventory carrying costs. This preference shift is most visible in North American metropolitan renovation markets where visual coordination with cabinetry hardware governs purchase decisions.
Bar and Prep Faucets Market Segmentation
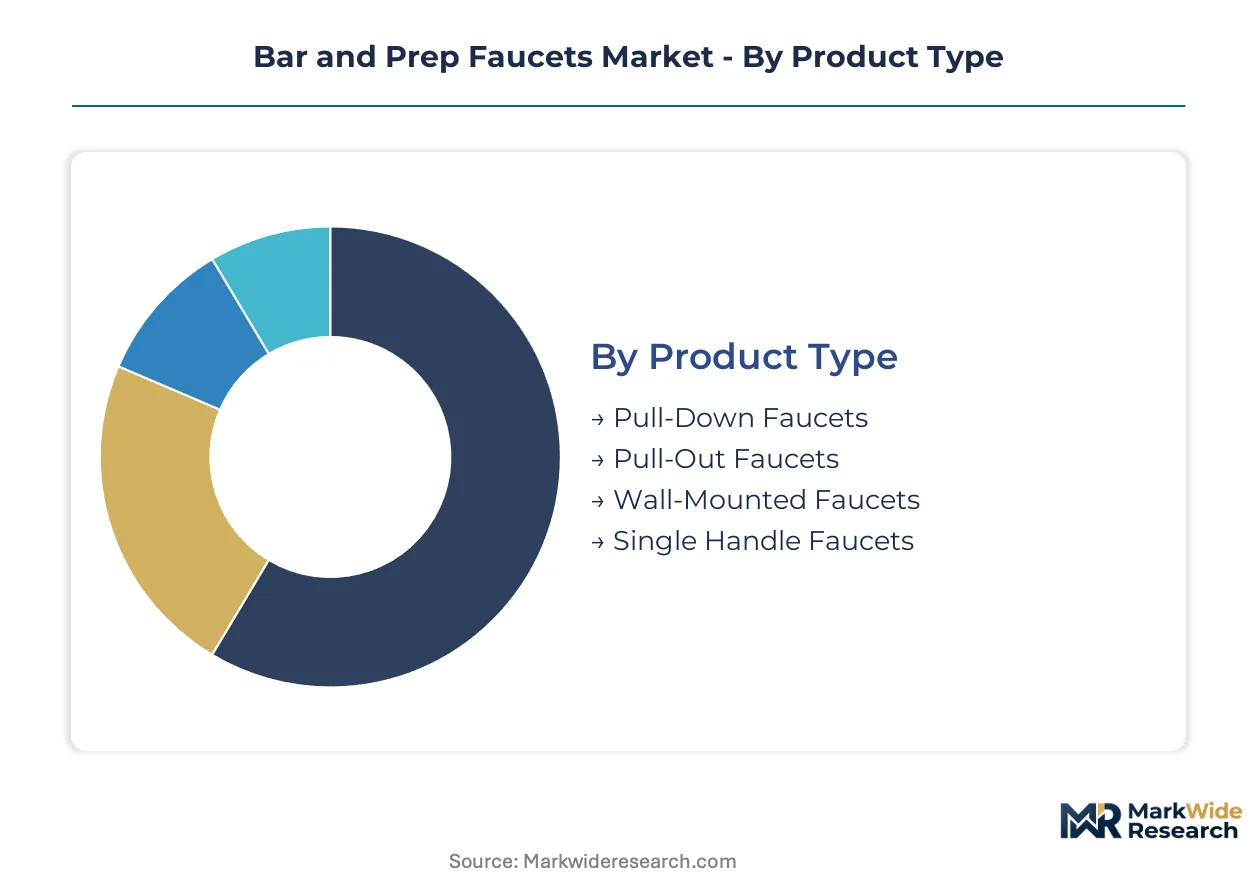
Bar and prep faucet procurement decisions cascade through four distinct lenses: fixture mechanics, material durability, mounting architecture, and end-use environment. Each segmentation axis carries divergent tooling costs, certification burdens, and channel requirements that reshape manufacturer resource allocation.
Product Type:
Capital intensity peaks with pull-down mechanisms requiring precision hose-retract engineering and multi-part injection molding for counterweight systems.
- Pull-Down Faucets:Hose-retract mechanisms with magnetic or spring-loaded docking systems dominate residential kitchen renovations. North American metropolitan housing markets specify these for secondary sink installations where counter depth constraints limit lateral spout movement. EPA WaterSense certification timelines extend development cycles for these complex assemblies.
- Pull-Out Faucets:Shorter hose travel suits compact basins prevalent in Japanese urban residential retrofits. German kitchen manufacturing clusters favor these configurations for integrated sink systems where spout clearance must remain below 8 inches.
- Wall-Mounted Faucets:Concealed rough-in plumbing elevates installation labor costs and requires coordination with framing trades.
- Single Handle Faucets:Simplified cartridge architecture reduces foundry complexity and accelerates municipal code compliance testing.
Pull-down configurations absorb the bulk of installed capacity; touchless-enabled pull-out variants are expanding most quickly in commercial foodservice specifications.
Material:
Raw material selection governs corrosion resistance thresholds, finishing line capital requirements, and margin architecture across distribution tiers.
- Stainless Steel:Austenitic 304-grade dominates high-moisture environments for its chromium-nickel corrosion resistance. Captive foundry networks in the United States stabilize input costs for volume manufacturers serving big-box retail channels. EU Green Deal embedded carbon tracking is elevating compliance documentation burdens for European stainless suppliers.
- Chrome:Electroplated finishes over brass substrates balance cost efficiency with aesthetic durability in mid-market residential segments.
- Bronze:Oil-rubbed and living finishes command margin premiums in design-forward renovation markets where visual coordination with cabinetry hardware governs selection.
- Plastic:Polymer composites reduce unit weight and enable snap-fit assembly for economy-tier temporary installations.
Stainless steel commands the greatest production volume; bronze finishes are climbing the fastest as finish-driven specification behavior rotates toward premium aesthetics.
Installation Type:
Mounting architecture determines rough-in coordination requirements, aftermarket replacement difficulty, and electrification compatibility for emerging building codes.
- Deck Mount:Standard 1-3 hole configurations accommodate most residential sink decks and simplify retrofit replacement. California Title 20 efficiency mandates fragment SKU requirements for national distributors serving this mainstream segment.
- Wall Mount:Requires concealed valve bodies and structural backing that elevate upfront plumbing costs.
- Touchless:Infrared and capacitive sensor modules eliminate manual contact, consolidating specification authority among system integrators. Hospitality operators adopt these at accelerated pace to satisfy HACCP-aligned hygiene protocols.
- Countertop:Vessel sink pairings in commercial restroom and bar applications demand elevated spout clearances.
Deck mount retains the deepest installed base; touchless systems are gaining share fastest as hygiene protocols penetrate foodservice capital planning.
End User:
Demand concentration varies sharply by procurement authority, replacement cycle velocity, and specification complexity tolerance.
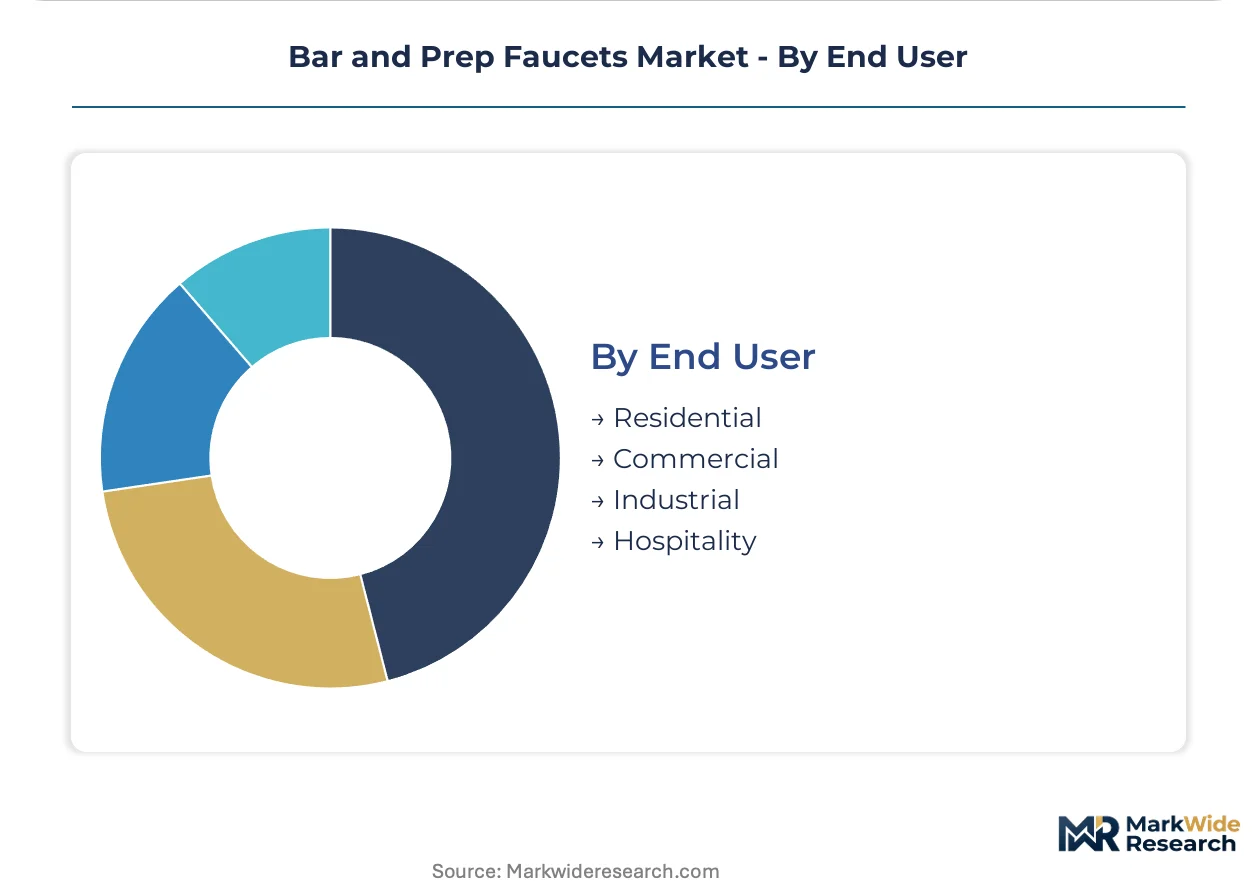
- Residential:Renovation-driven replacement cycles accelerate in North American housing stock turnover, with secondary sink installations prioritizing pull-down utility. Finish coordination with cabinet hardware and appliance suites governs final selection authority.
- Commercial:Foodservice operators prioritize NSF certification and touchless hygiene compliance over aesthetic differentiation.
- Industrial:Heavy-duty brass construction and ceramic disc longevity outweigh conservation metrics in utility and manufacturing settings.
- Hospitality:Brand-standard consistency across property portfolios drives centralized procurement with extended warranty requirements.
Residential renovation absorbs the bulk of unit volume; hospitality specification is expanding most quickly as hotel development rebounds in metropolitan markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metropolitan housing markets in the United States drive the largest share of bar and prep faucet procurement, with kitchen renovation cycles accelerating specification of pull-down configurations. Municipal plumbing code tightening across multiple jurisdictions is fragmenting product requirements and reshaping distribution logistics.
United States
Secondary sink installations in residential renovations absorb the bulk of North American volume, with pull-down mechanisms dominating specification for counter-constrained spaces. EPA WaterSense certification timelines extend product development cycles, compressing seasonal revenue windows for manufacturers. California's Title 20 efficiency mandates exceed federal baselines, forcing distributors to maintain fragmented SKU inventories for national coverage.
Germany
Kitchen manufacturing clusters in the Stuttgart and Düsseldorf corridors specify compact pull-out configurations for integrated sink systems. EU Ecodesign Directive efficiency thresholds are tightening allowable flow-rate ranges, requiring redesigned internal waterways. Ceramic disc valve precision engineering concentrates among specialized component suppliers in the Baden-Württemberg region.
Japan
Tokyo and Osaka metropolitan retrofits prioritize 6-inch spout clearance configurations for space-constrained urban housing. METI efficiency standards and JIS certification requirements shape product development priorities for domestic manufacturers. Compact basin specifications in high-density residential units are driving integrated hose-retract mechanism adoption.
China
Yangtze River Delta manufacturing bases supply stainless steel components for global faucet assembly networks. GB standards and dual carbon goals are elevating documentation requirements for brass and zinc alloy sourcing. Zhejiang and Jiangsu province foundries are consolidating capacity to serve export-oriented fixture manufacturers.
Canada
Toronto and Vancouver housing markets mirror US renovation-driven replacement cycles for secondary sink fixtures. Health Canada and PMRA regulations align with EPA efficiency benchmarks, simplifying cross-border product certification. Ontario-based distributors leverage proximity to US midwestern manufacturing clusters for inventory optimization.
Bar and Prep Faucets Market Competitive Environment
The competitive structure tilts toward diversified fixture conglomerates with captive foundry networks and specialized precision valve engineers. Consolidation among mid-tier brands is compressing pricing bandwidth for standard configurations. Three archetypes dominate: vertically integrated plumbing conglomerates controlling metal supply chains, German-engineered ceramic disc specialists, and Asian-scale manufacturers optimizing for export volume. Capacity expansion in stainless steel foundries and strategic partnerships for sensor module integration represent the primary competitive vectors.
Among North American plumbing conglomerates, Kohler Co., Moen Incorporated, and Delta Faucet Company occupy positions that exemplify the vertically integrated archetype, with geographic naming conventions indicating Wisconsin, Ohio, and Indiana origins respectively. These entities anchor the premium-standard tier through control over upstream metal supply and exclusive retail channel relationships. Grohe AG and Hansgrohe SE represent the German-engineered precision archetype, with AG and SE suffixes indicating public corporate structures. LIXIL Group and Masco Corporation exemplify diversified portfolio approaches spanning multiple fixture categories beyond bar and prep faucets.
| Leading Market Players |
|---|
| Kohler Co. |
| Moen Incorporated |
| Delta Faucet Company |
| Grohe AG |
| Hansgrohe SE |
| American Standard Brands |
| Fortune Brands Innovations |
| LIXIL Group |
| Masco Corporation |
| Others |
Value Chain & Pricing Dynamics
Big-box retail procurement concentration in North America anchors a three-tier pricing structure across premium, standard, and economy levels, with WaterSense certification tiers and finish-grade differentiation determining margin capture. Stainless steel foundry capacity constraints and ceramic cartridge supply bottlenecks feed directly into pricing power distribution between captive metal suppliers and precision valve engineers.
Pricing Analysis
Value-based pricing anchored to WaterSense certification outcomes separates premium-certified configurations from standard-tier alternatives. Price differentiation rests on ceramic disc precision grade and bronze finish PVD coating quality, with hospitality specifiers least sensitive and economy-channel residential renovators most responsive to unit cost. Cost compression in standard-tier pull-down mechanisms intensifies as Asian-scale manufacturers optimize for export volume. Stainless steel commodity exposure and foundry energy costs exert upward pressure on input-side pricing.
Supply Chain Analysis
Trans-Pacific container freight volatility and inland trucking cost inflation are reshaping landed cost calculations for brass and zinc alloy components. Geographic supply concentration centers on China for stainless steel casting, Germany for ceramic disc cartridge precision engineering, and the United States for captive foundry networks serving big-box retail. Raw material dependencies include austenitic 304-grade stainless steel, brass billet for chrome-plated substrates, and sensor module electronics for touchless configurations. Single-source vulnerability in German-engineered valve technology creates procurement risk for pull-down mechanism assemblers. Distribution runs through exclusive big-box retail partnerships and specialized kitchen showroom channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive control over stainless steel foundry networks determines pricing power and supply security. Players are pursuing backward integration into precision ceramic cartridge engineering to escape component bottlenecks.
For Market Incumbents: Lock in exclusive big-box retail shelf space through multi-year category captain agreements before Asian-scale manufacturers achieve WaterSense certification parity. Expand captive foundry capacity in the United States to neutralize stainless steel input cost volatility threatening margin in standard-tier pull-down configurations. For New Entrants and Emerging Players: Capture specification authority in Japanese compact residential retrofits where 6-inch spout clearance configurations remain underserved by incumbent pull-down-focused portfolios. Partner with sensor module integrators to bypass mechanical valve engineering barriers in hospitality touchless segments. For Investors and Strategic Acquirers: The window for entry favors mid-tier fixture brands with established WaterSense certification and regional distribution infrastructure. Acquisition targets should demonstrate ceramic cartridge supply relationships or in-house precision engineering capability. Monitor EPA certification timeline compression as the inflection signal for R&D bandwidth constraints among volume manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Foundry Capacity Expansion | Stabilizes stainless steel input costs against Yangtze River Delta energy price volatility. |
| Ceramic Cartridge Supply Agreement | Secures Baden-Württemberg precision engineering for extended product lifecycle ratings. |
| Touchless Sensor Module Integration | Captures hospitality specification authority under HACCP-aligned hygiene protocols. |
| WaterSense Certification Acceleration | Compresses product launch windows ahead of municipal plumbing code tightening. |
| Bronze Finish PVD Line Investment | Commands margin premiums in North American metropolitan renovation markets. |
Study Parameters
Independent corroboration across primary interviews with kitchen renovation contractors, plumbing fixture procurement managers, and ceramic cartridge engineering specialists, combined with secondary validation of EPA WaterSense certification databases, EU Ecodesign Directive filings, and customs trade data for brass and stainless steel imports, underwrites the qualitative findings. Bottom-up triangulation of distributor inventory cycles and top-down reconciliation with housing renovation expenditure patterns anchor volume estimates.
Rate-of-change decomposition across the analysis window isolates replacement cycle velocity, efficiency mandate compliance thresholds, and finish-driven specification rotation as primary growth determinants. Segmentation modeling incorporates product type mechanics, material durability tiers, installation architecture, and end-use environment procurement authority. CAGRs derive from fitted trend lines applied to verified point estimates, with stainless steel foundry capacity utilization and ceramic cartridge lead times serving as industry-specific forecast inputs.
The model holds under stable municipal plumbing code implementation timelines and continued big-box retail channel dominance; deviation in California Title 20 fragmentation or sensor module supply disruption would shift trajectory. Forecasts reflect documented assumptions regarding housing stock turnover and certification compliance rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Foodservice Packaging
Compostable Food Service Packaging Market
Foodservice Packaging
United States Disposable Tableware Market
Foodservice Packaging
Canada Foodservice Packaging Market
Foodservice Packaging
Italy Disposable Tableware Market
Foodservice Packaging
Food Service Packaging (FSP) Market
Foodservice Packaging
Compostable Food Service Tray Market
Foodservice Packaging
Foodservice Paper Bags Market
Foodservice Packaging
North America Foodservice Packaging Market
Foodservice Packaging
France Disposal Tableware Market
Foodservice Packaging
Foodservice Disposable Packaging Market