
 Food Service Packaging (FSP) Market | 2026-2036
Food Service Packaging (FSP) Market Size, Share, and Industry Trends Forecast 2026-2036
Food Service Packaging (FSP) Market Foresight
Subscription-based packaging replenishment programs for high-volume restaurant chains is recalibrating how suppliers monetize food service relationships. Huhtamaki Oyj leverages its molded fiber technology leadership to anchor European quick service accounts. Sealed Air competes through proprietary barrier film platforms that extend shelf-life performance for prepared meals. Mondi dominates kraft paper-based solutions across Central European cafeteria and catering channels.
Food service packaging encompasses single-use and limited-reuse containers, wraps, and vessels engineered from paperboard, plastics, aluminum foil, or biodegradable films to protect, transport, and present prepared food items while maintaining temperature, hygiene, and portion integrity. Manufacturing employs thermoforming, injection molding, or pressed-pulp processes with specified grease-resistance and moisture-barrier thresholds calibrated to food contact regulations. Paperboard and molded pulp segments lead volume due to brand-driven sustainability commitments and regulatory bans on expanded polystyrene, while biodegradable films represent the fastest-growing material category as enzyme-based and PHA formulations achieve cost parity in premium quick service applications. Clamshells and trays command the largest share of packaging type revenue, though cups and bowls are gaining share through specialty beverage and bowl-format menu expansion across takeaway outlets.
The EU F-Gas Regulation and REACH chemical restrictions constrain fluorinated grease-barrier coatings in paperboard applications, redirecting R&D toward plant-based wax and clay alternatives. FDA food contact substance notifications and state-level extended producer responsibility laws in California and New York shape permissible material compositions and end-of-life accountability for US suppliers. Stakeholders must monitor evolving compostability certification standards across jurisdictions to avoid stranded inventory as municipal organics collection infrastructure scales unevenly.
Market Dynamics
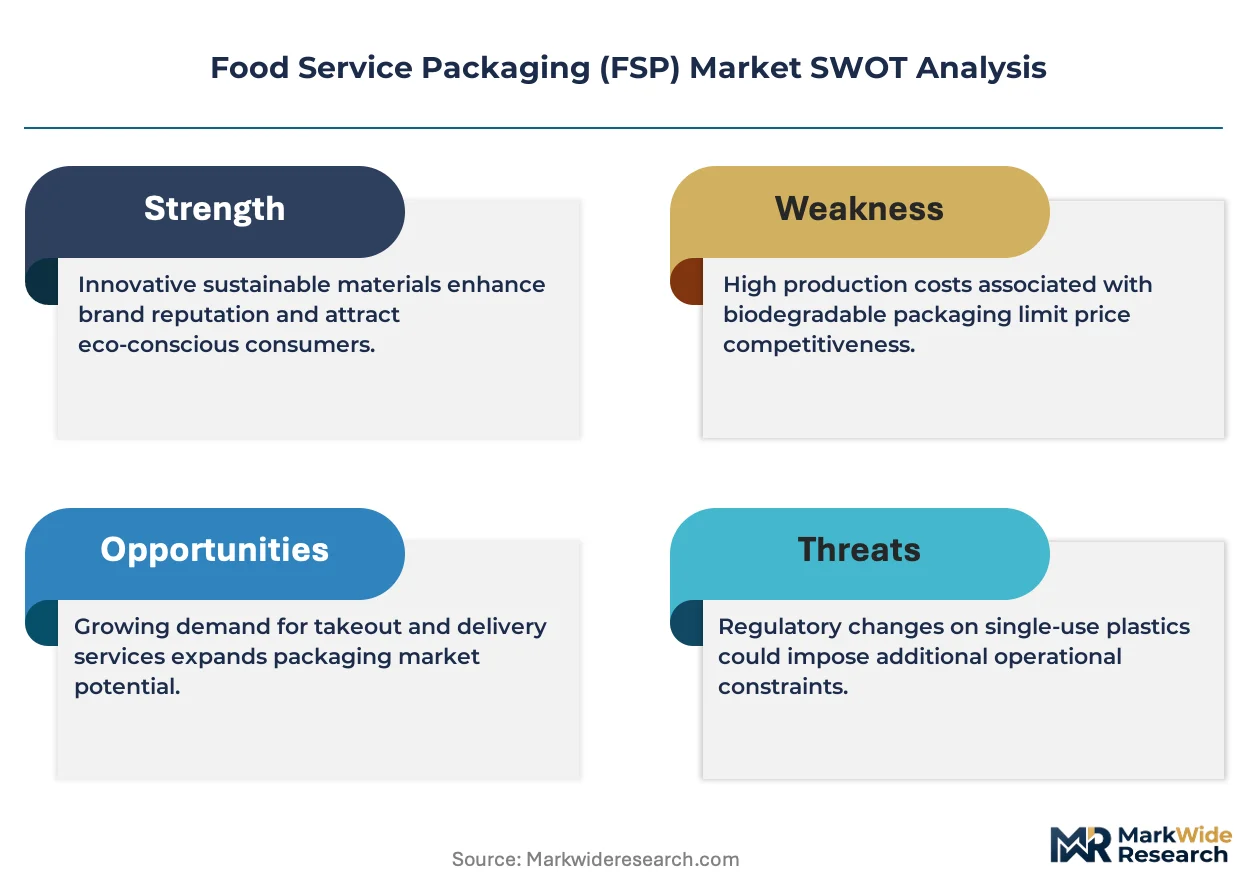
Material substitution mandates across the EU and select US states are compressing polystyrene capacity while redirecting capital toward molded fiber and barrier-coated paperboard platforms.
Growth Catalysts
- EU Single-Use Plastics Directive:Bans on expanded polystyrene food containers accelerate demand for certified compostable alternatives in quick service restaurant networks.
- China food delivery expansion:Cold-chain packaging requirements for premium meal kits and hot-meal preservation are pulling investment into multi-layer insulated solutions.
- Enzyme-based barrier coatings:Plant-derived grease resistance achieving performance parity with fluorinated chemistries unlocks premium pricing in European cafeteria channels.
Market Restraints
- Pulp fiber cost volatility:Nordic softwood supply disruptions and energy-intensive drying processes compress margins for molded fiber tray manufacturers.
- Fluorinated coating phase-out:REACH restrictions on PFAS-based grease barriers strand existing paperboard inventory and force costly formulation pivots.
- Composting infrastructure gaps:Uneven municipal organics collection across German and French regions creates end-of-life uncertainty for biodegradable film investments.
Strategic Opportunities
- Subscription replenishment models:High-volume restaurant chains are shifting from spot purchasing to contracted packaging-as-a-service arrangements with integrated waste recovery.
- India food service modernization:Quick service penetration in Tier-2 cities and airport catering hubs creates first-mover advantage for kraft-based clamshell suppliers.
- PHAs and algal films:Convergence of marine-derived feedstocks with blow-molding equipment adaptations opens thermoformed bowl applications previously locked to petroleum plastics.
Industry Challenges
- Compostability certification fragmentation:Divergent TÜV Austria, BPI, and OK Compost HOME standards across jurisdictions force redundant testing and label complexity.
- Barrier film integration:Lamination of oxygen-scavenging layers with paperboard substrates requires retooling of legacy thermoforming lines and skilled technician scarcity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Service Packaging (FSP) Market |
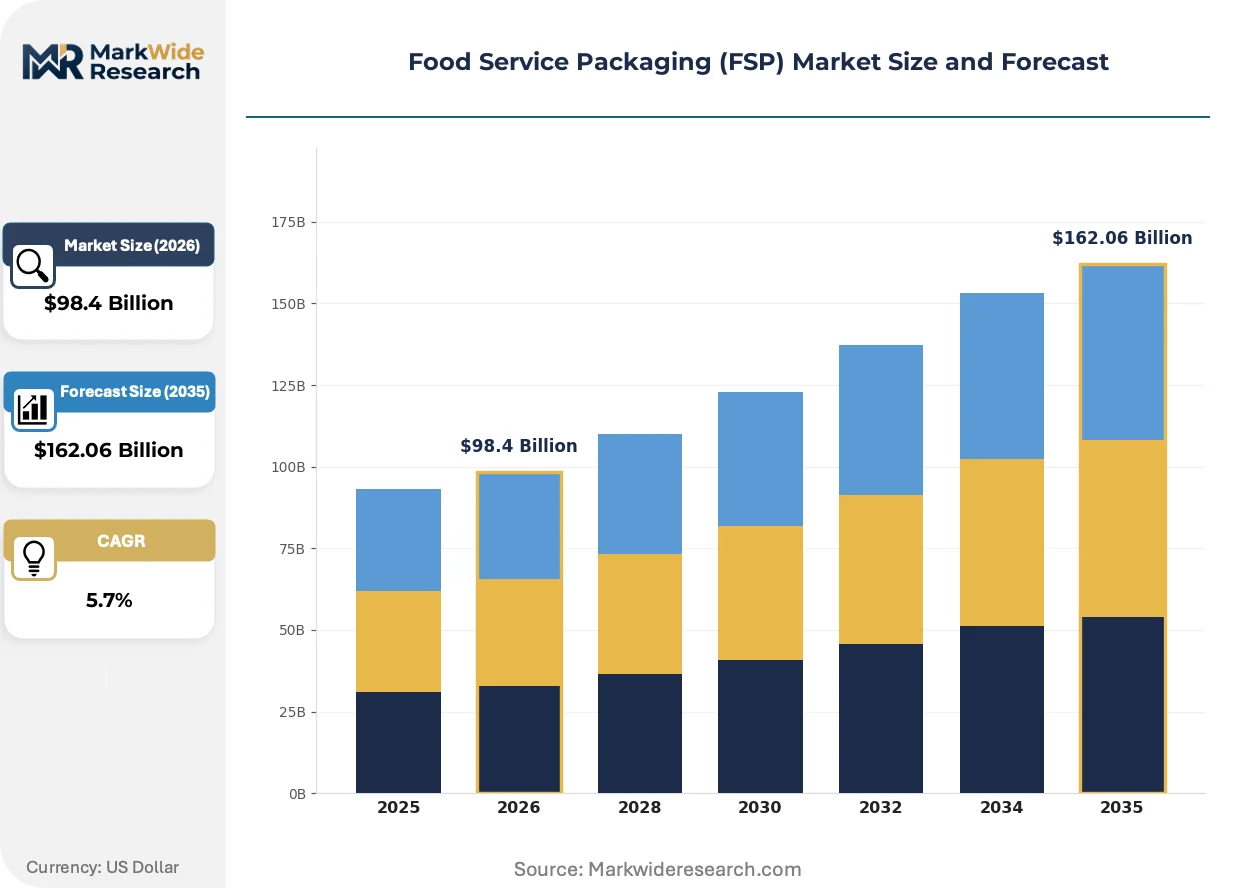
| Market Size in 2026 | $98.4 Billion |
| Market Size in 2035 | $162.06 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Paperboard, Plastics, Aluminum Foil, Polystyrene, Biodegradable Films, Molded Pulp Packaging Type: Clamshells, Trays, Cups, Bags, Bowls, Wraps End Use Industry: Quick Service Restaurants, Cafeterias, Catering Services, Food Trucks, Takeaway Outlets Distribution Channel: Direct Sales, Online Retailers, Distributors, Wholesale Suppliers, Institutional Procurement |
| Companies Covered | Amcor plc, Berry Global Inc, Huhtamaki Oyj, Sonoco Products Company, Sealed Air, WestRock Company, Pactiv Evergreen Inc., Genpak LLC, Mondi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Service Packaging (FSP) Market Shifts & Advancements
Active barrier technologies and digital printing integration are redefining performance specifications and brand communication surfaces across takeaway packaging categories.
Molded fiber manufacturing with precision-pressed pulp geometries is modularizing production economics for regional quick service suppliers. Mid-size restaurant groups in France and the Netherlands are adopting cell-based forming lines that slot into existing distribution centers. This distributed manufacturing model is modularizing supply chains previously dominated by centralized thermoforming operations.
REACH chemical restrictions and the EU F-Gas Regulation are eliminating fluorinated grease-barrier coatings from paperboard food contact applications. Industrial consequence includes accelerated R&D spending on clay-latex and plant-wax alternatives at major European converters. Quick service salad and hot-food segments are most affected, with chains reformulating packaging specifications to meet impending compliance deadlines.
Centralized procurement consolidation among multinational restaurant operators is compressing supplier rosters and lengthening contract durations. Legacy spot-buying through distributors is giving way to direct strategic partnerships with integrated packaging firms capable of design-to-waste-recovery accountability. This pattern is most visible in Germany and the UK where sustainability-linked contract terms now dominate RFP evaluation criteria.
Food Service Packaging (FSP) Market Segmentation
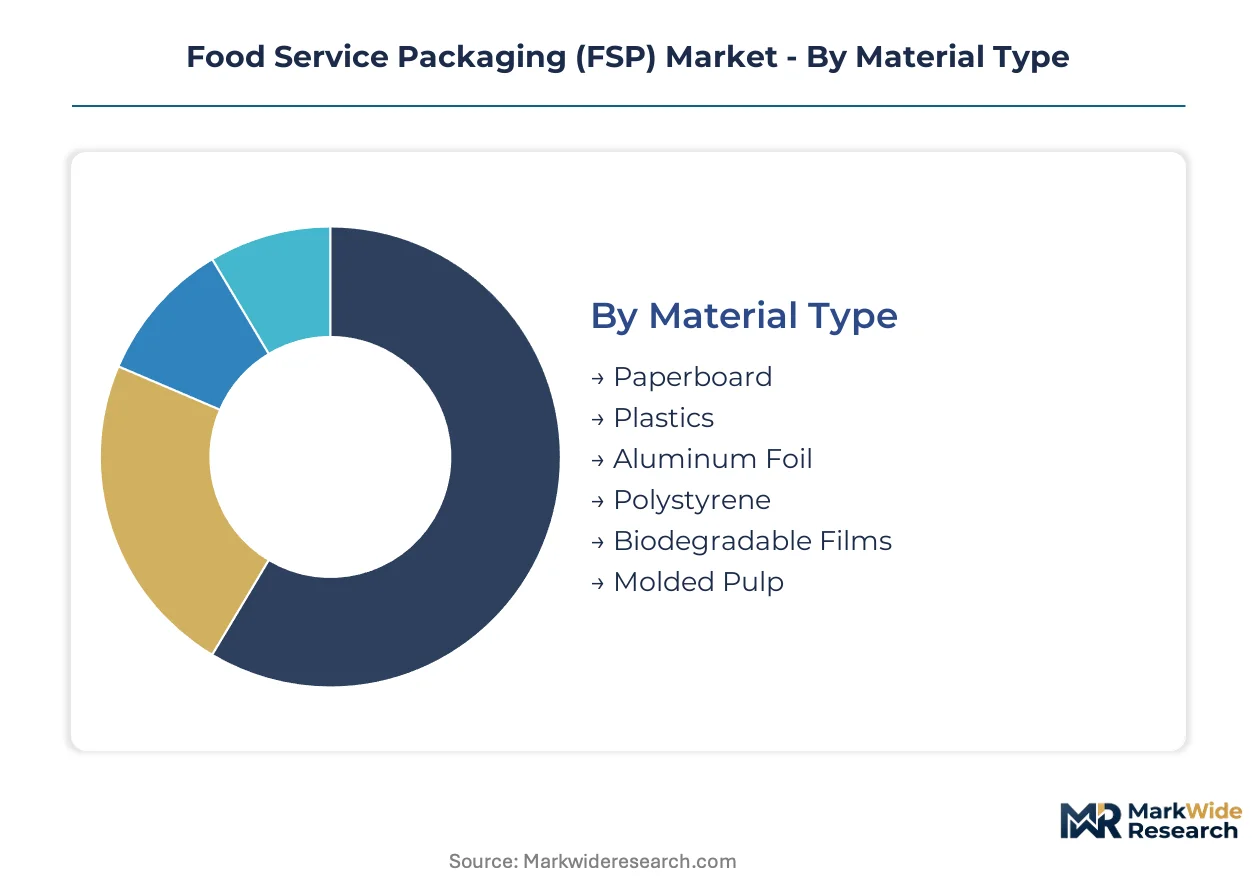
Food service packaging segments diverge sharply in supply economics and regulatory exposure. Material composition determines margin vulnerability to pulp volatility and chemical restrictions, while packaging format shapes automation compatibility and brand differentiation potential.
Material Type:
Supply concentration in Nordic softwood pulp and petroleum feedstocks creates divergent cost trajectories across material categories.
- Paperboard:Multi-layer kraft and solid bleached sulfate boards with clay-latex or plant-wax grease barriers dominate European quick service procurement. German and French cafeteria chains are consolidating specifications around FSC-certified sources to preempt EUDR deforestation compliance costs.
- Molded Pulp:Pressed-fiber trays and clamshells from bagasse or recycled paper slurry anchor sustainability transitions. Huhtamaki Oyj's European capacity expansion responds to EU Single-Use Plastics Directive bans on expanded polystyrene in takeaway containers.
- Plastics:Polypropylene and PET thermoformed vessels retain cost advantage in high-volume US quick service chains despite state-level extended producer responsibility laws in California and New York.
- Biodegradable Films:PHA and PLA formulations achieve cost parity in premium bowl applications. Enzyme-based barrier performance is unlocking European salad and hot-food segments previously locked to fluorinated coatings.
- Aluminum Foil:Laminated foil-paper hybrids serve hot-hold and grilling applications with superior thermal retention. Energy-intensive smelting constrains European supply expansion.
- Polystyrene:Expanded and solid polystyrene faces stranded capacity as REACH restrictions and US state bans compress end-markets. Remaining demand concentrates in price-sensitive institutional catering with limited compliance enforcement.
Today's leader: Paperboard. Tomorrow's challenger: Biodegradable films.
Packaging Type:
Format selection tracks menu architecture shifts toward bowl-based meals and specialty beverages.
- Clamshells:Hinged-lid containers in molded pulp or PET dominate burger and sandwich presentation. Quick service chains in India are adopting kraft-based clamshells for Tier-2 city expansion.
- Cups:Double-wall paperboard and PLA-lined cold cups are gaining share through bubble tea and specialty coffee proliferation. China's food delivery sector is pulling multi-layer insulated cup investment.
- Trays:Compartmentalized molded pulp and foam alternatives serve cafeteria and airline catering with portion control precision. Nordic pulp cost volatility compresses manufacturer margins.
- Bowls:Round-bottom paperboard and bagasse vessels align with grain-bowl and poke menu trends. PHA and algal film blow-molding adaptations are opening petroleum-free alternatives.
- Bags:Grease-resistant paper and biodegradable film pouches handle fried foods and bakery items. Flat-bottom and stand-up formats differentiate premium takeaway positioning.
- Wraps:Foil-paper laminates and waxed sheets provide flexible enclosure for burritos and flatbreads. Active barrier integration extends shelf-life for prepared meal kits.
Cups and bowls are climbing the fastest as beverage and bowl-format menus expand.
End Use Industry:
Customer scale determines procurement sophistication and sustainability specification stringency.
- Quick Service Restaurants:Global chains with centralized procurement drive volume and standardization. Subscription-based replenishment programs are replacing spot purchasing with integrated waste recovery contracts.
- Cafeterias:Corporate and institutional feeding operations prioritize cost control and compostability certification. German and Dutch mid-size groups are adopting cell-based molded fiber forming lines for distributed manufacturing.
- Catering Services:Event and airline catering demands premium presentation with batch variability. Aluminum foil hybrids and clear PLA lids serve visual merchandising requirements.
- Food Trucks:Mobile operators prioritize space-efficient nesting and rapid service compatibility. Compact clamshell and wrap formats dominate with minimal customization.
- Takeaway Outlets:Independent restaurants and ghost kitchens balance cost sensitivity with platform-driven rating pressure. Digital printing integration enables brand differentiation on limited runs.
Quick service restaurants command current volume. Catering services present the steepest premiumization trajectory.
Distribution Channel:
Channel structure is consolidating around direct strategic partnerships with integrated packaging firms.
- Direct Sales:Packaging converters engage multinational restaurant operators through design-to-waste-recovery accountability. Germany and UK sustainability-linked contract terms now dominate RFP evaluation.
- Distributors:Regional broadline foodservice distributors maintain relevance for fragmented independent restaurants. Inventory pooling reduces working capital for small-format takeaway outlets.
- Institutional Procurement:Government and healthcare purchasing cooperatives leverage scale for standardized specifications. Compostability certification requirements are tightening pre-qualification criteria.
- Online Retailers:E-commerce platforms serve small-batch and startup food brands with minimal order quantities. Digital storefronts enable rapid sampling of biodegradable film alternatives.
- Wholesale Suppliers:Cash-and-carry and warehouse club channels support price-sensitive food truck and catering operators with generic specifications and immediate availability.
Direct sales anchor large-account control. Institutional procurement is gaining specification influence through sustainability mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's food delivery sector pulls cold-chain packaging investment while Germany's EU Single-Use Plastics Directive compliance reshapes molded fiber supply chains.
China
Meituan and Ele.me platform expansion drives multi-layer insulated packaging demand for premium meal kits and hot-meal preservation. SAMR food contact regulations tighten migration limits for plastic vessels. Yangtze River Delta manufacturers scale PHA blow-molding capacity for bowl-format applications.
Germany
Quick service restaurant procurement consolidation favors direct strategic partnerships with integrated packaging firms. REACH restrictions on PFAS-based grease barriers force clay-latex formulation pivots among Bavarian converters. Berlin-Brandenburg cell-based molded fiber lines enable distributed manufacturing for mid-size restaurant groups.
United States
State-level extended producer responsibility laws in California and New York reshape material accountability for quick service chains. FDA food contact substance notifications govern barrier coating approvals. Southeast packaging clusters face margin pressure from Nordic pulp cost volatility.
India
Tier-2 city quick service penetration and airport catering expansion create first-mover openings for kraft-based clamshell suppliers. FSSAI packaging material regulations tighten compliance requirements for food contact applications. Maharashtra and Gujarat manufacturing hubs scale molded fiber capacity for domestic quick service networks.
France
Cafeteria and catering channels prioritize compostability certification under tightening EUDR deforestation compliance timelines. ANSM chemical safety assessments influence barrier coating specifications. Île-de-France quick service operators consolidate procurement around sustainability-linked contract terms.
Food Service Packaging (FSP) Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with consolidated multinational converters dominating quick service procurement while regional molded fiber specialists capture cafeteria and catering niches. The vendor base organizes around three archetypes: integrated packaging firms with design-to-waste-recovery accountability, barrier technology licensors with proprietary film platforms, and distributed manufacturing enablers with cell-based forming equipment. Capacity expansion and strategic partnerships represent the dominant competitive moves, with direct sales relationships replacing legacy distributor channels.
Among integrated packaging specialists, Huhtamaki Oyj and Sealed Air occupy positions anchoring distinct technology vectors, while Mondi exemplifies kraft-based solution dominance across European cafeteria channels. These firms represent the tier capable of sustaining sustainability-linked contract terms with multinational restaurant operators.
| Leading Market Players |
|---|
| Amcor plc |
| Berry Global Inc |
| Huhtamaki Oyj |
| Sonoco Products Company |
| Sealed Air |
| WestRock Company |
| Pactiv Evergreen Inc. |
| Genpak LLC |
| Mondi |
| Others |
Supply & Pricing Matrix
Cell-based molded fiber forming lines are compressing capital barriers for mid-size restaurant groups while simultaneously fragmenting production geography and eroding centralized pricing power previously held by thermoforming incumbents. This distributed manufacturing shift is recalibrating how suppliers capture margin across European quick service networks.
Pricing Analysis
Capacity additions in Germany and the Netherlands are reshaping price floors for molded pulp clamshells and trays. Three-tier pricing structure across premium, standard, and economy levels separates FSC-certified fiber with plant-wax barriers from generic kraft and residual polystyrene alternatives. Pricing pressure stems from Nordic softwood pulp cost volatility and energy-intensive drying processes. Institutional catering operators exhibit highest price sensitivity, while multinational quick service chains prioritize sustainability-linked contract terms over unit cost.
Supply Chain Analysis
Domestic-content mandates under the EU Single-Use Plastics Directive are redirecting sourcing toward regional fiber processors and away from Asian polystyrene resin imports. Supply concentrates in Finland, Sweden, and Germany for softwood pulp, while bagasse feedstock draws from India and Thailand. Single-source vulnerability sits with Nordic pulp suppliers exposed to energy cost spikes. Distribution runs through direct strategic partnerships with integrated packaging firms, replacing legacy broadline distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Food Service Packaging Market operates as a stable compounder, with regulatory-driven material substitution creating durable replacement demand across European and North American quick service networks.
For Market Incumbents: Anticipate margin compression from enzyme-based barrier coating commoditization by securing captive pulp supply through backward integration into Nordic fiber assets or long-term offtake agreements. Defend positioning by accelerating PHA and algal film R&D ahead of petroleum plastic phase-outs in California and New York. For New Entrants and Emerging Players: Launch via subscription replenishment models targeting mid-size cafeteria chains in France and the Netherlands seeking distributed manufacturing partnerships. Penetrate India's Tier-2 city quick service expansion with kraft-based clamshell solutions, leveraging local molded fiber capacity scaling in Maharashtra and Gujarat. For Investors and Strategic Acquirers: Valuations sit cheapest among regional molded fiber specialists with cell-based forming equipment and established compostability certification. Target acquisition archetypes include European converters with clay-latex barrier formulation expertise and existing Huhtamaki or Mondi supply relationships. Monitor SAMR food contact regulation tightening in China as inflection signal for multi-layer insulated packaging demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Supply | Captive Nordic softwood fiber secures margin stability against energy cost volatility. |
| Enzyme-Based Barrier Coating Scale-Up | Plant-derived grease resistance unlocks premium pricing in European salad segments. |
| Cell-Based Forming Equipment Deployment | Modular production lines enable distributed manufacturing for mid-size restaurant groups. |
| PHA Blow-Molding Capacity Addition | Marine-derived feedstocks open petroleum-free bowl applications for quick service chains. |
| Compostability Certification Investment | TÜV Austria and BPI credentials preempt stranded inventory from municipal infrastructure gaps. |
Research Methodology
Multiple input streams — primary interviews with packaging procurement directors, sustainability officers at multinational restaurant operators, and molded fiber plant managers; secondary validation through EU ECHA restriction dossiers, FDA food contact substance notifications, and FSC chain-of-custody databases; plus customs trade data on pulp and resin flows — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation anchored volume and value outputs across material type, packaging format, and end-use industry segmentation, with regional regulatory clusters modeled separately. CAGRs were derived from slope-intercept analysis of historical substitution patterns and projected compliance deadlines. Forecast inputs incorporated REACH chemical restriction timelines and China SAMR food contact migration limit revisions.
Several conditions sit outside the modeled scope, including unannounced national bans on polystyrene, abrupt pulp supply disruptions from Nordic energy policy shifts, and municipal organics collection infrastructure build-out pace. Forecasts reflect documented assumptions on regulatory enforcement consistency and certification standard convergence. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Foodservice Packaging
United States Disposable Tableware Market
Foodservice Packaging
North America Foodservice Packaging Market
Foodservice Packaging
France Disposal Tableware Market
Foodservice Packaging
Foodservice Disposable Packaging Market
Foodservice Packaging
Compostable Food Service Packaging Market
Foodservice Packaging
Canada Foodservice Packaging Market
Foodservice Packaging
Bar and Prep Faucets Market
Foodservice Packaging
Compostable Food Service Tray Market
Foodservice Packaging
Foodservice Paper Bags Market
Foodservice Packaging
Italy Disposable Tableware Market