
 North America Foodservice Packaging Market | 2026-2036
North America Foodservice Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
North America Foodservice Packaging Market Analytics
Asset-light leasing models for thermoforming and extrusion equipment are fragmenting competitive barriers across the North America foodservice packaging landscape. Novolex Holdings LLC leverages its captive resin sourcing and broad converting footprint to sustain cost advantages in polyethylene-based formats. Huhtamaki Oyj anchors its position through molded fiber innovation for hot-beverage cups, competing directly against plastic legacy systems. Dart Container Corporation dominates the insulated cup segment through proprietary foam technologies that extend temperature retention performance.
Foodservice packaging encompasses single-use and limited-use containers, utensils, cups, and lids engineered from plastic resins, paperboard, molded fiber, aluminum, or certified biodegradable substrates to preserve food safety, temperature integrity, and handling convenience during away-from-home consumption. Manufacturing processes span thermoforming, injection molding, extrusion blow molding, and pressed-fiber molding, with wall thickness, grease resistance, and sealability constituting critical functional parameters for hot-fill and fatty-food applications. Containers and cups capture the largest volume share within product-type segmentation, while biodegradable materials represent the fastest-expanding material category as municipal composting capacity expands. The direct-sales channel occupies the deepest margin pools by bypassing distributor markups for large quick-service restaurant accounts.
The FDA governs food-contact notifications and substance safety thresholds, while the EPA oversees per- and polyfluoroalkyl substance restrictions that are forcing reformulation of grease-resistant paperboard. State regulators in California and New York enforce extended producer responsibility frameworks that reshape material selection and end-of-life labeling obligations. Stakeholders must monitor pending federal PFAS prohibitions and patchwork state compostability certification requirements to anticipate which material platforms will retain market access.
Market Dynamics
Quick-service restaurant chains are consolidating purchasing power while simultaneously fragmenting format requirements, forcing packaging suppliers to engineer modular substrate platforms that pivot between foam, fiber, and recyclable plastic specifications without retooling.
Growth Catalysts
- Extended Producer Responsibility frameworks:California and New York mandates are accelerating fiber-based format adoption by assigning end-of-life cost accountability to manufacturers.
- Municipal composting infrastructure expansion:Dense urban networks in the Northeast corridor and Southern California are creating viable offtake channels for certified compostable containers.
- Off-premise dining format proliferation:Drive-thru and delivery-optimized kitchen layouts are amplifying demand for insulated delivery packaging with extended temperature retention.
Market Restraints
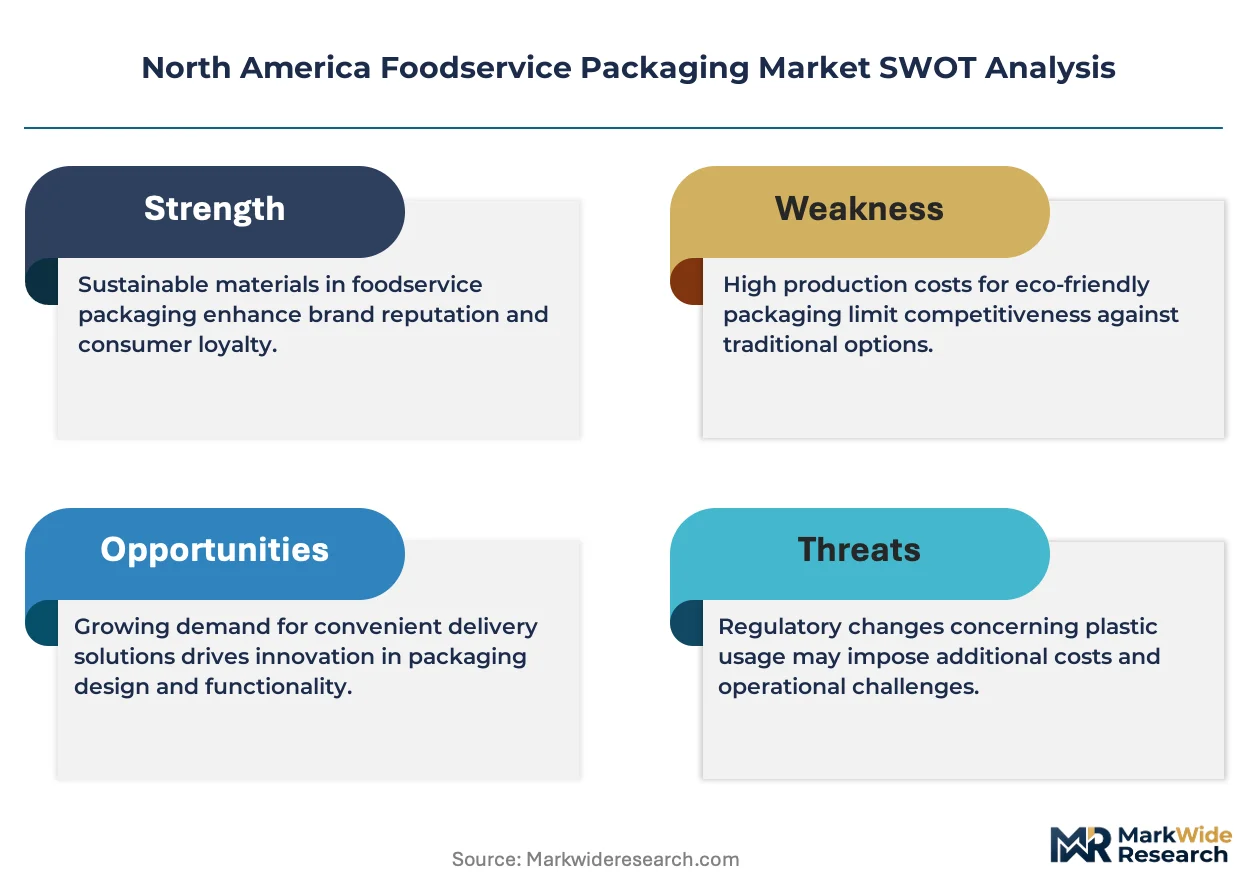
- Resin price volatility:Polyethylene and polypropylene input costs swing with crude oil indices, compressing margins on conventional plastic formats.
- PFAS regulatory friction:EPA restrictions on per- and polyfluoroalkyl substances are forcing grease-resistant paperboard reformulation before certified alternatives achieve scale.
- Regional supply concentration:Molded fiber capacity clusters in the Southeastern United States, creating logistics cost penalties for West Coast quick-service accounts.
Strategic Opportunities
- Canadian market underpenetration:Ontario and Quebec quick-service networks lag U.S. adoption curves for certified compostable formats, presenting first-mover positioning.
- Direct-sales channel expansion:Bypassing distributor markups for large quick-service restaurant accounts deepens margin pools and locks in volume commitments.
- Asset-light equipment leasing:Thermoforming and extrusion equipment leasing models lower capital barriers for regional converters entering fiber-based production.
Industry Challenges
- Compostability certification timeline:BPI and CMA certification cycles stretch 18-24 months, delaying market access for novel biodegradable substrates.
- Legacy system integration:Automated filling and sealing lines optimized for plastic formats require retrofit investment to handle fiber-based material variability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Foodservice Packaging Market |
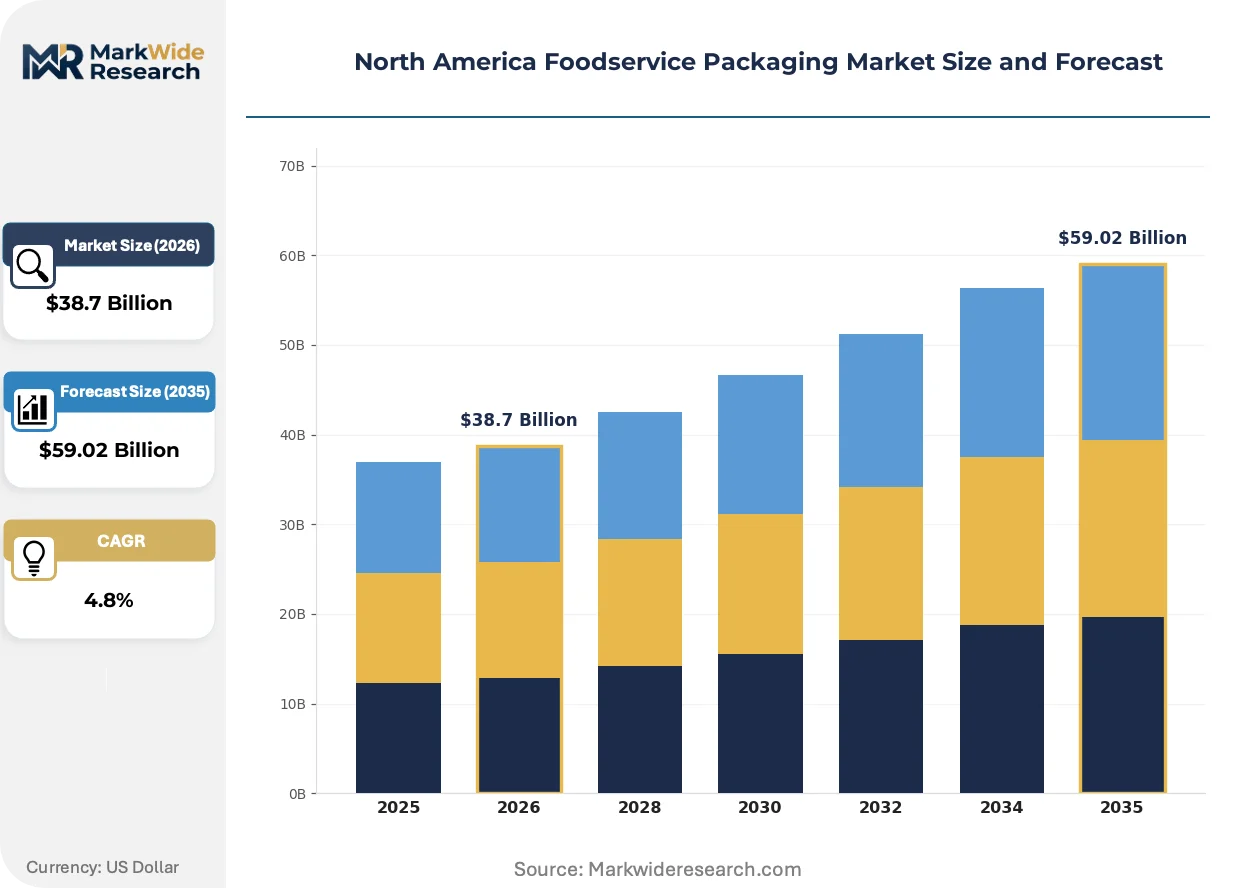
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $59.02 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Containers, Utensils, Cups, Lids Material: Plastic, Paper, Biodegradable, Aluminum End User: Restaurants, Cafes, Catering Services, Food Trucks Distribution Channel: Online, Offline, Direct Sales, Wholesalers |
| Companies Covered | Genpak LLC, Amcor plc, Novolex Holdings LLC, Graphic Packaging International Inc., Berry Global Inc., Huhtamaki Oyj, Pactiv Evergreen Inc., Sonoco Products Company, Dart Container Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Foodservice Packaging Market Evolving Landscape
Material science breakthroughs and regulatory compression are converging to restructure substrate hierarchies across quick-service and casual-dining supply chains, with performance parity now achievable at commercial scale.
Barrier-coated molded fiber is migrating from hot-beverage cup lids into broader food-container applications as quick-service chains in the Northeast corridor accelerate pilot programs. The technology delivers grease resistance without PFAS chemistry, though throughput rates on existing thermoforming lines lag plastic equivalents by 15-20%. This migration is compressing the traditional foam-to-plastic upgrade path and forcing equipment manufacturers to engineer hybrid press configurations.
EPA restrictions on per- and polyfluoroalkyl substances are compelling paperboard converters to eliminate fluorinated chemistry from fry-carton and sandwich-wrapper specifications. The industrial consequence is a supply scramble for bio-based barrier coatings that meet FDA food-contact substance thresholds while achieving comparable oil resistance. Quick-service fried-chicken and burger segments in California are most affected, with several chains accelerating fiber-format transitions ahead of pending federal prohibitions.
Large quick-service restaurant chains are consolidating supplier relationships from fragmented regional distributor networks toward direct master-service agreements with national packaging converters. This consolidation disrupts traditional foodservice distribution channels and replaces them with vendor-managed inventory programs tied to point-of-sale demand signals. The shift is most visible in the U.S. Northeast corridor, where dense store networks enable just-in-time delivery optimization and reduce working capital requirements for both operators and suppliers.
North America Foodservice Packaging Market Segmentation
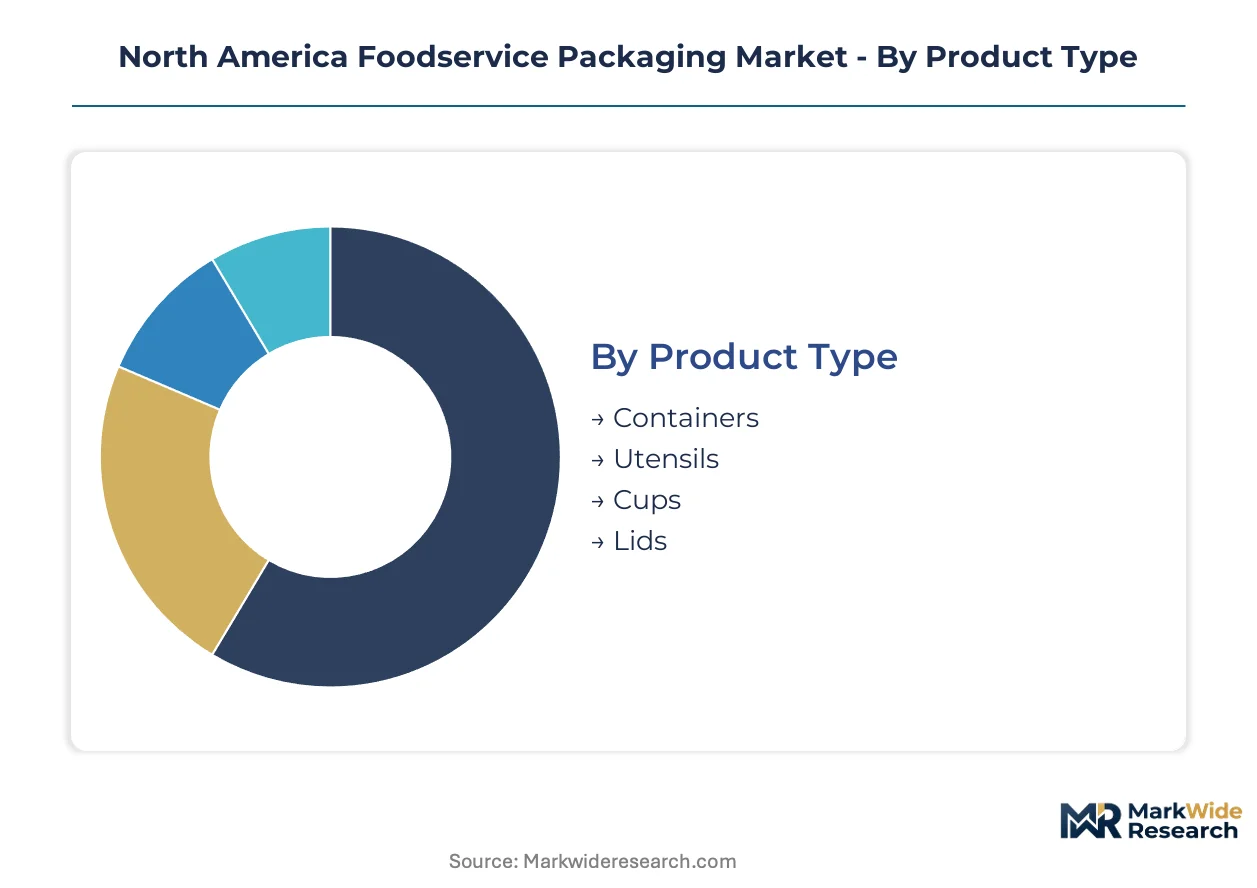
Substrate selection and format geometry in foodservice packaging determine temperature retention, grease resistance, and end-of-life pathway compliance. Each segmentation dimension carries distinct margin profiles and regulatory exposure that reshape supplier positioning across quick-service and institutional channels.
Product Type:
Application function dictates wall thickness specifications, sealability requirements, and automation compatibility on filling lines.
- Containers:Thermoformed clamshells and injection-molded bases handle hot-fill and fatty-food applications with structural ribs for stacking strength. Quick-service burger and fried-chicken chains in the U.S. Northeast corridor are consolidating volume here, driving demand for grease-resistant fiber alternatives as California and New York extended producer responsibility frameworks assign end-of-life cost accountability to manufacturers.
- Cups:Double-wall insulated constructions and single-wall cold-beverage formats span polystyrene foam, polypropylene, and molded fiber substrates. Drive-thru and delivery-optimized kitchen layouts across Southern California are amplifying procurement of extended temperature-retention designs, compressing the traditional foam-to-plastic upgrade path.
- Utensils:Polypropylene and polylactic acid sporks, knives, and straws face mechanical performance thresholds for frozen-dessert and dense-food applications.
- Lids:Straw-slot and sip-through designs in polyethylene terephthalate and molded fiber require dimensional stability across hot-fill and frozen temperature ranges.
Containers hold installed capacity. Cups are rotating up the share rankings.
Material:
Cost tier and regulatory compliance trajectory separate substrate selection for quick-service procurement teams.
- Plastic:Polyethylene, polypropylene, and polystyrene resins dominate volume through thermoforming and injection molding efficiency. Polyethylene and polypropylene input costs swing with crude oil indices, compressing margins on conventional formats while FDA food-contact substance regulations maintain safety thresholds.
- Biodegradable:Polylactic acid, bagasse, and certified compostable molded fiber formats are climbing the fastest as municipal composting infrastructure expands in dense urban networks across the Northeast corridor and Southern California, creating viable offtake channels for BPI-certified containers.
- Paper:Bleached and unbleached paperboard with bio-based barrier coatings are eliminating fluorinated chemistry ahead of EPA per- and polyfluoroalkyl substance restrictions.
- Aluminum:Foil containers and lids serve high-temperature holding and reheatable applications in catering and institutional channels.
Plastic retains volume dominance. Biodegradable formats are expanding most quickly.
End User:
Customer type determines order frequency, specification complexity, and direct-sales channel viability.
- Restaurants:Quick-service chains with consolidated purchasing power are fragmenting format requirements across foam, fiber, and recyclable plastic specifications. Large accounts in the U.S. Northeast corridor are bypassing distributor markups through vendor-managed inventory programs tied to point-of-sale demand signals.
- Catering Services:Event-based volume spikes require modular substrate platforms that pivot between disposable and limited-use specifications without retooling.
- Cafes:Specialty coffee and bakery formats prioritize aesthetic differentiation and brand-customized printing on cup exteriors.
- Food Trucks:Mobile operators with constrained storage footprint favor nested, space-efficient container geometries and multi-compartment designs.
Restaurants anchor procurement volume. Catering services are gaining share fastest.
Distribution Channel:
Margin capture and customer relationship depth vary sharply across channel architecture.
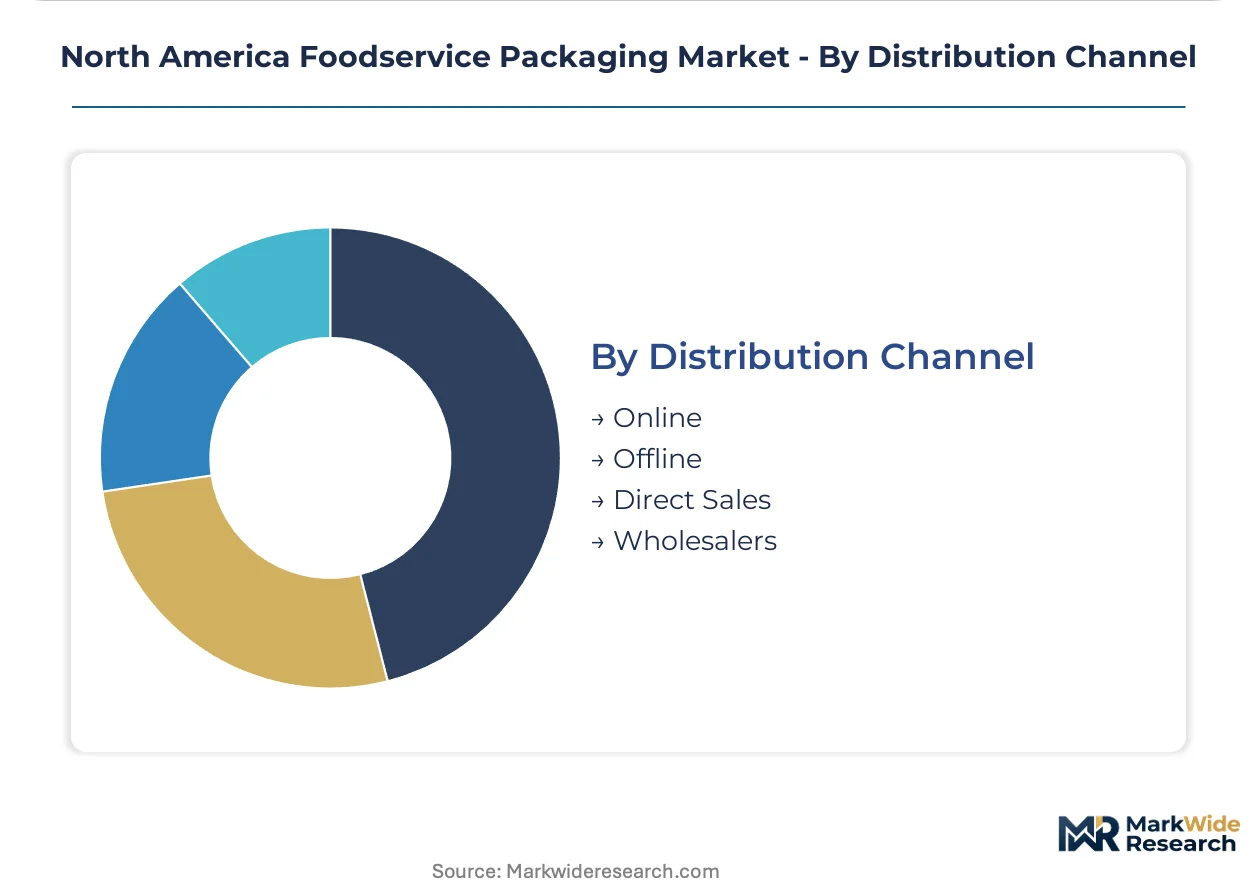
- Direct Sales:National packaging converters bypass distributor markups for large quick-service restaurant accounts, deepening margin pools and locking in volume commitments through master-service agreements. This shift is most visible in the U.S. Northeast corridor, where dense store networks enable just-in-time delivery optimization.
- Wholesalers:Broadline foodservice distributors aggregate fragmented regional demand with inventory risk absorption for smaller operators.
- Online:E-procurement platforms serve independent restaurants and emerging virtual brands with smaller minimum order quantities.
- Offline:Traditional distributor sales representatives handle specification consultation and equipment-integrated packaging systems.
Direct sales commands the deepest margin pools. Online channels are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cross-border resin flows and finished packaging trade create asymmetric supply relationships across the region. Canada imports substantial thermoformed container volumes from U.S. Midwest production hubs. Mexico's maquiladora corridor exports converted packaging back into Texas and California distribution networks.
United States
Quick-service restaurant chains in the Northeast corridor are consolidating purchasing through vendor-managed inventory programs tied to point-of-sale data. The EPA enforces per- and polyfluoroalkyl substance restrictions that compel paperboard converters to eliminate fluorinated chemistry from fry-carton specifications. Southern California's municipal composting infrastructure creates viable offtake channels for certified compostable containers across Los Angeles and San Diego metro networks.
Canada
Ontario and Quebec quick-service networks lag U.S. adoption curves for certified compostable formats, presenting first-mover positioning for fiber-based suppliers. Health Canada maintains food-contact substance regulations aligned with FDA safety thresholds while allowing provincial extended producer responsibility experiments. The Greater Toronto Area's dense urban foodservice network overlaps with emerging municipal composting pilots in Vancouver and Montreal.
Mexico
Maquiladora converters along the northern border states supply thermoformed clamshells and injection-molded bases to Texas and California quick-service accounts. Mexico's federal environmental regulator oversees industrial waste frameworks that remain less prescriptive than California's extended producer responsibility mandates. The Baja California corridor clusters polyethylene resin conversion capacity serving cross-border logistics networks into San Diego and Los Angeles distribution hubs.
Northeast Corridor
Dense urban foodservice networks from Boston through Washington D.C. enable just-in-time delivery optimization and reduce working capital requirements for suppliers and operators. State regulators in New York enforce extended producer responsibility frameworks that reshape material selection and end-of-life labeling obligations. The corridor's overlapping municipal composting infrastructure supports pilot programs for barrier-coated molded fiber migrating from hot-beverage cup lids into broader food-container applications.
Southern California
Drive-thru and delivery-optimized kitchen layouts across Los Angeles and San Diego amplify procurement of extended temperature-retention packaging designs. California's extended producer responsibility law assigns end-of-life cost accountability to manufacturers, accelerating fiber-based format adoption ahead of federal mandates. The region's quick-service fried-chicken and burger segments face immediate supply scrambles for bio-based barrier coatings as chains accelerate transitions ahead of pending federal PFAS prohibitions.
North America Foodservice Packaging Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower substrate focus. The vendor base stratifies between consolidated national converters with captive resin sourcing and regional specialists leasing thermoforming equipment. Three archetypes dominate: resin-integrated conglomerates with backward control over polyethylene supply chains; fiber-focused innovators pressing molded pulp into hot-beverage and food-container formats; and foam-technology incumbents defending insulated cup positions through proprietary temperature-retention systems. Competitive moves concentrate on direct-sales channel expansion for large quick-service accounts and asset-light equipment leasing to lower capital barriers for regional converters entering fiber-based production.
Among North American packaging conglomerates, Novolex Holdings LLC exemplifies the resin-integrated archetype through captive polyethylene sourcing and broad converting footprints that sustain cost advantages in conventional plastic formats. Huhtamaki Oyj anchors the fiber-innovation tier with molded fiber positioning for hot-beverage applications, competing directly against legacy plastic systems through barrier-coated designs. Dart Container Corporation occupies the insulated-format specialist position, defending foam-technology positions through proprietary temperature-retention performance in double-wall cup constructions.
| Leading Market Players |
|---|
| Genpak LLC |
| Amcor plc |
| Novolex Holdings LLC |
| Graphic Packaging International Inc. |
| Berry Global Inc. |
| Huhtamaki Oyj |
| Pactiv Evergreen Inc. |
| Sonoco Products Company |
| Dart Container Corporation |
| Others |
Value Network & Pricing Analysis
Overcapacity in Southeastern U.S. molded fiber plants is compressing spot pricing for clamshell containers while tightening margins for converters serving West Coast quick-service accounts. This utilization imbalance forces suppliers to choose between absorbing logistics penalties or ceding share to regional competitors with shorter haul distances.
Pricing Analysis
Quick-service restaurant procurement teams anchor contract negotiations through master-service agreements that lock in volume commitments across multi-year terms. Pricing stratifies across premium, standard, and economy tiers based on certification grade and customization level, with BPI-certified compostable formats commanding premiums over conventional polyethylene. Cost compression in fiber-based categories is intensifying because resin-integrated conglomerates leverage captive polyethylene supply to defend plastic-format share. Independent restaurant operators exhibit highest price sensitivity, while national quick-service chains prioritize supply security over unit cost.
Supply Chain Analysis
Contract thermoformers clustered in Ohio, Indiana, and Illinois hold dominant capacity for injection-molded bases and clamshell containers serving U.S. and Canadian quick-service networks. Raw material flows draw from Gulf Coast polyethylene resin production, Canadian pulp mills for molded fiber feedstock, and imported polylactic acid from Thailand and China. Single-source vulnerability concentrates in PFAS-free barrier coating formulations, where qualified suppliers remain limited ahead of EPA enforcement deadlines. Distribution runs through vendor-managed inventory programs for large accounts, with broadline distributors absorbing inventory risk for smaller regional operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Extended producer responsibility mandates across California and New York are accelerating material-format disruption faster than converter capacity can pivot, creating asymmetric reward for first-movers in certified compostable platforms.
For Market Incumbents: Insulate foam-format positions through proprietary temperature-retention technology upgrades while accelerating backward integration into pulp sourcing for fiber-based lines. Novolex-style captive resin advantages face erosion from regulatory compression on polyethylene; certification investment in BPI and CMA pathways secures market access ahead of federal PFAS prohibitions. For New Entrants and Emerging Players: Ontario and Quebec quick-service networks present underpenetrated terrain where U.S. adoption curves for certified compostable formats lag by 24-36 months. First-mover positioning in Canadian fiber-based supply, combined with direct-sales channel bypass of entrenched distributor relationships, unlocks volume commitments before incumbent converters redirect capacity northward. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fiber-focused innovators with vendor-managed inventory programs tied to point-of-sale demand signals. Long-term viability over a five-to-ten-year window rests on acquisition targets possessing dual certification in BPI and CMA pathways plus geographic diversification beyond Southeastern U.S. capacity clusters. The signal to watch is municipal composting infrastructure buildout velocity in secondary Canadian and U.S. Midwest metro markets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Sourcing | Captive fiber supply secures margin control as resin volatility compresses plastic-format economics. |
| Dual Certification Investment | Simultaneous BPI and CMA pathways accelerate market access as state labeling mandates proliferate. |
| Direct-Sales Channel Expansion | Vendor-managed inventory programs with national quick-service accounts deepen margin pools and lock volume. |
| Barrier-Coating R&D Partnership | PFAS-free chemistry development addresses immediate regulatory pressure in California fried-food segments. |
| Canadian Market Entry | Ontario and Quebec procurement lag creates first-mover positioning before incumbent capacity redirection. |
Research Methodology
Initial hypotheses were tested against primary input from quick-service restaurant procurement directors, packaging converter plant managers, municipal composting facility operators, and FDA regulatory affairs specialists, then refined through secondary validation. Bottom-up demand modeling triangulated against top-down supply capacity assessments drew from SEC 10-K filings of publicly traded converters, EPA enforcement action databases, state extended producer responsibility rulemakings, and municipal waste infrastructure investment records.
Demand-supply balance dynamics across the analysis window were modeled through segmentation by product type, material substrate, end-user category, and distribution channel, with regional regulatory clusters as an overlay dimension. CAGRs were derived from installed capacity utilization rates, format substitution elasticities, and municipal composting infrastructure buildout curves. Forecast inputs incorporated quick-service restaurant unit expansion pipelines, resin price volatility indices, and certification timeline distributions.
The forecast holds incumbent behavior within observed patterns; aggressive capacity addition by resin-integrated conglomerates or accelerated federal PFAS prohibitions would shift outcomes beyond modeled ranges. Quarterly review of state-level extended producer responsibility rulemaking, municipal composting pilot announcements, and barrier-coating supplier qualification timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Foodservice Packaging
Bar and Prep Faucets Market
Foodservice Packaging
Compostable Food Service Tray Market
Foodservice Packaging
United States Disposable Tableware Market
Foodservice Packaging
Italy Disposable Tableware Market
Foodservice Packaging
Foodservice Disposable Packaging Market
Foodservice Packaging
France Disposal Tableware Market
Foodservice Packaging
Food Service Packaging (FSP) Market
Foodservice Packaging
Compostable Food Service Packaging Market
Foodservice Packaging
Canada Foodservice Packaging Market
Foodservice Packaging
Foodservice Paper Bags Market