
 Compostable Food Service Tray Market | 2026-2036
Compostable Food Service Tray Market Size, Share, and Industry Trends Forecast 2026-2036
Compostable Food Service Tray Market Analytics
Multi-source resin procurement is consolidating around certified compostable feedstock suppliers with verified ASTM D6400 and EN 13432 documentation. Huhtamaki Group leverages its molded fiber manufacturing network across Finland and the United States to secure volume contracts with institutional foodservice operators. Vegware Ltd. differentiates through closed-loop composting partnerships with waste haulers in the United Kingdom and Ireland. WorldCentric anchors its position with carbon-neutral shipping and BPI-certified bagasse tray lines targeting university and corporate cafeteria accounts.
Compostable food service trays are rigid or semi-rigid serving vessels engineered from plant-derived polymers, processed agricultural residues, or mycelium-bound substrates, designed to decompose within industrial composting conditions within 90 to 180 days per ASTM D6400 or EN 13432 protocols; their primary commercial purpose is to replace expanded polystyrene and conventional plastics in foodservice environments where post-consumer composting infrastructure exists. The material dimension shows bagasse and PLA capturing dominant volume in North American foodservice procurement, while CPLA commands premium positioning for hot-food applications due to its higher thermal resistance threshold. Trays and containers within the product type split are outpacing plates in institutional contract growth, driven by grab-and-go format expansion in healthcare and education sectors.
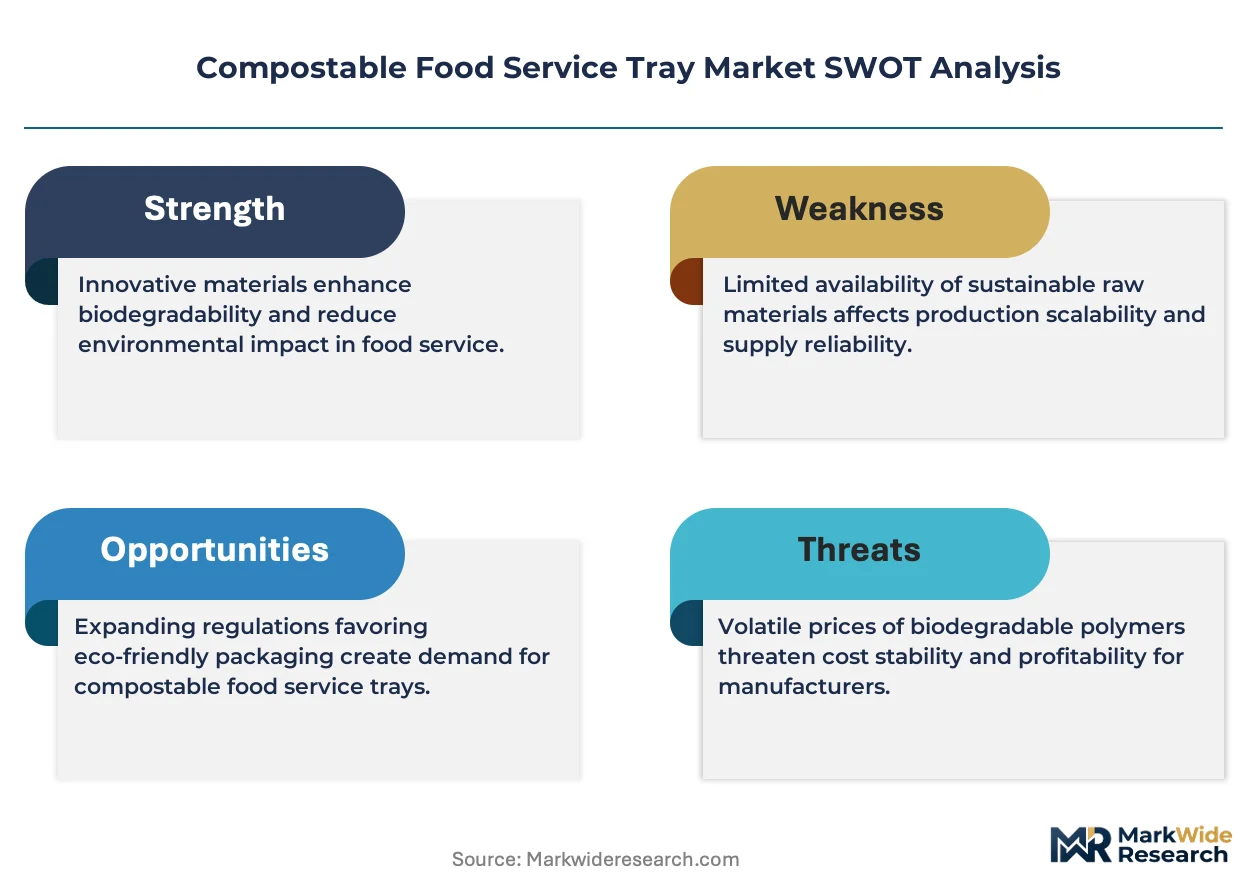
The U.S. Federal Trade Commission's Green Guides and state-level extended producer responsibility frameworks in California and Washington shape labeling requirements and compostability claims verification, while the European Commission's Packaging and Packaging Waste Regulation tightens recyclability and compostability definitions for single-use items entering EU markets. BPI certification in North America and TÜV Austria's OK Compost INDUSTRIAL mark in Europe function as de facto market access credentials for tray suppliers seeking multi-regional distribution. Stakeholders must monitor composting facility capacity buildout rates against production capacity expansion timelines to avoid feedstock-certification mismatches that strand inventory or trigger compliance penalties.
Market Dynamics
The compostable food service tray market pivots on municipal composting infrastructure buildout rates racing against manufacturing capacity expansion, with certification mismatches stranding inventory when ASTM D6400-certified trays reach regions lacking industrial composting facilities.
Growth Catalysts
- EU Single-Use Plastics Directive:Mandatory phase-outs of expanded polystyrene containers across member states force foodservice operators toward certified alternatives, with Germany's municipal composting network absorbing volume at scale.
- Bagasse fiber processing advances:Steam-injection molding improvements cut cycle times for sugarcane pulp trays, enabling price parity with conventional plastics in high-volume quick-service restaurant procurement.
- Healthcare sector conversion:Hospital and long-term care cafeteria contracts specify BPI-certified serviceware to meet sustainability procurement mandates, with tray formats outpacing plates in institutional RFPs.
Market Restraints
- PLA resin price volatility:Corn and cassava feedstock costs swing with agricultural commodity markets, compressing margins for tray manufacturers locked into annual foodservice contracts.
- Composting facility concentration:Industrial composting capacity clusters in coastal US states and Western Europe, leaving interior regions with certified product but no degradation pathway.
- Hot-food performance ceiling:Unmodified PLA trays deform above 110°F, restricting their use in steam-table and fried-food applications where CPLA carries 40-60% price premiums.
Strategic Opportunities
- Midwest US infrastructure gap:States lacking municipal composting present first-mover advantage for vertically integrated suppliers offering collection-hauling-processing bundled services.
- Mycelium substrate integration:Fungal-bound agricultural waste combines with conventional pulp molding to create water-resistant tray surfaces without synthetic coatings.
- California SB 54 EPR framework:Extended producer responsibility rules create compliance-driven demand for certified compostable packaging among foodservice distributors serving state facilities.
Industry Challenges
- ASTM D6400 testing backlog:Third-party certification timelines stretch 4-6 months, delaying product launches and contract awards for new tray formulations.
- Composting facility contamination standards:Non-compostable lookalike products entering waste streams trigger rejection thresholds that disqualify entire truckloads of certified material.
- Legacy equipment retrofit costs:Converting molded fiber production lines from petroleum-based to plant-based resin handling requires capital outlays that strain mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compostable Food Service Tray Market |
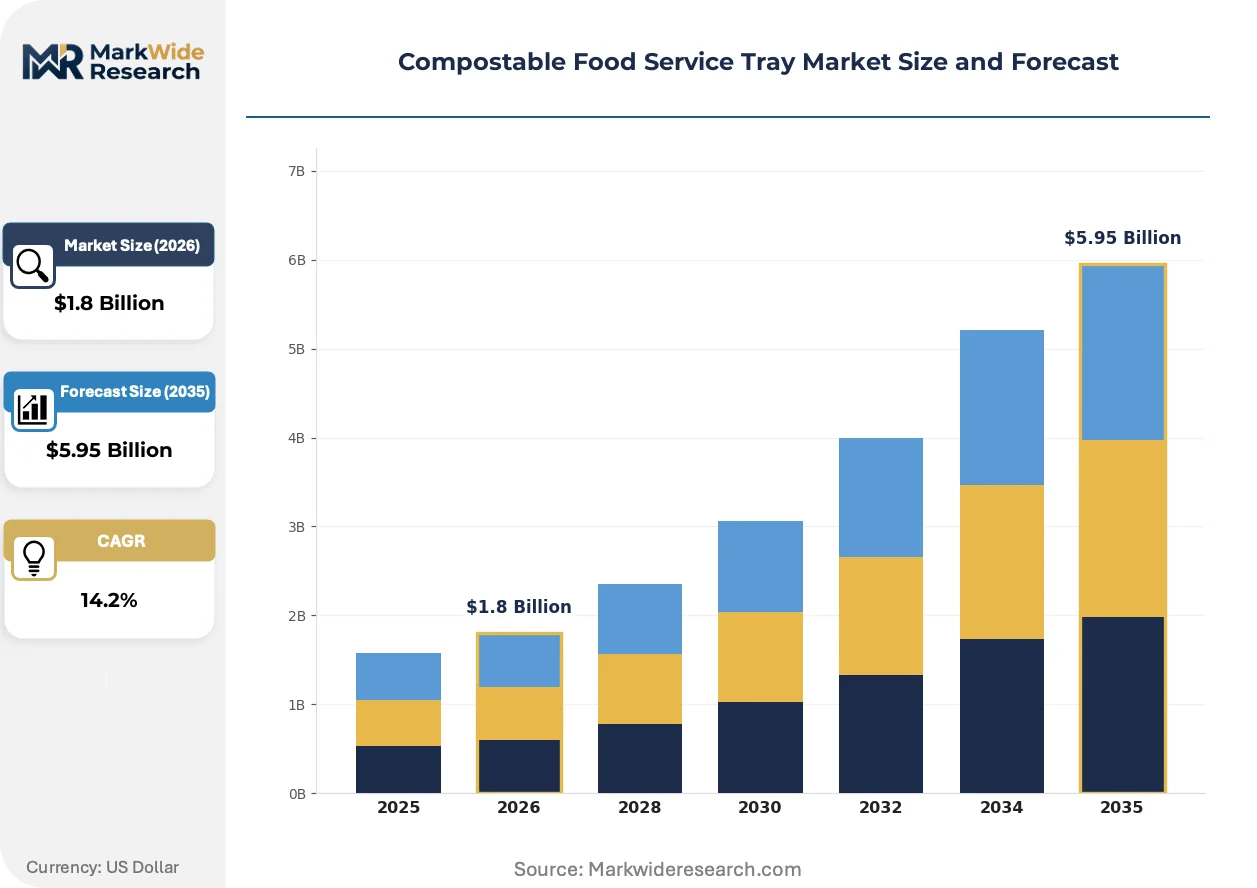
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plates, Bowls, Trays, Containers Material: PLA, Bagasse, CPLA, Bamboo End User: Restaurants, Catering Services, Events, Food Trucks Distribution Channel: Online Retail, Supermarkets, Wholesale, Direct Sales |
| Companies Covered | Eco-Products, Inc., Huhtamaki Group, Vegware Ltd., BioPak, Green Paper Products, Anchor Packaging LLC, WorldCentric, Biotrem, Enviropack, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compostable Food Service Tray Market Evolving Landscape
Material science breakthroughs and regulatory precision are compressing the gap between certified compostability claims and actual end-of-life processing outcomes, reshaping how tray suppliers validate performance.
Mycelium-bound pulp formulations are consolidating around standardized growth protocols that replace synthetic binders in molded fiber trays. Quick-service restaurant chains in the Pacific Northwest specify these substrates for cold-food applications where moisture resistance matches conventional performance. The technology is consolidating supplier bases as cultivation-to-molding integration requires capital commitments that smaller compounders cannot match.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances (PFAS) in food contact materials accelerate fluorine-free barrier coating development across EU member states. Tray manufacturers reformulate oil-resistant layers using lignin and chitosan derivatives to maintain grease resistance without regulatory exposure. Hot-food segments in Germany and France face immediate reformulation deadlines, pushing CPLA and bagasse alternatives into premium positioning.
University and corporate cafeteria operators now require proof-of-composting documentation alongside product certification, shifting vendor selection criteria beyond price-per-unit to verified end-of-life outcomes. Foodservice management companies contract directly with regional composting facilities to secure offtake guarantees, then source trays exclusively from suppliers meeting those facility's contamination standards. This behavior concentrates most visibly in California and Washington state procurement frameworks.
Compostable Food Service Tray Market Segmentation
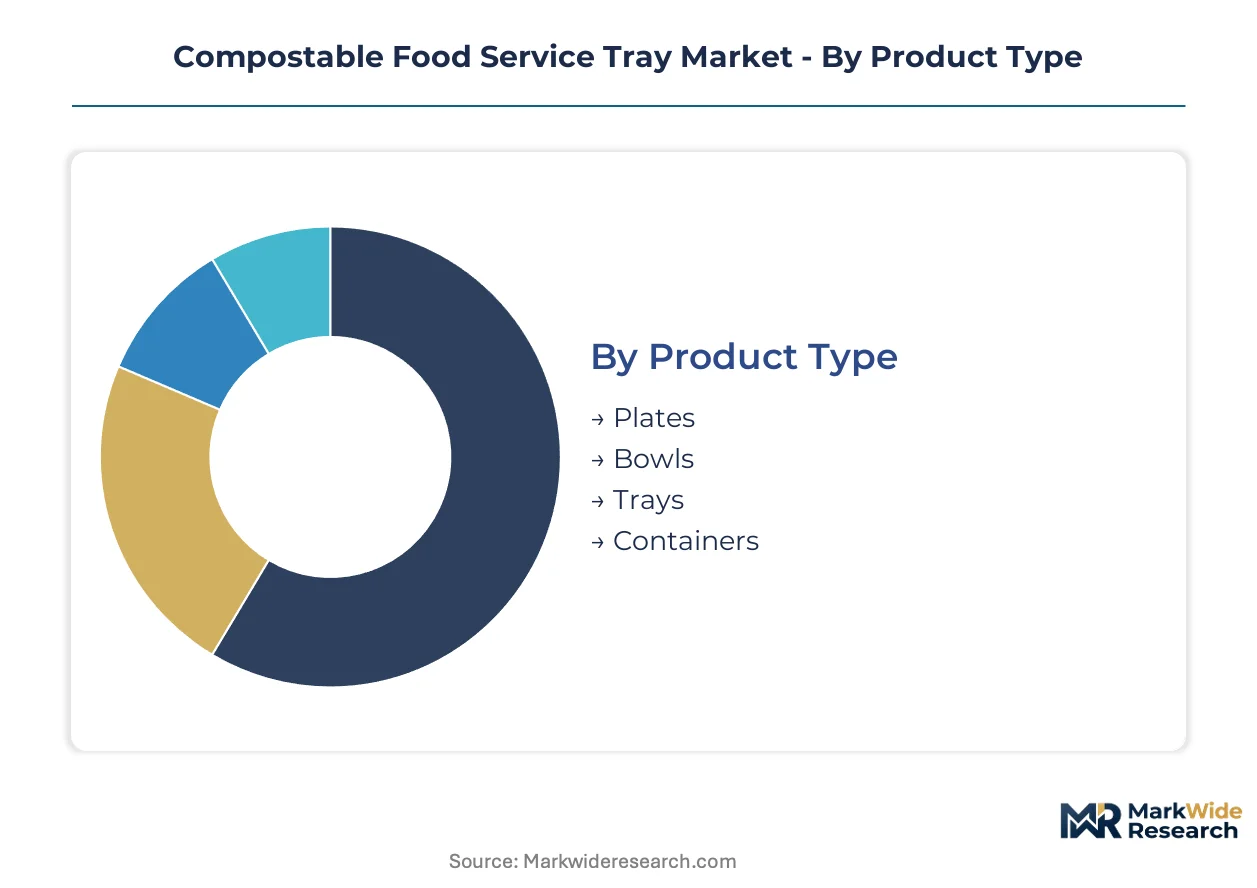
Compostable food service tray procurement splits sharply between standardized commodity formats for high-volume quick-service contracts and customized specifications for institutional accounts with precise contamination thresholds. Certification requirements vary by segment, creating procurement silos that favor suppliers with multi-standard documentation.
Product Type:
Standardization dominates grab-and-go formats while customization concentrates in healthcare and education sectors with specialized dimensional requirements.
- Trays:Rigid serving platforms engineered from bagasse or CPLA for institutional cafeterias and quick-service assembly lines. Hospital and university contracts in California and Washington specify BPI-certified trays with documented composting outcomes, outpacing plates in RFP volume.
- Containers:Lidded formats with barrier coatings for hot and cold food separation. Quick-service chains in Germany's municipal composting network absorb volume at scale for takeout applications.
- Plates:Flat-pressed molded fiber for casual dining and event catering where stacking efficiency matters.
- Bowls:Deep-drawn formats for soup and grain bowls in fast-casual concepts.
Leading the category by volume: Trays. Expanding most quickly: Containers.
Material:
Cost tiers separate commodity feedstocks from performance-grade polymers with thermal resistance premiums.
- Bagasse:Steam-injection molded sugarcane pulp achieving price parity with conventional plastics in high-volume procurement. North American quick-service operators specify bagasse for cold-food applications where moisture resistance suffices.
- CPLA:Crystallized polylactic acid with thermal resistance above 110°F for steam-table and fried-food service. Hot-food segments in Germany and France accept 40-60% price premiums for CPLA over unmodified PLA.
- PLA:Standard polylactic acid from corn or cassava feedstock, constrained by agricultural commodity price swings.
- Bamboo:Grass-pulp composite for premium positioning in corporate cafeteria sustainability showcases.
Bagasse dominates procurement volume. CPLA commands the steepest price escalation for performance-critical applications.
End User:
Customer type determines certification stringency and contract duration, with institutional accounts locking multi-year supply agreements.
- Restaurants:Quick-service chains specify ASTM D6400 or EN 13432 certification for system-wide rollout, with procurement concentrated in coastal US states and Western Europe where composting infrastructure exists.
- Catering Services:Event-based demand with seasonal spikes, favoring standardized formats for inventory efficiency.
- Events:Festival and stadium contracts with single-use mandates driving volume in jurisdictions with extended producer responsibility frameworks.
- Food Trucks:Mobile operators prioritizing lightweight formats and stackability for space-constrained service environments.
Restaurants anchor procurement volume. Food trucks represent the most price-sensitive segment with lowest certification requirements.
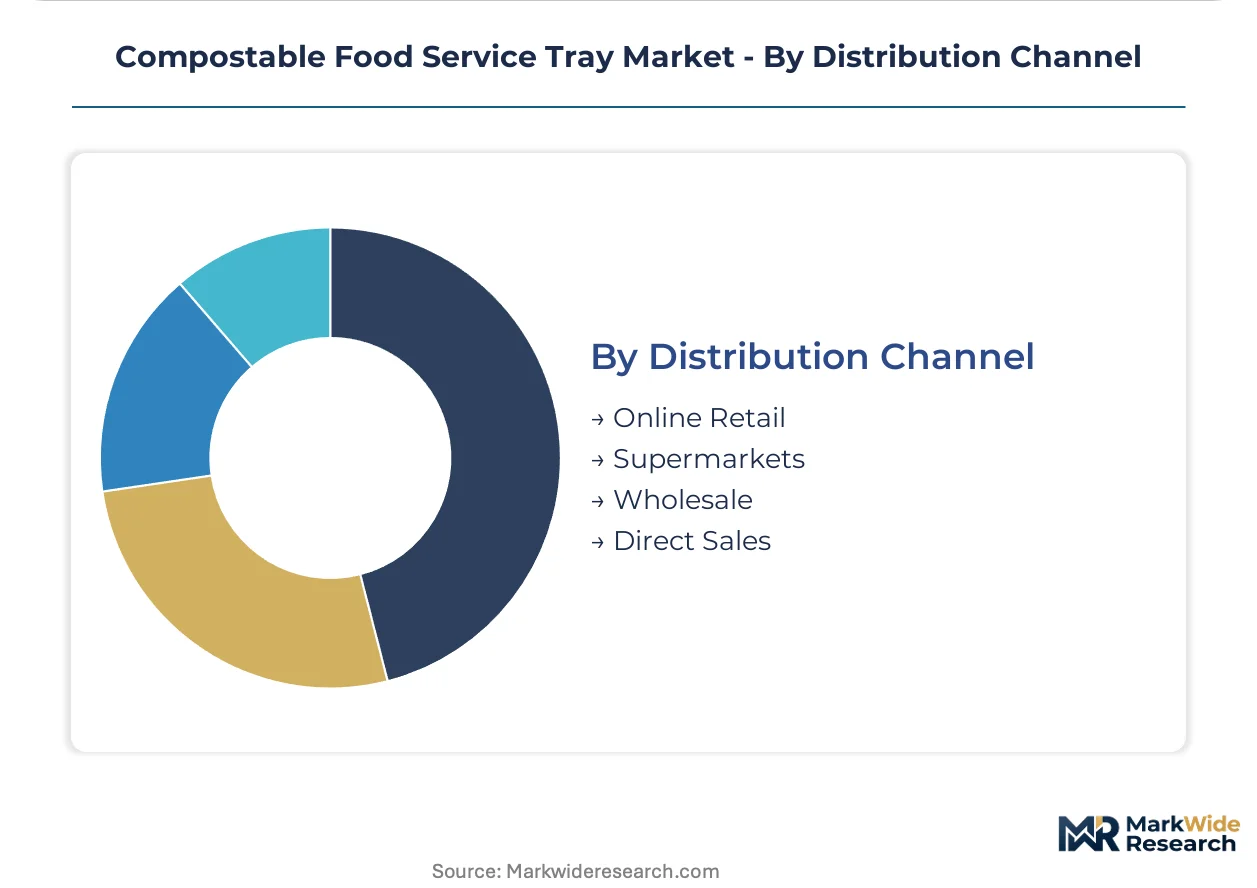
Distribution Channel:
Channel concentration reflects geographic composting infrastructure density, with direct sales penetrating markets lacking mature retail certification literacy.
- Wholesale:Foodservice distributors bundle certified trays with composting facility partnerships in California and Washington, offering collection-hauling-processing verification to institutional accounts.
- Direct Sales:Manufacturers contract directly with quick-service chains and healthcare systems for volume commitments with customized specifications.
- Online Retail:E-commerce penetration for small-format catering and event planners seeking pallet-scale procurement without distributor relationships.
- Supermarkets:Retail shelf presence for consumer partyware and small-event applications, constrained by composting facility proximity requirements.
Wholesale channels move the greatest volume. Direct sales deliver the highest margin capture through specification premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sugarcane bagasse processing clusters in Guangxi and Yunnan provinces anchor Asia-Pacific feedstock supply for molded fiber tray production. Corn-derived PLA resin concentrates in the US Midwest agricultural belt. Municipal composting infrastructure density determines regional uptake velocity.
United States
Quick-service restaurant chains in California and Washington specify BPI-certified trays under state extended producer responsibility frameworks. The FTC Green Guides enforce compostability claim verification. Seattle-Tacoma and San Francisco-Oakland clusters absorb volume through verified composting partnerships with waste haulers.
Germany
Municipal composting networks in Bavaria and North Rhine-Westphalia process certified trays at industrial scale. The EU Single-Use Plastics Directive mandates EPS phase-out by 2026. Berlin-Brandenburg institutional cafeterias lock multi-year supply contracts with documented end-of-life verification.
United Kingdom
Closed-loop composting partnerships between foodservice operators and regional waste processors concentrate in Greater London and the South East. The Environment Agency enforces contamination thresholds for industrial composting facility acceptance. Manchester and Birmingham healthcare systems specify CPLA trays for hot-food service applications.
France
REACH Annex XVII PFAS restrictions accelerate fluorine-free barrier coating adoption in Île-de-France foodservice procurement. The French Agency for Food, Environmental and Occupational Health Safety monitors food contact compliance. Lyon and Marseille quick-service operators transition to bagasse formats for cold-food applications.
Canada
Provincial extended producer responsibility programs in British Columbia and Quebec drive institutional cafeteria conversion. Health Canada regulates food contact materials under the Food and Drugs Act. Toronto and Vancouver metropolitan areas build composting capacity to match certified product inflows from US suppliers.
Compostable Food Service Tray Market Competitive Landscape
Global majors compete with regional champions across certification documentation and composting infrastructure partnerships. The vendor base stratifies between integrated resin-to-tray manufacturers and specialized molded fiber fabricators. Three archetypes dominate: multinational packaging conglomerates with multi-continental production networks, regional specialists with captive composting partnerships, and agricultural waste processors backward-integrated into pulp molding. Capacity expansion and strategic certification licensing represent the dominant competitive vectors.
Among Finland-based and US-based integrated manufacturers, Huhtamaki Group exemplifies the multinational archetype with molded fiber networks spanning both regions. UK specialists Vegware Ltd. and Australia-originated BioPak occupy positions within the regional partnership tier, anchoring closed-loop composting arrangements with waste haulers in their respective home markets. These three represent divergent geographic anchoring strategies within a market where composting facility proximity determines contract viability.
| Leading Market Players |
|---|
| Eco-Products, Inc. |
| Huhtamaki Group |
| Vegware Ltd. |
| BioPak |
| Green Paper Products |
| Anchor Packaging LLC |
| WorldCentric |
| Biotrem |
| Enviropack |
| Others |
Value Network & Pricing Analysis
Steam-injection molding advances in bagasse fiber processing simultaneously compress unit economics and consolidate supplier tiers around capital-intensive equipment operators. This production-method transition concentrates pricing power with integrated manufacturers while squeezing compounders lacking in-house pulp molding capabilities.
Pricing Analysis
Collection-hauling-processing bundled services separate premium-tier suppliers from unbundled commodity vendors in institutional procurement. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and composting facility partnership depth. Price differentiation hinges on BPI or TÜV Austria verification status and geographic delivery cost to composting infrastructure. Cost compression in standard-grade bagasse trays is intensifying because agricultural commodity swings transmit directly to resin pricing. Food truck operators exhibit highest price sensitivity; healthcare systems with sustainability mandates show lowest.
Supply Chain Analysis
Post-consumer tray return flows for industrial composting create reverse-logistics dependencies that anchor supplier-customer contracts. Feedstock supply concentrates in Guangxi and Yunnan provinces for sugarcane bagasse, the US Midwest for corn-derived PLA resin, and Bavaria for mycelium cultivation substrates. Raw material dependencies rest on agricultural waste streams, polymer resin batches, and fluorine-free barrier coatings. Single-source vulnerability in certified composting facility access threatens inventory stranding when production outruns regional processing capacity. Distribution runs through foodservice wholesalers with verified composting partnerships in coastal US states and Western Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Compostable food service tray manufacturing sits in a materials-transition phase where mycelium-bound substrates and fluorine-free coatings displace legacy petroleum-based and PFAS-containing formats.
For Market Incumbents: To counter PLA resin price volatility eroding contract margins, Huhtamaki-class manufacturers should secure multi-year agricultural feedstock offtake agreements and expand molded fiber capacity in Germany's municipal composting corridor. Certification investment in TÜV Austria's OK Compost INDUSTRIAL mark defends European market access against REACH Annex XVII enforcement tightening. For New Entrants and Emerging Players: Midwest US institutional cafeterias lacking municipal composting infrastructure represent the most penetrable buyer archetype for vertically integrated suppliers offering bundled collection-hauling-processing services. First-mover positioning in Ohio and Illinois healthcare systems with direct composting facility partnerships bypasses wholesale channel concentration. Go-to-market execution should anchor on California SB 54 EPR framework compliance documentation. For Investors and Strategic Acquirers: Re-rating potential sits with agricultural waste processors backward-integrated into pulp molding given EU Single-Use Plastics Directive volume guarantees. Long-term viability over a multi-year horizon favors suppliers with captive composting partnerships over pure manufacturing plays. Monitor ASTM D6400 certification backlog clearance timelines as inflection indicator for production capacity absorption rates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Supply | Corn and sugarcane pulp sourcing from Guangxi and US Midwest agricultural belts secures margin control against commodity swings. |
| Composting Facility Partnership | Direct contracts with Bavaria and California waste haulers guarantee end-of-life verification for institutional RFP compliance. |
| Fluorine-Free Barrier Coating Development | Lignin and chitosan formulation investment addresses REACH Annex XVII PFAS restrictions in German and French hot-food segments. |
| Multi-Standard Certification Licensing | Dual BPI and TÜV Austria documentation unlocks cross-Atlantic distribution without regulatory delay. |
| Mycelium Substrate Scale-Up | Fungal-bound agricultural waste cultivation-to-molding integration captures quick-service cold-food specifications in Pacific Northwest. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with foodservice procurement directors, composting facility operators, molded fiber plant managers, and sustainability officers at quick-service chains cross-validated volume and pricing assumptions. Secondary sources included BPI certification databases, TÜV Austria OK Compost registries, EU Single-Use Plastics Directive implementation reports, and US EPA municipal composting capacity surveys. Bottom-up production capacity estimates triangulated against top-down foodservice operator spend data.
Data-stream reconciliation across supply-side capacity buildouts and demand-side contract awards shaped the analytical framework. Segmentation dimensions spanned product type, material grade, end-user category, and distribution channel across the analysis window. CAGRs derived from installed composting facility capacity growth rates mapped against manufacturing expansion timelines. Industry-specific forecast inputs incorporated agricultural commodity price indices and regulatory phase-out schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to municipal infrastructure buildout delays and certification standard revisions. Forecasts reflect documented assumptions on composting facility contamination thresholds and resin feedstock availability. Practitioners should monitor ASTM D6400 testing backlog durations and regional composting capacity commissioning announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Foodservice Packaging
France Disposal Tableware Market
Foodservice Packaging
Food Service Packaging (FSP) Market
Foodservice Packaging
United States Disposable Tableware Market
Foodservice Packaging
Italy Disposable Tableware Market
Foodservice Packaging
Foodservice Disposable Packaging Market
Foodservice Packaging
Foodservice Paper Bags Market
Foodservice Packaging
Compostable Food Service Packaging Market
Foodservice Packaging
Canada Foodservice Packaging Market
Foodservice Packaging
Bar and Prep Faucets Market
Foodservice Packaging
North America Foodservice Packaging Market