
 Foodservice Disposable Packaging Market | 2026-2036
Foodservice Disposable Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Foodservice Disposable Packaging Market Foresight
Quick-service restaurant consolidation is recalibrating procurement volumes across the foodservice disposable packaging value chain. Huhtamäki Oyj leverages its molded fiber expertise to dominate European quick-service accounts. Dart Container Corporation anchors North American foam and plastic cup production through extensive thermoforming infrastructure. Pactiv Evergreen Inc. competes across multiple substrates with integrated manufacturing from raw pulp to finished containers.
Foodservice disposable packaging encompasses single-use containers, utensils, cups, and wraps engineered from paperboard, plastics, aluminum, or agricultural fibers to safely transport prepared food from commercial kitchens to end consumers. These products must meet specified grease resistance, thermal insulation, and structural rigidity thresholds while complying with food-contact safety standards. Paper bowls and biodegradable cups now attract the fastest margin expansion as brands seek compostable alternatives to polystyrene. Plastic containers retain volume leadership in liquid-heavy applications where barrier properties remain unmatched by fiber substitutes. Aluminum trays occupy a stable niche in oven-ready and premium catering segments where reheat performance commands price premiums.
The FDA governs food-contact substance notifications in the United States, while the EU's REACH and Single-Use Plastics Directive restrict specific polymers and mandate extended producer responsibility schemes across member states. India's FSSAI and BIS standards increasingly address migration limits and labeling requirements for disposable food-contact articles sold through organized retail channels. Stakeholders must monitor how diverging national timelines for polymer phase-outs reshape material sourcing strategies and capital allocation across regional production networks.
Market Dynamics
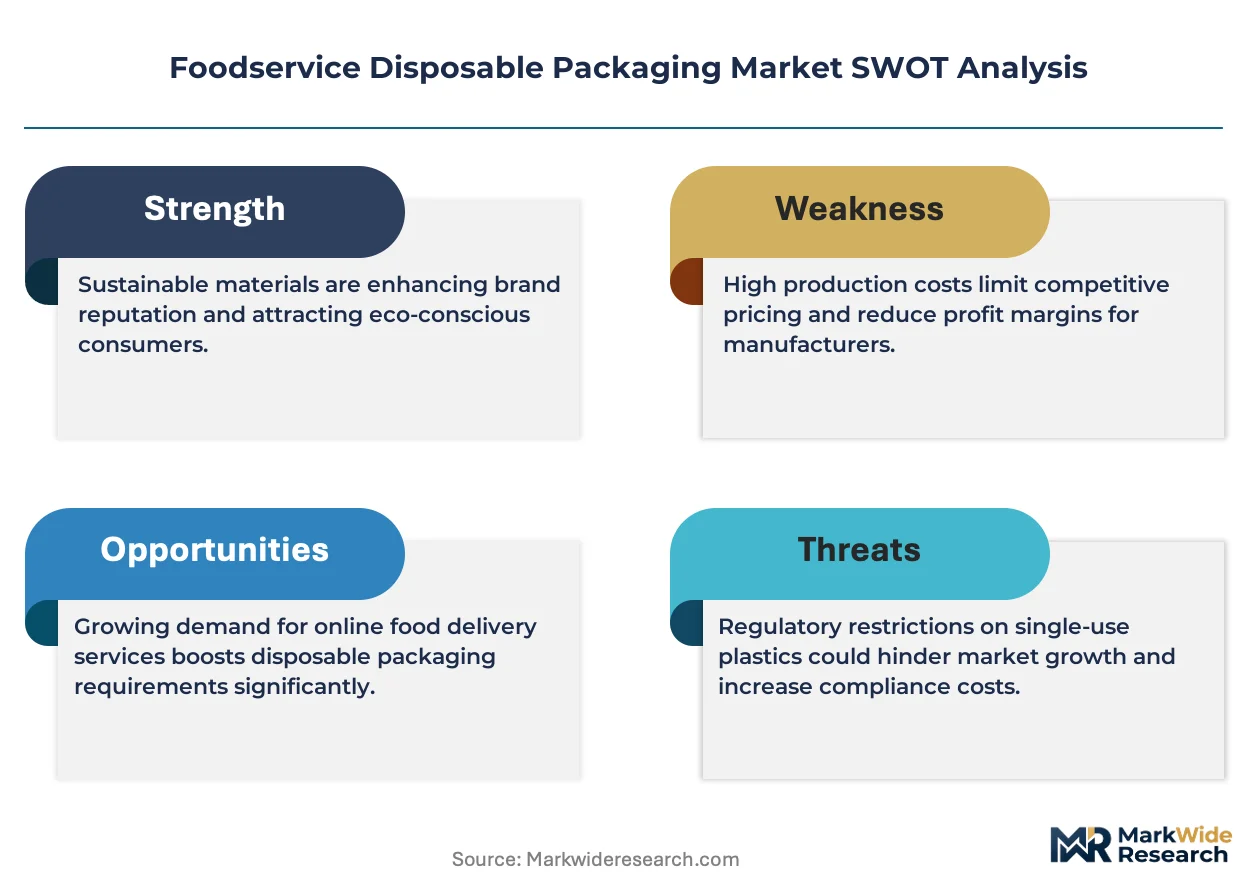
Single-use plastics phase-outs across major economies are forcing substrate substitution at scale, compressing polystyrene demand while expanding molded fiber and biopolymer capacity investments throughout the value chain.
Growth Catalysts
- EU Single-Use Plastics Directive:Mandates banning expanded polystyrene food containers and oxo-degradable plastics, redirecting procurement toward fiber-based alternatives across quick-service and catering segments.
- Cloud kitchen proliferation:India's urban food delivery corridors are multiplying aggregator-platform-dependent ghost kitchens, each requiring standardized disposable packaging for brand-consistent presentation.
- Barrier coating advances:Aqueous and PLA-based grease-resistant treatments are closing performance gaps against plastic, enabling hot-fill and liquid applications previously reserved for polymer containers.
Market Restraints
- Pulp cost volatility:Northern European and Brazilian softwood pulp markets swing with energy and logistics inputs, squeezing margins for integrated and non-integrated converters alike.
- Barrier performance ceilings:Fiber substitutes still fail extended shelf-life requirements for acidic and high-fat prepared foods, preserving polymer dominance in meal-kit and retail-ready segments.
- Composting infrastructure gaps:Certified compostable packaging requires industrial composting facilities that remain concentrated in Germany, Netherlands, and select US coastal corridors, limiting end-of-life value realization elsewhere.
Strategic Opportunities
- India's tier-2 city expansion:Swiggy and Zomato are penetrating Jaipur, Lucknow, and Kochi, creating first-mover packaging specification opportunities before standards consolidate.
- Reusable system integration:Loop-style returnable container pilots with quick-service chains in France and UK are opening service-revenue models beyond single-use unit sales.
- US state-level extended producer responsibility:Maine and Oregon laws are shifting cost structures toward producer-funded recovery, rewarding designs with higher recyclability and recycled content thresholds.
Industry Challenges
- Molded fiber tooling lead times:Precision aluminum die production for complex geometries stretches 16-24 weeks, constraining rapid product development cycles for seasonal menu launches.
- Migration testing backlog:FDA food-contact substance notifications face extended review timelines for novel biopolymer chemistries, delaying commercialization of next-generation barrier coatings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foodservice Disposable Packaging Market |
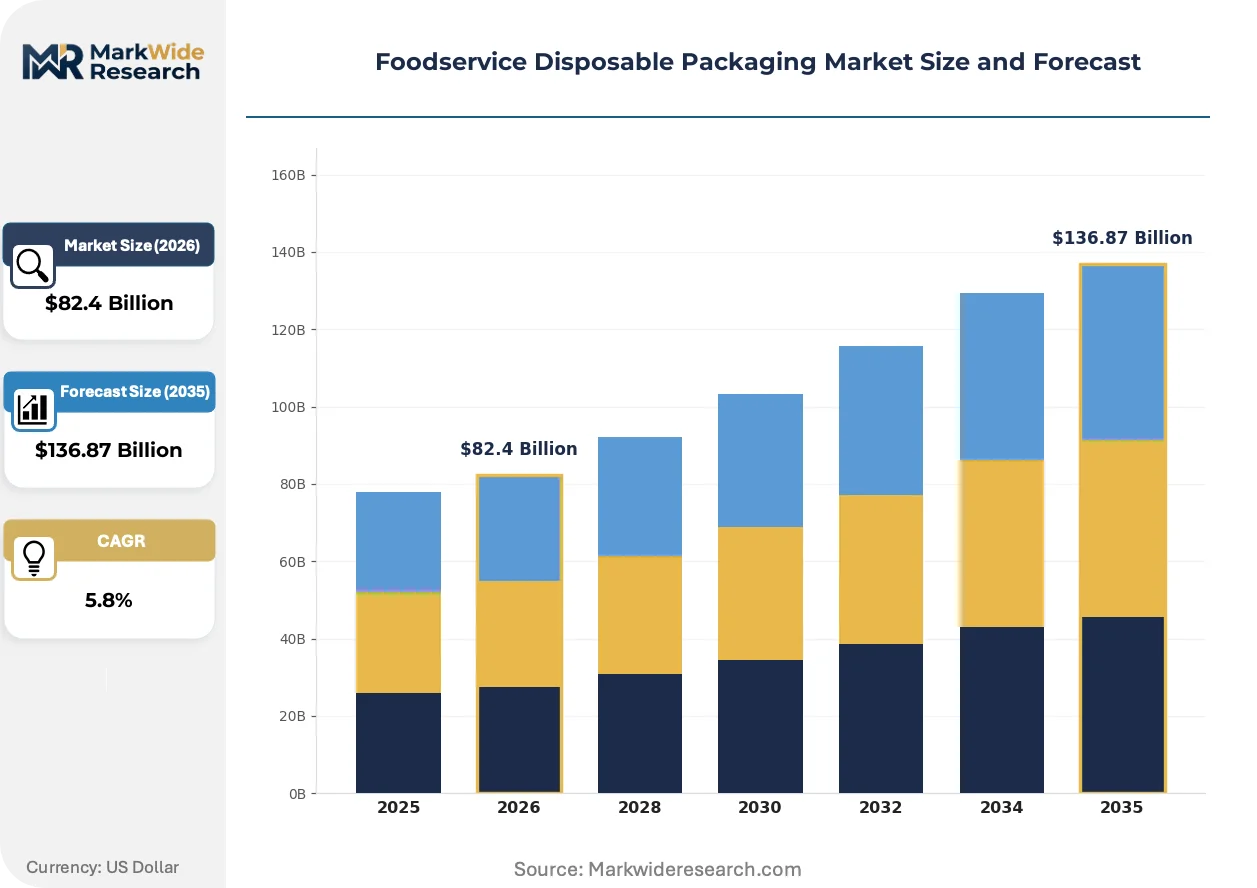
| Market Size in 2026 | $82.4 Billion |
| Market Size in 2035 | $136.87 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Paper Bowls, Plastic Containers, Aluminum Trays, Foam Plates, Biodegradable Cups Material: Cardboard, Polystyrene, Polypropylene, Bamboo Fiber, Bagasse Application: Fast Food Chains, Catering Services, Cafeterias, Street Vendors, Delivery Packaging End User: Restaurants, Hotels, Event Organizers, Food Trucks, Institutional Dine-In |
| Companies Covered | Huhtamäki Oyj, Dart Container Corporation, Pactiv Evergreen Inc., Berry Global Inc., Graphic Packaging International, LLC, Sonoco Products Company, Georgia-Pacific LLC, Sabert Corporation, Anchor Packaging LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foodservice Disposable Packaging Market Shifts & Advancements
Material science breakthroughs and regulatory compression are converging to redefine performance benchmarks, with functionality no longer assumed to require fossil-derived inputs.
Advanced molded fiber forming is rewriting the competitive map for hot-food containment. Precision thermoformed fiber geometries now match polystyrene's insulation properties at comparable unit economics. European quick-service chains are specifying these containers for fry and burger packaging at scale. The technology is rewriting capital allocation patterns as thermoforming equipment suppliers retool for fiber-dominant product mixes.
REACH restrictions on intentionally added microplastics are tightening the regulatory noose around conventional polymer additives. Industrial consequence includes reformulation costs for colorants and slip agents throughout the European supply base. Quick-service packaging in Germany and France is responding fastest, with chains preemptively eliminating suspect additives ahead of enforcement deadlines.
Aggregator-platform procurement consolidation is compressing supplier diversity in Southeast Asian markets. GrabFood and Foodpanda are centralizing packaging specifications across multi-brand cloud kitchen portfolios, displacing restaurant-level purchasing autonomy. This concentration is most visible in Bangkok and Jakarta, where platform-specified containers now dominate last-mile presentation standards.
Foodservice Disposable Packaging Market Segmentation
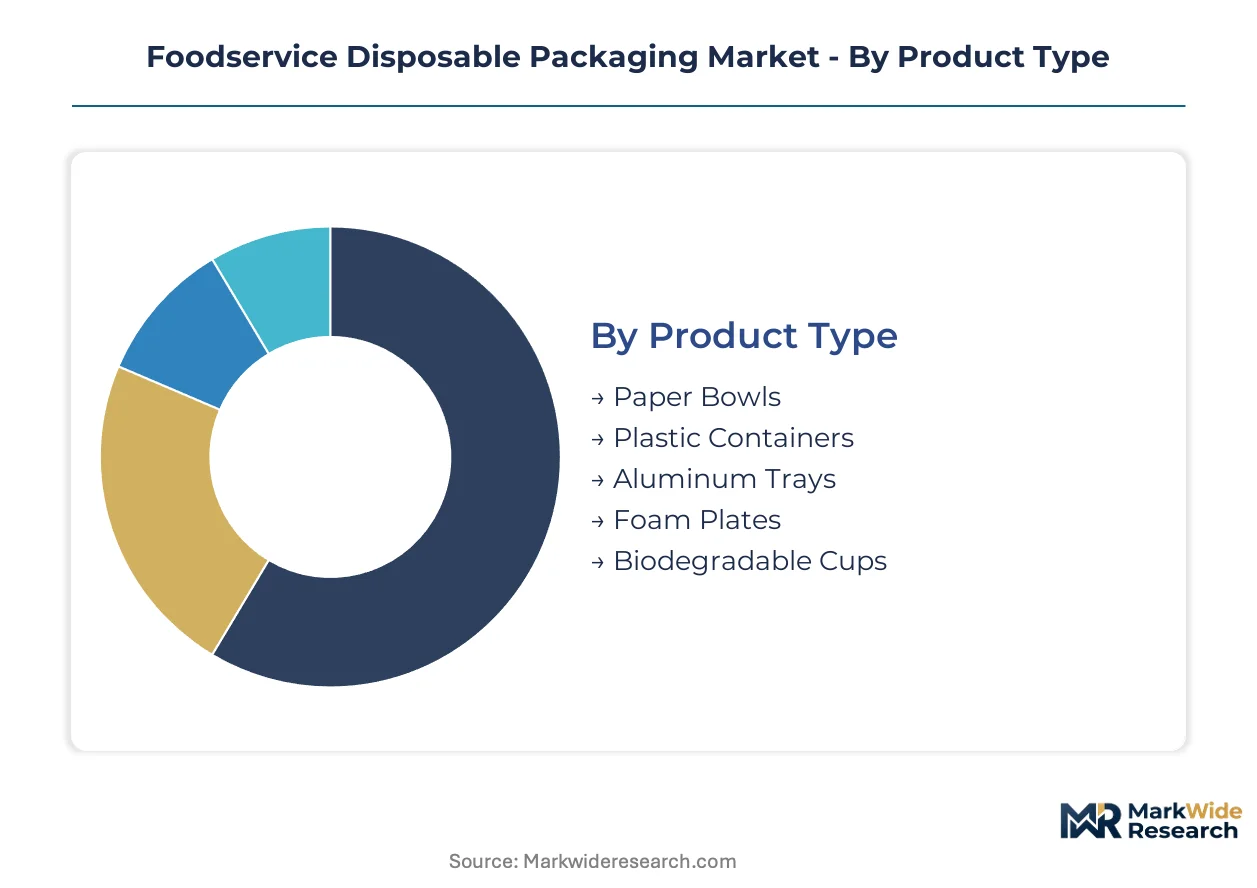
Foodservice disposable packaging segmentation reveals how substrate choices, application intensity, and end-user procurement scale create divergent margin profiles across the value chain. Understanding these fault lines enables suppliers to align capacity investments with where specification power and volume growth actually concentrate.
Product Type:
Standardized formats dominate high-volume quick-service procurement, while custom geometries command premiums in catering and delivery segments where brand presentation drives repeat purchase.
- Paper Bowls:Thermoformed fiber constructions with aqueous grease barriers now match polystyrene's hot-fill performance at scale. India's cloud kitchen corridors and Southeast Asian aggregator platforms are specifying these for rice and noodle applications as polystyrene phase-outs accelerate.
- Plastic Containers:Polypropylene and PET formats retain unmatched barrier properties for acidic, high-fat prepared foods and extended shelf-life meal kits. Liquid-heavy applications in North American retail-ready segments preserve polymer dominance where fiber substitutes still fail migration and shelf-stability thresholds.
- Aluminum Trays:Oven-ready formats with lidded configurations serve premium catering and airline meal segments where reheat uniformity commands price premiums.
- Foam Plates:Expanded polystyrene formats face collapsing demand across EU member states under Single-Use Plastics Directive enforcement, with residual volume concentrating in US institutional procurement.
- Biodegradable Cups:PLA and bagasse-lined formats attract specification in German and French quick-service chains seeking compostable credentials, though industrial composting infrastructure gaps limit end-of-life value realization elsewhere.
Most installed capacity flows through Plastic Containers. Expansion is steepest in Paper Bowls.
Material:
Cost tier stratification separates commodity pulp grades from engineered biopolymers, with energy and logistics inputs driving margin volatility most acutely in integrated fiber supply chains.
- Cardboard:Unbleached kraft and clay-coated solid bleached sulfate grades anchor quick-service clamshell and pizza box production. European converters are retooling lines for higher recycled content thresholds as extended producer responsibility schemes in Maine and Oregon reshape cost structures.
- Polystyrene:Virgin and recycled-content expanded and solid grades face regulatory compression across EU member states and growing US municipal restrictions, with remaining demand concentrating in price-sensitive institutional segments.
- Polypropylene:Homopolymer and random copolymer grades deliver microwave-safe, dishwasher-durable performance for reusable container pilots and extended-use meal kit applications.
- Bamboo Fiber:Rapid-renewable grass pulp substitutes offer Asian supply base advantages for molded fiber converters serving quick-service chains with Asian market exposure.
- Bagasse:Sugarcane processing residue provides fiber feedstock with lower water intensity than wood pulp, attracting sustainability-linked procurement from US coastal quick-service operators.
Cardboard commands the largest production footprint. Bagasse is climbing the fastest as converters seek agricultural fiber alternatives to softwood pulp volatility.
Application:
Volume concentration varies sharply by occasion type, with aggregator-platform dependence creating procurement centralization in delivery corridors that displaces restaurant-level purchasing autonomy.
- Fast Food Chains:Standardized specifications across thousands of outlets create massive procurement scale, with European chains preemptively eliminating suspect polymer additives ahead of REACH microplastics enforcement deadlines.
- Catering Services:Event-driven demand with high seasonality requires flexible supply arrangements, with premium aluminum tray and lidded fiber formats dominating wedding and corporate segments.
- Cafeterias:Institutional procurement through group purchasing organizations favors cost-optimized foam and paper formats, though US K-12 and university segments are shifting toward compostable mandates.
- Street Vendors:Fragmented, price-sensitive demand across emerging market urban cores relies on lowest-unit-cost polystyrene and thin-gauge plastic formats with minimal barrier performance.
- Delivery Packaging:GrabFood and Foodpanda centralization in Bangkok and Jakarta is compressing supplier diversity, with platform-specified containers now dominating last-mile presentation standards across multi-brand cloud kitchen portfolios.
Fast Food Chains absorb the greatest production volume. Delivery Packaging is gaining share fastest as aggregator penetration deepens.
End User:
Customer type determines specification complexity, with full-service and event-driven segments demanding custom geometries that quick-serve and institutional buyers reject.
- Restaurants:Independent operators retain fragmented purchasing patterns, while chain consolidation is recalibrating procurement volumes toward centralized specification and direct mill relationships.
- Hotels:In-room dining and banquet operations require premium presentation formats with brand-coordinated printing, with luxury properties specifying molded fiber with embossed logos.
- Event Organizers:Single-use mandates at music festivals and sporting venues in Germany and Netherlands are driving compostable format adoption, though infrastructure gaps elsewhere limit geographic transferability.
- Food Trucks:Mobile operators prioritize space-efficient, nested formats with thermal retention for extended holding periods, favoring foam clamshells where regulations permit.
- Institutional Dine-In:Healthcare and correctional facilities demand tamper-evident, portion-controlled formats with food-contact safety documentation meeting FDA notification requirements.
Restaurants represent the largest addressable base. Event Organizers are expanding most quickly as experience-economy formats proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's fiber-based packaging conversion outpaces India's volume growth, yet both markets face divergent infrastructure constraints that shape supplier strategies.
United States
Quick-service chains and cloud kitchens drive container demand across urban delivery corridors. Maine and Oregon extended producer responsibility laws shift cost structures toward producer-funded recovery. The Pacific Northwest and Northeast coastal states concentrate compostable packaging adoption where industrial composting facilities exist.
Germany
REACH microplastics restrictions and Single-Use Plastics Directive enforcement eliminate expanded polystyrene from quick-service specifications. ECHA reformulation deadlines accelerate additive-free polymer development. The Rhine-Ruhr industrial corridor hosts molded fiber capacity expansion serving pan-European quick-service accounts.
India
Swiggy and Zomato aggregator platforms multiply cloud kitchens across tier-2 cities including Jaipur, Lucknow, and Kochi. FSSAI migration limits and BIS labeling requirements tighten food-contact safety standards for organized retail channels. Mumbai-Pune and Bengaluru corridors concentrate first-mover packaging specification opportunities.
France
Loop-style returnable container pilots with quick-service chains pioneer service-revenue models beyond single-use unit sales. EU Green Deal implementation timelines compress polymer phase-out schedules ahead of neighboring markets. The Paris basin anchors premium catering and airline meal packaging demand.
Thailand
GrabFood centralizes packaging specifications across multi-brand cloud kitchen portfolios in Bangkok. Platform-specified containers displace restaurant-level purchasing autonomy throughout metropolitan delivery zones. The Chao Phraya corridor concentrates last-mile presentation standard consolidation.
Foodservice Disposable Packaging Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across substrate categories, creating tiered competitive dynamics. The vendor base clusters around three strategic archetypes: integrated pulp-to-package converters, substrate-specific thermoforming specialists, and diversified multi-material platforms. Consolidation pressures intensify as quick-service procurement centralization favors suppliers with cross-regional scale. Capacity expansion and backward integration into raw pulp supply represent dominant competitive moves.
Among Nordic-integrated converters, Huhtamäki Oyj exemplifies the molded fiber specialist archetype with European quick-service penetration. Dart Container Corporation anchors North American foam and plastic production capacity. Pactiv Evergreen Inc. occupies a diversified multi-material position spanning pulp integration through finished container supply. These three entities represent distinct strategic postures within a market fragmenting along substrate and geography lines.
| Leading Market Players |
|---|
| Huhtamäki Oyj |
| Dart Container Corporation |
| Pactiv Evergreen Inc. |
| Berry Global Inc. |
| Graphic Packaging International, LLC |
| Sonoco Products Company |
| Georgia-Pacific LLC |
| Sabert Corporation |
| Anchor Packaging LLC |
| Others |
Supply & Pricing Matrix
Molded fiber thermoforming advances are compressing unit economics for hot-food containers while concentrating specification power among European quick-service chains with direct mill relationships. This substrate transition simultaneously elevates capital barriers for new converters and rewards integrated pulp-to-package players with captive fiber supply.
Pricing Analysis
Capacity additions in Germany and the Netherlands are reshaping price floors for aqueous-barrier paper bowls as Rhine-Ruhr converters achieve scale efficiencies. Three-tier pricing structure across premium molded fiber, standard clay-coated grades, and economy polystyrene residual segments reflects certification grade and volume scale differentiation. Cost compression in economy tiers is intensifying because Indian aggregator platforms are consolidating procurement across cloud kitchen portfolios. Institutional cafeterias exhibit highest price sensitivity; premium catering services demonstrate lowest.
Supply Chain Analysis
Skilled thermoforming technician shortages in Finland and Wisconsin are constraining molded fiber capacity ramp rates despite equipment availability. Supply concentrates in Germany, China, and the United States for precision aluminum die production and fiber pulping infrastructure. Raw material dependencies center on Northern European softwood pulp, Brazilian eucalyptus fiber, and PLA biopolymer feedstocks. Single-source vulnerability runs through precision aluminum tooling for complex geometries. Distribution runs through quick-service chain direct procurement and aggregator-platform centralized specification in urban delivery corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Foodservice disposable packaging offers margin expansion through barrier coating premiumization and substrate substitution tailwinds. Cost-down drivers in fiber forming and biopolymer scale economics support this trajectory.
For Market Incumbents: Extend molded fiber capacity in the Rhine-Ruhr corridor to capture European quick-service specification consolidation. Deepen backward integration into Brazilian pulp supply to insulate against Nordic energy cost volatility. Preempt REACH additive restrictions through reformulation investment ahead of ECHA enforcement deadlines.
For New Entrants and Emerging Players: Aqueous barrier coating specialization offers entry into Indian tier-2 city cloud kitchen procurement before standards consolidate. Target Jaipur and Lucknow delivery corridors where Swiggy and Zomato are penetrating without established supplier relationships. Lead with compostable certification and platform-direct sales models.
For Investors and Strategic Acquirers: Valuations sit cheapest among non-integrated thermoforming specialists lacking pulp captive supply. Five-to-ten-year viability favors converters with demonstrated quick-service chain qualification and geographic diversification beyond single-region regulatory exposure. Monitor EU member state composting infrastructure buildout as inflection indicator for compostable format value realization.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Supply | Captive fiber sourcing insulates margin against Nordic energy volatility and Brazilian logistics swings. |
| Barrier Coating R&D Partnership | Collaboration with PLA and aqueous chemistry specialists closes performance gaps against polymer containers. |
| Aggregator Platform Direct Contracting | Centralized procurement with GrabFood and Foodpanda locks in volume across multi-brand cloud kitchen portfolios. |
| Composting Infrastructure Joint Venture | Partnerships with German and Dutch facility operators secure end-of-life value realization for certified formats. |
| Precision Tooling Capacity Expansion | Aluminum die production in-house cuts 16-24 week lead times constraining seasonal product development cycles. |
Research Methodology
Coverage spans Germany, India, the United States, and Southeast Asia, with primary inputs from each region combining executive interviews with quick-service chain procurement directors, molded fiber plant managers, aggregator platform supply chain leads, and food-contact regulatory consultants. Secondary validation draws from EU Single-Use Plastics Directive implementation tracking, FDA food-contact substance notification databases, FSSAI labeling circulars, and Indian BIS standard revisions. Bottom-up volume modeling triangulates with top-down value chain analysis across substrate categories.
Granularity-level modeling operates at product type-by-material-by-application intersection, with separate treatment of fast food chain, catering service, and delivery packaging demand drivers. CAGRs derive from segment-level volume trajectories applied to evolving average selling price assumptions. Forecast inputs incorporate pulp futures curves, thermoforming equipment installation pipelines, and regulatory phase-out timelines across EU member states and US coastal jurisdictions.
The model holds under continued EU Single-Use Plastics Directive enforcement and Indian aggregator platform growth; deviation in composting infrastructure deployment or biopolymer feedstock cost spikes would shift substrate substitution trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Foodservice Packaging
Canada Foodservice Packaging Market
Foodservice Packaging
Foodservice Paper Bags Market
Foodservice Packaging
France Disposal Tableware Market
Foodservice Packaging
Italy Disposable Tableware Market
Foodservice Packaging
Compostable Food Service Packaging Market
Foodservice Packaging
Compostable Food Service Tray Market
Foodservice Packaging
United States Disposable Tableware Market
Foodservice Packaging
Bar and Prep Faucets Market
Foodservice Packaging
Food Service Packaging (FSP) Market
Foodservice Packaging
North America Foodservice Packaging Market