
 Compostable Food Service Packaging Market | 2026-2036
Compostable Food Service Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Compostable Food Service Packaging Market Analysis
Independent cafes and fast-casual chains is collapsing the historical dominance of institutional foodservice buyers in compostable packaging procurement. World Centric leverages its West Coast manufacturing base to supply biopolymer clamshells directly to regional restaurant groups. Huhtamaki Oyj anchors European demand through its molded fiber production network across Finland and Germany. Vegware Ltd competes in the UK and Irish markets with transparent supply chain certifications that resonate with contract catering buyers.
Compostable food service packaging comprises single-use items engineered from biopolymers or plant fibers to degrade in industrial composting conditions within specified timeframes, typically meeting ASTM D6400 or EN 13432 standards for disintegration and ecotoxicity. PLA dominates material type volumes due to existing resin capacity and thermal performance suited to cold applications, though bagasse grows fastest where microwave-safe properties matter for takeaway containers. Cutlery lags plates and bowls in adoption because durability requirements strain current biopolymer formulations, concentrating margin pools in lidded containers for food delivery platforms.
FDA regulates food contact substances for compostable packaging in the United States, while the EU F-Gas Regulation and REACH restrict certain chemical additives in fiber-based products. BPI certification in North America and TÜV Austria's OK Compost INDUSTRIAL mark in Europe function as de facto market access requirements, filtering out uncertified imports. Stakeholders must monitor whether municipal composting facility expansion keeps pace with packaging unit growth to avoid landfill diversion that undermines environmental claims.
Market Dynamics
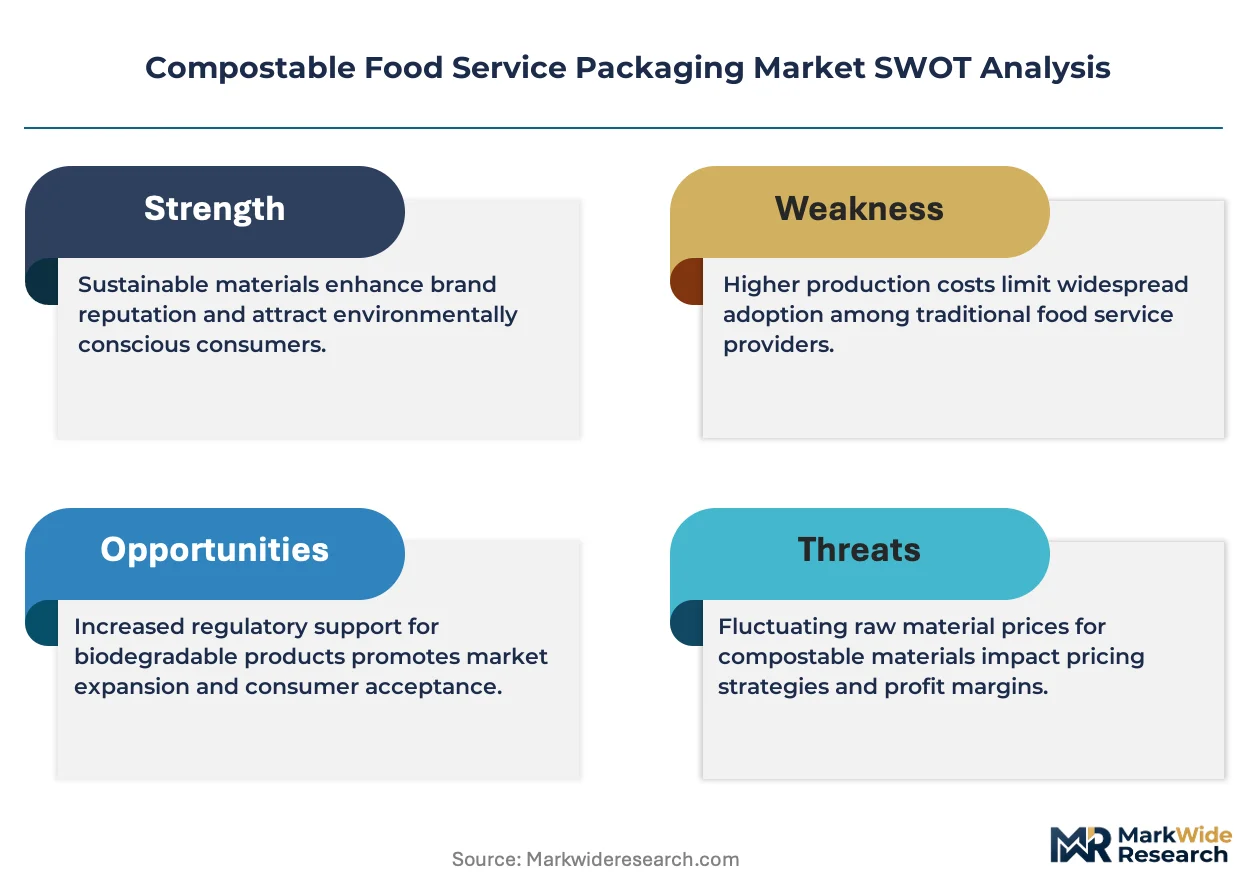
Municipal composting infrastructure gaps are forcing packaging manufacturers to absorb end-of-life verification costs, compressing margins while certified product premiums erode under volume competition from uncertified imports.
Growth Catalysts
- EU Single-Use Plastics Directive:The ban on conventional plastic serviceware across member states mandates material transitions in foodservice procurement, creating immediate substitution demand for certified alternatives.
- Bagasse fiber technology:Microwave-safe molded fiber formulations are capturing takeaway container volumes previously held by expanded polystyrene, particularly in fast-casual restaurant chains.
- California and New York state bans:State-level legislation ahead of federal action is concentrating early-adopter procurement volumes in these jurisdictions, pulling manufacturing capacity westward.
Market Restraints
- PLA resin supply concentration:Biopolymer feedstock dependence on corn starch processors in the US Midwest creates input cost volatility tied to agricultural commodity cycles.
- Industrial composting facility scarcity:Limited municipal processing capacity in secondary US cities diverts certified packaging to landfill, undermining environmental claims and buyer willingness-to-pay.
- Cutlery durability limitations:Current biopolymer formulations fail heat-resistance thresholds required for hot-food applications, ceding premium utensil segments to conventional plastics.
Strategic Opportunities
- Home composting certification expansion:TÜV Austria's OK Compost HOME standard opens residential end-of-life pathways in European markets lacking industrial facility access.
- Food delivery platform integration:Direct supplier relationships with aggregator apps bypass distributor markups and capture lidded container volumes at scale.
- Blockchain supply chain verification:Distributed ledger tracking from farm fiber to compost facility addresses greenwashing accusations and supports premium pricing.
Industry Challenges
- ASTM D6400 certification timelines:Third-party testing protocols for disintegration and ecotoxicity extend product launch cycles by 8-14 months, delaying revenue recognition.
- Composting facility integration complexity:Packaging designed for industrial conditions requires coordination with municipal waste operators on contamination thresholds and processing speeds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compostable Food Service Packaging Market |
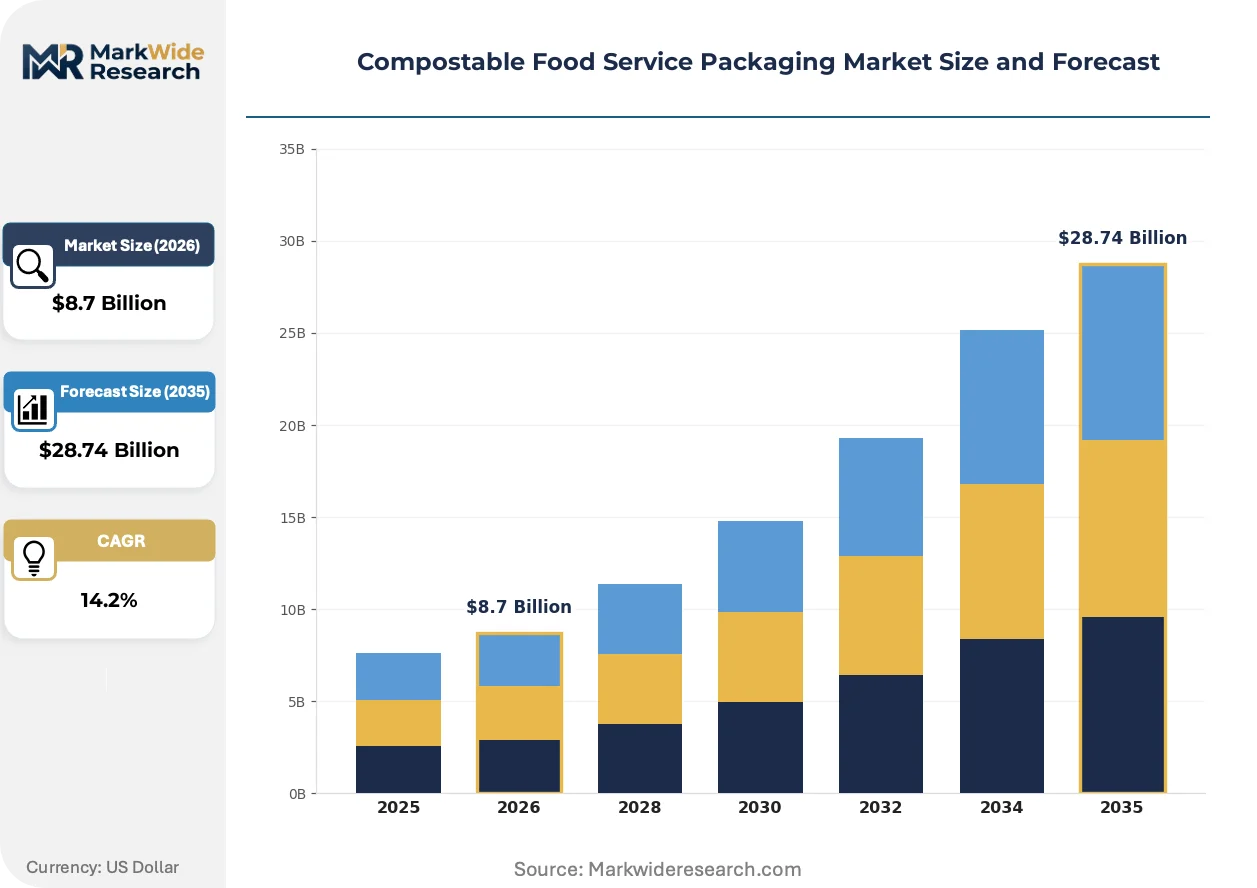
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: PLA, PHA, Bagasse, Wheat Straw Application: Takeaway, Catering, Food Delivery, Fast Food End User: Restaurants, Cafes, Catering Services, Food Trucks Product Type: Plates, Bowls, Containers, Cutlery |
| Companies Covered | BioPak, World Centric, Huhtamaki Oyj, Genpak LLC, Pactiv Evergreen Inc., Dart Container Corporation, Eco-Products, Sabert Corporation, Vegware Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compostable Food Service Packaging Market Emerging Trajectories
Material science breakthroughs and regulatory enforcement tightening are converging to redefine performance benchmarks and procurement criteria across foodservice packaging categories.
PHA (polyhydroxyalkanoate) thermoformed containers are supplanting PLA in hot-food applications due to superior heat deflection temperatures above 100°C. Quick-service chains in the US Southwest are piloting PHA clamshells for fried protein packaging, compressing the historical PLA-bagasse duopoly in temperature-critical segments.
REACH chemical restriction amendments are eliminating per- and polyfluoroalkyl substances (PFAS) from molded fiber food contact materials across EU markets. The ban forces fiber producers to reformulate oil and grease barriers using bio-based coatings, raising unit costs while creating first-mover advantage for compliant suppliers in German and French institutional catering contracts.
Certification-driven preference consolidation is concentrating procurement authority among buyers demanding BPI or TÜV Austria marks as table-stakes qualifications. Contract catering operators in the UK and Ireland are disintermediating uncertified distributors, sourcing directly from manufacturers with transparent chain-of-custody documentation to satisfy corporate sustainability reporting requirements.
Compostable Food Service Packaging Market Segmentation
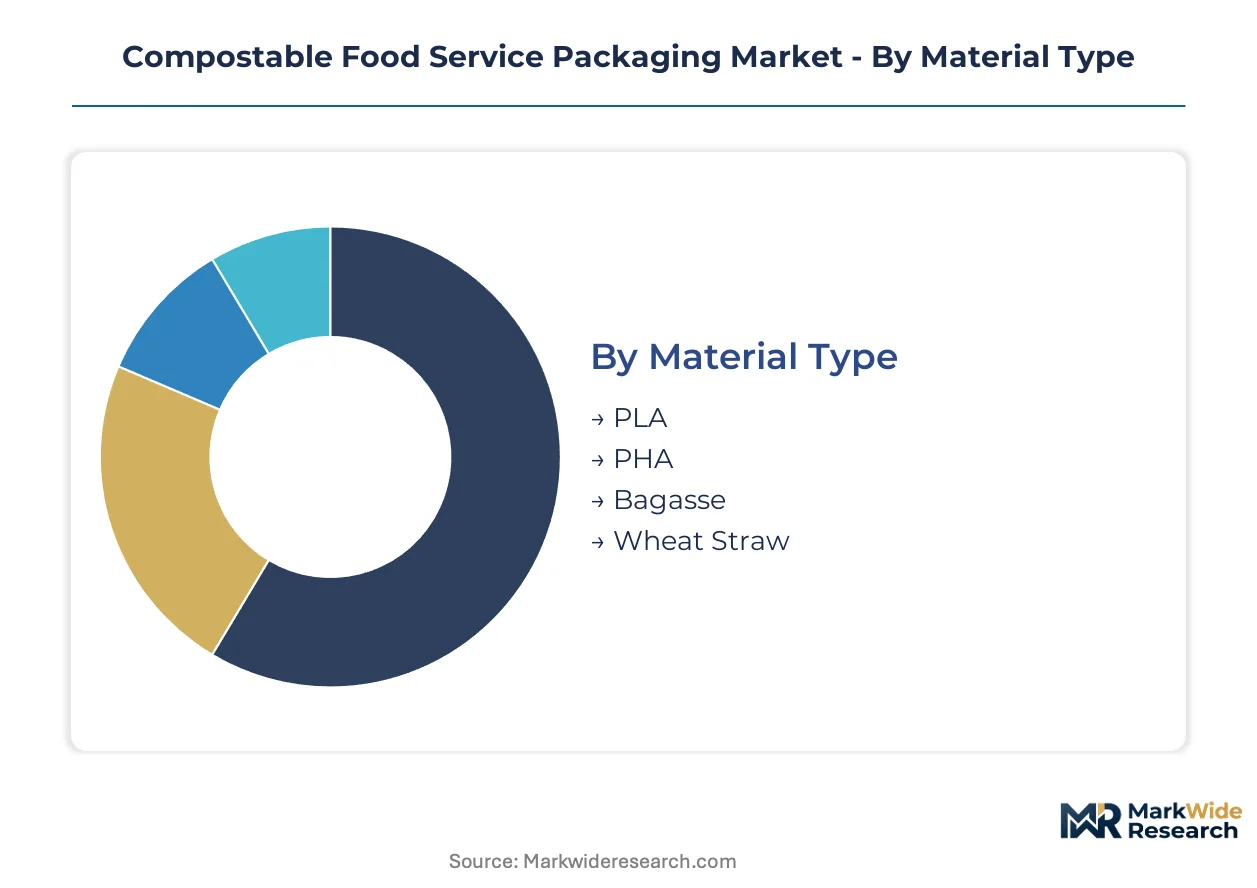
Compostable food service packaging segments diverge sharply by material performance thresholds and end-of-life pathway requirements. Channel mix varies: institutional buyers prioritize certified bulk formats, while food delivery platforms drive lidded container innovation.
Material Type:
Channel flows split between direct manufacturer relationships for high-volume PLA and distributor-mediated specialty resins for emerging biopolymers.
- PLA:Corn-starch-derived polylactic acid delivers thermal stability for cold applications and dominates existing resin production capacity. Quick-service chains in the United States specify PLA clamshells for refrigerated display cases, though heat deflection limitations exclude hot-food segments.
- PHA:Microbial fermentation yields polyhydroxyalkanoate with superior heat resistance exceeding 100°C. Pilot deployments in US Southwest fried protein packaging are displacing both PLA and bagasse where temperature performance is non-negotiable.
- Bagasse:Sugarcane fiber pulp provides microwave-safe molded fiber for takeaway containers.
- Wheat Straw:Agricultural residue fiber offers lower-density alternatives for cold-service plates and bowls.
PLA dominates installed base. PHA is where expansion concentrates.
Application:
Cost tier stratification separates premium certified formats for corporate catering from economy-grade alternatives for high-volume fast food.
- Takeaway:Single-use containers and bags engineered for consumer transport of prepared meals. Bagasse fiber bowls capture fast-causal chain procurement in California and New York where municipal composting access is concentrated.
- Catering:Bulk serviceware for institutional events and corporate dining. Contract operators in the UK and Ireland demand TÜV Austria OK Compost INDUSTRIAL certification as a table-stakes qualification, disintermediating uncertified distributors.
- Food Delivery:Lidded containers optimized for aggregator platform logistics. Direct supplier relationships with delivery apps bypass traditional distributor markups and capture volume at scale.
- Fast Food:High-velocity disposable formats for quick-service restaurant chains. PHA thermoformed clamshells are gaining traction for hot protein packaging where PLA warping is unacceptable.
Takeaway commands current volume share. Food Delivery is climbing the fastest.
End User:
Customer type determines procurement authority concentration versus fragmentation.
- Restaurants:Full-service and casual dining establishments specifying compostable alternatives for dine-in and takeout. Independent cafes and fast-casual chains are collapsing historical institutional buyer dominance through direct manufacturer relationships.
- Cafes:Coffee-focused operations requiring cup, lid, and sleeve formats. West Coast manufacturing bases supply biopolymer clamshells directly to regional cafe groups, compressing distributor margins.
- Catering Services:Event and institutional foodservice operators. Corporate sustainability reporting requirements drive preference for blockchain-verified supply chain documentation.
- Food Trucks:Mobile food vendors with limited storage and high turnover. Economy-grade bagasse formats dominate where certification premiums strain operational budgets.
Restaurants anchor procurement volume. Catering Services is where margin expansion concentrates.
Product Type:
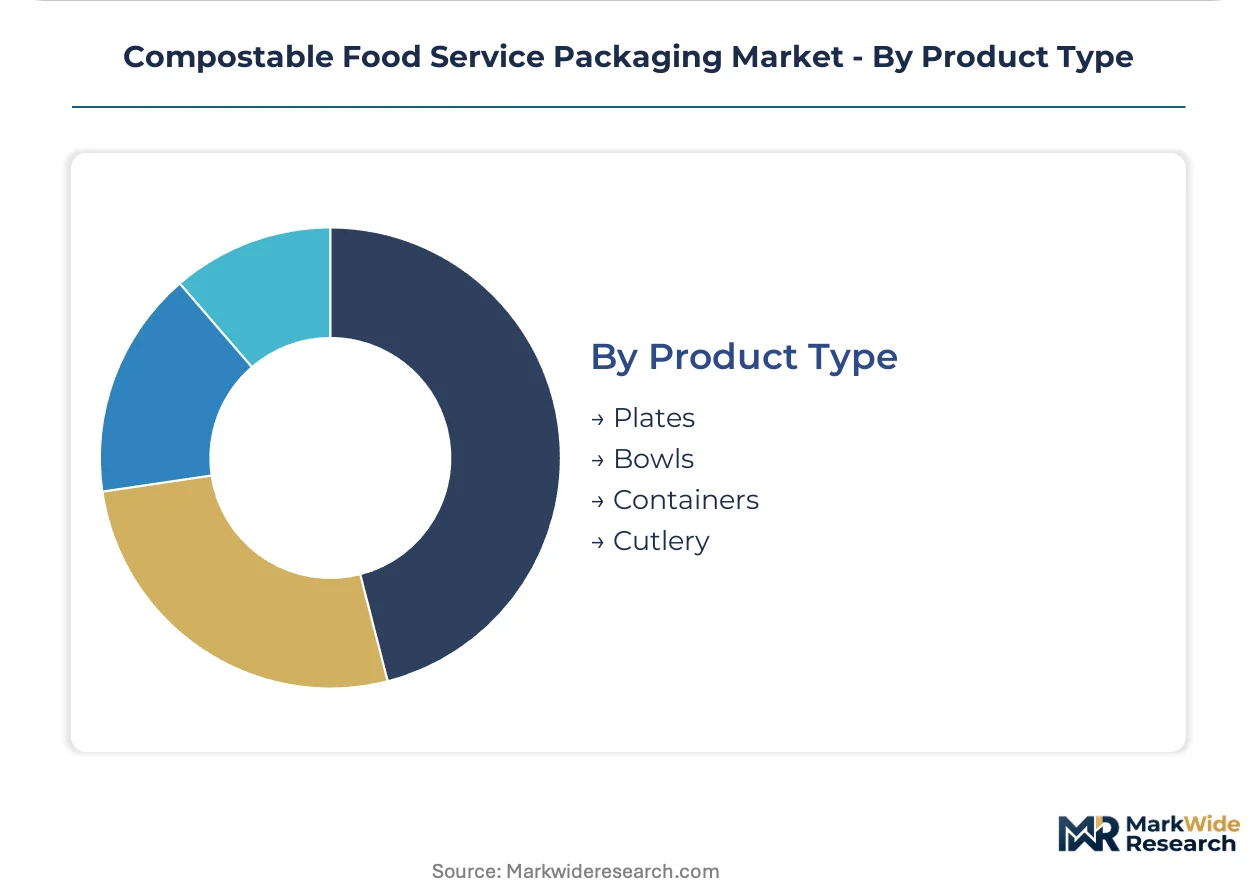
Volume distribution skews toward containment formats while durability constraints suppress utensil adoption.
- Containers:Lidded and clamshell formats for meal transport and storage. Food delivery platform integration captures this segment at scale, with PHA formulations displacing PLA-bagasse duopoly in temperature-critical applications.
- Plates:Flat serviceware for dine-in and buffet service. Molded fiber production networks across Finland and Germany anchor European supply for institutional contracts.
- Bowls:Deep formats for soups, grain bowls, and mixed dishes. Microwave-safe bagasse formulations are capturing volumes previously held by expanded polystyrene in fast-casual chains.
- Cutlery:Forks, knives, and spoons from biopolymer or fiber materials. Current formulations fail heat-resistance thresholds for hot-food applications, ceding premium utensil segments to conventional plastics.
Containers dominate revenue contribution. Bowls is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Institutional buyers and quick-service chains concentrate procurement authority in jurisdictions with mature composting infrastructure and enforceable single-use plastic bans. Geographic demand patterns track regulatory stringency and municipal waste processing capacity rather than population density alone.
United States
California and New York state legislation mandates certified compostable alternatives ahead of federal action, pulling manufacturing capacity toward the West Coast. FDA food contact substance regulations govern material safety, while BPI certification functions as de facto market access. World Centric leverages its West Coast manufacturing base to supply biopolymer clamshells directly to regional restaurant groups in the Bay Area and Los Angeles metro.
Germany
Institutional catering contracts in Bavaria and North Rhine-Westphalia drive premium-tier demand for TÜV Austria-certified formats. REACH chemical restrictions eliminate PFAS from molded fiber food contact materials, forcing reformulation of oil and grease barriers. Huhtamaki Oyj anchors European supply through its molded fiber production network across Finland and Germany, capturing volumes in Frankfurt and Munich foodservice procurement.
United Kingdom
Contract catering operators in London and the Southeast disintermediate uncertified distributors, sourcing directly from manufacturers with transparent chain-of-custody documentation. Corporate sustainability reporting requirements concentrate procurement authority among buyers demanding OK Compost INDUSTRIAL marks. Vegware Ltd competes in UK and Irish markets with supply chain certifications that resonate with contract catering buyers in Greater London.
France
Quick-service chains in Île-de-France pilot PHA thermoformed containers for hot-food applications where PLA warping is unacceptable. EU Single-Use Plastics Directive enforcement accelerates material transitions in Paris metro foodservice procurement. Bio-based coating specialists in Auvergne-Rhône-Alpes capture first-mover advantage in PFAS-compliant fiber barrier formulations for institutional contracts.
Canada
Health Canada and PMRA regulate food contact substances while provincial composting infrastructure expansion lags packaging availability in Toronto and Vancouver metros. Municipal procurement in Ontario and British Columbia prioritizes certified compostable formats for institutional foodservice. Pacific Northwest supply chain linkages connect Canadian buyers to West Coast manufacturing capacity for biopolymer resin and molded fiber inputs.
Compostable Food Service Packaging Market Vendor Landscape
Player mix skews toward mid-cap specialists with captive biopolymer resin capacity or regional molded fiber production networks. Market structure concentrates around three strategic archetypes: West Coast biopolymer formulators serving quick-service chains, European molded fiber producers anchoring institutional contracts, and UK-based certification-focused suppliers capturing contract catering. Dominant competitive moves include direct manufacturer relationships bypassing distributor markups and geographic capacity expansion to serve state-level ban jurisdictions.
Within the West Coast biopolymer tier, World Centric and Eco-Products occupy positions defined by proximity to California and Oregon procurement gravity. European molded fiber production is represented by Huhtamaki Oyj, which exemplifies the integrated producer archetype with cross-border manufacturing networks. Among certification-focused specialists, Vegware Ltd represents the transparent supply chain positioning that resonates with UK and Irish contract catering buyers demanding TÜV Austria marks.
| Leading Market Players |
|---|
| BioPak |
| World Centric |
| Huhtamaki Oyj |
| Genpak LLC |
| Pactiv Evergreen Inc. |
| Dart Container Corporation |
| Eco-Products |
| Sabert Corporation |
| Vegware Ltd |
| Others |
Supply Flow & Price Mechanics
Inventory cycles stretching 90-120 days for PLA resin shipments from US Midwest corn processors compress margin buffers for West Coast formulators while amplifying pricing power among bagasse fiber suppliers with integrated pulp operations. This lead-time asymmetry between biopolymer feedstocks and plant-fiber alternatives concentrates procurement leverage among buyers with multi-material qualification capabilities.
Pricing Analysis
The technology-generation pricing gap separates incumbent PLA formulations from emerging PHA thermoforms and next-generation home-compostable resins. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and heat-resistance performance, with BPI-certified PHA clamshells commanding substantial premiums over uncertified bagasse alternatives. Pricing pressure stems from volume competition in PLA cold-service segments where resin capacity expansion outpaces differentiated product development. Quick-service chains exhibit highest price sensitivity in high-velocity cutlery procurement, while contract catering operators demonstrate lowest sensitivity when sustainability reporting requirements mandate certified formats.
Supply Chain Analysis
Inbound logistics costs from Asia-Pacific fiber pulp shipments through West Coast ports strain molded fiber producers dependent on imported agricultural residues. Raw material sourcing concentrates in Thailand and India for bagasse pulp, the US Midwest for corn-starch PLA feedstock, and Brazil for sugarcane-derived biopolymers. Supply chain risk centers on single-source vulnerability for PHA fermentation capacity, where limited commercial-scale producers create bottleneck exposure. Distribution runs through foodservice distributor networks in North America, direct manufacturer relationships with delivery platforms, and institutional procurement consortia in European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The compostable food service packaging market represents a high-growth disruption anchored by regulatory bans on conventional plastics and material science breakthroughs in heat-resistant biopolymers. PHA commercialization and PFAS-free fiber barrier formulations constitute the technological inflection redefining competitive viability.
For Market Incumbents: Shield core PLA capacity positions by securing captive corn-starch supply agreements with Midwest processors before agricultural commodity volatility intensifies. Accelerate PHA pilot-to-scale transitions in US Southwest quick-service chain partnerships to preempt displacement by fermentation specialists. Certification investment in TÜV Austria OK Compost HOME standards opens residential composting pathways where municipal infrastructure lags.
For New Entrants and Emerging Players: Lead with home-compostable certification gaps in secondary US cities lacking industrial facility access, where incumbent products face landfill diversion and reputational damage. Target food truck and mobile vendor segments with economy-grade wheat straw formats where certification premiums strain incumbent cost structures. Blockchain-verified supply chain documentation offers differentiation in UK and Irish contract catering procurement.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because jurisdiction-level plastic bans create guaranteed substitution demand regardless of macroeconomic cycles. Acquisition targets should cluster around mid-cap molded fiber producers with integrated European production networks and established TÜV Austria certification pathways. The signal to watch is municipal composting facility permitting velocity in California and New York state jurisdictions.
| Strategic Initiative | Industry Significance |
|---|---|
| PHA Thermoform Scale-Up | Captures hot-food segments where PLA warping disqualifies incumbent materials from quick-service chain specifications. |
| PFAS-Free Barrier Development | REACH compliance in EU markets creates first-mover advantage for bio-based coating specialists in German institutional contracts. |
| Direct Platform Integration | Bypasses distributor markups by supplying lidded containers directly to food delivery aggregators at volume scale. |
| Home Compost Certification | TÜV Austria OK Compost HOME opens residential end-of-life pathways in markets lacking industrial facility access. |
| Blockchain Chain-of-Custody | Distributed ledger verification addresses greenwashing accusations and supports premium pricing in corporate sustainability reporting. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with quick-service restaurant procurement directors, composting facility operations managers, biopolymer resin plant managers, and foodservice distributor category buyers. Secondary validation drew from FDA food contact substance filings, BPI certification databases, REACH restriction amendments, and municipal composting infrastructure investment records. Bottom-up unit volume estimates across material types and applications were triangulated against top-down market value projections derived from resin capacity disclosures and foodservice procurement expenditure patterns.
Across the analysis window, the forecasting framework modeled volume and value trajectories by material type, application segment, end-user category, and product format. Segmentation dimensions incorporated thermal performance thresholds, certification requirements, and geographic regulatory clusters. CAGRs were derived from elasticity-adjusted substitution rates tied to enforcement timelines for single-use plastic bans and facility expansion curves for municipal composting infrastructure. Industry-specific inputs included PLA resin price indices, bagasse pulp trade flows, and food delivery platform order volume growth patterns.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement, viable composting facility expansion, and biopolymer scale-up economics would require recalibration. Forecasts reflect documented assumptions regarding substitution elasticities and certification adoption curves. Composting infrastructure deployment delays, agricultural commodity price spikes, or PFAS regulatory scope expansion represent specific risk factors that could revise projections. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Foodservice Packaging
United States Disposable Tableware Market
Foodservice Packaging
France Disposal Tableware Market
Foodservice Packaging
Foodservice Disposable Packaging Market
Foodservice Packaging
Bar and Prep Faucets Market
Foodservice Packaging
Italy Disposable Tableware Market
Foodservice Packaging
Foodservice Paper Bags Market
Foodservice Packaging
Compostable Food Service Tray Market
Foodservice Packaging
North America Foodservice Packaging Market
Foodservice Packaging
Food Service Packaging (FSP) Market
Foodservice Packaging
Canada Foodservice Packaging Market