
 United States Disposable Tableware Market | 2026-2036
United States Disposable Tableware Market Size, Share, and Industry Trends Forecast 2026-2036
United States Disposable Tableware Market Analytics
California's SB 54 mandate for source-reduction and recycling is broadening the addressable market for fiber-based and certified-compostable formats. Huhtamaki North America leverages its molded-fiber capacity to supply quick-service chains with plastic-alternative packaging. Dart Container Corporation anchors the insulated-foam segment through extensive thermoforming operations in the Midwest and Southeast. Eco-Products Inc. specializes in plant-based resin formulations that meet BPI certification for commercial composting facilities.
United States disposable tableware encompasses single-use serving items manufactured from plastic resins, paperboard, molded pulp, expanded polystyrene, or bio-based polymers, typically designed for one food-contact event before discard. These products undergo thermoforming, injection molding, or dry-press fiber molding to achieve specified rigidity, grease resistance, and temperature tolerance for safe food service. Plates and cups dominate volume throughput due to universal application across quick-service and casual-dining channels, while biodegradable materials capture expanding shelf space as retail buyers enforce sustainability scorecards. Cutlery lags in fiber substitution because tines and serrated edges require higher modulus materials, leaving this segment dependent on reinforced polylactic acid or hybrid resin systems that carry price premiums over conventional polypropylene.
The FDA regulates food-contact substances under 21 CFR, while the EPA oversees per- and polyfluoroalkyl substance restrictions that threaten legacy grease-resistant coatings, and state legislatures in New York, Washington, and Maine enforce phased bans on expanded polystyrene foodservice items. These overlapping frameworks compel manufacturers to reformulate coatings, validate new substrates, and maintain multi-SKU portfolios that comply with the strictest applicable jurisdiction. Stakeholders must monitor pending federal PFAS rulemakings and state procurement preferences to time capacity investments and avoid stranded inventory in non-compliant material categories.
Market Dynamics
State-level single-use plastic bans are fragmenting the addressable market for conventional polystyrene and polypropylene tableware, forcing manufacturers to maintain parallel SKU portfolios calibrated to jurisdiction-specific material allowances. This regulatory mosaic is compressing production runs and elevating compliance costs across the value chain.
Growth Catalysts
- California SB 54 Mandate:The state's source-reduction and recycling requirements are expanding procurement volume for certified-compostable fiber formats in quick-service and institutional foodservice channels.
- Event Tourism Concentration:Florida and Texas host sustained volume pull from stadium concessions, festival vendors, and hospitality clusters seeking lightweight, low-labor serving solutions.
- Molded-Fiber Thermoforming:Dry-press fiber molding advances are improving grease resistance and structural rigidity, enabling substitution of plastic lids and clamshells in hot-food applications.
Market Restraints
- Pulp Input Volatility:Recycled paperboard and agricultural fiber feedstocks face price swings tied to OCC export demand and seasonal harvest yields, compressing margin predictability for molded-fiber producers.
- PFAS Coating Sunset:EPA restrictions on per- and polyfluoroalkyl substances threaten legacy grease-resistant formulations, requiring capital-intensive reformulation without proven commercial-scale alternatives.
- Composting Infrastructure Gaps:Commercial composting facility density remains uneven across the Midwest and Mountain West, stranding certified-compostable products in landfill streams and eroding buyer confidence.
Strategic Opportunities
- Texas Institutional Procurement:State university systems and correctional facilities represent underpenetrated volume for durable molded-fiber tray formats with extended temperature tolerance.
- Hybrid Resin Cutlery:Reinforced polylactic acid and bio-polypropylene blends offer a technical wedge into the serrated-edge segment where pure fiber substitutes fail.
- Retail Sustainability Scorecards:Major grocery and club-store private-label programs are mandating third-party certifications, creating preferential shelf access for BPI-validated suppliers.
Industry Challenges
- Multi-Jurisdiction Compliance Talent:Few regulatory affairs specialists possess simultaneous fluency in FDA food-contact substance rules, state plastic bans, and municipal composting standards, creating hiring bottlenecks.
- Legacy Thermoforming Asset Stranding:Converting expanded polystyrene lines to fiber-compatible equipment demands seven-figure capital outlays with uncertain payback periods given patchwork state bans.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Disposable Tableware Market |
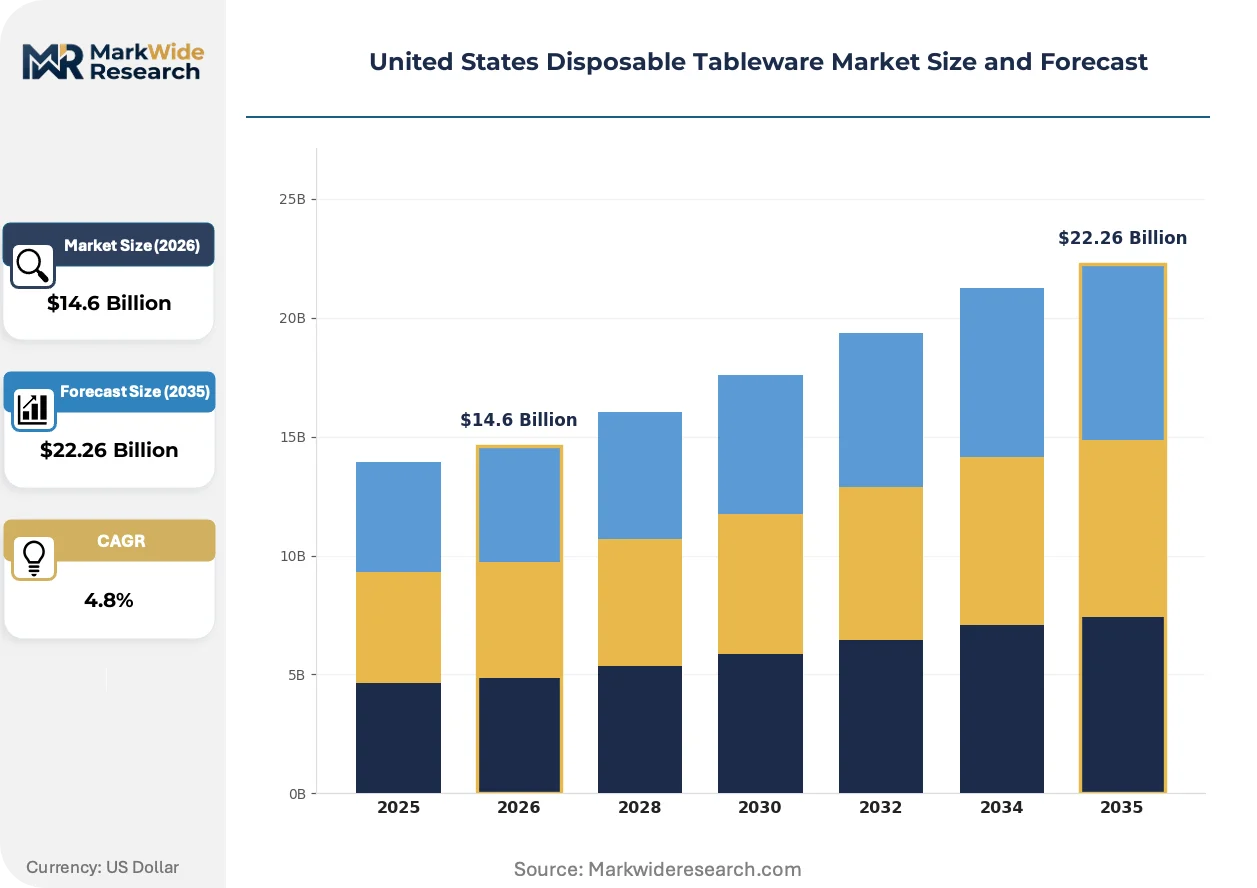
| Market Size in 2026 | $14.6 Billion |
| Market Size in 2035 | $22.26 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plates, Bowls, Cutlery, Cups Material: Plastic, Paper, Biodegradable, Foam End User: Households, Restaurants, Catering Services, Events Distribution Channel: Online, Retail Stores, Wholesale, Direct Sales |
| Companies Covered | Huhtamaki North America, Genpak LLC, Dart Container Corporation, Eco-Products Inc., Sabert Corporation, Georgia-Pacific LLC, Pactiv Evergreen Inc., World Centric, Reynolds Consumer Products, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Disposable Tableware Market Evolving Landscape
Dry-press fiber molding and bio-resin formulation advances are redrawing material boundaries across the disposable tableware category. These technical shifts are compressing the performance gap between conventional plastics and sustainable alternatives.
Dry-press molded fiber technology is decentralizing production geography by enabling smaller-footprint manufacturing facilities closer to agricultural fiber sources. Quick-service chains in the Southeast are piloting regional supply agreements with fiber molders sited near sugarcane bagasse and wheat straw concentrations. This distributed model is reducing freight costs and insulating buyers from resin price volatility tied to petrochemical feedstocks.
EPA rulemakings on PFAS in food-contact applications are accelerating coating substitution timelines. Manufacturers are validating silicone, clay, and bio-wax barrier treatments to maintain grease resistance without fluorinated chemistry. The insulated-foam segment faces the steepest compliance climb, as legacy extruded polystyrene relies heavily on PFAS-treated paperboard laminates for hot-beverage cups.
Foodservice procurement teams are consolidating supplier rosters around vertically integrated molders capable of certifying full material chain-of-custody. Large contract feeders in California and Washington are dropping multi-source bidding in favor of single-partner accountability for compostability claims and regulatory documentation. This concentration is most visible in K-12 and healthcare channels where liability exposure from non-compliant products carries reputational risk.
United States Disposable Tableware Market Segmentation
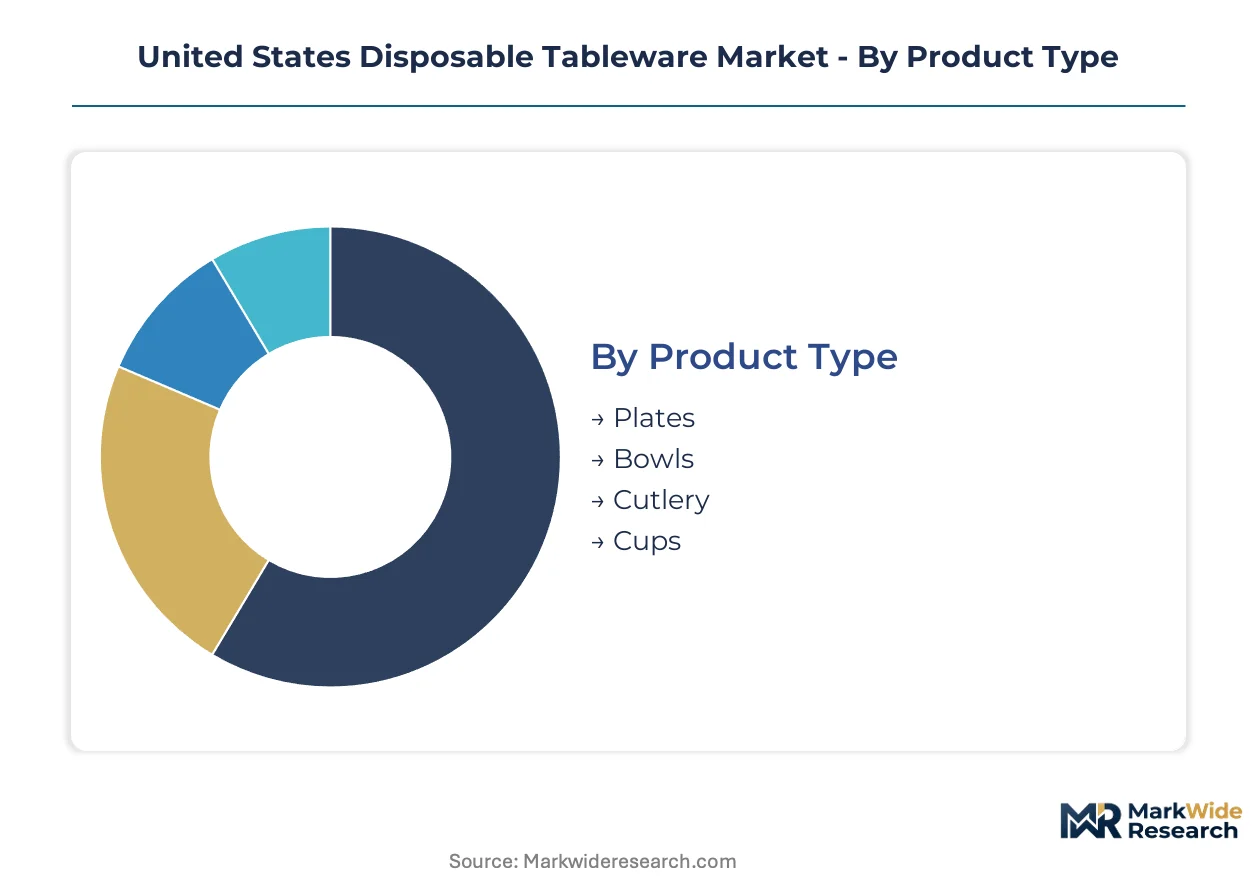
Disposable tableware purchasing decisions split between standardized high-volume formats for institutional buyers and customized specifications for branded foodservice chains. Material certification requirements and state-level regulatory fragmentation further complicate SKU rationalization across manufacturer portfolios.
Product Type:
Standardization dominates plates and cups where thermoforming economies scale efficiently, while cutlery retains customization complexity due to performance engineering demands.
- Plates:Molded fiber and bagasse-based pressed pulp formats achieve grease resistance through silicone barrier coatings. Quick-service chains in California and Washington specify BPI-certified compostable plates to meet procurement mandates. Most installed capacity flows through Plates. Expansion is steepest in Cutlery.
- Cups:Double-wall insulated paperboard and expanded polystyrene compete for hot-beverage applications, with fiber alternatives gaining traction in stadium concessions across Texas and Florida. Lidding compatibility and stack height standardization drive purchasing decisions for high-throughput coffee chains.
- Bowls:Deep-draw fiber molding produces nested bowl formats for grain and salad applications, with petroleum-based plastic alternatives retreating in coastal markets.
- Cutlery:Reinforced polylactic acid and bio-polypropylene blends address torsion and serration requirements where pure fiber substitutes fracture.
Volume concentration favors Plates due to universal meal service applications. Cutlery gains share fastest as fiber-reinforced resin technologies mature.
Material:
Cost tier stratification separates commodity resin volumes from certified-compostable premiums, with regulatory compliance costs compressing mid-tier positioning.
- Plastic:Polypropylene and polystyrene resins retain cost advantage in states without single-use bans, though FDA food-contact substance documentation requirements elevate supplier qualification barriers.
- Biodegradable:Polylactic acid and polyhydroxyalkanoate formulations command price premiums tied to BPI and CMA certification maintenance, with demand clustering in California institutional procurement.
- Paper:Coated paperboard cups and plates leverage existing converting infrastructure, though PFAS coating sunsets threaten legacy grease-resistant specifications.
- Foam:Extruded polystyrene faces phased elimination in New York, Maine, and Washington, stranding Midwest and Southeast manufacturing assets dependent on regional regulatory forbearance.
Plastic retains the largest installed base. Biodegradable formats expand most quickly as composting infrastructure matures in coastal states.
End User:
Application intensity varies dramatically between low-frequency household purchasing and high-velocity foodservice replenishment cycles.
- Restaurants:Quick-service chains drive molded-fiber volume through centralized procurement agreements specifying full material chain-of-custody documentation. California SB 54 compliance requirements favor suppliers with vertical fiber sourcing.
- Events:Stadium concessions and festival vendors in Florida and Texas generate concentrated seasonal demand for lightweight, stackable serving formats with minimal labor requirements for setup and breakdown.
- Catering Services:Full-service caterers balance presentation quality against disposability, specifying premium laminated paperboard for formal occasions.
- Households:Retail shelf placement and club-store private-label programs dominate purchasing, with sustainability scorecards increasingly filtering assortment.
Restaurants absorb the majority of production volume. Events demonstrate the steepest demand trajectory tied to tourism recovery and outdoor venue expansion.
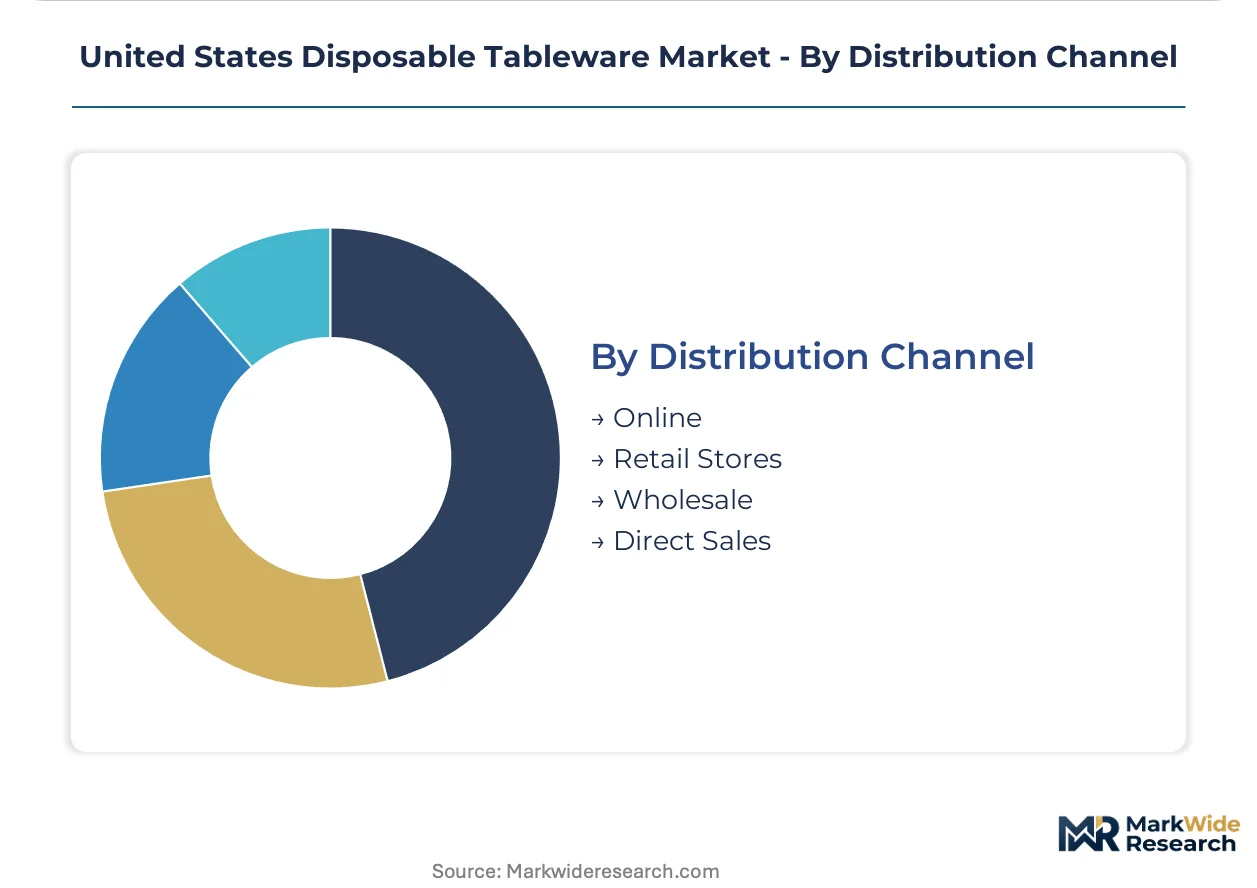
Distribution Channel:
Customer type determines channel preference, with institutional buyers consolidating through direct manufacturer relationships while fragmented foodservice operators rely on distributor intermediaries.
- Wholesale:Broadline distributors maintain regional warehouses supplying independent restaurants and catering operations across the Midwest and Mountain West where composting infrastructure gaps limit certified-product penetration.
- Direct Sales:National quick-service chains negotiate multi-year supply agreements with molded-fiber specialists, consolidating procurement around single-source accountability for regulatory documentation.
- Retail Stores:Grocery and club-store private-label programs mandate third-party sustainability certifications, creating preferential shelf access for BPI-validated suppliers.
- Online:E-commerce penetration remains limited to specialty biodegradable formats and bulk institutional purchasing, with freight economics disadvantaging low-margin commodity resins.
Wholesale channels handle the greatest throughput volume. Direct sales expand fastest as procurement teams consolidate supplier rosters for compliance risk management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foodservice labor pools and agricultural fiber processing expertise concentrate demand in coastal states with stringent environmental mandates, while petrochemical corridor proximity sustains conventional resin production in Gulf Coast and Midwest manufacturing zones.
California
Quick-service restaurant procurement teams and institutional foodservice buyers drive molded-fiber volume through compliance with SB 54 source-reduction mandates. The California Department of Resources Recycling and Recovery enforces rigorous certification requirements for compostable products entering state facilities. Los Angeles and San Francisco Bay Area clusters host vertically integrated fiber molders supplying BPI-validated formats to K-12 and healthcare channels.
Texas
Stadium concessions, festival vendors, and hospitality clusters generate concentrated seasonal demand for lightweight serving solutions across Dallas-Fort Worth and Houston metros. The Texas Commission on Environmental Quality maintains permitting frameworks that accommodate both conventional resin and emerging bio-based material streams. Gulf Coast petrochemical infrastructure anchors expanded polystyrene and polypropylene thermoforming operations serving multi-state distribution.
Florida
Event tourism and outdoor venue expansion sustain high-velocity replenishment cycles for disposable plates and cups in Orlando and Miami-Dade corridors. State procurement guidelines for park and correctional facilities increasingly reference third-party compostability certifications. Tampa Bay and Jacksonville manufacturing zones supply laminated paperboard and insulated foam formats to southeastern distribution networks.
New York
Phased bans on expanded polystyrene foodservice items are compressing addressable volume for legacy foam producers while accelerating fiber-alternative adoption in metropolitan foodservice. The New York State Department of Environmental Conservation administers enforcement timelines that vary by municipality, creating compliance complexity. Hudson Valley and Long Island converting operations pivot toward coated paperboard and molded pulp to serve institutional buyers.
Pacific Northwest
Washington and Oregon state legislatures enforce among the nation's most aggressive single-use plastic elimination schedules, privileging certified-compostable fiber formats in quick-service procurement. The Washington State Department of Ecology coordinates with municipal composting operators to align product specifications with available processing capacity. Seattle and Portland metro areas host pilot programs for regional fiber supply chains sourcing agricultural residues from Columbia River basin wheat and grass seed operations.
United States Disposable Tableware Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent technology paths in the United States disposable tableware market. Consolidated molded-fiber specialists with captive pulp supply maintain cost advantages against resin-dependent thermoformers facing feedstock volatility. Three archetypes dominate: vertically integrated fiber molders with agricultural sourcing relationships, diversified packaging conglomerates with multi-material portfolios, and sustainability-focused niche players with certification-heavy product lines. Capacity expansion and strategic partnerships represent the dominant competitive moves as firms position for state-level regulatory transitions.
Among North American molded-fiber specialists, Huhtamaki North America and Dart Container Corporation exemplify scale-driven archetypes with extensive thermoforming footprints. Eco-Products Inc. occupies a position within the certified-compostable tier, representing the sustainability-focused model that procurement teams increasingly favor for regulatory risk management. These three entities anchor competitive dynamics as foodservice buyers consolidate supplier rosters around single-source accountability for compliance documentation.
| Leading Market Players |
|---|
| Huhtamaki North America |
| Genpak LLC |
| Dart Container Corporation |
| Eco-Products Inc. |
| Sabert Corporation |
| Georgia-Pacific LLC |
| Pactiv Evergreen Inc. |
| World Centric |
| Reynolds Consumer Products |
| Others |
Value Network & Pricing Analysis
Molded-fiber thermoforming technicians in the Pacific Northwest command wage premiums that compress margin spreads between BPI-certified compostable tiers and conventional resin alternatives. Labor-cost differentials between coastal certification-heavy production zones and Gulf Coast petrochemical corridors translate directly into pricing-tier stratification across quick-service procurement contracts.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates BPI-validated fiber formats from mid-tier coated paperboard and commodity polypropylene alternatives. Price differentiation hinges on certification maintenance costs and volume-scale procurement commitments from national quick-service chains. Cost compression in the standard tier is intensifying because agricultural fiber feedstock volatility outpaces resin price stability. Institutional buyers in California and Washington demonstrate lowest price sensitivity due to SB 54 compliance mandates, while independent restaurant operators in the Midwest remain most responsive to per-unit cost differentials.
Supply Chain Analysis
Domestic-content requirements under California SB 54 and Washington state procurement guidelines are reshaping sourcing patterns toward captive pulp supply and regional agricultural fiber processing. Manufacturing concentration spans Michigan thermoforming clusters, Pacific Northwest fiber-molding operations, and Gulf Coast petrochemical corridors. Raw material dependencies include recycled OCC paperboard, sugarcane bagasse, wheat straw residuals, and bio-resin feedstocks. Single-source vulnerability concentrates in PFAS-free barrier coating formulations where commercial-scale alternatives remain limited. Distribution runs through broadline foodservice distributors for fragmented operators and direct manufacturer agreements for consolidated quick-service chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion pathways through backward integration into agricultural fiber sourcing and premium-tier certification positioning that commands procurement preference in regulated coastal states.
For Market Incumbents: To counter stranded-asset risk from expanded polystyrene bans, accelerate dry-press fiber molding capacity additions in Southeast agricultural zones and secure multi-year bagasse supply contracts. Prioritize BPI certification maintenance as a barrier to commodity resin competitors seeking coastal market access. For New Entrants and Emerging Players: PFAS-free silicone barrier coating technology offers entry into the insulated-cup segment where legacy formulations face EPA sunset timelines. Target Texas institutional procurement channels for durable molded-fiber tray formats with extended temperature tolerance. Pursue white-label partnerships with broadline distributors serving correctional and university foodservice systems. For Investors and Strategic Acquirers: Quick-service restaurant chains are the most active acquirer in this space, seeking single-source accountability for regulatory documentation and compostability claims. Long-term viability favors vertically integrated molders with captive agricultural fiber supply and multi-jurisdiction compliance infrastructure. Monitor EPA PFAS rulemaking progression as the inflection signal for coating substitution capex cycles and stranded-foam-asset write-downs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Agricultural Fiber Supply | Captive bagasse and wheat straw sourcing insulates margins from OCC export price volatility. |
| PFAS-Free Barrier Coating Scale-Up | Silicone and bio-wax validation opens insulated-cup revenue streams ahead of EPA restrictions. |
| Direct Sales Consolidation with Quick-Service Chains | Single-source accountability contracts reduce compliance liability exposure in California and Washington. |
| BPI Certification Maintenance Investment | Third-party validation secures preferential shelf access under retail sustainability scorecards. |
| Regional Manufacturing Footprint Expansion | Distributed fiber molding near agricultural sources cuts freight costs and resin price exposure. |
Research Methodology
Multiple input streams — regulatory filings, trade association production data, and foodservice procurement surveys — were reconciled to construct market estimates. Primary interviews with sustainability officers at quick-service chains, procurement directors at broadline distributors, plant managers at molded-fiber facilities, and regulatory affairs specialists at packaging manufacturers informed demand-side and supply-side dynamics. Secondary validation drew from FDA food-contact substance registrations, EPA PFAS rulemaking dockets, state legislative tracking databases, and industry association shipment reports. Bottom-up volume modeling and top-down value reconciliation triangulated segment-level outputs.
Data-stream reconciliation across product type, material substrate, end-user channel, and geographic regulatory cluster anchored the analytical framework throughout the projection horizon. Segmentation dimensions modeled include certification tier, foodservice format, procurement channel concentration, and state-level compliance intensity. CAGRs were derived from trend extrapolation of historical shipment data adjusted for regulatory phase-in schedules and infrastructure buildout timelines. Forecast inputs incorporated composting facility capacity expansion pipelines and quick-service chain sustainability commitment disclosures.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EPA PFAS final rule timing, commercial composting infrastructure deployment rates, and agricultural fiber harvest variability. Forecasts reflect assumptions regarding regulatory enforcement consistency and certification standard harmonization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Foodservice Packaging
Foodservice Paper Bags Market
Foodservice Packaging
Bar and Prep Faucets Market
Foodservice Packaging
France Disposal Tableware Market
Foodservice Packaging
Compostable Food Service Packaging Market
Foodservice Packaging
Italy Disposable Tableware Market
Foodservice Packaging
Food Service Packaging (FSP) Market
Foodservice Packaging
North America Foodservice Packaging Market
Foodservice Packaging
Canada Foodservice Packaging Market
Foodservice Packaging
Foodservice Disposable Packaging Market
Foodservice Packaging
Compostable Food Service Tray Market