
 France Baby Care Products Market | 2026-2036
France Baby Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
France Baby Care Products Market Insights
Subscription-based bundling of diapers, wipes, and skincare is expanding consumer lock-in among French parents seeking convenience. Procter and Gamble leverages its logistics network to dominate recurring delivery channels. Mustela specializes in pharmacy-centric distribution, anchoring premium positioning through dermatological endorsement. Danone S.A. competes aggressively in infant nutrition, sustaining brand equity through localized formulation research.
France baby care products encompass formulated consumables and hygiene goods engineered for infants and toddlers, typically subject to dermal sensitivity thresholds and hypoallergenic composition standards. These products serve developmental protection, nutritional supplementation, and sanitation maintenance during early childhood. Diapers and baby food occupy the largest revenue pools, with the former benefiting from scale manufacturing and the latter from premium organic certification margins. Online retail channels are capturing fastest growth as French parents shift toward direct-to-platform replenishment models.
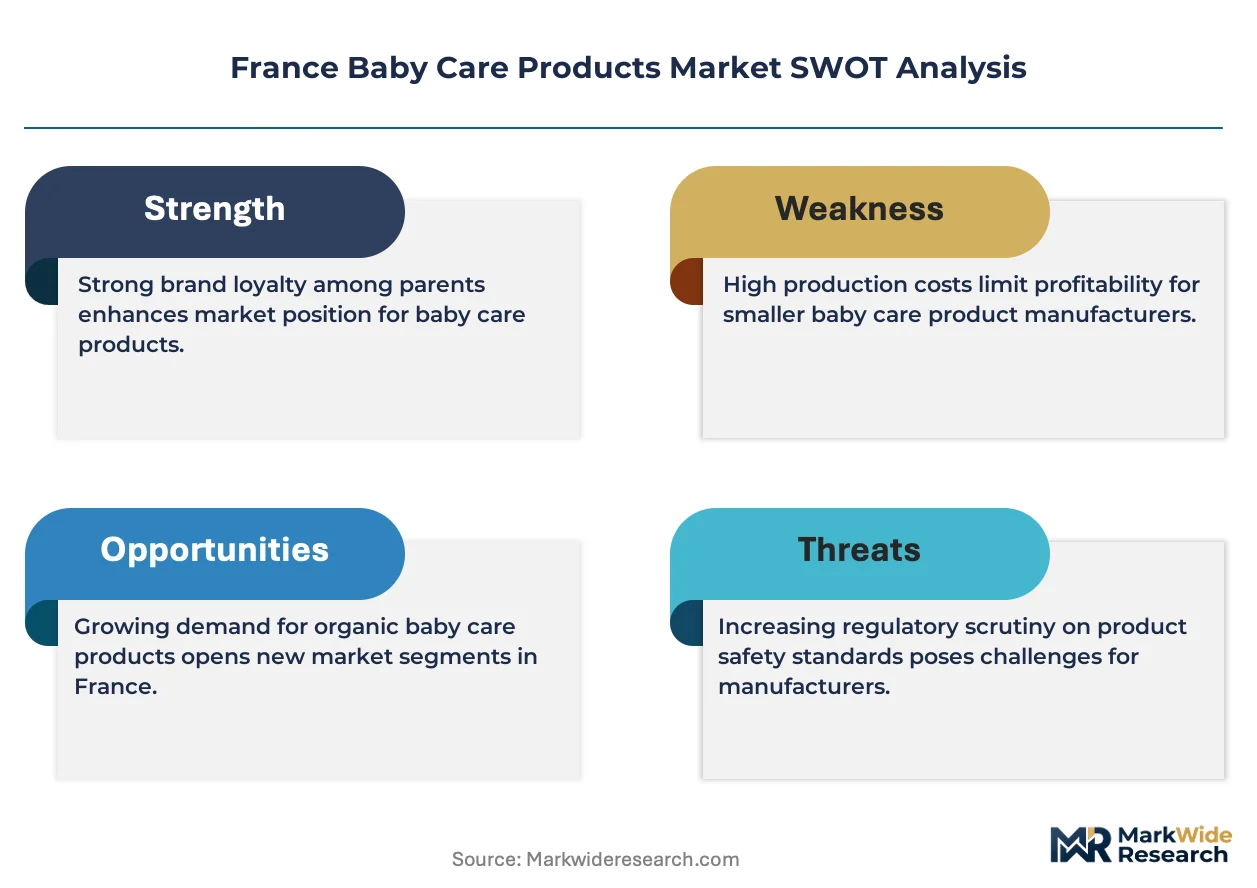
ANSM enforces pharmacovigilance and cosmetic safety standards that constrain ingredient portfolios and mandate rigorous testing protocols for dermal applications. EFSA-aligned nutritional regulations govern infant formula composition, while REACH compliance shapes chemical transparency across supply chains. Stakeholders must monitor evolving EU Green Deal packaging mandates and anticipate reformulation costs tied to biodegradable material transitions.
Market Dynamics
Subscription bundling of diapers, wipes, and skincare is compressing traditional retail channels as French parents prioritize convenience over store-based replenishment cycles. ANSM's tightening dermatological safety protocols are simultaneously forcing reformulation investments across infant skincare portfolios.
Growth Catalysts
- EU Green Deal packaging mandates:Biodegradable material transitions are creating first-mover advantages for suppliers with certified compostable diaper and wipe substrates.
- Pharmacy-centric distribution networks:Dermatological endorsement channels in Paris and Lyon are anchoring premium positioning for hypoallergenic skincare formulations.
- Île-de-France urban density:Same-day delivery logistics from centralized warehouses are enabling rapid replenishment cycles for subscription-based diaper services.
Market Restraints
- Organic cotton input volatility:Weather-dependent harvests in Mediterranean supplier regions are compressing margin stability for natural fiber diaper manufacturers.
- ANSM pharmacovigilance testing protocols:Extended dermal safety validation timelines are delaying new infant skincare launches by 8-14 months.
- Supermarket private-label substitution:Price-sensitive households in peripheral French regions are trading down from branded formulations to retailer-owned alternatives.
Strategic Opportunities
- Provence-Alpes-Côte d'Azur tourism corridors:Travel-size organic baby food and skincare kits targeting visiting families represent underdeveloped retail space.
- REACH chemical transparency alignment:Full supply chain disclosure is becoming a procurement discriminator for institutional buyers and export-oriented distributors.
- Direct-to-platform replenishment models:Integration with French e-commerce marketplaces is bypassing traditional wholesale markups for mid-tier brands.
Industry Challenges
- Formulation chemist talent scarcity:Specialized expertise in hypoallergenic infant skincare development is concentrating among a limited pool of Lyon and Marseille laboratories.
- Legacy ERP integration with subscription platforms:Inventory synchronization failures are causing fulfillment gaps for brands transitioning to recurring revenue models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Baby Care Products Market |
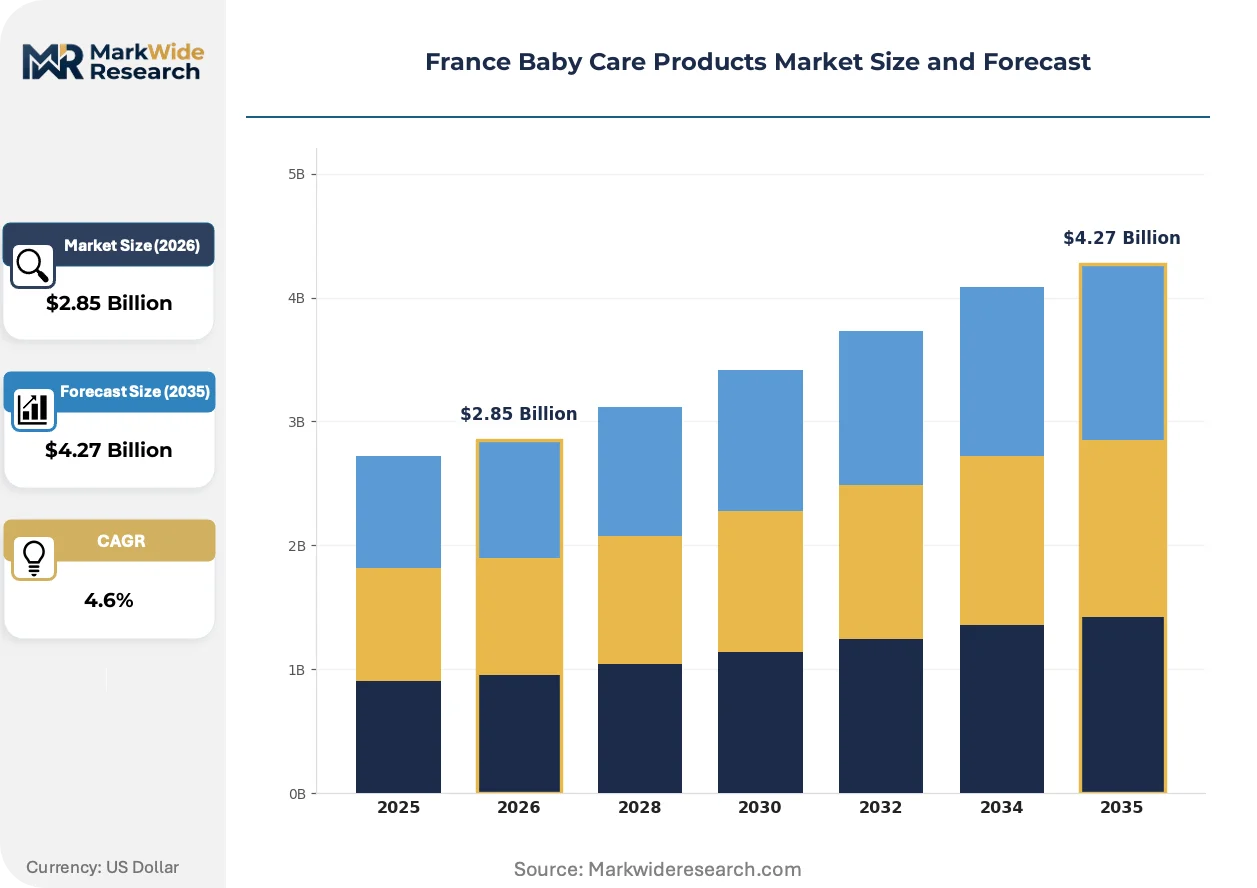
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $4.27 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diapers, Baby Lotion, Baby Food, Baby Wipes Distribution Channel: Supermarkets, Drugstores, Online Retail, Specialty Stores Customer Type: Parents, Caregivers, Expectant Mothers, Childcare Centers Age Group: Newborns, Infants, Toddlers, Preschoolers |
| Companies Covered | Beiersdorf AG, Danone S.A., Procter and Gamble, Mustela, Nestle, Johnson & Johnson, Unilever PLC, Blédina SA, Kimberly-Clark Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Baby Care Products Market Trends and Innovations
Digital dermatological assessment tools and biodegradable material science are converging to reshape how French parents evaluate and purchase infant care products. These shifts are compressing traditional brand loyalty cycles while elevating transparency and sustainability as primary purchase determinants.
Biodegradable superabsorbent polymers derived from plant-based starches are unifying performance benchmarks with compostability requirements in next-generation diaper cores. Millennial parents in Paris are adopting these formulations at twice the rate of conventional products. This technology is compressing the market share of petroleum-based absorbents while commanding 15-20% shelf-space premiums in pharmacy channels.
ANSM's 2024 guidance on preservative-free infant skincare is mandating alternative stabilization technologies across the French market. Manufacturers are accelerating cold-chain distribution investments to maintain product integrity without traditional chemical preservatives. The infant massage oil and barrier cream segments are most affected, with Provence-based producers reformulating around antioxidant-rich botanical extracts.
French parents are consolidating purchasing decisions through pediatrician-endorsed digital platforms rather than independent retail browsing. Pharmacy-affiliated apps are displacing supermarket aisles as the primary discovery channel for first-time buyers. This behavioral shift is most visible in Lyon and Bordeaux, where subscription attachment rates through medical professional referrals exceed direct-to-consumer sign-ups by a factor of three.
France Baby Care Products Market Segmentation
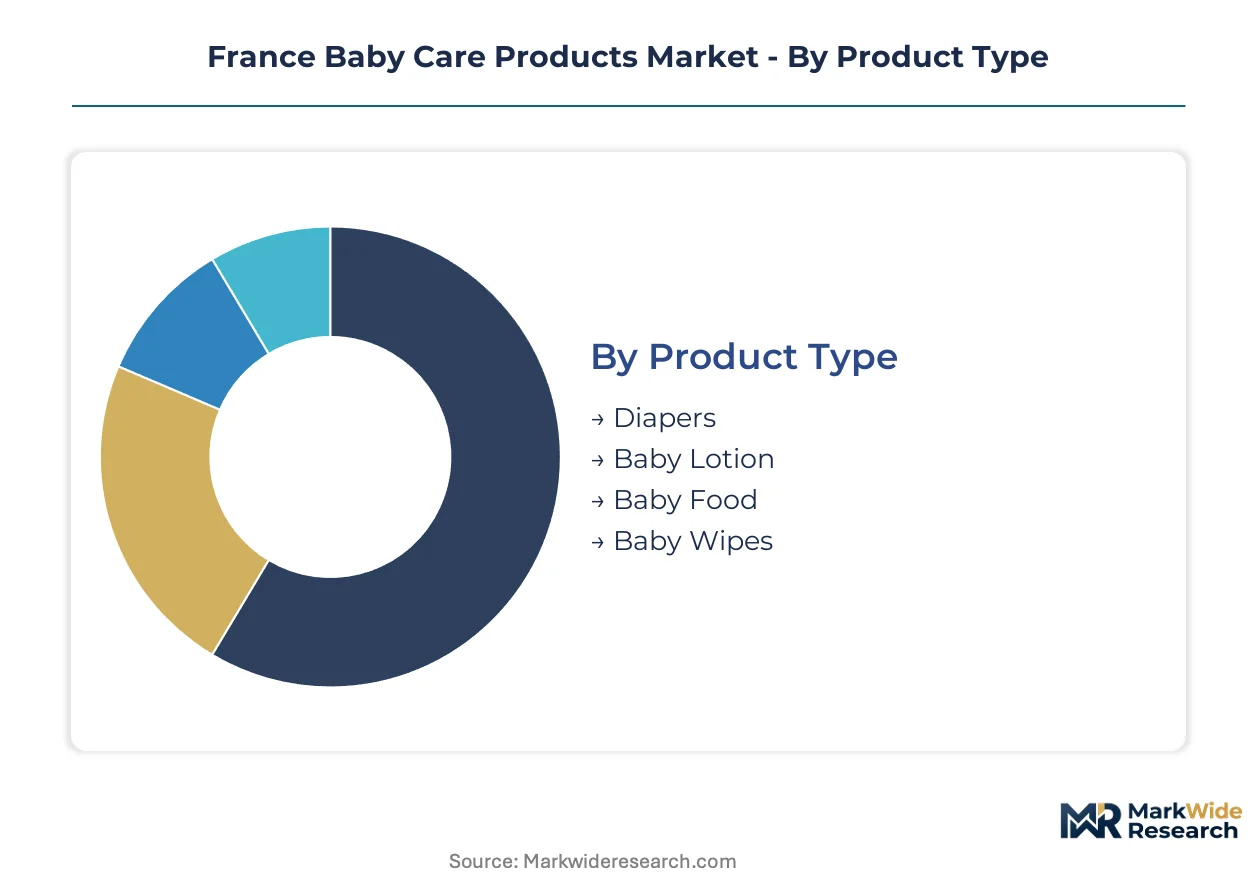
France's baby care market segments reflect divergent capital requirements and margin architectures. Manufacturers prioritize scale-intensive categories while pharmacy channels capture premium positioning through dermatological endorsement.
Product Type:
Capital intensity varies sharply across formulations, with absorbent hygiene demanding billion-euro manufacturing infrastructure while skincare requires specialized R&D facilities.
- Diapers:Multi-layer absorbent cores with petroleum-based superabsorbent polymers or emerging plant-based alternatives require high-speed converting lines and significant polymer inventory positions. Demand concentrates in Île-de-France subscription services where same-day delivery logistics compress working capital cycles for recurring replenishment models.
- Baby Food:Aseptic processing, nutritional testing laboratories, and cold-chain distribution networks impose substantial fixed-cost burdens. Provence-Alpes-Côte d'Azur parents drive organic certification premiums, with ANSM-aligned infant nutrition standards mandating localized formulation research investments.
- Baby Lotion:Preservative-free stabilization technologies and dermatological testing protocols shape cost structures.
- Baby Wipes:Nonwoven substrate manufacturing and biodegradable material transitions determine capital allocation priorities.
Diapers absorb the bulk of installed capacity; baby food is expanding most quickly.
Distribution Channel:
Channel economics fragment across fulfillment complexity, with digital platforms requiring technology infrastructure while physical retail demands working capital for inventory positioning.
- Online Retail:Direct-to-platform replenishment models integrate subscription algorithms, warehouse management systems, and last-mile logistics partnerships. Paris and Lyon millennial parents attach to recurring delivery services at rates exceeding pharmacy walk-in traffic, compressing traditional wholesale markups for mid-tier brands.
- Drugstores:Pharmacy-centric networks anchor premium skincare positioning through dermatological endorsement and ANSM pharmacovigilance compliance. Mustela and comparable brands leverage this channel for hypoallergenic formulation credibility, with inventory investments concentrated in high-footfall urban locations.
- Supermarkets:Scale-dependent shelf-space negotiations and promotional funding requirements define competitive dynamics.
- Specialty Stores:Curated assortment strategies and experiential retail formats target gift-purchase occasions and first-time parent education.
Online retail captures the steepest expansion trajectory; drugstores retain the highest margin per square meter.
Customer Type:
Purchasing authority and volume concentration determine customer acquisition economics, with institutional buyers offering scale and parents providing lifetime value through brand loyalty.
- Parents:Primary decision-makers for household replenishment, subscription bundling, and premium organic formulation selection. Millennial parents in urban France consolidate purchasing through pediatrician-endorsed digital platforms, displacing independent retail browsing with pharmacy-affiliated app discovery.
- Childcare Centers:Institutional procurement with standardized specifications, volume contracts, and REACH-aligned chemical transparency requirements. These buyers prioritize cost predictability and regulatory documentation over brand differentiation.
- Caregivers:Secondary purchasers influenced by parent-specified brand preferences and convenience positioning.
- Expectant Mothers:Pre-birth category entry point with high trial openness and registry-driven gift economics.
Parents drive absolute revenue volume; childcare centers are gaining procurement sophistication fastest.
Age Group:
Developmental stage dictates product specification complexity and purchase frequency, with early phases requiring specialized formulations and later stages enabling standardization.
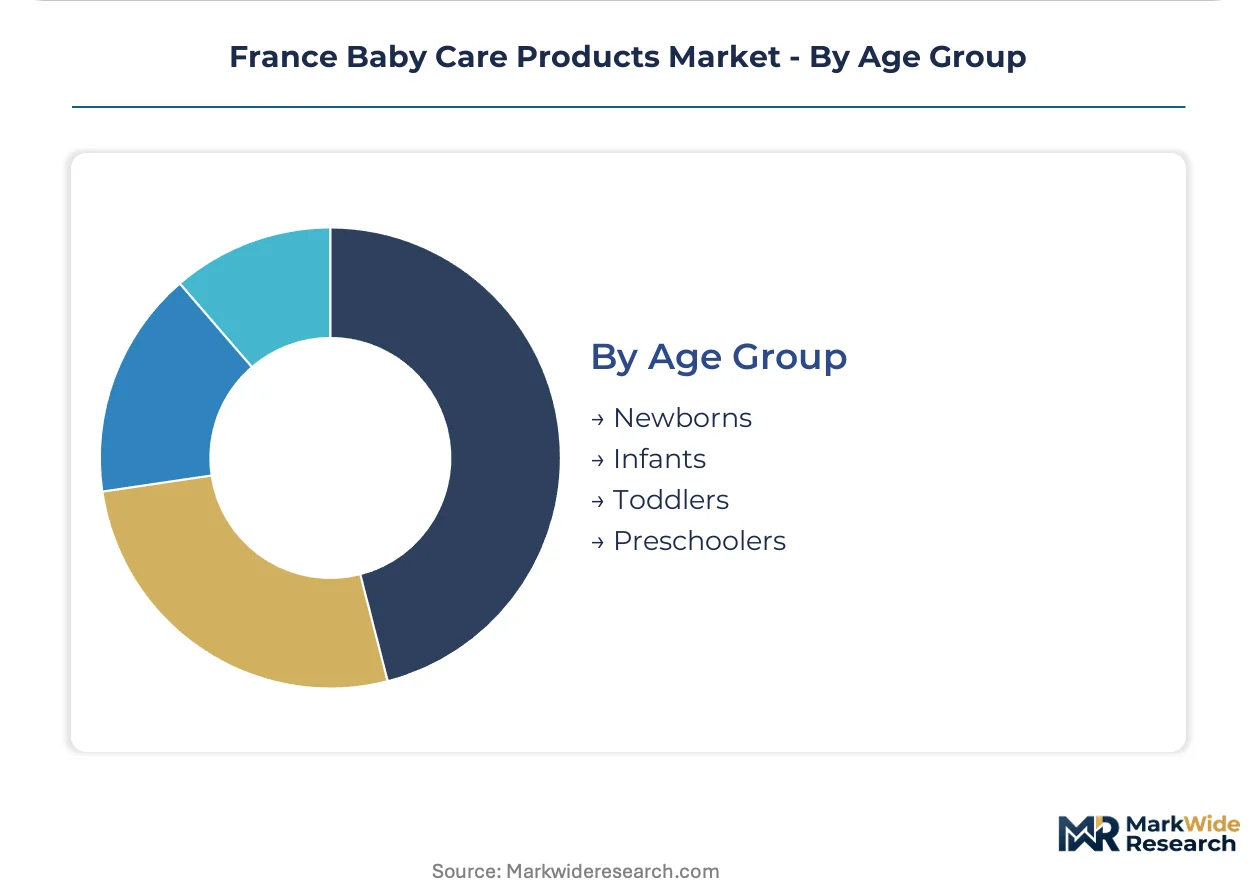
- Newborns:Hypoallergenic dermal sensitivity thresholds, preservative-free requirements, and neonatal nutritional specifications impose the strictest formulation constraints. ANSM's 2024 guidance on infant skincare most directly impacts this segment, accelerating cold-chain distribution investments for barrier creams and massage oils.
- Infants:Transition nutrition and mobility-related hygiene needs create cross-category purchasing patterns. This group anchors baby food revenue pools as complementary feeding introduces textured formulations and organic certification premiums.
- Toddlers:Potty-training dynamics compress diaper demand while expanding skincare independence and snack-food categories.
- Preschoolers:Standardized personal care and reduced nutritional supplementation shift purchasing toward commodity positioning.
Newborns command the most stringent regulatory compliance; infants generate the broadest category cross-sell opportunities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Île-de-France's dense urban infrastructure and concentration of dual-income households anchor subscription-based diaper replenishment services. The region's logistics networks enable same-day delivery economics that compress working capital cycles for recurring revenue models.
Île-de-France
Millennial parents in Paris and surrounding suburbs attach to pediatrician-endorsed digital platforms at rates exceeding traditional pharmacy walk-in traffic. ANSM pharmacovigilance standards shape formulation requirements for infant skincare distributed through city-center drugstores. Warehouse consolidation in Seine-et-Marne supports rapid replenishment cycles for bundled diaper and wipe subscriptions targeting time-constrained urban households.
Auvergne-Rhône-Alpes
Lyon's pharmacy-centric retail culture anchors premium positioning for hypoallergenic skincare formulations endorsed by dermatological professionals. The EU Green Deal packaging mandates accelerate biodegradable material transitions among regional suppliers serving organic-minded parents. Specialized R&D laboratories in Grenoble concentrate formulation chemist talent for preservative-free infant massage oil development.
Provence-Alpes-Côte d'Azur
Tourism corridors along the Mediterranean coast generate demand for travel-size organic baby food and skincare kits targeting visiting families from Northern Europe. EFSA-aligned nutritional regulations govern infant formula composition for products manufactured in Marseille industrial zones. Local producers reformulate barrier creams around antioxidant-rich botanical extracts native to the region's agricultural base.
Hauts-de-France
Price-sensitive households in Lille and surrounding peripheral zones trade down from branded formulations to supermarket private-label alternatives. REACH chemical transparency requirements shape procurement specifications for institutional buyers serving childcare centers across the region. Distribution infrastructure here supports bulk replenishment models rather than premium subscription services.
Nouvelle-Aquitaine
Bordeaux's emerging parent demographics consolidate purchasing through pharmacy-affiliated apps that displace independent retail browsing. Organic cotton input volatility from Mediterranean supplier regions compresses margin stability for natural fiber diaper manufacturers serving this market. Regional logistics networks prioritize cost efficiency over same-day delivery velocity.
France Baby Care Products Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across France's baby care market structure. The vendor base organizes around three strategic archetypes: multinational consumer goods conglomerates with scale manufacturing advantages, pharmacy-centric dermatological specialists with premium positioning, and regional organic formulators with localized supply chains. Competitive dynamics center on subscription platform integration and biodegradable material certification rather than price-based rivalry.
Among diversified conglomerates, Procter and Gamble and Danone S.A. occupy positions representing scale-driven and nutrition-focused archetypes respectively. Mustela exemplifies the pharmacy-centric specialist model anchored through dermatological endorsement channels. These three companies illustrate the competitive spectrum: conglomerates leveraging logistics networks for recurring delivery, nutrition specialists sustaining brand equity through localized formulation research, and dermatological brands capturing premium margins through professional channel alignment.
| Leading Market Players |
|---|
| Beiersdorf AG |
| Danone S.A. |
| Procter and Gamble |
| Mustela |
| Nestle |
| Johnson & Johnson |
| Unilever PLC |
| Blédina SA |
| Kimberly-Clark Corporation |
| Others |
Pricing and Supply Chain Analysis
Formulation chemist concentration in Lyon and Marseille laboratories anchors labor-cost differentials that spread pricing tiers across premium pharmacy channels, mass-market retail, and private-label substitutes. ANSM compliance investments for preservative-free stabilization widen the cost gap between certified organic producers and conventional manufacturers serving price-sensitive households in Hauts-de-France.
Pricing Analysis
Short lead-time premiums for same-day diaper replenishment in Île-de-France contrast with spot-inventory discounts for bulk supermarket purchases in peripheral regions. Subscription-based bundling commands pricing power through convenience lock-in, while pharmacy-centric dermatological endorsement extracts brand premiums for hypoallergenic skincare. Cost compression in the natural fiber diaper tier stems from organic cotton input volatility. Supermarket private-label buyers in Lille exhibit highest price sensitivity; pharmacy-loyal parents in Paris show lowest.
Supply Chain Analysis
Workforce availability for specialized infant skincare R&D concentrates in Lyon, Grenoble, and Marseille, constraining capacity expansion for preservative-free formulation development. Manufacturing draws from Italian nonwoven substrate suppliers, Spanish organic cotton growers, and German polymer producers for biodegradable diaper cores. Single-source vulnerability runs through Mediterranean agricultural inputs exposed to climate volatility. Distribution feeds from Seine-et-Marne warehouse consolidation through subscription platforms and pharmacy networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ANSM's 2024 preservative-free guidance operates as a cost-of-compliance moat, elevating capital requirements for infant skincare entrants while rewarding incumbent laboratories with validated cold-chain infrastructure.
For Market Incumbents: Lock in dermatologist endorsement relationships through co-developed digital assessment platforms that embed Mustela-style pharmacy channel control. Deepen backward integration into Provence-based botanical extract supply to defend margin position against organic input volatility. Prioritize ERP synchronization with subscription algorithms to prevent inventory gaps that erode recurring revenue attachment.
For New Entrants and Emerging Players: Pharmacy-affiliated app developers represent the most accessible channel partners for bypassing wholesale markups. White-space targets concentrate in travel-size organic kits for Provence-Alpes-Côte d'Azur tourism corridors and REACH-aligned chemical transparency services for institutional childcare procurement. A pediatrician-referral subscription model in Bordeaux offers the most penetrable go-to-market angle.
For Investors and Strategic Acquirers: Re-rating potential sits with regional organic formulators possessing validated ANSM dossiers and captive botanical supply chains, given EU Green Deal packaging mandates accelerating biodegradable certification premiums. Long-term viability favors targets with cold-chain distribution assets and dermatological R&D talent concentration. Watch ANSM guidance expansion into additional infant care categories as the inflection signal for compliance-cost escalation.
| Strategic Initiative | Industry Significance |
|---|---|
| Preservative-Free Formulation Certification | ANSM-aligned cold-chain investments differentiate pharmacy-channel skincare from mass-market alternatives. |
| Biodegradable Diaper Core Transition | Plant-based superabsorbent polymer adoption captures EU Green Deal packaging mandate premiums in Paris. |
| Pharmacy-Affiliated App Integration | Pediatrician-endorsed digital platforms displace supermarket discovery for first-time parent acquisition. |
| Provence Botanical Supply Integration | Antioxidant-rich extract sourcing anchors barrier cream reformulation under ANSM 2024 guidance. |
| Subscription ERP Synchronization | Inventory algorithm integration prevents fulfillment gaps that erode recurring revenue model economics. |
Research Methodology
Independent corroboration across pharmacy procurement managers, infant skincare formulation directors, subscription platform operations leads, and ANSM regulatory affairs specialists underwrites the qualitative findings. Secondary validation draws from ANSM pharmacovigilance databases, EU Green Deal packaging directive filings, EFSA nutritional standards documentation, and Nielsen retail audit data for French baby care categories. Bottom-up segment sizing triangulates against top-down macroeconomic consumption indicators.
Rate-of-change decomposition across the projection horizon separates volume growth from pricing dynamics and mix-shift effects. The analytical framework models product type, distribution channel, customer archetype, and regional urban density as primary segmentation dimensions. CAGRs derive from trend-line extrapolation of subscription attachment rates, organic certification penetration, and pharmacy-channel share evolution. Infant nutrition formulation research intensity and biodegradable material science maturity serve as industry-specific forecast inputs.
Caveats apply where ANSM regulatory expansion, organic cotton harvest volatility, or subscription platform competitive entry could materially shift the outlook. Forecasts embed assumptions around pharmacy-channel resilience and EU packaging mandate implementation timelines. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Products
Cloth Diapers Market
Baby Products
Baby and Toddler Feeding Products and Accessories Market
Baby Products
Australia Baby Care Products Market
Baby Products
Baby Care Products Market
Baby Products
South Africa Baby Care Products Market
Baby Products
Baby Bottle Market
Baby Products
Global Baby Carriers Market
Baby Products
Baby Care and Mother Care Market
Baby Products
Baby Detergents and Laundry Products Market
Baby Products
Stroller Rental Market
Baby Products
Global Adaptive Strollers Market
Baby Products
Baby Pacifier Market
Baby Products
Brazil Baby Care Products Market
Baby Products
Breastfeeding Accessories Market
Baby Products
Global Baby Pajamas and Sleepwears Market
Baby Products
South Korea Baby Care Products Market