
 Brazil Baby Care Products Market | 2026-2036
Brazil Baby Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Baby Care Products Market Insights
Southeast Brazil is narrowing the gap between imported premium formulations and domestically manufactured baby care lines. Procter & Gamble Co leverages its established diaper manufacturing footprint to sustain volume leadership across mass and mid-tier segments. Kimberly-Clark Corp anchors its position through specialized newborn and toddler sub-ranges with reinforced absorbency technology. Johnson & Johnson competes by emphasizing dermatological testing protocols and pharmacy channel control.
Baby care products encompass topical formulations, absorbent hygiene articles, and cleansing items engineered with pH-balanced compositions, hypoallergenic certifications, and pediatric safety testing for infant skin tolerance. These products serve the primary commercial purpose of maintaining infant hygiene, skin barrier integrity, and comfort during critical developmental stages. Diapers and baby wipes occupy the dominant volume position due to daily consumption frequency and established replenishment cycles. Baby shampoo and baby oil extract margin from smaller pack sizes and premium natural positioning, particularly within pharmacy and specialty store channels.
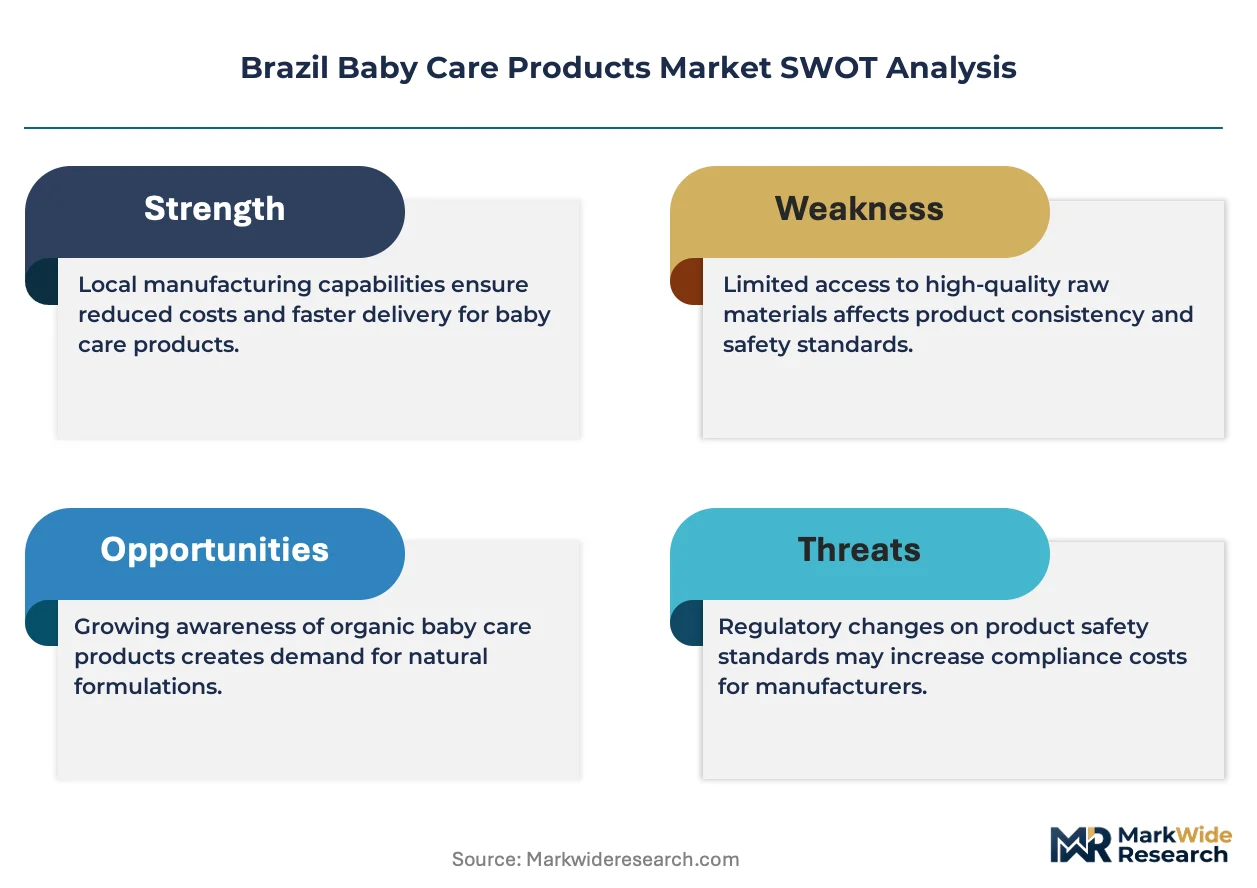
ANVISA governs cosmetic and infant product registration, while the Brazilian Consumer Defense Code mandates rigorous labeling and adverse event reporting for baby care formulations. These frameworks elevate compliance costs for new entrants but reinforce quality signaling for established manufacturers. Stakeholders must monitor pending ingredient restriction proposals and state-level waste management laws affecting disposable diaper distribution.
Market Dynamics
ANVISA's tightened cosmetic and infant safety standards are compressing product registration timelines and forcing manufacturers to revalidate ingredient portfolios across entire baby care lines. This regulatory tightening concentrates competitive advantage among established players with dedicated compliance infrastructure.
Growth Catalysts
- Urban Millennial Demand:São Paulo and Rio de Janeiro parents prioritize premium natural-formulation baby care, expanding addressable market for dermatologically tested products.
- ANVISA Registration Modernization:Streamlined digital submission pathways for baby care products reduce time-to-market for compliant formulations.
- Southeast Retail Penetration:Modern trade expansion in Minas Gerais and Espírito Santo extends distribution reach beyond traditional metropolitan cores.
Market Restraints
- Import Dependency for Specialty Ingredients:Plant-derived emollients and organic surfactants concentrate sourcing from European and Asian suppliers, exposing margins to currency volatility.
- ANVISA Compliance Cost Escalation:Mandatory pediatric safety testing and toxicological dossier requirements create six-figure entry barriers for regional formulators.
- Disposable Diaper Waste Legislation:Pending state-level extended producer responsibility laws in São Paulo threaten distribution economics for absorbent hygiene articles.
Strategic Opportunities
- Northeast Regional Underpenetration:Bahia and Pernambuco exhibit rising birth rates with limited premium baby care retail presence, creating first-mover potential.
- Pharmacy Channel Specialization:Dermatologist-endorsed sub-ranges for atopic-prone infants command price premiums through controlled dispensing networks.
- Biodegradable Wipe Formulations:Convergence of cellulose fiber innovation and composting infrastructure investment opens sustainable positioning for cleansing products.
Industry Challenges
- Pediatric Dermatology Talent Scarcity:Formulation science positions requiring toxicology and infant skin physiology expertise face recruitment bottlenecks in Brazilian labor markets.
- Legacy ERP Integration:Batch traceability mandates for ANVISA adverse event reporting force costly upgrades to manufacturing execution systems at mid-tier facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Baby Care Products Market |
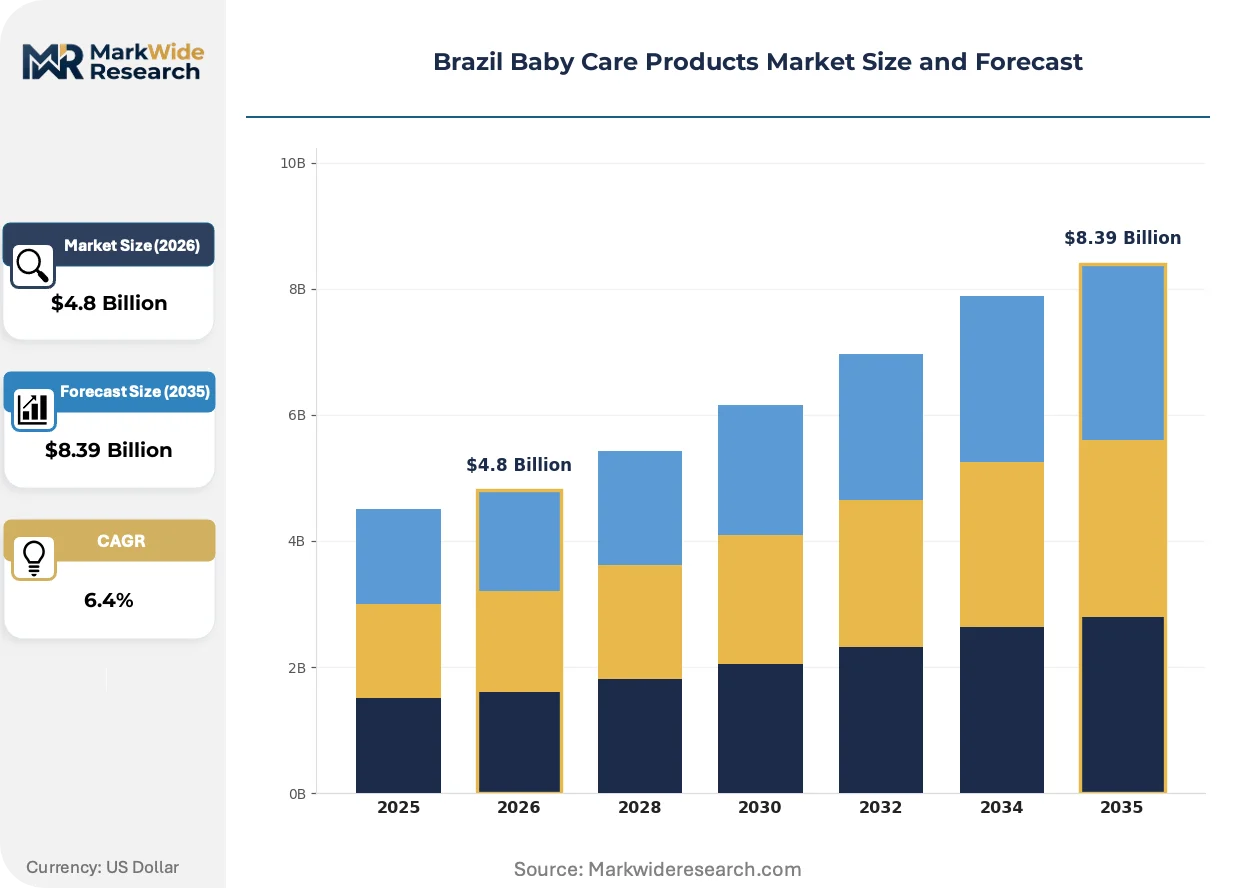
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diapers, Baby Wipes, Baby Oil, Baby Shampoo Distribution Channel: Supermarkets, Online Retail, Pharmacies, Specialty Stores Customer Type: First-Time Parents, Expecting Parents, Gift Givers, Childcare Providers Packaging Type: Bulk Packs, Individual Packs, Eco-Friendly Packaging, Travel Size |
| Companies Covered | Unilever PLC, The Himalaya Drug Company, Johnson & Johnson, Dermobaby, Soft N Dry Diapers Corp, Procter & Gamble Co, Beiersdorf AG, Honasa Consumer, Kimberly-Clark Corp, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Baby Care Products Market Trends and Innovations
Bioactive ingredient science and circular material flows are reconfigulating how Brazilian manufacturers differentiate baby care portfolios. These forces compress traditional formulation paradigms while opening premium positioning avenues.
Microbiome-friendly preservation systems are collapsing the historical trade-off between shelf stability and skin barrier compatibility. Premium-positioned manufacturers in São Paulo adopt postbiotic and prebiotic active complexes at accelerated rates. This technology is collapsing the market share of conventional paraben-based preservative platforms across pharmacy and specialty channels.
ANVISA's pending ingredient transparency mandate requires full fragrance component disclosure on baby care labels. Manufacturers must reformulate proprietary scent profiles or abandon fragrance entirely in sensitive-skin sub-ranges. Newborn and atopic-specific lines face the steepest compliance timelines, with several domestic formulators already transitioning to unfragranced base architectures.
Subscription replenishment models for diapers and wipes are capturing urban professional households in Rio de Janeiro and Brasília. Direct-to-consumer platforms displace hypermarket bulk purchasing for time-constrained millennial parents. This behavioral shift concentrates most visibly in dual-income households with children under 24 months, where convenience premiums override price sensitivity.
Brazil Baby Care Products Market Segmentation
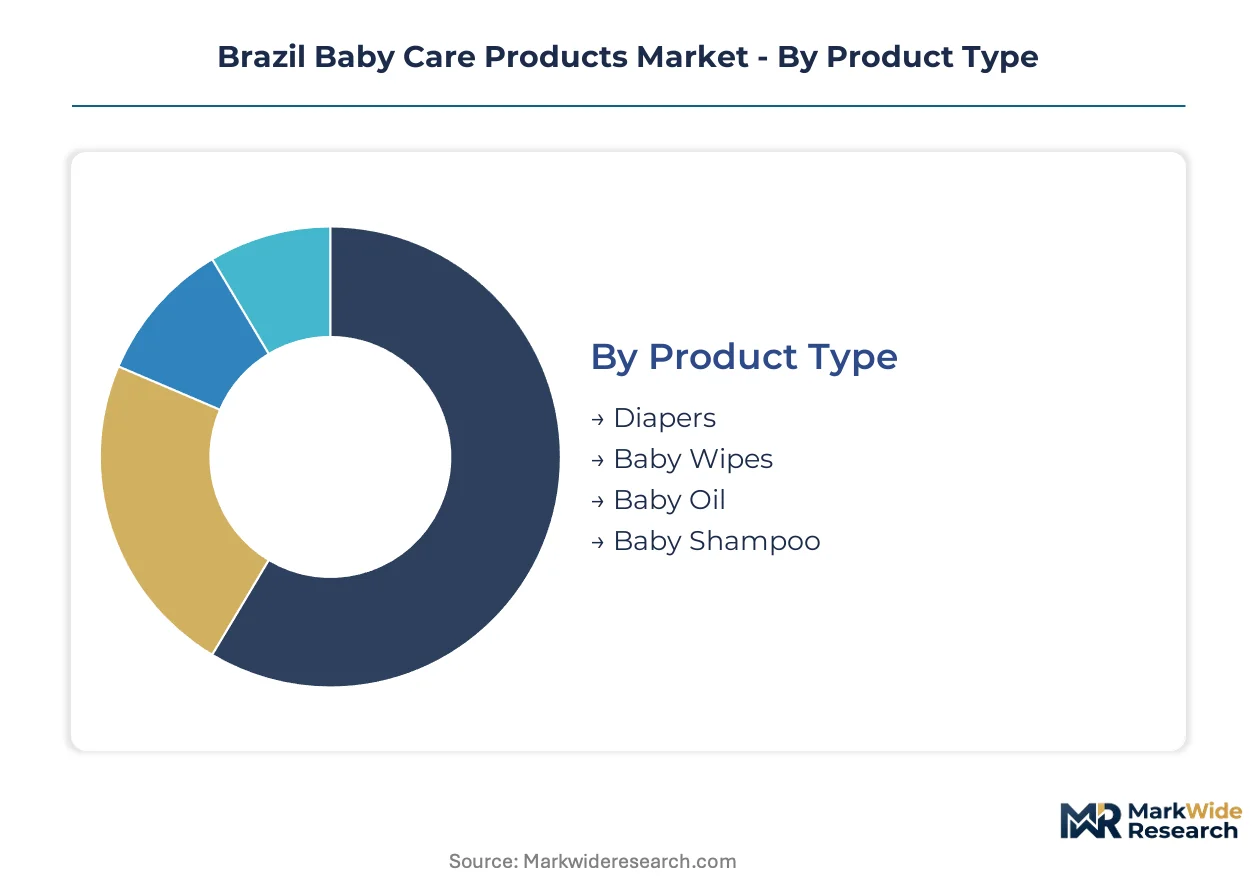
Brazil's baby care market fragments across usage occasion, purchase context, and buyer motivation. Understanding these segment boundaries reveals where premium positioning commands price realization versus where volume scale dominates economics.
Product Type:
Mature absorbent hygiene articles anchor manufacturer revenue, while emerging natural-formulation topicals reshape margin structures.
- Diapers:Multi-layer absorbent cores with elasticized waistbands and breathable outer films address daily consumption needs. São Paulo and Rio de Janeiro households drive demand for premium-tier products with dermatological certifications and wetness indicator technology.
- Baby Wipes:Nonwoven cellulose substrates saturated with pH-balanced cleansing solutions and preservative systems engineered for infant skin tolerance. Pharmacy and specialty channels favor alcohol-free formulations with postbiotic active claims.
- Baby Oil:Mineral oil or plant-derived emollient bases packaged in smaller formats for massage and moisture barrier applications. Regional formulators in Minas Gerais compete on price against imported premium positioning.
- Baby Shampoo:Mild surfactant systems with tear-free formulations and natural extract positioning. ANVISA's pending fragrance disclosure mandate forces reformulation of proprietary scent architectures.
Diapers retain volume leadership; baby wipes hold the steepest expansion curve.
Distribution Channel:
Channel selection separates planned stock-up purchasing from impulse and professional-guided acquisition.
- Supermarkets:High-frequency replenishment destinations with prominent shelf placement for diaper bulk packs and wipe multipacks. Hypermarket chains in Southeast Brazil consolidate purchasing power over mass-tier suppliers.
- Online Retail:Subscription models and direct-to-consumer platforms capture time-constrained millennial households. Brasília and São Paulo urban professionals favor auto-replenishment for absorbent hygiene articles.
- Pharmacies:Controlled dispensing networks where dermatologist endorsement and clinical testing claims justify price premiums. Atopic-prone infant sub-ranges concentrate here.
- Specialty Stores:Curated natural and organic positioning with educated staff consultation. Rio de Janeiro's upscale neighborhoods host concentrated premium baby boutique presence.
Supermarkets retain volume leadership; online retail holds the steepest expansion curve.
Customer Type:
Buyer lifecycle stage and relationship to the infant determine sensitivity to price, certification, and convenience attributes.
- First-Time Parents:Information-seeking buyers prioritizing safety certifications and pediatrician recommendations over price. Digital research intensity peaks in this segment before purchase commitment.
- Expecting Parents:Pre-birth stockpiling behavior favors trial-sized variety packs and gift registry participation. Nursery preparation timelines concentrate purchasing in second and third trimesters.
- Gift Givers:Premium packaging and brand recognition drive selection for baby shower and welcome occasions. Price insensitivity permits margin extraction on presentation-focused formats.
- Childcare Providers:Institutional procurement with volume discount requirements and bulk packaging preferences. Creches and daycare centers in urban centers standardize on mid-tier diaper specifications.
First-time parents retain volume leadership; expecting parents hold the steepest expansion curve.
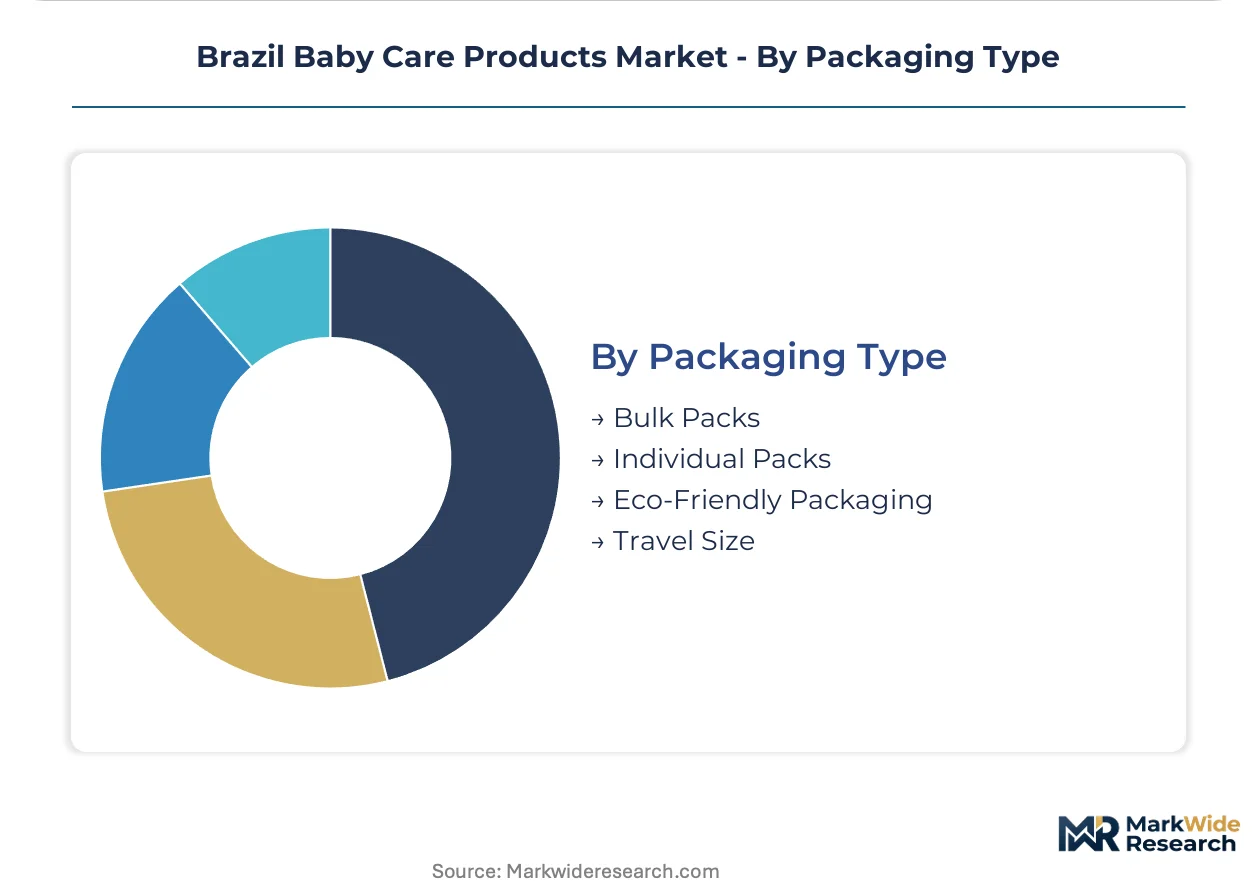
Packaging Type:
Format engineering balances supply chain efficiency, usage occasion flexibility, and sustainability signaling.
- Bulk Packs:Economical per-unit pricing for predictable consumption patterns with warehouse club and online channel concentration. Diaper cartons and wipe refill pouches dominate this architecture.
- Individual Packs:Portable single-serve formats for travel, diaper bags, and emergency replenishment. Convenience premiums override unit economics in pharmacy impulse placement.
- Eco-Friendly Packaging:Recycled content, biodegradable films, and reduced plastic positioning for sustainability-motivated urban households. Composting infrastructure gaps in Brazil limit full value realization.
- Travel Size:TSA-compliant volumes and trial formats for sampling and short-duration trips. Hotel amenity partnerships and airline baby care kits extend distribution reach.
Bulk packs retain volume leadership; eco-friendly packaging holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic manufacturing concentrates in São Paulo state, where absorbent hygiene production clusters serve national distribution networks. Southeast Brazil generates disproportionate value capture through premium-formulation demand and modern retail density.
São Paulo
Urban millennial households in Greater São Paulo drive premium natural-formulation adoption, expanding pharmacy channel penetration for dermatologically tested baby care lines. ANVISA's digital registration modernization accelerates product launches for compliant domestic formulators. The São Paulo metropolitan corridor anchors diaper manufacturing scale and specialty ingredient import logistics.
Rio de Janeiro
Dual-income professional families in Rio de Janeiro prioritize subscription replenishment models for diapers and wipes, displacing hypermarket bulk purchasing. State-level extended producer responsibility proposals threaten disposable diaper distribution economics. Upscale neighborhoods concentrate specialty baby boutiques with curated organic positioning.
Minas Gerais
Rising disposable income in Belo Horizonte and surrounding municipalities extends modern trade penetration beyond traditional metropolitan cores. ANVISA compliance cost escalation filters regional formulator participation, favoring established manufacturers with dedicated regulatory infrastructure. The state serves as a secondary manufacturing hub with cost-advantaged production for mid-tier segments.
Bahia
Elevated birth rates in Salvador and Recife metropolitan areas contrast with limited premium baby care retail presence, creating first-mover expansion potential. National distributors face logistics complexity serving Northeast markets from Southeast production centers. Local pharmacy chains increasingly stock dermatologist-endorsed sub-ranges for atopic-prone infants.
Rio Grande do Sul
Southern Brazilian consumer preferences favor European-imported specialty ingredients and fragrance-free formulations. State environmental regulations on packaging waste precede national mandates, pressuring manufacturers toward biodegradable film adoption. Porto Alegre's retail landscape supports mid-tier positioning with selective premium boutique presence.
Brazil Baby Care Products Market Competitive Landscape
Multinational consumer goods conglomerates and specialized regional formulators split the market across mass-volume and premium-niche vectors. Tiered competitive dynamics concentrate volume leadership among scale-driven players with established ANVISA compliance infrastructure, while boutique specialists extract margin through pharmacy channel control and natural positioning. Strategic moves center on portfolio diversification into microbiome-friendly formulations and backward integration into specialty ingredient sourcing.
Among multinational anchors, Procter & Gamble Co and Kimberly-Clark Corp exemplify scale-driven competitive positioning through absorbent hygiene manufacturing depth. Johnson & Johnson occupies a position within the dermatological-specialist archetype, leveraging pharmacy channel relationships. Regional specialists including Dermobaby represent the domestic formulator tier navigating compliance cost barriers.
| Leading Market Players |
|---|
| Unilever PLC |
| The Himalaya Drug Company |
| Johnson & Johnson |
| Dermobaby |
| Soft N Dry Diapers Corp |
| Procter & Gamble Co |
| Beiersdorf AG |
| Honasa Consumer |
| Kimberly-Clark Corp |
| Others |
Pricing and Supply Chain Analysis
São Paulo state's absorbent hygiene manufacturing cluster concentrates domestic diaper and wipe production capacity, translating scale economies into pricing leverage for compliant manufacturers serving Southeast Brazil's premium-tier demand while regional formulators in Minas Gerais compete on cost-advantaged mid-tier positioning.
Pricing Analysis
ANVISA's pediatric safety testing mandates dictate the pricing tier structure across Brazil's baby care market. Three-tier pricing separates dermatologist-endorsed pharmacy channel products from standard modern trade offerings and economy-tier private labels. Certification grade and volume scale drive price differentiation, with ANVISA compliance cost escalation compressing margins for non-specialized formulators. Price erosion runs through the economy tier as hypermarket chains consolidate purchasing power over mass-market suppliers. First-time parents in São Paulo and Rio de Janeiro exhibit lowest price sensitivity, while childcare providers and bulk institutional procurement face highest pressure.
Supply Chain Analysis
European export controls on specialized plant-derived emollients and organic surfactants constrain ingredient flows into Brazilian formulators. Manufacturing capacity concentrates in Brazil, Germany, and the United States for premium baby care equipment and testing infrastructure. Domestic production draws from imported cellulose fibers, specialty preservatives, and dermatological testing services. Single-source vulnerability persists for postbiotic active complexes sourced from Scandinavian suppliers. Distribution runs through São Paulo-based national distributors serving pharmacy chains, hypermarket networks, and emerging direct-to-consumer platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's baby care market sits in early-cycle expansion, with Northeast regional underpenetration and pharmacy channel specialization offering runway ahead of competitive saturation in Southeast metropolitan cores.
For Market Incumbents: Insulate margin structures by deepening backward integration into specialty ingredient sourcing for microbiome-friendly formulations, while reinforcing ANVISA compliance infrastructure as a barrier against emerging regional formulators. Capacity addition in Bahia and Pernambuco secures first-mover positioning ahead of modern trade expansion. For New Entrants and Emerging Players: Establish a beachhead in dermatologist-endorsed atopic-prone infant sub-ranges distributed through controlled pharmacy networks, where certification requirements filter mass-market competition. The Northeast region offers the most penetrable geography, with rising birth rates and limited premium retail presence. A go-to-market angle anchored in biodegradable wipe formulations aligns with pending state-level extended producer responsibility legislation. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors domestic formulators with captive ANVISA registration expertise and established pharmacy channel relationships. Long-term viability hinges on portfolio migration toward preservative-free and fragrance-free architectures. The signal to watch is ANVISA's final ingredient transparency mandate implementation timeline, which will force accelerated reformulation capex across the competitive set.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Wipe Formulation Launch | Composting infrastructure investment in São Paulo and Rio de Janeiro enables sustainable positioning ahead of waste legislation. |
| Pharmacy Channel Expansion | Dermatologist endorsement networks in Southeast Brazil command price premiums for atopic-specific sub-ranges. |
| Northeast Regional Distribution Buildout | Logistics complexity from Southeast production centers creates first-mover advantage for localized warehousing in Salvador. |
| Subscription Replenishment Platform | Auto-replenishment models capture dual-income millennial households in Brasília with convenience premiums. |
| ANVISA Compliance Infrastructure Investment | Dedicated toxicological dossier capabilities filter regional competition and accelerate product launch timelines. |
Research Methodology
A spread of perspectives from brand managers at multinational consumer goods companies, category buyers at hypermarket chains, pharmacy procurement directors, ANVISA regulatory affairs consultants, and supply planners at absorbent hygiene manufacturers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through ANVISA registration databases, Nielsen retail audit data, customs import records for specialty ingredients, and SEC filings of publicly traded parent companies. Bottom-up volume modeling and top-down macroeconomic triangulation anchored the analytical framework.
Demand-supply balance dynamics shaped the forecast architecture across the analysis window. Segmentation dimensions included product type, distribution channel, customer lifecycle stage, and packaging format. CAGRs derived from historical trajectory analysis and penetration curve modeling for emerging segments. Forecast inputs incorporated birth rate projections, modern trade expansion timelines, and ANVISA regulatory modernization implementation schedules.
Stress conditions across currency volatility for imported ingredients, state-level extended producer responsibility adoption rates, and pharmacy channel consolidation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on competitive response intensity and retail format evolution. Material shifts in ANVISA's pending fragrance disclosure mandate timeline or Northeast regional logistics infrastructure investment would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Products
Kids Activity Box Market
Baby Products
Baby Wipes Market
Baby Products
Baby Playpens Market
Baby Products
Silicone Baby Product Market
Baby Products
Global Baby Play Mats Market
Baby Products
Japan Baby Care Product Market
Baby Products
Baby Feeding Bottles Market
Baby Products
Baby Detergents and Laundry Products Market
Baby Products
Global Smart Connected Baby Monitors Market
Baby Products
Baby Walker Market
Baby Products
Pregnancy Products Market
Baby Products
Kids Training Pant Market
Baby Products
Baby Swaddle Wrap Market
Baby Products
Baby Cradles Market
Baby Products
Smart Pacifier Market
Baby Products
Baby Pacifier Market