
 Global Adaptive Strollers Market | 2026-2036
Global Adaptive Strollers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Adaptive Strollers Market Foresight
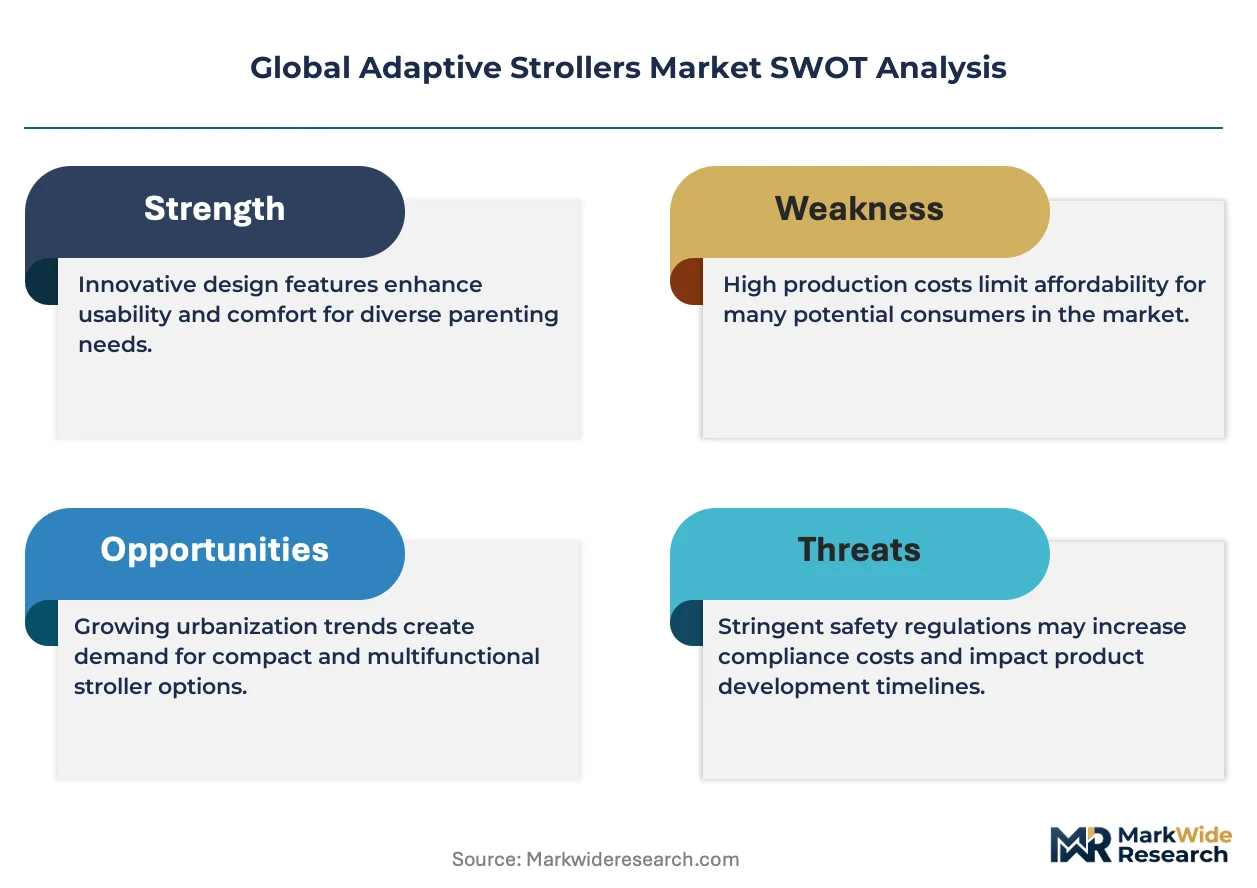
Premium crash-test certification is unwinding baseline expectations across the Global Adaptive Strollers Market. Sunrise Medical leverages its European manufacturing footprint to sustain compliance leadership under MDR and ISO 13485 frameworks. Convaid Products anchors its position through deep specialization in pediatric positioning systems for complex medical needs. Thomashilfen differentiates via German-engineered modular seating that competes on adjustability rather than price alone.
Adaptive strollers are wheeled mobility devices engineered with adjustable seating angles, modular harness systems, and shock-absorbing frames designed to transport children with cerebral palsy, muscular dystrophy, and other neuromuscular conditions. Aluminum alloy construction and pneumatic tire configurations define the performance envelope, with crash-test validation to ISO 7176 standards serving as the primary safety gate for institutional procurement. Lightweight strollers occupy the highest volume tier due to caregiver portability demands, while travel systems command concentrated margin pools from Medicaid and private payer reimbursement. Shock absorption technology leads R&D allocation as manufacturers respond to terrain variability in community-based therapy programs.
FDA 510(k) premarket notification requirements and the EU Medical Device Regulation (MDR) frame product entry barriers, with notified body audits extending certification timelines for new frame geometries and restraint designs. Health Canada's Medical Devices Bureau and Australia's TGA impose parallel clinical evidence standards that shape export strategies for North American and European manufacturers. Stakeholders must monitor evolving pediatric restraint standards from ISO and national disability equipment funding formulas that determine institutional purchasing authority.
Market Dynamics
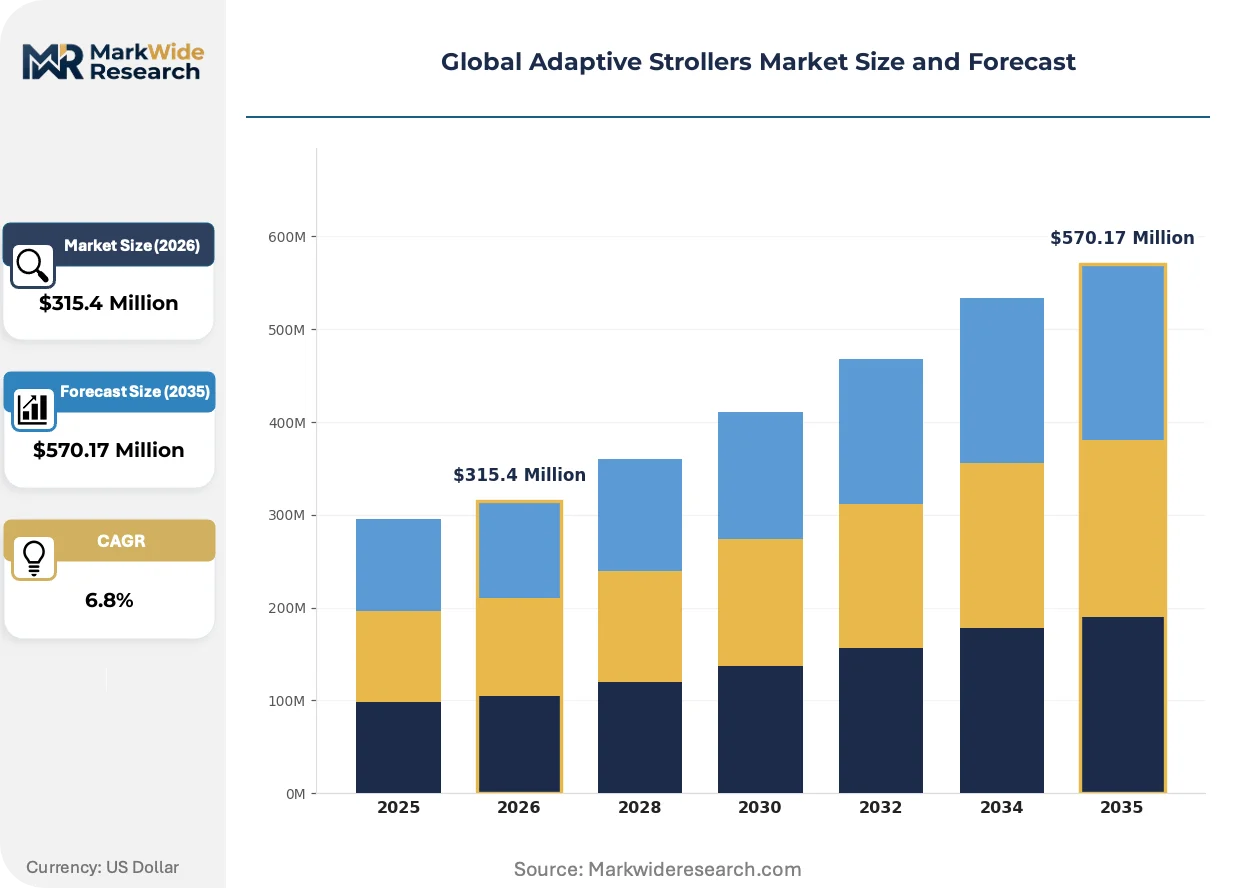
Crash-test certification to ISO 7176 standards is compressing procurement timelines for institutional buyers while elevating compliance costs for manufacturers seeking FDA 510(k) clearance and EU MDR conformity. This safety-documentation escalation is reshaping competitive positioning toward vertically integrated producers with captive testing capabilities.
Growth Catalysts
- Pediatric rehabilitation center expansion:Specialized mobility equipment procurement is accelerating in Germany and the United States as regional therapy networks consolidate purchasing authority under outcome-based reimbursement frameworks.
- EU Medical Device Regulation harmonization:MDR Article 120 transition provisions are creating predictable certification pathways that reduce notified body audit variability for frame geometry innovations.
- Lightweight aluminum alloy adoption:Caregiver portability demands are pulling pneumatic tire configurations into community-based therapy programs where terrain variability exceeds institutional corridor specifications.
Market Restraints
- Notified body capacity constraints:EU MDR technical documentation reviews are extending certification timelines by 8-14 months for novel restraint designs, freezing product launch windows.
- Medicaid reimbursement fragmentation:State-level durable medical equipment formulary exclusions in the United States create patchwork coverage that limits addressable demand for travel system configurations.
- Crash-test facility concentration:ISO 7176 validation capacity clusters in Germany and the United Kingdom, creating geographic bottlenecks for Asian and Latin American manufacturers seeking export certification.
Strategic Opportunities
- Australia's TGA parallel approval pathway:Health Canada's recognition of FDA 510(k) clearances enables synchronized North American-Australian market entry that amortizes clinical evidence costs across jurisdictions.
- Modular seating-IoT convergence:Pressure mapping sensors and telemetric posture monitoring are creating subscription revenue attachments for pediatric positioning systems in complex medical need segments.
- Direct-to-therapist digital channels:Institutional procurement is bypassing traditional durable medical equipment distributors through manufacturer-integrated configurators that spec seating angles and harness systems online.
Industry Challenges
- Biomechanical engineering talent scarcity:Pediatric seating design requires specialized expertise in neuromuscular condition kinematics that outpaces university rehabilitation technology program output in the United States and Germany.
- Legacy frame geometry recertification:EU MDR Annex I general safety and performance requirements are forcing retrospective clinical evidence generation for pre-2017 product lines that lack systematic post-market surveillance data.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Adaptive Strollers Market |
| Market Size in 2026 | $315.4 Million |
| Market Size in 2035 | $570.17 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reclining Strollers, Lightweight Strollers, Jogging Strollers, Travel Systems Technology: Shock Absorption, Adjustable Handles, Safety Harness, Swivel Wheels End User: Infants, Toddlers, Children with Special Needs, Mobility Challenged Distribution Channel: Online Retailers, Specialty Stores, Baby Boutiques, Department Stores |
| Companies Covered | Adaptive Star, Convaid Products, Sunrise Medical, Invacare Corporation, Thomashilfen, Special Tomato, Eurovema, Meyra, R82 A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Adaptive Strollers Market Shifts & Advancements
Shock absorption technology is commanding disproportionate R&D allocation as manufacturers respond to terrain variability in community-based therapy programs. Three distinct vectors are restructuring product architecture and go-to-market economics.
Modular seating architecture is decomposing the traditional integrated-frame-supply-chain into separable component ecosystems. Pediatric positioning specialists in California's regional center network are specifying third-party seating systems on generic stroller bases. This interoperability is compressing margin capture for frame manufacturers while elevating seating subsystem suppliers.
EU MDR Article 10 post-market surveillance obligations are mandating systematic complaint handling and trend reporting that exceeds FDA 510(k) periodic reporting requirements. Manufacturers must maintain electronic data capture systems that trace field failures to specific production lots. Travel system configurations with complex harness geometries face disproportionate documentation burden under this framework.
England's National Health Service wheelchair services are consolidating purchasing authority through framework agreements that specify ISO 7176-19 crash-test validation as a gate criterion. Smaller rehabilitation centers are losing independent procurement autonomy as regional commissioning groups centralize adaptive stroller specification. This buyer concentration is compressing supplier margins while extending contract durations.
Global Adaptive Strollers Market Segmentation
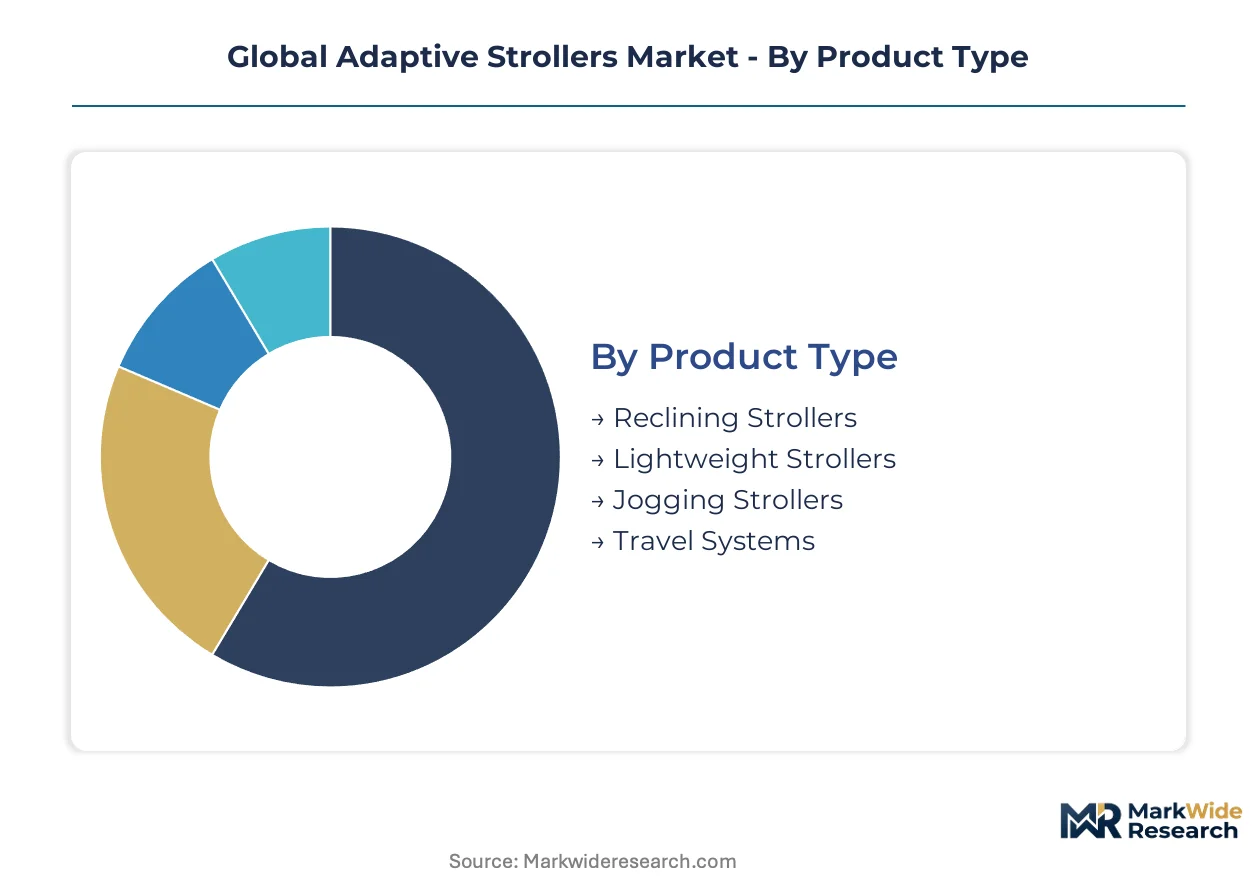
Adaptive stroller procurement channels diverge sharply between institutional reimbursement pathways and direct consumer purchase. Product specifications, technology integration, and distribution access determine which segments capture Medicaid-funded volume versus private-pay margin pools.
Product Type:
Channel mix splits between durable medical equipment distributors handling institutional contracts and specialty retailers serving private-pay caregivers.
- Reclining Strollers:Aluminum frames with multi-angle seat positioning accommodate postural support requirements for cerebral palsy and muscular dystrophy patients. California's regional center network and England's NHS wheelchair services concentrate procurement of these systems under outcome-based reimbursement frameworks.
- Lightweight Strollers:Pneumatic tire configurations and collapsible frames address caregiver portability demands in community-based therapy programs. Germany's pediatric rehabilitation centers are expanding lightweight procurement as ambulatory care shifts toward home-based intervention models.
- Jogging Strollers:Three-wheel stability systems with suspension geometry for active caregiver mobility.
- Travel Systems:Modular car seat-stroller combinations capturing concentrated margin pools from private payer reimbursement where Medicaid formulary exclusions limit addressable demand.
Lightweight strollers dominate installed base. Travel systems represent the fastest-growing trajectory as private-pay segments expand.
Technology:
Cost tier stratification separates premium sensor-integrated systems from baseline mechanical configurations.
- Shock Absorption:Pneumatic tire and spring-damper assemblies responding to terrain variability in community therapy programs command disproportionate R&D allocation. FDA 510(k) clearance pathways for novel suspension geometries extend certification timelines.
- Adjustable Handles:Telescoping push-bar mechanisms accommodating caregiver height variation.
- Safety Harness:Five-point restraint systems with ISO 7176-19 crash-test validation serving as the primary procurement gate for institutional buyers.
- Swivel Wheels:Locking caster configurations enabling maneuverability in corridor versus outdoor environments.
Safety harness systems anchor baseline compliance. Shock absorption technology is where manufacturer differentiation concentrates.
End User:
Application severity determines reimbursement coding and seating specification complexity.
- Children with Special Needs:Modular positioning systems for complex neuromuscular conditions requiring custom seating angles and harness configurations. England's NHS framework agreements and California's regional centers drive volume concentration.
- Mobility Challenged:Post-injury or degenerative condition users with progressive adaptation requirements.
- Infants:Early intervention eligibility creating Medicaid-funded entry points.
- Toddlers:Growth-adjustable frame specifications spanning 18-36 month developmental windows.
Children with special needs segments dominate installed base. Mobility challenged users are climbing the fastest as aging caregiver populations expand.
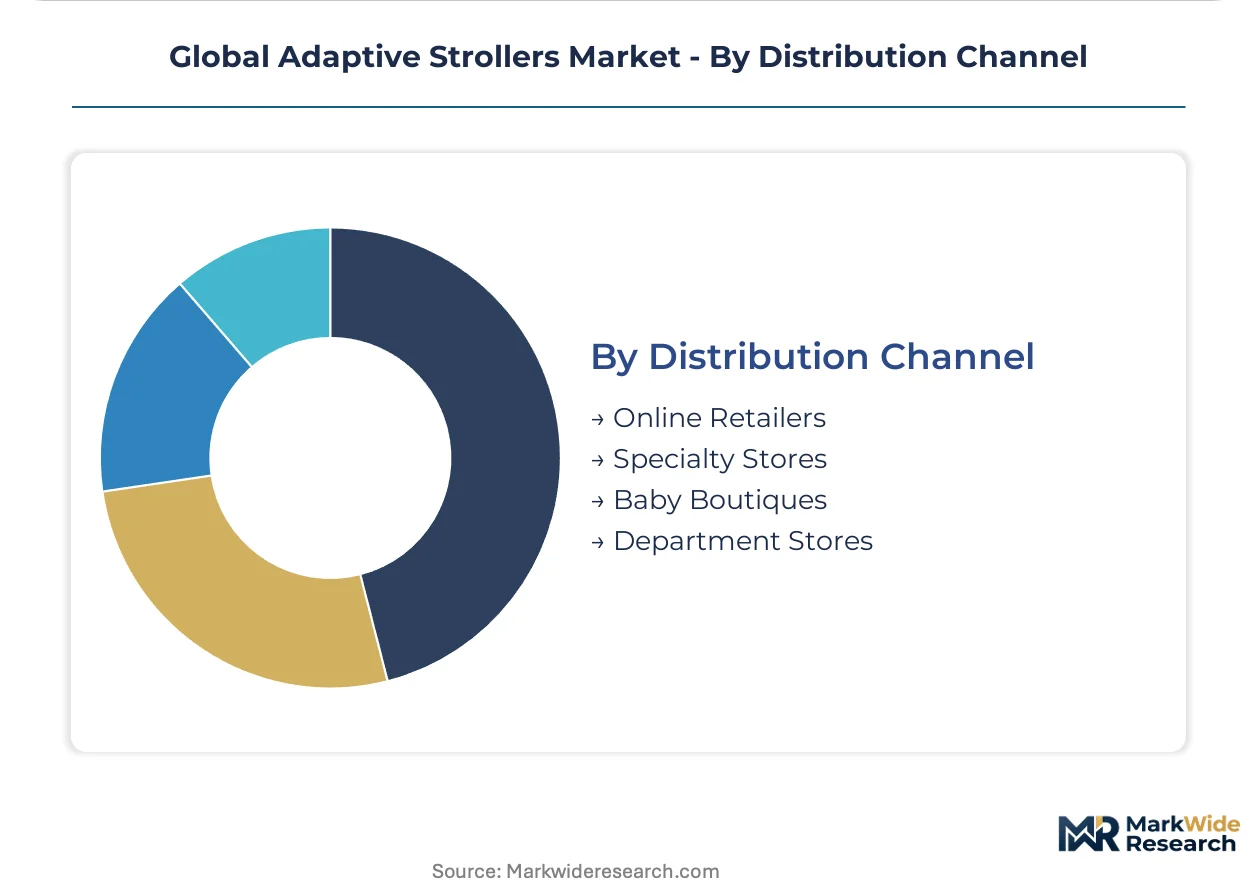
Distribution Channel:
Customer type bifurcation between institutional procurement authority and individual caregiver decision-making.
- Specialty Stores:Trained seating specialists conducting in-person assessments for complex medical needs. Germany's rehabilitation technology providers and US durable medical equipment dealers maintain physical assessment capabilities.
- Online Retailers:Direct-to-therapist digital configurators bypassing traditional distributors for standardized lightweight configurations.
- Baby Boutiques:Premium private-pay segments with limited insurance navigation support.
- Department Stores:Mass-market accessibility for baseline travel system configurations.
Specialty stores dominate institutional procurement. Online retailers are gaining share fastest as manufacturer-integrated configurators compress distribution layers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medicaid-funded buyers in the United States exhibit the highest price elasticity, while NHS-procured systems in England and private-pay segments in Germany absorb premium positioning without volume contraction.
United States
California's regional center network and Texas Medicaid waiver programs concentrate procurement authority for complex seating configurations. FDA 510(k) clearance pathways impose documentation burdens that extend certification timelines for novel restraint geometries. Chicago-based durable medical equipment distributors maintain assessment capabilities for institutional contracts across the Midwest.
Germany
Pediatric rehabilitation centers in Bavaria and North Rhine-Westphalia are expanding lightweight stroller procurement under ambulatory care shift mandates. EU MDR notified body audits from TÜV Süd and DEKRA frame conformity assessment timelines for frame innovations. Stuttgart's rehabilitation technology cluster anchors engineering talent pools for modular seating development.
United Kingdom
England's NHS wheelchair services framework agreements specify ISO 7176-19 crash-test validation as mandatory procurement criteria. Regional commissioning groups in Greater Manchester and the West Midlands are centralizing purchasing authority away from individual rehabilitation centers. Sheffield hosts specialized testing facilities serving manufacturers seeking UKCA marking compliance.
Australia
TGA parallel approval pathways enable synchronized market entry for North American manufacturers with existing FDA 510(k) clearances. New South Wales and Victoria state disability equipment programs drive volume concentration for travel system configurations. Sydney-based seating specialists are integrating manufacturer configurators into direct-to-therapist procurement workflows.
Canada
Health Canada's Medical Devices Bureau recognition of FDA clearances reduces clinical evidence duplication for US-exporting manufacturers. Provincial formulary variations between Ontario and British Columbia create coverage patchwork for premium positioning systems. Toronto's rehabilitation hospital network serves as the primary institutional buyer concentration for complex medical need segments.
Global Adaptive Strollers Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with German-engineered modular seating specialists commanding premium positioning while aluminum frame fabricators compete on caregiver portability metrics. The vendor base clusters around three strategic archetypes: vertically integrated rehabilitation equipment conglomerates, pediatric positioning specialists, and regional durable medical equipment suppliers. M&A activity concentrates on seating subsystem capabilities, while geographic expansion targets Australia's TGA pathway for FDA-cleared manufacturers.
Among European-based specialists, Thomashilfen GmbH and Meyra GmbH exemplify the engineering-intensive archetype competing on adjustability rather than price alone. Sunrise Medical anchors the scale-driven tier with manufacturing footprints spanning multiple jurisdictions. Convaid Products occupies a specialist position within pediatric positioning systems for complex neuromuscular conditions.
| Leading Market Players |
|---|
| Adaptive Star |
| Convaid Products |
| Sunrise Medical |
| Invacare Corporation |
| Thomashilfen |
| Special Tomato |
| Eurovema |
| Meyra |
| R82 A/S |
| Others |
Supply & Pricing Matrix
Aluminum alloy substitution for steel frame construction simultaneously shifts component sourcing toward German and Chinese extrusion specialists while compressing per-unit manufacturing economics for mid-tier producers. This material transition elevates transport cost sensitivity for North American distributors sourcing European-engineered seating subsystems, tightening margin capture across the value chain.
Pricing Analysis
After-market service contracts and replacement seating components generate lifetime value multiples exceeding initial hardware margins for institutional accounts. Three-tier pricing structure across premium crash-tested configurations, standard MDR-compliant systems, and economy lightweight models stratifies buyer access. Cost compression in the economy tier intensifies as Medicaid formulary exclusions in Texas and Florida limit reimbursement depth. Private-pay caregivers in Germany absorb premium positioning without volume contraction, while US institutional buyers exhibit acute price elasticity.
Supply Chain Analysis
Inventory cycles for ISO 7176-certified frame assemblies extend lead times for Asian manufacturers lacking captive testing facilities in Germany or the United Kingdom. Component sourcing draws from Chinese aluminum forging operations, German pneumatic tire specialists, and Italian textile harness suppliers. Single-source vulnerability concentrates in notified body audit capacity, where TÜV Süd and DEKRA bottlenecks freeze certification queues. Distribution runs through durable medical equipment distributors with assessment capabilities, though manufacturer-integrated digital configurators are compressing intermediary layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement authority is concentrating in England's NHS regional commissioning groups and California's regional center networks, shifting negotiating leverage toward institutional buyers with framework agreement scale. This buyer consolidation demands defensive repositioning across supplier tiers.
For Market Incumbents: Consolidate seating subsystem capabilities through targeted acquisition of pediatric positioning specialists, neutralizing margin compression from third-party interoperability. Deepen backward integration into aluminum alloy forging to offset transport cost inflation from German component sourcing. Capture channel control by embedding digital configurators that bypass traditional distributor assessment layers.
For New Entrants and Emerging Players: Anchor in Australia's TGA parallel approval pathway for synchronized North American-Pacific market entry that amortizes clinical evidence costs. Target lightweight stroller configurations for community-based therapy programs in Germany's expanding ambulatory care networks. Pursue direct-to-therapist digital channels with manufacturer-integrated spec tools that circumvent established distributor relationships.
For Investors and Strategic Acquirers: EU MDR Article 120 transition completion reshapes the acquisition landscape by elevating compliance infrastructure value over pure product portfolios. Long-term viability hinges on post-market surveillance data capture capabilities spanning the projection horizon. Target acquisition candidates with electronic complaint handling systems and systematic trend reporting infrastructure. Monitor notified body audit queue lengths as inflection indicators for certification-constrained product launch windows.
| Strategic Initiative | Industry Significance |
|---|---|
| Notified Body Partnership | Secures predictable EU MDR certification timelines for novel frame geometries. |
| Modular Seating Acquisition | Captures margin pools from third-party interoperability in California regional centers. |
| Digital Configurator Deployment | Bypasses durable medical equipment distributor layers for direct therapist engagement. |
| Crash-Test Facility Investment | Reduces geographic bottlenecks for Asian and Latin American export certification. |
| Pressure Sensor Integration | Creates subscription revenue attachments for pediatric positioning system monitoring. |
Research Methodology
A spread of perspectives from pediatric rehabilitation clinicians, biomedical engineers, durable medical equipment procurement managers, and GPO contracts specialists converged on the working assumptions shaping demand modeling. Primary field engagement combined with secondary validation from FDA 510(k) filings, EU MDR notified body audit records, CMS Medicare durable medical equipment claims data, and NHS wheelchair services procurement databases. Bottom-up installed base estimates triangulated against top-down reimbursement flow analysis across jurisdictions.
Segmentation dimensions modeled include product type tier, technology integration level, end-user severity classification, and distribution channel structure across the projection horizon. CAGRs derived from elasticity-adjusted volume trajectories responding to Medicaid formulary variation and NHS framework agreement expansion. Industry-specific forecast inputs incorporated ISO 7176-19 crash-test certification adoption curves and MDR Article 10 post-market surveillance compliance cost escalation.
Decision-makers should treat outputs as directional under stable regulatory transition timelines and sustained institutional procurement consolidation; material deviation in notified body capacity or reimbursement policy would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Products
Noise-Muffling Infant Hat Market
Baby Products
Baby Digital Monitor Market
Baby Products
Smart Crib Market
Baby Products
Baby Personal Care Products Market
Baby Products
Baby and Toddler Feeding Products and Accessories Market
Baby Products
Feeding Pillow Market
Baby Products
South Korea Baby Care Products Market
Baby Products
Baby Changing Light Market
Baby Products
Baby Food Dispensing Spoon Market
Baby Products
United Arab Emirates Baby Care Products Market
Baby Products
India Baby Care Products Market
Baby Products
Diaper Pails Market
Baby Products
Crib Mattress Market
Baby Products
Baby Bottle Market
Baby Products
Baby Playpens Market
Baby Products
Feeding Bra Market