
 Baby Detergents and Laundry Products Market | 2026-2036
Baby Detergents and Laundry Products Market Size, Share, and Industry Trends Forecast 2026-2036
Baby Detergents and Laundry Products Market Outlook
Premium hypoallergenic certification is rotating toward the center of competitive strategy as parents reject standard formulations for infant care. Procter & Gamble leverages its global manufacturing footprint to supply certified-safe product lines across multiple continents. Henkel AG & Co. KGaA anchors its position through specialized dermatological testing protocols that exceed baseline regulatory requirements. The Honest Company differentiates via direct-to-parent subscription channels that emphasize ingredient transparency and recurring revenue capture.
Baby detergents and laundry products comprise surfactant-based cleaning formulations engineered with reduced enzyme activity, neutral pH ranges between 6.0 and 7.5, and exclusion of optical brighteners to prevent residual irritation on infant skin and respiratory pathways. These products serve the commercial purpose of removing organic stains and pathogens from textiles while preserving fabric integrity and minimizing chemical exposure for developing immune systems. Liquid formulations dominate volume due to pre-measured dosing convenience and cold-water solubility advantages, while fragrance-free ingredient types command premium shelf positioning as pediatric dermatologist recommendations shift parent purchasing behavior. Natural ingredient segments attract venture-backed entrants despite higher per-unit costs, whereas enzymatic variants retain institutional demand from hospital procurement systems.
The EPA Safer Choice program and EU REACH chemical authorization process constrain permissible surfactant chemistries, compelling reformulation investments that smaller manufacturers struggle to absorb. FDA oversight of cosmetic-drug claims on baby product labeling creates compliance barriers for brands marketing therapeutic skin benefits without clinical substantiation. Parents and procurement officers must monitor evolving state-level disclosure mandates in California and New York that extend beyond federal minimums, as these jurisdictions often prefigure broader North American standards.
Market Dynamics
EU REACH chemical authorization and EPA Safer Choice certification requirements are forcing wholesale surfactant reformulation across the baby detergent supply base, compressing margins for non-compliant manufacturers while rewarding early adopters of bio-based alternatives.
Growth Catalysts
- Pediatric dermatologist endorsement protocols:Medical professional recommendations for fragrance-free formulations are accelerating parent purchasing decisions in clinical and retail channels alike.
- California Cleaning Product Right to Know Act:Ingredient disclosure mandates are normalizing transparency expectations that premium brands now leverage for competitive differentiation.
- Cold-water enzymatic chemistry:Low-temperature surfactant activation is reducing household energy consumption and expanding addressable markets in regions with limited hot water infrastructure.
Market Restraints
- Palm kernel oil price volatility:Primary feedstock for gentle surfactant production exposes formulators to agricultural commodity swings and sustainability certification costs.
- China surfactant intermediate concentration:Overreliance on Zhejiang and Jiangsu province chemical clusters creates single-source vulnerability for global supply chains.
- Enzyme stability limitations:Temperature-sensitive protease and lipase variants degrade in liquid suspension, constraining shelf-life extension and distribution radius.
Strategic Opportunities
- Subscription commerce penetration:Direct-to-parent recurring delivery models capture lifetime value and reduce customer acquisition costs versus traditional retail.
- India urban middle-class expansion:First-time parents in metropolitan Bangalore, Mumbai, and Delhi represent underpenetrated demand for certified-hypoallergenic segments.
- Biodegradable polymer encapsulation:Converging materials science with detergent chemistry enables controlled-release fragrance systems that satisfy clean-label preferences.
Industry Challenges
- Toxicology assessment bottlenecks:Pediatric safety testing protocols require 18-24 month validation cycles that delay product launches and strain R&D budgets.
- Legacy ERP integration:Batch manufacturing systems struggle to accommodate lot-level ingredient traceability mandated by evolving disclosure regulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baby Detergents and Laundry Products Market |
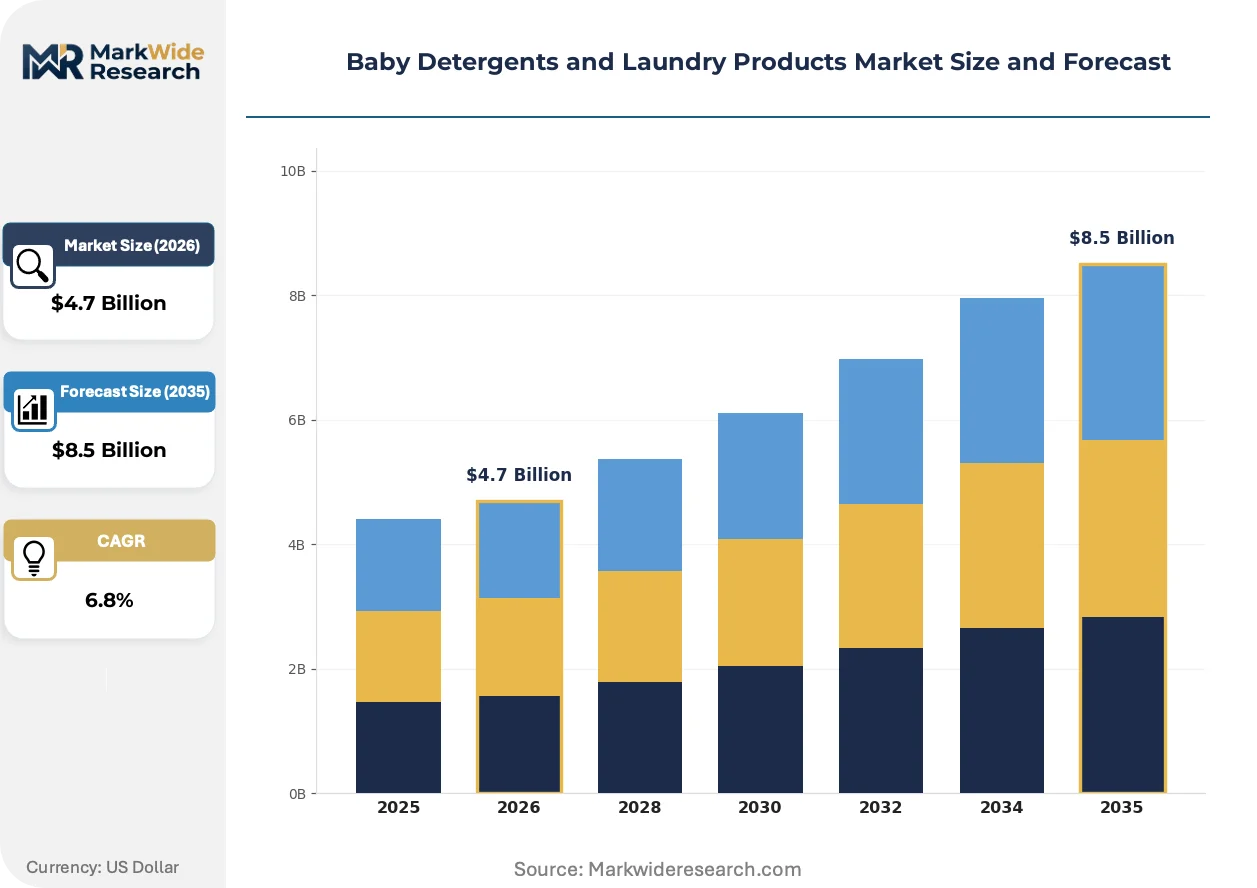
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $8.5 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
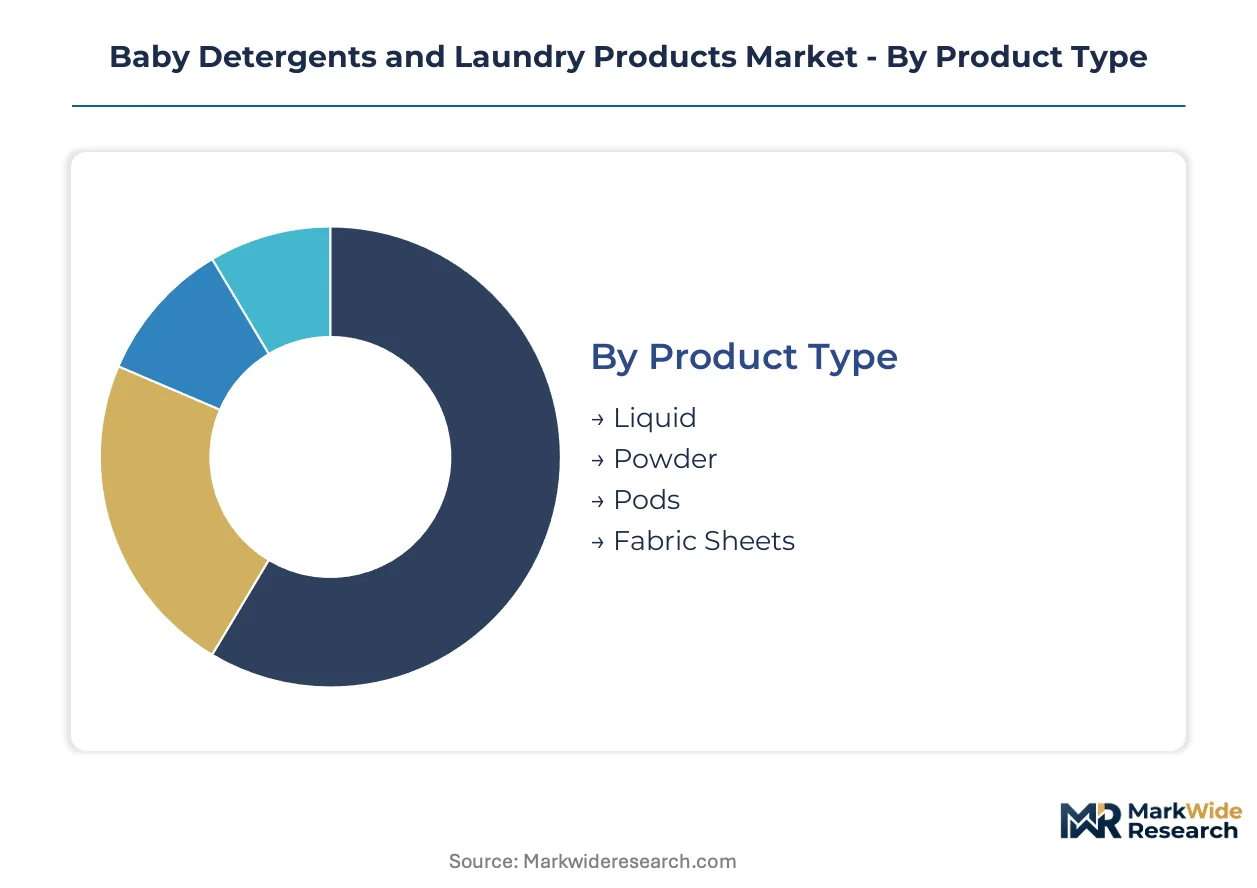
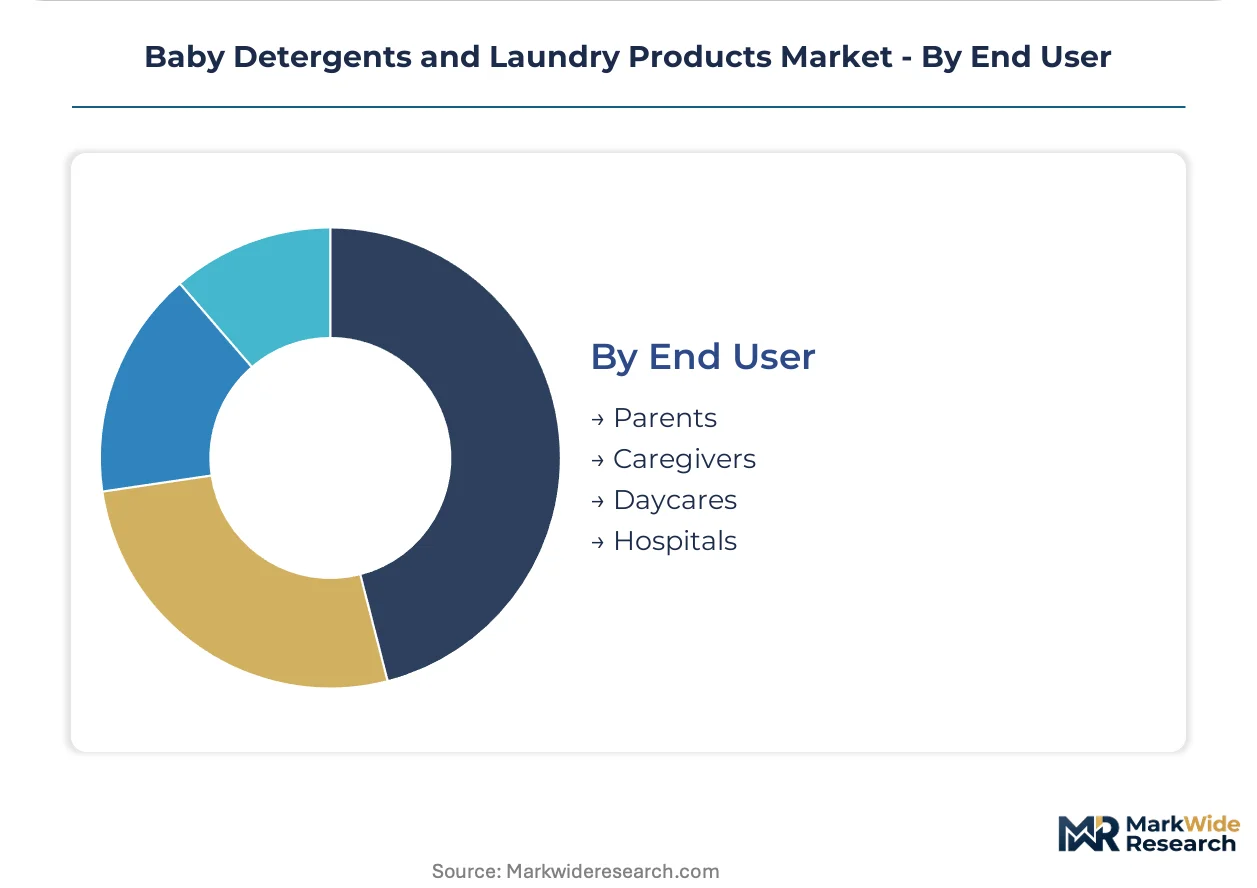
| Segmentation | Product Type: Liquid, Powder, Pods, Fabric Sheets Ingredient Type: Natural, Hypoallergenic, Fragrance-Free, Enzymatic Packaging Type: Bottles, Sachets, Boxes, Jars End User: Parents, Caregivers, Daycares, Hospitals |
| Companies Covered | Procter & Gamble, Johnson & Johnson, Unilever, Henkel AG & Co. KGaA, The Clorox Company, Church & Dwight Co., Inc., Seventh Generation, The Honest Company, Babyganics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baby Detergents and Laundry Products Market Strategic Shifts
Formulation chemistry and distribution architecture are undergoing parallel transformation as sustainability credentials and convenience expectations reshape competitive standards across the value chain.
Plant-derived alkyl polyglucoside surfactants are replacing petroleum-based alternatives in premium formulations. Pediatric dermatology clinics and hospital procurement systems are adopting these bio-based lines at accelerated rates. The technology is miniaturizing production footprints, enabling regional contract manufacturing that reduces freight emissions and import dependency.
REACH authorization requirements for nonylphenol ethoxylates and boron compounds are eliminating legacy surfactant chemistries from EU-sold formulations. Manufacturers must resubmit safety dossiers for replacement ingredients, absorbing regulatory consulting costs that disadvantage smaller competitors. Liquid detergent segments face the steepest compliance burden given their higher surfactant loadings versus powder alternatives.
Hospital and childcare institution procurement officers are consolidating supplier relationships around single-source certified vendors. Pediatric wards and neonatal intensive care units now specify dermatologically tested formulations in tender documents, displacing fragmented multi-brand purchasing. Germany and France exhibit the most concentrated institutional buying power, with procurement cooperatives negotiating multi-year supply agreements.
Baby Detergents and Laundry Products Market Segmentation
Segmentation in baby detergents and laundry products reveals how regulatory pressure and pediatric safety standards fragment demand across formulation chemistry, delivery format, and institutional procurement channels. Manufacturers must navigate divergent compliance requirements while capturing value from parents seeking certified-safe home use and hospitals requiring clinical-grade supply assurance.
Product Type:
EU REACH authorization for nonylphenol ethoxylates and EPA Safer Choice surfactant restrictions are driving divergence in formulation chemistry across physical delivery formats, with liquid formats absorbing the steepest compliance costs due to higher surfactant loadings.
- Liquid:Surfactant-based aqueous formulations with neutral pH 6.0-7.5 and reduced enzyme activity predominate in household channels where cold-water solubility and pre-measured dosing convenience matter. Demand concentrates in the United States and Germany as premium hypoallergenic certifications command shelf positioning in mass retail and subscription commerce.
- Pods:Water-soluble polymer encapsulation of concentrated surfactant blends enables precise dosing control and reduced packaging waste, though pediatric ingestion risk has triggered child-resistant packaging mandates from the Consumer Product Safety Commission.
- Powder:Granular alkali-based formulations with lower surfactant density face declining household preference but retain institutional demand from hospital procurement systems in France and Japan seeking bulk-scale pathogen removal with extended shelf stability.
- Fabric Sheets:Dryer-added conditioning substrates containing cationic surfactants and optional fragrance microcapsules serve convenience-oriented parents, though respiratory sensitization concerns are displacing these from neonatal intensive care unit supply lists.
Liquid handles the majority of throughput; pods are gaining share fastest as subscription commerce penetration normalizes concentrated delivery formats.
Ingredient Type:
Cost tier stratification separates premium-positioned dermatologically tested lines from commodity alternatives, with certification grade determining margin capture and retail access.
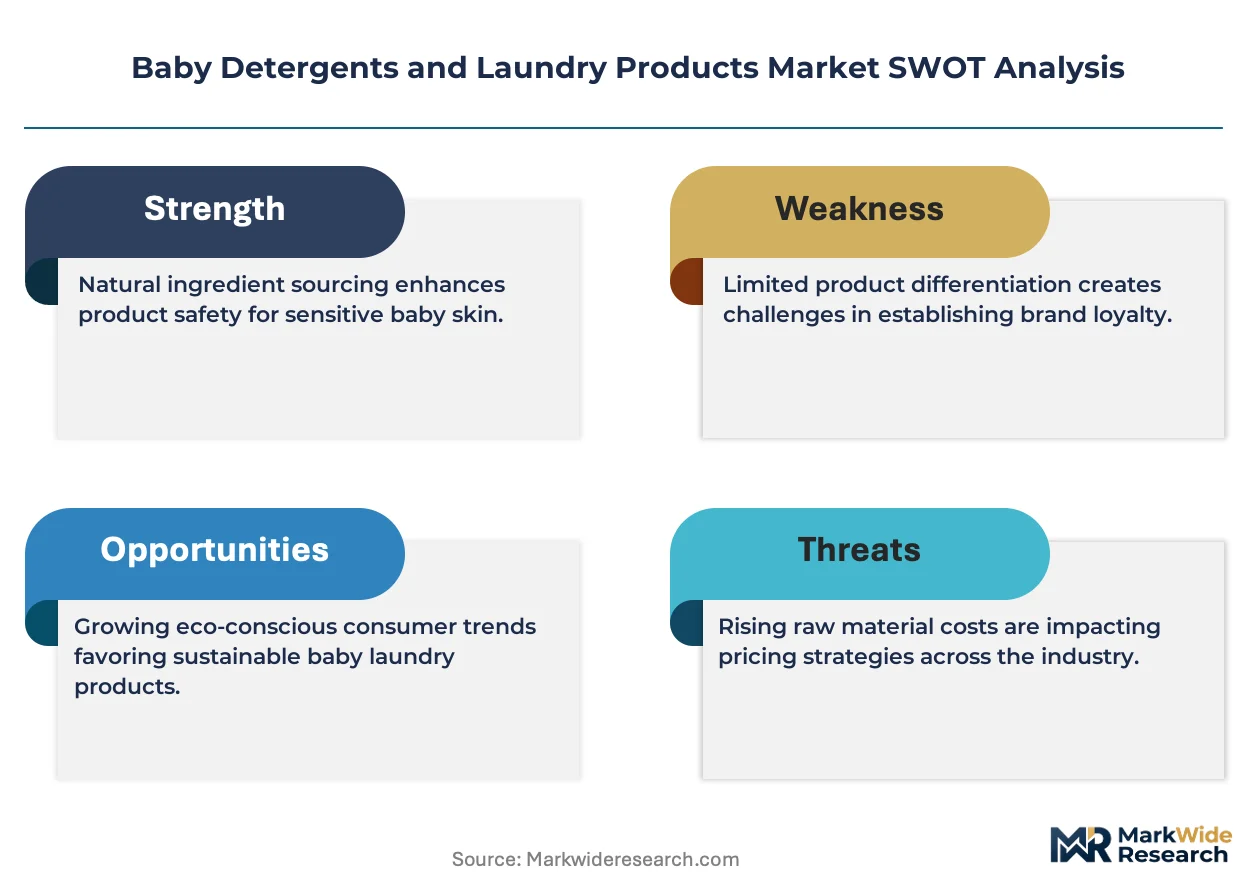
- Hypoallergenic:Formulations subjected to pediatric dermatologist endorsement protocols and patch testing on sensitive skin populations command premium shelf positioning in pharmacy and specialty retail channels. Germany and the United States exhibit the steepest demand concentration as medical professional recommendations accelerate parent purchasing decisions.
- Fragrance-Free:Complete exclusion of synthetic odorants and masking agents addresses respiratory pathway concerns for infants with developing immune systems, with California Cleaning Product Right to Know Act disclosure mandates normalizing transparency expectations that premium brands leverage.
- Natural:Plant-derived alkyl polyglucoside surfactants from coconut and corn feedstocks attract venture-backed entrants despite 15-30% per-unit cost premiums over petroleum alternatives.
- Enzymatic:Protease and lipase variants engineered for low-temperature activation reduce household energy consumption but face shelf-life constraints from temperature-sensitive degradation in liquid suspension.
Hypoallergenic captures the largest revenue pool; fragrance-free is expanding most quickly as pediatric dermatologist recommendations displace standard formulations.
Packaging Type:
Volume economics and supply concentration in blow-molded PET and flexible film converting determine competitive access across container formats.
- Bottles:HDPE and PET containers with child-resistant closures dominate liquid detergent segments, though lightweighting pressures and post-consumer recycled content mandates from the EU Packaging and Packaging Waste Regulation are forcing resin reformulation investments.
- Sachets:Single-use flexible film pouches concentrate surfactant doses for travel and trial formats, with water-soluble polymer development enabling direct-to-drum dispensing that eliminates wrapper waste.
- Boxes:Corrugated and paperboard secondary packaging for powder formats aligns with retailer sustainability scorecards, though moisture sensitivity constrains distribution radius in humid climates.
- Jars:Wide-mouth PET containers serve institutional bulk formats and refill station pilots in German and French retail cooperatives.
Bottles handle the majority of throughput; sachets are climbing the fastest as direct-to-parent subscription models normalize sample-to-subscription conversion funnels.
End User:
Customer type determines specification intensity, with institutional procurement consolidating around certified vendors while fragmented parent demand rewards transparency marketing.
- Parents:First-time parents in metropolitan India and China represent underpenetrated demand for certified-hypoallergenic segments, with digital-native cohorts exhibiting elevated willingness-to-pay for ingredient transparency and subscription convenience.
- Hospitals:Pediatric wards and neonatal intensive care units in Germany and France specify dermatologically tested formulations in tender documents, consolidating supplier relationships around single-source certified vendors with multi-year supply agreements.
- Daycares:Licensed childcare facilities in the United States face state-level sanitation mandates that specify fragrance-free and dye-free requirements, creating procurement scale for mid-tier institutional formats.
- Caregivers:Professional and familial caregivers serving infants with diagnosed skin conditions drive demand for prescription-adjacent therapeutic positioning, though FDA oversight of cosmetic-drug claims creates compliance barriers for brands lacking clinical substantiation.
Parents represent the largest addressable base; hospitals are gaining specification authority fastest as procurement cooperatives consolidate vendor relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances concentrate manufacturing advantage in chemical clusters with integrated surfactant feedstock access, while premium consumption gravitates toward high-income markets with stringent pediatric safety standards. The United States, Germany, and China anchor the three poles of this trade geometry.
United States
Pediatric dermatologist endorsement protocols and subscription commerce penetration drive premium-tier demand concentration. The California Cleaning Product Right to Know Act extends ingredient disclosure mandates beyond federal EPA Safer Choice minimums. Manufacturing clusters in New Jersey and Ohio supply liquid formulation capacity serving domestic and Canadian markets.
Germany
Procurement cooperatives for hospital and neonatal intensive care units consolidate supplier relationships around REACH-certified vendors. The EU REACH authorization process for nonylphenol ethoxylates forces surfactant reformulation investments that smaller competitors struggle to absorb. The Rhine-Ruhr chemical corridor hosts specialized dermatological testing laboratories exceeding baseline regulatory requirements.
China
First-time parents in metropolitan Shanghai, Beijing, and Shenzhen exhibit elevated willingness-to-pay for certified-hypoallergenic segments. The Ministry of Ecology and Environment enforces dual carbon goals that constrain petroleum-based surfactant expansion. Zhejiang and Jiangsu province chemical clusters supply global intermediate demand despite single-source vulnerability concerns.
India
Urban middle-class expansion in Bangalore, Mumbai, and Delhi represents underpenetrated demand for fragrance-free formulations. The Bureau of Indian Standards develops pediatric safety testing protocols aligned with international benchmarks. Gujarat's specialty chemical belt attracts venture-backed entrants pursuing natural surfactant feedstock integration.
France
Hospital procurement systems specify dermatologically tested formulations in multi-year tender documents with concentrated buying power. ANSM oversight of cosmetic-drug claims creates compliance barriers for therapeutic positioning without clinical substantiation. The Lyon-Grenoble chemical valley anchors institutional-grade production capacity for pediatric ward supply.
Baby Detergents and Laundry Products Market Competitive Environment
Concentration sits with multinational consumer goods conglomerates possessing global manufacturing footprints and dermatological testing infrastructure. The vendor base stratifies across three tiers: scale-driven mass-market suppliers, mid-cap specialists in hypoallergenic certification, and venture-backed natural ingredient entrants. Dominant competitive moves include strategic partnerships with pediatric dermatology clinics and portfolio diversification into subscription commerce channels.
Among Cincinnati-based consumer goods conglomerates, Procter & Gamble exemplifies scale-driven archetype positioning with multi-continent supply network coverage. Within the German chemical specialist tier, Henkel AG & Co. KGaA occupies a position defined by REACH compliance leadership and institutional procurement relationships. On the direct-to-parent vector, The Honest Company represents the subscription commerce archetype emphasizing ingredient transparency and recurring revenue capture.
| Leading Market Players |
|---|
| Procter & Gamble |
| Johnson & Johnson |
| Unilever |
| Henkel AG & Co. KGaA |
| The Clorox Company |
| Church & Dwight Co., Inc. |
| Seventh Generation |
| The Honest Company |
| Babyganics |
| Others |
Value Chain & Pricing Dynamics
Multi-year procurement agreements between hospital cooperatives and REACH-certified manufacturers lock in surfactant supply access while stabilizing unit costs against palm kernel oil volatility. These contracts concentrate purchasing power among German and French institutional buyers, compressing margin flexibility for formulators serving fragmented parent demand in retail channels.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that dominate institutional procurement in Germany and France. Pricing stratifies across premium hypoallergenic, standard enzymatic, and economy bulk tiers, with certification grade and pediatric dermatologist endorsement driving the widest spreads. Pricing pressure stems from REACH reformulation costs transferring to liquid detergent lines. Parents in subscription commerce channels exhibit lowest price sensitivity; commodity powder buyers in institutional bulk face highest pressure.
Supply Chain Analysis
Inventory buffers for temperature-sensitive protease variants extend lead times for liquid formulation distributors serving hospital systems. Manufacturing concentrates in China, Germany, and the United States, with Zhejiang province chemical clusters feeding global surfactant intermediate demand. Feedstock draws from palm kernel oil plantations in Indonesia and Malaysia, coconut-derived alkyl polyglucoside sources in the Philippines, and petroleum-based ethylene crackers on the US Gulf Coast. Single-source vulnerability in Jiangsu province intermediates threatens continuity. Distribution runs through institutional procurement cooperatives in Europe and direct-to-parent subscription platforms in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across parent demand archetypes creates white-space openings as digital-native cohorts reject mass-market formulations for transparency-positioned alternatives.
For Market Incumbents: Shield margin position by deepening captive supply of bio-based surfactant feedstocks against palm oil price swings. Accelerate pediatric dermatologist endorsement protocols to defend shelf positioning against venture-backed natural entrants. Prioritize ERP modernization to satisfy lot-level ingredient traceability mandates from California and New York regulators. For New Entrants and Emerging Players: Lead with subscription commerce penetration in underpenetrated Indian metropolitan markets, where first-time parents in Bangalore and Mumbai exhibit elevated willingness-to-pay for certified-hypoallergenic positioning. Target fragrance-free segments where pediatrician recommendations are displacing standard formulations fastest. Deploy direct-to-parent digital acquisition funnels with sample-to-subscription conversion mechanics. For Investors and Strategic Acquirers: Regional contract manufacturers with integrated dermatological testing capabilities represent the most defensible acquisition profile for exposure to institutional procurement consolidation. Long-term viability hinges on REACH compliance infrastructure and hospital cooperative relationships rather than brand equity alone. Monitor EPA Safer Choice certification expansion as signal for regulatory acceleration that rewards early bio-based adopters.| Strategic Initiative | Industry Significance |
|---|---|
| Pediatric Dermatologist Endorsement Protocol | Medical professional validation accelerates parent purchasing decisions in pharmacy and specialty retail channels. |
| Subscription Commerce Platform Launch | Recurring revenue models reduce customer acquisition costs versus traditional mass retail distribution. |
| Backward Integration into Bio-Based Feedstocks | Captive supply of plant-derived surfactants insulates margins from agricultural commodity volatility. |
| Hospital Procurement Cooperative Partnership | Multi-year supply agreements with German and French institutions lock in institutional volume. |
| Lot-Level Traceability System Deployment | ERP modernization satisfies California Cleaning Product Right to Know Act disclosure mandates. |
Study Parameters
Cross-validation between primary interviews with pediatric dermatologists, hospital procurement officers, and brand managers anchors the qualitative findings against secondary validation from EPA Safer Choice certifications, EU REACH authorization dossiers, and customs trade data. Bottom-up triangulation across formulation chemistry segments converges with top-down demand modeling from Nielsen retail audit data and hospital procurement databases.
Sensitivity analysis across surfactant feedstock price scenarios and regulatory acceleration timelines shapes the analytical framework over the projection horizon. Segmentation dimensions include product type, ingredient certification grade, packaging format, and end-user channel. CAGRs derive from regression analysis against pediatric birth rate projections and premium-tier adoption curves, with cold-water enzymatic chemistry penetration and subscription commerce growth as key forecast inputs.
Forecasts assume regulatory continuity in EPA Safer Choice and EU REACH regimes; material policy shifts would require re-modeling surfactant authorization pathways and compliance cost burdens. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Products
France Baby Care Products Market
Baby Products
Sippy Cups Market
Baby Products
Baby Prams and Strollers Market
Baby Products
Noise-Muffling Infant Hat Market
Baby Products
Travel Pillow Market
Baby Products
Luxury Baby Stroller Market
Baby Products
Cloth Diapers Market
Baby Products
AI Smart Baby Monitors Market
Baby Products
Electric Baby Nail Trimmer Market
Baby Products
Puppy Teething Toys Market
Baby Products
Postpartum Products Market
Baby Products
Baby Pacifier Thermometer Market
Baby Products
Soft Sole Baby Shoes Market
Baby Products
Netherlands Baby Care Products Market
Baby Products
Indonesia Baby Care Products Market
Baby Products
Diaper Bag Market