
 Global Tampons Market | 2026-2036
Global Tampons Market Size, Share, and Industry Trends Forecast 2026-2036
Global Tampons Market Intelligence
The U.S. FDA's Class II medical device designation for tampons is unwinding the historical dominance of legacy materials, creating new entry points. Procter & Gamble leverages its extensive distribution network and brand recognition to maintain market share. In contrast, specialists like Natracare and Corman differentiate through their focus on organic and chemical-free product lines. Kimberly-Clark competes on a global scale with a broad portfolio covering multiple absorbency levels.
Tampons are absorbent menstrual hygiene products inserted into the vagina to absorb menstrual flow. They are typically constructed from a blend of purified cotton and rayon fibers, with standardized absorbency ratings measured in grams to ensure user safety. Within product types, organic tampons are seeing significant uptake due to health and environmental concerns. The teen end-user segment is a critical battleground for manufacturers, influencing long-term brand loyalty and purchasing habits.
Regulatory frameworks from bodies like the U.S. FDA and Australia's TGA mandate strict testing for absorbency and material safety. In Europe, regulations such as REACH restrict the use of certain chemicals, influencing material sourcing for tampon manufacturing. Navigating these divergent regional regulations for material composition and marketing claims remains a central challenge for brands seeking a unified global product strategy.
Market Dynamics
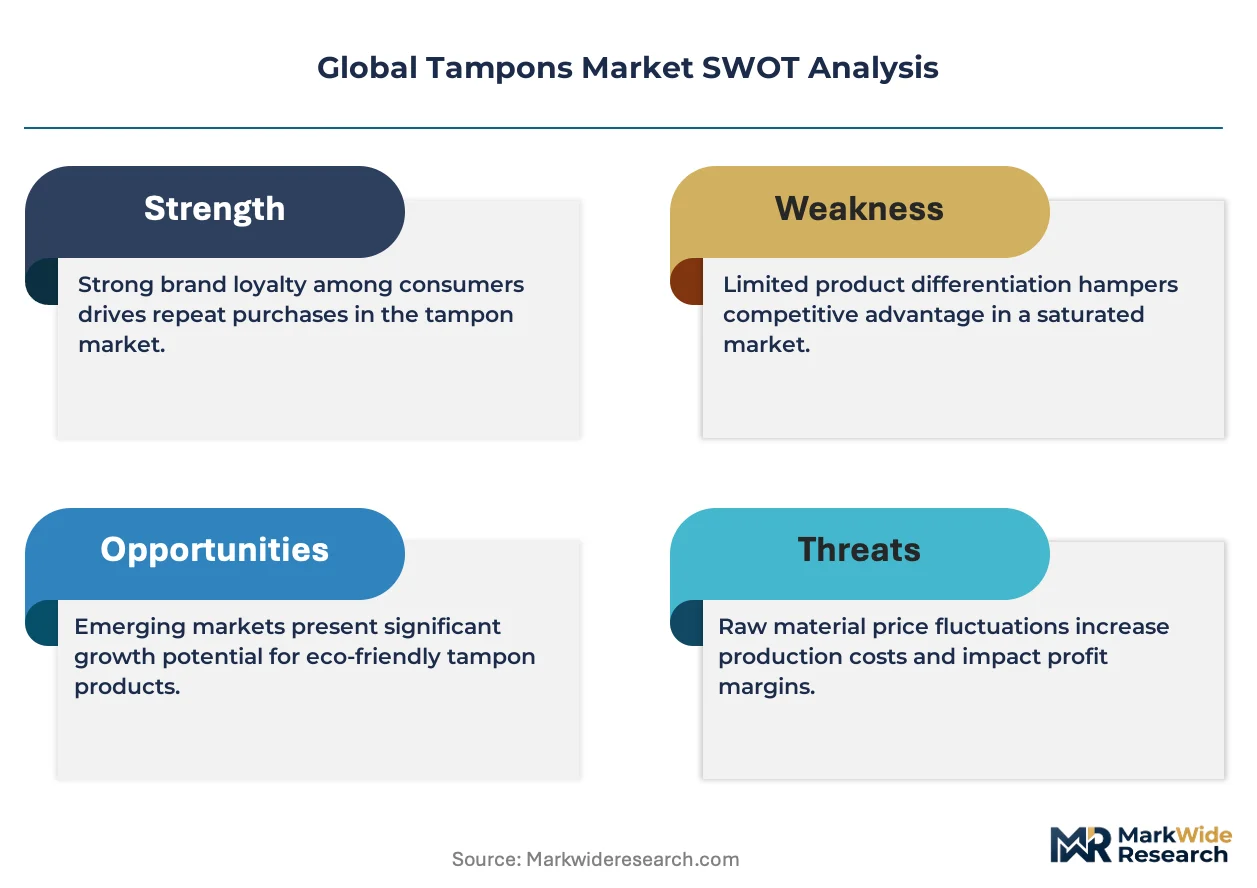
The central dynamic in the tampons market is the tension between medical device regulation driving material standardization and consumer-led demand for product differentiation. This conflict forces brands to balance compliance with bodies like the FDA against marketing sustainable materials like organic cotton.
Growth Catalysts
- Public Health Initiatives:Health campaigns in India are destigmatizing menstruation, driving first-time adoption in a key market.
- Sustainable Materials:Consumer demand for environmental transparency fuels growth for organic cotton and bio-plastic applicator segments.
- Athlete End-Use:Adoption by athletes for protection during sports normalizes use and provides a performance-based marketing angle.
Market Restraints
- Regulatory Divergence:Conflicting rules between the U.S. FDA and Europe's REACH framework complicate global product strategies and increase compliance costs.
- Input Cost Volatility:Price fluctuations for certified organic cotton create margin pressure for brands specializing in the premium, sustainable product tier.
- Substitution Threat:The rising adoption of reusable menstrual cups and discs presents a direct substitution threat to the disposable tampon model.
Strategic Opportunities
- Geographic Expansion:Untapped demand in rural Southeast Asia and Africa presents growth potential via education-led market entry strategies.
- DTC Channels:Direct-to-consumer subscription models build brand loyalty and gather consumer data, bypassing traditional retail gatekeepers.
- Product Personalization:Tampons with wider absorbency arrays or specialized shapes can capture niche segments with specific physiological needs.
Industry Challenges
- Compliance Burden:The extensive and costly absorbency testing mandated by regulators like Australia's TGA creates a significant barrier for new and small-scale manufacturers.
- Cultural Barriers:Overcoming deep-seated cultural taboos and misinformation surrounding tampon use remains a primary challenge for market development in many conservative regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Tampons Market |
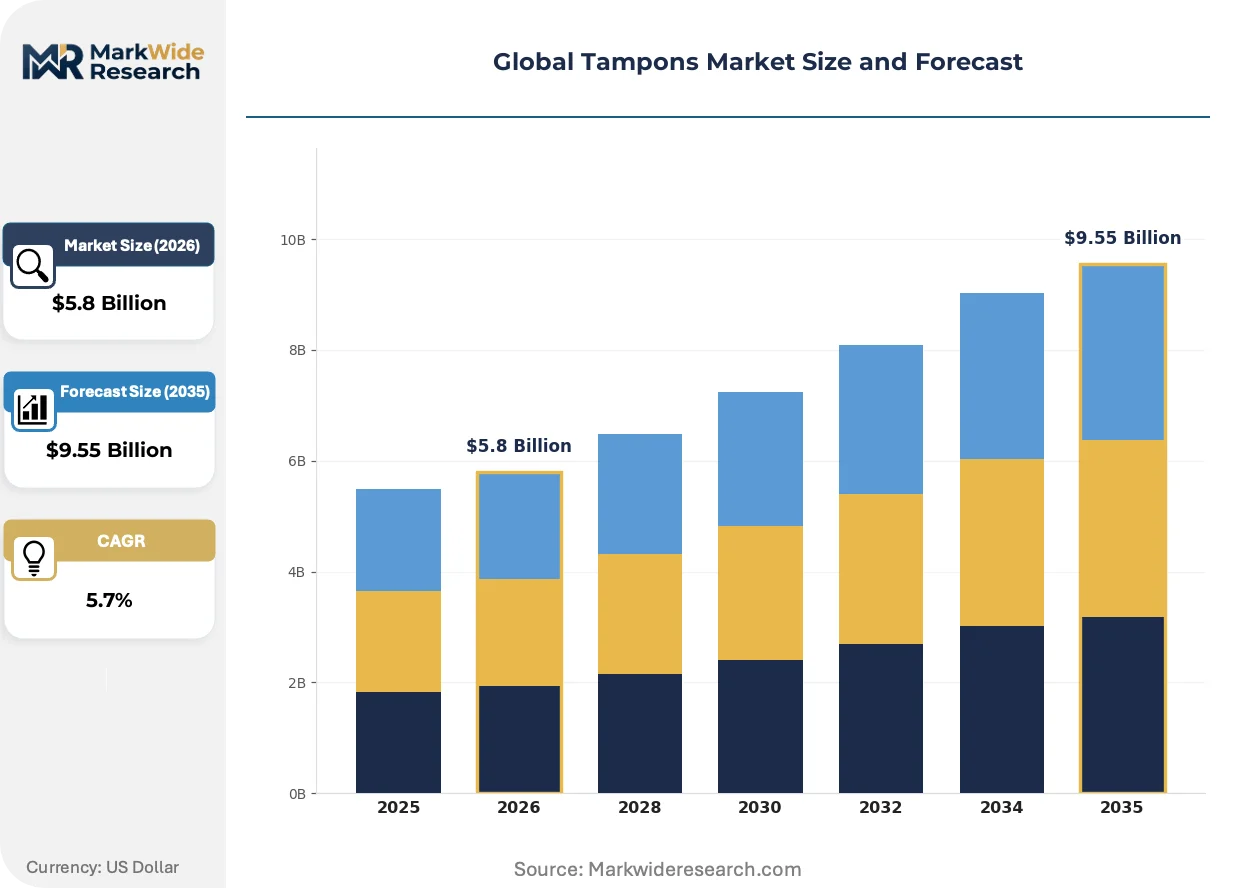
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Regular, Super, Ultra, Organic, Scented Application: Menstrual Protection, Postpartum Care, Sports Activities, Daily Use, Travel End User: Teens, Working Women, Athletes, Travelers, Students Packaging Type: Box, Pouch, Plastic Wrapper, Eco-Friendly Wrap, Compact Case |
| Companies Covered | Procter & Gamble, Johnson & Johnson, Kimberly-Clark, Edgewell Personal Care Company, Unicharm, Natracare, Rossmann, Corman, Svenska Cellulosa Aktiebolaget, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Tampons Market Strategic Shifts & Innovations
Material science and evolving consumer health priorities are redefining the tampon category. Innovations are shifting the product focus from basic functionality toward holistic wellness, environmental impact, and ingredient transparency, creating new competitive arenas.
Bio-based applicators and plastic-free tampon designs, often using organic cotton, represent a key product evolution. These sustainable alternatives are being rapidly adopted by health-conscious and environmentally aware consumers, particularly in European markets. This material diversification is fragmenting the traditional, monolithic rayon-cotton blend market, creating distinct niches for sustainability-focused brands to thrive.
Europe's REACH regulation imposes strict controls on chemical substances, directly influencing material sourcing for tampons sold within the EU. This forces manufacturers to rigorously vet their supply chains for restricted chemicals, often leading to the adoption of purer, certified materials. The regulation most affects brands with complex global supply chains, pushing them toward regionalized material sourcing strategies to ensure compliance.
A notable behavioral shift is the move toward subscription-based purchasing models for menstrual care products. This trend disrupts the traditional one-time purchase cycle in pharmacies and supermarkets, with direct-to-consumer (DTC) brands gaining traction. This direct relationship is most visible in North America, where it allows for product personalization and builds long-term customer loyalty.
Global Tampons Market Segmentation
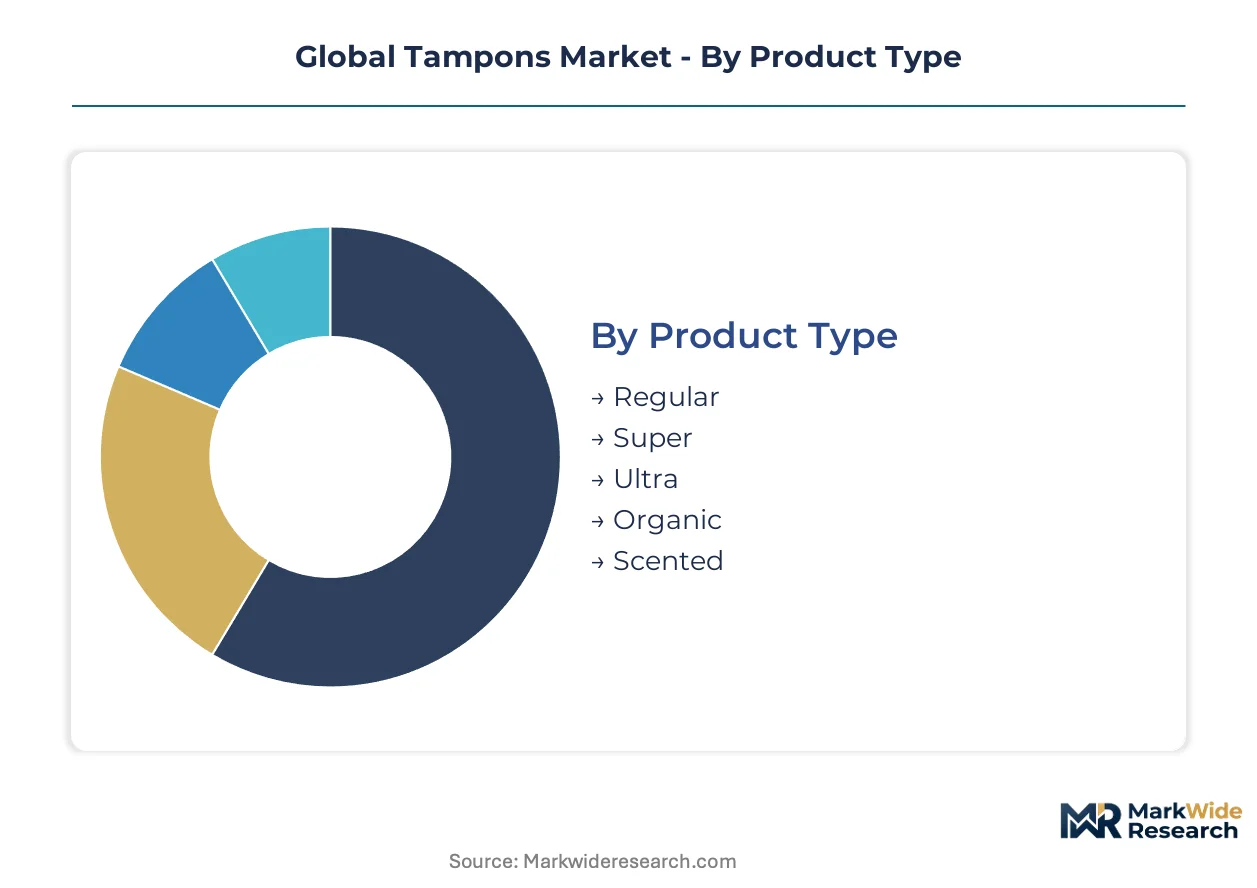
The tampons market segments reflect the diverse needs of consumers and the evolving regulatory landscape. Understanding these distinctions allows brands to tailor product development and marketing strategies effectively. This market structure also highlights the tension between standardized medical device requirements and consumer demand for differentiated products.
Product Type:
Regulatory bodies like the U.S. FDA and Europe's REACH framework directly influence the material composition and safety standards for various tampon product types.
- Organic:These tampons feature purified cotton that is grown without synthetic pesticides or fertilizers, appealing to health-conscious consumers. Demand for organic variants concentrates in European markets, driven by stringent environmental regulations and consumer preferences.
- Ultra:Designed for very heavy menstrual flow, Ultra tampons offer the highest absorbency levels, measured in grams, to provide extended protection. This product type is critical for individuals requiring maximum security, particularly during overnight use or specific physical activities.
- Regular:This standard absorbency level is suitable for light to moderate menstrual flow, representing a foundational product within the market.
- Super:Offering higher absorbency than Regular, Super tampons cater to moderate to heavy flow, providing reliable protection for many users.
- Scented:These tampons contain added fragrances, though some consumers avoid them due to potential irritation concerns.
Established volume favors Regular absorbency; emerging adoption favors Organic product types.
Application:
The diverse needs of individuals drive specific application categories for tampon products.
- Menstrual Protection:This is the primary and most widespread application, providing internal absorption of menstrual flow for daily comfort and hygiene. This core application drives the majority of product development and sales volume across all geographies.
- Sports Activities:Tampons offer discreet and secure menstrual protection for athletes, enabling participation in various sports without discomfort or leakage concerns. Adoption in this segment is a key growth vector, supported by performance-based marketing.
- Postpartum Care:Some individuals use tampons for lochia absorption after childbirth, though specific medical guidance is often recommended.
- Daily Use:While less common due to health recommendations, some users may opt for tampons for daily light discharge or spotting.
- Travel:Compact and discreet, tampons are a preferred choice for menstrual hygiene during travel, offering convenience and portability.
Core demand concentrates in Menstrual Protection, while Sports Activities exhibit the steepest expansion trajectory.
End User:
Manufacturers tailor product features and marketing efforts to distinct end-user demographics within the tampons market.
- Teens:This segment represents a critical battleground for manufacturers, influencing long-term brand loyalty and purchasing habits through early product experiences. Educational campaigns on menstrual hygiene often target this demographic in developing markets like India.
- Athletes:Individuals engaged in sports activities prefer tampons for their discreetness and ability to provide secure protection during physical exertion. This end-user group values performance and comfort.
- Working Women:This broad demographic seeks reliable and comfortable menstrual hygiene solutions that integrate seamlessly into their professional lives.
- Travelers:Portability and discretion are key considerations for travelers, making tampons a convenient option for menstrual care on the go.
- Students:Similar to teens, students require accessible and effective menstrual hygiene products for use in academic and social settings.
Long-term brand loyalty often originates with Teens, while Athletes represent a segment with performance-driven purchasing habits.
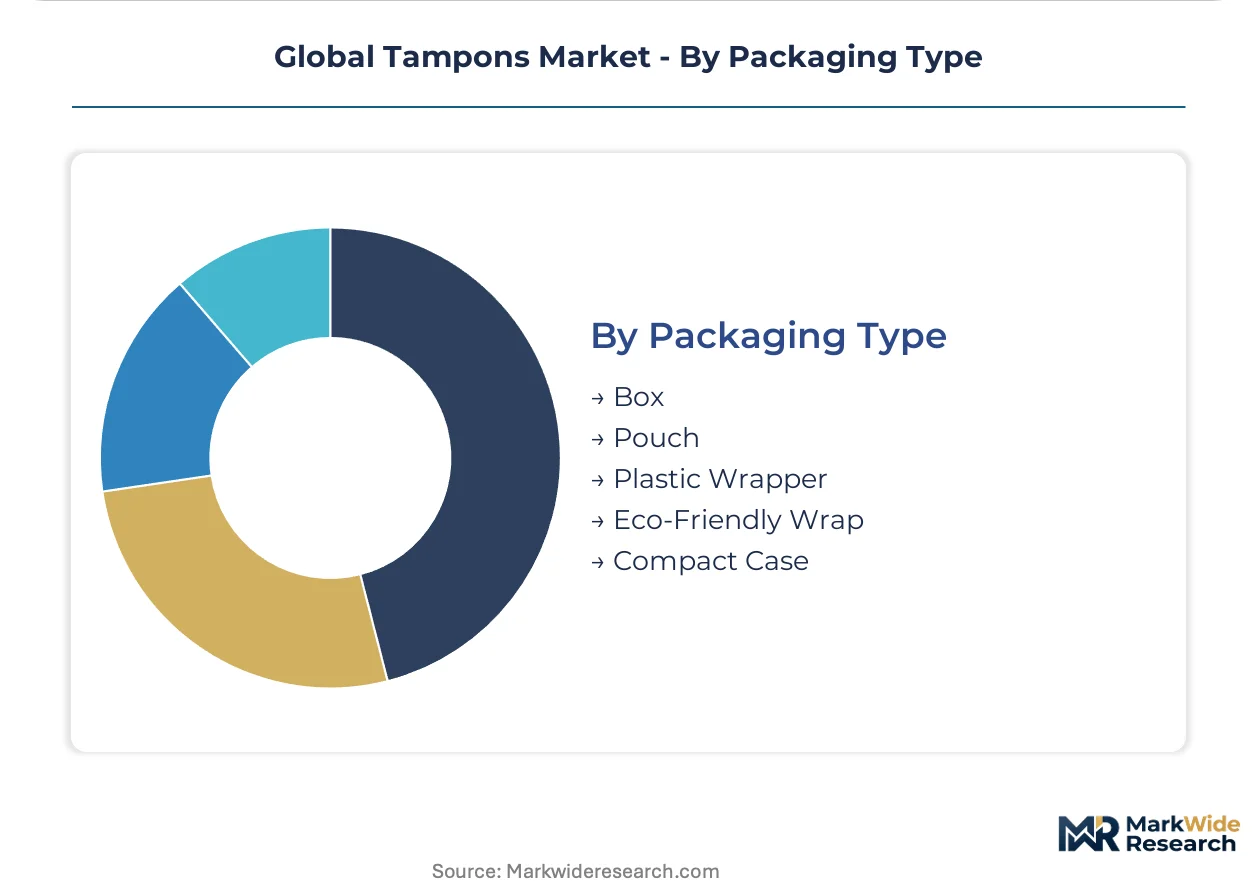
Packaging Type:
Consumer preferences for sustainability and convenience directly shape the packaging type innovations in the market.
- Eco-Friendly Wrap:This packaging type utilizes biodegradable or compostable materials, such as bio-plastics or paper, aligning with consumer demand for sustainable products. Adoption is particularly strong in European markets due to environmental awareness.
- Box:The traditional and widely recognized packaging format, typically made from cardboard, providing structural integrity and product protection. Box packaging offers a cost-effective and familiar presentation for consumers.
- Pouch:Flexible pouch packaging offers convenience and a compact design, often used for smaller quantities or travel-sized packs.
- Plastic Wrapper:Individual tampons are often encased in plastic wrappers for hygiene and ease of disposal, though environmental concerns are driving alternatives.
- Compact Case:Reusable or discreet cases designed to carry tampons, offering portability and privacy for users.
Traditional Box packaging maintains significant market presence, but Eco-Friendly Wrap is gaining share fastest due to environmental considerations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer-archetype concentration in the tampons market heavily influences regional demand patterns. Teens represent a critical demographic for long-term brand loyalty, particularly in developing markets like India. Working women and athletes also drive specific product needs across diverse geographies, demanding reliable and discreet solutions.
India
Public health initiatives in India are destigmatizing menstruation, driving first-time adoption among a vast and previously underserved population. The Indian government's focus on women's health through various campaigns supports menstrual hygiene awareness programs. Major metropolitan centers like Mumbai and Delhi see increasing distribution of modern menstrual products, signaling market maturity.
United States
Consumer preference for organic materials and clear absorbency ratings drives significant demand across the United States. The U.S. FDA's Class II medical device designation ensures strict product safety and labeling standards. New York City and Los Angeles exhibit high consumer engagement with sustainable and direct-to-consumer tampon brands.
Germany
Strong consumer demand for sustainable products and stringent environmental regulations shape the German tampons market. Europe's REACH framework directly influences material sourcing for tampons sold across Germany. Berlin and Munich are centers for eco-conscious consumer purchasing, favoring organic cotton options.
Australia
Athlete adoption for menstrual protection during sports activities is a significant growth vector in Australia. Australia's TGA mandates strict testing for absorbency and material safety, ensuring user confidence. Sydney and Melbourne see strong sales for performance-oriented tampon products, especially among active women.
France
Health-conscious consumers in France increasingly prioritize organic and chemical-free product lines. European regulations like REACH impact material composition and marketing claims for French brands. Paris and Lyon are key markets for bio-based applicator innovations and plastic-free tampon designs.
Global Tampons Market Key Industry Players
Player mix skews toward established, diversified consumer goods companies with extensive brand portfolios. These global CPG giants often leverage broad distribution networks to maintain market presence. Specialized organic and chemical-free brands represent a distinct archetype, focusing on niche consumer segments. Regional private label manufacturers also occupy a significant portion of the market, competing on price. Portfolio diversification and geographic expansion remain dominant competitive moves across the industry.
Within the global consumer goods tier, Procter & Gamble and Kimberly-Clark exemplify the broad market reach and multi-product strategies of large corporations. Procter & Gamble maintains market share through its extensive distribution network and brand recognition across various product types. Kimberly-Clark competes on a global scale with a broad portfolio covering multiple absorbency levels and consumer needs. Natracare, a specialist brand, differentiates through its focus on organic and chemical-free product lines, representing the growing sustainable segment. These entities collectively shape the competitive dynamics through product innovation and market penetration.
| Leading Market Players |
|---|
| Procter & Gamble |
| Johnson & Johnson |
| Kimberly-Clark |
| Edgewell Personal Care Company |
| Unicharm |
| Natracare |
| Rossmann |
| Corman |
| Svenska Cellulosa Aktiebolaget |
| Others |
Cost & Logistics Intelligence
Scale economies in tampon manufacturing, particularly for conventional products, drive down per-unit costs. This inherent scale shapes supply concentration among large producers and establishes competitive price floors for widely adopted product types.
Pricing Analysis
Cost-plus contracts, often indexed to raw material prices like purified cotton and rayon, govern large-volume tampon procurement. Price differentiation stems from organic certification levels and brand premium, particularly for specialized products. Pricing pressure stems from input cost volatility for certified organic cotton, impacting premium segments. Teen end-users are highly brand-sensitive for initial purchases but also exhibit price sensitivity.
Supply Chain Analysis
Just-in-time inventory strategies are common for conventional tampon products due to shelf-life considerations and high volume. Supply concentrates in countries with established manufacturing infrastructure like the United States and Germany. Raw material dependencies include purified cotton, rayon fibers, and bio-based plastics. Regulatory divergence between the U.S. FDA and Europe's REACH framework presents a structural supply chain risk. Distribution runs through retail pharmacies and increasingly direct-to-consumer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tampons market offers a significant service-attach opportunity, with direct-to-consumer (DTC) subscription models expanding faster than traditional product sales. This recurring-revenue stream builds long-term customer loyalty and provides valuable consumer data.
For Market Incumbents:Fortify existing market share by expanding sustainable product lines, leveraging extensive distribution networks for organic and bio-based tampons. This addresses the substitution threat from reusable alternatives and changing consumer preferences. Invest in R&D for advanced material science to maintain a competitive edge against specialist brands.
For New Entrants and Emerging Players:Differentiate on environmental impact and ingredient transparency, targeting health-conscious consumers in European markets. Penetrate underserved rural Southeast Asia through education-led market entry strategies. Utilize direct-to-consumer channels to build brand loyalty and bypass traditional retail gatekeepers.
For Investors and Strategic Acquirers:Mid-cycle technology positioning favors specialists in sustainable menstrual hygiene products with strong intellectual property in bio-based materials. Long-term viability rests on adapting to evolving regulatory frameworks and consumer demand for eco-friendly solutions. Regulatory mandates for plastic reduction in Europe represent a crucial inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Bio-based Material R&D | Develops next-generation tampon materials, addressing environmental concerns and European regulations. |
| Direct-to-Consumer Subscription Launch | Builds brand loyalty among teen end-users and provides valuable purchasing data in North America. |
| Geographic Expansion in India | Capitalizes on public health initiatives and first-time adoption in a key developing market. |
| Organic Product Line Extension | Caters to health-conscious consumers and aligns with stringent environmental standards like REACH. |
| Absorbency Level Diversification | Captures niche segments like athletes requiring specialized protection for sports activities. |
Research Approach
A standing panel of brand managers, regulatory affairs specialists, material scientists, and public health officials provided ongoing calibration for this study. Primary interviews with these industry stakeholders were combined with rigorous secondary research for validation. Secondary data sources included U.S. FDA guidance, Europe's REACH regulations, Australia's TGA reports, and published consumer trend analyses. Bottom-up and top-down triangulation ensured comprehensive market sizing.
Output consistency was validated against external benchmarks, including historical sales data and public health statistics across the analysis window. The analytical framework modeled growth across product types like organic and ultra, diverse applications such as sports activities, and end-user segments including teens. Compound annual growth rates were derived from a multi-factor regression model, incorporating inputs like public health campaign effectiveness and material innovation rates.
The analysis sits within stated boundaries; outcomes outside significant regulatory shifts or unforeseen material science breakthroughs would require recalibration. Forecasts reflect documented assumptions regarding consumer preferences and market development. Revision becomes warranted when major policy changes concerning menstrual hygiene or material safety cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Grooming Products
Baby Oil Market
Personal Grooming Products
Baby Grooming Kits Market
Personal Grooming Products
Europe and MEA Condom Market
Personal Grooming Products
Insoles Market
Personal Grooming Products
Sneaker Deodorant Market
Personal Grooming Products
Global Away-From-Home Tissue and Hygiene Market
Personal Grooming Products
Heated Razor Starter Kit Market
Personal Grooming Products
Facial Hair Care Wipes Market
Personal Grooming Products
Global Mosquito Repellent Products Market
Personal Grooming Products
Electric Tooth Polisher Market
Personal Grooming Products
India Beard Trimmer Market
Personal Grooming Products
Massage Fascia Gun Market
Personal Grooming Products
Global Consumer Use IPL Hair Removal Devices Market
Personal Grooming Products
Military Hydration Products Market
Personal Grooming Products
Toothpaste Tablet Market
Personal Grooming Products
Mexico Beard Trimmer Market