
 Belladonna Market | 2026-2036
Belladonna Market Size, Share, and Industry Trends Forecast 2026-2036
Belladonna Market Analytics
Multi-source alkaloid procurement is decoupling from single-plantation dependency as manufacturers diversify geographic supply bases. Standard Homeopathic Company leverages its vertically integrated tincture operations to secure consistent raw material flows. Dr. Willmar Schwabe GmbH & Co. KG anchors European demand through its specialized mother tincture portfolio. Weleda competes in premium cosmetic and therapeutic channels with certified biodynamic sourcing protocols.
Atropa belladonna, a perennial Solanaceae species, yields tropane alkaloids—principally hyoscyamine, scopolamine, and atropine—extracted from leaf and root tissues via maceration or percolation for pharmaceutical and homeopathic processing. Extracts dominate value capture due to stringent pharmacopeial standardization and API-grade purification requirements, while capsules sustain volume growth through direct-to-consumer nutraceutical channels. Teas remain a mature, price-pressured segment concentrated in traditional medicine practitioner networks.
The FDA botanical drug guidance, EMA's Committee on Herbal Medicinal Products monographs, and the EU Traditional Herbal Medicinal Products Directive collectively enforce marker compound thresholds and GMP traceability across the value chain. These frameworks elevate compliance costs for smaller raw material traders while consolidating market access around certified extractors. Stakeholders must monitor evolving alkaloid scheduling debates and pharmacovigilance reporting obligations that could reshape product registration pathways.
Market Dynamics
Pharmacopeial standardization mandates from EMA and FDA are compressing the supplier base for belladonna extracts, forcing raw material traders to absorb compliance costs or exit while certified extractors consolidate procurement relationships.
Growth Catalysts
- EU Traditional Herbal Medicinal Products Directive:Registration pathways for homeopathic tinctures create formal demand channels in Germany, France, and Italy, locking in volume commitments from pharmacy networks.
- Antispasmodic formulation demand:Gastroenterology and urology pharmaceutical pipelines expand hyoscyamine procurement for irritable bowel syndrome and overactive bladder therapeutics.
- Biodynamic certification protocols:Premium cosmetic manufacturers in Switzerland and Austria specify Demeter-certified belladonna for mother tincture inputs, commanding price premiums over conventional extracts.
Market Restraints
- Wild population harvesting constraints:Atropa belladonna's protected status across multiple European habitats limits scalable raw material sourcing, concentrating supply among licensed cultivators in Poland and Hungary.
- Alkaloid content volatility:Seasonal variation in hyoscyamine and scopolamine concentrations requires batch-specific standardization, elevating quality control overhead for extractors.
- Synthetic tropane substitution:Laboratory-produced atropine and scopolamine from precursors bypass agricultural supply chains entirely for pure API applications.
Strategic Opportunities
- Veterinary phytomedicine expansion:Homeopathic belladonna formulations for equine colic and bovine mastitis remain underdeveloped in North American markets, offering first-mover positioning.
- CSRD supply chain disclosure:EU corporate sustainability reporting mandates create competitive differentiation for extractors with documented wild-harvest-to-shelf traceability systems.
- Direct-to-practitioner e-commerce:Specialized tincture portals bypass traditional wholesale-pharmacy intermediaries, capturing margin from naturopathic and anthroposophic medical networks.
Industry Challenges
- Phytochemical analytical expertise scarcity:HPLC and titration specialists capable of validating alkaloid marker compounds command premium compensation, constraining smaller extractors' expansion capacity.
- Multi-jurisdiction registration complexity:Divergent FDA botanical drug guidance, EMA herbal monographs, and national homeopathic pharmacopeias require parallel dossier preparation for cross-border product placement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Belladonna Market |
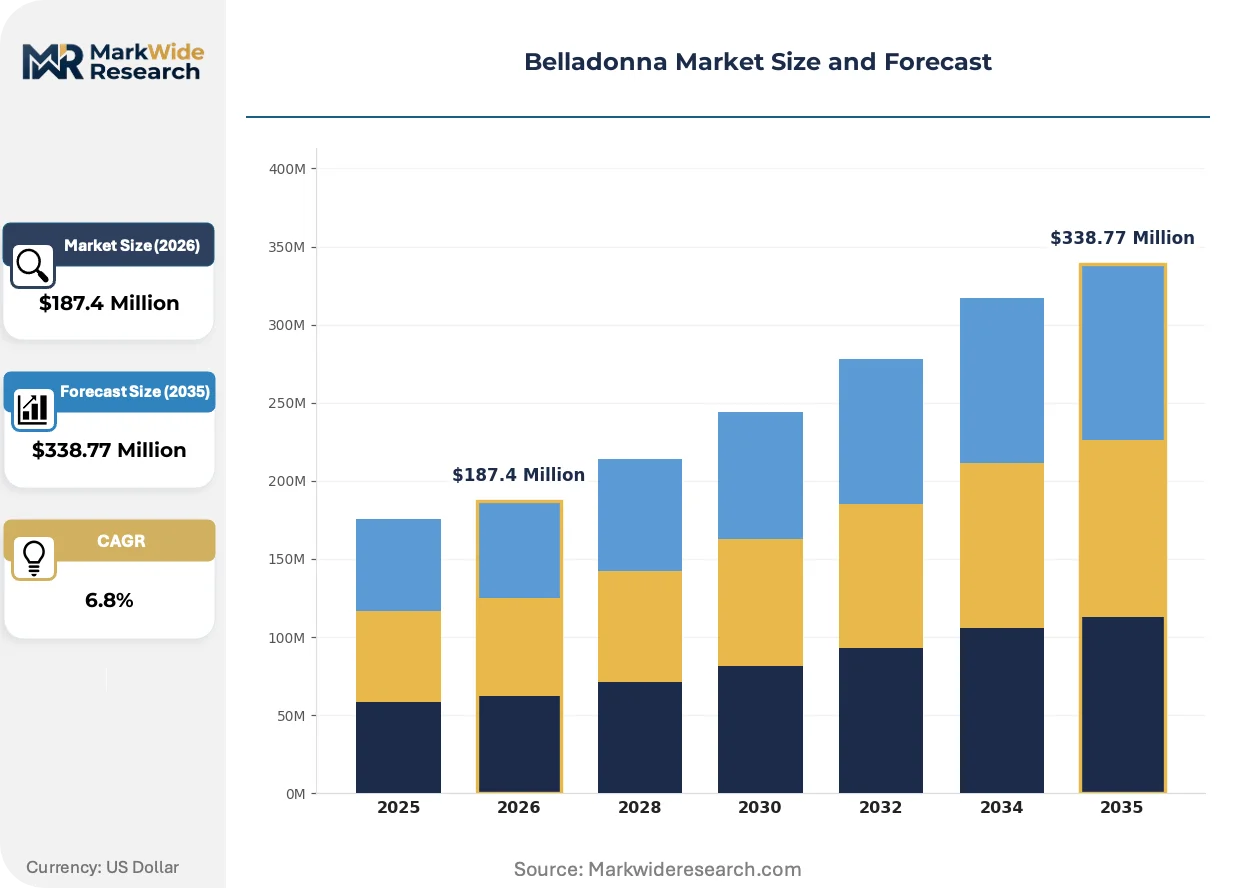
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Extracts, Powders, Capsules, Teas End User: Pharmaceuticals, Herbalists, Retailers, Laboratories Application: Medicinal Use, Homeopathy, Cosmetics, Traditional Remedies Delivery Mode: Oral, Topical, Inhalation, Others |
| Companies Covered | Standard Homeopathic Company, Dr. Willmar Schwabe GmbH & Co. KG, Weleda, Xian Aladdin Biological Technology, Shanxi Zhendong Anxin Biopharmaceutical Co.,Ltd., CSPC Ouyi Pharmaceutical Co.,Ltd., Biologische Heilmittel Heel GmbH, Riotto Botanical, Laboratoires Boiron SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Belladonna Market Evolving Landscape
Extraction technology and procurement architecture are converging to reshape how belladonna alkaloids move from field to finished formulation, with implications for cost structures and competitive positioning across therapeutic categories.
Supercritical CO2 extraction systems are absorbing market share from conventional solvent-based maceration in high-purity API manufacturing. German and Swiss pharmaceutical extractors deploy these units to eliminate residual solvent contamination risks that complicate FDA botanical drug applications. The technology is absorbing capital investment that previously flowed into percolation infrastructure, compressing equipment supplier margins for traditional extraction hardware.
REACH authorization requirements for tropane alkaloid handling are tightening occupational exposure protocols across EU manufacturing facilities. ECHA's 2023 updated guidance on highly toxic plant extracts mandates closed-system processing and specialized waste containment, elevating facility retrofit costs. Small-scale tincture producers in Portugal and Spain are responding by consolidating into shared-service extraction cooperatives to amortize compliance investments.
Hospital formulary committees are tightening botanical drug inclusion criteria, shifting procurement toward standardized extracts with published bioequivalence data. German university hospital networks now require ISM-compliant documentation for homeopathic mother tinctures, displacing traditional supplier relationships based on historical purchasing patterns. This behavioral shift concentrates most visibly in Bavaria and Baden-Württemberg, where integrated care contracts bundle phytomedicine reimbursement under outcome accountability frameworks.
Belladonna Market Segmentation
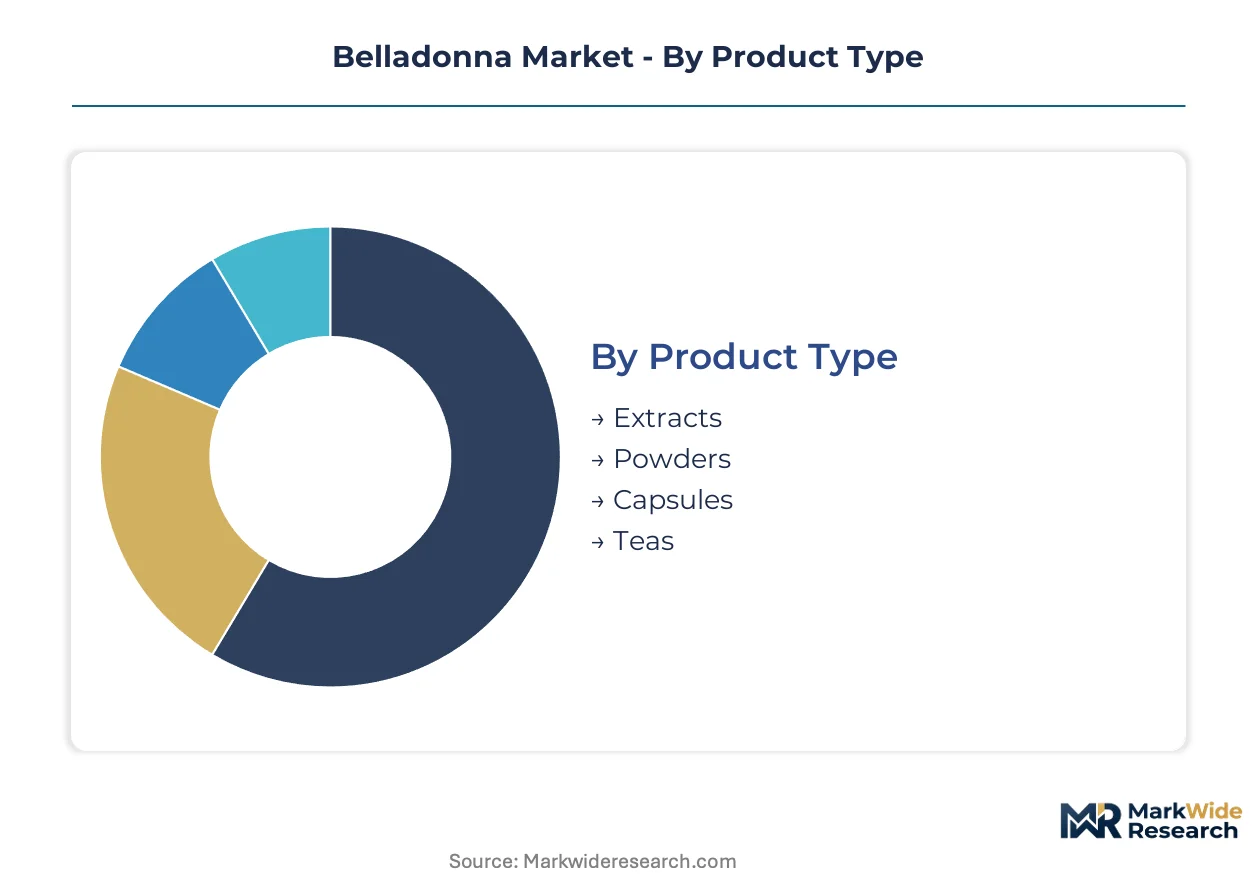
Belladonna market segmentation reveals distinct value capture patterns across processing intensities and regulatory exposure. Product form determines pharmacopeial compliance burden, while end-user concentration shapes procurement contract structures and pricing power distribution.
Product Type:
Upgrade cycles in extraction technology are displacing legacy solvent-based systems, concentrating investment in supercritical CO2 infrastructure for high-purity alkaloid recovery.
- Extracts:Liquid and dry standardized preparations containing defined hyoscyamine and scopolamine concentrations. Pharmaceutical manufacturers in Germany and Switzerland absorb the majority of API-grade extract volumes under EMA monograph compliance frameworks.
- Capsules:Encapsulated dried leaf or root powder with variable alkaloid content. Direct-to-consumer nutraceutical channels in North America drive volume expansion, though FDA botanical drug guidance limits therapeutic claim positioning.
- Powders:Milled dried botanical material for compounding and formulation feedstock. Homeopathic pharmacies in France and Italy specify pharmacopeial-grade powders for mother tincture preparation.
- Teas:Whole or cut dried leaf for traditional preparation. Practitioner networks in Eastern Europe sustain residual demand despite declining retail shelf presence.
Extracts sit at the top of the volume ranking, with capsules climbing the fastest as e-commerce nutraceutical channels expand.
End User:
Customer type stratification reflects divergent specification tolerances and batch size requirements, with pharmaceutical buyers enforcing the tightest marker compound thresholds.
- Pharmaceuticals:GMP-certified manufacturers producing antispasmodic and analgesic formulations. Irritable bowel syndrome and overactive bladder therapeutic pipelines at mid-cap European drug makers anchor hyoscyamine procurement.
- Herbalists:Licensed practitioners prescribing mother tinctures and custom preparations. German Heilpraktiker networks maintain formal reimbursement pathways under statutory health insurance adjunct coverage.
- Retailers:Pharmacy chains and specialized phytomedicine outlets. Austrian and Swiss pharmacy cooperatives specify Demeter-certified SKUs for premium positioning.
- Laboratories:Analytical service providers and research institutions validating alkaloid content. ECHA REACH compliance testing for import certification drives recurring reference standard demand.
Pharmaceuticals command the largest contract values, while herbalists are expanding most quickly through practitioner network formalization.
Application:
Application-based demand fragmentation correlates with regulatory pathway complexity, from prescription-only pharmaceutical channels to unregulated cosmetic ingredient use.
- Medicinal Use:Allopathic pharmaceutical applications requiring documented bioequivalence. Gastroenterology and urology therapeutic categories concentrate demand in German and Swiss hospital formularies.
- Homeopathy:Potentized preparations following Hahnemannian or Korsakovian dilution protocols. Mother tincture demand clusters in Baden-Württemberg and Bavaria under integrated care reimbursement contracts.
- Cosmetics:Premium skincare formulations leveraging belladonna's vasoconstrictive properties. Swiss and Austrian biodynamic manufacturers specify certified organic sourcing for anthroposophic beauty lines.
- Traditional Remedies:Ethnopharmacological preparations outside formal regulatory frameworks. Polish and Hungarian traditional medicine practitioners sustain regional tincture commerce.
Medicinal use retains the steepest revenue concentration, with cosmetics gaining share fastest through clean beauty certification trends.
Delivery Mode:
Route of administration selection reflects bioavailability requirements and patient compliance optimization across therapeutic categories.
- Oral:Tablets, capsules, and liquid preparations for systemic alkaloid absorption. Irritable bowel syndrome therapeutics favor enteric-coated oral formulations to minimize systemic anticholinergic effects.
- Topical:Creams, ointments, and plasters for localized action. Rheumatology applications in German rehabilitation clinics utilize topical belladonna preparations for musculoskeletal symptom management.
- Inhalation:Nebulized or vaporized extracts for respiratory indications. Limited commercial penetration due to tropane alkaloid occupational exposure restrictions under ECHA guidance.
- Others:Suppositories and parenteral formulations for specialized indications. Hospital compounding pharmacies in Austria maintain small-scale production for pediatric antispasmodic applications.
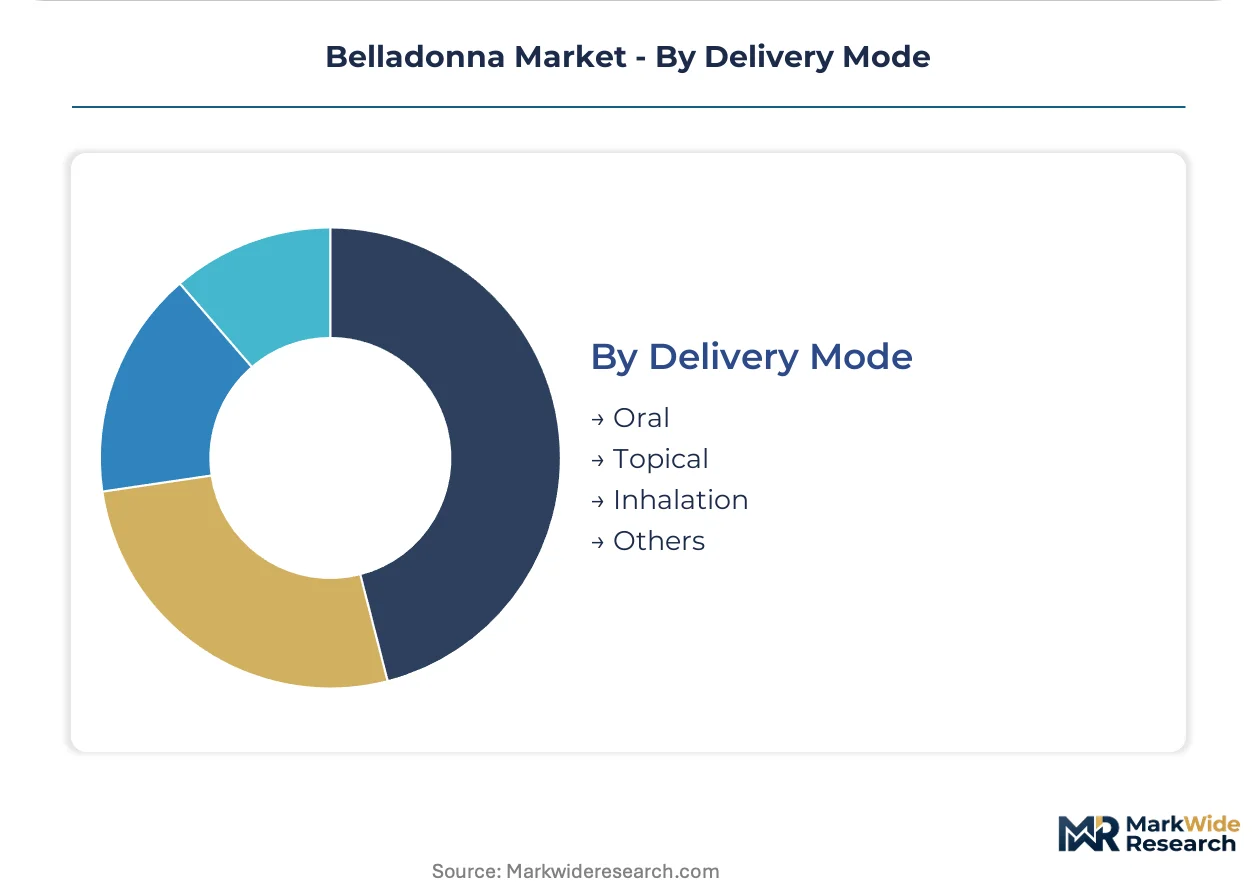
Oral delivery dominates current volumes, with topical applications showing the most rapid uptake through rehabilitation clinic network expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting belladonna alkaloid extraction capacity toward jurisdictions with streamlined herbal licensing frameworks, as EMA and FDA compliance costs compress margins for legacy European processors.
Germany
Homeopathic tincture demand from Bavarian and Baden-Württemberg pharmacy networks anchors European volume. The EU Traditional Herbal Medicinal Products Directive locks in formal registration pathways for mother tinctures. Stuttgart-based extractors maintain GMP-certified facilities serving hospital formulary committees across the Rhine-Ruhr metropolitan corridor.
Switzerland
Swissmedic's streamlined botanical drug guidelines attract premium cosmetic manufacturers seeking Demeter-certified alkaloid inputs. The country's pharmaceutical regulator enforces stringent traceability mandates that biodynamic suppliers leverage for price positioning. Zurich and Basel clusters concentrate supercritical CO2 extraction infrastructure for high-purity API manufacturing.
Poland
Licensed cultivators in the Lesser Poland and Silesian regions supply raw Atropa belladonna to German and Austrian processors. The country's national pharmaceutical regulator administers wild-harvest permits under EU habitat protection frameworks. Krakow-area extraction cooperatives amortize REACH compliance costs through shared-service processing facilities.
China
Domestic tropane alkaloid production for traditional medicine applications sustains cultivation in Shaanxi and Shanxi provinces. NMPA botanical drug guidance creates parallel registration tracks for export-oriented extractors. Xi'an-based biological technology clusters supply reference standards to European analytical laboratories under ECHA import certification protocols.
United States
FDA botanical drug guidance limits therapeutic claim positioning for belladonna capsules in direct-to-consumer channels. The agency's evolving marker compound thresholds elevate analytical validation costs for nutraceutical importers. Standard Homeopathic Company maintains vertically integrated tincture operations serving practitioner networks across the Midwest and Northeast corridors.
Belladonna Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue veterinary phytomedicine and direct-to-practitioner e-commerce channels to bypass consolidated pharmacy procurement. The supplier base compresses around certified extractors with documented pharmacopeial compliance, while smaller raw material traders absorb compliance costs or exit. Three archetypes dominate: vertically integrated homeopathic specialists, API-grade pharmaceutical extractors, and biodynamic-certified cosmetic ingredient suppliers. Competitive moves concentrate on M&A consolidation of licensed cultivation assets and technology licensing for supercritical CO2 infrastructure.
Among German homeopathic specialists, Dr. Willmar Schwabe GmbH & Co. KG and Biologische Heilmittel Heel GmbH exemplify the vertically integrated archetype with captive tincture processing capabilities. Standard Homeopathic Company represents the North American practitioner-channel positioning. French homeopathic pharmaceutical manufacturer Laboratoires Boiron SA occupies a position bridging European pharmacy network access with international distribution scale. Chinese biological technology suppliers Xian Aladdin Biological Technology and Shanxi Zhendong Anxin Biopharmaceutical Co.,Ltd. exemplify the raw material and reference standard supply tier serving export markets.
| Leading Market Players |
|---|
| Standard Homeopathic Company |
| Dr. Willmar Schwabe GmbH & Co. KG |
| Weleda |
| Xian Aladdin Biological Technology |
| Shanxi Zhendong Anxin Biopharmaceutical Co.,Ltd. |
| CSPC Ouyi Pharmaceutical Co.,Ltd. |
| Biologische Heilmittel Heel GmbH |
| Riotto Botanical |
| Laboratoires Boiron SA |
| Others |
Value Network & Pricing Analysis
Family-owned cultivation cooperatives in Poland and Hungary anchor raw material ownership patterns, concentrating supply discipline among licensed harvesters who negotiate long-term offtake contracts with German and Swiss extractors. This ownership structure feeds pricing power upstream while compressing margins for unintegrated tincture processors competing on spot markets.
Pricing Analysis
Distributor margin layers separate API-grade extract premiums from direct-to-consumer capsule pricing, with pharmacy cooperative markups in Germany and Austria widening spreads for Demeter-certified mother tinctures. Three-tier pricing structure across pharmacopeial-grade, certified-organic, and conventional extract levels reflects EMA compliance investment and biodynamic certification costs. Cost compression in conventional leaf powder runs through alkaloid content volatility and batch-rejection rates at quality control. Retailers and direct-to-consumer nutraceutical channels exhibit highest price sensitivity, while hospital formulary committees absorb premiums for documented bioequivalence data.
Supply Chain Analysis
Phytochemical analytical specialists in Krakow and Stuttgart extraction clusters command premium compensation, constraining workforce scalability for smaller tincture producers. Geographic supply concentration centers on Poland, Hungary, and China's Shaanxi province for raw Atropa belladonna, with German and Swiss facilities handling pharmaceutical-grade purification. Raw material dependencies rest on licensed cultivator networks, ECHA-authorized processing equipment, and pharmacopeial reference standards. Single-source vulnerability persists in supercritical CO2 extraction system supply, where German and Swiss equipment manufacturers dominate installed base. Distribution runs through pharmacy cooperatives, practitioner-direct portals, and hospital procurement frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in belladonna alkaloids hinges on alkaloid standardization premiums and veterinary phytomedicine tier development, with compliance cost absorption separating integrated extractors from spot-market traders.
For Market Incumbents: Anchor GMP-certified capacity in Baden-Württemberg and Bavaria through M&A consolidation of licensed Polish cultivation assets. Deepen captive tincture processing to defend against synthetic tropane substitution in pure API applications. Prioritize ISM-compliant documentation investments to lock in German university hospital formulary positioning. For New Entrants and Emerging Players: Direct-to-practitioner e-commerce portals offer lowest barrier entry for North American veterinary phytomedicine formulations targeting equine colic and bovine mastitis. Veterinary channels remain underpenetrated relative to human therapeutic saturation. Pursue CSRD-aligned traceability certification to differentiate in EU corporate sustainability reporting mandates. For Investors and Strategic Acquirers: Valuations sit cheapest among small-scale extraction cooperatives in Portugal and Spain amortizing REACH compliance through shared-service models. Long-term viability favors certified extractors with documented wild-harvest-to-shelf systems serving pharmaceutical and biodynamic cosmetic tiers. Monitor ECHA alkaloid scheduling debates as inflection signal for product registration pathway disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Extraction Scale-Up | Eliminates residual solvent contamination risks for FDA botanical drug submissions from German facilities. |
| Licensed Cultivation Asset Acquisition | Secures protected-species raw material access under EU habitat conservation frameworks in Poland. |
| CSRD Supply Chain Disclosure Implementation | Creates competitive differentiation for extractors with documented traceability systems serving EU corporate buyers. |
| Veterinary Phytomedicine Formulation Development | Captures first-mover positioning in underdeveloped North American equine and bovine therapeutic channels. |
| Direct-to-Practitioner E-Commerce Launch | Bypasses wholesale-pharmacy intermediaries to capture margin from naturopathic and anthroposophic networks. |
Research Methodology
Bottom-up pharmaceutical manufacturer procurement tracking reconciled against top-down cultivation license and extraction capacity monitoring forms the analytical core of this study. Primary interviews with GMP-certified extraction facility managers, pharmacopeial quality control directors, hospital formulary committee members, and licensed Atropa belladonna cultivators in Poland and Hungary combined with secondary validation against EMA herbal monographs, FDA botanical drug guidance filings, EU Traditional Herbal Medicinal Products Directive registration databases, and REACH authorization records.
Historical alkaloid procurement volume trendlines by therapeutic application and product form established baseline growth patterns across the projection horizon. Segmentation modeling incorporated product type, end-user concentration, application regulatory pathway, and delivery mode dimensions. CAGRs derived from weighted regression of disclosed procurement contract values and cultivation license expansion rates, with alkaloid content standardization thresholds and synthetic substitution elasticity as key forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA alkaloid scheduling decisions and FDA botanical drug guidance revisions. Projections reflect assumptions on regulatory pathway stability, licensed cultivation permit renewal rates, and synthetic tropane cost curves. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Extracts
Essential Oil Isolates Market
Extracts
Cassia Seed Extract Market
Extracts
Asia-Pacific Spirulina Extract Market
Extracts
Medicinal Plant Extracts Market
Extracts
Global Azadirachtin Market
Extracts
Lotus Extract Market
Extracts
Laurel Oil Market
Extracts
Irish Moss Extract Market
Extracts
Cochineal Extract Market
Extracts
Antioxidants Reagent Market
Extracts
Global Magnolia Bark Extract Market
Extracts
Copaiba Essential Oil Market
Extracts
Cassia Extract Market
Extracts
Gelatin Hydrolysates Market
Extracts
Bidens Pilosa Extract Market
Extracts
Chamomile Oil Market