
 Extracts and Distillates Market | 2026-2036
Extracts and Distillates Market Size, Share, and Industry Trends Forecast 2026-2036
Extracts and Distillates Market Foresight
India's spice-processing corridor is reshaping supply dynamics for natural extracts. Givaudan leverages captive sourcing partnerships in Kerala to secure cardamom and black pepper oleoresins. Synthite Industries Ltd anchors domestic capacity with integrated extraction through solvent and supercritical CO2 systems. dsm-firmenich competes on R&D intensity, deploying biotechnology platforms to replicate rare botanical actives.
Extracts and distillates comprise concentrated bioactive fractions recovered from plant, microbial, or fermentation sources through thermal, mechanical, or chemical separation processes, typically standardized to defined marker compound percentages for batch consistency. These inputs serve as functional precursors in formulated consumer products where sensory, therapeutic, or preservative properties must meet precise specification windows. Essential oils and flavor extracts command the dominant value share, though CO2 extraction is gaining traction as a premium method that eliminates thermal degradation and solvent residues. Herbal extracts represent the fastest-growing product class, propelled by nutraceutical brands seeking substantiated health claims for adaptogenic and nootropic formulations.
Regulators including the FDA, EFSA, and India's FSSAI enforce divergent purity thresholds and labeling requirements that fragment compliance costs across export destinations. REACH registration obligations in Europe and FSSAI license mandates in India both restrict market entry for uncertified producers while rewarding vertically integrated operators with analytical capabilities. Stakeholders must monitor evolving maximum residue limits for pesticides and heavy metals, as these thresholds increasingly determine which suppliers retain access to premium pharmaceutical and infant-nutrition channels.
Market Dynamics
Supercritical CO2 extraction is collapsing batch-to-batch variability in premium essential oil production, compressing quality assurance timelines from weeks to days and forcing solvent-based processors to reposition toward commodity grades.
Growth Catalysts
- Clean-label beverage mandates:Major soft drink and spirits formulators now require solvent-free extraction certificates for botanical inclusions, pulling capacity toward CO2 and cold-press systems.
- India's FSSAI export licensing:Streamlined registration for spice-derived oleoresins has consolidated contract manufacturing in Kerala and Tamil Nadu processing clusters.
- Adaptogenic nutraceutical pipelines:Functional food brands are locking multi-year offtake agreements for standardized ashwagandha and turmeric extracts with defined withanolide and curcuminoid percentages.
Market Restraints
- Raw material volatility:Cardamom and black pepper harvest fluctuations in Kerala and Karnataka transmit directly into oleoresin input costs, squeezing margin predictability for flavor houses.
- Residual solvent scrutiny:REACH registration thresholds for aromatic distillates now require sub-ppm detection capabilities that smaller European distillers cannot fund.
- Synthetic biology substitution:Fermentation-derived vanillin and citrus terpenes are capturing share in cost-sensitive beverage applications where natural certification carries no price premium.
Strategic Opportunities
- Underpenetrated pharmaceutical channel:USP-grade herbal extract demand for clinical trial materials outstrips GMP-certified capacity in North American and European supply bases.
- Biotechnology-platform convergence:Cell culture and precision fermentation systems are enabling biosynthesis of rare botanical actives previously constrained by cultivation cycles and climate risk.
- Direct-to-manufacturer digital procurement:B2B marketplaces for certified extracts are disintermediating traditional broker networks, compressing price discovery from months to real-time auction mechanisms.
Industry Challenges
- Analytical chemist scarcity:HPLC and GC-MS method development for marker compound validation requires specialized talent that extraction facilities in secondary Indian and Chinese cities cannot attract.
- Multi-jurisdiction certification lag:Simultaneous pursuit of USP, EP, and JP monograph compliance extends product launch timelines by 18-24 months for novel botanical extracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Extracts and Distillates Market |
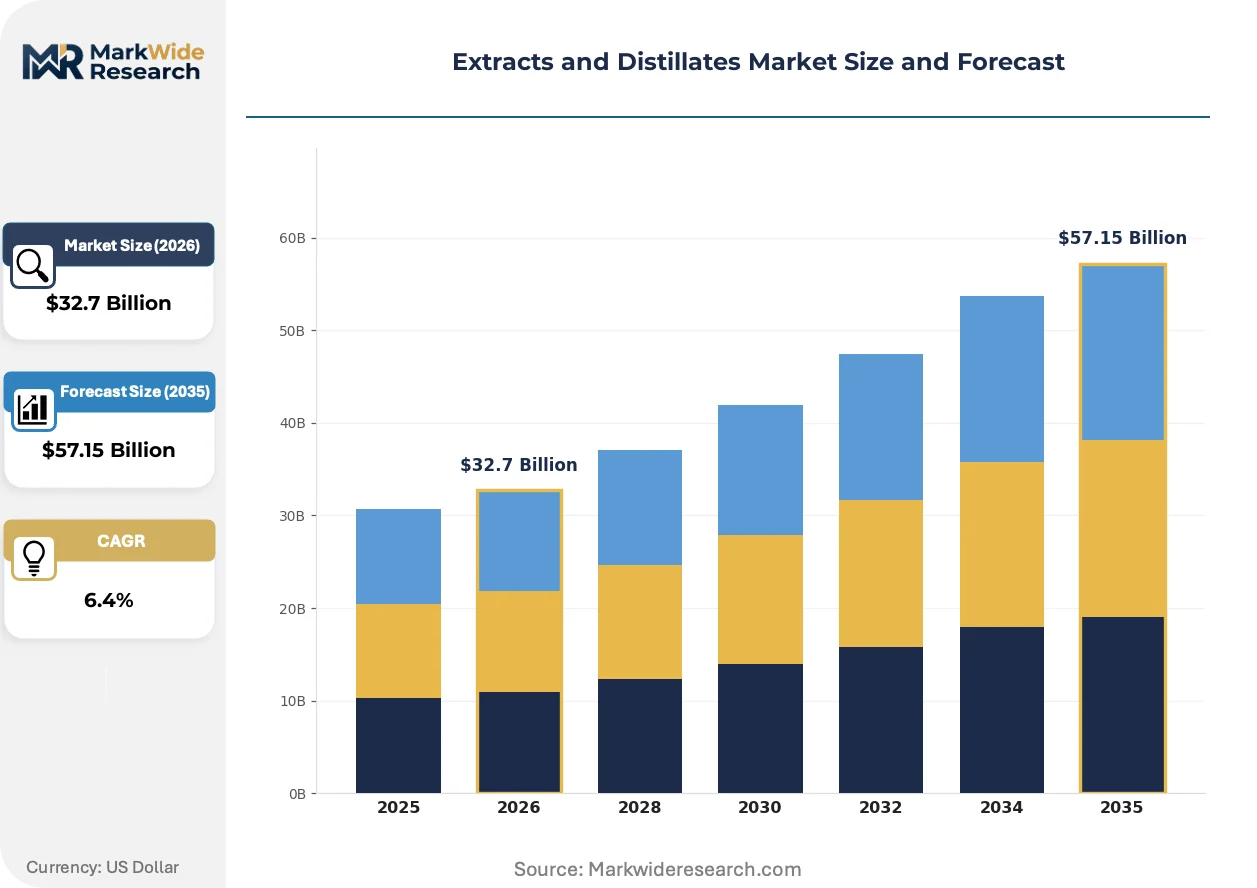
| Market Size in 2026 | $32.7 Billion |
| Market Size in 2035 | $57.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Essential Oils, Flavor Extracts, Herbal Extracts, Aromatic Distillates Application: Food & Beverage, Cosmetics, Pharmaceuticals, Nutraceuticals Extraction Method: Steam Distillation, Cold Pressing, Solvent Extraction, CO2 Extraction End User: Food Manufacturers, Cosmetic Companies, Pharmaceutical Firms, Herbal Product Retailers |
| Companies Covered | International Flavors & Fragrances Inc., Givaudan, Symrise AG, Sensient Technologies Corporation, Synthite Industries Ltd, dsm-firmenich, ADM, Döhler, Kalsec Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Extracts and Distillates Market Shifts & Advancements
Extraction technology trajectories are compressing the cost-performance gap between artisanal and industrial production, while regulatory disclosure requirements and procurement digitization are rewriting supplier qualification protocols across end-use verticals.
Supercritical CO2 systems with integrated fractionation modules are collapsing the distinction between essential oil and oleoresin product categories, enabling single-pass recovery of both volatile terpenes and non-volatile resinoids. Premium cosmetics and therapeutic-grade aromatherapy brands are specifying these dual-output systems for new capacity investments. The technology is collapsing the traditional separation between distillation and solvent extraction facility footprints, permitting smaller-batch, higher-SKU operations without capital duplication.
REACH Article 33 disclosure obligations for residual solvents in aromatic distillates now mandate supply chain transparency down to the extraction facility level, not merely the importing distributor. European flavor houses are responding by consolidating supplier bases to vertically integrated operators with captive analytical laboratories. Fragrance compounds destined for personal care applications face the steepest compliance cost escalation, as dermatological safety dossiers now require solvent provenance documentation.
Long-term offtake contracting is displacing spot market purchasing for high-value botanical extracts, with nutraceutical and pharmaceutical formulators locking three-to-five-year supply agreements to secure batch consistency and price predictability. This procurement compression is concentrating purchasing power among the ten largest global flavor and fragrance houses, marginalizing mid-tier brokers who previously intermediated fragmented spice processor output. The shift is most visible in North American and European adaptogenic ingredient sourcing, where ashwagandha and rhodiola extract buyers now contract directly with Indian and Chinese integrated processors.
Extracts and Distillates Market Segmentation
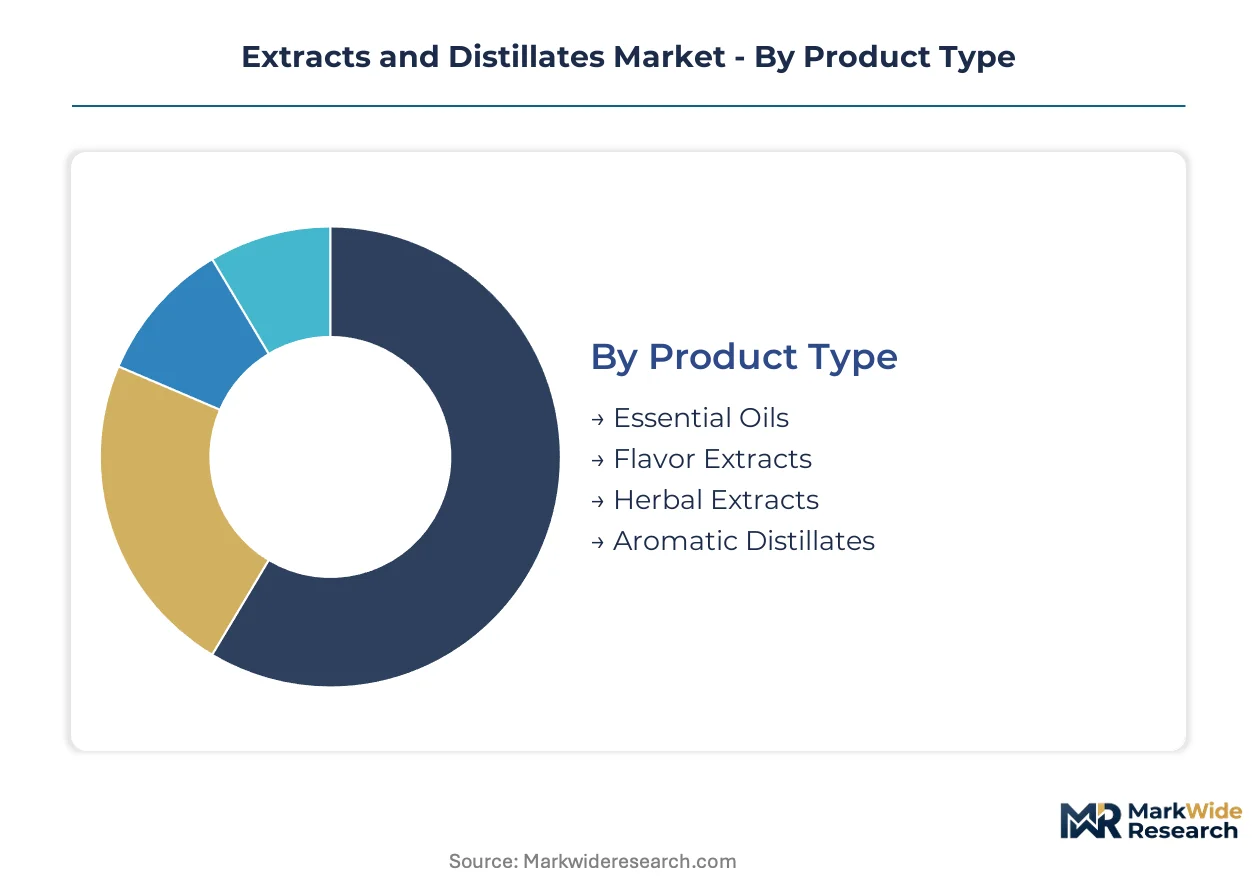
Segmentation in extracts and distillates reveals divergent margin structures and compliance burdens. Product categories split between mature commodity grades and emerging premium certifications, while extraction technologies stratify capital requirements and regulatory exposure.
Product Type:
Mature commodity segments dominate volume throughput, while emerging premium categories command disproportionate value capture through certification premiums.
- Essential Oils:Concentrated volatile terpene fractions recovered through steam distillation or mechanical expression, standardized for aromatic intensity and chemical profile. Demand concentrates in cosmetics and therapeutic applications across France and Switzerland, where ISO 9235 natural certification commands price premiums over conventional grades.
- Herbal Extracts:Standardized bioactive preparations from medicinal plants, defined by marker compound percentages such as withanolides or curcuminoids. Nutraceutical formulators in India and the United States are locking multi-year supply agreements for adaptogenic ingredients, driving fastest share expansion in this category.
- Flavor Extracts:Solvent-derived or cold-pressed concentrates for beverage and confectionery applications.
- Aromatic Distillates:Water-soluble fractions co-produced with essential oils, used in fine fragrance and personal care.
Essential oils handle the majority of throughput; herbal extracts are the fastest mover on share.
Application:
Application segments stratify by regulatory intensity, with pharmaceutical-grade requirements imposing steepest analytical and documentation burdens.
- Food & Beverage:Clean-label mandates from major soft drink and spirits formulators now require solvent-free extraction certificates, pulling capacity toward CO2 and cold-press systems in Kerala and Tamil Nadu processing clusters.
- Pharmaceuticals:USP-grade and EP-compliant extracts for clinical trial materials and finished dosage forms, requiring GMP-certified manufacturing and validated analytical methods. North American and European demand outstrips certified capacity, creating supply constraints for novel botanical actives.
- Cosmetics:Fragrance and active ingredients for skincare and personal care, subject to REACH Article 33 disclosure obligations.
- Nutraceuticals:Standardized supplements and functional foods with substantiated health claims.
Food and beverage absorbs the largest volume; pharmaceuticals is expanding most quickly on value per kilogram.
Extraction Method:
Extraction technologies span a capital intensity spectrum from artisanal to industrial, with supercritical systems collapsing batch-to-batch variability at premium cost positions.
- CO2 Extraction:Supercritical fluid systems operating at pressures above 73 bar and 31°C, eliminating thermal degradation and residual solvents while enabling fractionation of volatile and non-volatile components. Premium cosmetics and therapeutic aromatherapy brands in Germany and Switzerland specify these dual-output systems for new capacity investments.
- Steam Distillation:Traditional thermal separation for essential oil recovery, dominant in established production bases.
- Solvent Extraction:Hexane or ethanol-based processes for oleoresin production, facing REACH scrutiny on residual thresholds.
- Cold Pressing:Mechanical expression for citrus and seed oils, preserving heat-sensitive actives.
Steam distillation retains the installed base; CO2 extraction is gaining share fastest in premium channels.
End User:
End-user categories diverge in procurement sophistication, with pharmaceutical and multinational food manufacturers consolidating supplier bases while herbal retailers fragment across spot purchasing.
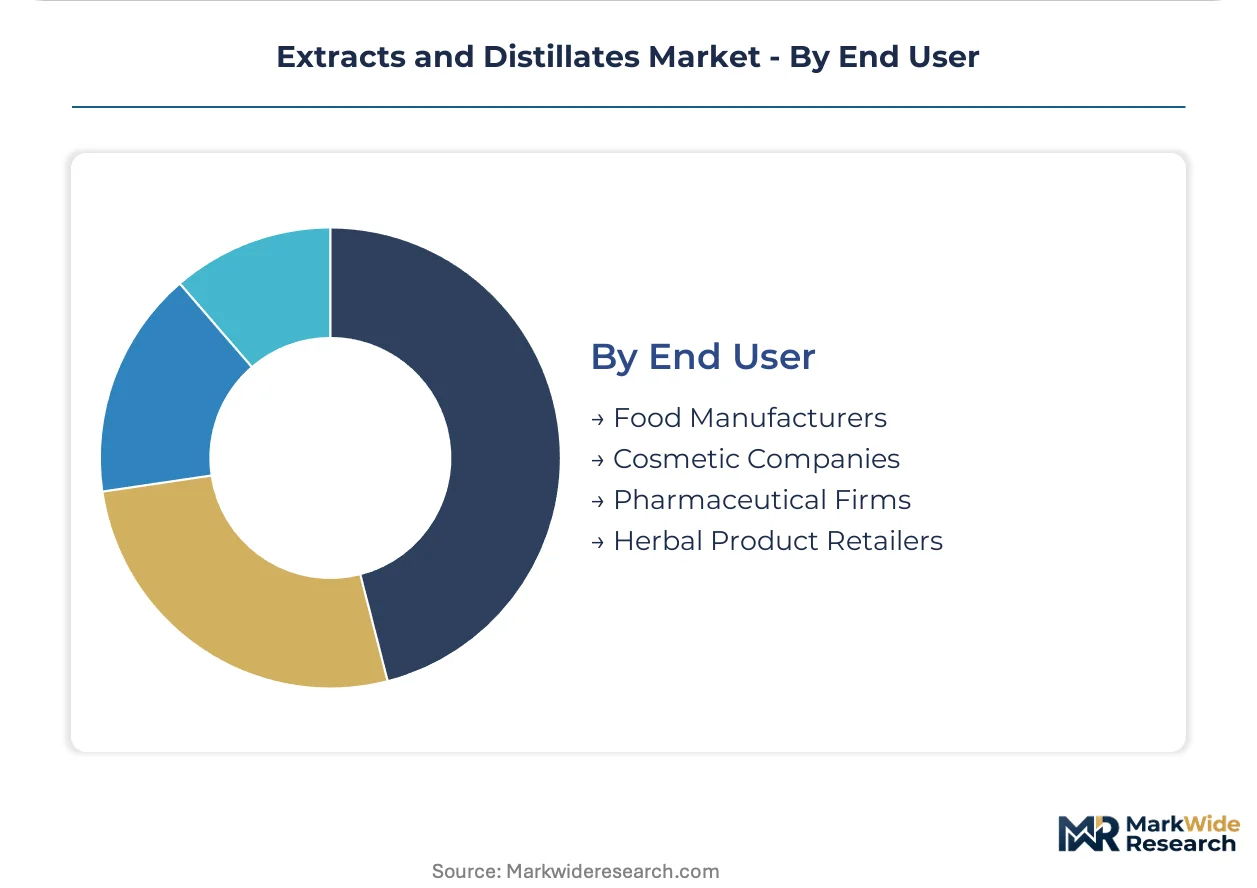
- Food Manufacturers:Multinational beverage and confectionery houses requiring batch consistency, food safety certification, and solvent provenance documentation. Long-term offtake contracting is displacing spot market purchasing, concentrating purchasing power among the ten largest global flavor houses.
- Pharmaceutical Firms:Clinical trial material suppliers and finished dosage formulators demanding USP, EP, and JP monograph compliance. Simultaneous pursuit of multi-jurisdiction certification extends product launch timelines by 18-24 months for novel botanical extracts.
- Cosmetic Companies:Fine fragrance and skincare formulators with dermatological safety dossier requirements.
- Herbal Product Retailers:Direct-to-consumer supplement brands and traditional medicine practitioners.
Food manufacturers represent the largest procurement volume; pharmaceutical firms are climbing the fastest on specification intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Extraction capacity clusters in South India and Western Europe, with regulatory divergence in purity standards fragmenting compliance costs across export destinations. Processing facilities concentrate near raw material sources and pharmaceutical demand centers, creating distinct regional specialization patterns.
United States
Pharmaceutical-grade herbal extract demand outstrips GMP-certified domestic capacity, forcing clinical trial material suppliers to source from Indian and European processors. FDA enforcement of USP monograph compliance for botanical drug substances extends qualification timelines for novel actives. New Jersey and North Carolina host the largest concentration of finished dosage formulators seeking validated extract inputs.
India
Spice-derived oleoresin exports dominate global flavor house procurement, with Kerala and Tamil Nadu processing clusters capturing contract manufacturing from multinational brands. FSSAI streamlined export licensing for standardized extracts, consolidating capacity among integrated operators with captive analytical laboratories. Kochi anchors the cardamom and black pepper oleoresin trade, while Bengaluru supports biotechnology platforms replicating rare botanical actives.
Germany
REACH Article 33 disclosure obligations for residual solvents in aromatic distillates mandate supply chain transparency down to the extraction facility level. ECHA registration thresholds for sub-ppm solvent detection favor vertically integrated operators with in-house GC-MS capabilities. Hamburg and Frankfurt concentration of fine fragrance formulators drives specification intensity for dermatological safety dossiers.
Switzerland
Therapeutic-grade aromatherapy and premium cosmetic brands specify supercritical CO2 systems with integrated fractionation modules for new capacity investments. Swissmedic pharmaceutical extract regulations impose batch consistency requirements that collapse supplier bases to certified processors. Geneva and Basel host flavor and fragrance houses locking multi-year offtake agreements for standardized botanical inputs.
China
Herbal extract exports face escalating maximum residue limit scrutiny for pesticides and heavy metals in pharmaceutical and infant-nutrition channels. NMPA alignment with international pharmacopeial standards is compressing the supplier base toward GMP-certified facilities. Shandong and Sichuan provinces concentrate traditional medicine processing capacity upgrading to meet export monograph compliance.
Extracts and Distillates Market Competitive Landscape
Vertically integrated specialists and diversified ingredient conglomerates split the market between premium certification tiers and commodity volume plays. The supplier base concentrates around ten global flavor and fragrance houses that have displaced mid-tier brokers through direct contracting with processing clusters. Three archetypes dominate: captive sourcing operators with plantation-to-extraction control, biotechnology platforms synthesizing rare actives, and regional processors competing on FSSAI and REACH compliance bundling. Competitive moves center on multi-year offtake contracting for adaptogenic extracts and supercritical CO2 capacity expansion for solvent-free certification.
Among diversified Swiss and Dutch ingredient conglomerates, Givaudan, dsm-firmenich, and Symrise AG exemplify the integrated archetype combining captive sourcing partnerships with biotechnology R&D platforms. These operators occupy positions where REACH compliance bundling and pharmaceutical-grade certification create defensive moats against regional price competition. Synthite Industries Ltd represents the India-based integrated processor archetype, anchoring domestic capacity through solvent and supercritical systems while serving multinational flavor house contract demand from Kerala extraction facilities.
| Leading Market Players |
|---|
| International Flavors & Fragrances Inc. |
| Givaudan |
| Symrise AG |
| Sensient Technologies Corporation |
| Synthite Industries Ltd |
| dsm-firmenich |
| ADM |
| Döhler |
| Kalsec Inc. |
| Others |
Supply & Pricing Matrix
Overcapacity in European solvent-based extraction facilities is forcing distressed asset sales and contract renegotiations, compressing pricing power for commodity-grade oleoresins while tightening premiums for CO2-certified outputs. This utilization asymmetry rewards integrated Indian processors with captive Kerala spice sourcing and punishes standalone European distillers facing REACH compliance cost escalation.
Pricing Analysis
REACH Article 33 disclosure obligations dictate the pricing tier structure across aromatic distillate categories, separating solvent-traceable premium grades from commodity lots. Three-tier pricing structure across premium, standard, and economy levels reflects certification intensity: USP-grade extracts with full solvent provenance command the highest tier, REACH-compliant conventional grades occupy the middle, and uncertified bulk oleoresins face price erosion. Cost compression in standard-tier solvent extracts is intensifying because smaller European distillers cannot fund sub-ppm detection capabilities. Contract manufacturers in Kerala demonstrate the least price sensitivity due to long-term offtake agreements with multinational flavor houses, while spot-market spice processors in Karnataka show acute sensitivity to cardamom harvest volatility.
Supply Chain Analysis
Extended payment terms from multinational flavor houses are straining working capital for mid-tier Indian processors, accelerating consolidation toward integrated operators with supply-chain finance facilities. Raw material sourcing draws from Kerala cardamom plantations, Karnataka black pepper estates, and Tamil Nadu turmeric cultivation belts. Key inputs include hexane and ethanol solvents facing REACH residual scrutiny, supercritical CO2 for premium certification, and standardized biomass with defined marker compound percentages. Single-source vulnerability concentrates in Kerala's monsoon-dependent spice harvests. Distribution runs through direct long-term contracting with the ten largest global flavor and fragrance houses, disintermediating traditional broker networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermentation-derived substitutes for vanillin and citrus terpenes are capturing share in cost-sensitive beverage applications, forcing natural extract incumbents to defend premium positioning through certification differentiation and biotechnology platform investment.
For Market Incumbents: Build regulatory compliance moats by securing simultaneous USP, EP, and JP monograph certification for novel botanical actives, collapsing competitor launch timelines. Anchor capacity expansion in Kerala and Tamil Nadu processing clusters to exploit FSSAI streamlined export licensing and captive spice sourcing. Defend against synthetic biology substitution by locking multi-year offtake agreements with adaptogenic nutraceutical brands seeking substantiated health claims. For New Entrants and Emerging Players: North American pharmaceutical-grade herbal extract demand outstrips GMP-certified capacity, creating white-space opportunity for qualified entrants. Target USP-certified manufacturing for clinical trial materials where supply constraints persist. Pursue biotechnology-platform convergence for biosynthesis of rare botanical actives previously constrained by cultivation cycles, positioning as specialty supplier to Swiss and German therapeutic-grade aromatherapy brands. For Investors and Strategic Acquirers: Long-term, this sits as a certification-arbitrage play because regulatory divergence in purity thresholds fragments compliance costs and rewards vertically integrated operators with analytical capabilities. Acquisition targets include Indian integrated processors with captive Kerala extraction facilities and in-house GC-MS laboratories. Watch biotechnology-platform announcements from flavor houses as signal of synthetic biology substitution acceleration that would compress natural extract premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Capacity Expansion | Eliminates thermal degradation and solvent residues for clean-label beverage certificates. |
| Backward Integration into Kerala Spice Plantations | Secures cardamom and black pepper oleoresin supply against harvest volatility. |
| Multi-Jurisdiction Certification Investment | Captures USP, EP, and JP compliance premiums in pharmaceutical and infant-nutrition channels. |
| Biotechnology Platform Development | Enables biosynthesis of rare botanical actives previously constrained by climate risk. |
| Direct-to-Manufacturer Digital Procurement | Disintermediates broker networks through real-time auction mechanisms for certified extracts. |
Research Methodology
Desk research of customs trade records, FSSAI export licensing databases, and ECHA REACH registration filings preceded structured interviews with extraction facility technical directors, flavor house procurement managers, nutraceutical formulators, and analytical laboratory certification leads. Primary fieldwork across Kerala, Tamil Nadu, and Swiss processing clusters validated capacity utilization rates and compliance cost structures. Secondary triangulation drew from SEC filings of listed ingredient conglomerates, EU customs data on aromatic distillate imports, and Indian Spice Board export statistics. Bottom-up volume modeling across extraction technology types and top-down value reconciliation against flavor and fragrance house revenue disclosures ensured cross-validation.
Assumptions held fixed include current REACH residual solvent thresholds, FSSAI licensing procedures, and supercritical CO2 equipment cost structures; variables tested included biotechnology substitution rates, spice harvest volatility scenarios, and pharmaceutical certification adoption curves. The analytical framework modeled product type, extraction method, application segment, and end-user procurement sophistication across the projection horizon. CAGRs derived from segment-level volume trajectories and value-per-kilogram trends, with specific inputs including Kerala oleoresin export volumes, Swiss CO2 system installation rates, and USP-certified facility capacity expansion announcements.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Chinese GMP-certified processors or breakthrough fermentation economics from synthetic biology platforms would shift outcomes. Macroeconomic deviation in spice-producing regions, regulatory threshold tightening for pesticide residues, or technological disruption in cell culture biosynthesis would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Extracts
White Willow Bark Extract Market
Extracts
Marigold Essential Oil Market
Extracts
Myrrh Powder Market
Extracts
Helichrysum Oil Market
Extracts
Cassia Extract Market
Extracts
Amla Extract Market
Extracts
Potassium Hydrogen Tartrate Market
Extracts
Herba Houttuyniae Extract Market
Extracts
Global Herbal Extract Market
Extracts
Global Azadirachtin Market
Extracts
Gelatin Hydrolysates Market
Extracts
Cochineal Extract Market
Extracts
Cosmetic Grade Portulaca Oleracea Extract Market
Extracts
Basil Extracts Market
Extracts
Citrus Powder Market
Extracts
Pearl Extract Market