
 Asia-Pacific Mineral Turpentine Market | 2026-2036
Asia-Pacific Mineral Turpentine Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Mineral Turpentine Market Insights
The Asia-Pacific mineral turpentine market is recalibrating around a widening split between rectified grades for pharmaceutical and fragrance applications and commodity streams feeding bulk coatings production. ExxonMobil leverages its integrated refinery-solvent network across Singapore and Thailand to control feedstock costs for premium distillation. Idemitsu Kosan anchors Japanese supply through specialized hydrotreating capacity that meets domestic purity thresholds.
Mineral turpentine comprises a refined hydrocarbon solvent blend derived from petroleum distillation, typically featuring aliphatic and aromatic fractions in the C9-C12 range with controlled evaporation rates for industrial coating systems. The substance functions primarily as a thinning and cleanup medium in alkyd-based paints, varnishes, and surface preparation chemicals. Rectified turpentine commands the highest margin pool due to stringent residual sulfur and moisture specifications demanded by fragrance compounders and active pharmaceutical ingredient processors. Synthetic turpentine volumes are accelerating fastest as Indian and Chinese producers expand catalytic reforming capacity to offset natural gum turpentine supply volatility.
China's SAMR enforces GB standards limiting benzene content in industrial solvents, while India's BIS mandates flash point and aromatic thresholds for domestic mineral turpentine grades. Japan's METI chemical management framework requires hazard communication alignment with GHS classification for cross-border solvent shipments. Stakeholders must monitor how Australia's TGA and South Korea's MFDS adopt divergent purity benchmarks for pharmaceutical-grade material.
Market Dynamics
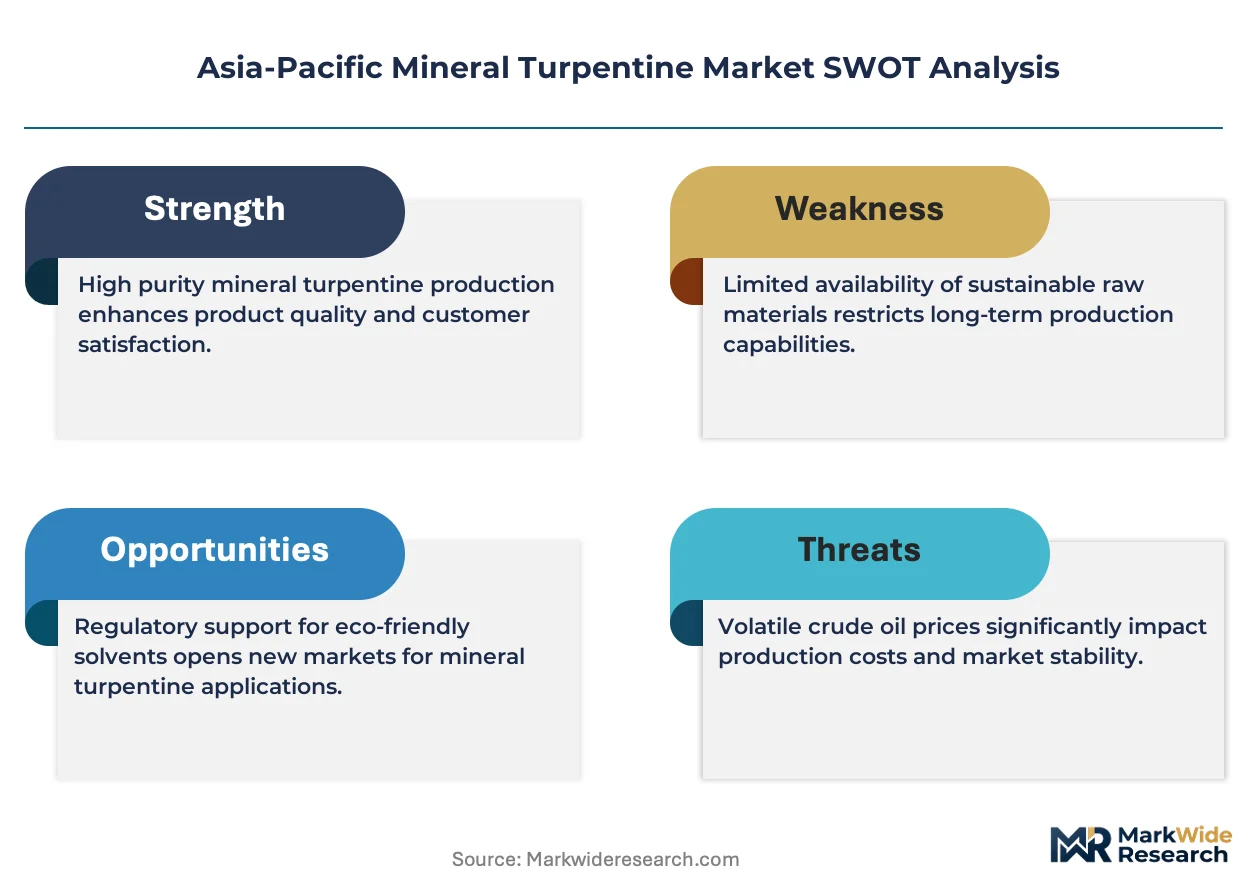
Refinery-solvent integration across Singapore and Thailand is compressing feedstock costs for premium distillation, while India's western industrial corridor from Gujarat to Maharashtra concentrates bulk coatings demand. This structural concentration is forcing mid-scale blenders to specialize or exit.
Growth Catalysts
- GB Standards Enforcement:China's SAMR mandates limiting benzene content in industrial solvents are accelerating hydrotreating investments among domestic refiners seeking compliance-ready output.
- Infrastructure Procurement Surge:Southeast Asian paints and coatings manufacturers are expanding solvent procurement as public infrastructure investment accelerates across Indonesia and Vietnam.
- Pharmaceutical-Grade Specification:India's CDSCO and BIS alignment on residual sulfur thresholds for active pharmaceutical ingredient processing is opening margin pools for rectified turpentine specialists.
Market Restraints
- Feedstock Volatility:Catalytic reforming feedstock costs fluctuate with naphtha crack spreads, compressing margins for Chinese and Indian commodity-grade producers without captive refinery supply.
- Supply Concentration Risk:Singapore and Thailand host the region's dominant integrated refinery-solvent complexes, creating geographic chokepoints for premium distillation capacity.
- Natural Gum Turpentine Substitution:Synthetic turpentine volumes are displacing natural gum-derived material as Indian and Chinese producers expand catalytic reforming to offset pine resin supply instability.
Strategic Opportunities
- Underpenetrated Bangladesh Market:Dhaka-Chittagong industrial corridor lacks domestic solvent distillation capacity, creating import substitution potential for Indian and Thai exporters meeting BIS-adjacent specifications.
- Japan METI Chemical Management Alignment:Hazard communication standardization with GHS classification for cross-border shipments reduces compliance friction for exporters serving Japanese fragrance compounders.
- Digital Procurement Platforms:Bulk coatings manufacturers in Maharashtra and Gujarat are adopting B2B solvent marketplaces, disintermediating traditional distributor networks and compressing working capital cycles.
Industry Challenges
- Hydrotreating Skill Scarcity:Specialized operators capable of maintaining sub-ppm sulfur specifications in pharmaceutical-grade distillation are concentrated among Japanese and South Korean engineering firms.
- Dual Certification Timelines:Simultaneous BIS and CDSCO compliance for Indian pharmaceutical-grade material extends qualification cycles by 8-14 months versus commodity-grade registration.
- Legacy Alkyd Formulation Integration:Coatings manufacturers with established solvent blends face reformulation costs when switching between mineral turpentine sources with divergent aromatic profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Mineral Turpentine Market |
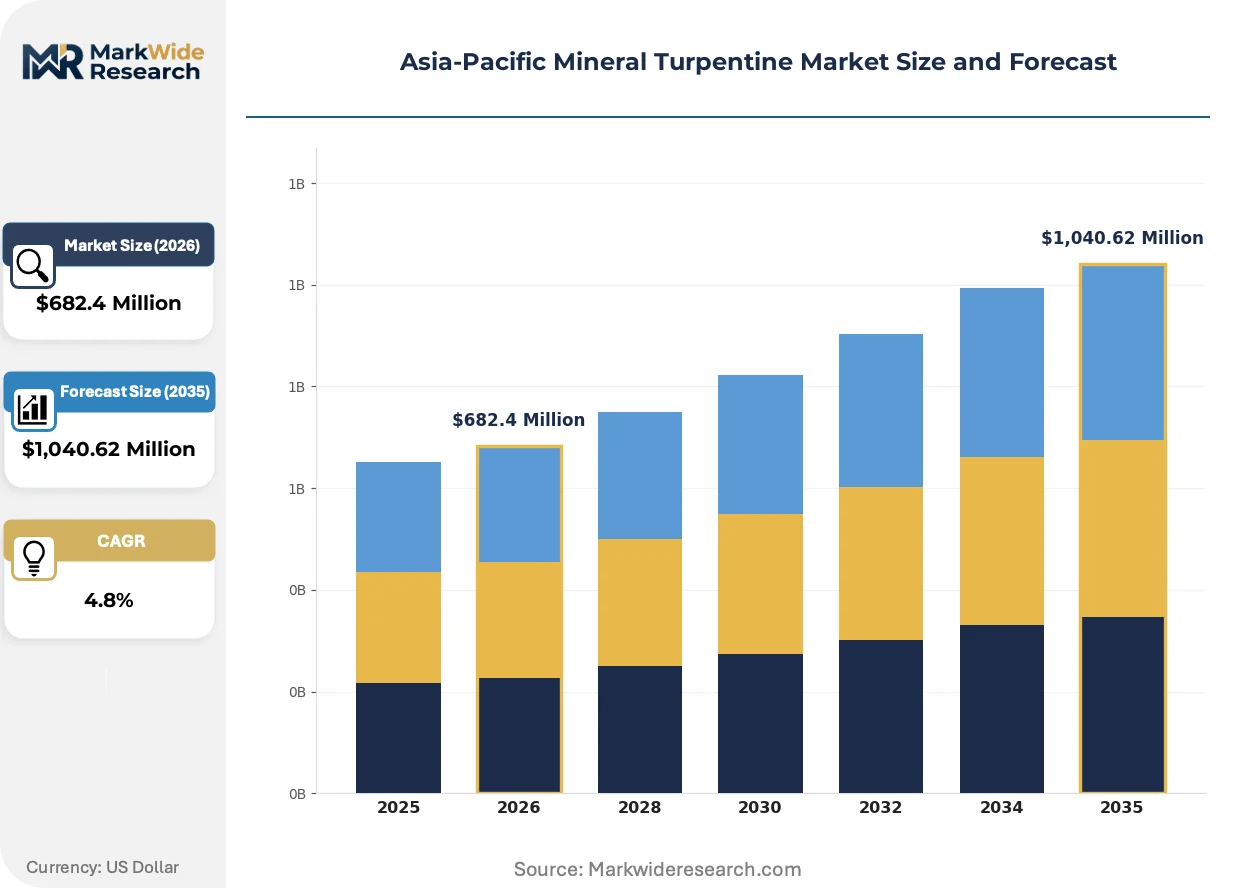
| Market Size in 2026 | $682.4 Million |
| Market Size in 2035 | $1,040.62 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rectified Turpentine, Crude Turpentine, Steam Distilled Turpentine, Synthetic Turpentine End User: Paints & Coatings, Adhesives, Rubber, Pharmaceuticals Application: Solvent, Thinner, Fragrance, Chemical Intermediate Distribution Channel: Online, Retail, Direct Sales, Wholesalers |
| Companies Covered | Chevron Phillips Chemical Company, PetroChina Company Limited, ExxonMobil, Indian Oil Corporation Ltd, SK Innovation Co., Ltd., Royal Dutch Shell, Idemitsu Kosan Co., Ltd., Bharat Petroleum Corporation Limited, Total S.A., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Mineral Turpentine Market Trends and Innovations
Membrane separation and advanced hydrotreating are reshaping purity thresholds across pharmaceutical and fragrance applications, while digital traceability systems penetrate bulk coatings procurement. These shifts are compressing the premium-commodity grade spread.
Membrane separation technology is integrating into rectified turpentine finishing trains, enabling sub-50 ppm moisture specifications without thermal degradation of aromatic fractions. Japanese fragrance compounders and Indian active pharmaceutical ingredient processors are adopting these systems at pilot scale. This capability is integrating premium-grade producers into long-term supply contracts that lock out commodity competitors.
China's GB standards for industrial solvents are tightening benzene content ceilings and flash point minimums, forcing domestic refiners to retire legacy atmospheric distillation units. The policy compresses available supply of economy-grade material while elevating compliant product pricing. Coatings manufacturers in Guangdong and Jiangsu provinces are responding by qualifying Thai and Singaporean imports to bridge supply gaps.
Coatings formulators are consolidating solvent procurement around fewer, larger suppliers capable of certificate-of-analysis consistency and lot-level traceability. This behavior is displacing fragmented distributor networks across India's western industrial corridor. The shift is most visible in Maharashtra, where automotive OEMs now mandate solvent supplier accreditation as a condition of coatings vendor qualification.
Asia-Pacific Mineral Turpentine Market Segmentation
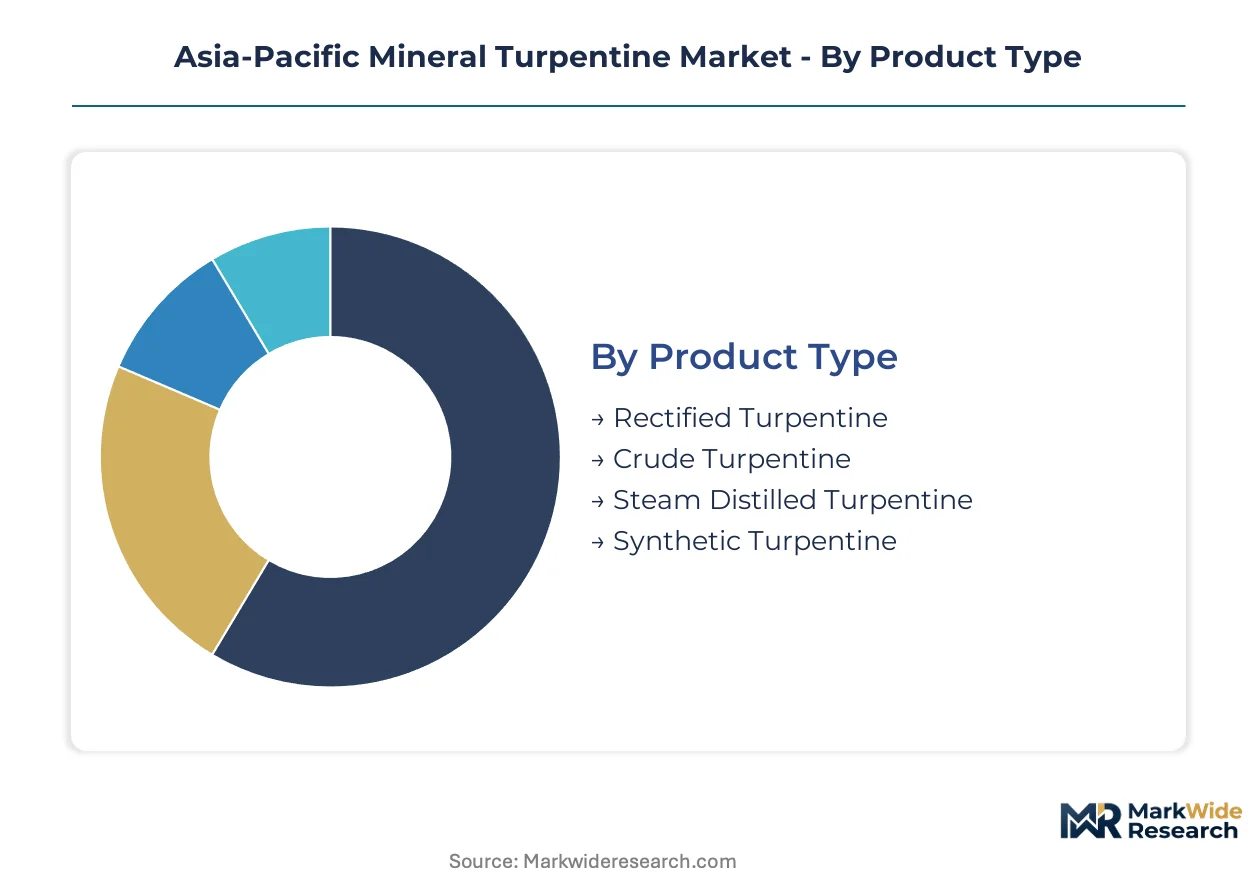
Segmentation in the Asia-Pacific mineral turpentine market reveals how purity specifications, end-use certification requirements, and procurement channel preferences fragment commercial opportunities. Buyers across pharmaceutical, coatings, and fragrance applications operate with incompatible solvent standards that prevent supplier interchangeability.
Product Type:
Purchasers in this category differentiate primarily by residual impurity tolerance and downstream regulatory compliance burden.
- Rectified Turpentine:Ultra-purified through fractional distillation and hydrotreating to achieve sub-50 ppm sulfur and moisture specifications. Indian API processors and Japanese fragrance compounders in Kansai and Kanto prefectures drive demand for material meeting simultaneous BIS, CDSCO, and METI standards.
- Synthetic Turpentine:Manufactured via catalytic reforming of naphtha feedstocks to deliver consistent aromatic profiles independent of pine resin harvest volatility. Chinese and Indian producers along the western industrial corridor from Gujarat to Maharashtra are expanding capacity to offset natural gum supply instability.
- Crude Turpentine:Raw distillate requiring further processing; primarily traded among integrated refiners with captive hydrotreating assets.
- Steam Distilled Turpentine:Intermediate purity grade serving regional coatings manufacturers with moderate aromatic content requirements.
Synthetic turpentine leads volumes today; rectified grades are gaining share fastest.
End User:
Margin capture potential varies sharply across end users based on certification stringency and contract duration.
- Paints & Coatings:Bulk consumers of commodity-grade material for alkyd resin thinning and equipment cleanup. Maharashtra and Gujarat automotive OEMs now mandate solvent supplier accreditation as a condition of coatings vendor qualification, consolidating procurement around fewer, larger distributors.
- Pharmaceuticals:Requires rectified grades with documented lot-level traceability for API synthesis and excipient applications. India's CDSCO alignment with BIS residual sulfur thresholds has extended qualification cycles, locking qualified suppliers into multi-year contracts.
- Adhesives:Consumes medium-purity grades for solvent-based formulation; price-sensitive procurement through wholesale channels dominates.
- Rubber:Niche application for tire manufacturing and rubber processing chemicals; demand concentrates in Thailand and Indonesia.
Coatings manufacturers represent the largest volume pool; pharmaceutical qualification requirements are expanding most quickly.
Application:
Functional role determines evaporation rate specifications and aromatic fraction tolerance.
- Solvent:Dominant application for industrial cleaning and resin dissolution; flash point and benzene content regulated under China's GB standards and India's BIS mandates.
- Thinner:Precision blending for viscosity control in alkyd paints; coatings formulators require certificate-of-analysis consistency across lots.
- Fragrance:Ultra-low sulfur rectified grades for perfume compounders; Japan's METI chemical management framework requires GHS-aligned hazard communication for cross-border shipments.
- Chemical Intermediate:Feedstock for terpene derivative synthesis; purity requirements vary by downstream synthesis pathway.
Solvent applications command the largest share; fragrance-grade specifications are climbing the fastest.
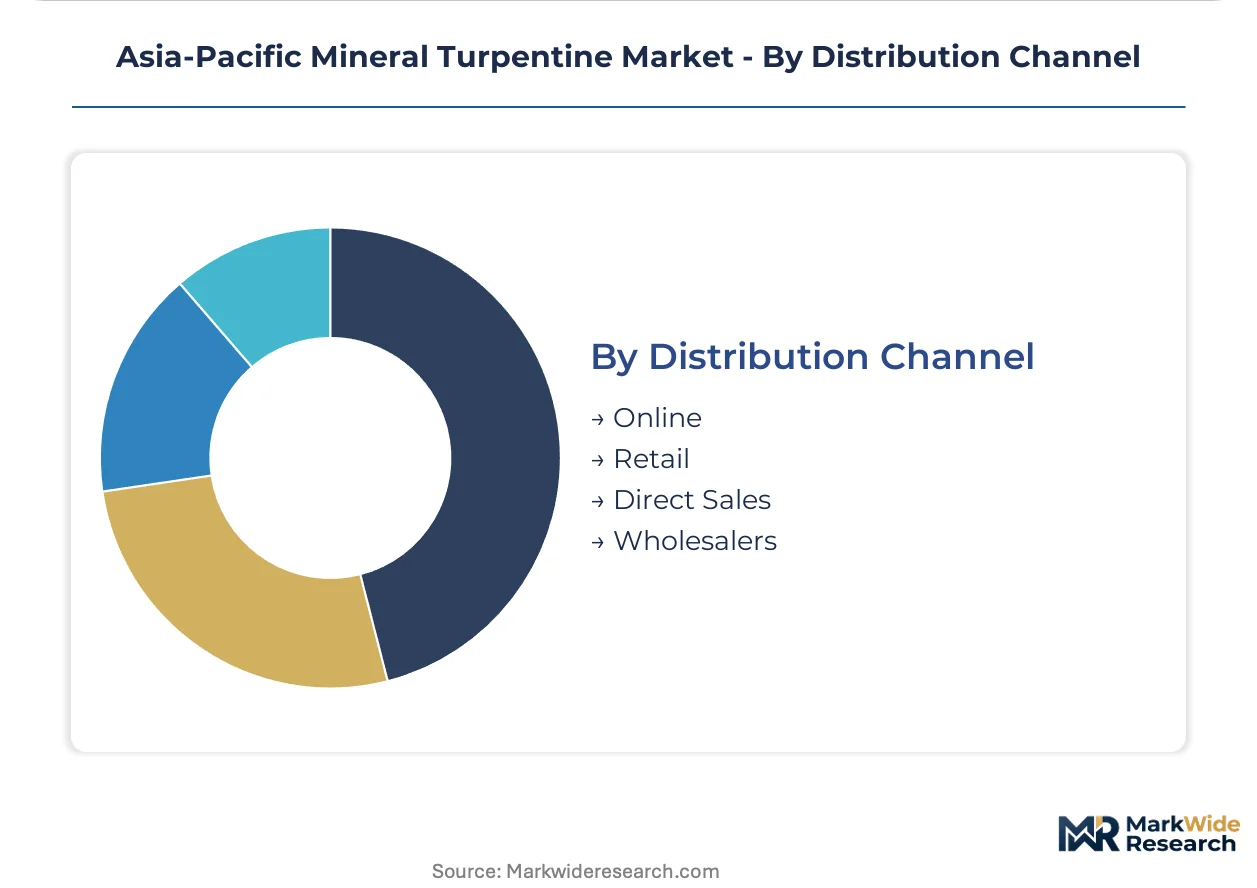
Distribution Channel:
Working capital efficiency and lot traceability requirements are restructuring how buyers access supply.
- Direct Sales:Long-term contracts between integrated refiners and large coatings manufacturers; ExxonMobil's Singapore-Thailand network and Idemitsu Kosan's Japanese hydrotreating capacity anchor this channel with captive supply security.
- Online:B2B procurement platforms penetrating Maharashtra and Gujarat bulk coatings markets, disintermediating traditional distributor networks and compressing payment cycles.
- Wholesalers:Fragmented regional distributors serving mid-scale blenders without volume leverage for direct refinery relationships.
- Retail:Small-volume sales to maintenance contractors and automotive refinishing shops; limited growth trajectory.
Direct sales channels dominate premium-grade volumes; digital platforms are expanding most rapidly in commodity segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's integrated refinery-solvent complexes command premium distillation capacity, while India's western industrial corridor drives bulk coatings consumption through Gujarat-Maharashtra manufacturing clusters. Japan maintains the region's strictest pharmaceutical-grade specifications, creating regulatory moats for qualified suppliers. Southeast Asian infrastructure investment is accelerating solvent procurement across Indonesia and Vietnam.
China
Catalytic reforming capacity expansion in Shandong and Jiangsu provinces is offsetting natural gum turpentine supply volatility. SAMR's GB standards enforcement on benzene content limits is forcing legacy atmospheric distillation unit retirements. Guangdong coatings manufacturers are qualifying Thai and Singaporean imports to bridge domestic supply gaps.
India
CDSCO-BIS alignment on residual sulfur thresholds for API processing is extending pharmaceutical-grade qualification cycles. Maharashtra automotive OEMs now mandate solvent supplier accreditation as a condition of coatings vendor qualification. The Gujarat-Maharashtra industrial corridor concentrates bulk demand for alkyd resin thinning applications.
Japan
METI's chemical management framework requires GHS-aligned hazard communication for cross-border fragrance compounder shipments. Kansai and Kanto prefectures drive demand for sub-50 ppm sulfur rectified grades. Idemitsu Kosan's specialized hydrotreating capacity anchors domestic supply meeting purity thresholds.
Singapore
Integrated refinery-solvent infrastructure compresses feedstock costs for premium distillation serving regional export markets. Jurong Island's petrochemical cluster hosts captive hydrotreating assets for rectified grade production. ExxonMobil leverages this network to supply coatings manufacturers across Southeast Asia.
Thailand
Rayong's eastern seaboard petrochemical complex supports synthetic turpentine production via naphtha reforming. Domestic rubber processing and regional coatings demand absorb medium-purity grades. Thai exporters are capturing displaced Chinese supply as GB standards tighten domestic availability.
Asia-Pacific Mineral Turpentine Market Competitive Landscape
Top-tier vendors anchor integrated refinery-solvent networks, while mid-scale blenders face specialization-or-exit pressure from feedstock cost compression. The market structure concentrates around petroleum majors with captive hydrotreating capacity and national oil companies expanding downstream solvent distillation. Strategic archetypes include integrated petroleum majors, state-backed refiners, and regional specialty blenders. Dominant competitive moves involve refinery-solvent integration investments and digital procurement platform partnerships.
Within the integrated petroleum tier, ExxonMobil and Idemitsu Kosan exemplify the refinery-solvent network archetype. ExxonMobil's Singapore-Thailand infrastructure represents upstream-downstream coordination for premium distillation feedstock security. Idemitsu Kosan occupies a position as the Japanese market's purity-threshold specialist. PetroChina Company Limited anchors the state-backed refiner category with domestic catalytic reforming scale. Chevron Phillips Chemical Company sits within the international specialty chemicals segment serving cross-border pharmaceutical and coatings demand.
| Leading Market Players |
|---|
| Chevron Phillips Chemical Company |
| PetroChina Company Limited |
| ExxonMobil |
| Indian Oil Corporation Ltd |
| SK Innovation Co., Ltd. |
| Royal Dutch Shell |
| Idemitsu Kosan Co., Ltd. |
| Bharat Petroleum Corporation Limited |
| Total S.A. |
| Others |
Pricing and Supply Chain Analysis
Sovereign-backed refiners and integrated petroleum majors anchor supply-side discipline across Singapore and Thailand, translating captive feedstock control into pricing power over rectified grades. This ownership pattern compresses margin leakage at the premium tier while forcing mid-scale Indian and Chinese blenders into commodity-grade competition without upstream cost buffers.
Pricing Analysis
Bundled long-term offtake contracts dominate premium-grade procurement, while unbundled spot transactions govern commodity-grade exchange. Three-tier pricing structure across rectified, synthetic, and crude grades separates pharmaceutical compounders from coatings manufacturers from mid-scale blenders. Cost compression in synthetic grades is intensifying because Indian and Chinese producers are expanding catalytic reforming capacity. Coatings manufacturers in Maharashtra and Gujarat exhibit highest price sensitivity; Japanese fragrance compounders in Kansai prefecture show least sensitivity due to certification lock-in.
Supply Chain Analysis
Specialized hydrotreating operators are concentrated among Japanese and South Korean engineering firms, constraining capacity expansion for sub-ppm sulfur specifications. Supply draws from Singapore, Thailand, and India as primary manufacturing geographies. Feedstock dependencies center on naphtha crack spreads, catalytic reforming catalysts, and pine resin harvests. Single-source vulnerability runs through Singapore's Jurong Island petrochemical cluster for premium distillation capacity. Distribution runs through direct refinery relationships for large coatings manufacturers and B2B digital platforms penetrating Gujarat-Maharashtra procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion pathways through hydrotreating technology deployment that unlocks pharmaceutical-grade qualification premiums. Feedstock integration into captive refinery networks remains the primary cost-down driver separating viable players from pressured blenders.
For Market Incumbents: To counter synthetic turpentine volume expansion by Chinese and Indian catalytic reformers, ExxonMobil and Idemitsu Kosan should deepen backward integration into naphtha supply and expand hydrotreating capacity for rectified grade dominance. Securing multi-year pharmaceutical contracts with CDSCO-BIS dual certification locks out commodity competitors. Channel control through direct sales relationships with Maharashtra automotive OEMs preserves pricing power against digital platform disintermediation. For New Entrants and Emerging Players: Capture the underpenetrated Bangladesh market by establishing BIS-adjacent import channels serving Dhaka-Chittagong industrial corridor solvent demand. Target pharmaceutical-grade rectified turpentine qualification as the most penetrable tier given extended incumbent qualification cycles. Deploy membrane separation technology partnerships with Japanese engineering firms as the go-to-market angle for premium-grade credibility. For Investors and Strategic Acquirers: Integrated petroleum majors with solvent distillation assets are the most active acquirer in this space, seeking hydrotreating capability to complete refinery-solvent networks. Five-to-ten year viability hinges on regulatory alignment with tightening GB standards and METI chemical management protocols. Acquisition target archetype: mid-scale Indian or Thai blenders with BIS certification and established coatings manufacturer relationships. Watch naphtha crack spread volatility as the inflection indicator for synthetic turpentine margin sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrotreating Capacity Expansion | Enables sub-50 ppm sulfur compliance for CDSCO-BIS pharmaceutical-grade contracts. |
| Backward Integration into Naphtha Supply | Compresses feedstock costs for Singapore and Thailand integrated refinery complexes. |
| Membrane Separation Technology Adoption | Allows Japanese fragrance compounders to achieve moisture specifications without thermal degradation. |
| B2B Digital Procurement Platform Partnership | Disintermediates traditional distributor networks across Maharashtra and Gujarat coatings markets. |
| Dual Certification Investment (BIS-CDSCO) | Extends qualification cycles but locks suppliers into multi-year pharmaceutical contracts. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with refinery operations managers, coatings procurement leads at Maharashtra automotive OEMs, pharmaceutical API process engineers, and B2B platform operators with secondary validation. Secondary sources included customs and trade flow databases, BIS and CDSCO regulatory filings, SEC 10-K disclosures from listed petroleum majors, and ACC solvent market reports. Bottom-up capacity modeling and top-down demand estimation triangulated volume figures across the analysis window.
Segment-weighting approaches distributed value and volume across product type, end user, application, and distribution channel dimensions. Grade-tier segmentation modeled rectified, synthetic, crude, and steam-distilled categories against coatings, pharmaceutical, adhesive, and rubber end-use demand. CAGRs derived from regression analysis of historical capacity additions, regulatory enforcement timelines, and infrastructure investment flows. Forecast inputs incorporated naphtha crack spread trajectories and GB standards compliance cost curves.
Feedstock price volatility, regulatory enforcement acceleration, and pharmaceutical qualification timeline extensions are the dominant revision risks to modeled outputs. Forecasts reflect assumptions about hydrotreating technology diffusion rates and coatings manufacturer procurement consolidation. Material deviation in naphtha crack spreads or BIS-CDSCO regulatory alignment warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Extracts
Laurel Oil Market
Extracts
Phytochemicals Market
Extracts
Global Herbal Extract Market
Extracts
Hydroglycolic Extracts Market
Extracts
Yucca Extract Material Market
Extracts
Hibiscus Flower Powder Market
Extracts
Kelp Extracts Market
Extracts
Nicotinic Acid Market
Extracts
Pullulan Market
Extracts
Amla Extract Market
Extracts
Gum Turpentine Oil Market
Extracts
Marine Algae Polysaccharides Market
Extracts
Myrrh Powder Market
Extracts
Ovalbumin Powder Market
Extracts
Passion Flower Extracts Market
Extracts
Natural Rosemarine Extract Market