
 CO2 Extract Market | 2026-2036
CO2 Extract Market Size, Share, and Industry Trends Forecast 2026-2036
CO2 Extract Market Outlook
Clean-label cosmetics buyers are gaining share as pharmaceutical procurement flattens, reorganizing supplier priorities across the CO2 extract value chain. Vitalis Extraction Technology anchors its position through large-scale supercritical systems for hop and cannabis processing. Flavex Nature Extract Gmbh specializes in European-sourced botanical oleoresins with documented supply chain traceability. Ginkgo BioWorks leverages synthetic biology platforms to complement traditional plant-derived extract portfolios.
CO2 extracts are concentrated substances obtained by exposing raw botanical material to pressurized carbon dioxide above or near its critical point, yielding solvent-free oils, waxes, and oleoresins with preserved volatile profiles. Supercritical extraction dominates commercial output due to tunable selectivity for target compounds versus residual waxes. Essential oils command premium positioning in aromatherapy and fragrance applications where terpene integrity determines value. The food and beverage end-user segment concentrates volume demand for flavoring-grade extracts meeting GRAS and EU food additive standards.
EPA oversees residual solvent limits for botanical extracts entering US commerce, while EMA and EFSA coordinate pharmacopoeial grade requirements across European member states. FDA GRAS notifications and REACH substance registrations create dual compliance burdens that favor extractors with in-house analytical laboratories. Stakeholders must monitor evolving carbon dioxide supply chain vulnerabilities and regional purity standard divergence to protect margin structures.
Market Dynamics
Supercritical extraction equipment manufacturers are consolidating around turnkey systems that compress commissioning timelines for botanical processors. This capital-access asymmetry between large-scale operators and artisanal extractors is restructuring competitive tiers across the value chain.
Growth Catalysts
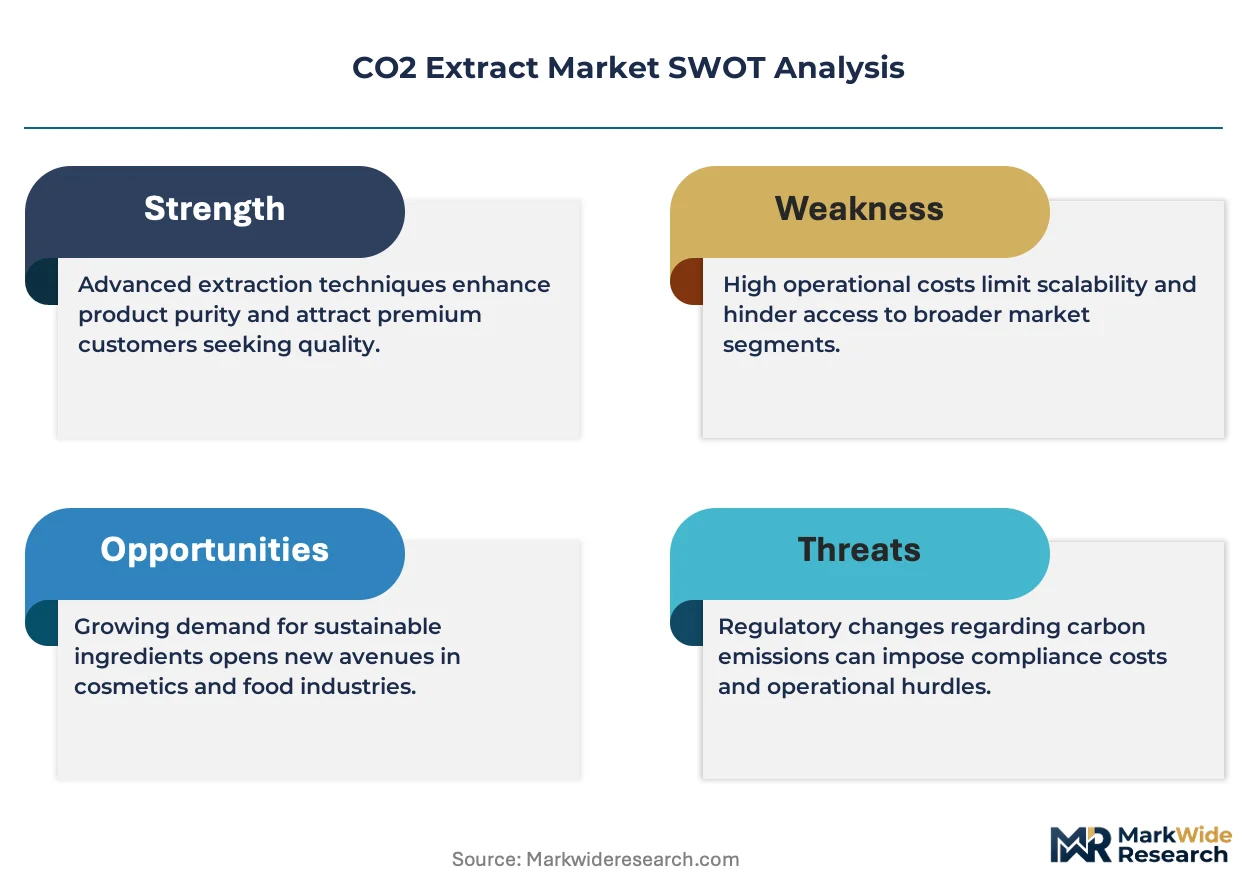
- REACH substance registration:European cosmetics formulators now require documented supply chain traceability for oleoresins, pushing procurement toward certified CO2 extractors with in-house analytical laboratories.
- India:Domestic essential oil distillation capacity is expanding under PLI scheme incentives for herbal processing infrastructure, concentrating regional demand for supercritical systems.
- Subcritical CO2 extraction:Lower-pressure systems are capturing mid-volume botanical processors seeking terpene preservation without full supercritical capex burdens.
Market Restraints
- Food-grade carbon dioxide supply concentration:Industrial gas production clusters in the US Gulf Coast and Rhine-Ruhr corridor create geographic vulnerability for extractors dependent on consistent CO2 purity.
- Steam distillation substitution:Conventional essential oil extraction retains cost advantages for high-volume commodity botanicals, compressing CO2 extract penetration in price-sensitive fragrance applications.
- EPA residual solvent testing protocols:Batch-level analytical requirements extend certification timelines for US-bound botanical extracts, increasing working capital intensity for smaller processors.
Strategic Opportunities
- Brazil:ANVISA's expanding herbal medicine registration pathway is opening pharmaceutical-grade demand for documented oleoresin purity that CO2 extraction uniquely satisfies.
- Precision fermentation convergence:Synthetic biology platforms are creating hybrid product portfolios where CO2 extracts provide complexity profiles that engineered molecules cannot replicate.
- Direct-to-formulator digital channels:Specialty botanical ingredient marketplaces are disintermediating traditional flavor house distribution, enabling extractors to capture margin from cosmetics and nutraceutical end-users.
Industry Challenges
- Supercritical system commissioning expertise:Shortage of process engineers capable of optimizing extraction parameters for novel botanical matrices extends facility ramp-up timelines.
- FDA GRAS self-determination documentation:Food and beverage extractors face protracted safety substantiation cycles for novel botanical sources, delaying commercialization of innovative flavor ingredients.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CO2 Extract Market |
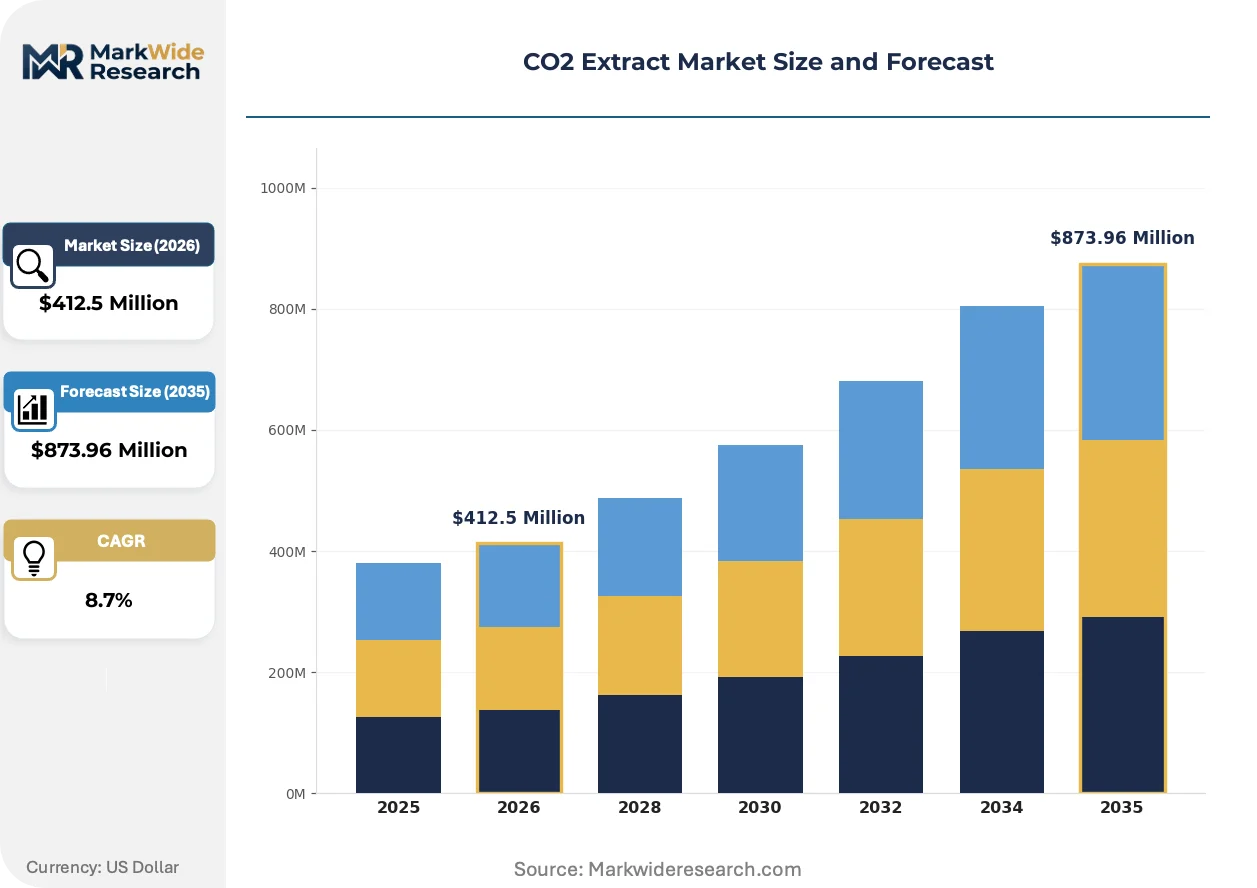
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $873.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Essential Oils, Herbs, Botanical Extracts, Flavors End User: Food & Beverage, Cosmetics, Pharmaceuticals, Nutraceuticals Application: Flavoring, Aromatherapy, Herbal Medicine, Fragrance Technology: Subcritical Extraction, Supercritical Extraction, Pressurized Liquid Extraction, Others |
| Companies Covered | Supercritical Fluid Technologies, Eden Labs, Vitalis Extraction Technology, Apeks Supercritical, extraktLAB, Botanic Innovations, Flavex Nature Extract Gmbh, Ginkgo BioWorks, CO2 Extraction Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CO2 Extract Market Strategic Shifts
Equipment automation and modular system architecture are compressing the minimum efficient scale for supercritical extraction, enabling mid-cap botanical processors to enter markets previously reserved for industrial operators.
Modular skid-mounted extraction units are fragmenting the capital barrier that historically separated artisanal botanical processors from commercial-scale production. Regional herb cooperatives in Germany and India are deploying these systems for hop and spice oleoresin production. The technology is fragmenting consolidated supply structures by enabling distributed processing close to agricultural source zones.
EMA and EFSA coordination on pharmacopoeial grade standards is tightening heavy metal and pesticide residue thresholds for European-bound botanical extracts. Extractors must now maintain dual analytical protocols to satisfy divergent US and European purity documentation. Cosmetics and pharmaceutical end-use segments are absorbing compliance costs through supplier qualification premiums.
Clean-label certification is displacing conventional quality assurance as the primary procurement filter for skincare formulators. Third-party verified supply chain documentation now precedes price negotiation in buyer-seller engagements. This behavioral shift is most visible in German and French cosmetics manufacturing clusters where retailer sustainability mandates cascade through ingredient specifications.
CO2 Extract Market Segmentation
CO2 extract procurement patterns diverge sharply across end-use segments, with pharmaceutical and cosmetics buyers demanding pharmacopoeial documentation that food-grade processors rarely require. Regulatory tiering creates distinct supplier qualification barriers that reshape competitive positioning within each segment category.
Product Type:
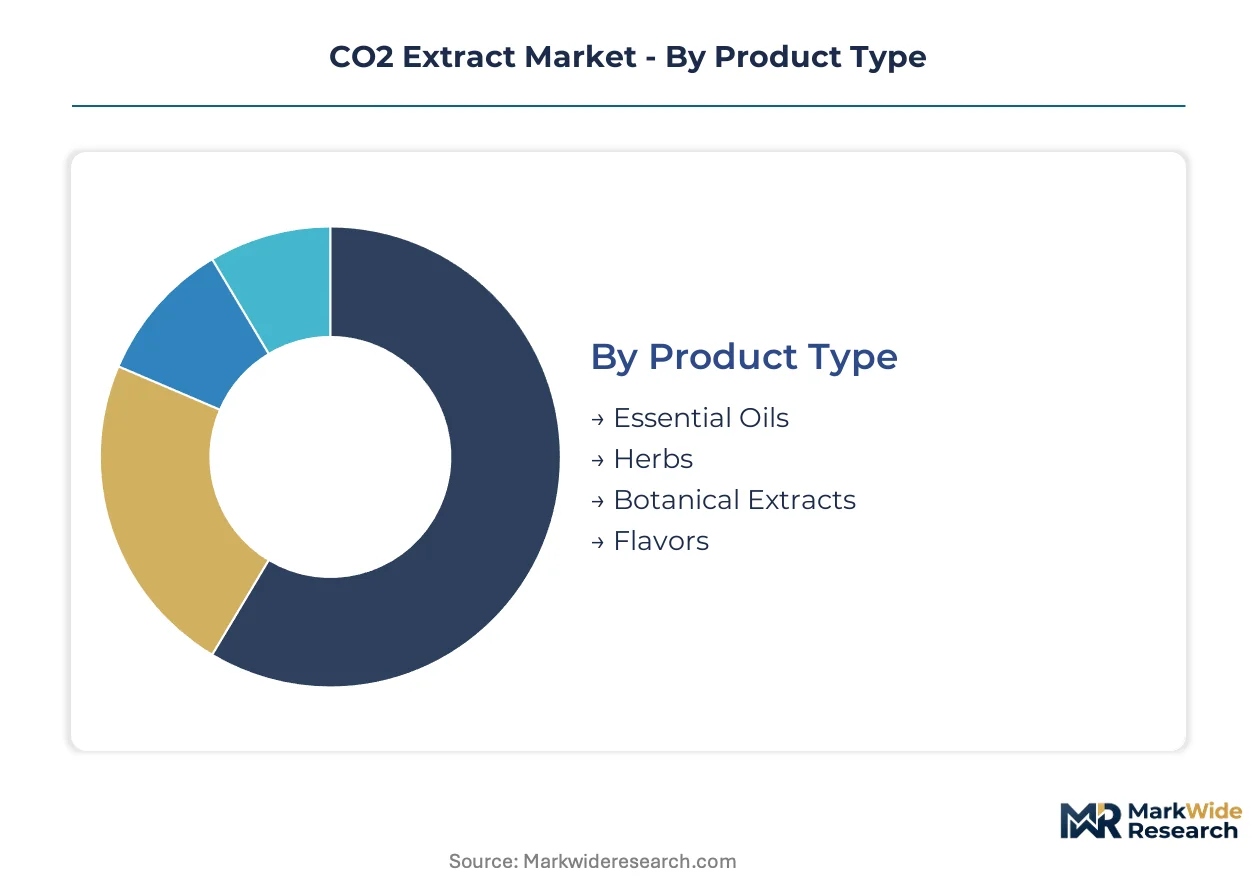
REACH substance registrations and FDA GRAS determinations impose divergent purity thresholds across botanical extract categories, forcing suppliers to maintain parallel analytical protocols.
- Essential Oils:Terpene-rich volatile concentrates extracted from aromatic botanicals where supercritical CO2 preserves heat-sensitive compounds. German and French cosmetics manufacturers dominate procurement for clean-label fragrance applications, with retailer sustainability mandates cascading into supplier specifications.
- Herbs:Dried plant material processed into standardized oleoresins with documented active compound concentrations. Indian PLI scheme incentives are expanding domestic distillation capacity for Ayurvedic and traditional medicine applications.
- Botanical Extracts:Standardized phytochemical preparations requiring heavy metal and pesticide residue documentation.
- Flavors:GRAS-notified taste and aroma compounds for food and beverage applications.
Essential oils handle the majority of throughput; botanical extracts are expanding most quickly on share.
End User:
Customer procurement sophistication varies by margin structure, with pharmaceutical buyers absorbing compliance premiums that commodity food processors resist.
- Food & Beverage:Volume-driven procurement of GRAS-compliant flavor extracts where cost sensitivity limits supercritical penetration. EPA residual solvent testing protocols extend certification timelines, compressing supplier margins on high-volume contracts.
- Cosmetics:Premium positioning for clean-label skincare formulations with third-party verified supply chain documentation. German and French manufacturing clusters now require sustainability certification before price negotiation.
- Pharmaceuticals:Pharmacopoeial-grade oleoresins with EMA-coordinated heavy metal and pesticide thresholds. Brazil's ANVISA expanding herbal medicine registration pathway is opening documented purity demand that CO2 extraction uniquely satisfies.
- Nutraceuticals:Dietary supplement ingredients with dual US-European compliance burdens.
Food & Beverage handles the majority of throughput; Cosmetics is gaining share fastest.
Application:
Functional use determines extraction parameter optimization, with aromatherapy and fragrance applications prioritizing terpene integrity over yield maximization.
- Flavoring:Taste and aroma compounds for food and beverage processing where GRAS self-determination documentation creates protracted commercialization cycles for novel botanical sources.
- Aromatherapy:Therapeutic-grade essential oils requiring preserved volatile profiles. Steam distillation retains cost advantages for commodity botanicals, limiting CO2 extract penetration in price-sensitive applications.
- Herbal Medicine:Standardized preparations for traditional and regulated pharmaceutical use.
- Fragrance:Fine perfumery ingredients where terpene complexity determines value positioning.
Flavoring handles the majority of throughput; Aromatherapy shows the steepest expansion trajectory.
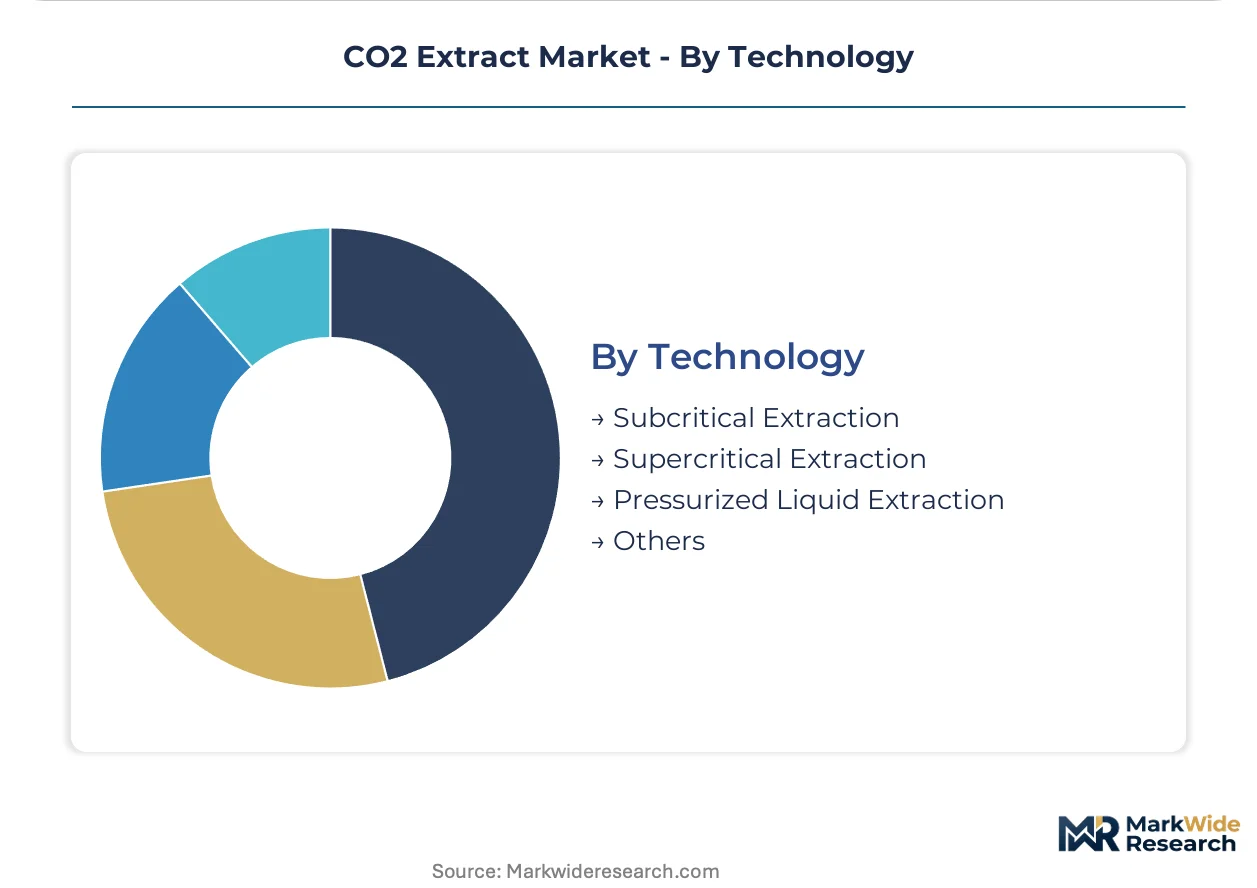
Technology:
Capital intensity and operating pressure differentiate extraction approaches, with equipment automation fragmenting historical scale barriers.
- Supercritical Extraction:Pressurized CO2 above critical point delivering tunable selectivity for target compounds. Large-scale operators in Germany and India deploy turnkey systems for hop and cannabis processing, compressing commissioning timelines through vendor consolidation.
- Subcritical Extraction:Lower-pressure systems preserving terpenes without full supercritical capex burdens. Mid-volume botanical processors in regional herb cooperatives are capturing market entry through modular skid-mounted units.
- Pressurized Liquid Extraction:Accelerated solvent-based methods for rapid compound recovery.
- Others:Emerging and hybrid extraction methodologies.
Supercritical extraction handles the majority of throughput; Subcritical systems are climbing the fastest on adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports precision supercritical extraction systems to processors across India and Brazil, creating a triangular trade flow that concentrates equipment know-how in Central Europe while locating production capacity near raw material source zones.
United States
Domestic hop and cannabis processors drive demand for large-scale supercritical systems. FDA GRAS self-determination documentation requirements extend certification timelines for novel botanical extracts. Equipment manufacturers cluster in Colorado and California, supplying turnkey systems that compress commissioning timelines for mid-cap operators.
Germany
REACH substance registration mandates documented supply chain traceability for oleoresins entering cosmetics formulations. ECHA compliance burdens favor extractors with in-house analytical laboratories. The Rhine-Ruhr corridor hosts industrial gas production clusters supplying food-grade carbon dioxide to regional processors.
India
Domestic essential oil distillation capacity expands under PLI scheme incentives for herbal processing infrastructure. FSSAI and CDSCO coordinate standards for Ayurvedic and traditional medicine applications. Karnataka and Maharashtra concentrate regional demand for supercritical systems serving spice and herb cooperatives.
Brazil
ANVISA's expanding herbal medicine registration pathway opens pharmaceutical-grade demand for documented oleoresin purity. The country's national pharmaceutical regulator tightens heavy metal and pesticide residue thresholds. São Paulo and Minas Gerais anchor processing capacity for botanical extracts serving Latin American nutraceutical markets.
China
Domestic flavor and fragrance manufacturers scale subcritical extraction capacity for terpene preservation. SAMR and NMPA coordinate food additive and pharmaceutical-grade standards. Yangtze River Delta industrial clusters concentrate equipment fabrication and botanical processing for export-oriented essential oil production.
CO2 Extract Market Competitive Environment
Player mix skews toward specialized equipment fabricators and botanical extract specialists with documented regulatory compliance capabilities. The vendor base separates into three tiers: large-scale system integrators serving industrial processors, mid-cap modular equipment suppliers enabling cooperative production, and purity-focused extractors with in-house analytical laboratories. Strategic moves concentrate on turnkey system consolidation and geographic expansion toward raw material source zones.
Within the equipment fabrication tier, Vitalis Extraction Technology and Apeks Supercritical represent large-scale system providers, while Flavex Nature Extract Gmbh anchors the European botanical oleoresin specialist segment. Ginkgo BioWorks occupies a synthetic biology platform position that complements traditional plant-derived extract portfolios. These three entities exemplify the strategic archetypes—industrial-scale equipment, regional purity documentation, and biotechnology convergence—that define competitive positioning across the value chain.
| Leading Market Players |
|---|
| Supercritical Fluid Technologies |
| Eden Labs |
| Vitalis Extraction Technology |
| Apeks Supercritical |
| extraktLAB |
| Botanic Innovations |
| Flavex Nature Extract Gmbh |
| Ginkgo BioWorks |
| CO2 Extraction Technologies |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between German equipment fabricators and Indian spice cooperatives lock in both supercritical system capacity and price visibility for oleoresin processors navigating volatile food-grade carbon dioxide markets. These arrangements transfer commissioning risk to vendors while securing feedstock access for buyers facing REACH documentation burdens.
Pricing Analysis
Supercritical versus subcritical extraction technology pricing gaps now exceed three-to-one on capital outlay, compressing mid-volume processor margins when terpene preservation demands full supercritical deployment. Three-tier pricing structure across pharmacopoeial-grade, food-grade, and cosmetic-grade certification levels segments buyer willingness-to-pay, with EMA-coordinated heavy metal documentation commanding substantial premiums. Pricing pressure stems from steam distillation substitution in commodity fragrance applications where cost sensitivity dominates procurement decisions. Food and beverage processors exhibit highest price sensitivity due to GRAS compliance costs, while pharmaceutical buyers absorb certification premiums without volume reduction.
Supply Chain Analysis
Container availability constraints on the Hamburg-Mumbai trade lane elevate inbound logistics costs for German-engineered extraction systems destined for Indian PLI-funded herb cooperatives. Equipment fabrication concentrates in Germany, China, and the United States, while raw material sourcing draws from Brazilian botanical zones, Indian spice belts, and German hop regions. Single-source vulnerability characterizes food-grade carbon dioxide supply, with industrial gas production clustering in the Rhine-Ruhr corridor and US Gulf Coast creating geographic chokepoints. Distribution runs through flavor house intermediaries for commodity extracts, though direct-to-formulator digital channels are fragmenting traditional structures for premium cosmetic-grade oleoresins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among German and French cosmetics manufacturers as retailer sustainability mandates cascade through ingredient specifications, consolidating procurement leverage around documented supply chain traceability. This fragmentation of supplier alternatives strengthens formulator negotiating position on certification premiums.
For Market Incumbents: Consolidate analytical laboratory capabilities to maintain dual US-European compliance protocols as EMA and EPA divergence intensifies documentation burdens. Acquire modular equipment suppliers serving regional herb cooperatives to preempt distributed processing competition. Anchor capacity expansion in Karnataka and Maharashtra to capture PLI scheme infrastructure incentives before mid-cap entrants secure land and power allocations. For New Entrants and Emerging Players: Differentiate on subcritical system deployment for mid-volume botanical processors seeking terpene preservation without full supercritical capex exposure. Target Brazil's ANVISA-expanding herbal medicine registration pathway where documented oleoresin purity requirements outpace incumbent extractor capacity. Pursue direct-to-formulator digital channel strategies that disintermediate flavor house distribution and capture margin from cosmetics end-users demanding third-party verified supply chain documentation. For Investors and Strategic Acquirers: Capital is best deployed toward purity-focused extractors with in-house analytical laboratories capable of satisfying both FDA GRAS self-determination and REACH substance registration requirements. These assets exhibit durable competitive positioning across the analysis window as regulatory divergence accelerates compliance costs for smaller processors. Monitor ANVISA herbal medicine registration volume as inflection indicator for pharmaceutical-grade demand acceleration in Latin American markets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Food-Grade CO2 Supply | Mitigates Rhine-Ruhr corridor concentration risk for German processors facing supply interruptions. |
| Modular System Deployment in Agricultural Zones | Enables Indian spice cooperatives to process close to raw material sources under PLI incentives. |
| Dual Analytical Protocol Investment | Satisfies divergent EMA heavy metal thresholds and EPA residual solvent testing for cross-border sales. |
| Direct-to-Formulator Digital Channel Launch | Bypasses flavor house intermediaries to capture margin from cosmetics manufacturers in French clusters. |
| ANVISA Registration Pathway Expansion | Opens pharmaceutical-grade demand for documented oleoresin purity that CO2 extraction uniquely satisfies. |
Study Parameters
Operator-level perspectives from supercritical equipment engineers, botanical extraction plant managers, cosmetics formulators, and regulatory compliance officers anchored the qualitative base for this study. Primary interviews with these stakeholders combined with secondary validation from ECHA registration databases, FDA GRAS notification filings, ANVISA herbal medicine registries, and Indian PLI scheme disbursement records. Bottom-up capacity estimates from regional herb cooperatives triangulated against top-down market size assessments from customs trade data and industrial gas production statistics.
Sensitivity analysis around carbon dioxide supply disruption scenarios and regulatory timeline slippage informed the forecast framework across the projection horizon. Segmentation dimensions modeled include extraction technology tier, end-use industry vertical, certification grade level, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to disclosed capacity additions and procurement contract values. Industry-specific forecast inputs incorporated PLI scheme infrastructure buildout schedules and ANVISA registration pathway expansion trajectories.
Material uncertainties — carbon dioxide supply chain vulnerabilities, regulatory standard divergence between EPA and EMA protocols, and steam distillation substitution rates in commodity fragrance applications — sit outside the modeled envelope. Forecasts reflect assumptions regarding sustained REACH compliance burdens and PLI scheme incentive continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Extracts
Asia-Pacific Spirulina Extract Market
Extracts
Helichrysum Oil Market
Extracts
Pullulan Market
Extracts
Organic Extracts Market
Extracts
Glycerol Extracts Market
Extracts
Hesperidin Market
Extracts
Turpentine Market
Extracts
Solid Phase Extraction Market
Extracts
Potassium Hydrogen Tartrate Market
Extracts
Extracts and Distillates Market
Extracts
Essential Oil Isolates Market
Extracts
Orange Oil Market
Extracts
Aloe Vera Derivatives Market
Extracts
Hydroglycolic Extracts Market
Extracts
Pennyroyal Oil Market
Extracts
Herba Houttuyniae Extract Market