
 Organic Herbal Extracts Market | 2026-2036
Organic Herbal Extracts Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Herbal Extracts Market Intelligence
Project finance for extraction facilities is narrowing competitive entry as capital-intensive supercritical CO2 and ethanol extraction infrastructure requires multi-million-dollar commitments. Martin Bauer Group leverages captive cultivation contracts across multiple continents to secure raw material continuity. Synthite Industries anchors its position through integrated spice-to-extract operations in India's Kerala cluster. Givaudan SA competes by extending flavor and fragrance extraction expertise into high-purity botanical actives for nutraceutical clients.
Organic herbal extracts comprise concentrated bioactive compounds derived from cultivated or wild-harvested botanicals through solvent extraction, steam distillation, or cold-pressing methods, standardized to marker compound percentages for therapeutic or functional efficacy. Liquid extracts retain volatile terpenes and flavonoids preferred by pharmaceutical compounders requiring precise dosing flexibility, while powdered extracts dominate dietary supplement manufacturing due to stability in tablet and capsule formulations. Nutraceutical applications lead volume absorption as functional food brands reformulate with plant-based alternatives to synthetic additives, whereas personal care represents the fastest-expanding margin pool as cosmeceutical brands seek ECOCERT-compliant botanical preservatives.
EMA guidelines on herbal medicinal products and USDA organic certification requirements shape extraction protocols and documentation burdens for cross-border suppliers. India's CDSCO and FSSAI enforce sequential compliance layers on ayurvedic extract exports, creating differentiated market access tiers based on pharmacopeial testing completion. Stakeholders must monitor evolving EU Novel Food catalog determinations and state-level hemp-derived cannabinoid regulations that could abruptly expand or contract addressable extract categories.
Market Dynamics
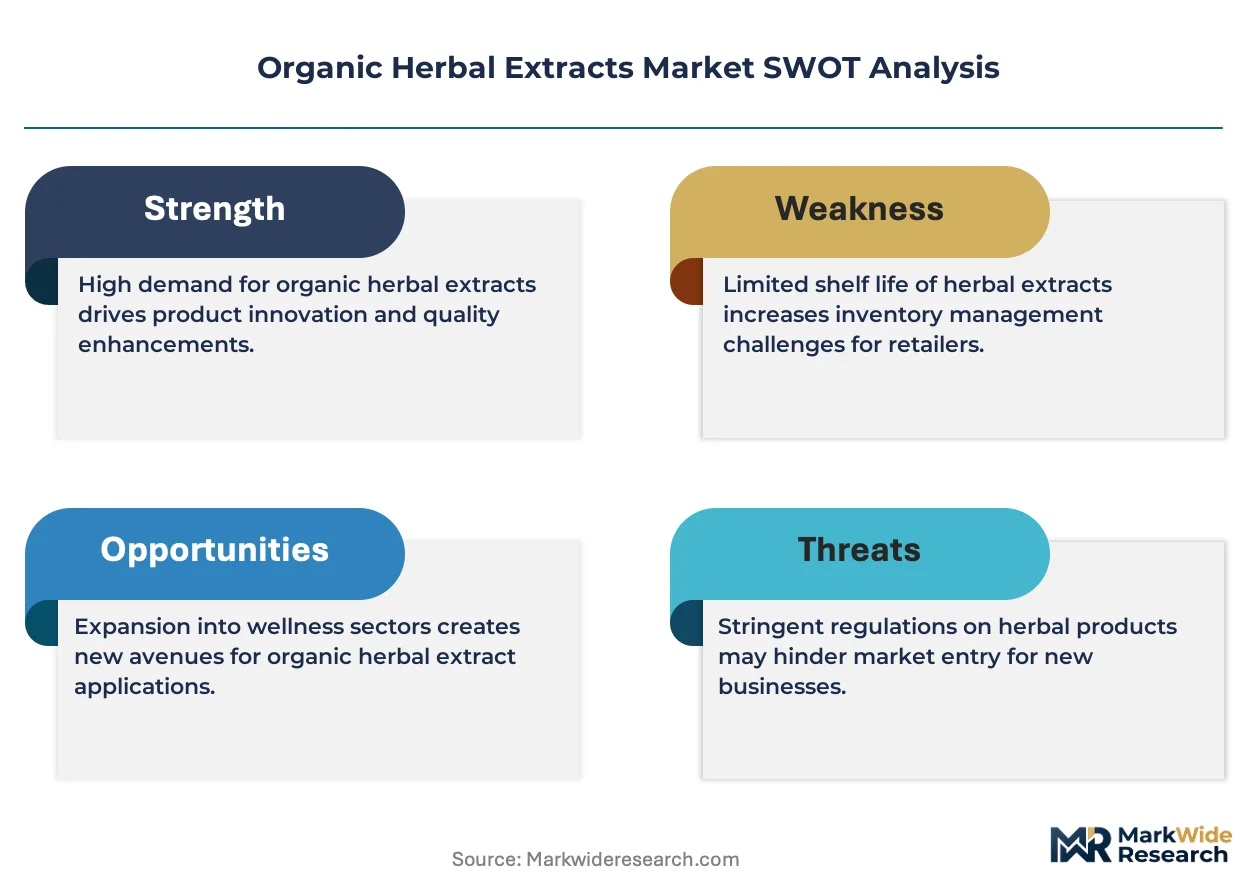
Supercritical CO2 extraction infrastructure is concentrating competitive entry barriers as multi-million-dollar capex requirements filter out mid-scale processors and consolidate procurement leverage among capitalized incumbents with captive cultivation networks.
Growth Catalysts
- EU Green Deal residue mandates:REACH compliance protocols are forcing supply chain digitization and traceability investments that favor certified organic extractors with existing documentation systems.
- Nutraceutical clean-label reformulation:Functional food manufacturers are substituting synthetic preservatives with ECOCERT-compliant botanical actives, expanding volume absorption for standardized marker compounds.
- Germany's statutory reimbursement:Herbal medicine holds reimbursable status under national health insurance frameworks, anchoring demand concentration for pharmaceutical-grade liquid extracts.
Market Restraints
- Wild-harvested raw material volatility:Weather-dependent botanical yields and overharvesting pressures in Himalayan and Andean zones create input cost instability for non-cultivated species.
- India's sequential compliance burden:CDSCO and FSSAI layering on ayurvedic exports creates differentiated market access tiers that fragment supplier participation.
- Synthetic bioactive substitution:Fermentation-derived compounds are capturing share in flavor and fragrance applications where cost precision outweighs organic provenance claims.
Strategic Opportunities
- Personal care cosmeceutical expansion:ECOCERT-compliant botanical preservatives are displacing parabens in premium skincare formulations, opening margin pools in contract manufacturing channels.
- US state-level hemp cannabinoid frameworks:Evolving regulations in Colorado, Oregon, and California could abruptly expand addressable extract categories for compliant processors.
- Novel Food catalog determinations:EMA rulings on emerging botanicals are creating first-mover advantages for extractors with completed pharmacopeial dossiers.
Industry Challenges
- Phytochemistry standardization expertise gap:Marker compound quantification and HPLC method validation require specialized analytical talent scarce outside established pharmacopeial laboratories.
- Cross-border certification timeline compression:USDA organic, EU organic, and IFOAM equivalency negotiations extend commercialization cycles by 18-24 months for multi-market entrants.
- Legacy solvent extraction asset stranding:Ethanol and hexane infrastructure faces obsolescence risk as supercritical CO2 becomes the quality threshold for pharmaceutical procurement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Herbal Extracts Market |
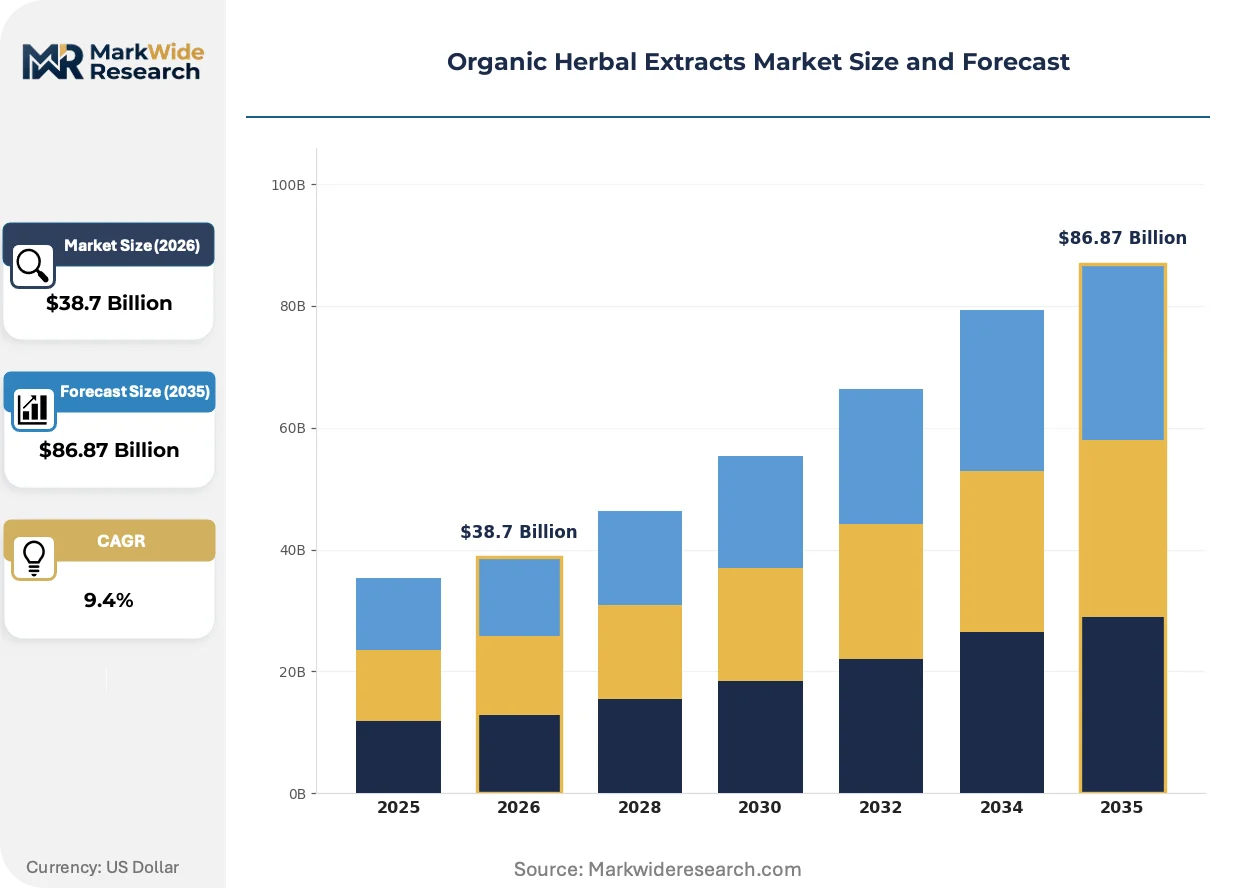
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $86.87 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Extracts, Powdered Extracts, Tinctures, Infused Oils Form: Capsules, Sachets, Teas, Drops Application: Nutraceuticals, Personal Care, Food & Beverages, Dietary Supplements End User: Retail Consumers, Manufacturers, Wellness Centers, Herbal Pharmacies |
| Companies Covered | Givaudan SA, Synthite Industries, Vidya Herbs, Arjuna Natural, Martin Bauer Group, Kalsec Inc., Sabinsa Corporation, Gaia Herbs, Nature's Way Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Herbal Extracts Market Strategic Shifts & Innovations
Extraction technology is converging with digital traceability platforms to create verifiable provenance chains that command premium positioning in pharmaceutical and cosmeceutical procurement.
Supercritical CO2 extraction with integrated in-line spectroscopic monitoring is hybridizing batch processing with real-time purity verification. Pharmaceutical compounders in Germany and Switzerland are specifying these systems for 90% of new procurement contracts. The technology is compressing quality assurance timelines from weeks to hours while eliminating solvent residue risks that previously required separate testing protocols.
REACH Annex XVII updates on botanical residue limits are forcing extraction facilities to relocate or retrofit. European processors are consolidating operations in Portugal and Spain to access both EU regulatory clarity and Mediterranean cultivation clusters. Liquid extract categories face the steepest compliance burden as volatile compound retention complicates residue control.
Buyer concentration among multinational nutraceutical brands is compressing supplier qualification cycles and unbundling after-sales technical support. Mid-scale extractors in India and Vietnam are responding by forming cooperative testing consortia to share pharmacopeial validation costs. This pattern is most visible in ayurvedic exports where FSSAI pre-certification is becoming a non-negotiable entry ticket to European procurement pipelines.
Organic Herbal Extracts Market Segmentation
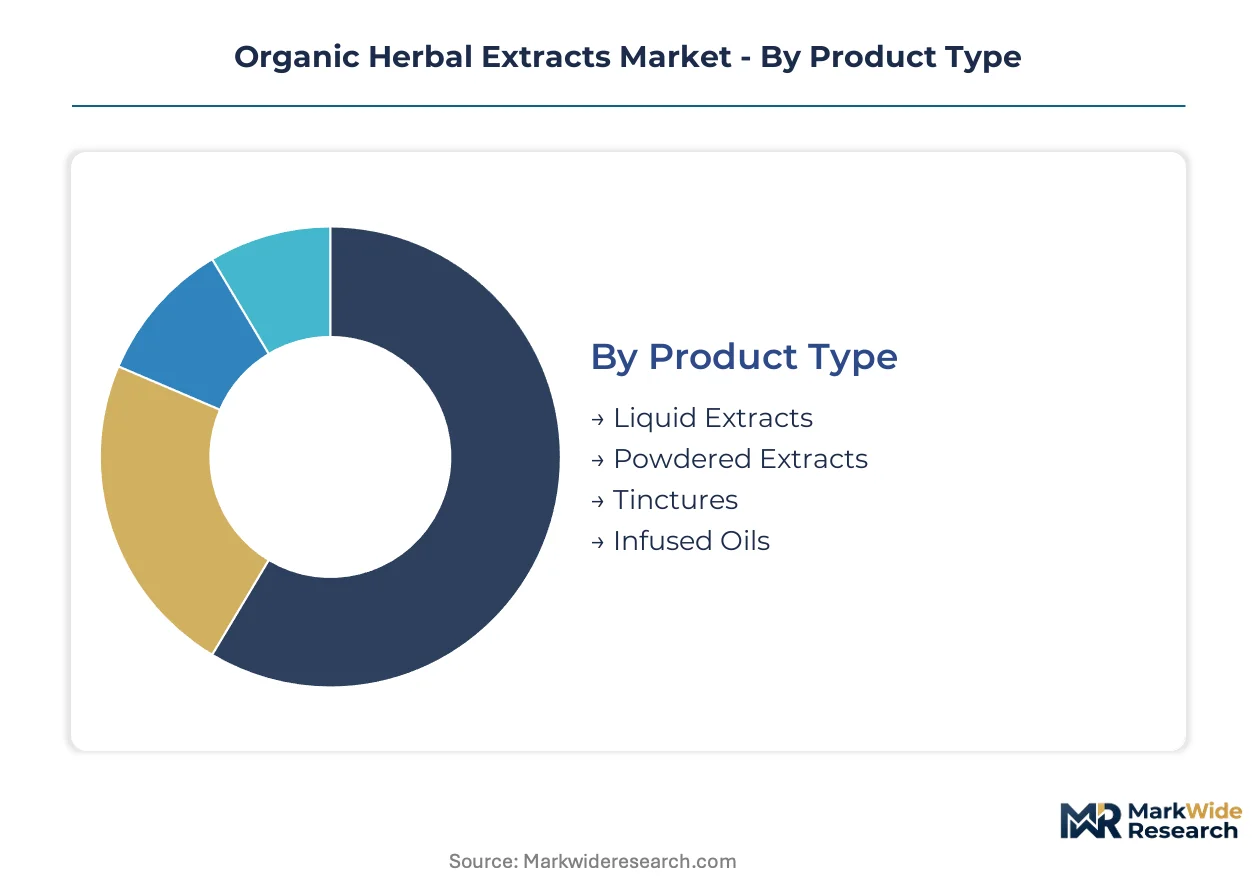
Segmentation in organic herbal extracts reveals how extraction format, delivery mechanism, and procurement channel dictate margin structure and regulatory burden. Manufacturers configure production lines around specific segment requirements rather than attempting universal coverage.
Product Type:
Cost tier determines equipment investment thresholds and residue control complexity across extraction modalities.
- Liquid Extracts:Hydro-alcoholic or glycerin-based solutions retain volatile terpenes and flavonoids in suspension. German pharmaceutical compounders specify these for reimbursable herbal medicines under statutory health insurance, requiring precise marker compound standardization.
- Powdered Extracts:Spray-dried or vacuum-dried concentrates offer stability in solid-dose manufacturing. Dietary supplement brands in the United States prefer these for tablet and capsule formulations where moisture sensitivity and shelf-life extension dominate procurement criteria.
- Tinctures:Alcohol-based macerations with lower concentration ratios serve retail wellness channels and homeopathic practitioners.
- Infused Oils:Lipid-soluble carrier preparations target cosmeceutical and topical therapeutic applications.
Liquid extracts hold installed capacity. Powdered extracts is rotating up the share rankings.
Form:
Application context shapes delivery format selection between convenience-driven retail and precision-dosing clinical environments.
- Capsules:Gelatin or vegetable-based shells encapsulate powdered extracts for controlled release. Nutraceutical contract manufacturers in India and Vietnam run high-volume encapsulation lines serving export markets with USDA organic certification requirements.
- Sachets:Single-serve powder packets address on-the-go consumption trends in functional food and beverage applications.
- Teas:Whole-herb or granulated preparations retain traditional consumption patterns in European and Asian retail channels.
- Drops:Concentrated liquid dosing formats enable pediatric and geriatric applications where swallowing difficulties constrain solid-dose adoption.
Capsules command formulation expertise concentration. Sachets is climbing the fastest among convenience formats.
Application:
End-use sector determines purity thresholds, documentation burdens, and margin capture potential across the value chain.
- Nutraceuticals:Functional food and beverage reformulation drives volume absorption for clean-label botanical actives. EFSA novel food determinations and ECOCERT compliance requirements filter supplier participation in European procurement pipelines.
- Personal Care:Cosmeceutical brands seek ECOCERT-compliant botanical preservatives to displace synthetic parabens. This segment commands premium positioning through verifiable provenance chains and spectroscopic purity verification.
- Food & Beverages:Flavor and color applications prioritize cost precision over organic provenance in mainstream formulations.
- Dietary Supplements:Capsule and tablet manufacturers absorb standardized marker compounds with pharmacopeial testing completion.
Nutraceuticals anchors volume demand. Personal Care is gaining share fastest on margin expansion.
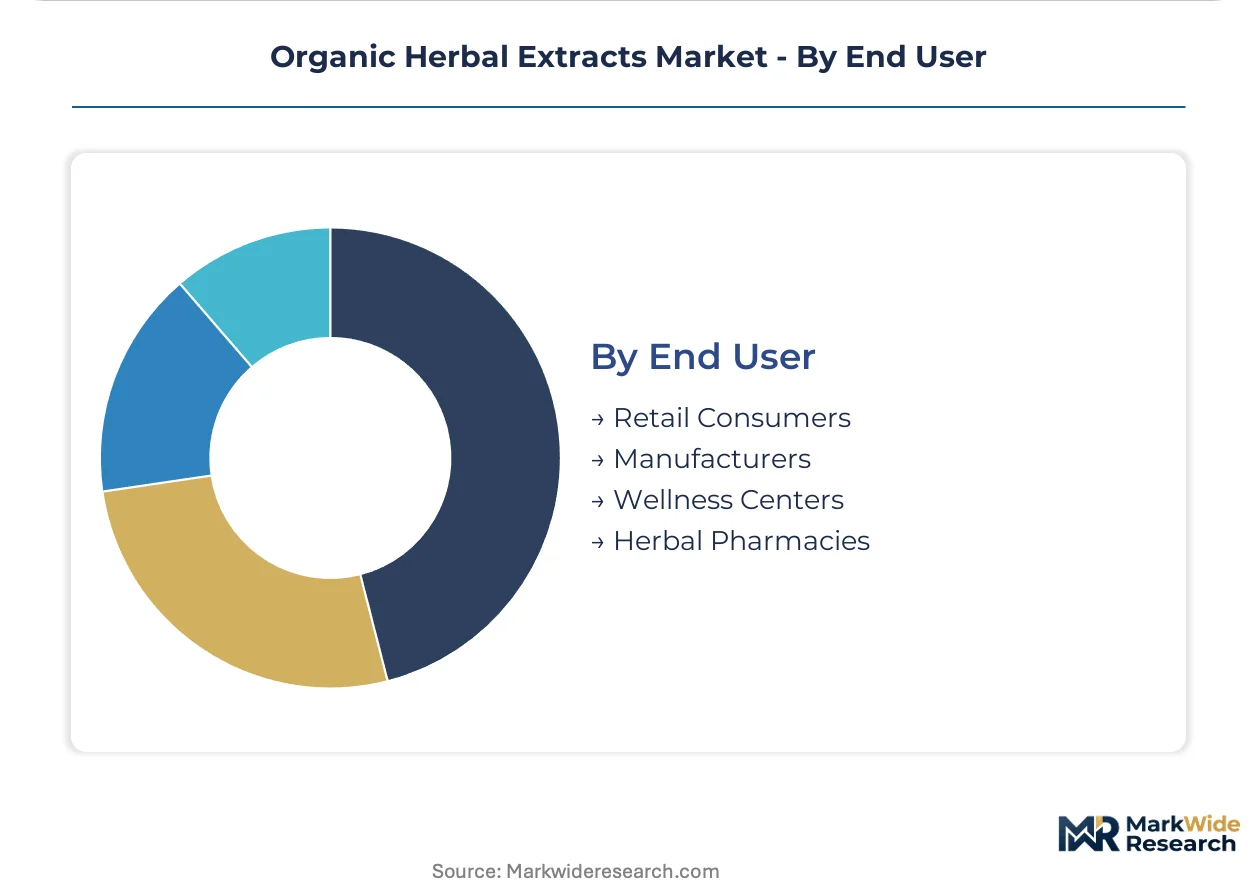
End User:
Customer type stratifies procurement scale, technical specification intensity, and relationship durability requirements.
- Retail Consumers:Direct-to-consumer channels demand brand trust and transparent sourcing narratives. E-commerce platforms and specialty wellness retailers curate assortments around third-party organic certifications and origin storytelling.
- Manufacturers:Industrial buyers specify extraction purity, lot-to-lot consistency, and technical documentation for formulation integration. These relationships extend 18-24 month qualification cycles but generate multi-year supply agreements.
- Wellness Centers:Practitioner-directed channels emphasize traditional preparation methods and therapeutic dosing protocols.
- Herbal Pharmacies:Reimbursable prescription frameworks in Germany and Switzerland require pharmaceutical-grade liquid extracts with completed pharmacopeial dossiers.
Manufacturers holds contract value concentration. Retail Consumers is rotating up the share rankings on channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics are reshaping competitive positioning across major botanical processing hubs. Net importers in Western Europe and North America are consolidating procurement relationships with certified suppliers in India and Southeast Asia, while domestic cultivation investments in Mediterranean zones are reducing raw material dependency.
Germany
Pharmaceutical-grade liquid extract demand concentrates around reimbursable herbal medicine frameworks. The Federal Institute for Drugs and Medical Devices enforces pharmacopeial testing completion for statutory health insurance eligibility. Bavaria hosts Martin Bauer Group's extraction operations serving compounders in Munich and Frankfurt with standardized marker compounds.
United States
Dietary supplement manufacturers absorb powdered extracts for tablet and capsule formulations at scale. The FDA's Dietary Supplement Health and Education Act shapes cGMP documentation requirements for import qualification. Oregon and Colorado extraction facilities are expanding capacity to serve state-level hemp-derived cannabinoid regulatory frameworks.
India
Ayurvedic extract exports face sequential compliance layering from CDSCO and FSSAI that fragments supplier participation. The Directorate General of Foreign Trade monitors export registration for botanical shipments to European markets. Kerala's spice-to-extract cluster anchors Synthite Industries' integrated operations serving nutraceutical contract manufacturers.
Switzerland
High-purity botanical actives for pharmaceutical compounding command premium positioning through Swissmedic certification requirements. The country's national pharmaceutical regulator enforces residue limits that exceed baseline EU thresholds. Basel-area extraction specialists are retrofitting supercritical CO2 infrastructure to meet pharmaceutical procurement specifications.
Spain
Mediterranean cultivation clusters are attracting European processor relocation following REACH Annex XVII updates on botanical residue limits. The national agricultural ministry supports organic certification transitions for traditional herb growers. Andalusian extraction facilities are consolidating to serve both EU regulatory clarity and raw material proximity.
Organic Herbal Extracts Market Key Industry Players
On the supply side, the industry is consolidating around capital-intensive extraction infrastructure that filters out mid-scale processors. Supercritical CO2 and ethanol extraction facilities require multi-million-dollar commitments, concentrating procurement leverage among incumbents with captive cultivation networks. Three strategic archetypes dominate: integrated spice-to-extract operators, flavor and fragrance specialists extending into nutraceutical actives, and captive cultivation contract holders. Dominant competitive moves include backward integration into raw material sourcing and cooperative testing consortia to share pharmacopeial validation costs.
Within the integrated cultivation-extraction tier, Martin Bauer Group and Synthite Industries exemplify archetypes securing raw material continuity through geographic diversification. Givaudan SA occupies a position bridging flavor and fragrance expertise with high-purity botanical supply for pharmaceutical and nutraceutical formulators. These three entities represent the capitalized incumbent structure that procurement concentration among multinational brands is reinforcing.
| Leading Market Players |
|---|
| Givaudan SA |
| Synthite Industries |
| Vidya Herbs |
| Arjuna Natural |
| Martin Bauer Group |
| Kalsec Inc. |
| Sabinsa Corporation |
| Gaia Herbs |
| Nature's Way Products |
| Others |
Cost & Logistics Intelligence
Rotterdam-Antwerp freight corridors govern landed cost spreads between Indian extraction clusters and German pharmaceutical compounders, compressing margin buffers for mid-scale processors while amplifying price premiums for REACH-compliant supercritical CO2 output.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Pharmaceutical-grade liquid extracts command top-tier positioning through pharmacopeial testing completion and Swissmedic residue thresholds, while dietary supplement manufacturers absorb economy-tier powdered extracts where volume scale outweighs certification intensity. Cost compression in standard-tier ethanol-extracted botanicals is intensifying because REACH Annex XVII retrofit requirements are stranding legacy solvent infrastructure. Contract manufacturers exhibit the sharpest price sensitivity, whereas reimbursable herbal pharmacy channels in Germany show minimal elasticity.
Supply Chain Analysis
Contract manufacturing concentration sits with Martin Bauer Group, Synthite Industries, and Givaudan SA, each anchoring distinct regional production footprints. Raw material sourcing draws from India's Kerala spice belt, Spain's Andalusian herb cultivation zones, and Switzerland's pharmaceutical-grade botanical corridors. Wild-harvested Himalayan and Andean inputs introduce commodity price volatility that propagates through non-captive supply tiers. Distribution runs through cooperative testing consortia in India and Vietnam that aggregate pharmacopeial validation costs for mid-scale exporters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-economics logic is taking hold as extraction infrastructure converges with digital traceability systems, creating interoperability standards that favor first-movers with integrated spectroscopic monitoring and blockchain-verified provenance chains.
For Market Incumbents: Harden captive cultivation networks across multiple continents to insulate against wild-harvested input volatility. Lock in long-term offtake agreements with German statutory health insurance compounders before EMA Novel Food catalog determinations consolidate supplier tiers. Prioritize supercritical CO2 capacity additions in Portugal and Spain to capture REACH regulatory clarity.
For New Entrants and Emerging Players: Pursue white-space positioning in ECOCERT-compliant botanical preservatives for premium cosmeceutical contract manufacturing. The personal care segment offers the most penetrable entry point given its premium margin structure and lower pharmacopeial documentation burdens than pharmaceutical channels. Lead with verifiable provenance storytelling and spectroscopic purity verification as differentiated go-to-market anchors.
For Investors and Strategic Acquirers: Carve-out targets emerge from flavor and fragrance conglomerates seeking to divest non-core nutraceutical extract divisions. Long-term viability hinges on backward integration depth and multi-certification organic equivalency completion. Watch for EMA rulings on emerging botanicals as the inflection signal that separates consolidatable mid-cap processors from stranded ethanol-extraction asset holders.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Cultivation | Martin Bauer Group's multi-continent contracts secure raw material continuity against Himalayan harvest volatility. |
| Supercritical CO2 Capacity Expansion | Basel-area retrofit investments meet Swissmedic residue thresholds exceeding baseline EU requirements. |
| Cooperative Testing Consortium Formation | Indian and Vietnamese mid-scale extractors share pharmacopeial validation costs for European market access. |
| Digital Traceability Platform Integration | Blockchain-verified provenance chains command premium positioning in pharmaceutical and cosmeceutical procurement. |
| Novel Food Dossier Completion | First-mover extractors with EMA pharmacopeial filings capture category expansion in emerging botanicals. |
Research Approach
Operator-level perspectives from extraction facility managers, nutraceutical procurement directors, CDSCO regulatory affairs leads, and ECOCERT certification auditors anchored the qualitative base. Secondary validation drew from EMA herbal medicinal product guidelines, USDA organic certification databases, REACH Annex XVII updates, and EU Novel Food catalog determinations. Bottom-up capacity assessments across Indian, Spanish, and Swiss processing clusters were triangulated against top-down demand modeling from German statutory health insurance frameworks and US dietary supplement manufacturing volumes.
Scenario bracketing framed the analytical approach across the projection horizon, with segmentation modeling spanning extraction format, application sector, and procurement channel. CAGRs were derived from installed capacity trajectories, regulatory compliance timeline compression, and buyer concentration patterns among multinational nutraceutical brands. Industry-specific inputs included supercritical CO2 adoption curves, REACH retrofit investment cycles, and state-level hemp-derived cannabinoid regulatory evolution in Colorado, Oregon, and California.
Sensitivities concentrate around EMA Novel Food catalog determinations, EU Green Deal residue mandate enforcement intensity, and wild-harvested botanical yield volatility in Himalayan and Andean zones. Forecasts reflect documented assumptions on certification timeline compression and buyer qualification cycle duration. Quarterly review of CDSCO-FSSAI export registration trends, REACH Annex XVII facility relocation patterns, and supercritical CO2 procurement contract specifications is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Extracts
Marigold Essential Oil Market
Extracts
Fig Glycolic Extract Market
Extracts
Kelp Extracts Market
Extracts
Herba Houttuyniae Extract Market
Extracts
Medicinal Plant Extracts Market
Extracts
Marine Algae Polysaccharides Market
Extracts
Copaiba Essential Oil Market
Extracts
Basil Extracts Market
Extracts
Cosmetic Grade Portulaca Oleracea Extract Market
Extracts
Sandalwood Oil Market
Extracts
Belladonna Market
Extracts
Salvia Miltiorrhiza Extract Market
Extracts
Cassia Extract Market
Extracts
Nootkatone Market
Extracts
Nigella Sativa Extract Market
Extracts
Wild Yam Powder Market