
 Pullulan Market | 2026-2036
Pullulan Market Size, Share, and Industry Trends Forecast 2026-2036
Pullulan Market Analytics
Direct procurement between pullulan fermenters and pharmaceutical capsule makers is rewriting traditional distributor-heavy supply chains in Asia. Hayashibara leverages decades of enzymatic refinement expertise to sustain premium positioning in Japanese excipient markets. Shandong Freda Biotechnology anchors volume supply through backward integration into Aureobasidium pullulans cultivation. Nagase Viita Co. Ltd. differentiates via specialized film-grade pullulan for oxygen-barrier packaging applications.
Pullulan is an extracellular polysaccharide produced by Aureobasidium pullulans fermentation, composed of maltotriose units linked through α-1,6 glycosidic bonds with molecular weights ranging from 10,000 to 2,000,000 Da, functioning primarily as a film-former, binder, and oxygen barrier in pharmaceutical and food systems. Powder grades dominate current fermentation output, while capsule applications capture expanding margin pools as gelatin-free oral dosage forms gain formulary preference. Film segments occupy a narrower but defensible niche in high-barrier edible packaging where oxygen transmission rates below 1 cc/m²/day command technical premiums.
Japan's PMDA maintains stringent microbial purity standards for excipient-grade pullulan, while the FDA's 21 CFR regulations govern its use in food contact substances and dietary supplement binders. REACH registration requirements in Europe constrain market access for unregistered Asian suppliers, redirecting trade flows toward documented purity dossiers. Stakeholders must monitor evolving pharmacopeial monograph harmonization between USP-NF and JPE standards, as divergence in heavy metal limits could fragment qualification requirements across destination markets.
Market Dynamics
Pharmaceutical capsule manufacturers are forcing supply chain reconfiguration as plant-based excipients displace gelatin across oral dosage form portfolios. This displacement is compressing traditional distributor margins while rewarding fermenters with direct technical service capabilities.
Growth Catalysts
- Capsule-grade purity standards:FDA's updated dietary supplement labeling rules tighten heavy metal and microbial benchmarks, disqualifying unqualified suppliers and concentrating demand on documented fermentation dossiers.
- Japan PMDA excipient harmonization:Stringent microbial purity standards for pharmaceutical-grade pullulan create qualification barriers that protect incumbent fermenters with multi-decade track records.
- Oxygen-barrier packaging demand:Edible film applications with transmission rates below 1 cc/m²/day command technical premiums in high-value confectionery and nutraceutical wrapping segments.
Market Restraints
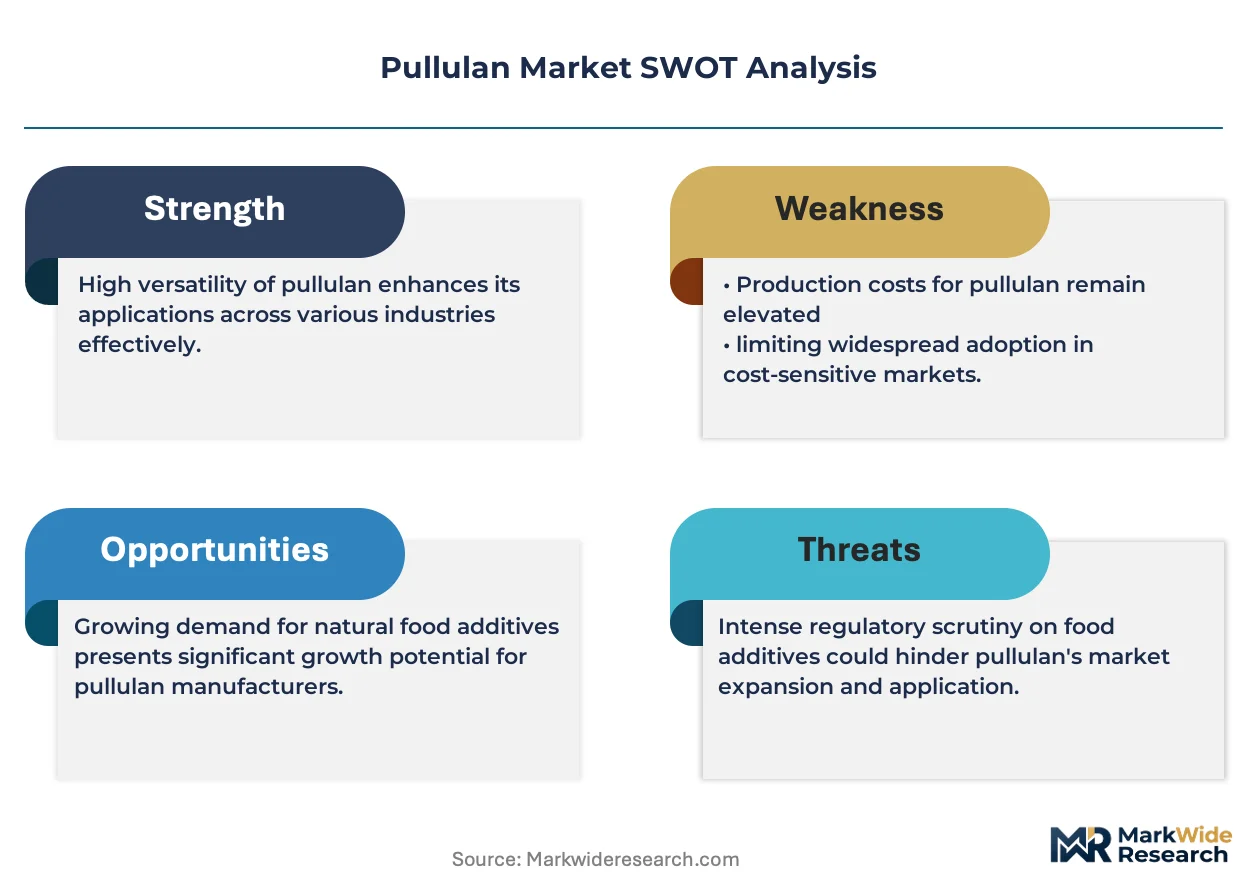
- Feedstock cost volatility:Sucrose and starch input prices fluctuate with agricultural commodity cycles, compressing fermentation margins during harvest volatility windows.
- Supply concentration risk:Aureobasidium pullulans cultivation expertise concentrates among Japanese and Chinese fermenters, creating single-source vulnerability for European and North American formulators.
- REACH registration friction:ECHA documentation requirements constrain market access for unregistered Asian suppliers, fragmenting trade flows toward dossier-complete producers.
Strategic Opportunities
- Underpenetrated Indian pharmaceutical excipient market:CDSCO's tightening impurity standards for imported excipients create first-mover advantage for pullulan suppliers establishing local technical service presence.
- Biodegradable active packaging convergence:Pullulan film barrier properties hybridize with antimicrobial agent incorporation, opening controlled-release food preservation applications.
- Direct procurement channel innovation:Capsule manufacturers in Germany bypass traditional chemical distributors to secure volume contracts with fermentation specialists, capturing technical specification control.
Industry Challenges
- Pharmacopeial monograph divergence:USP-NF and JPE heavy metal limit discrepancies force dual qualification protocols, extending certification timelines for multi-destination suppliers.
- Enzymatic refinement skill scarcity:Specialized biocatalysis expertise for molecular weight fractionation concentrates among aging technical workforces in Japanese fermentation clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pullulan Market |
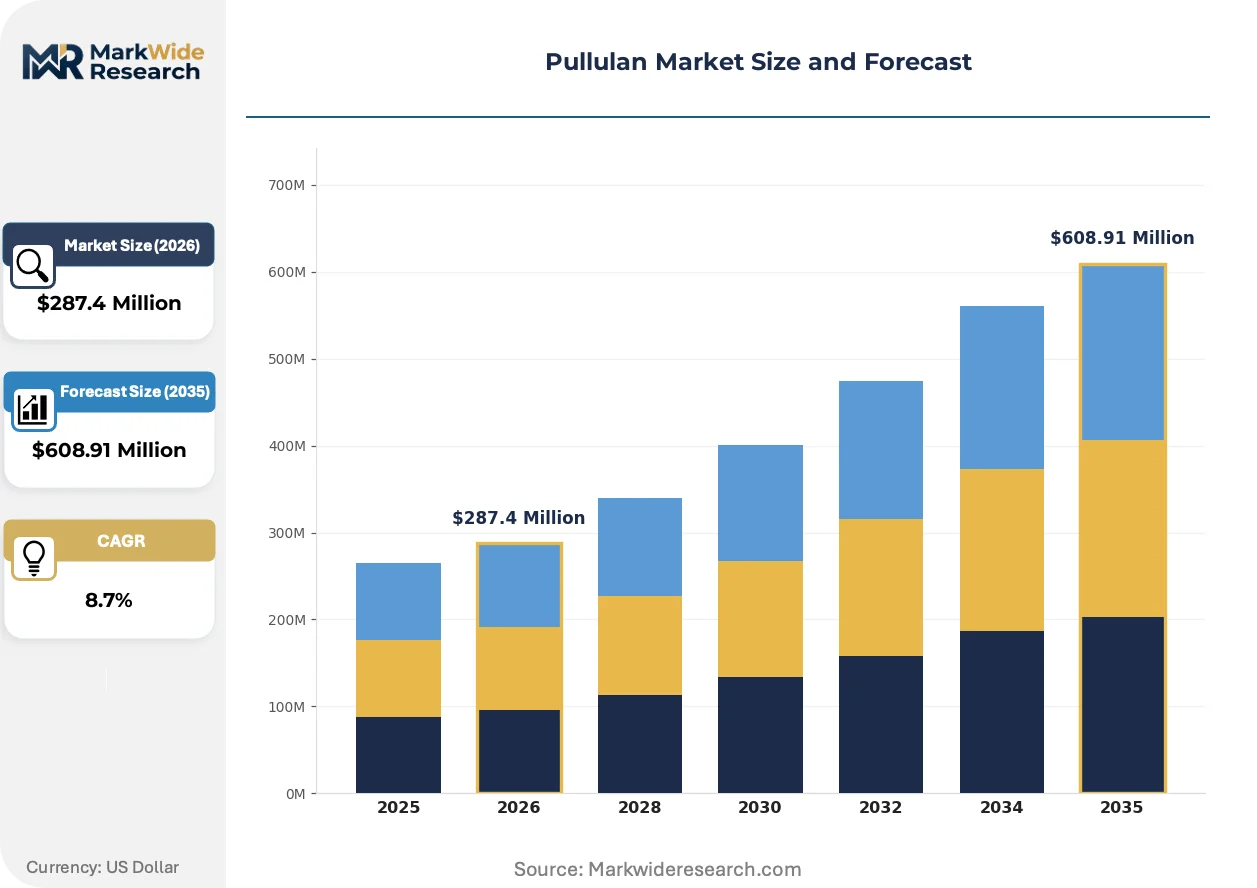
| Market Size in 2026 | $287.4 Million |
| Market Size in 2035 | $608.91 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Capsules, Films, Coatings Application: Pharmaceuticals, Food Additives, Dietary Supplements, Cosmetics Delivery Mode: Oral, Topical, Injectable, Transdermal End User: Healthcare Providers, Nutraceutical Companies, Food Manufacturers, Cosmetic Brands |
| Companies Covered | Shandong Freda Biotechnology Co. Ltd., KOPL, Hayashibara, Henbo Bio-technology, Higrand Biotech, Nagase Viita Co. Ltd., Shandong Kang Naxin Biotechnology, Jinmei Biotechnology, Meihua Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pullulan Market Evolving Landscape
Enzymatic process control and regulatory documentation automation are compressing qualification cycles while expanding addressable application spaces beyond traditional pharmaceutical binders.
Precision fermentation control systems is hybridizing batch consistency with real-time metabolite monitoring. Pharmaceutical excipient buyers in Germany and Japan are adopting these platforms at pilot scale before full manufacturing integration. The technology is hybridizing quality assurance workflows with predictive contamination detection, reducing release testing burdens.
REACH registration requirements in Europe are tightening purity documentation thresholds for polysaccharide excipients entering food contact and pharmaceutical applications. Industrial consequence includes redirection of Asian supply flows toward ECHA-registered fermentation facilities with complete toxicological dossiers. Capsule-grade pullulan shipments to European formulators now require substance identity specifications absent from commodity food-grade transactions.
Direct technical service contracts are displacing distributor-mediated procurement in North American nutraceutical supply chains. Capsule manufacturers are securing fermentation specialists for specification co-development, bypassing traditional chemical distribution intermediaries. This pattern concentrates most visibly in California and New Jersey contract manufacturing clusters where formulation agility commands premium positioning.
Pullulan Market Segmentation

Pullulan's functional versatility across molecular weight grades and film-forming specifications creates distinct technical service requirements for each segment. Manufacturers configure fermentation output and downstream processing to match end-use purity benchmarks, with capsule and pharmaceutical applications demanding the most intensive specification support.
Product Type:
After-sales service intensity varies sharply across physical forms, with capsule-grade production requiring dedicated technical liaison teams for pharmaceutical qualification support.
- Capsules:Hard and soft gelatin-replacement shells demand heavy metal limits below 10 ppm and microbial specifications meeting USP-NF and JPE monographs. German and Japanese pharmaceutical manufacturers are expanding direct procurement contracts with fermenters who provide batch-specific CoA documentation and stability study support.
- Powder:The foundational fermentation output serves as feedstock for downstream derivative production, with molecular weight fractionation determining final application suitability. Food-grade powder shipments to North American nutraceutical blenders concentrate volume demand, though margins compress during sucrose feedstock price spikes.
- Films:Edible oxygen-barrier layers with transmission rates below 1 cc/m²/day command technical premiums in high-value confectionery wrapping.
- Coatings:Tablet and supplement coating applications leverage pullulan's adhesive properties for moisture protection.
Powder holds the largest share; momentum sits with Capsules.
Application:
Cost tier stratification separates pharmaceutical-grade qualification expenses from commodity food additive positioning.
- Pharmaceuticals:Excipient-grade pullulan for capsule shells and tablet binders faces stringent PMDA microbial purity standards and FDA 21 CFR compliance requirements. REACH registration in Europe further fragments supply toward dossier-complete producers with full toxicological documentation.
- Dietary Supplements:FDA's updated labeling rules are tightening heavy metal and microbial benchmarks for binder applications in gummies and capsules. California and New Jersey contract manufacturing clusters are bypassing distributors to secure direct technical service contracts with fermentation specialists.
- Food Additives:Edible film and coating applications in confectionery and preservation systems operate under less intensive purity documentation.
- Cosmetics:Film-forming properties in skincare delivery systems occupy a narrower volume niche with distinct moisture-retention specifications.
Pharmaceuticals holds the largest share; Dietary Supplements is climbing the fastest.
Delivery Mode:
Volume concentration aligns with oral dosage form manufacturing scale across pharmaceutical and nutraceutical supply chains.
- Oral:Capsule, tablet, and film-based delivery dominates pullulan consumption, with plant-based excipient displacement of gelatin accelerating across North American and European formulators. Direct procurement channels are compressing traditional distributor margins while rewarding fermenters with specification co-development capabilities.
- Topical:Film-forming and moisture-barrier properties serve cosmetic and dermatological applications with specialized viscosity requirements.
- Injectable:Parenteral-grade specifications demand the highest purity tiers with endotoxin control and particulate matter limits.
- Transdermal:Patch and film applications for controlled release occupy an emerging niche with formulation complexity barriers.
Oral holds the largest share; Injectable commands the steepest expansion trajectory.
End User:
Customer type determines procurement sophistication, with healthcare providers and multinational nutraceutical firms driving direct technical service expectations.
- Nutraceutical Companies:North American supplement manufacturers in California and New Jersey clusters are forcing supply chain reconfiguration through direct contracts with fermentation specialists. These buyers prioritize formulation agility and rapid qualification turnaround over distributor-mediated convenience.
- Healthcare Providers:Hospital and clinic procurement of pharmaceutical-grade capsules and binders concentrates demand on documented purity dossiers with full regulatory traceability.
- Food Manufacturers:Confectionery and preservation system buyers leverage edible film barrier properties for oxygen-sensitive product wrapping.
- Cosmetic Brands:Skincare formulators utilize film-forming grades for moisture retention and active ingredient delivery.
Nutraceutical Companies holds the largest share; momentum sits with Healthcare Providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput anchors European pharmaceutical ingredient distribution, while the Port of Shanghai and Port of Nagoya handle Asia-Pacific fermentation exports. These maritime nodes determine pullulan trade velocity across pharmaceutical supply chains.
United States
California and New Jersey contract manufacturing clusters drive direct procurement of capsule-grade pullulan for nutraceutical formulations. FDA's updated dietary supplement labeling rules tighten heavy metal and microbial benchmarks, disqualifying unqualified suppliers. Los Angeles and Newark pharmaceutical hubs concentrate demand for documented fermentation dossiers with full regulatory traceability.
Germany
Pharmaceutical capsule manufacturers in Bavaria and North Rhine-Westphalia are expanding pullulan sourcing as plant-based alternatives displace gelatin. REACH registration requirements constrain market access for unregistered Asian suppliers, redirecting trade flows toward ECHA-registered facilities. The Frankfurt-Rhine-Main pharmaceutical corridor anchors excipient qualification protocols for European formulators.
Japan
PMDA maintains stringent microbial purity standards for excipient-grade pullulan, creating qualification barriers that protect incumbent fermenters. Hayashibara leverages decades of enzymatic refinement expertise from its Okayama fermentation complex. The Kansai region's technical workforce concentration sustains premium positioning in domestic excipient markets.
China
NMPA excipient registration requirements are tightening purity benchmarks for pharmaceutical-grade pullulan exports. Shandong Province anchors volume supply through backward integration into Aureobasidium pullulans cultivation. Qingdao and Jinan fermentation clusters concentrate production capacity serving both domestic and export markets.
India
CDSCO's tightening impurity standards for imported excipients create first-mover advantage for pullulan suppliers establishing local technical service presence. Maharashtra and Gujarat pharmaceutical manufacturing zones concentrate demand for plant-based capsule alternatives. Mumbai and Ahmedabad formulation hubs are bypassing distributors to secure direct contracts with fermentation specialists.
Pullulan Market Competitive Landscape
On the supply side, the industry is consolidating around fermentation specialists with multi-decade track records in enzymatic refinement and regulatory documentation. Three archetypes dominate: Japanese heritage fermenters with PMDA qualification depth, Chinese volume producers with backward integration into feedstock cultivation, and specialized film-grade suppliers targeting oxygen-barrier packaging niches. Competitive moves concentrate on direct technical service contracts with pharmaceutical manufacturers and ECHA registration completion for European market access.
Among Japanese heritage specialists, Hayashibara and Nagase Viita Co. Ltd. occupy positions defined by decades of PMDA-tracked production. Shandong Freda Biotechnology Co. Ltd. anchors the volume-driven tier with Shandong Province cultivation integration. These three exemplify the geographic bifurcation between premium qualification depth and scale-driven supply security.
| Leading Market Players |
|---|
| Shandong Freda Biotechnology Co. Ltd. |
| KOPL |
| Hayashibara |
| Henbo Bio-technology |
| Higrand Biotech |
| Nagase Viita Co. Ltd. |
| Shandong Kang Naxin Biotechnology |
| Jinmei Biotechnology |
| Meihua Group |
| Others |
Value Network & Pricing Analysis
The Shanghai-Nagoya maritime corridor channels fermentation output from Shandong Province to Japanese pharmaceutical formulators, with freight cost volatility amplifying price spreads between capsule-grade and food-grade tiers. This logistics artery concentrates supply-side leverage among established fermenters while forcing downstream buyers to absorb premium differentials for documented purity dossiers.
Pricing Analysis
Three-tier pricing structure across pharmaceutical, food-grade, and commodity powder levels separates capsule manufacturers from nutraceutical blenders from industrial users. Price differentiation hinges on USP-NF certification depth and volume commitment scale, with pharmaceutical buyers least sensitive due to formulary lock-in requirements. Cost compression in food-grade powder is intensifying because sucrose feedstock prices fluctuate with agricultural cycles, squeezing spot-market margins.
Supply Chain Analysis
Tariff exposure between China and Germany dominates supply chain risk planning for European pharmaceutical formulators seeking REACH-registered pullulan. Production concentrates in China, Japan, and select Indian fermentation facilities, with sucrose and starch feedstocks drawing from agricultural commodity markets. Single-source vulnerability persists for enzymatic refinement expertise concentrated in Japanese technical clusters. Distribution runs through direct procurement contracts bypassing traditional chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pullulan market rewards fermentation specialists who attach technical service contracts to base material supply, with stability study support and batch-specific CoA documentation expanding faster than commodity powder sales. This service layer captures margin pools unavailable to distributor-dependent competitors.
For Market Incumbents: Entrench PMDA-tracked production records as defensive moats against emerging Chinese volume producers by expanding direct technical liaison teams for German and North American pharmaceutical accounts. Deepen backward integration into Aureobasidium pullulans cultivation to secure feedstock cost control against agricultural price spikes. For New Entrants and Emerging Players: Establish a beachhead in the underpenetrated Indian pharmaceutical excipient market by securing CDSCO import qualification ahead of tightening impurity standards. Target Maharashtra and Gujarat formulation hubs with localized technical service presence, bypassing distributor channels that incumbent Japanese suppliers rely upon. For Investors and Strategic Acquirers: Japanese heritage fermenters with multi-decade enzymatic refinement track records represent the most defensible acquisition archetype in a market consolidating around regulatory documentation depth. Watch for REACH registration completion by mid-tier Chinese producers as the signal indicating European market access inflection and valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Cultivation | Shandong Province producers anchor cost control through captive Aureobasidium pullulans supply. |
| Direct Technical Service Contracting | German capsule manufacturers bypass distributors to secure specification co-development with fermentation specialists. |
| REACH Registration Completion | ECHA dossier submission unlocks European pharmaceutical formulator access for Asian suppliers. |
| Enzymatic Refinement Capacity Expansion | PMDA-tracked facilities in Okayama sustain premium positioning through molecular weight fractionation expertise. |
| Stability Study Support Bundling | California nutraceutical contract manufacturers pay premiums for batch-specific CoA documentation and regulatory traceability. |
Research Methodology
Initial hypotheses were tested against primary input from fermentation plant managers, pharmaceutical excipient procurement leads, regulatory affairs directors at capsule manufacturers, and technical service heads at Japanese heritage suppliers, then refined against secondary validation from FDA 21 CFR filings, ECHA REACH registration databases, PMDA excipient monographs, and USP-NF pharmacopeial standards. Bottom-up volume modeling triangulated against top-down market sizing across molecular weight grades and application purity tiers.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning pharmaceutical grade tier, oral delivery format, end-user procurement sophistication, and regional regulatory cluster. CAGRs derived from iterative convergence between historical fermentation capacity expansion patterns and forward-looking pharmaceutical capsule formulation shifts. Industry-specific inputs included sucrose feedstock price elasticity and enzymatic refinement labor scarcity indices.
Stress conditions across sucrose commodity volatility, REACH documentation timelines, and PMDA qualification renewal cycles were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions about regulatory harmonization trajectories and plant-based excipient displacement velocity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Extracts
Irish Moss Market
Extracts
Fig Glycolic Extract Market
Extracts
Algae Extracts Market
Extracts
Anise Extract Market
Extracts
Bromelain Market
Extracts
Cassia Extract Market
Extracts
Essential Oil Isolates Market
Extracts
Turpentine Market
Extracts
Corn Steep Powder Market
Extracts
Peppermint Oil Market
Extracts
Potassium Hydrogen Tartrate Market
Extracts
Pectinase Market
Extracts
Global Azadirachtin Market
Extracts
Cornflower Extract Market
Extracts
Thymoquinone Market
Extracts
Cochineal Extract Market