
 Botanicals Market | 2026-2036
Botanicals Market Size, Share, and Industry Trends Forecast 2026-2036
Botanicals Market Analysis
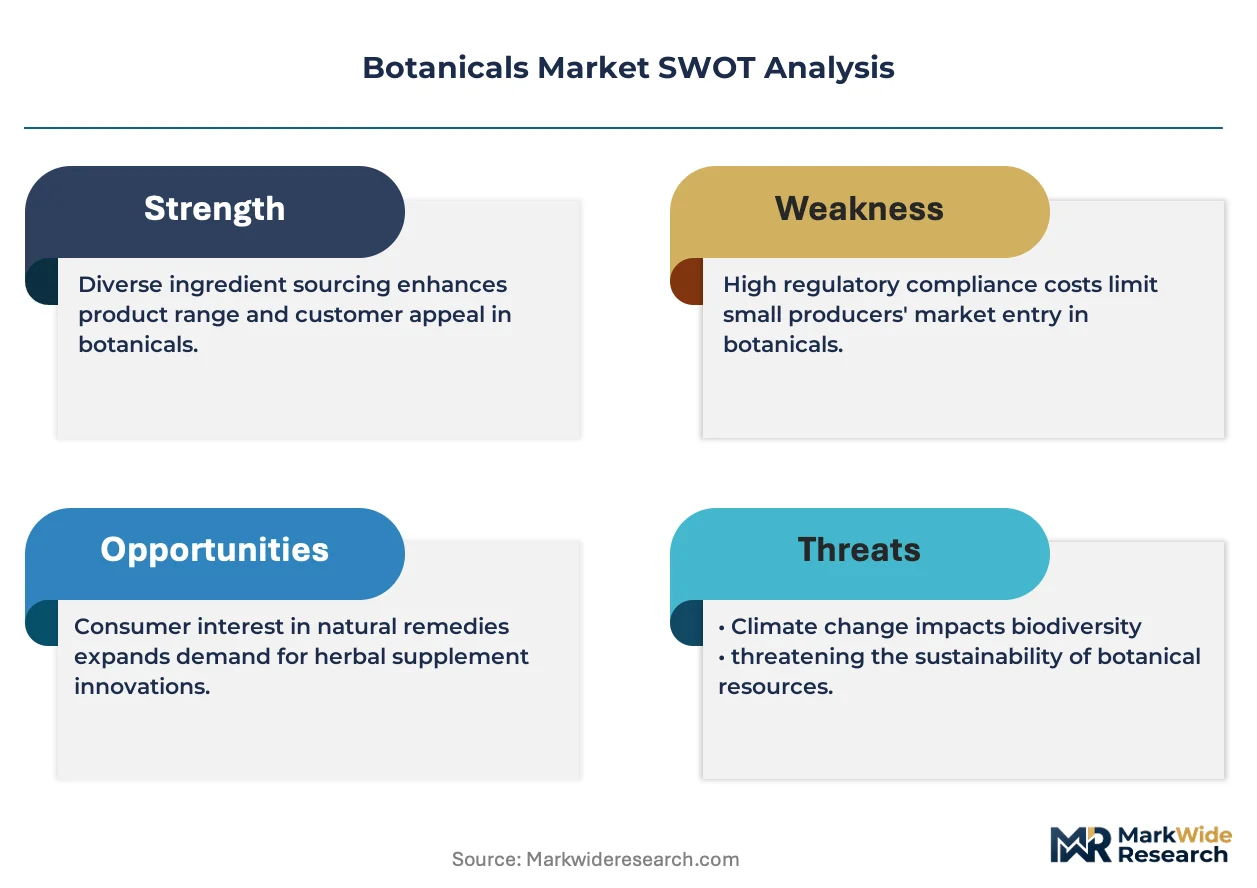
Subscription-based botanical traceability services is hardening into a core revenue layer as buyers demand chain-of-custody documentation. Symrise AG leverages integrated sourcing networks across temperate growing regions. Martin Bauer Group anchors large-scale extraction capacity for pharmaceutical-grade botanicals. International Flavors & Fragrances Inc. competes through flavor-specific botanical libraries that reduce reformulation cycles.
Botanicals comprise plant-derived materials—roots, leaves, flowers, seeds, and bark—extracted through solvent, steam distillation, or cold-press methods to yield standardized bioactive compounds for industrial formulation. Their primary commercial purpose centers on delivering functional properties—flavor, fragrance, therapeutic activity, or cosmetic benefit—without synthetic chemical attribution. Herbal extracts lead product-type revenue due to pharmaceutical and nutraceutical contract manufacturing demand, while essential oils command premium positioning in clean-label cosmetics where terpene profiles differentiate finished goods. Dietary supplements represents the fastest-growing application as consumers shift from synthetic vitamins to whole-plant formulations.
EMA guidelines on herbal medicinal products, REACH substance registration, and USDA organic certification collectively determine which botanicals gain market access in Europe and North America. EMA monograph compliance requires standardized marker compound levels, filtering out uncharacterized raw material suppliers. Stakeholders must monitor evolving extraction solvent restrictions under REACH Annex XVII, as these directly determine which processing technologies remain viable and where capital deployment for capacity expansion carries regulatory certainty.
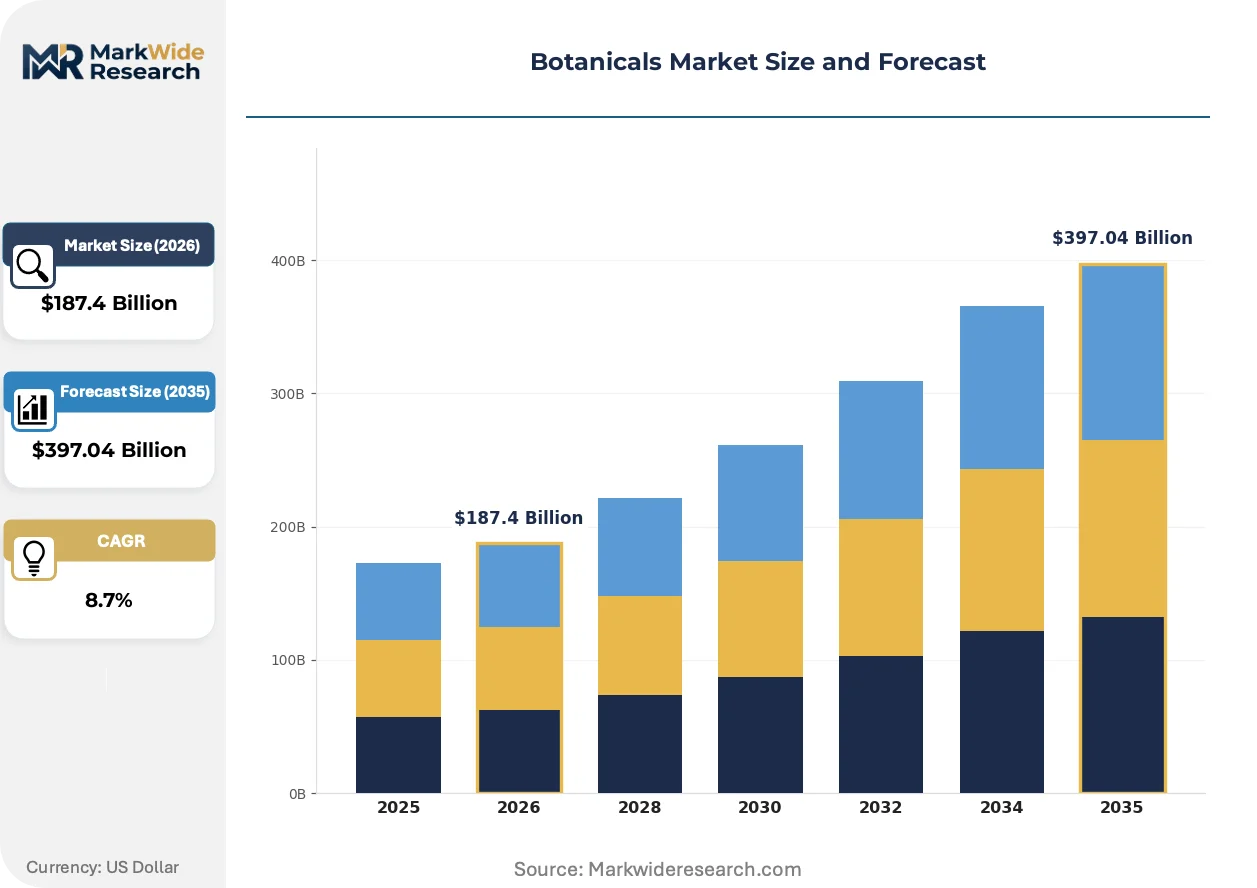
Market Dynamics
REACH Annex XVII solvent restrictions and EMA monograph compliance are forcing extraction technology upgrades while filtering raw material suppliers from European supply chains. Capital deployment now concentrates in processing clusters with regulatory certainty.
Growth Catalysts
- Clean-label cosmetics demand:Personal care formulators in Germany and France are replacing synthetic terpenes with standardized essential oil profiles to meet retailer sustainability mandates.
- REACH solvent modernization:ECHA's tightening extraction solvent standards are accelerating supercritical CO2 adoption, creating first-mover advantages for compliant processors.
- Pharmaceutical contract manufacturing:CDMOs in Switzerland and Italy are expanding dedicated botanical extraction lines to serve EMA-compliant herbal medicinal product pipelines.
Market Restraints
- Wild-harvest supply volatility:Weather-driven yield fluctuations for roots and bark in Balkan and Carpathian sourcing zones create raw material cost instability.
- EMA monograph compliance costs:Standardized marker compound testing requirements impose analytical chemistry capex that excludes smaller raw material traders.
- Synthetic terpene substitution:Biotechnology-derived aroma compounds from fermentation platforms threaten premium positioning of cold-pressed essential oils in mass-market fragrances.
Strategic Opportunities
- Blockchain traceability services:Subscription-based chain-of-custody documentation is hardening into a core revenue layer as EU buyers face CSRD supply chain disclosure requirements.
- Whole-plant dietary supplements:Consumer pivot from synthetic vitamins to full-spectrum botanical formulations is opening formulation partnerships with Nordic nutraceutical brands.
- Supercritical CO2 extraction convergence:Equipment suppliers are bundling solvent-recovery systems with extraction units to address F-Gas Regulation phase-down timelines.
Industry Challenges
- Phytochemistry analytical talent scarcity:Qualified chromatography specialists for marker compound quantification command premium compensation in German and Swiss processing hubs.
- Organic certification timeline compression:USDA and EU organic transition periods delay revenue recognition for newly converted cultivation operations by 24-36 months.
- Legacy solvent infrastructure stranding:Hexane-based extraction assets face accelerated depreciation as REACH restrictions expand to additional solvent categories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Botanicals Market |
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $397.04 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbal Extracts, Essential Oils, Dried Herbs, Powders Application: Food & Beverages, Pharmaceuticals, Cosmetics, Dietary Supplements Form: Liquid, Solid, Powder, Capsule Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | Symrise AG, Martin Bauer Group, International Flavors & Fragrances Inc., Indesso, Döhler GmbH, Givaudan SA, Firmenich SA, Lipoid Kosmetik AG, Archer Daniels Midland Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Botanicals Market Emerging Trajectories
Supercritical fluid extraction is converging with AI-driven phytochemical profiling to reshape how botanical processors standardize bioactive outputs. Regulatory disclosure mandates and buyer procurement model shifts are simultaneously rewriting competitive requirements.
Supercritical CO2 extraction technology is converging with in-line near-infrared spectroscopy for real-time marker compound monitoring. Pharmaceutical-grade botanical processors in Germany and Switzerland are adopting these integrated systems to compress batch release timelines. The convergence is enabling just-in-time contract manufacturing relationships that displace inventory-heavy supply arrangements.
ECHA's F-Gas Regulation phase-down is restricting hydrofluorocarbon use in temperature-controlled extraction processes. Industrial botanical processors are retrofitting cooling systems or relocating capacity to facilities with alternative refrigeration infrastructure. Essential oil distillation operations in Southern France and Northern Italy are most affected, with several facilities completing propane-based cooling conversions.
Subscription-based traceability documentation is replacing spot-certification purchases among mid-sized cosmetic formulators. Nordic and German buyers are requiring continuous chain-of-custody data rather than annual organic certificates. This behavioral shift is most visible in rosemary and lavender supply chains, where blockchain-registered harvest data now commands 15-20% procurement preference weighting.
Botanicals Market Segmentation
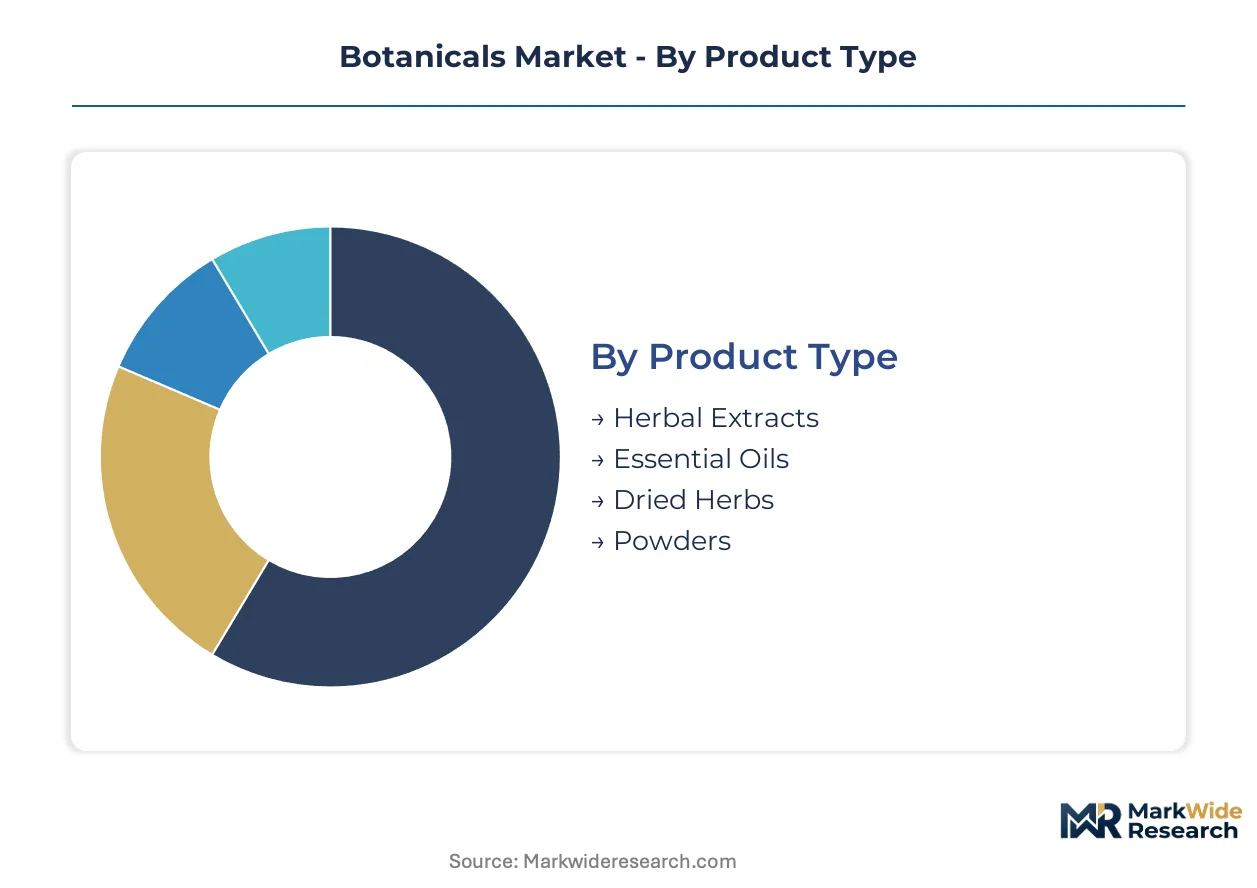
Botanical processors configure extraction capacity around product-specific solvent requirements and end-use regulatory thresholds. Segment boundaries determine which EMA monograph standards apply and where capital investment carries compliance certainty.
Product Type:
Supply concentration clusters around extraction technologies that satisfy REACH Annex XVII solvent restrictions while delivering standardized marker compounds.
- Herbal Extracts:Concentrated bioactive compounds produced through solvent or supercritical CO2 extraction, standardized to EMA monograph marker levels. Pharmaceutical contract manufacturers in Germany and Switzerland dominate procurement, driven by herbal medicinal product pipeline expansion and CDMO capacity investments.
- Essential Oils:Terpene-rich volatile fractions recovered via steam distillation or cold-press methods, with profiles varying by cultivar and harvest conditions. Clean-label cosmetic formulators in France prioritize certified organic lavender and rosemary oils to meet retailer sustainability mandates.
- Dried Herbs:Whole or cut plant material preserved through controlled dehydration, retaining structural integrity for traditional preparation methods. Tea processors and traditional medicine practitioners in Austria and Poland source bulk quantities.
- Powders:Finely milled plant material with standardized particle size distribution for encapsulation or direct formulation. Nutraceutical manufacturers in Nordic countries specify spray-dried powders for tablet compression efficiency.
Herbal extracts absorb the bulk of installed capacity; dietary supplement-grade powders are expanding most quickly.
Application:
End-use specifications fragment procurement requirements across pharmaceutical-grade, food-grade, and cosmetic-grade certification tiers.
- Food & Beverages:Flavoring and coloring agents subject to EFSA food additive regulations, requiring contaminant screening and origin documentation. Natural flavor houses in Italy and Spain drive volume for citrus and herbaceous botanicals.
- Pharmaceuticals:EMA-compliant herbal medicinal products demanding batch-to-batch marker compound consistency and GMP-certified processing. Swiss and German processors maintain dedicated extraction lines for this specification tier.
- Cosmetics:Fragrance and active ingredients governed by EU Cosmetics Regulation safety assessments, with growing preference for COSMOS-certified organic inputs. Formulators in France and Germany specify terpene profiles for clean-label positioning.
- Dietary Supplements:Whole-plant and standardized extracts for nutraceutical capsules and tablets, regulated as food supplements under national implementations of EU Food Supplements Directive. Nordic brands lead formulation innovation for full-spectrum products.
Pharmaceutical applications command premium pricing tiers; dietary supplements show the steepest expansion trajectory.
Form:
Processing economics and stability requirements determine which physical states dominate each distribution channel.
- Liquid:Tinctures, fluid extracts, and oil-based solutions with defined concentration ratios and shelf-life parameters. Retail pharmacy channels in Germany favor alcohol-based tinctures for traditional herbal medicine dispensing.
- Solid:Compressed tablets, softgels, and hard capsules requiring excipient compatibility and dissolution profile validation. Contract manufacturers in Italy specialize in botanical tablet production for private-label brands.
- Powder:Free-flowing particulate material with controlled moisture content and bulk density for flexible dosing. Sports nutrition formulators in the Netherlands specify instantized botanical powders for beverage applications.
- Capsule:Pre-measured unit doses in gelatin or vegetable-derived shells, with fill weight precision critical to label claim compliance. Direct-to-consumer brands in the UK prioritize capsule formats for subscription model logistics.
Solid forms occupy the largest production footprint; liquid extracts gain share fastest in practitioner-directed channels.
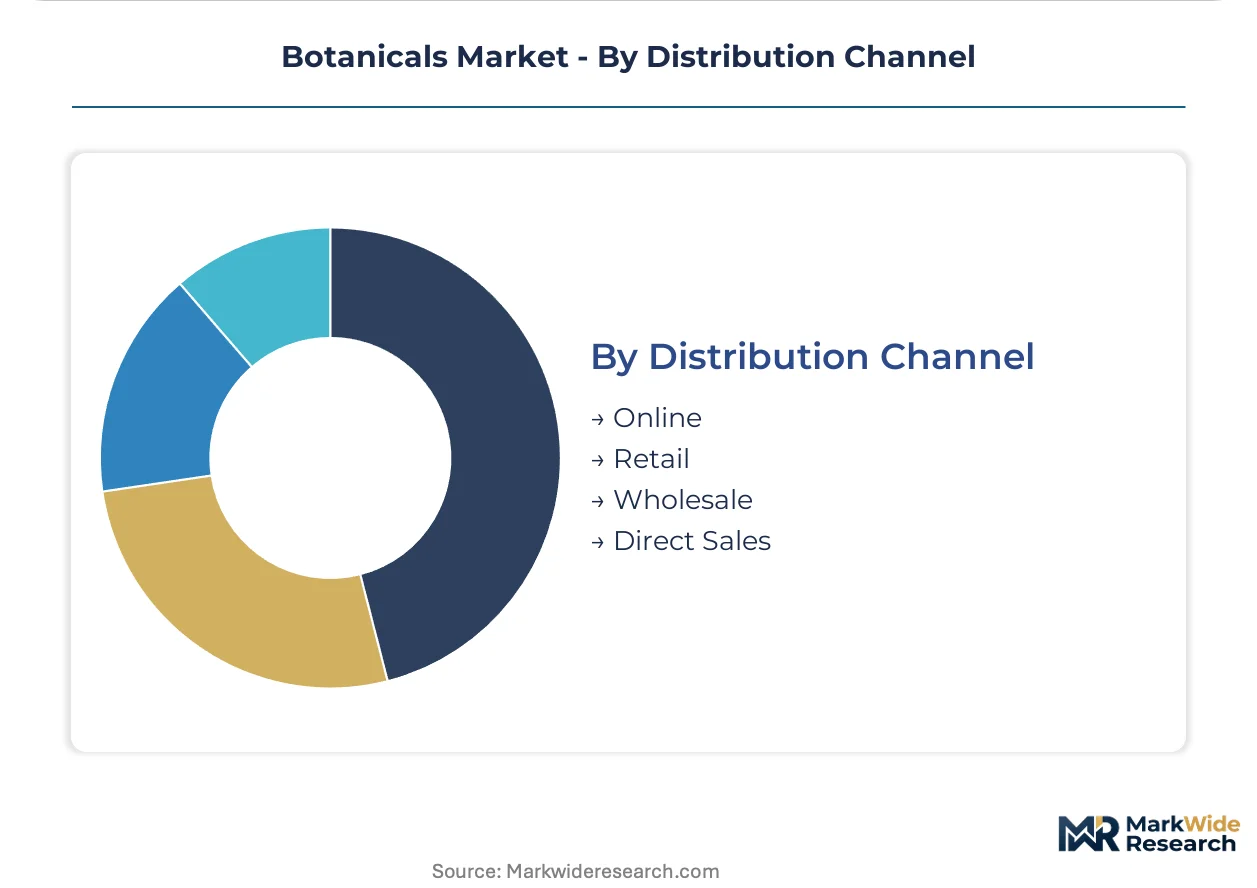
Distribution Channel:
Channel selection determines traceability documentation intensity and margin capture potential for botanical processors.
- Online:Direct-to-consumer and B2B platform sales requiring digital chain-of-custody documentation and subscription fulfillment infrastructure. Nordic and German buyers increasingly require blockchain-registered harvest data for procurement decisions.
- Retail:Pharmacy, health food store, and supermarket placement demanding packaged goods marketing support and slotting fee structures. French pharmacy chains dominate premium botanical supplement shelf space.
- Wholesale:Bulk ingredient supply to formulators and contract manufacturers with volume pricing and long-term supply agreements. German processing clusters anchor wholesale distribution for pharmaceutical-grade materials.
- Direct Sales:Relationship-based supply to large cosmetic and pharmaceutical houses with customized specification development. Symrise AG and Martin Bauer Group maintain dedicated account teams for direct strategic partnerships.
Wholesale channels handle the majority of volume throughput; online distribution is climbing the fastest as CSRD disclosure requirements elevate traceability premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Botanical processing capacity clusters in temperate growing zones with established extraction infrastructure, while consumption concentrates in pharmaceutical and cosmetic manufacturing centers. Germany and Switzerland anchor pharmaceutical-grade extraction, France and Italy dominate essential oil distillation, and the United States drives dietary supplement formulation demand.
Germany
Pharmaceutical contract manufacturers and CDMOs drive concentrated demand for EMA-compliant herbal extracts. REACH Annex XVII solvent restrictions and the F-Gas Regulation phase-down are accelerating supercritical CO2 adoption across processing facilities. The Hamburg-Berlin corridor hosts Martin Bauer Group and multiple GMP-certified extraction clusters serving European herbal medicinal product pipelines.
Switzerland
Swissmedic oversight and pharmaceutical manufacturing heritage create premium demand for batch-consistent botanical inputs. The country's herbal medicinal product regulatory framework exceeds baseline EU requirements, filtering supplier qualification. Basel-Zurich processing hubs specialize in high-purity extracts for contract manufacturing relationships with global pharma houses.
France
Clean-label cosmetic formulators in Provence and the Grasse region source certified organic lavender and rosemary essential oils. EU Cosmetics Regulation safety assessments and retailer sustainability mandates are tightening terpene profile specifications. Southern France distillation operations are completing propane-based cooling conversions to address F-Gas Regulation compliance timelines.
United States
Dietary supplement brands and direct-to-consumer botanical marketers drive formulation demand for whole-plant powders and capsules. FDA cGMP requirements and USDA organic certification determine supplier qualification for domestic brands. California and Utah host the largest concentration of contract manufacturers and private-label formulators.
Italy
Natural flavor houses and traditional medicine practitioners create segmented demand across food-grade and pharmaceutical-grade tiers. EFSA food additive regulations and national implementations of the EU Food Supplements Directive govern market access. Northern Italian processing clusters around Milan and Bologna specialize in citrus-derived botanicals and tablet compression for private-label brands.
Botanicals Market Vendor Landscape
Top-tier vendors anchor pharmaceutical and fragrance-grade extraction, while mid-cap specialists occupy dietary supplement and cosmetic ingredient niches. The vendor base stratifies across three tiers: integrated multinational processors with captive sourcing networks, regional extraction houses with certified capacity, and commodity traders with limited value-add processing. Strategic archetypes include backward-integrated growers, technology-differentiated extractors, and formulation-partnered ingredient suppliers. Competitive moves center on supercritical CO2 capacity expansion and blockchain-enabled traceability service launches.
Among Germany-based processors, Symrise AG and Martin Bauer Group exemplify the integrated multinational archetype with established temperate-region sourcing networks. International Flavors & Fragrances Inc. occupies a position representing flavor-specific botanical library specialists. These three entities sit within the top competitive tier where direct strategic partnerships with cosmetic and pharmaceutical houses replace transactional procurement relationships.
| Leading Market Players |
|---|
| Symrise AG |
| Martin Bauer Group |
| International Flavors & Fragrances Inc. |
| Indesso |
| Döhler GmbH |
| Givaudan SA |
| Firmenich SA |
| Lipoid Kosmetik AG |
| Archer Daniels Midland Company |
| Others |
Supply Flow & Price Mechanics
Pharmaceutical contract manufacturers in Germany and Switzerland anchor procurement concentration, driving contract-based long-term offtake agreements that stabilize pricing tiers across EMA-compliant extraction capacity. REACH Annex XVII solvent restrictions and F-Gas Regulation compliance costs filter supplier pools, concentrating pricing power among certified processors.
Pricing Analysis
Margin tightening in pharmaceutical-grade tiers reflects EMA monograph testing capex and supercritical CO2 equipment upgrades. Three-tier pricing structure across premium, standard, and economy levels separates GMP-certified extracts from food-grade and cosmetic-grade alternatives. Cost-down pressure on essential oil processors accelerates as biotechnology-derived terpenes gain traction in mass-market fragrances. Dietary supplement brands exhibit highest price sensitivity, while Swiss pharmaceutical houses prioritize batch consistency over unit cost.
Supply Chain Analysis
EMA monograph compliance and USDA organic certification gate market access, filtering raw material suppliers from European supply chains. Cultivation concentrates in Germany, France, and Bulgaria for temperate botanicals, with distillation operations anchored in Southern France and Northern Italy. Wild-harvest dependencies for roots and bark in Balkan and Carpathian zones create weather-driven yield volatility. Distribution runs through wholesale processing clusters in Hamburg-Berlin and Basel-Zurich corridors serving CDMO networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supercritical CO2 extraction technology is displacing legacy hexane-based infrastructure, creating first-mover advantages for compliant processors while stranding conventional assets.
For Market Incumbents: Deepen backward integration into temperate cultivation zones to secure raw material supply amid wild-harvest volatility. Expand supercritical CO2 capacity in German processing clusters before REACH solvent restrictions tighten further. Prioritize blockchain traceability service subscriptions to capture CSRD-driven documentation demand from Nordic and German buyers.
For New Entrants and Emerging Players: Launch via direct-to-consumer subscription models targeting whole-plant dietary supplement segments in Nordic markets where formulation partnerships remain underdeveloped. Focus on certified organic lavender and rosemary essential oils for clean-label cosmetic formulators in France seeking alternatives to established processors. Differentiate through AI-driven phytochemical profiling bundled with extraction services.
For Investors and Strategic Acquirers: The window for entry favors regional extraction houses with EMA-compliant capacity and established GMP certifications. Long-term viability hinges on regulatory compliance infrastructure rather than commodity trading relationships. Watch for F-Gas Regulation enforcement intensity as the inflection signal determining which cooling system retrofits create stranded asset risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Capacity Expansion | Addresses REACH Annex XVII solvent restrictions while enabling pharmaceutical-grade extraction for EMA-compliant herbal medicinal products. |
| Blockchain Traceability Service Launch | Captures subscription revenue from CSRD-mandated supply chain disclosure requirements among German and Nordic cosmetic formulators. |
| Backward Integration into Cultivation | Reduces wild-harvest supply volatility for roots and bark sourced from Balkan and Carpathian growing zones. |
| AI-Driven Phytochemical Profiling Partnership | Compresses batch release timelines for just-in-time contract manufacturing relationships with Swiss pharmaceutical CDMOs. |
| Propane-Based Cooling Retrofit | Ensures F-Gas Regulation compliance for essential oil distillation operations in Southern France and Northern Italy. |
Methodological Framework
EMA monograph databases, REACH substance registration filings, and Swissmedic herbal product approvals formed the secondary backbone for regulatory compliance mapping. Primary interviews with extraction plant managers, procurement leads at pharmaceutical CDMOs, and regulatory affairs directors at German processing clusters validated capacity and certification claims. Customs data for botanical raw materials and SEC filings for publicly traded flavor houses supplied trade flow triangulation alongside bottom-up and top-down market sizing.
Bottom-up modeling aggregated installed extraction capacity across German and Swiss processing hubs, while top-down validation cross-referenced EMA-compliant herbal medicinal product pipeline expansions. Segmentation dimensions included product type, application tier, physical form, and distribution channel intensity across the analysis window. CAGRs derived from capacity utilization trends and contract manufacturing growth trajectories, with supercritical CO2 adoption curves and CSRD disclosure timelines as industry-specific forecast inputs.
Regulatory enforcement intensity, wild-harvest yield volatility, and biotechnology substitution rates are the dominant revision risks to projection assumptions. Forecasts reflect documented expectations for EMA guideline evolution and F-Gas Regulation phase-down timelines. A model refresh is warranted upon material change in REACH Annex XVII solvent category restrictions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Extracts
Industrial Extractor Market
Extracts
Global Azadirachtin Market
Extracts
Agmatine Market
Extracts
Marigold Essential Oil Market
Extracts
Eucommia Extract Market
Extracts
Apple Powder Market
Extracts
Medicinal Plant Extracts Market
Extracts
Botanical CO2 Extracts Market
Extracts
Phytochemicals Market
Extracts
Passion Flower Extracts Market
Extracts
Black Fungus Extract Market
Extracts
Algae Extracts Market
Extracts
Aloe Vera Extract Market
Extracts
Aloe Vera Derivatives Market
Extracts
Gum Turpentine Oil Market
Extracts
Jalapeno Extract Market