
 India Real Time Payments Market | 2026-2036
India Real Time Payments Market Size, Share, and Industry Trends Forecast 2026-2036
India Real Time Payments Market Foresight
The capital-intensity gap between full-stack payment infrastructure operators and app-layer intermediaries is collapsing as NPCI opens UPI rails to non-bank fintechs at regulated cost structures. PhonePe Private Limited leverages its Walmart-backed balance sheet to sustain merchant acquisition subsidies across tier-2 and tier-3 urban centers. Google LLC anchors its India payments strategy through GPay's pre-installed Android distribution, while Paytm Payments Bank Ltd competes via integrated financial services spanning wallets, savings, and credit.
India real time payments denote fund transfer systems that clear and settle transactions within seconds through API-linked bank accounts, with UPI processing over 24-hour availability at sub-ten-second confirmation speeds. The architecture eliminates interbank settlement risk through immediate debit-credit posting, serving retail commerce, utility billing, and peer-to-peer remittance use cases. UPI dominates payment method volume due to zero merchant discount rate structures and interoperable QR code standards, while micro transactions lead transaction size segments driven by transit fares, tea stalls, and neighborhood retail. Merchant-facing service types capture expanding margin pools as platforms bundle instant transfers with working capital credit and inventory management tools.
RBI's regulatory sandbox, BIS certification mandates for payment hardware, and NPCI's operational guidelines collectively shape market access through tiered KYC requirements and transaction velocity limits. The central bank's phased escalation of UPI transaction ceilings directly expands addressable use cases into property purchases, tuition payments, and B2B supplier settlements. Stakeholders must monitor how RBI's proposed credit-on-UPI framework reallocates revenue pools between banks, fintech distributors, and merchant acquirers.
Market Dynamics
The capital-intensity gap between full-stack payment infrastructure operators and app-layer intermediaries is collapsing as NPCI opens UPI rails to non-bank fintechs at regulated cost structures. This structural compression forces incumbents to defend margin pools through bundled financial services rather than transaction fees alone.
Growth Catalysts
- RBI's regulatory sandbox:The framework accelerates platform certification timelines for fintech innovators, compressing go-to-market cycles for new payment architectures.
- Merchant QR code networks:Interoperable standards at tea stalls, transit terminals, and neighborhood retail drive transaction velocity in tier-2 and tier-3 urban centers.
- Phased UPI ceiling escalation:The central bank's staged limit increases expand addressable use cases into property purchases, tuition payments, and B2B supplier settlements.
Market Restraints
- BIS certification mandates:Payment hardware compliance timelines create friction for device manufacturers seeking market entry.
- Banking infrastructure concentration:Core settlement systems depend on a limited pool of technology service providers, creating single-point vulnerability.
- Tiered KYC requirements:Documentation burdens for small merchants limit network expansion velocity in rural Maharashtra and Karnataka.
Strategic Opportunities
- Credit-on-UPI framework:RBI's proposed embedded lending architecture reallocates revenue pools between banks, fintech distributors, and merchant acquirers.
- Working capital bundling:Platforms integrating instant transfers with inventory management tools capture expanding margin pools among Delhi NCR wholesalers.
- Voice-based UPI:NLP interfaces for non-smartphone users open penetration pathways in semi-urban Karnataka and Maharashtra districts.
Industry Challenges
- API integration complexity:Legacy core banking systems at regional banks require costly middleware development for real-time settlement compatibility.
- Compliance talent scarcity:Shortage of professionals versed in NPCI operational guidelines and RBI sandbox protocols delays product rollouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Real Time Payments Market |
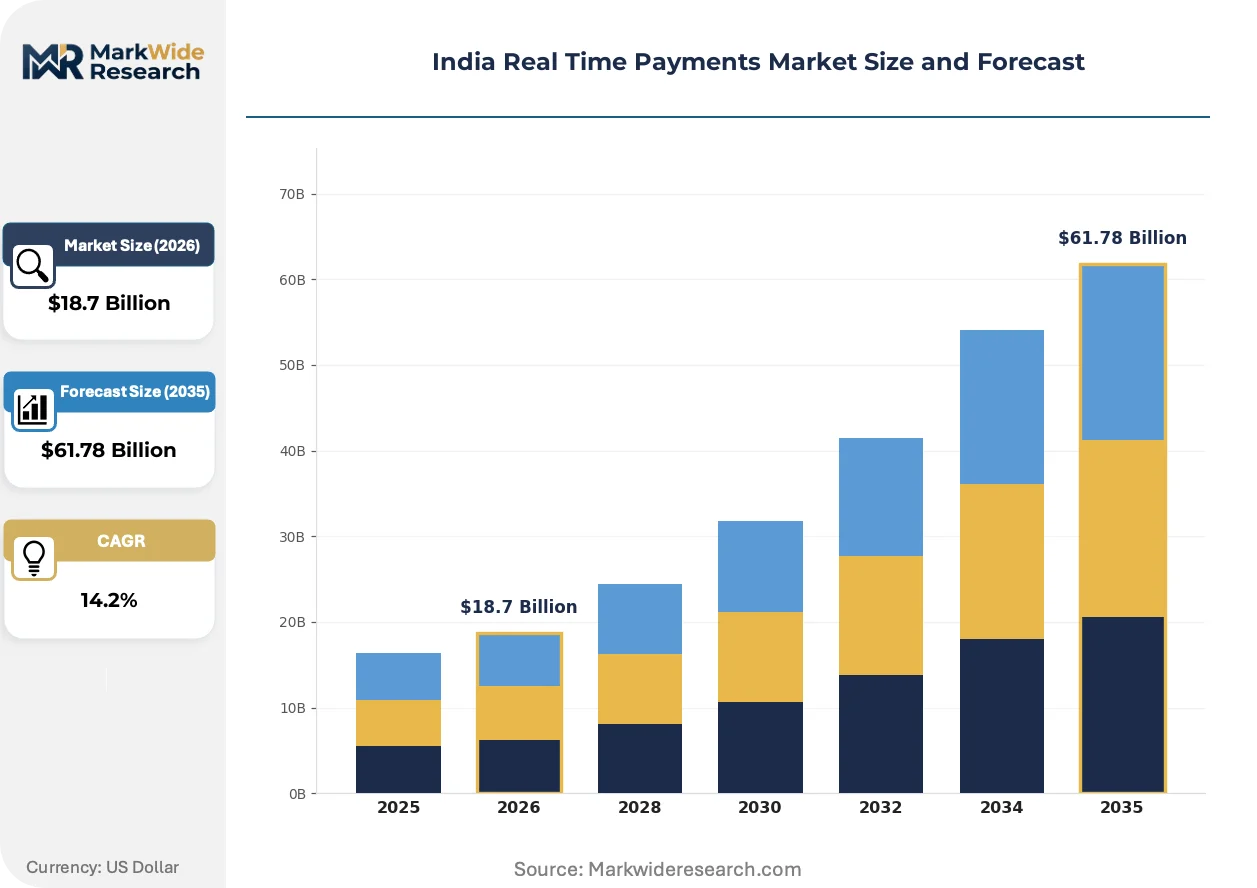
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: UPI, Mobile Wallets, Credit Cards, Net Banking End User Type: Consumers, Small Businesses, Large Enterprises, Merchants Transaction Size: Micro Transactions, Small Transactions, Medium Transactions, Large Transactions Service Type: Instant Transfers, Scheduled Payments, Bill Payments, Cross-Border Transactions |
| Companies Covered | PhonePe Private Limited, Google LLC (Alphabet Inc.), NPCI (National Payments Corporation of India), Paytm Payments Bank Ltd, Razorpay Technologies Pvt Ltd, BharatPe, PayU Payments Pvt Ltd, Amazon Pay (Amazon.com Inc.), WhatsApp Pay (Meta Platforms Inc.), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Real Time Payments Market Shifts & Advancements
Payment infrastructure is converging with credit distribution and merchant software, collapsing traditional boundaries between transaction processing and financial services. This convergence rewards platforms that control both the payment rail and the merchant relationship.
Voice-enabled UPI interfaces are fragmenting the assumption that smartphone penetration gates digital payment adoption. Rural merchants in Maharashtra and Karnataka are piloting voice-based transaction initiation through feature phones, compressing the technology stack required for merchant acceptance. This modality is fragmenting hardware requirements and expanding addressable merchant density beyond smartphone-equipped populations.
RBI's phased escalation of UPI transaction ceilings is restructuring B2B payment flows. The policy shift enables property purchases, tuition settlements, and supplier invoice payments through instant rails, displacing NEFT and RTGS for mid-value transfers. Manufacturing clusters in Delhi NCR are migrating working capital movements to UPI, compressing settlement cycles from T+1 to real-time.
Merchant acquisition economics are inverting as platforms subsidize onboarding to capture lending relationships. Tea stalls and transit operators in tier-2 urban centers receive free QR terminals and zero merchant discount rates, with platforms monetizing through working capital credit and cash flow analytics. This behavior shift concentrates margin capture in the credit layer rather than the transaction layer.
India Real Time Payments Market Segmentation
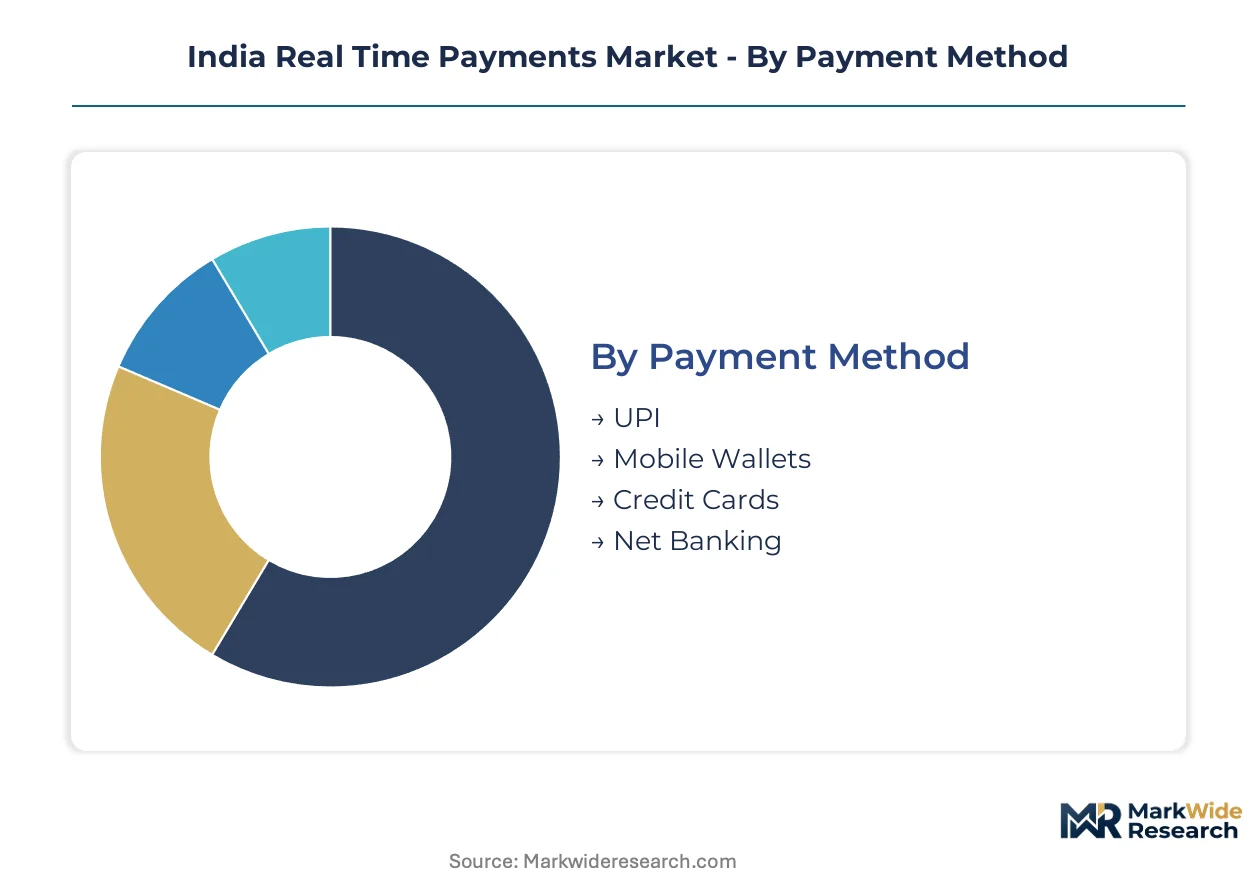
Segmentation in India's real-time payments market reveals how RBI's tiered regulatory framework creates distinct operational requirements across payment rails. Each category maps to specific infrastructure investments, compliance burdens, and monetization pathways that shape competitive positioning.
Payment Method:
RBI's zero merchant discount rate policy for UPI creates a structural cost differential against card networks, while BIS certification mandates impose hardware compliance layers on non-UPI instruments.
- UPI:API-linked bank account transfers clear through NPCI's centralized switch with sub-ten-second confirmation. Maharashtra and Karnataka merchants drive volume concentration due to dense QR code penetration and interoperable standards.
- Mobile Wallets:Stored-value instruments operating under RBI's semi-closed wallet license require tiered KYC escalation for balance limits. Delhi NCR transit corridors and tea stall networks sustain wallet velocity where feature phone penetration exceeds smartphone access.
- Credit Cards:Card networks face merchant acquisition cost disadvantages against zero-MDR UPI rails. BIS-mandated POS terminal certification and interchange fee caps compress margin pools for card issuers.
- Net Banking:Direct bank-to-bank transfers through IMPS and NEFT rails serve B2B settlements and high-value consumer transactions. Legacy core banking integration complexity at regional banks limits real-time availability outside tier-1 urban centers.
UPI handles the majority of throughput; mobile wallets are gaining share fastest among non-smartphone user bases.
End User Type:
Customer acquisition economics invert across the size spectrum, with platforms subsidizing small merchant onboarding to capture embedded lending relationships downstream.
- Small Businesses:Neighborhood retailers and tea stalls in tier-2 and tier-3 urban centers receive free QR terminals and zero merchant discount rates. Platforms monetize through working capital credit and cash flow analytics rather than transaction fees.
- Consumers:Peer-to-peer remittances and utility bill settlements dominate transaction patterns. Voice-enabled UPI interfaces through feature phones are expanding penetration in semi-urban Maharashtra and Karnataka districts.
- Merchants:Delhi NCR wholesalers and manufacturing clusters are migrating supplier invoice payments to UPI rails, compressing settlement cycles from T+1 to real-time.
- Large Enterprises:B2B supplier settlements and payroll disbursements require API integration with ERP systems. RBI's phased escalation of UPI transaction ceilings is enabling property purchases and tuition payments through instant rails.
Small businesses absorb the bulk of platform subsidy investment; large enterprises are expanding transaction ceilings fastest as RBI raises limits.
Transaction Size:
RBI's staged limit increases are restructuring addressable use cases, with each ceiling expansion displacing NEFT and RTGS for adjacent value bands.
- Micro Transactions:Sub-rupee-100 transfers for transit fares, tea stalls, and neighborhood retail constitute the highest velocity segment. Interoperable QR standards and zero merchant discount rates eliminate friction at the point of sale.
- Small Transactions:Daily commerce and utility bill payments in the rupee-100-to-rupee-2,000 range. Karnataka and Maharashtra urban centers show densest concentration due to merchant network maturity.
- Medium Transactions:Property deposits, tuition installments, and B2B supplier advances. RBI's ceiling escalations are expanding this segment's addressable volume through UPI rails.
- Large Transactions:Property purchases and capital equipment settlements approaching current UPI limits. Manufacturing clusters in Delhi NCR are piloting large-ticket UPI adoption for working capital efficiency.
Micro transactions generate the highest velocity; medium transactions are climbing the fastest as ceiling limits expand.
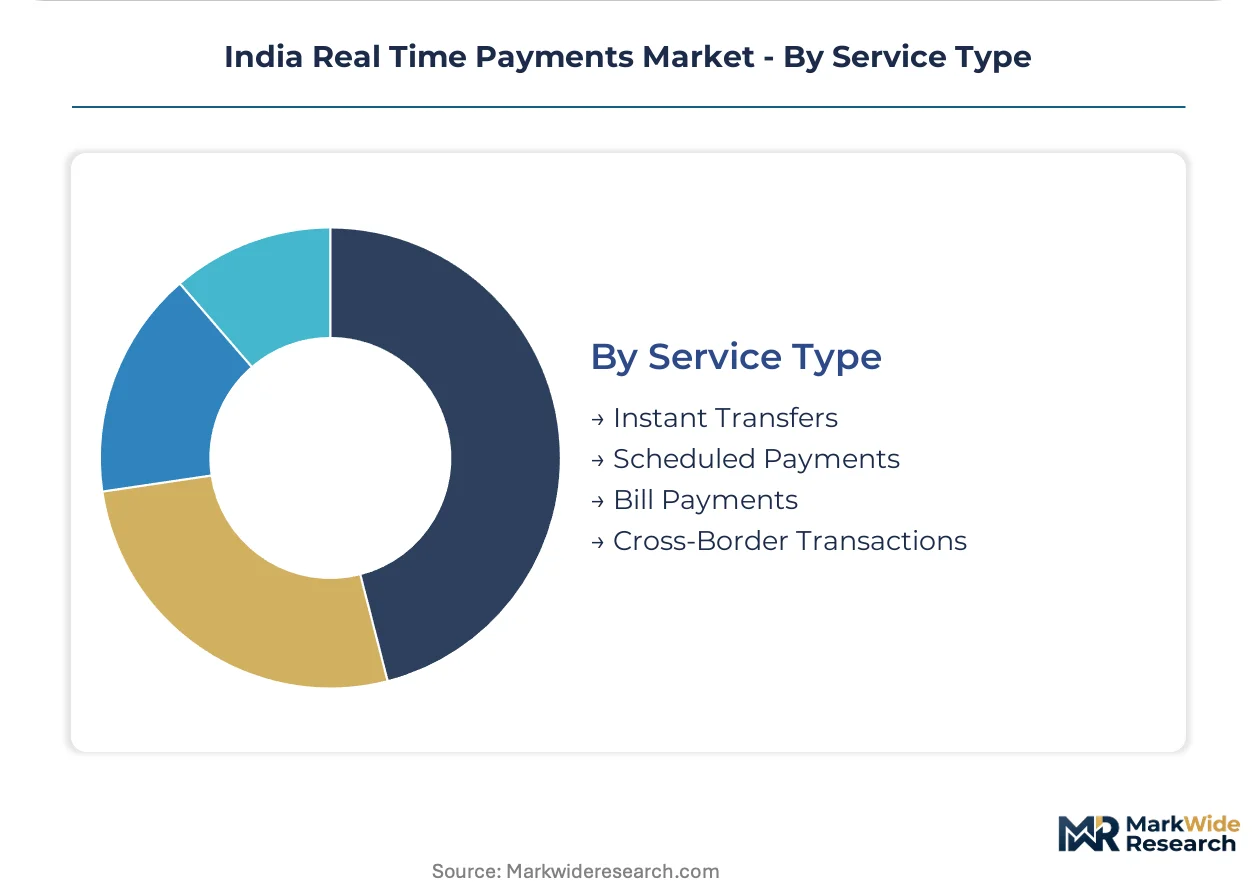
Service Type:
Platform bundling strategies are collapsing boundaries between transaction processing and adjacent financial services, with margin capture shifting to credit and software layers.
- Instant Transfers:Real-time debit-credit posting through UPI rails eliminates interbank settlement risk. This service anchors competitive positioning for all major platforms.
- Bill Payments:Utility and subscription settlements through BBPS integration. Recurring payment mandates under RBI's framework enable automated collections.
- Scheduled Payments:Future-dated transfers and standing instructions for recurring obligations. Corporate treasury applications in Delhi NCR manufacturing clusters show emerging adoption.
- Cross-Border Transactions:Remittance corridors and merchant settlements requiring NPCI's international UPI linkages. Regulatory sandbox approvals are accelerating platform certification for outbound corridors.
Instant transfers command the dominant share; cross-border transactions are expanding most quickly as international UPI linkages mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Payment infrastructure utilization varies sharply across Indian states, with western and southern regions deploying UPI for high-velocity micro-commerce while northern manufacturing belts migrate B2B settlements toward instant rails.
Maharashtra
Mumbai's dense QR code networks and Pune's SME manufacturing clusters drive transaction velocity through interoperable merchant acceptance standards. RBI's phased UPI ceiling escalation enables property purchases and tuition payments through instant rails. Nagpur's wholesale markets are piloting large-ticket supplier settlements, compressing working capital cycles from T+1 to real-time.
Karnataka
Bengaluru's tech workforce sustains peer-to-peer remittance density, while tier-2 districts deploy voice-enabled UPI interfaces for feature phone penetration. NPCI's operational guidelines for non-bank fintech access accelerate platform certification timelines. Mysuru and Hubli-Dharwad merchant networks expand fastest among semi-urban tea stall and transit terminal operators.
Delhi NCR
Gurugram's corporate headquarters and Noida's manufacturing units migrate B2B invoice payments to UPI rails, displacing NEFT for mid-value transfers. The central bank's regulatory sandbox accelerates fintech innovation cycles for embedded lending architectures. Faridabad's auto component clusters are integrating instant transfers with inventory management tools for working capital efficiency.
Gujarat
Surat's diamond polishing units and Ahmedabad's textile merchants leverage zero merchant discount rate structures for high-frequency small transactions. BIS certification mandates for payment hardware create compliance timelines for device manufacturers seeking market entry. Vadodara's chemical processing districts show emerging adoption of scheduled payment mandates for recurring supplier obligations.
Tamil Nadu
Chennai's automotive supply chains and Coimbatore's pump manufacturing clusters require API integration with ERP systems for real-time settlement compatibility. Tiered KYC requirements for small merchants limit network expansion velocity in rural Tiruppur and Salem districts. Madurai's neighborhood retail networks receive subsidized QR terminals to capture downstream lending relationships.
India Real Time Payments Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with full-stack operators controlling payment rails while app-layer intermediaries compete through merchant relationship density. The capital-intensity gap between these tiers collapses as NPCI opens UPI access to non-bank fintechs at regulated cost structures. Three archetypes dominate: retail commerce platforms subsidizing merchant acquisition, technology distributors leveraging pre-installed device penetration, and bank-backed operators bundling wallets with credit products. Competitive moves concentrate on working capital bundling and voice-based interface development for non-smartphone user bases.
Within the retail commerce platform tier, PhonePe Private Limited and Paytm Payments Bank Ltd exemplify divergent approaches to merchant monetization—one through Walmart-backed balance sheet subsidies, the other through integrated financial services spanning savings and credit. Google LLC anchors the technology distributor archetype through Android pre-installation advantages. NPCI occupies a unique position as rail operator and standard-setter, regulating cost structures that reshape competitive dynamics across all tiers.
| Leading Market Players |
|---|
| PhonePe Private Limited |
| Google LLC (Alphabet Inc.) |
| NPCI (National Payments Corporation of India) |
| Paytm Payments Bank Ltd |
| Razorpay Technologies Pvt Ltd |
| BharatPe |
| PayU Payments Pvt Ltd |
| Amazon Pay (Amazon.com Inc.) |
| WhatsApp Pay (Meta Platforms Inc.) |
| Others |
Supply & Pricing Matrix
Platform scale economies at NPCI's centralized switch compress transaction processing costs toward marginal utility pricing, concentrating margin capture among operators who bundle credit and merchant software layers. This scale compression shapes both supply concentration among rail infrastructure providers and price floors for app-layer intermediaries competing through subsidy-funded merchant acquisition.
Pricing Analysis
After-sales revenue from working capital credit and cash flow analytics drives lifetime value beyond zero-MDR transaction processing. Pricing stratifies across premium bundled services, standard instant transfers, and economy QR-only acceptance tiers. Price differentiation hinges on merchant data depth for underwriting and geographic density for network effects. Cost compression in the transaction layer is intensifying because NPCI's regulated cost structures eliminate infrastructure rent extraction. Small tea stall merchants in tier-2 urban centers show highest price sensitivity; Delhi NCR wholesalers with ERP integration requirements show lowest.
Supply Chain Analysis
Inventory-light architecture compresses hardware lead times for QR terminal deployment to sub-72-hour fulfillment cycles. Core settlement infrastructure concentrates in India through NPCI's domestic switch operations, with secondary dependencies on cloud compute capacity from global hyperscalers. Raw material inputs span BIS-certified POS terminal chipsets, encrypted communication modules, and API middleware licenses. Single-source vulnerability rests on NPCI's exclusive control over UPI rail certification. Distribution runs through direct platform-to-merchant onboarding teams and indirect banking channel partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among large merchant acquirers who subsidize network density to capture downstream lending relationships, fragmenting price-setting autonomy for pure-play transaction processors.
For Market Incumbents: Secure merchant data exclusivity through integrated inventory management and working capital credit bundling. Defend against fintech entrants leveraging NPCI's non-bank rail access by deepening certification investment in RBI's regulatory sandbox pathways. Prioritize voice-based UIP interface development for feature phone penetration in semi-urban Karnataka and Maharashtra districts. For New Entrants and Emerging Players: Voice-enabled transaction initiation for non-smartphone user bases represents the most penetrable service-layer gap where incumbents under-serve. Target semi-urban merchant networks in Maharashtra's Nagpur wholesale corridors and Karnataka's Mysuru district retail clusters. Deploy NLP interface pilots through telecom channel partnerships to compress go-to-market cycles. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among platforms controlling both payment rail access and merchant lending relationships. Long-term viability across the projection horizon favors operators with RBI sandbox certification momentum and working capital book depth. Monitor NPCI's phased UPI ceiling escalation as the inflection signal for B2B payment flow migration.| Strategic Initiative | Industry Significance |
|---|---|
| Credit-on-UPI Framework Development | RBI's embedded lending architecture reallocates revenue pools between banks, fintech distributors, and merchant acquirers. |
| Voice-Based UPI Interface Launch | NLP transaction initiation expands merchant density beyond smartphone-equipped populations in semi-urban districts. |
| Merchant Data Platform Integration | Inventory management tool bundling captures working capital credit margins among Delhi NCR manufacturing clusters. |
| Regulatory Sandbox Certification | Accelerated platform approval timelines compress go-to-market cycles for new payment architectures under RBI oversight. |
| Cross-Border UPI Linkage Expansion | International remittance corridor activation opens outbound transaction revenue through NPCI's bilateral agreements. |
Research Methodology
A standing panel of payment platform executives, RBI regulatory affairs specialists, merchant acquirer operations heads, and NPCI technology architects provided ongoing calibration against market developments. Primary interview insights combined with secondary validation from NPCI transaction volume disclosures, RBI circulars and sandbox approvals, BIS certification registries, and telecom subscriber penetration data. Bottom-up merchant network modeling and top-down payment flow aggregation enabled triangulation across independent estimation approaches.
Consistency checks validated volume and value outputs against NPCI-published UPI throughput statistics and RBI's periodic payment system reports. The analytical framework modeled segmentation across payment method, end user type, transaction size tier, and service type throughout the forecast period. CAGRs derived from trend extrapolation of rail capacity expansion, merchant network density curves, and regulatory ceiling escalation schedules. Industry-specific inputs included NPCI's phased limit increase announcements and sandbox participant rosters.
Underlying assumptions cover sustained RBI policy support for zero-MDR structures, NPCI infrastructure scaling, and merchant subsidy continuation, with deviation risk concentrated in regulatory shifts toward interchange fee introduction or credit-on-UPI framework delays. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
GCC Mobile Payment Market
Payments
Romania POS Terminals Market
Payments
Smart Payment Market
Payments
Africa Mobile Money Market
Payments
Remittance Market
Payments
Biometric Payment Market
Payments
Saudi Arabia Cash Management Services Market
Payments
Global Accounts Payable Software Market
Payments
Payment Security Software Market
Payments
Social Media Payment Solution Market
Payments
Hong Kong Credit Cards Market
Payments
Canada Payment Gateway Market
Payments
Mobile Card Reader Market
Payments
Israel Credit Cards Market
Payments
France Buy Now Pay Later Services Market
Payments
Brazil POS Terminal Market