
 Canada Dermocosmetics Market | 2026-2036
Canada Dermocosmetics Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Dermocosmetics Market Insights
The capital-intensity divergence between mass-market and clinical-grade manufacturing capabilities is bifurcating competitive dynamics in Canada. L'Oréal S.A. leverages its dermatological heritage through pharmacy-centric distribution networks. Pierre Fabre Group anchors its position with thermal spring water formulations and dermatologist endorsement programs. Groupe Marcelle Inc. competes through domestic manufacturing flexibility and bilingual marketing reach across Quebec and Ontario.
Dermocosmetics denotes skincare formulations developed at the intersection of dermatological science and cosmetic efficacy, typically incorporating active concentrations of niacinamide, retinoids, or azelaic acid within cosmetically elegant bases designed for daily consumer use without prescription oversight. The category serves consumers seeking clinically substantiated solutions for persistent skin concerns beyond basic moisturization. Moisturizers and anti-aging creams occupy the largest revenue pools given their daily-use frequency and premium positioning, while acne treatments represent the fastest-expanding segment driven by post-pandemic maskne awareness and younger demographic entry. E-commerce platforms capture disproportionate growth momentum as direct-to-consumer brands bypass traditional pharmacy gatekeepers, though specialty stores retain margin advantages through personalized consultation services.
Health Canada's Cosmetic Regulations mandate ingredient disclosure and prohibit certain active concentrations, while the Natural Health Products Directorate governs products making therapeutic claims through distinct licensing pathways. The Competition Bureau monitors advertising substantiation, creating compliance costs that favor established players with regulatory affairs infrastructure. Stakeholders must monitor pending amendments to the Food and Drugs Act that could reclassify certain retinoid or hydroquinone formulations, reshaping product portfolios and channel access requirements.
Market Dynamics
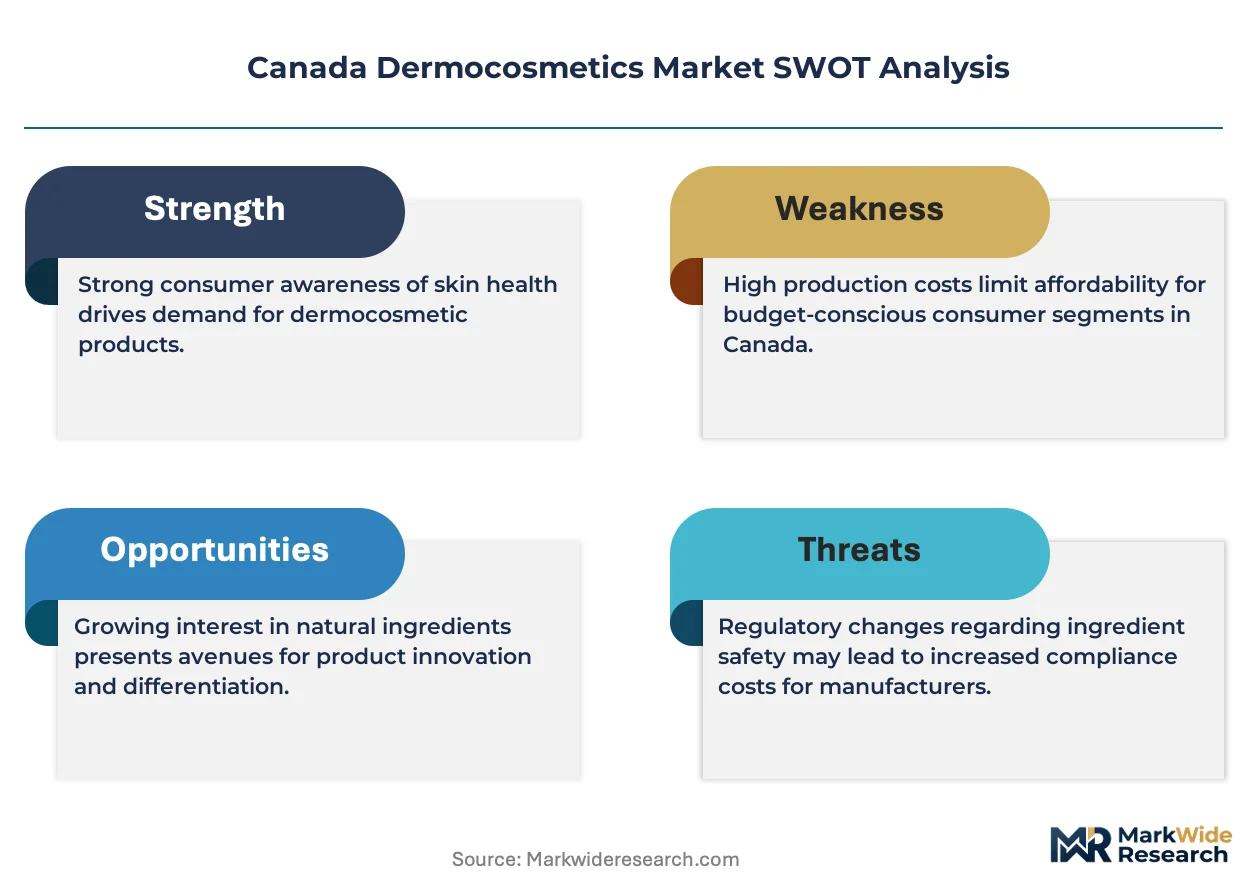
Clinically validated ingredient transparency is compressing traditional cosmetic marketing advantages in Canada as consumers cross-reference Health Canada databases before purchase decisions. This verification behavior rewards manufacturers with robust substantiation dossiers while penalizing heritage brands dependent on aesthetic positioning alone.
Growth Catalysts
- Health Canada Cosmetic Regulations:Mandatory ingredient disclosure builds consumer trust in pharmacy-distributed formulations over general retail alternatives. Regulatory clarity accelerates dermatologist endorsement programs.
- Urban Millennial concentration:Toronto and Montreal consumers prioritize niacinamide and retinoid regimens with published clinical data. This demographic cluster sustains premium pricing for evidence-based products.
- Post-pandemic maskne awareness:Persistent acne concerns among younger Canadians expand azelaic acid and adapalene adoption beyond traditional age demographics. Pharmacy consultation services capture this incremental demand.
Market Restraints
- Active ingredient concentration caps:Health Canada prohibits retinoid strengths available in US and European markets, limiting therapeutic efficacy claims and compressing differentiation space for domestic formulators.
- Quebec bilingual packaging mandates:Groupe Marcelle and domestic competitors absorb dual-label production costs that offshore entrants avoid through Ontario-focused distribution strategies.
- Dermatologist channel concentration:Ontario and Quebec clinic networks control prescription-adjacent recommendation flows, creating gatekeeper dependency for clinical-grade positioning.
Strategic Opportunities
- Atlantic Canada underpenetration:Halifax and St. John's lack dedicated dermocosmetics retail infrastructure. Direct-to-consumer platforms can establish first-mover positioning before pharmacy network expansion.
- Natural Health Products Directorate licensing:Therapeutic claim pathways for sensitive skin and eczema indications offer margin expansion beyond cosmetic classification. Early filers secure category exclusivity windows.
- Tele-dermatology convergence:Virtual consultation platforms in Ontario integrate product recommendation algorithms. Formulation partnerships with digital health providers bypass traditional retail gatekeepers.
Industry Challenges
- Regulatory affairs talent scarcity:Health Canada submission expertise concentrates in Toronto and Montreal. Atlantic and Prairie manufacturers face recruitment premiums or outsourced dependency.
- Clinical substantiation capex:In-vivo efficacy studies for niacinamide and peptide formulations require six-figure investment per claim. Mid-tier brands struggle to match L'Oréal and Pierre Fabre dossier depth.
- Competition Bureau advertising scrutiny:Substantiation challenges against "clinically proven" claims trigger costly legal defense. Smaller players lack compliance infrastructure to preempt enforcement actions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Dermocosmetics Market |
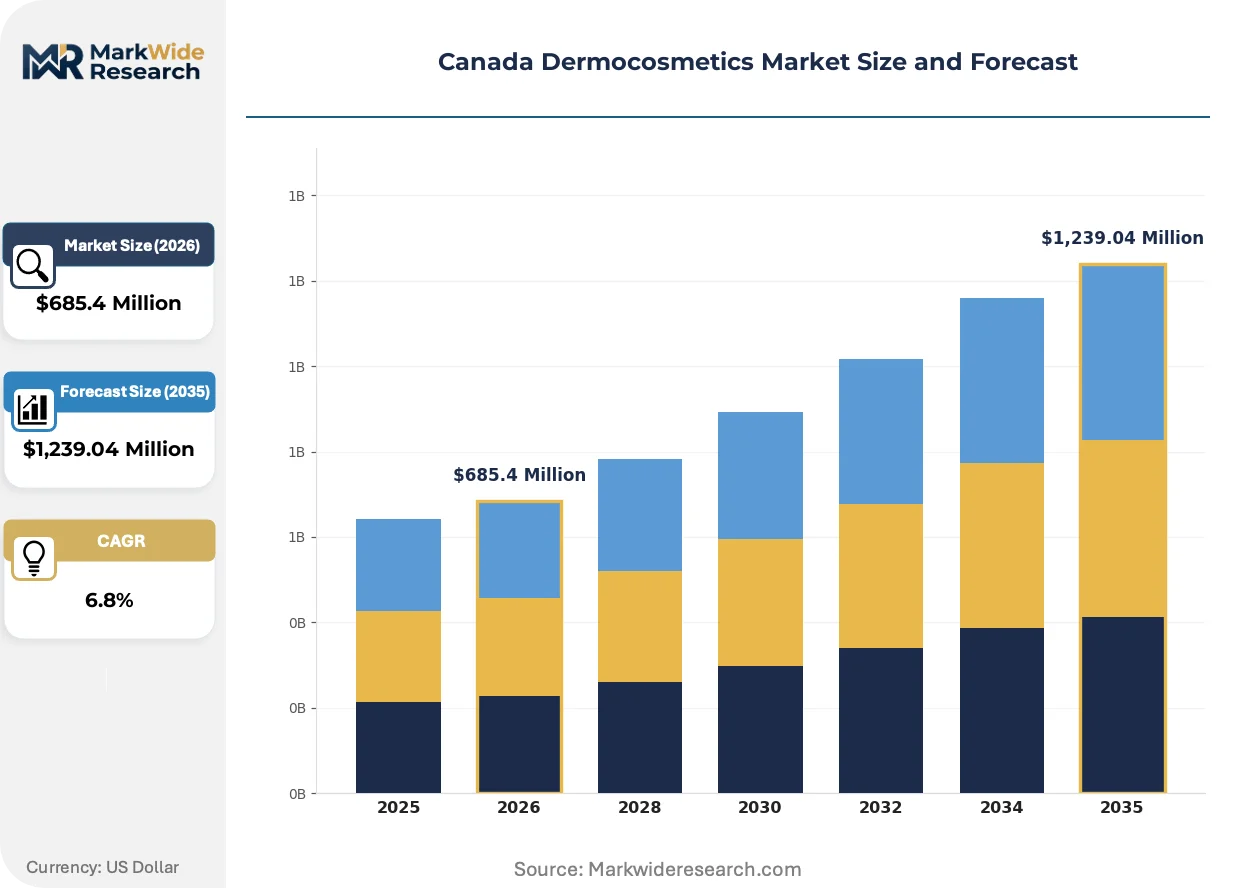
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Moisturizers, Sunscreens, Anti-Aging Creams, Acne Treatments, Skin Lightening Solutions Skin Concern: Dryness, Hyperpigmentation, Wrinkles, Acne, Sensitivity End User: Dermatology Clinics, Beauty Salons, Pharmacies, Online Retailers, Spas Distribution Channel: Specialty Stores, E-commerce Platforms, Direct Sales, Department Stores, Healthcare Facilities |
| Companies Covered | Groupe Marcelle Inc., Pierre Fabre Group, L'Oréal S.A., Chanel Limited, Omy Laboratoires, The Estée Lauder Companies Inc., Coty Inc., Revlon, Inc., Shiseido Company, Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Dermocosmetics Market Trends and Innovations
Biotechnology-derived actives and microbiome science are displacing traditional botanical positioning in Canadian formulation development. Manufacturers now compete on genomic substantiation rather than heritage narratives.
Microbiome-targeted formulations containing postbiotic lysates and prebiotic oligosaccharides is supplanting simplistic pH-balanced marketing in acne and sensitive skin segments. Gen Z consumers in Vancouver and Calgary prioritize these mechanisms over conventional salicylic acid claims. This shift compresses margin for brands without fermentation technology partnerships or in-house screening capabilities.
Health Canada's pending amendments to the Food and Drugs Act signal potential reclassification of hydroquinone and certain retinoid strengths. Cosmetic manufacturers with Natural Health Products Directorate licenses gain transition pathways unavailable to pure cosmetic registrants. Quebec-based formulators accelerate therapeutic claim dossiers to preempt regulatory displacement.
Pharmacy consultation unbundling disrupts traditional dermocosmetics distribution in Ontario and Quebec. Consumers now purchase recommended products through Amazon or brand-direct websites after in-person skin analysis. This disintermediation pressures Shoppers Drug Mart and Jean Coutu to develop exclusive private-label equivalents or subscription loyalty programs to retain basket capture.
Canada Dermocosmetics Market Segmentation
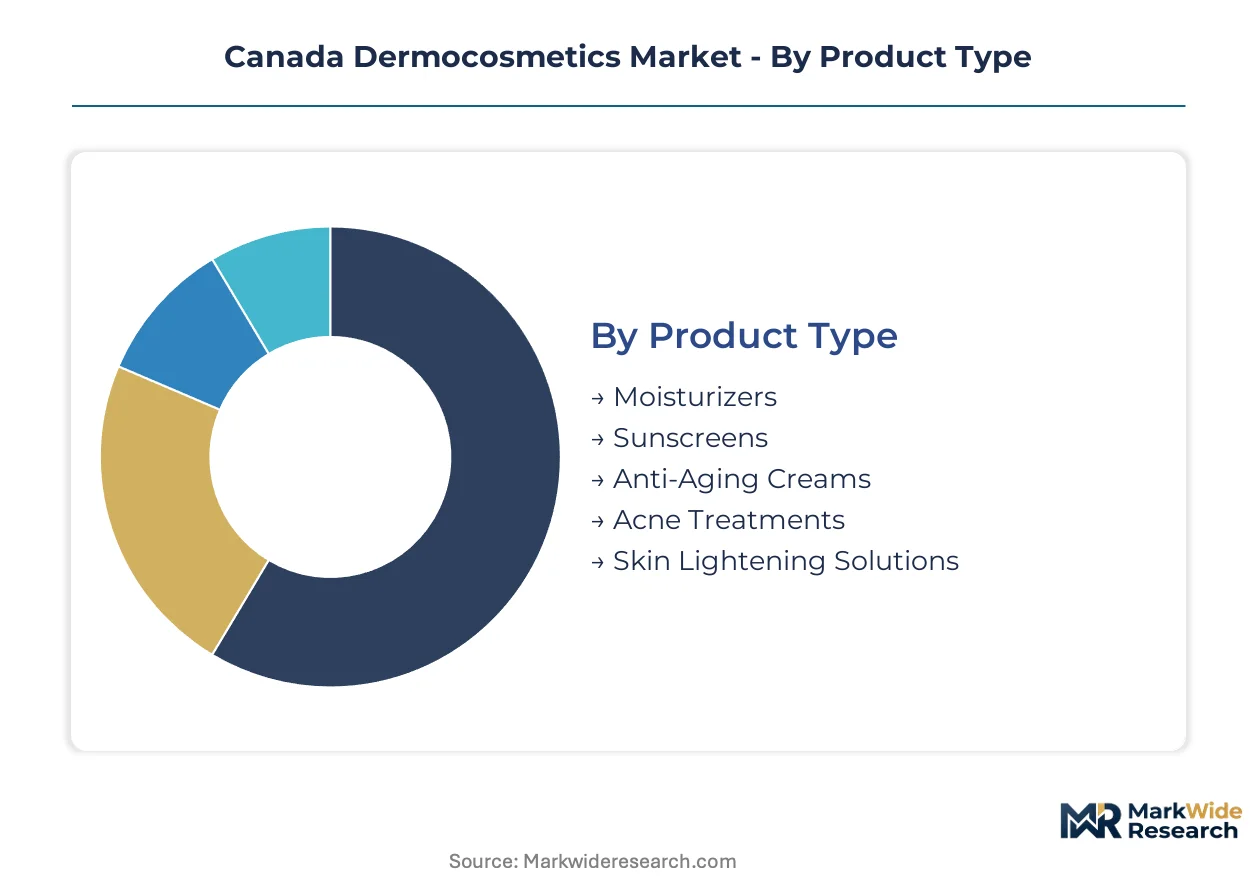
Segmentation in the Canadian dermocosmetics market reveals how regulatory frameworks and channel structures reshape competitive positioning across product categories. Understanding these divisions exposes where Health Canada compliance costs concentrate and where tele-dermatology platforms are disintermediating traditional pharmacy networks.
Product Type:
Domestic manufacturing capacity concentrates on daily-use formulations with established Health Canada registrations, while import-dependent segments face concentration caps that limit therapeutic positioning.
- Moisturizers:Niacinamide and ceramide-based formulations dominate pharmacy shelves with published clinical substantiation. Ontario and Quebec consumers sustain premium pricing through daily replenishment cycles. This segment holds the largest share; momentum sits with acne treatments.
- Sunscreens:Mineral filters and hybrid chemical-physical formulations require distinct PMRA approvals that extend registration timelines. Vancouver and Calgary dermatology clinics drive adoption of photostable zinc oxide variants for post-procedure protocols.
- Anti-Aging Creams:Retinoid strength limitations under Health Canada Cosmetic Regulations compress differentiation against US competitors. Toronto consumers cross-reference concentration databases before purchase.
- Acne Treatments:Azelaic acid and adapalene formulations expand fastest through post-pandemic maskne awareness among younger demographics.
- Skin Lightening Solutions:Hydroquinone pending reclassification under Food and Drugs Act amendments creates regulatory uncertainty for Quebec formulators.
Moisturizers anchor revenue stability; acne treatments capture expansion velocity through younger entry demographics.
Skin Concern:
Cost tier stratification separates pharmacy-distributed clinical formulations from mass-market alternatives, with substantiation investment determining margin capture.
- Dryness:Barrier repair formulations with ceramide NP and cholesterol ratios dominate winter seasonal demand cycles. Prairie provinces sustain volume through extended heating-season application frequency.
- Hyperpigmentation:Tyrosinase inhibitors and acid blends require careful Health Canada concentration compliance. Montreal consumers prioritize visible efficacy timelines over heritage brand loyalty.
- Wrinkles:Peptide complexes and growth factor alternatives attract premium positioning where retinoid caps limit traditional anti-aging claims. Vancouver tele-dermatology platforms recommend these as prescription alternatives.
- Acne:Inflammatory and non-inflammatory subtypes drive distinct formulation architectures, with benzoyl peroxide stability concerns shifting demand toward azelaic acid alternatives.
- Sensitivity:Microbiome-targeted postbiotic formulations command margin premiums through genomic substantiation requirements that smaller brands cannot match.
Dryness concerns generate the highest absolute volume; sensitivity indications produce the steepest margin expansion through therapeutic claim pathways.
End User:
Channel concentration in Ontario and Quebec creates gatekeeper dependency, while Atlantic Canada underpenetration opens direct-to-consumer bypass opportunities.
- Dermatology Clinics:Prescription-adjacent recommendation flows in Toronto and Montreal anchor clinical-grade brand positioning. Consultation fees subsidize product margin capture.
- Beauty Salons:Post-facial retail capture depends on aesthetician training programs that L'Oréal and Pierre Fabre sponsor for proprietary protocol integration.
- Pharmacies:Shoppers Drug Mart and Jean Coutu networks control mass-market dermocosmetics access, though consultation unbundling pressures basket retention.
- Online Retailers:Amazon and brand-direct websites disintermediate pharmacy gatekeepers after virtual skin analysis completion.
- Spas:Thermal spring water heritage brands leverage Quebec distribution infrastructure for premium experiential positioning.
Pharmacies retain volume leadership; online retailers expand most quickly through tele-dermatology convergence.
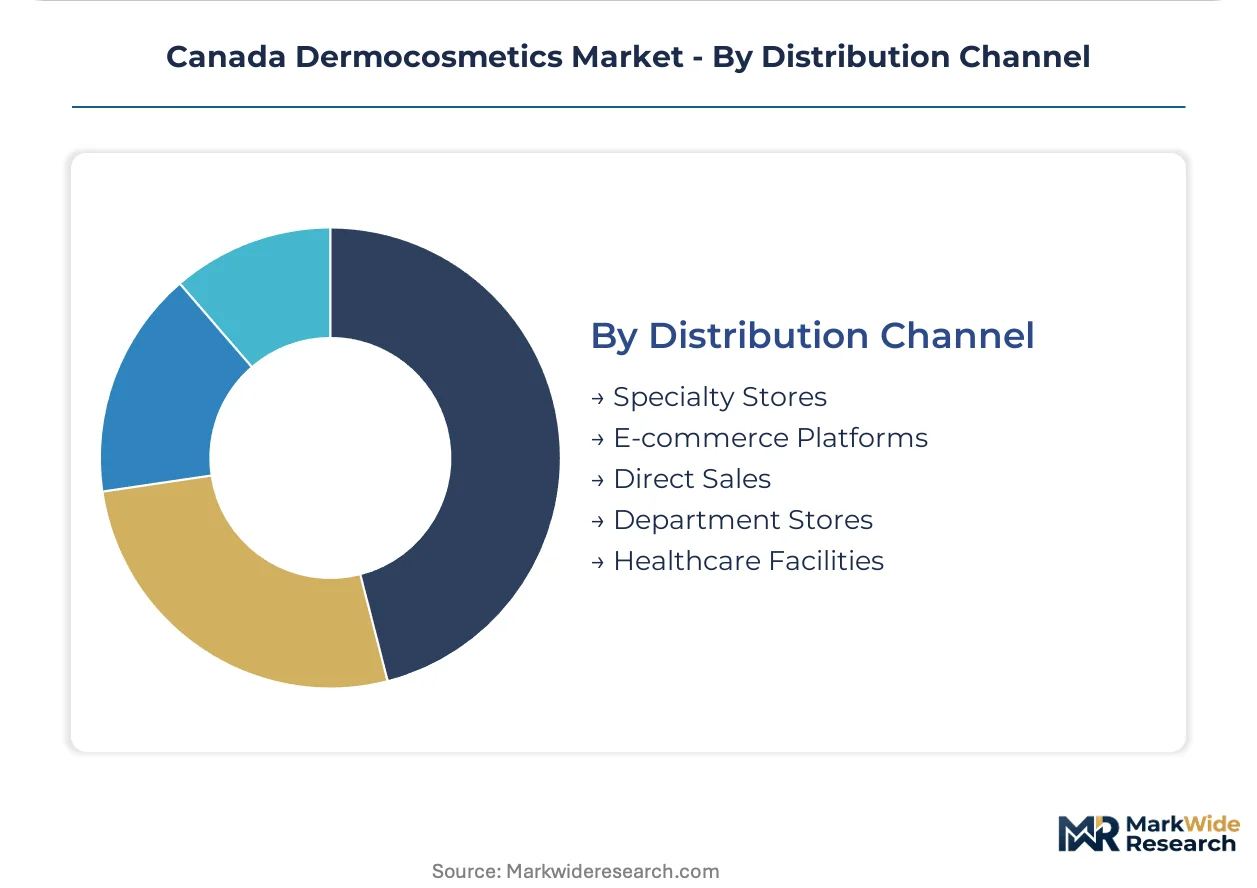
Distribution Channel:
Customer type fragmentation separates informed cross-referencing consumers from consultation-dependent purchasers, reshaping marketing investment allocation.
- Specialty Stores:Personalized skin analysis services retain margin advantages through exclusive brand access and aesthetician consultation depth. Montreal flagship locations anchor Quebec market development.
- E-commerce Platforms:Direct-to-consumer brands bypass bilingual packaging mandates through Ontario-focused fulfillment, avoiding Quebec regulatory complexity.
- Direct Sales:Subscription loyalty programs and replenishment algorithms capture recurring revenue from niacinamide and retinoid regimen adherents.
- Department Stores:Heritage cosmetic counters face compression as clinically validated transparency rewards pharmacy and specialty channel migration.
- Healthcare Facilities:Hospital-affiliated dermatology departments in Toronto and Vancouver integrate product dispensing with procedural protocols.
Specialty stores command premium positioning; e-commerce platforms gain share fastest through algorithmic personalization and subscription retention mechanics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ontario and Quebec concentrate pharmacy-distributed dermocosmetics consumption through dense dermatology clinic networks, while Alberta and British Columbia favor direct-to-consumer platforms with higher tele-dermatology penetration.
Ontario
Toronto consumers cross-reference Health Canada ingredient databases before purchasing niacinamide and retinoid formulations. The province's Cosmetic Regulations enforcement creates compliance cost advantages for established players with regulatory affairs infrastructure. L'Oréal S.A. anchors its pharmacy-centric distribution through Shoppers Drug Mart's provincial network dominance.
Quebec
Montreal's bilingual consumer base sustains Groupe Marcelle Inc.'s domestic manufacturing flexibility through dual-label production requirements. Health Canada's Natural Health Products Directorate licensing activity concentrates in this province for therapeutic claim pathways. Pierre Fabre Group leverages thermal spring water heritage through Jean Coutu's retail network and dermatologist endorsement programs.
British Columbia
Vancouver tele-dermatology platforms integrate product recommendation algorithms that bypass traditional pharmacy gatekeepers. The province's younger demographic skew drives microbiome-targeted postbiotic adoption ahead of national averages. Omy Laboratoires captures this channel shift through direct-to-consumer personalization services.
Alberta
Calgary's post-pandemic maskne awareness expands azelaic acid demand among younger consumers entering clinical skincare regimens. The province lacks dedicated dermocosmetics retail infrastructure compared to Ontario and Quebec. Direct sales subscription models capture recurring revenue from retinoid regimen adherents in this underpenetrated market.
Atlantic Canada
Halifax and St. John's present first-mover opportunities for e-commerce platforms before pharmacy network expansion reaches these markets. Health Canada regulatory affairs talent scarcity creates recruitment premiums for manufacturers considering regional production. The Estée Lauder Companies Inc. tests algorithmic personalization in these lower-competition environments.
Canada Dermocosmetics Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Canada's dermocosmetics structure. L'Oréal S.A. and Pierre Fabre Group anchor the upper tier through dermatological heritage and pharmacy network control. Mid-tier domestic players compete on manufacturing flexibility and bilingual marketing reach. Strategic moves concentrate on tele-dermatology platform partnerships and Natural Health Products Directorate licensing for therapeutic claim expansion.
Within the integrated multinational tier, L'Oréal S.A. and Pierre Fabre Group represent pharmacy-centric distribution archetypes with established Health Canada compliance infrastructure. Groupe Marcelle Inc. occupies a distinct position as a domestic specialist leveraging Quebec manufacturing proximity and bilingual packaging capabilities. Among premium heritage players, Chanel Limited and Shiseido Company, Limited exemplify aesthetic-positioning strategies facing compression from clinically validated transparency demands. Coty Inc. and Revlon, Inc. sit within mass-market segments where ingredient disclosure requirements challenge traditional marketing advantages.
| Leading Market Players |
|---|
| Groupe Marcelle Inc. |
| Pierre Fabre Group |
| L'Oréal S.A. |
| Chanel Limited |
| Omy Laboratoires |
| The Estée Lauder Companies Inc. |
| Coty Inc. |
| Revlon, Inc. |
| Shiseido Company, Limited |
| Others |
Pricing and Supply Chain Analysis
Health Canada's Cosmetic Regulations and Natural Health Products Directorate licensing pathways gate both manufacturing qualification and price differentiation simultaneously, as compliance infrastructure requirements separate established pharmacy-distributed players from general retail alternatives while concentration caps on retinoids and pending hydroquinone reclassification compress therapeutic claim premiums.
Pricing Analysis
Long-term offtake agreements between L'Oréal S.A., Pierre Fabre Group, and Shoppers Drug Mart pharmacy networks anchor volume commitments that stabilize ingredient procurement costs against spot market volatility for niacinamide and ceramide actives. Three-tier pricing structure across premium dermatology clinic formulations, standard pharmacy retail, and mass-market alternatives reflects certification depth and consultation bundling rather than raw material cost alone. Cost compression in the premium tier is intensifying as tele-dermatology platforms disintermediate consultation fees and redirect margin to algorithmic personalization providers. Price sensitivity concentrates among Atlantic Canada consumers where pharmacy network underpenetration forces direct-to-consumer brands to compete on subscription value rather than heritage positioning.
Supply Chain Analysis
France and the United States anchor active ingredient production for retinoid and peptide formulations consumed in Canadian dermocosmetics manufacturing, while domestic Quebec facilities handle final formulation and bilingual packaging compliance. Raw material dependencies rest on Korean fermentation technology partnerships for postbiotic lysates, Swiss peptide synthesis capabilities, and Indian botanical extract supplies for heritage-positioned brands. Single-source vulnerability concentrates in Health Canada regulatory affairs talent pools located exclusively in Toronto and Montreal, creating recruitment premiums that Atlantic and Prairie manufacturers must absorb or outsource. Distribution runs through pharmacy-centric networks in Ontario and Quebec, with direct-to-consumer platforms capturing incremental share in British Columbia and Alberta through tele-dermatology convergence.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canada's dermocosmetics sector sits at a high-growth inflection as pending Food and Drugs Act amendments threaten to reclassify hydroquinone and certain retinoid strengths, forcing cosmetic manufacturers toward Natural Health Products Directorate therapeutic licensing or portfolio displacement.
For Market Incumbents: Secure Natural Health Products Directorate licenses for sensitive skin and eczema indications before regulatory displacement windows close, while deepening dermatologist endorsement programs in Toronto and Montreal clinic networks to maintain prescription-adjacent recommendation flows against tele-dermatology platform disintermediation. Backward integration into Quebec-based manufacturing capacity mitigates bilingual packaging mandate costs that offshore competitors avoid. For New Entrants and Emerging Players: Lead with Atlantic Canada e-commerce first-mover positioning in Halifax and St. John's before pharmacy network expansion reaches these underpenetrated markets, targeting microbiome-targeted postbiotic formulations where genomic substantiation requirements filter out heritage brands lacking fermentation technology partnerships. Algorithmic personalization services bypass traditional retail gatekeeper dependency entirely. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across clinical substantiation capabilities as in-vivo efficacy studies for peptide and niacinamide claims require six-figure investment per claim that mid-tier brands cannot match. Acquisition targets should demonstrate existing Health Canada submission dossiers or Natural Health Products Directorate licensing progress rather than pure cosmetic registrations. The signal to watch is Health Canada enforcement action frequency against "clinically proven" advertising claims, which would accelerate compliance cost concentration among established players.| Strategic Initiative | Industry Significance |
|---|---|
| Natural Health Products Directorate Licensing | Therapeutic claim pathways for eczema and sensitive skin indications unlock margin expansion unavailable to pure cosmetic registrants. |
| Tele-Dermatology Platform Partnership | Algorithmic product recommendation integration bypasses Shoppers Drug Mart and Jean Coutu pharmacy gatekeeper control. |
| Microbiome Formulation Development | Postbiotic lysate capabilities command premium positioning as Gen Z consumers prioritize genomic substantiation over conventional acid claims. |
| Quebec Manufacturing Footprint Expansion | Domestic production flexibility absorbs bilingual packaging mandate costs that Ontario-focused offshore entrants avoid. |
| Direct-to-Consumer Subscription Launch | Replenishment algorithms capture recurring revenue from niacinamide and retinoid regimen adherents in underpenetrated Prairie and Atlantic markets. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with dermatology clinic directors, pharmacy category buyers at Shoppers Drug Mart and Jean Coutu, regulatory affairs specialists with Health Canada submission experience, brand managers at domestic and multinational manufacturers, and tele-dermatology platform operators. Secondary validation drew from Health Canada Cosmetic Regulations enforcement databases, Natural Health Products Directorate licensing records, PMRA sunscreen approval timelines, Nielsen retail audit data for pharmacy channel performance, and Competition Bureau advertising substantiation case files. Bottom-up demand modeling across patient population segments and top-down market sizing from manufacturer revenue disclosures were triangulated to establish segment boundaries.
Across the analysis window, the quantitative framework modeled product type segmentation by formulation complexity and registration pathway, skin concern segmentation by therapeutic claim eligibility, end-user channel concentration by province, and distribution method by consultation dependency versus algorithmic personalization. CAGRs were derived from regression analysis of historical pharmacy dispensing data and e-commerce platform growth trajectories, with inputs including dermatology clinic density projections, tele-dermatology platform user acquisition rates, and Health Canada regulatory amendment implementation timelines.
Forecasts assume regulatory continuity in Health Canada Cosmetic Regulations and Natural Health Products Directorate frameworks; material policy shifts such as accelerated Food and Drugs Act reclassification or PMRA sunscreen filter restrictions would require re-modeling. Recalibration cycles align with material shifts in Health Canada enforcement patterns, tele-dermatology platform market share inflections, and Natural Health Products Directorate licensing volume trends.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Pore Strips Market
Beauty & Personal Care
Beauty Pillowcases Market
Beauty & Personal Care
Saudi Arabia Eyelash Serum Market
Beauty & Personal Care
United Kingdom Hair Care Market
Beauty & Personal Care
UV Nail Gel Lamp Market
Beauty & Personal Care
Hair Styling Equipment Market
Beauty & Personal Care
Personal Care Contract Manufacturing Market
Beauty & Personal Care
Facial Care Market
Beauty & Personal Care
Nail Care Market
Beauty & Personal Care
Japan Aromatherapy Products Market
Beauty & Personal Care
Europe Shampoo Market
Beauty & Personal Care
Sustainable Personal Care Market
Beauty & Personal Care
Europe and Asia Pacific Herbal Beauty Products Market
Beauty & Personal Care
Hair Salon Equipment Market
Beauty & Personal Care
Makeup Setting Spray Market
Beauty & Personal Care
Pre-Shave Care Market