
 Australia Skin Care Products Market | 2026-2036
Australia Skin Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Skin Care Products Market Outlook
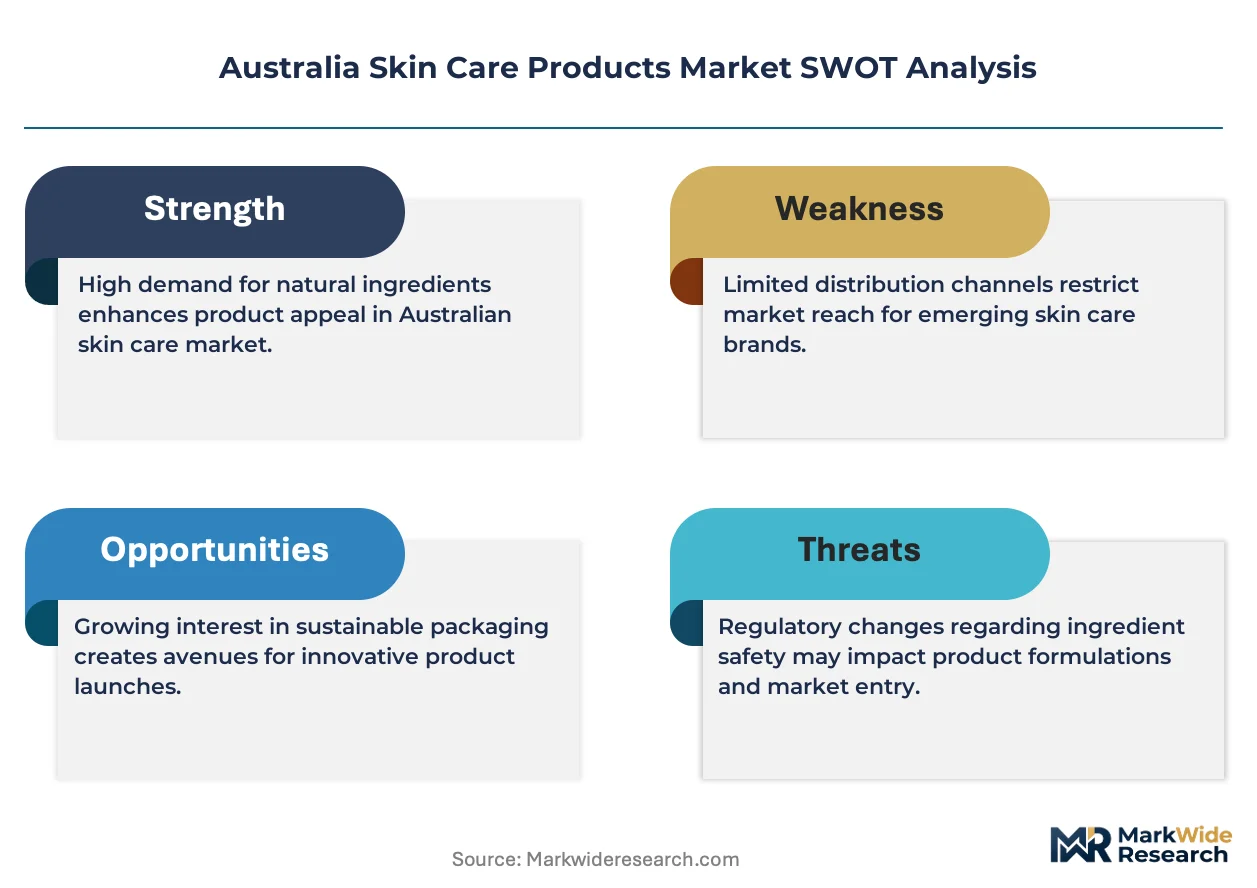
The Australian Competition and Consumer Commission's intensified scrutiny of green marketing claims is decoupling superficial sustainability branding from genuine formulation transparency. L'Oréal SA anchors its position through captive biotechnology research on native botanical extracts. Beiersdorf AG differentiates via dermatological testing protocols aligned with TGA guidelines. Estée Lauder Companies Inc. controls premium department-store distribution channels across Sydney and Melbourne.
Australia skin care products comprise topical formulations designed for epidermal maintenance, including emulsions with specified SPF ratings, lipid-based barrier creams, and active-ingredient serums containing retinoids or ascorbic acid above threshold concentrations. Moisturizers occupy the largest volume share due to daily-use frequency across age demographics, while sunscreens command premium pricing driven by Australia's extreme UV index standards and TGA-regulated SPF certification requirements. Natural and organic ingredient segments attract margin-rich positioning as consumers scrutinize INCI lists against the ACCC's anti-greenwashing enforcement.
TGA regulates therapeutic sunscreens and therapeutic claims on cosmeceuticals, while the ACCC enforces consumer protection against misleading environmental representations, and Standards Australia maintains ISO 16128-aligned natural and organic cosmetic criteria. Compliance costs favor larger multinationals with dedicated regulatory affairs teams, compressing mid-tier brand viability. Stakeholders must monitor pending reforms to cosmetic ingredient transparency rules and assess whether reformulation investments or portfolio pruning better preserves returns.
Market Dynamics
The Australian Competition and Consumer Commission's enforcement against greenwashing claims is forcing brands to substantiate every environmental assertion with verified supply-chain documentation, compressing marketing lead times and elevating compliance costs above R&D budgets.
Growth Catalysts
- UV Index Standards:Australia's extreme solar exposure mandates daily SPF application, creating perpetual replenishment cycles for TGA-certified sunscreens across all age demographics.
- Native Botanical Research:Biotechnology platforms extracting bioactive compounds from Kakadu plum and finger lime are accelerating clean-label serum development pipelines.
- Millennial Purchasing Power:Sydney and Melbourne consumers aged 25-40 are prioritizing INCI transparency over brand heritage, rewarding reformulation investments with loyalty premiums.
Market Restraints
- Ingredient Import Dependency:Active compounds including niacinamide and hyaluronic acid concentrate in Chinese and Korean manufacturing clusters, exposing margins to freight volatility and currency fluctuation.
- TGA Compliance Burden:Therapeutic sunscreen registration timelines extend 18-24 months, freezing product pipelines for mid-tier brands lacking dedicated regulatory affairs teams.
- Biomass Substitution Threat:Synthetic retinoid alternatives from laboratory fermentation are achieving cost parity with plant-derived vitamin A, pressuring natural-positioned pricing premiums.
Strategic Opportunities
- Queensland Expansion:Brisbane and Gold Coast retail corridors remain underpenetrated by premium dermatological brands, offering first-mover positioning before saturation mirrors Sydney-Melbourne intensity.
- Telehealth Integration:Virtual skin consultations are creating direct-to-consumer prescription pathways for cosmeceutical-grade retinoids, bypassing traditional pharmacy distribution.
- ACCC Transparency Alignment:Early adoption of blockchain-verified ingredient provenance systems satisfies impending disclosure mandates while commanding price premiums from skeptical consumers.
Industry Challenges
- Formulation Chemistry Talent Gap:Cosmetic chemists with TGA submission experience command salaries exceeding mid-tier brand budgets, constraining in-house innovation capacity.
- Packaging Reconfiguration Costs:Transitioning to mono-material or refillable formats requires capital-intensive mold retooling and supply chain renegotiation with Asian converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Skin Care Products Market |
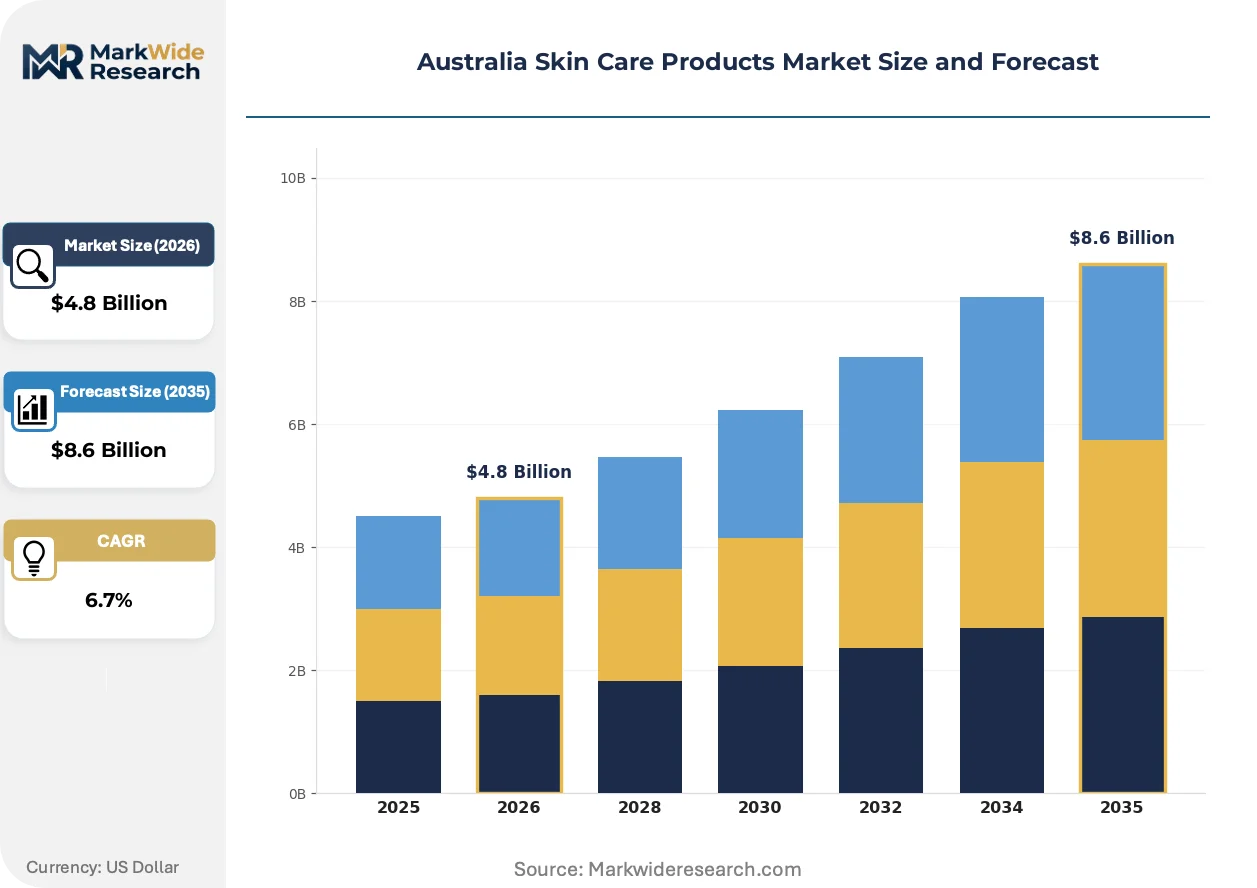
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Moisturizers, Cleaners, Sunscreens, Serums Gender: Women, Men, Unisex, Kids Ingredients: Natural, Organic, Chemical-Based, Synthetic Price Tier: Premium, Mid-Range, Budget, Discount |
| Companies Covered | Estée Lauder Companies Inc., Shiseido Company Limited, L'Oréal SA, Kao Corporation, Kenvue Inc., Unilever PLC, Beiersdorf AG, Galderma S.A., Procter & Gamble Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Skin Care Products Market Strategic Shifts
Biotechnology extraction methods and regulatory disclosure mandates are converging to redefine competitive advantage, rewarding brands that integrate laboratory verification with consumer-facing transparency tools.
Biotechnology-derived native Australian botanical extracts is absorbing capital from traditional solvent-based extraction as L'Oréal SA and domestic competitors establish captive research facilities in Melbourne. The technology reduces batch-to-batch variability in ascorbic acid concentration while satisfying ACCC substantiation requirements for "Australian-made" claims. This absorption is compressing shelf space for imported generic serums lacking provenance documentation.
TGA's evolving cosmetic ingredient disclosure requirements are extending pre-market notification timelines for therapeutic sunscreens and cosmeceuticals containing retinoids above threshold concentrations. Domestic brands with established regulatory affairs infrastructure are absorbing these delays as competitive moats, while imported entrants face portfolio pruning decisions. The policy shift most impacts Korean and French brands dependent on fast-cycle innovation models.
Clean-label scrutiny among Australian millennials and Gen Z consumers is rotating purchase authority from department-store beauty advisors toward independently verified ingredient databases. Sydney and Melbourne shoppers now cross-reference INCI lists against EWG Skin Deep and ACCC complaint registers before completing transactions. This behavioral pivot is compressing brand loyalty cycles and elevating third-party certification premiums above traditional advertising spend effectiveness.
Australia Skin Care Products Market Segmentation
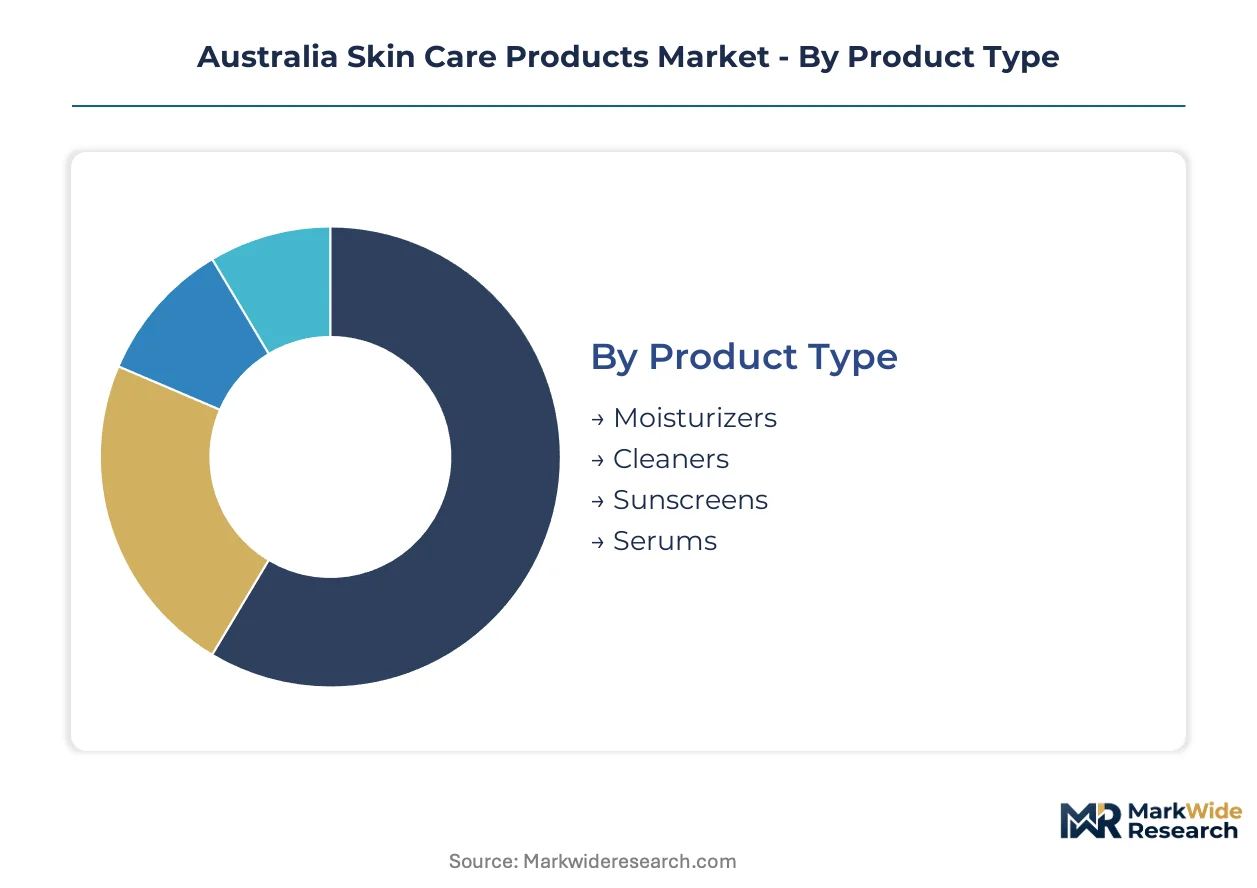
Segmentation in the Australian skin care market exposes where TGA compliance costs and ACCC transparency mandates concentrate competitive advantage. Understanding how product types, gender targeting, ingredient positioning, and price tiers fragment demand reveals which configurations absorb margin pressure and which face portfolio pruning.
Product Type:
Supply concentration among TGA-certified manufacturers favors segments with therapeutic registration infrastructure, while fast-cycle cosmetic categories face margin compression from import dependency.
- Moisturizers:Emulsion-based formulations with ceramide and hyaluronic acid matrices dominate daily-use frequency across all Australian demographics. New South Wales and Victoria households replenish these products on 4-6 week cycles, though Korean and Chinese ingredient sourcing exposes margins to freight volatility.
- Sunscreens:Therapeutic SPF formulations require 18-24 month TGA registration timelines that freeze pipelines for mid-tier brands lacking dedicated regulatory affairs teams. Australia's extreme UV index standards create perpetual replenishment demand, but compliance infrastructure acts as a competitive moat favoring established domestic and multinational players.
- Cleaners:Surfactant-based and micellar formulations target makeup removal and pollution defense for urban Sydney and Melbourne consumers.
- Serums:Concentrated active-ingredient formulations with retinoid or ascorbic acid thresholds attract clean-label scrutiny from millennial purchasers cross-referencing INCI lists.
Today's leader: Sunscreens. Tomorrow's challenger: Serums.
Gender:
Application intensity varies sharply by gender segment, with male-targeted products still underpenetrated despite rising grooming normalization among Australian millennials.
- Women:Multi-step regimen adherence drives the highest per-capita spend and category breadth, spanning preventive anti-aging through corrective pigmentation treatments. Sydney and Melbourne department-store distribution concentrates premium positioning here, though independent verification databases are eroding traditional beauty-advisor influence.
- Men:Simplified two-step routines (cleanser plus moisturizer) dominate, but beard-care adjacencies and sunscreen compliance are expanding addressable spend. Brisbane and Gold Coast retail corridors show underpenetration relative to female-skewed Sydney-Melbourne intensity.
- Unisex:Clean-label positioning and minimalist packaging appeal to cohabiting millennials seeking cabinet consolidation.
- Kids:Fragrance-free and mineral-sunscreen formulations align with parental scrutiny of pediatric skin sensitivity.
Women anchor current revenue. Men represent the steepest expansion trajectory as grooming normalization accelerates.
Ingredients:
Margin structure inverts sharply between certified natural positioning and synthetic alternatives achieving cost parity through laboratory fermentation.
- Natural:Native Australian botanical extracts from Kakadu plum and finger lime command price premiums when provenance is blockchain-verified against ACCC disclosure mandates. Biotechnology extraction platforms reduce batch-to-batch variability while satisfying substantiation requirements.
- Organic:Standards Australia ISO 16128-aligned certification requires supply-chain documentation that compresses marketing lead times but rewards early adopters with skeptical consumer loyalty.
- Chemical-Based:Niacinamide and hyaluronic acid concentrates depend on Chinese and Korean manufacturing clusters, exposing formulations to currency fluctuation.
- Synthetic:Laboratory-fermented retinoid alternatives are achieving cost parity with plant-derived vitamin A, pressuring natural-positioned pricing premiums.
Natural claims dominate premium shelf space. Synthetic alternatives are climbing fastest on cost convergence.
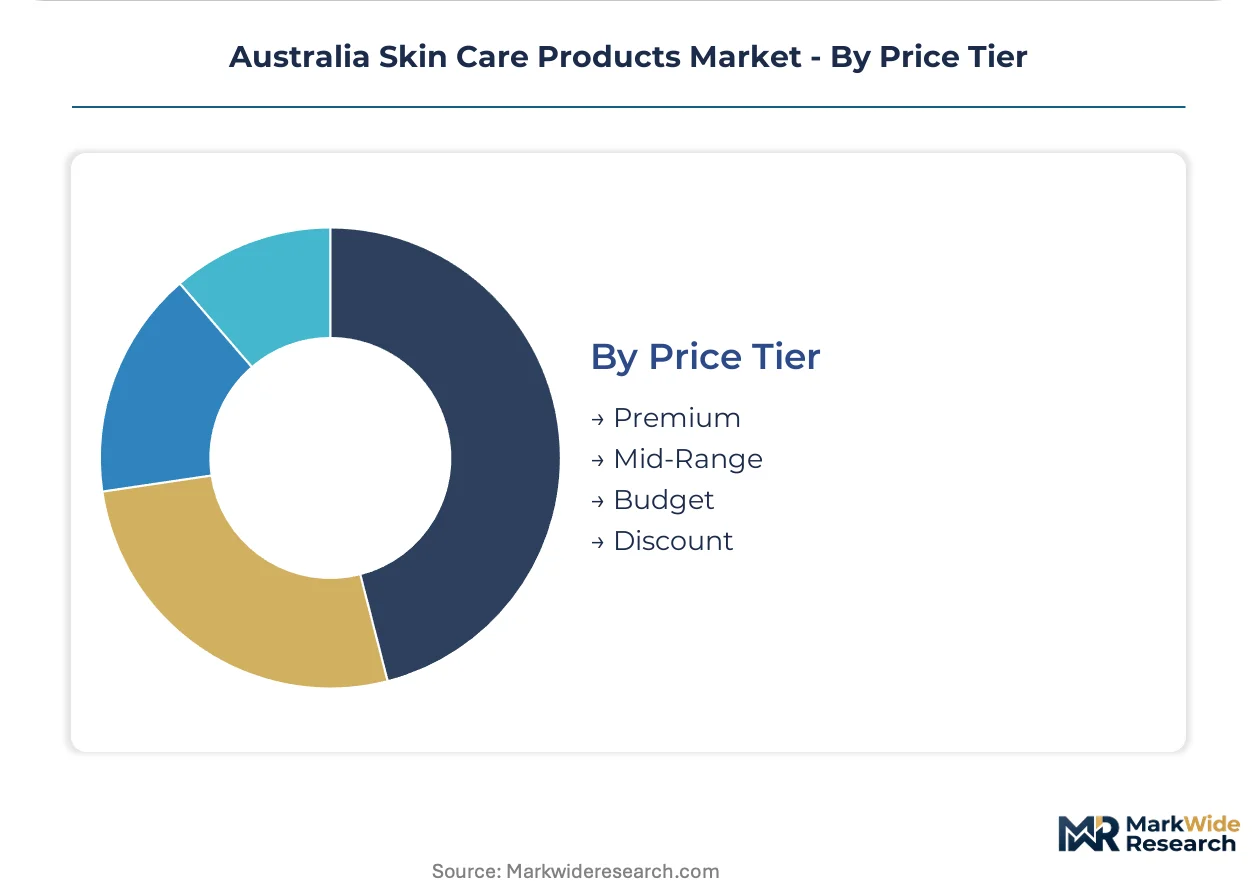
Price Tier:
Customer type stratification reflects how ACCC anti-greenwashing enforcement has decoupled superficial sustainability branding from genuine formulation transparency.
- Premium:Department-store distribution across Sydney and Melbourne supports margin-rich positioning for dermatologically tested formulations with TGA-aligned protocols. INCI transparency and third-party certification now outweigh brand heritage in purchase authority.
- Mid-Range:Pharmacy and specialty retail channels balance accessibility with ingredient quality claims, though reformulation investments to meet evolving disclosure rules are elevating compliance costs above R&D budgets.
- Budget:Mass-market retail penetration depends on volume scale, but import dependency for active compounds constrains margin flexibility.
- Discount:Price-driven purchasing concentrates in value-oriented retail formats with minimal service attachment.
Premium tier absorbs compliance investment. Mid-Range faces the most intense margin squeeze from simultaneous transparency and cost pressures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia's skin care industry traces its modern commercial lineage to post-war Sydney and Melbourne, where European pharmaceutical traditions merged with local botanical knowledge to establish formulation standards that now govern the national market.
New South Wales
Sydney's affluent eastern suburbs and North Shore drive premium serum and sunscreen replenishment cycles among millennial professionals. TGA's therapeutic sunscreen registration requirements concentrate compliance infrastructure in Parramatta and Macquarie Park corporate clusters. The city's department-store distribution networks anchor Estée Lauder and L'Oréal's premium positioning.
Victoria
Melbourne's inner-north and bayside municipalities exhibit the highest per-capita spend on clean-label facial treatments and dermatologically tested moisturizers. ACCC enforcement against greenwashing claims has elevated demand for blockchain-verified ingredient provenance systems among St Kilda and Fitzroy consumers. Biotechnology research facilities in Parkville support native botanical extraction platforms.
Queensland
Brisbane and Gold Coast retail corridors remain underpenetrated by premium dermatological brands relative to Sydney-Melbourne intensity. Extreme UV exposure drives perpetual sunscreen demand, though therapeutic registration timelines delay new entrant pipelines. The state's northern latitude amplifies mineral-SPF preference among outdoor-active demographics.
Western Australia
Perth's isolated metropolitan market depends on air-freighted inventory from eastern distribution centers, elevating landed costs for Korean and Chinese ingredient-dependent formulations. Mining-sector incomes sustain premium-tier purchasing despite geographic distance from TGA regulatory affairs clusters. Local consumers prioritize high-SPF daily wear given southwestern Australia's extreme solar index.
Australia Skin Care Products Market Competitive Environment
Premium-margin players sit above commodity-margin players across regulatory compliance infrastructure, with TGA therapeutic registration capabilities and ACCC substantiation systems defining tier boundaries. The market consolidates around multinational incumbents with dedicated regulatory affairs teams, while mid-tier brands face portfolio pruning from extended pre-market timelines. Three archetypes dominate: biotechnology-integrated native extract specialists, dermatological protocol adherents, and mass-market scale operators. Competitive moves concentrate on captive research facility establishment and blockchain-verified supply chain documentation.
Within the biotechnology-integrated tier, L'Oréal SA anchors positioning through Melbourne-based native botanical research infrastructure. Beiersdorf AG exemplifies dermatological protocol alignment with TGA guidelines, while Estée Lauder Companies Inc. occupies premium department-store distribution control across Sydney and Melbourne. These three multinationals represent distinct competitive vectors—research captiveization, regulatory integration, and channel dominance—that compress viability for entrants lacking comparable resource deployment.
| Leading Market Players |
|---|
| Estée Lauder Companies Inc. |
| Shiseido Company Limited |
| L'Oréal SA |
| Kao Corporation |
| Kenvue Inc. |
| Unilever PLC |
| Beiersdorf AG |
| Galderma S.A. |
| Procter & Gamble Company |
| Others |
Value Chain & Pricing Dynamics
Captive biotechnology research infrastructure anchors both supply security and premium pricing power for leading Australian skin care manufacturers. L'Oréal SA's Melbourne-based native botanical extraction facilities insulate ingredient costs from freight volatility while supporting margin-rich positioning for Kakadu plum and finger lime formulations.
Pricing Analysis
Premium-mid-economy pricing differentiation stratifies across certification grade and provenance verification intensity. TGA therapeutic registration status and blockchain-verified Australian-made claims command substantial premiums from Sydney and Melbourne consumers. Cost compression in the mid-range tier intensifies because reformulation investments to meet ACCC disclosure mandates are elevating compliance costs above R&D budgets. Budget-tier buyers exhibit highest price sensitivity, while premium purchasers prioritize INCI transparency over absolute cost.
Supply Chain Analysis
Direct-to-retail pharmacy channels handle therapeutic sunscreen distribution, while department-store networks manage premium serum and moisturizer placement. Active compound manufacturing concentrates in China and South Korea for niacinamide and hyaluronic acid feedstocks. Biotechnology extraction platforms in Melbourne and Sydney are reducing batch-to-batch variability for native botanicals. Single-source vulnerability for Korean ingredient clusters exposes margins to currency fluctuation and logistics disruption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Australian skin care rests on biotechnology-derived ingredient cost convergence and premium-tier consumer willingness to pay for verified provenance. Reformulation investments that satisfy impending TGA disclosure mandates will separate viable players from portfolio casualties.
For Market Incumbents: Hedge against synthetic retinoid cost parity by accelerating captive extraction capacity for Kakadu plum and finger lime bioactives. Deepen regulatory affairs infrastructure in Parramatta and Macquarie Park corporate clusters to absorb extended TGA therapeutic registration timelines as competitive moats. Defensive patent filings on biotechnology extraction methods will constrain fast-follower entry. For New Entrants and Emerging Players: Telehealth-integrated dermatology platforms offer the most penetrable channel for cosmeceutical-grade retinoid distribution, bypassing traditional pharmacy gatekeepers. Queensland's Brisbane and Gold Coast retail corridors present white-space positioning before saturation mirrors Sydney-Melbourne intensity. Early ACCC transparency alignment through blockchain-verified ingredient provenance systems commands price premiums from skeptical millennial purchasers. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier brands with established TGA regulatory affairs infrastructure because compliance cost concentration is compressing independent viability. Brands with therapeutic sunscreen registrations and native botanical extraction partnerships represent priority acquisition profiles. Watch for synthetic retinoid laboratory-fermentation cost curves as the inflection signal for natural-positioned pricing premium erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Biotechnology Research Facility Establishment | Melbourne-based extraction platforms reduce dependency on Chinese and Korean active compound imports. |
| TGA Therapeutic Registration Pipeline Investment | Eighteen-to-twenty-four month approval timelines freeze competitor pipelines for mid-tier brands. |
| Blockchain-Verified Ingredient Provenance System | ACCC-aligned transparency tools command loyalty premiums from INCI-scrutinizing Sydney consumers. |
| Telehealth-Integrated Direct-to-Consumer Launch | Virtual skin consultations create prescription pathways for cosmeceutical-grade retinoids outside pharmacy distribution. |
| Queensland Retail Corridor Expansion | Brisbane and Gold Coast underpenetration offers first-mover positioning before saturation intensifies. |
Study Parameters
Coverage spans New South Wales, Victoria, Queensland, and Western Australia, with primary inputs from each state. The research combines interviews with brand managers, category buyers at pharmacy and department-store retailers, cosmetic formulation chemists, and TGA regulatory affairs specialists with secondary validation. Secondary sources include TGA therapeutic product registrations, ACCC complaint registers, Standards Australia ISO 16128 certification databases, and customs import records for active compound flows. Bottom-up demand modeling and top-down market sizing triangulate volume and value estimates.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include product type, gender targeting, ingredient positioning, price tier, and state-level geographic cluster. CAGRs derive from trend extrapolation of replenishment cycle frequencies, premium-tier share shifts, and regulatory compliance cost absorption patterns. Biotechnology extraction capacity expansion and synthetic retinoid cost convergence curves inform industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to TGA disclosure mandate timing, ACCC enforcement intensity against greenwashing claims, and Korean-Chinese ingredient supply disruption. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Germany Beauty Industry Market
Beauty & Personal Care
Makeup Brushes Market
Beauty & Personal Care
Underarm Antiperspirant and Deodorant Market
Beauty & Personal Care
Europe Professional Beauty Services Market
Beauty & Personal Care
Global Organic Personal Care Products Market
Beauty & Personal Care
Coffee Beauty Products Market
Beauty & Personal Care
Salon Products Market
Beauty & Personal Care
Beauty Pillowcases Market
Beauty & Personal Care
Pre-Shave Care Market
Beauty & Personal Care
Australia Beauty and Personal Care Products Market
Beauty & Personal Care
India Herbal Shampoo Market
Beauty & Personal Care
Leave-In Conditioner Market
Beauty & Personal Care
South Korea Beauty Fridges Market
Beauty & Personal Care
Women Intimate Care Products Market
Beauty & Personal Care
Sunless Tanners Market
Beauty & Personal Care
Global Personal Care Market