
 Faba Beans Market | 2026-2036
Faba Beans Market Size, Share, and Industry Trends Forecast 2026-2036
Faba Beans Market Foresight
Precision dehulling and air-classification technology is reshaping how faba bean protein isolates achieve functional parity with soy and pea equivalents. Cargill Incorporated leverages its North American grain handling infrastructure to secure premium identity-preserved faba bean streams for food ingredient customers. Prairie Fava Ltd differentiates through proprietary cultivar development optimized for protein content and reduced vicine-convicine alkaloid levels. Archer Daniels Midland Company anchors its position via integrated processing capabilities spanning whole bean cleaning through fractionated protein concentrate production.
Faba beans, botanically Vicia faba, are cool-season legumes containing approximately 25-30% protein by dry weight with a balanced amino acid profile notable for lysine richness but methionine limitation; primary industrial purpose centers on human food ingredient applications, animal feed formulation, and emerging plant-protein ingredient streams. Dried faba beans occupy the dominant volume position due to established export infrastructure and multi-year storage stability, while processed faba beans command margin premiums as protein isolates and textured fractions penetrate meat-alternative formulations. Organic faba beans represent the fastest-expanding product type as European retailers enforce procurement mandates tied to the EU Green Deal farm-to-fork targets.
EU Green Deal agricultural policy frameworks and REACH food-contact material standards collectively elevate compliance burdens for non-European suppliers seeking market access. Health Canada and FDA GRAS self-determination pathways shape divergent timelines for novel protein ingredient approvals across North American jurisdictions. Stakeholders must monitor evolving alkaloid threshold regulations and carbon intensity scoring methodologies that will determine which origin-processor combinations retain preferred supplier status.
Market Dynamics
The EU Green Deal's protein self-sufficiency mandates are redirecting agricultural subsidies toward domestic pulse cultivation, forcing processors to rebuild supply chains around identity-preserved faba bean streams rather than commodity imports.
Growth Catalysts
- EU Green Deal farm-to-fork targets:Procurement mandates from European retailers are accelerating organic faba bean acreage expansion and long-term contracting between processors and growers.
- Precision dehulling technology:Air-classification systems now enable protein isolates to match soy and pea functional parity, opening formulation slots in meat-alternative products.
- German food processor demand:Industrial buyers in Baden-Württemberg and Bavaria are securing multi-year supply agreements for dehulled faba bean fractions to lock in volume.
Market Restraints
- Vicine-convicine alkaloid thresholds:REACH food-contact material standards and evolving EU alkaloid regulations impose compliance burdens that disqualify non-European suppliers lacking testing infrastructure.
- Methionine amino acid limitation:The lysine-rich but methionine-deficient protein profile requires blending with complementary proteins, raising formulation complexity and cost.
- Yellow pea substitution:Established pea protein supply chains with lower alkaloid content and GRAS recognition in North America divert R&D investment from faba bean fractionation.
Strategic Opportunities
- Health Canada novel food approvals:The GRAS self-determination pathway offers faster regulatory clearance than FDA processes, creating a first-mover window for Canadian-origin protein isolates.
- Textured protein convergence:Twin-screw extrusion combined with high-moisture processing is enabling whole-muscle analog applications previously reserved for soy and wheat gluten.
- Carbon intensity scoring:The EU's emerging farm-to-fork carbon accounting methodologies favor domestic European cultivation over imported pulses, rewarding local processing investments.
Industry Challenges
- Fractionation capex intensity:Commercial-scale protein isolate facilities require significant capital for dehulling, milling, air-classification, and drying trains, constraining mid-tier processor expansion.
- Alkaloid breeding timeline:Proprietary cultivar development for reduced vicine-convicine lines spans multiple growing seasons, delaying variety commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Faba Beans Market |
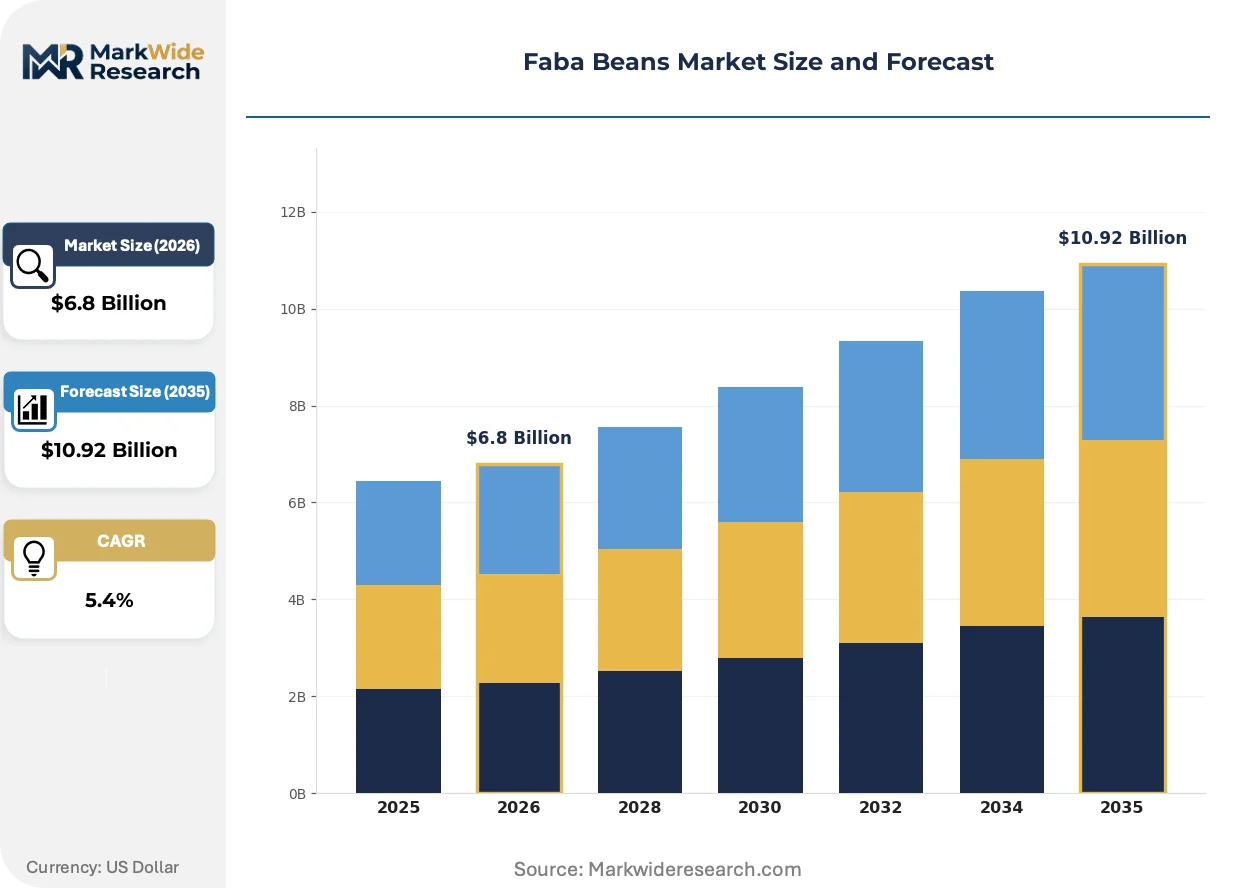
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dried Faba Beans, Processed Faba Beans, Frozen Faba Beans, Organic Faba Beans End Use: Food Industry, Animal Feed, Nutraceuticals, Biofuels Distribution Channel: Direct Sales, Supermarkets, Online Retail, Wholesale Distributors Packaging Type: Bags, Boxes, Vacuum Sealed, Bulk Packaging |
| Companies Covered | Alberta Pulse Growers Commission, Pawnee Buttes Seed Inc, Prairie Fava Ltd, Cargill Incorporated, Archer Daniels Midland Company, Unigrain Pty Ltd, Stamp Seeds Inc, Bunge Limited, Roland Beans, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Faba Beans Market Shifts & Advancements
Digital traceability platforms and precision breeding are compressing the gap between farm output and food-grade ingredient specifications, reshaping how quality premiums flow back to growers.
Air-classification coupled with electrostatic separation is virtualizing the traditional wet-fractionation pipeline for protein concentrate production. Food ingredient manufacturers in the Netherlands and Denmark are adopting these dry-processing trains to reduce water intensity and energy costs. The technology is virtualizing capital deployment patterns, enabling smaller-scale regional processors to compete with integrated multinationals on isolate purity metrics.
REACH food-contact material standards now explicitly address alkaloid migration limits in protein isolates used in infant nutrition and clinical formulations. The European Chemicals Agency's guidance documents have triggered reformulation cycles across German and French ingredient houses. Specialty nutrition segments are responding by demanding certified low-alkaloid cultivar streams with full chain-of-custody documentation.
Long-term offtake contracting is displacing spot-market purchasing for dehulled faba bean fractions. Meat-alternative manufacturers in Germany and the UK are negotiating three to five-year supply agreements directly with processors, bypassing traditional grain merchants. This pattern concentrates most visibly in the clean-label frozen entree segment, where formulation lock-in requires supply security.
Faba Beans Market Segmentation
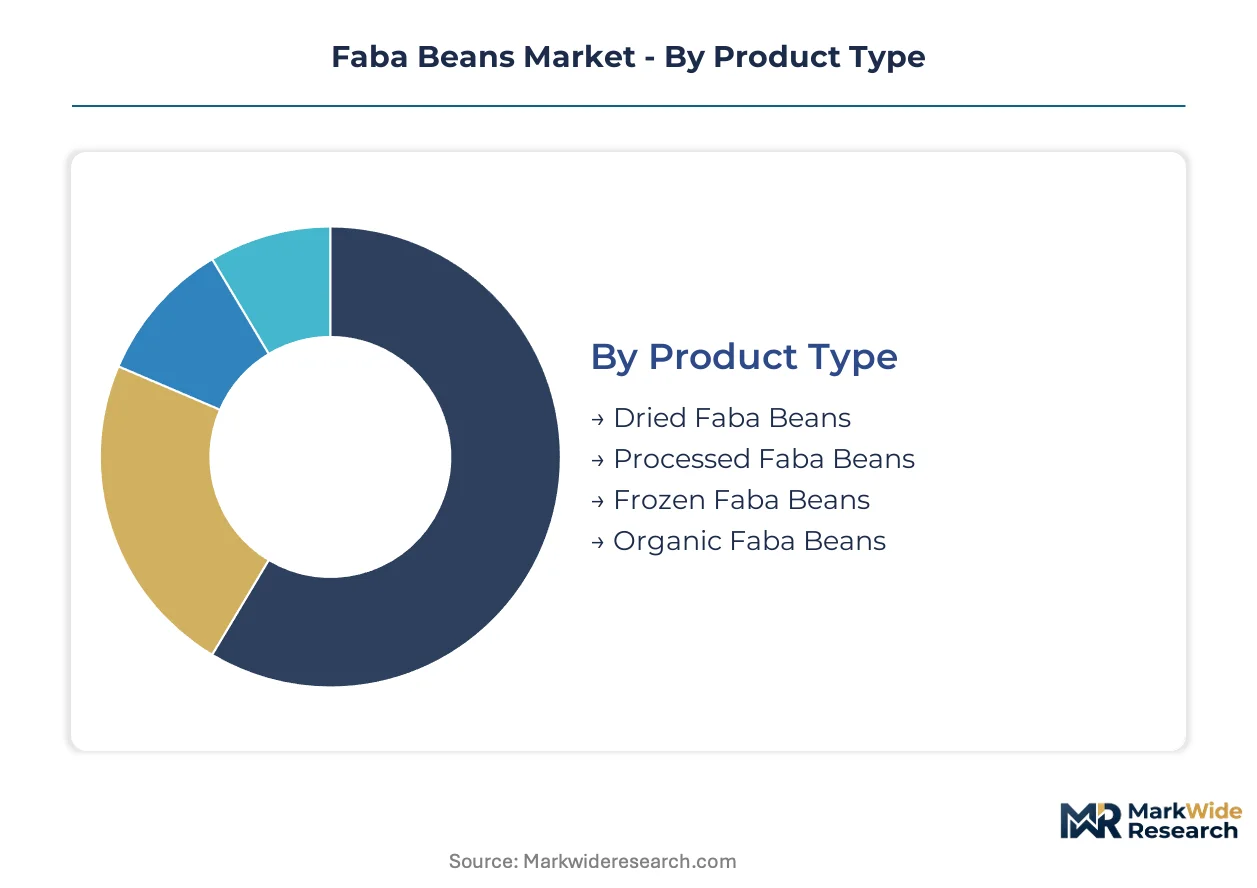
Faba bean commercialization splits across four distinct axes, each governing how value flows from field to final application. Product type determines processing intensity and margin capture. End use dictates specification tolerances and regulatory exposure. Distribution and packaging choices reflect buyer scale and shelf-life requirements.
Product Type:
Form selection traces the value-add continuum from commodity grain to functional ingredient, with each tier commanding different margin structures and customer relationships.
- Dried Faba Beans:Whole seeds at 12-14% moisture content serve as the foundational trade unit for export markets and long-duration storage. Baden-Württemberg food processors and Rotterdam traders anchor procurement volume for this segment, leveraging established bulk handling infrastructure across Baltic and North Sea ports.
- Processed Faba Beans:Dehulled, split, or fractionated products capture premium positioning through protein isolate and textured protein applications. Air-classification technology now enables functional parity with soy and pea isolates, driving German meat-alternative manufacturers toward multi-year supply contracting for dehulled fractions.
- Frozen Faba Beans:Blanched and quick-frozen pods or kernels target foodservice and retail ready-meal channels with minimal processing but cold-chain dependency.
- Organic Faba Beans:Certified cultivation under EU organic regulation commands procurement mandates from European retailers enforcing EU Green Deal farm-to-fork targets.
The dominant share belongs to Dried Faba Beans, while Processed Faba Beans is closing the gap fastest.
End Use:
Application diversification splits the market between mature feed volumes and emerging high-value nutrition streams, with regulatory pathways determining entry barriers.
- Food Industry:Human consumption spans whole bean applications, flour milling, and protein isolate extraction for meat alternatives and bakery fortification. German frozen entree manufacturers and Dutch ingredient houses drive specification tightening around alkaloid thresholds and carbon intensity scoring.
- Animal Feed:Whole beans and press cakes supply ruminant and monogastric formulations, though vicine-convicine toxicity limits inclusion rates for certain species without heat treatment.
- Nutraceuticals:Protein concentrates and peptide fractions target clinical nutrition and sports supplements, with REACH food-contact standards and EFSA novel food pathways shaping commercialization timelines.
- Biofuels:Starch-rich fractions and processing residues enter fermentation pathways for ethanol production, particularly where agricultural policy incentivizes crop diversification.
Food Industry commands the largest value share, though Nutraceuticals is expanding most quickly as alkaloid-reduced cultivars unlock clinical formulation opportunities.
Distribution Channel:
Channel selection reflects buyer scale, with industrial processors bypassing traditional merchants through direct contracting while retail channels fragment across format preferences.
- Direct Sales:Long-term offtake agreements between processors and end-users eliminate intermediary margins and enable formulation lock-in. UK and German meat-alternative manufacturers increasingly source dehulled fractions through three to five-year direct contracts.
- Supermarkets:Packaged whole beans and frozen products reach consumers through conventional retail, with organic certification and clean-label positioning driving shelf placement.
- Online Retail:Direct-to-consumer channels serve specialty and ethnic food segments, particularly for imported varieties and heritage cultivars.
- Wholesale Distributors:Aggregated supply to foodservice, small processors, and regional traders maintains relevance for spot-market purchasing and lower-volume buyers.
Direct Sales holds the dominant position among value-capturing channels, while Online Retail is climbing fastest as specialty ingredient e-commerce penetrates European markets.
Packaging Type:
Packaging economics balance protection requirements against handling efficiency, with specification grade determining whether retail presentation or bulk logistics prevails.
- Bulk Packaging:One-tonne totes and bulk containers dominate ingredient-grade shipments to processors, minimizing unit costs for high-volume contracts.
- Bags:Woven polypropylene sacks at 25-50kg serve export trade and intermediate handling, with identity-preserved labeling for certified organic or low-alkaloid streams.
- Vacuum Sealed:Oxygen-barrier packaging extends shelf life for high-value protein isolates and retail whole beans, justifying premium positioning.
- Boxes:Retail-ready cartons and display cases serve supermarket and foodservice channels with branding and portioning flexibility.
Bulk Packaging retains the largest volume share, though Vacuum Sealed formats are gaining share fastest as protein isolate specifications tighten and retail premiumization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows from Baltic and North Sea ports dominate trade volumes, while import dependence in Asian markets is shifting toward regional cultivation partnerships. Processing capacity concentrates where EU Green Deal subsidies and alkaloid testing infrastructure overlap.
Germany
Baden-Württemberg and Bavaria food processors drive dehulled fraction demand through multi-year supply agreements. EU Green Deal farm-to-fork procurement mandates redirect agricultural subsidies toward domestic pulse cultivation. The Stuttgart industrial cluster anchors protein isolate formulation for meat-alternative manufacturers.
Canada
Prairie province growers leverage Health Canada's faster novel food approval pathways versus FDA timelines. The Canadian Grain Commission enforces identity-preserved handling standards for premium ingredient streams. Saskatchewan and Manitoba processing hubs concentrate air-classification capacity for North American protein isolate supply.
Netherlands
Rotterdam traders and Dutch ingredient houses adopt dry-processing trains to reduce water intensity in concentrate production. ECHA REACH guidance on alkaloid migration limits triggers reformulation cycles across infant nutrition segments. The Wageningen food innovation corridor accelerates cultivar development partnerships with reduced vicine-convicine lines.
Australia
Victoria and South Australia growers expand organic acreage under retailer procurement mandates tied to EU import requirements. The country's national agricultural regulator enforces certification standards for low-alkaloid export streams. Melbourne processing facilities specialize in vacuum-sealed protein isolate packaging for Asian nutraceutical markets.
France
Île-de-France and Hauts-de-France regions rebuild supply chains around identity-preserved domestic streams rather than commodity imports. EFSA novel food pathways shape commercialization timelines for clinical nutrition applications. Lille ingredient houses demand certified low-alkaloid cultivars with full chain-of-custody documentation.
Faba Beans Market Competitive Landscape
On the supply side, the industry is consolidating around integrated processors with captive cultivar development and fractionation infrastructure. Mid-tier regional players compete through dry-processing technology adoption that virtualizes capital requirements. Three archetypes dominate: multinational grain handlers with identity-preserved sourcing networks, proprietary cultivar developers, and regional processors leveraging air-classification licensing. Competitive moves center on long-term offtake contracting with meat-alternative manufacturers and backward integration into low-alkaloid breeding programs.
Within the integrated processor tier, Cargill Incorporated and Archer Daniels Midland Company exemplify scale-driven positioning through North American grain handling infrastructure and fractionated protein concentrate capabilities. Prairie Fava Ltd occupies a specialist position representing proprietary cultivar development optimized for protein content and alkaloid reduction. These three anchors illustrate how supply chain control and breeding IP determine preferred supplier status under tightening EU regulatory frameworks.
| Leading Market Players |
|---|
| Alberta Pulse Growers Commission |
| Pawnee Buttes Seed Inc |
| Prairie Fava Ltd |
| Cargill Incorporated |
| Archer Daniels Midland Company |
| Unigrain Pty Ltd |
| Stamp Seeds Inc |
| Bunge Limited |
| Roland Beans |
| Others |
Supply & Pricing Matrix
Vicine-convicine alkaloid regulatory thresholds function as a tariff-like barrier that simultaneously widens pricing spreads between certified low-alkaloid streams and commodity grades while forcing supply chain reconfiguration toward identity-preserved handling infrastructure in Germany, France, and the Netherlands.
Pricing Analysis
Air-classification technology deployment gaps separate pricing tiers: established dry-fractionation processors command premium positioning against wet-process legacy operators, while next-generation electrostatic separation systems promise further cost compression. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and carbon intensity scoring rather than protein content alone. Pricing pressure stems from yellow pea protein substitution in North American formulations, where GRAS recognition accelerates R&D diversion. Contract food manufacturers exhibit highest price sensitivity; meat-alternative brand owners with formulation lock-in requirements show lowest.
Supply Chain Analysis
EU REACH food-contact material standards on alkaloid migration operate as de facto export controls, restricting non-European supplier market access without compliant testing infrastructure. Supply concentrates in Germany, Canada, and Australia, with Dutch traders anchoring Baltic and North Sea export flows. Raw material dependencies center on certified seed stock, specialized dehulling equipment, and cold-chain logistics for frozen fractions. Single-source vulnerability pervades low-alkaloid cultivar genetics controlled by proprietary breeding programs. Distribution runs through direct long-term offtake agreements displacing spot-market grain merchants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Faba bean commercialization fragments across regulatory compliance tiers, creating specialist niches as EU Green Deal procurement mandates splinter demand into certified organic, low-alkaloid, and carbon-scored sub-streams.
For Market Incumbents: Insulate margin position through backward integration into captive low-alkaloid breeding programs in Saskatchewan or Victoria, while securing Health Canada novel food approvals ahead of FDA timelines to lock in North American formulation slots before pea protein substitution accelerates.
For New Entrants and Emerging Players: Establish a beachhead in vacuum-sealed protein isolate packaging for Asian nutraceutical channels, where Australian and Canadian origin premiums offset higher processing capital requirements; target Melbourne and Rotterdam as logistics hubs with existing cold-chain infrastructure.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated processors with proprietary cultivar IP and fractionation assets; acquisition targets should combine air-classification licensing with established German or UK meat-alternative offtake relationships. Watch Health Canada approval velocity versus FDA delays as the inflection signal determining which origin-processor combinations capture preferred supplier status.
| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Three to five-year offtake contracts with Baden-Württemberg meat-alternative manufacturers lock in volume and justify fractionation capex. |
| Backward Integration | Captive low-alkaloid breeding programs in Prairie provinces reduce vicine-convicine compliance risk and secure identity-preserved seed supply. |
| Green Certification Program | EU organic regulation alignment opens procurement mandates from retailers enforcing EU Green Deal farm-to-fork targets. |
| Capacity Expansion | Air-classification train additions in Rotterdam and Lille reduce water intensity and compete with wet-fractionation multinationals. |
| Joint Venture | Wageningen corridor partnerships accelerate cultivar development timelines for reduced vicine-convicine commercialization. |
Research Methodology
A spread of perspectives from plant protein R&D directors, EU regulatory affairs specialists, German frozen entree procurement managers, and Canadian grain commission inspectors converged on the working assumptions. Primary interviews with ingredient house formulators and meat-alternative manufacturer supply chain heads combined with secondary validation against ECHA REACH guidance documents, Health Canada novel food submission databases, EU organic regulation enforcement records, and customs trade flow data. Bottom-up acreage and processing capacity estimates triangulated against top-down protein isolate demand projections.
Demand-supply balance modeling across product type, end use, distribution channel, and packaging format dimensions generated volume and value outputs over the projection horizon. CAGRs derived from segment-level growth rate reconciliation against aggregate market expansion. Industry-specific inputs incorporated alkaloid threshold regulatory evolution timing and carbon intensity scoring methodology adoption curves.
Macroeconomic conditions sit as an overlay; deviation in agricultural input costs, energy pricing for drying trains, or transatlantic shipping rates would shift the trajectory. Forecasts reflect documented assumptions on regulatory pathway timelines and cultivar commercialization schedules. Material shifts in EU alkaloid threshold enforcement or Health Canada approval velocity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
China Rice Seed Market
Seeds
South Africa Forage Seed Market
Seeds
Cotton Seed Treatment Market
Seeds
Europe Amaranth Market
Seeds
China Forage Seed Market
Seeds
Africa Sorghum Seed Market
Seeds
Global Onion Seed Market
Seeds
Poppy Seed Market
Seeds
Asparagus Seeds Market
Seeds
Flower Seed Market
Seeds
Caraway Seeds Market
Seeds
Pasture Seeds Market
Seeds
China Seed Market
Seeds
Native Grass Seeds Market
Seeds
Asia-Pacific Cotton Seed Market
Seeds
Mustard Seeds Market