
 Europe Sustainable Casket and Coffin Market | 2026-2036
Europe Sustainable Casket and Coffin Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Sustainable Casket and Coffin Market Analytics
Subscription-based maintenance and end-of-life planning software is restructuring how European funeral homes source sustainable caskets. Ecoffins leverages its UK manufacturing base to supply certified biodegradable vessels across British natural burial grounds. The Natural Burial Company sustains a direct-to-cemetery model that bypasses traditional funeral home markups. Loop Living Cocoon differentiates through mycelium-based vessels that decompose within weeks rather than decades.
Europe sustainable caskets and coffins comprise burial containers engineered from rapidly renewable or recycled feedstocks, typically achieving complete soil integration within three to seven years depending on soil chemistry and vessel wall thickness. Their primary commercial purpose is to satisfy cemetery operators and consumers seeking burial methods that eliminate persistent synthetic residues from soil and groundwater. Biodegradable caskets and natural burial pods command the strongest volume positions, while recycled materials and cardboard variants capture the fastest expansion as price-sensitive municipalities revise procurement specifications. Wood and bamboo materials anchor the value pool due to established certification chains through FSC and PEFC schemes, though organic cotton linings now attract premium positioning in Scandinavian markets.
EMA guidelines on environmental claims, the EU Green Deal's circular economy action plan, and national implementations of REACH chemical restrictions collectively reshape material eligibility and marketing language across member states. France's ANSM and Germany's federal environmental agency enforce divergent biodegradability testing protocols, fragmenting compliance burdens for cross-border suppliers. Stakeholders must monitor how the EU AI Act and emerging digital product passport requirements extend traceability obligations to funeral sector supply chains.
Market Dynamics
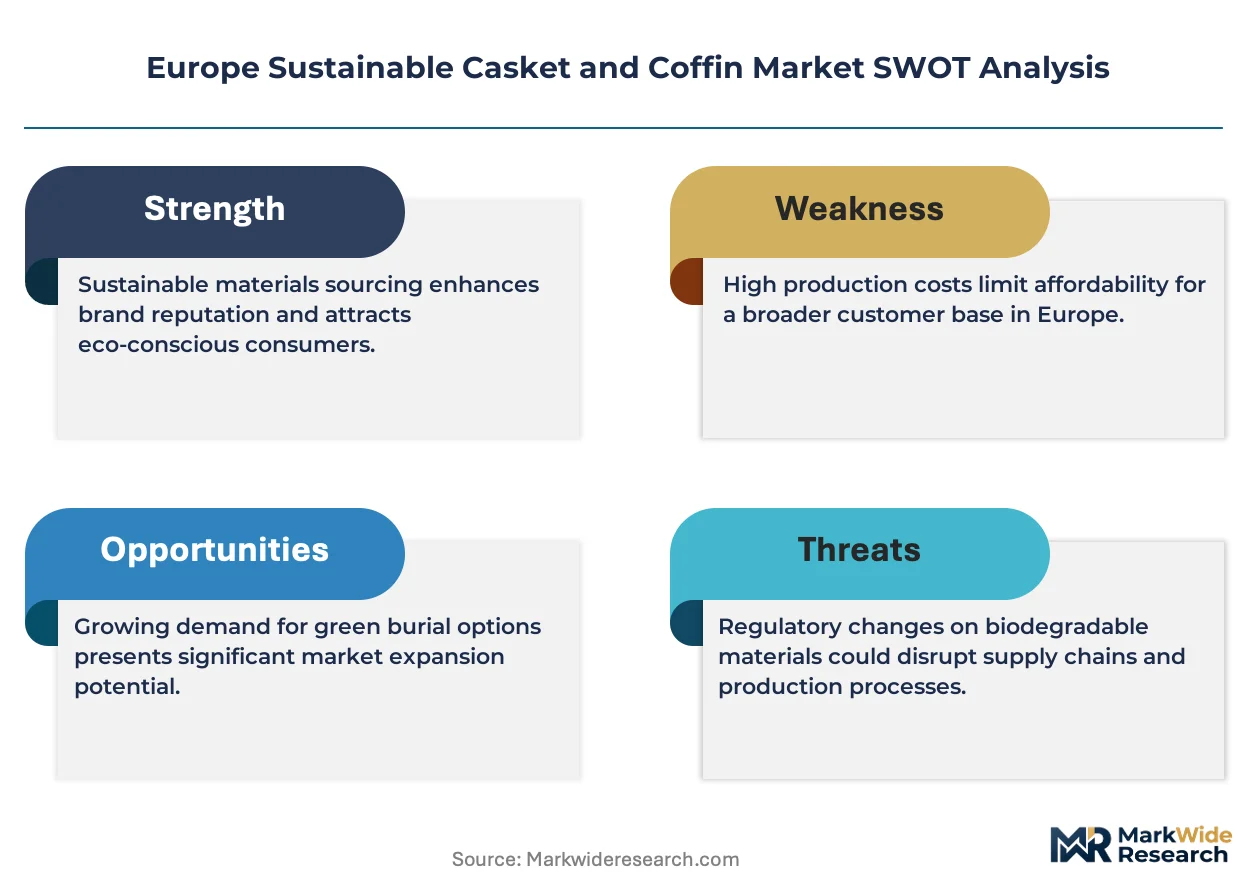
EU Green Deal procurement mandates are forcing municipal cemeteries across Germany and the Netherlands to rewrite burial vessel specifications, accelerating substitution away from tropical hardwoods and synthetic finishes toward certified biodegradable alternatives.
Growth Catalysts
- EU Green Deal circular economy mandates:National green procurement rules in member states now require biodegradable burial vessels for public cemetery contracts, creating guaranteed demand pipelines for certified suppliers.
- Natural burial ground expansion:British and Scandinavian cemetery operators have registered new natural burial sites at the fastest pace in Europe, concentrating volume demand for soil-integrating containers.
- FSC and PEFC certification chains:Established wood and bamboo tracking systems enable funeral homes to verify renewable sourcing, reducing procurement risk for sustainability claims.
Market Restraints
- Input cost volatility for mycelium substrates:Agricultural waste feedstock prices fluctuate with grain harvest cycles, compressing margins for bio-fabricated vessel manufacturers.
- Divergent biodegradability testing protocols:France's ANSM and Germany's federal environmental agency enforce incompatible soil integration standards, fragmenting compliance costs for cross-border suppliers.
- Technical limitation in cold-climate decomposition:Northern European soil temperatures below five degrees Celsius extend vessel breakdown timelines beyond cemetery lease periods, creating customer satisfaction risk.
Strategic Opportunities
- Underpenetrated Eastern European markets:Poland and Romania lack natural burial ground infrastructure, offering first-mover positioning for cemetery-direct distribution models.
- EU AI Act traceability requirements:Digital product passport mandates will extend to funeral supply chains, creating competitive advantage for suppliers with existing batch-tracking systems.
- Mycelium-cardboard hybrid technology:Combining rapid-decomposition mycelium shells with structural cardboard cores addresses both cost and performance gaps in current biodegradable offerings.
Industry Challenges
- Skill gap in bio-fabrication operations:Mycelium cultivation requires specialized microbiology expertise that traditional woodworking regions lack, constraining production scaling.
- REACH chemical compliance timelines:Linings and adhesives face extended substance authorization periods, delaying product launches by twelve to eighteen months.
- Integration complexity with legacy cemetery management software:Biodegradable vessel inventory systems must interface with decades-old municipal burial record databases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Sustainable Casket and Coffin Market |
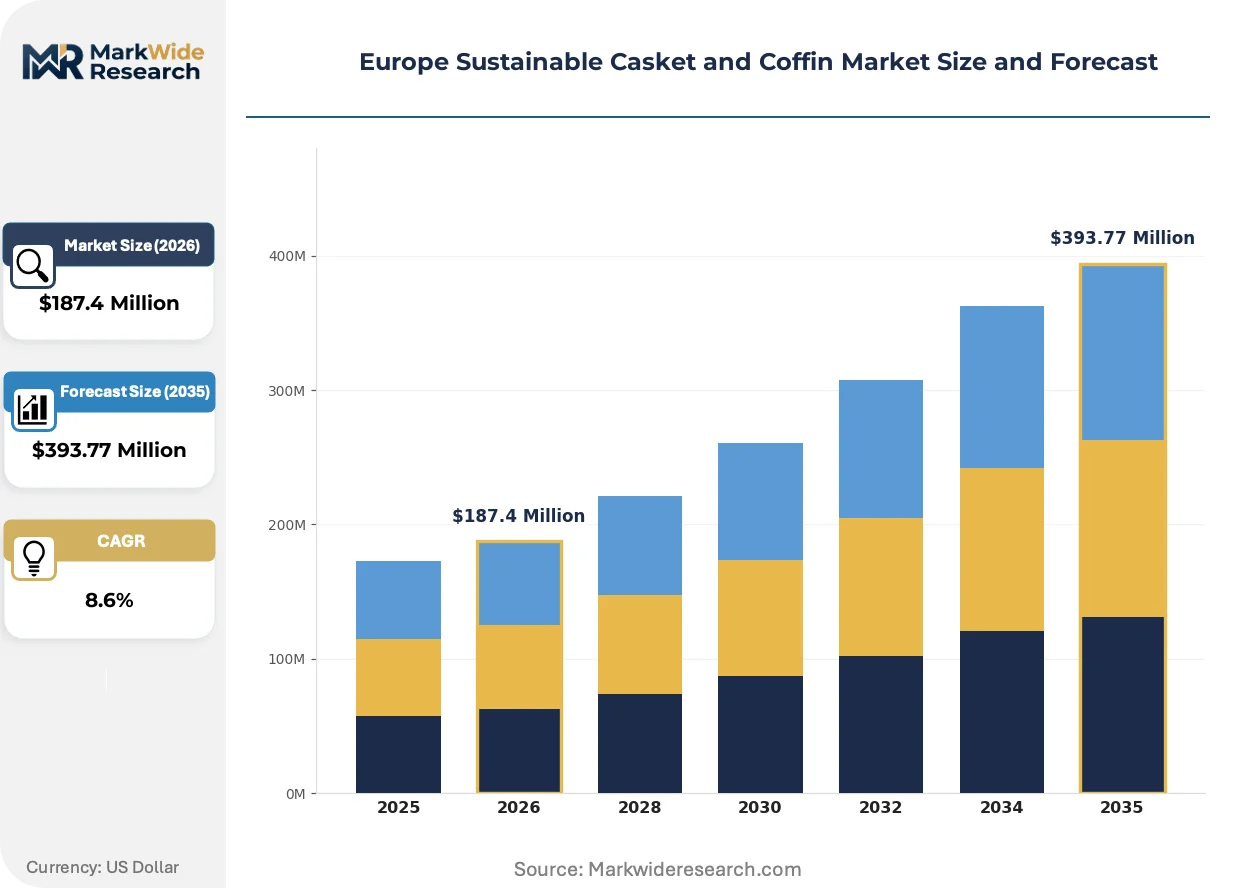
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $393.77 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biodegradable Caskets, Eco-Friendly Coffins, Natural Burial Pods, Recycled Materials Material: Wood, Bamboo, Cardboard, Organic Cotton Distribution Channel: Funeral Homes, Online Retailers, Direct Sales, Specialty Stores End User: Individual Consumers, Non-Profit Organizations, Eco-Conscious Families, Funeral Service Providers |
| Companies Covered | Ecoffins, The Natural Burial Company, Green Burial Council, Cardboard Coffin Company, Natural Woven Products Ltd, Caring Coffins, Green Coffins Ireland Ltd, Loop Living Cocoon, Ecoffins UK LLP, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Sustainable Casket and Coffin Market Evolving Landscape
Burial vessel manufacturing is converging with agricultural biotechnology and digital traceability systems, restructuring how European funeral homes evaluate supplier partnerships and inventory risk.
Mycelium-based vessel production is converging with precision fermentation techniques to achieve consistent wall thickness and decomposition rates. German and Dutch municipal buyers now specify mycelium alternatives in tender documents. This convergence is compressing acceptable decomposition timelines from decades to weeks, forcing traditional wood-casket manufacturers to accelerate material experimentation or lose public procurement access.
REACH chemical restrictions are eliminating formaldehyde-based finishes and synthetic adhesives from approved material lists. The regulation forces reformulation of interior linings and structural bonds across all vessel categories. Scandinavian markets respond fastest, with Swedish and Danish funeral homes already completing supplier transitions to organic cotton and plant-based resin alternatives.
Direct cemetery purchasing is displacing traditional funeral home intermediation in natural burial segments. British natural burial grounds now contract directly with vessel manufacturers, bypassing conventional markup structures. This channel shift concentrates price negotiation power with cemetery operators and compresses available margin for distributors serving the UK market.
Europe Sustainable Casket and Coffin Market Segmentation
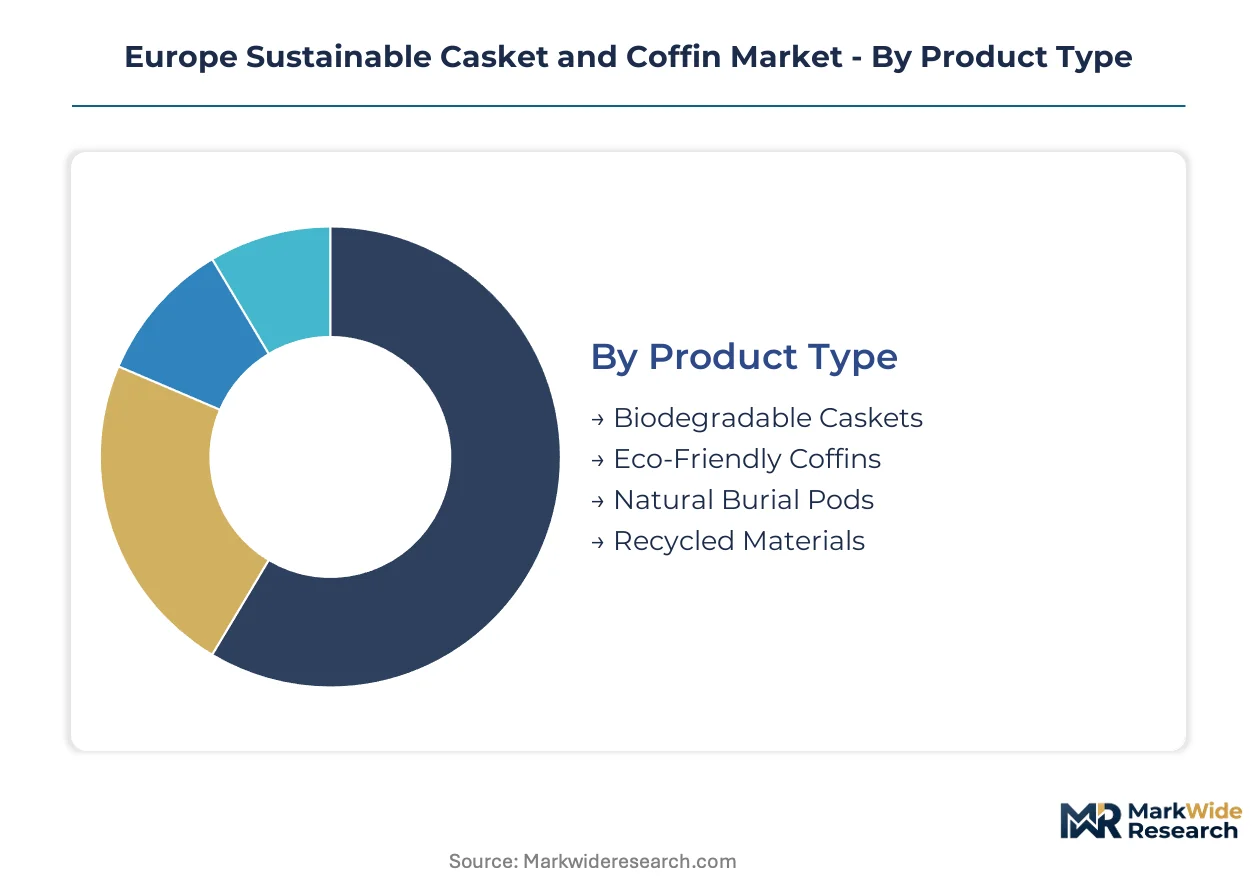
Segmentation in the Europe sustainable casket and coffin market reveals how procurement authority, material science, and channel economics fragment demand across distinct buyer configurations. Understanding these divides exposes where pricing power concentrates and where new entrants face structural barriers.
Product Type:
Buyers differentiate primarily by decomposition timeline requirements and cemetery lease terms rather than aesthetic preference.
- Biodegradable Caskets:Engineered from FSC-certified wood, bamboo, or woven willow with unbleached cotton interiors. British natural burial grounds specify these for soil integration within three to seven years, driving concentrated procurement from UK cemetery operators.
- Eco-Friendly Coffins:Traditional form factors constructed without tropical hardwoods, synthetic varnishes, or metal hardware. German municipal cemeteries mandate these under EU Green Deal procurement rules, creating guaranteed demand pipelines for certified domestic suppliers.
- Natural Burial Pods:Egg-shaped vessels designed for full-body tree planting integration. Scandinavian markets favor these for forest burial sites, though cold-climate decomposition delays limit penetration north of 60 degrees latitude.
- Recycled Materials:Pressed cardboard and reclaimed wood fiber constructions. Price-sensitive municipalities in the Netherlands specify these for public cemetery contracts, capturing fastest expansion as procurement specifications tighten.
Biodegradable caskets lead volumes today; recycled materials are gaining share fastest.
Material:
Cost tier and certification availability determine material selection, with supply chain maturity separating premium from commodity positioning.
- Wood:Softwood and hardwood alternatives from managed European forests with full FSC or PEFC chain-of-custody documentation. UK and German funeral homes prefer these for established supplier relationships and predictable decomposition rates.
- Bamboo:Rapid-renewable grass species with tensile strength exceeding oak by weight. Dutch importers source primarily from certified plantations in Portugal and Spain, reducing tropical supply dependence.
- Cardboard:Post-consumer recycled fiber with soy-based inks and plant-derived adhesives. French municipal buyers specify these for cost-controlled public contracts, though REACH compliance for interior coatings extends qualification timelines.
- Organic Cotton:Unbleached, undyed interior linings from certified organic cultivation. Scandinavian markets command premium positioning for these materials, with Swedish funeral homes completing supplier transitions ahead of EU chemical restriction deadlines.
Wood dominates value capture today; bamboo is climbing the fastest as certification infrastructure matures.
Distribution Channel:
Channel selection reflects buyer sophistication and procurement scale, with direct cemetery purchasing displacing traditional intermediation in natural burial segments.
- Funeral Homes:Traditional intermediaries with established relationships and inventory financing capacity. UK funeral homes face margin compression as cemetery-direct models bypass conventional markup structures.
- Online Retailers:Direct-to-consumer platforms with configuration tools for material and lining selection. These channels capture individual pre-planning demand in urban UK and Scandinavian markets.
- Direct Sales:Manufacturer-to-cemetery contracts eliminating distributor margins. British natural burial grounds favor this model for volume pricing and batch traceability.
- Specialty Stores:Physical showrooms for tactile material evaluation and end-of-life planning consultation. These serve eco-conscious families in German metropolitan areas with high natural burial ground density.
Funeral homes retain volume leadership today; direct sales are expanding most quickly as cemetery procurement autonomy increases.
End User:
End-user categories separate individual pre-planning demand from institutional procurement with divergent price sensitivity and specification authority.
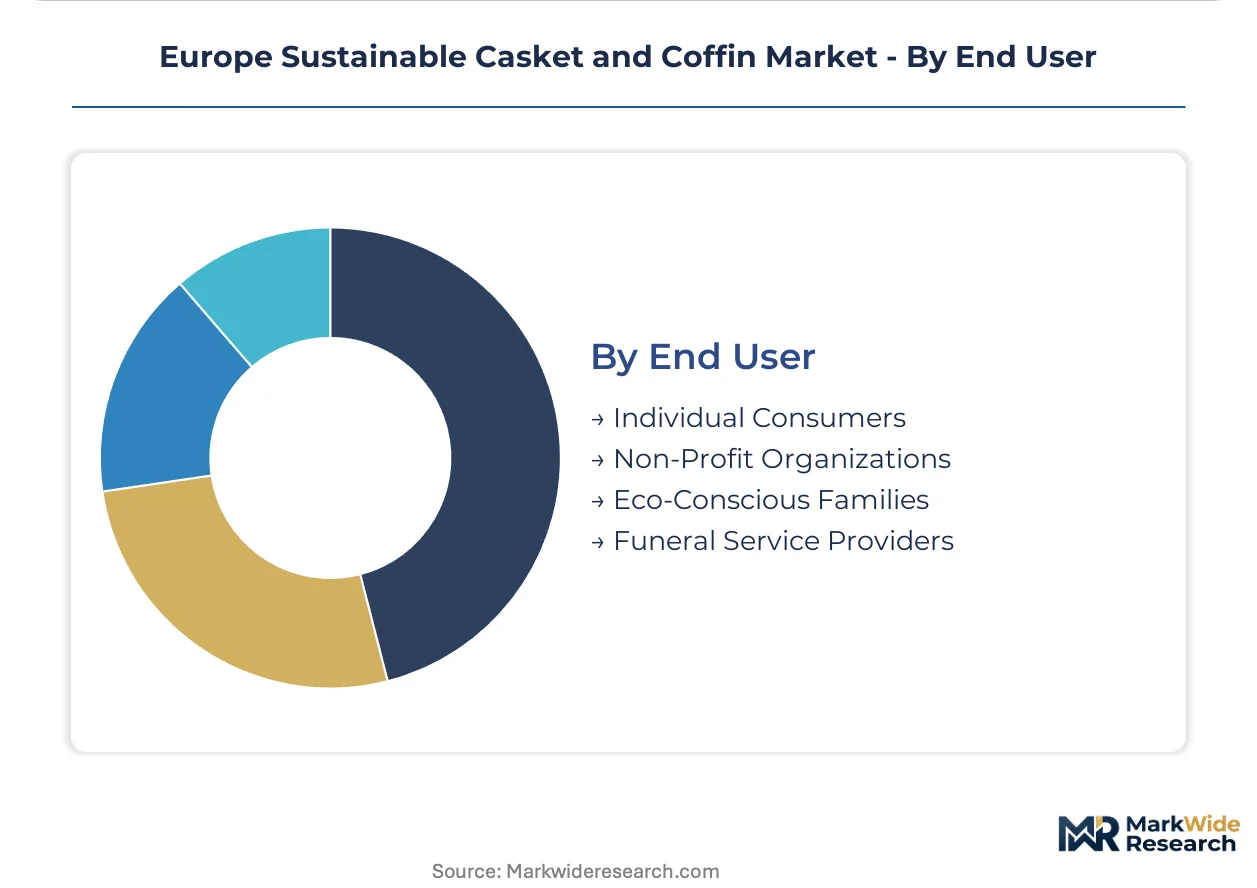
- Individual Consumers:Pre-need purchasers arranging burial vessels through funeral planning services. These buyers prioritize material certification and decomposition timeline transparency.
- Non-Profit Organizations:Religious and community burial societies with collective purchasing power. German church-affiliated cemeteries negotiate multi-year supply contracts with certified manufacturers.
- Eco-Conscious Families:Post-need buyers seeking alignment with decedent environmental values. Scandinavian markets show highest concentration of this segment, driving premium material adoption.
- Funeral Service Providers:Commercial operators managing inventory across multiple cemetery relationships. These buyers demand supply reliability and batch traceability for regulatory documentation.
Funeral service providers lead procurement volumes today; non-profit organizations are gaining share fastest as municipal cemetery outsourcing accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and the United Kingdom present contrasting procurement models, with German municipal cemeteries enforcing strict EU Green Deal mandates while British natural burial grounds pioneer direct-to-cemetery distribution channels that bypass traditional funeral home intermediaries.
Germany
Federal environmental agency biodegradability protocols drive municipal cemetery specifications across North Rhine-Westphalia and Bavaria. The country's federal procurement office enforces green procurement rules that eliminate tropical hardwoods from public contracts. Cologne and Munich cluster certified wood-casket manufacturers serving municipal buyers with FSC and PEFC documentation requirements.
United Kingdom
Natural burial ground registrations have expanded fastest in England and Wales, concentrating demand for soil-integrating containers. The UK Environment Agency regulates cemetery soil chemistry standards without federal procurement mandates. Norfolk and Yorkshire host Ecoffins manufacturing operations supplying British natural burial grounds through direct cemetery contracts.
Netherlands
Municipal cemeteries in Randstad cities specify recycled cardboard vessels for cost-controlled public contracts. The Dutch government's green procurement framework accelerates material substitution away from synthetic finishes. Eindhoven Region importers source bamboo primarily from certified Portuguese and Spanish plantations, reducing tropical supply dependence.
France
ANSM enforces divergent biodegradability testing protocols that fragment compliance burdens for cross-border suppliers. Municipal buyers in Île-de-France specify cardboard constructions with extended REACH qualification timelines for interior coatings. Lyon and Marseille funeral homes transition supplier relationships to organic cotton and plant-based resin alternatives ahead of chemical restriction deadlines.
Scandinavia
Swedish and Danish funeral homes complete supplier transitions to organic cotton linings faster than continental markets. Forest burial sites in southern Sweden favor natural burial pods, though cold-climate decomposition delays limit penetration north of 60 degrees latitude. Stockholm and Copenhagen eco-conscious families drive premium material adoption through post-need purchasing patterns.
Europe Sustainable Casket and Coffin Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with certification-holding wood-casket producers commanding municipal procurement pipelines while bio-fabricated vessel startups capture natural burial ground contracts. The vendor base organizes around three strategic archetypes: FSC-certified wood specialists with established cemetery relationships, mycelium-based innovators leveraging agricultural biotechnology, and recycled-material fabricators serving price-sensitive municipal buyers. Capacity expansion and direct cemetery distribution partnerships represent the dominant competitive moves reshaping channel economics.
Among UK-based fabricators, Ecoffins and The Natural Burial Company exemplify divergent channel strategies within the same geography. Ecoffins anchors the certified wood-casket tier through manufacturing concentration in Norfolk and Yorkshire. The Natural Burial Company occupies a position within the cemetery-direct distribution archetype, bypassing conventional funeral home markup structures. Loop Living Cocoon represents the mycelium-based innovation vector, with Dutch operations positioning it at the intersection of agricultural biotechnology and precision fermentation techniques.
| Leading Market Players |
|---|
| Ecoffins |
| The Natural Burial Company |
| Green Burial Council |
| Cardboard Coffin Company |
| Natural Woven Products Ltd |
| Caring Coffins |
| Green Coffins Ireland Ltd |
| Loop Living Cocoon |
| Ecoffins UK LLP |
| Others |
Value Network & Pricing Analysis
Certification-grade bifurcation between FSC-certified wood caskets and uncertified cardboard alternatives manifests in divergent margin structures and procurement channel configurations across the European market. Premium-tier vessels command three to seven year decomposition guarantees through established certification chains, while commodity-grade recycled fiber products compete on unit economics for municipal contracts in the Netherlands and France.
Pricing Analysis
Capacity additions in Portugal and Spain for certified bamboo cultivation are reshaping price floors for rapid-renewable alternatives, compressing the historical premium over European softwood. Three-tier pricing structure across premium, standard, and economy levels reflects decomposition timeline guarantees and certification depth. Cost compression in the recycled materials tier is intensifying because Dutch municipal buyers consolidate volume through multi-year public tenders. Municipal cemetery operators in Germany exhibit lowest price sensitivity due to EU Green Deal procurement mandates, while individual consumers in Eastern European markets remain most responsive to unit cost.
Supply Chain Analysis
FSC and PEFC chain-of-custody documentation requirements gate supplier eligibility for German and British municipal contracts, fragmenting qualified vendor pools across national certification infrastructures. Manufacturing concentrates in the United Kingdom, Germany, and the Netherlands, with Portuguese and Spanish plantations feeding bamboo raw material demand. Feedstock supply rests on agricultural waste streams from grain harvest cycles and managed European forest thinnings. Single-source vulnerability exists for mycelium substrate suppliers dependent on specific regional grain processing byproducts. Distribution runs through direct cemetery contracts in British natural burial segments, bypassing traditional funeral home markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities emerge between German federal procurement premiums and Polish municipal cost baselines, where green burial infrastructure investment lags by approximately half a decade. Regulatory divergence between France's ANSM testing protocols and Germany's federal environmental agency standards creates compliance cost differentials that favor regional specialization over pan-European scale.
For Market Incumbents: Anticipate margin erosion from mycelium-based entrants by accelerating certification investments in organic cotton linings and plant-based resin adhesives ahead of REACH chemical restriction deadlines. Defensive consolidation through backward integration into Portuguese bamboo plantation partnerships secures feedstock access against agricultural commodity volatility. Channel control via direct cemetery software integration addresses the threat of disintermediation from natural burial ground purchasing autonomy. For New Entrants and Emerging Players: Launch via cemetery-direct distribution models in Poland and Romania, where natural burial ground infrastructure remains underdeveloped and first-mover positioning carries minimal competitive encumbrance. White-space targets include mycelium-cardboard hybrid vessels addressing both cost and cold-climate decomposition performance gaps. The most penetrable segment comprises price-sensitive municipal buyers in Eastern European markets seeking EU Green Deal compliance without premium-tier certification costs. For Investors and Strategic Acquirers: Consolidation pressure builds where batch-traceability systems intersect with EU AI Act digital product passport requirements, favoring acquisition targets with existing compliance infrastructure over greenfield capability builds. Long-term viability across the projection horizon hinges on certification chain control and direct cemetery channel relationships rather than funeral home intermediary access. The signal to watch as inflection indicator is German federal environmental agency protocol harmonization with French ANSM standards, which would compress cross-border compliance costs and accelerate vendor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Chain Investment | FSC and PEFC documentation secures German municipal procurement pipelines against regulatory exclusion. |
| Direct Cemetery Distribution | Bypassing funeral home intermediaries captures margin compression from British natural burial ground purchasing autonomy. |
| Mycelium-Cardboard Hybrid R&D | Combining rapid decomposition with structural integrity addresses cold-climate performance limitations in Scandinavian markets. |
| Portuguese Plantation Partnership | Backward integration into certified bamboo cultivation reduces tropical supply dependence and input cost volatility. |
| Digital Product Passport Integration | Batch-traceability systems position suppliers ahead of EU AI Act funeral supply chain mandates. |
Research Methodology
Multiple input streams — cemetery operator procurement directors, funeral home inventory managers, FSC certification auditors, and REACH compliance consultants — were reconciled against customs data for bamboo and wood fiber imports, EU tender documentation databases, and national burial ground registration records. Primary interviews with municipal cemetery procurement officers in Germany, the Netherlands, and the United Kingdom were cross-validated through secondary analysis of green procurement framework implementations and natural burial ground expansion filings. Bottom-up vessel shipment estimates and top-down cemetery contract value aggregation were triangulated to constrain forecast variance.
Historical decomposition timeline data and expert panel input on material substitution trajectories were cross-referenced across the analysis window. Segmentation dimensions modeled include product type, material certification tier, distribution channel configuration, and end-user procurement authority. CAGRs were derived from logistic curve fitting to cemetery infrastructure expansion rates and municipal contract award patterns. Industry-specific forecast inputs incorporated EU Green Deal procurement mandate implementation schedules and REACH chemical restriction phase-in timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under divergent biodegradability testing protocol harmonization scenarios and agricultural commodity price shocks. Projections reflect assumptions regarding municipal cemetery outsourcing acceleration and mycelium cultivation yield consistency. A model refresh is warranted upon material change in EU AI Act digital product passport enforcement timelines or German-French regulatory standard convergence.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Goods
Professional Hair Care Products Market
Consumer Goods
Acrylic Marker Pen Market
Consumer Goods
Canada Pet Food Market
Consumer Goods
Baby Gate Market
Consumer Goods
Middle East and Africa Leather Goods Market
Consumer Goods
Moving Supplies Market
Consumer Goods
Cat Litter Product Market
Consumer Goods
Hair Removal Spray Market
Consumer Goods
Robotic Pool Cleaner Market
Consumer Goods
Pre-Shave Care Market
Consumer Goods
Global Nap Pod Market
Consumer Goods
Camping Cooler Market
Consumer Goods
Smart Bathtub Market
Consumer Goods
Fishing Reels Market
Consumer Goods
Handmade Cigars Market
Consumer Goods
Qatar Retail Market