
 Speaker Cabinets, Grilles and Materials Market | 2026-2036
Speaker Cabinets, Grilles and Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Speaker Cabinets, Grilles and Materials Market Analytics
CE marking under the EU Construction Products Regulation is bifurcating supplier eligibility for fire-rated cabinet materials sold into European professional installations. Foshan Hongyu leverages integrated plywood lamination lines to control raw material costs across its Guangdong operations. Wendell Fabrics Corporation sustains niche dominance in acoustically transparent synthetic grille cloths for studio monitor applications. Mojotone anchors its position through specialized supply to the aftermarket guitar amplifier segment, where vintage-specification grille cloth commands premium positioning.
Speaker cabinets, grilles and materials encompass the structural enclosures, protective fronts, and constituent substances engineered to house transducers, manage acoustic output, and withstand environmental stress across operating temperatures from minus twenty to plus sixty degrees Celsius. MDF substrates dominate mid-range consumer and professional cabinet construction due to uniform density and machinability, though birch plywood retains preference in touring-grade active cabinets where impact resistance determines service life. Plastic injection-molded enclosures represent the fastest-expanding material category, driven by portable sound systems and automotive door-panel integrations where weight reduction directly influences fuel economy ratings. Grilles as a product type concentrate margin pools in custom-weave metal mesh and hydrophobic fabric treatments that satisfy IP-rated outdoor deployment specifications.
FCC electromagnetic compatibility standards govern cabinet shielding performance for consumer electronics sold in the United States, while ECHA REACH restrictions constrain halogenated flame retardants in European-bound MDF and plastic formulations. China's GB standards for indoor air quality, administered by SAMR, limit formaldehyde emissions from engineered wood products, compelling substrate suppliers to certify E0-grade particleboard for home theater OEM contracts. Stakeholders must monitor evolving acoustic performance benchmarks from ISO and IEC working groups, as revised measurement protocols for cabinet damping coefficients will soon differentiate qualified suppliers from those reliant on legacy test data.
Market Dynamics
Composite grille materials are displacing legacy metal mesh in professional audio installations as concert venues and broadcast studios prioritize acoustic transparency combined with impact resistance. REACH compliance pressures in Europe and GB standard enforcement in China are simultaneously reshaping substrate formulations and supplier qualification requirements across the value chain.
Growth Catalysts
- Professional Audio Venue Expansion:Concert halls and broadcast studios in Germany and the United States are specifying hydrophobic fabric grille treatments for IP-rated outdoor deployments, expanding the addressable premium segment for treated synthetic weaves.
- REACH-Driven Material Reformulation:ECHA restrictions on halogenated flame retardants are compelling substrate suppliers to develop phosphorus-based alternatives for MDF and plastic cabinet enclosures bound for European professional installations.
- Automotive Lightweighting Mandates:Plastic injection-molded enclosures are capturing share in automotive door-panel integrations as fuel economy regulations in Japan and South Korea penalize component weight.
Market Restraints
- Birch Plywood Supply Concentration:Touring-grade active cabinet manufacturers face input cost volatility as Baltic region suppliers control premium void-free birch ply stock essential for impact-resistant enclosures.
- Formaldehyde Emission Certification Burden:China's SAMR-administered GB standards for indoor air quality impose E0-grade particleboard mandates that disqualify uncertified substrate suppliers from home theater OEM contracts.
- Legacy MDF Density Limitations:Uniform-density fiberboard substrates exhibit inferior damping coefficients compared to plywood alternatives, constraining high-fidelity studio monitor applications where cabinet resonance control determines product positioning.
Strategic Opportunities
- Aftermarket Guitar Amplifier Specialization:Vintage-specification grille cloth for tube amplifier restoration commands premium positioning in the United States and United Kingdom where collector markets sustain small-batch production economics.
- CE Marking Bifurcation:EU Construction Products Regulation fire-rating requirements are creating supplier eligibility tiers that reward early certifiers with exclusive access to professional installation channels in France, Italy, and Spain.
- Composite-Metal Hybrid Grilles:Convergence of custom-weave metal mesh with hydrophobic fabric treatments enables single-supplier solutions for mixed indoor-outdoor venue deployments, consolidating procurement relationships.
Industry Challenges
- Acoustic Measurement Protocol Gaps:ISO and IEC working groups are revising cabinet damping coefficient test standards, threatening to invalidate legacy qualification data for suppliers without updated laboratory investments.
- Electromagnetic Shielding Integration:FCC electromagnetic compatibility standards for consumer electronics require cabinet-level shielding designs that complicate thermal management in compact active speaker architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Speaker Cabinets, Grilles and Materials Market |
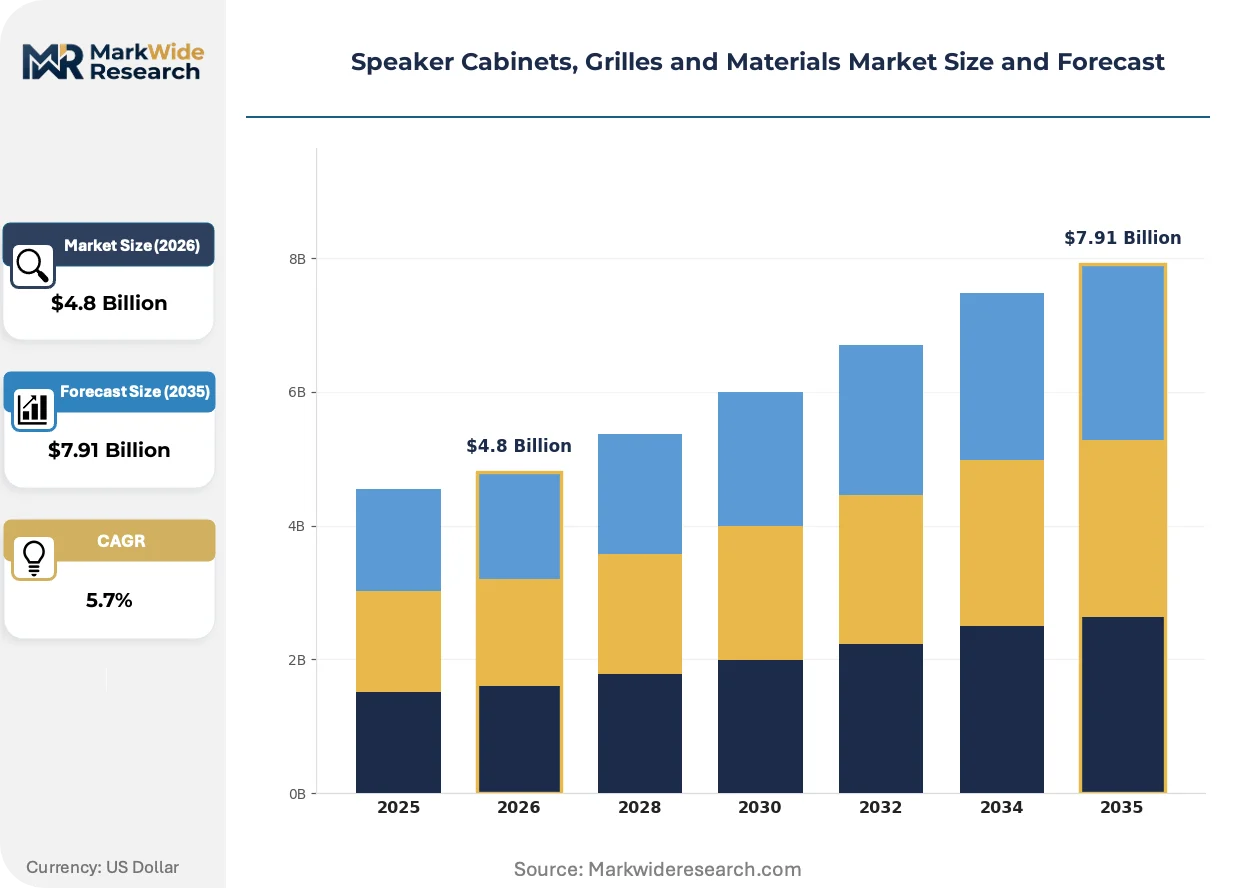
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passive Cabinets, Active Cabinets, Grilles, Components Material: Wood, MDF, Plastic, Metal End User: Consumer Electronics, Professional Audio, Automotive, Home Theater Application: Portable Sound Systems, Home Audio, Studio Monitors, Public Address |
| Companies Covered | Foshan Hongyu, Wendell Fabrics Corporation, Mojotone, Acoustone, Dongxingli, Taizhou Jinjue Mesh Screen, Simply Speakers, B&C Speakers, SB Acoustics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Speaker Cabinets, Grilles and Materials Market Evolving Landscape
Material science advances and regulatory stringency are converging to reshape competitive positioning across enclosure substrates and protective grille systems. Three developments are actively restructuring supplier capabilities and buyer procurement criteria.
Glass-reinforced polypropylene compounds are displacing mineral-filled ABS in portable sound system enclosures, offering superior impact resistance at reduced wall thickness. Live event rental companies in the United States and Germany are specifying these materials for flyable subwoofer cabinets where weight reduction directly affects rigging costs. The shift is compressing margins for legacy injection molders without compounding expertise or automotive-tier quality certifications.
REACH restrictions on halogenated flame retardants are forcing reformulation of MDF and plastic substrates bound for European professional installations. Suppliers must now certify phosphorus-based or nitrogen-based alternatives through extended burn-test protocols before CE marking eligibility. German and Dutch cabinet OEMs are consolidating supplier bases to those with in-house flame-retardant compounding capabilities, disqualifying distributors of commodity substrates.
Certification-driven procurement is consolidating buyer-seller relationships around qualified material suppliers with multi-jurisdiction compliance documentation. Studio monitor manufacturers in the United Kingdom and Japan are unbundling grille cloth sourcing from cabinet fabrication, contracting directly with acoustically transparent synthetic weave specialists. Direct material sourcing is compressing traditional distributor margins while rewarding textile suppliers with IEC acoustic transparency certifications and SAMR formaldehyde compliance documentation.
Speaker Cabinets, Grilles and Materials Market Segmentation
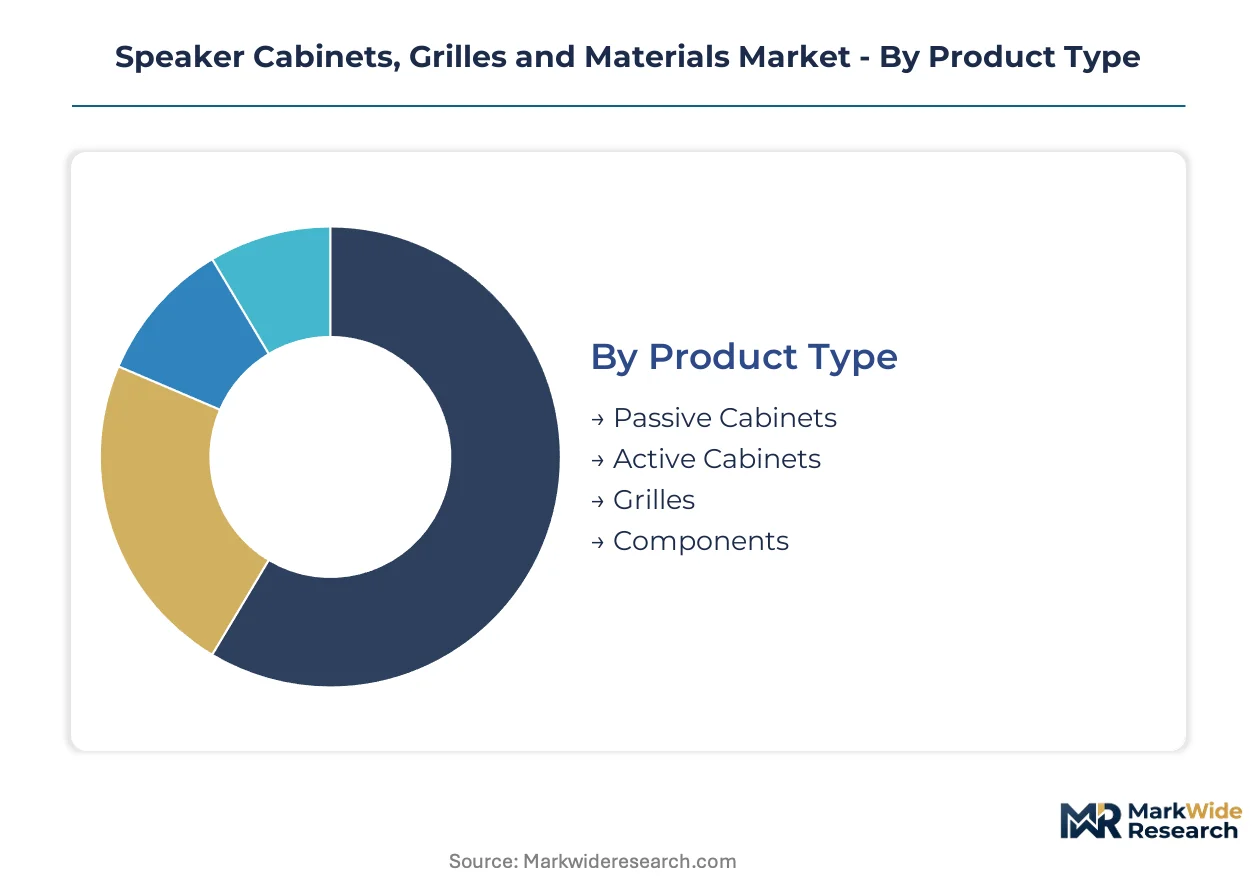
Segmentation in speaker cabinets, grilles and materials determines procurement routing, margin capture, and regulatory compliance pathways. Channel strategies diverge sharply between mass-market consumer electronics and certified professional installations.
Product Type:
Channel routing splits between OEM direct supply for active cabinets and distributor networks for passive enclosures and replacement grilles.
- Passive Cabinets:Unpowered enclosures rely on external amplification and dominate home theater and studio monitor configurations. Baltic birch plywood variants flow through specialty audio distributors in Germany and the United States, while MDF-based units reach consumer markets via mass retail channels.
- Active Cabinets:Integrated amplifier-cabinet systems command premium positioning in touring audio and broadcast installations. Demand concentrates in live event rental fleets across the United Kingdom and Japan, where self-powered designs reduce setup complexity and cable inventory.
- Grilles:Protective fronts span metal mesh, fabric, and composite formulations. Aftermarket replacement demand sustains specialized textile suppliers with vintage-specification weaving capabilities.
- Components:Drivers, crossovers, and damping materials supply DIY builders and repair technicians through online specialty retailers.
Passive cabinets dominate installed base. Active cabinets are where expansion concentrates.
Material:
Cost tiers stratify sharply, with plastic injection-molded enclosures capturing automotive volume and wood substrates retaining professional audio premium positioning.
- Wood:Birch and pine plywood deliver superior damping coefficients for studio monitor and high-fidelity applications. Void-free Baltic birch remains supply-constrained, with German and Polish mills commanding price premiums for touring-grade stock.
- MDF:Medium-density fiberboard offers uniform machinability at mid-range price points. E0-grade certification under China's GB standards now gates access to home theater OEM contracts, disqualifying uncertified substrate suppliers.
- Plastic:Glass-reinforced polypropylene compounds are climbing the fastest in portable sound system applications, driven by live event rental demand for flyable, impact-resistant enclosures.
- Metal:Aluminum and steel enclosures serve industrial public address installations and outdoor-rated permanent deployments where weather resistance overrides acoustic optimization.
MDF holds volume leadership across consumer tiers. Plastic compounds are gaining share fastest in weight-sensitive segments.
End User:
Customer type dictates specification stringency, with professional audio and automotive channels demanding certified compliance documentation that consumer electronics bypass.
- Consumer Electronics:Portable Bluetooth speakers and entry-level home audio systems prioritize cost-optimized MDF and plastic enclosures. FCC electromagnetic compatibility requirements govern shielding performance for US-bound products.
- Professional Audio:Concert venues, broadcast studios, and live event rental companies specify REACH-compliant substrates and IP-rated grille treatments. CE marking under the EU Construction Products Regulation gates supplier eligibility for fire-rated installations in France, Italy, and Spain.
- Automotive:Door-panel and dashboard integrations demand lightweight plastic formulations to satisfy fuel economy regulations in Japan and South Korea. Tier-1 suppliers require IATF quality certifications and formaldehyde emission documentation.
- Home Theater:Custom installation channels favor veneered MDF and genuine wood finishes, with E0-grade particleboard mandates from China's SAMR reshaping supplier qualification requirements.
Consumer electronics commands unit volume. Professional audio delivers margin concentration.
Application:
Use-case environments determine durability specifications and grille treatment requirements, from climate-controlled studios to exposed outdoor deployments.
- Portable Sound Systems:Battery-powered and flyable enclosures prioritize impact-resistant plastic compounds. German and US rental companies are specifying glass-reinforced polypropylene for subwoofer cabinets where rigging costs scale with weight.
- Home Audio:Bookshelf and floor-standing speakers favor MDF construction with vinyl or wood veneer finishes. Acoustic performance requirements are less stringent than studio applications, permitting cost-optimized substrate selection.
- Studio Monitors:Nearfield and midfield reference speakers demand cabinet damping coefficients that minimize coloration. Birch plywood retains preference over MDF for critical listening environments in the United Kingdom and Japan.
- Public Address:Stadium, transportation hub, and emergency notification installations require weather-resistant metal or treated plastic enclosures with hydrophobic grille fabrics. IP ratings govern outdoor procurement specifications.
Home audio sustains baseline demand. Portable sound systems are where technology substitution is most active.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Professional audio buyers concentrate in Germany, the United States, Japan, China, and the United Kingdom, each presenting distinct procurement patterns tied to local venue construction cycles and regulatory enforcement timelines.
Germany
Live event rental companies and broadcast studios drive specification-grade cabinet demand for touring-grade active systems. ECHA REACH restrictions on halogenated flame retardants compel substrate suppliers to certify phosphorus-based alternatives before CE marking eligibility. Hamburg and Berlin host clusters of cabinet OEMs consolidating supplier bases to qualified compounders with in-house flame-retardant capabilities.
United States
Concert venues in Nashville and Los Angeles specify hydrophobic fabric grille treatments for outdoor amphitheater deployments. FCC electromagnetic compatibility standards govern cabinet shielding performance for consumer electronics distribution. Mojotone anchors aftermarket supply from North Carolina, where vintage-specification grille cloth production serves tube amplifier restoration markets.
Japan
Studio monitor manufacturers in Tokyo and Osaka demand birch plywood enclosures with superior damping coefficients for critical listening environments. METI fuel economy regulations accelerate plastic injection-molded enclosure adoption in automotive door-panel integrations. Kanto-based tier-1 suppliers require IATF quality certifications and formaldehyde emission documentation for home theater OEM contracts.
China
Guangdong Province absorbs the majority of new capacity for MDF and treated wood cabinet substrates serving export markets. SAMR-administered GB standards limit formaldehyde emissions from engineered wood products, compelling E0-grade particleboard certification. Foshan Hongyu leverages integrated plywood lamination lines across its Guangdong operations to control raw material costs for professional audio OEMs.
United Kingdom
Broadcast studios in London and Manchester specify REACH-compliant composite grille materials combining acoustic transparency with impact resistance. CE marking under the EU Construction Products Regulation gates supplier eligibility for fire-rated installations in professional channels. Wendell Fabrics Corporation sustains niche positioning from its UK base in acoustically transparent synthetic grille cloths for studio monitor applications.
Speaker Cabinets, Grilles and Materials Market Competitive Landscape
Player mix skews toward specialized material suppliers and integrated fabricators with multi-jurisdiction compliance documentation. The vendor base separates into three tiers: large-scale substrate compounders with automotive-tier certifications, mid-size cabinet OEMs with regional market focus, and niche textile specialists serving aftermarket restoration segments. Competitive dynamics center on CE marking pre-qualification for European professional channels and SAMR E0-grade certification for Chinese home theater contracts.
Among specialized suppliers, Wendell Fabrics Corporation occupies a position exemplifying acoustically transparent synthetic weave expertise for studio applications. Mojotone anchors the aftermarket guitar amplifier segment where vintage-specification grille cloth commands premium positioning. Foshan Hongyu represents the integrated plywood lamination model controlling raw material costs across Guangdong operations. These three entities illustrate how compliance documentation and specialized weaving capabilities determine supplier viability in procurement consolidation trends.
| Leading Market Players |
|---|
| Foshan Hongyu |
| Wendell Fabrics Corporation |
| Mojotone |
| Acoustone |
| Dongxingli |
| Taizhou Jinjue Mesh Screen |
| Simply Speakers |
| B&C Speakers |
| SB Acoustics |
| Others |
Value Network & Pricing Analysis
Guangdong's integrated plywood lamination clusters generate scale economies that compress raw material conversion costs by fifteen to twenty percent against fragmented Baltic suppliers, concentrating margin capture among vertically integrated fabricators while establishing price floors for uncertified substrate distributors. This concentration dynamic bifurcates procurement power between E0-grade certified compounders serving home theater OEMs and commodity MDF distributors locked out of SAMR-compliant contracts.
Pricing Analysis
Cost-plus contracts with Baltic birch indexation dominate touring-grade active cabinet procurement, with German and Polish mill prices setting baseline reference points for impact-resistant enclosures. Price differentiation separates REACH-certified phosphorus-based formulations from legacy halogenated alternatives, with CE marking eligibility commanding fifteen to twenty percent premiums in French and Italian professional channels. Pricing pressure stems from automotive lightweighting mandates in Japan and South Korea, where plastic injection molders absorb margin compression to secure tier-1 door-panel volumes. Consumer electronics buyers exhibit highest price sensitivity, while broadcast studios and live event rental companies prioritize acoustic performance and compliance documentation over unit cost.
Supply Chain Analysis
Strategic stockpiling of void-free Baltic birch ply characterizes touring-grade cabinet OEM procurement, contrasting with just-in-time MDF flows from Guangdong mills serving mass-market consumer electronics. Supply concentrates in China for engineered wood substrates, the Baltic region for premium plywood, and Germany for flame-retardant compounding capabilities. Raw material dependencies include phenolic resin binders, glass-reinforced polypropylene pellets, and acoustically transparent synthetic yarns. Single-source vulnerability runs through Baltic birch suppliers, where Estonian and Latvian mill consolidation limits alternative sourcing for impact-resistant touring enclosures. Distribution runs through specialty audio distributors for professional channels and mass retail networks for consumer tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory entrenchment story, where multi-jurisdiction compliance documentation creates switching costs that cement incumbent positions and raise barriers for uncertified challengers.
For Market Incumbents: Consolidate supplier relationships around in-house flame-retardant compounding capabilities to meet ECHA REACH requirements without distributor markups. Capture backward integration into E0-grade particleboard production in Guangdong to secure SAMR-compliant substrate supply for home theater OEM contracts. Defend against emerging composite-metal hybrid grille specialists by locking exclusive procurement relationships with acoustically transparent synthetic weave vendors. For New Entrants and Emerging Players: Lead with aftermarket guitar amplifier restoration demand in the United States and United Kingdom, where vintage-specification grille cloth production sustains small-batch economics outside automotive-tier certification requirements. Target portable sound system applications with glass-reinforced polypropylene enclosures, penetrating live event rental fleets through weight-driven rigging cost savings. Establish direct material sourcing relationships with studio monitor manufacturers unbundling grille cloth procurement from cabinet fabrication. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized textile suppliers with IEC acoustic transparency certifications and multi-jurisdiction compliance documentation over commodity substrate distributors facing margin compression. Long-term viability rests on regulatory entrenchment depth rather than volume scale, with five-to-ten year windows favoring acquisition targets holding CE marking pre-qualification and SAMR E0-grade certification. Watch for ISO and IEC cabinet damping coefficient test standard revisions as inflection indicators that invalidate legacy qualification data and trigger laboratory investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Flame-Retardant Compounding | ECHA REACH compliance secures CE marking eligibility for German and Dutch cabinet OEMs. |
| E0-Grade Particleboard Certification Investment | SAMR GB standard compliance gates access to China's home theater OEM procurement channels. |
| Direct Grille Cloth Sourcing Unbundling | Studio monitor manufacturers in Japan and the United Kingdom bypass traditional distributor margins. |
| Glass-Reinforced Polypropylene Capacity Addition | METI fuel economy regulations in Japan accelerate automotive door-panel integration demand. |
| Vintage-Specification Weaving Capability Acquisition | Aftermarket tube amplifier restoration markets in the United States sustain premium positioning. |
Research Methodology
Desk research of customs trade databases, SEC 10-K filings from listed audio equipment manufacturers, and ECHA regulatory guidance documents preceded structured interviews with cabinet OEM procurement directors, live event rental fleet managers, acoustic textile R&D leads, and SAMR certification consultants. Primary fieldwork captured procurement consolidation trends, reformulation timelines for phosphorus-based flame retardants, and unbundling patterns in grille cloth sourcing. Secondary validation drew from IEC acoustic measurement working group publications, FSC chain-of-custody certification registries, and IATF automotive quality audit disclosures. Bottom-up volume builds triangulated against top-down spending estimates from professional audio installation contractors.
Variance decomposition across material grade tiers, end-user segments, and regional regulatory clusters structured the analytical framework over the projection horizon. Modeled segmentation spanned enclosure substrates, grille formulations, and application durability requirements, with geographic supply concentration and certification penetration rates as cross-cutting dimensions. CAGRs derived from installed base turnover cycles, venue construction pipelines, and automotive platform refresh schedules. Industry-specific forecast inputs included flyable subwoofer cabinet weight specifications and E0-grade particleboard adoption curves in Chinese home theater channels.
Forecasts assume regulatory continuity in ECHA REACH enforcement, SAMR GB standard administration, and FCC electromagnetic compatibility regimes; material policy shifts would require re-modeling substrate qualification pathways and supplier eligibility tiers. Specific risks that could revise projections include ISO/IEC cabinet damping coefficient standard revisions invalidating legacy test data, Baltic birch supply disruptions from geopolitical developments, and accelerated halogenated flame-retardant phase-outs beyond current ECHA timelines. Revision becomes warranted when certification documentation costs cross thresholds that trigger supplier base consolidation or distributor exit.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Audio Equipment
Global Automotive Premium Audio System Market
Audio Equipment
Consumer Audio Market
Audio Equipment
Japan Gaming Headset Market
Audio Equipment
Canada Gaming Headsets Market
Audio Equipment
Motorcycle Audio Systems Market
Audio Equipment
Asia-Pacific Wireless Audio Market
Audio Equipment
Mixing Console Market
Audio Equipment
Wireless Audio Products Market
Audio Equipment
Global Wireless Audio Market
Audio Equipment
Amps & Effects Market
Audio Equipment
Speaker Driver Market
Audio Equipment
Radio Headset Market
Audio Equipment
Home Audio Equipment Market
Audio Equipment
Portable Audio Amplifier Market
Audio Equipment
Studio Headphones Market
Audio Equipment
Digital a/V Decoder Market