
 US Aromatherapy Diffusers Market | 2026-2036
US Aromatherapy Diffusers Market Size, Share, and Industry Trends Forecast 2026-2036
US Aromatherapy Diffusers Market Insights
Subscription-based essential oil replenishment services is consolidating the traditional hardware-plus-consumables model into recurring revenue architectures. dōTERRA leverages its captive member network to sustain high attach rates for ultrasonic diffuser hardware. Young Living Essential Oils anchors its positioning through vertically controlled botanical sourcing that differentiates its nebulizing product line. Newell Brands competes via mass retail channel control, occupying shelf space across big-box and e-commerce platforms with programmable technology variants.
An aromatherapy diffuser disperses essential oils into ambient air through ultrasonic vibration, pressurized nebulization, thermal evaporation, or passive wick-based methods, typically operating at frequencies between 1.6 and 2.4 MHz for ultrasonic units to produce micro-fine mist without heat degradation of terpene compounds. These devices serve residential wellness routines, commercial hospitality environments, clinical healthcare settings, and spa treatment rooms where controlled olfactory delivery supports stated therapeutic or atmospheric objectives. Ultrasonic diffusers command the largest installed base due to lower unit economics and quieter operation, while nebulizing formats capture premium positioning through unheated oil preservation that appeals to clinical and high-end spa procurement. Bluetooth-enabled technology segments are expanding fastest as consumers integrate diffusers into smart home ecosystems, though manual and programmable categories retain dominance in cost-sensitive commercial channels where IT infrastructure constraints limit connectivity adoption.
The Federal Trade Commission enforces substantiation standards for health-related advertising claims attached to diffuser and essential oil bundles, while the Consumer Product Safety Commission monitors electrical safety compliance for plugged ultrasonic and heat-based units. California's Proposition 65 mandates warning labels for specific chemical exposures, directly affecting glass and metal material sourcing decisions and packaging design for products sold into that state. Stakeholders must monitor whether the FTC expands enforcement against unsubstantiated wellness claims and whether CPSC considers mandatory automatic shutoff standards for unattended residential operation, as these regulatory vectors will determine which technology and material configurations retain market access.
Market Dynamics
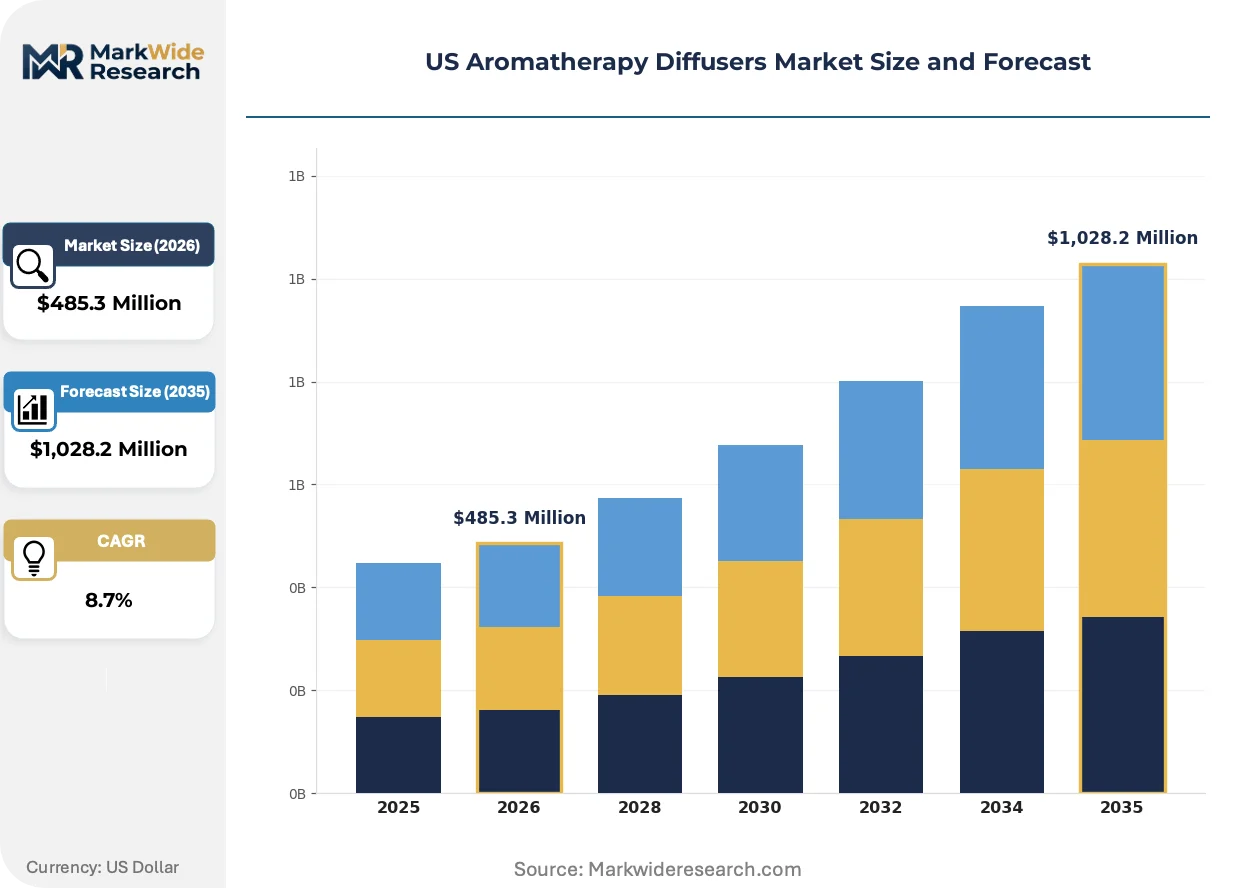
Subscription-based essential oil replenishment services are consolidating the traditional hardware-plus-consumables model into recurring revenue architectures, forcing manufacturers to reconfigure product lifecycles around attach rates rather than standalone unit sales.
Growth Catalysts
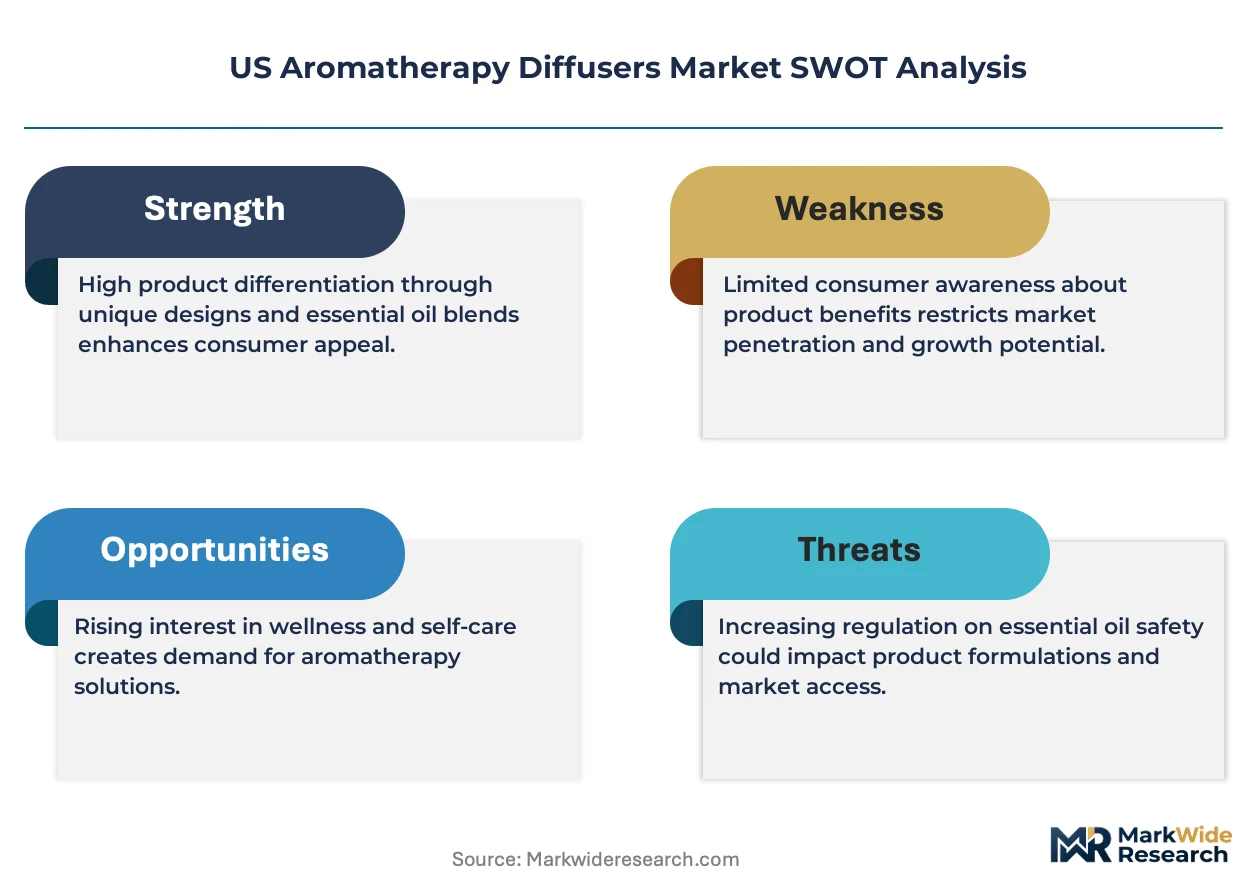
- FTC substantiation requirements:Stricter enforcement against unsubstantiated wellness claims is filtering out low-quality competitors and elevating compliant brands with documented terpene preservation data.
- Bluetooth-enabled smart home integration:Residential consumers in California and Texas are demanding app-controlled scheduling and voice-assistant compatibility, expanding the addressable premium segment.
- Spa-sector procurement concentration:Commercial hospitality buyers in Florida are standardizing on nebulizing formats for treatment rooms, creating predictable replacement cycles for high-durability hardware.
Market Restraints
- California Proposition 65 compliance costs:Warning label mandates for specific chemical exposures in glass and metal components are increasing packaging design expenses and material sourcing complexity for products sold into that state.
- Essential oil supply concentration:Vertically controlled botanical sourcing by incumbent oil suppliers limits independent diffuser manufacturers' ability to bundle competitive consumables.
- Heat-based model obsolescence:Thermal evaporation technology faces accelerated displacement as ultrasonic and nebulizing formats demonstrate superior terpene compound preservation.
Strategic Opportunities
- Underpenetrated clinical healthcare settings:Hospital wellness programs and outpatient clinics in Texas represent an emerging application vertical for controlled olfactory delivery systems with documented therapeutic protocols.
- FCC connectivity certification tailwinds:Streamlined approval pathways for low-power Bluetooth devices are reducing time-to-market for smart diffuser variants targeting residential automation ecosystems.
- Direct-to-consumer channel innovation:Essential oil subscription services are bypassing traditional retail markups, enabling manufacturers to capture lifetime value through recurring consumable revenue.
Industry Challenges
- CPSC electrical safety certification timelines:Mandatory testing for automatic shutoff mechanisms in unattended residential operation is extending product launch schedules and increasing validation costs.
- Smart home platform fragmentation:Integration complexity across incompatible voice-assistant and home-automation protocols is forcing manufacturers to maintain multiple firmware variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Aromatherapy Diffusers Market |
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $1,028.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasonic, Nebulizing, Heat-Based, Evaporative Technology: Bluetooth, Wi-Fi, Manual, Programmable Material: Plastic, Glass, Wood, Metal End User: Residential, Commercial, Healthcare, Spa |
| Companies Covered | Young Living Essential Oils, dōTERRA, Newell Brands, NOW Foods, Edens Garden, Organic Aromas, Greenair, Plant Therapy, Escents Aromatherapy, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Aromatherapy Diffusers Market Trends and Innovations
Active sensor integration and algorithmic mist control are transforming diffusers from passive appliances into responsive wellness devices, while regulatory pressure on health claims is accelerating documentation investments across the supply chain.
Ultrasonic vibration technology operating between 1.6 and 2.4 MHz is rewriting the competitive landscape for residential wellness routines. Home automation enthusiasts in California and Texas are adopting frequency-modulated units that adjust output based on ambient humidity sensors. This capability is rewriting margin structures as manufacturers compete on firmware sophistication rather than hardware commoditization.
The Federal Trade Commission's substantiation standards for health-related advertising claims are tightening enforcement against diffuser and essential oil bundles. Manufacturers must now maintain clinical documentation for any stated therapeutic benefit, raising compliance costs for smaller competitors. Wellness-focused residential consumers in Florida are gravitating toward brands with published terpene preservation studies, rewarding documented performance over marketing assertions.
Spa-sector buyers are compressing replacement cycles through essential oil subscription tie-ins that bundle hardware refreshes with consumable replenishment. Commercial hospitality procurement in Texas and California is shifting from capital expenditure models to per-treatment-room service contracts. This pattern is most visible in resort properties where operational simplicity outweighs upfront cost minimization.
US Aromatherapy Diffusers Market Segmentation
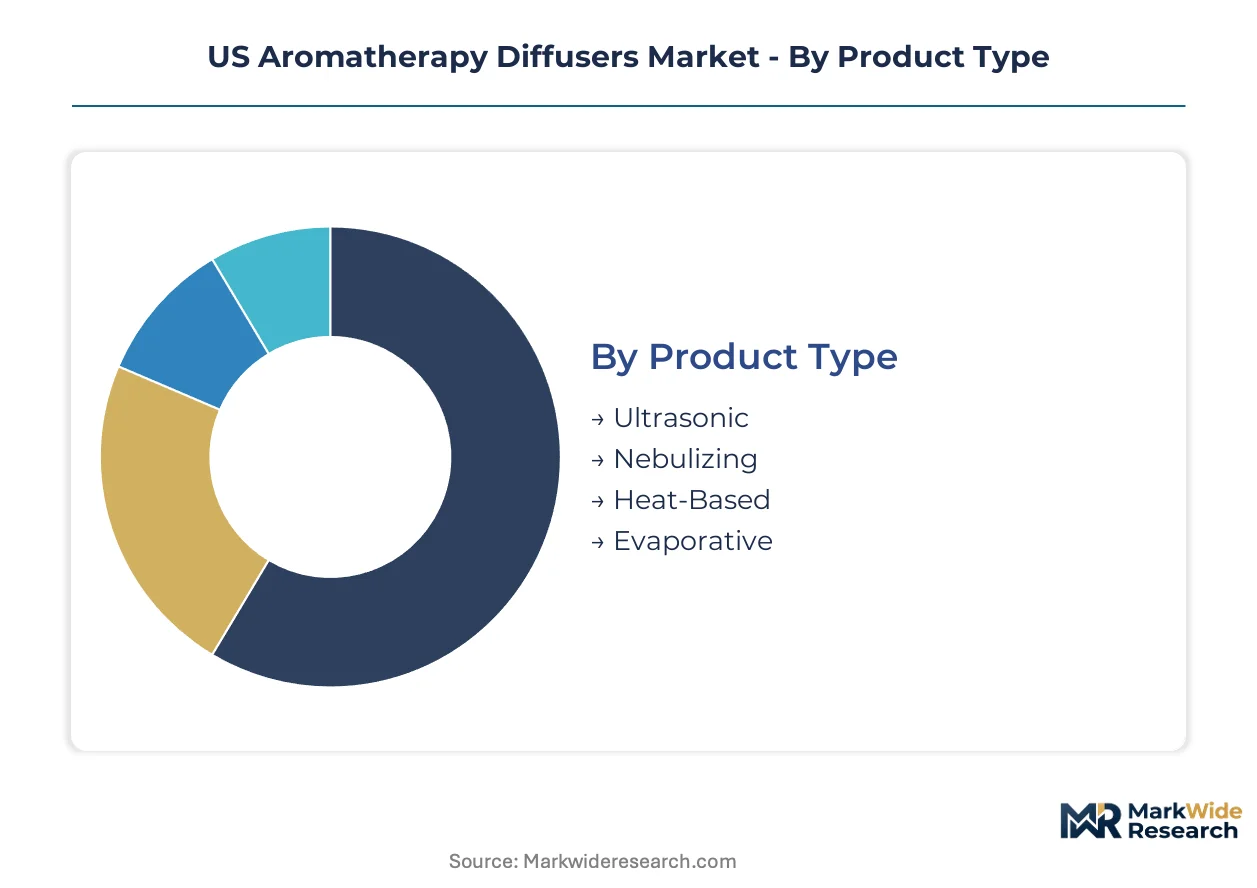
Segmentation in the US aromatherapy diffusers market tracks how replacement cycles and upgrade incentives vary across hardware formats, connectivity tiers, and end-use environments. Manufacturers configure warranty terms and subscription attach rates differently for each segment to maximize lifetime value.
Product Type:
Replacement cycles differ sharply across diffusion mechanisms, with ultrasonic units driving volume through shorter functional lifespans and nebulizing formats extending hardware longevity through modular component design.
- Ultrasonic:These units operate at 1.6 to 2.4 MHz frequencies to generate micro-fine mist without thermal degradation of terpene compounds. Demand concentrates in California residential wellness routines where quieter operation and lower unit economics favor mass adoption. The FTC's substantiation requirements for health claims are pushing manufacturers toward documented frequency stability specifications.
- Nebulizing:Pressurized atomization preserves essential oil integrity through unheated dispersion, commanding premium positioning in Florida spa treatment rooms where therapeutic protocol credibility matters. Commercial hospitality buyers standardize on these formats for predictable replacement cycles tied to service contracts.
- Heat-Based:Thermal evaporation technology faces accelerated displacement as ultrasonic alternatives demonstrate superior compound preservation.
- Evaporative:Passive wick-based diffusion occupies entry-level price tiers with minimal electrical complexity.
Ultrasonic sits at the top of the volume ranking, with nebulizing climbing the fastest as spa-sector procurement standardizes on unheated preservation formats.
Technology:
Connectivity tier determines margin structure and customer acquisition cost, with smart home integration commanding premium pricing while manual formats retain commercial channel dominance.
- Bluetooth:Low-power wireless protocols enable app-controlled scheduling and voice-assistant compatibility for residential automation ecosystems in Texas and California. FCC certification streamlining is reducing time-to-market for these variants.
- Wi-Fi:Full internet connectivity supports remote monitoring and firmware updates, appealing to hospitality operators managing distributed property portfolios.
- Manual:Simple dial or button controls dominate cost-sensitive commercial channels where IT infrastructure constraints limit connectivity adoption.
- Programmable:Timer-based operation without wireless connectivity occupies the mid-tier for residential users seeking scheduling convenience without smart home ecosystem dependencies.
Manual controls retain the largest installed base, though Bluetooth-enabled variants are expanding most quickly as home automation penetration deepens in key states.
Material:
California Proposition 65 compliance costs are reshaping material sourcing decisions, with warning label mandates favoring certain compositions over others in the largest state market.
- Plastic:Injection-molded polymer housings dominate mass retail channels due to manufacturing scalability and color customization options.
- Glass:Borosilicate and hand-blown components face heightened regulatory scrutiny under chemical exposure warning requirements, increasing packaging design expenses.
- Wood:Bamboo and hardwood finishes command aesthetic premiums in residential wellness segments where natural material associations reinforce brand positioning.
- Metal:Aluminum and stainless steel elements trigger Proposition 65 labeling obligations that complicate supply chain configuration for California-bound products.
Plastic leads by unit volume, while wood is gaining share fastest among wellness-focused consumers prioritizing natural material aesthetics.
End User:
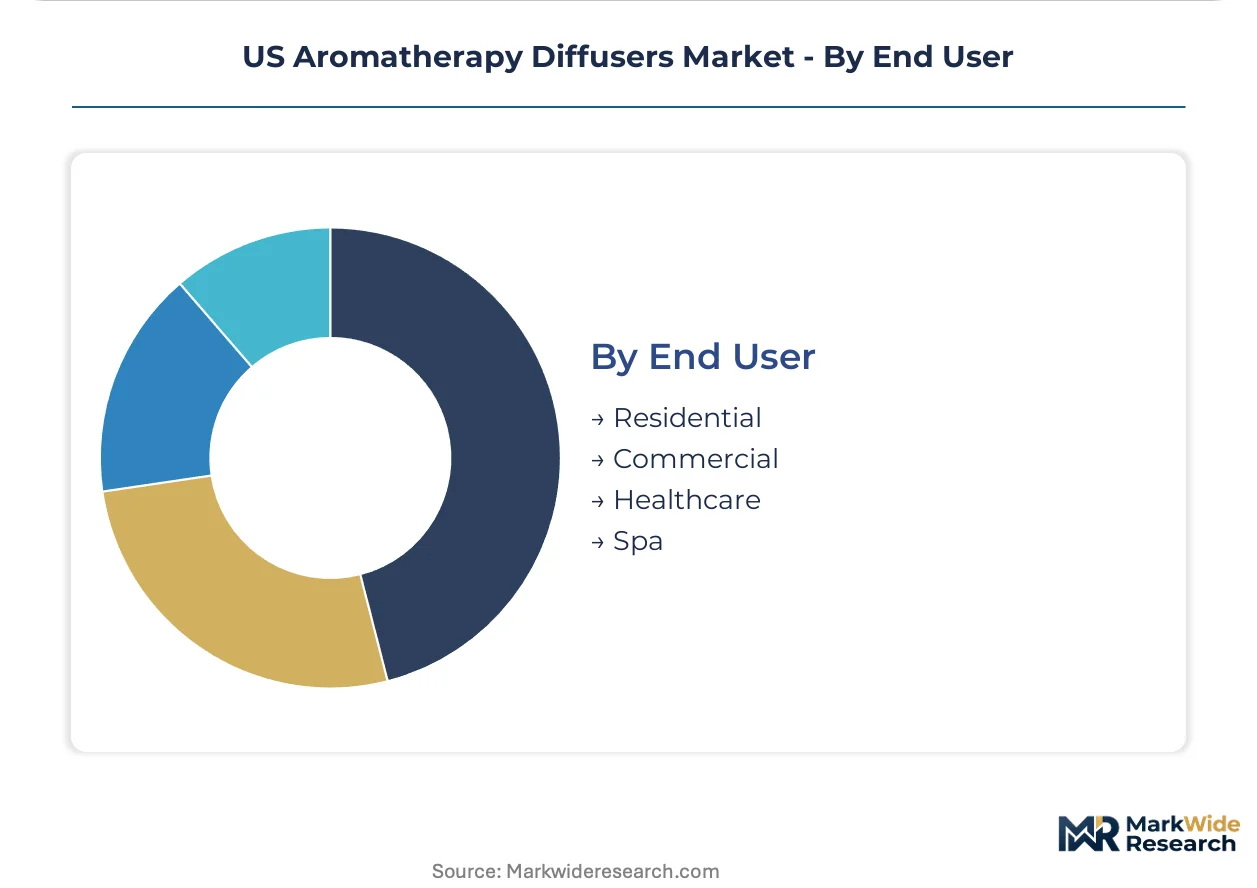
Customer type determines procurement modality and attach rate potential, with subscription service compatibility varying significantly across residential, commercial, and institutional buyers.
- Residential:Wellness-focused consumers in California, Texas, and Florida drive replacement cycles through direct-to-consumer essential oil subscriptions that bundle hardware refreshes with consumable replenishment.
- Commercial:Hospitality operators in Florida and Texas are shifting from capital expenditure models to per-treatment-room service contracts that prioritize operational simplicity.
- Healthcare:Hospital wellness programs and outpatient clinics in Texas represent an emerging vertical for controlled olfactory delivery systems requiring documented therapeutic protocols.
- Spa:Treatment room procurement concentrates in resort properties where nebulizing format standardization creates predictable hardware replacement schedules.
Residential captures the greatest unit volume, with healthcare demonstrating the steepest expansion trajectory as clinical settings adopt documented aromatherapy protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are pushing manufacturing toward states with lower Proposition 65 compliance burdens, while demand concentrates where wellness expenditure and spa-sector density create replacement-cycle velocity.
California
Residential wellness consumers in Los Angeles and San Francisco Bay Area drive ultrasonic unit volume through subscription-tied hardware refreshes. The state's Proposition 65 warning label mandates elevate packaging costs for glass and metal components, compressing margins on premium-format imports. San Diego's spa-sector procurement standardizes on nebulizing formats for treatment-room service contracts.
Texas
Hospital wellness programs in Houston and Dallas-Fort Worth represent emerging clinical demand for documented therapeutic protocols. The state's lighter regulatory burden on material sourcing attracts distributors serving California-bound products through fulfillment arbitrage. Austin's direct-to-consumer brands leverage lower operational costs to undercut coastal competitors on essential oil subscription pricing.
Florida
Resort properties in Miami and Orlando compress replacement cycles through per-treatment-room service contracts bundling nebulizing hardware with consumable replenishment. The state's hospitality procurement concentration rewards operational simplicity over upfront cost minimization. Tampa's outpatient clinic networks pilot controlled olfactory delivery systems for patient anxiety management.
New York Metro
Urban residential density in Manhattan and Brooklyn sustains demand for compact ultrasonic units with smart home integration. The region's retail channel concentration forces manufacturers to compete on programmable technology variants for big-box placement. Connecticut's suburban wellness consumers extend replacement cycles through premium-brand loyalty.
Pacific Northwest
Seattle and Portland's sustainability-conscious consumers favor bamboo and hardwood material finishes over plastic housings. The region's lower spa-sector density limits commercial procurement volume relative to residential wellness routines. Vancouver-area cross-border sourcing complicates FTC substantiation documentation for health claims on bundled essential oil products.
US Aromatherapy Diffusers Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with vertically integrated oil suppliers capturing hardware attach rates through captive distribution networks. The market exhibits moderate concentration at the top tier, where member-based essential oil companies sustain recurring revenue architectures that independent manufacturers cannot replicate. Three archetypes dominate: oil-first integrators controlling consumable supply, mass-retail channel operators optimizing shelf-space economics, and technology-forward specialists betting on smart home ecosystem integration. Competitive moves center on backward integration into botanical sourcing and FCC certification acceleration for Bluetooth-enabled variants.
Within the oil-first integrator tier, Young Living Essential Oils and dōTERRA exemplify how captive member networks sustain high hardware attach rates through subscription-locked replenishment cycles. Newell Brands occupies a position representing mass-retail channel control, anchoring programmable technology variants across big-box and e-commerce platforms where shelf-space economics outweigh ecosystem integration. These three companies collectively illustrate how consumable bundling, retail scale, and smart home connectivity represent divergent vectors for margin defense.
| Leading Market Players |
|---|
| Young Living Essential Oils |
| dōTERRA |
| Newell Brands |
| NOW Foods |
| Edens Garden |
| Organic Aromas |
| Greenair |
| Plant Therapy |
| Escents Aromatherapy |
| Others |
Pricing and Supply Chain Analysis
Essential oil subscription bundling by wellness-focused residential consumers in California and Texas is forcing manufacturers to absorb hardware margin compression in exchange for recurring consumable revenue, which in turn concentrates sourcing decisions on ultrasonic component suppliers capable of tiered volume pricing.
Pricing Analysis
Retailer markup layers in mass retail channels drive three-tier pricing structure across premium, standard, and economy levels for ultrasonic units, with differentiation anchored in Bluetooth certification grade and firmware sophistication. Price erosion runs through entry-level heat-based formats as ultrasonic alternatives capture volume. Spa-sector procurement in Florida demonstrates lowest price sensitivity due to per-treatment-room service contract structures, while direct-to-consumer residential buyers in Texas exhibit highest elasticity.
Supply Chain Analysis
ETL and FCC certification gating for Bluetooth-enabled variants concentrates final assembly in China, Mexico, and domestic US contract manufacturers serving California-bound products. Component sourcing draws from Taiwanese semiconductor suppliers for ultrasonic vibration modules, Chinese injection molders for polymer housings, and Vietnamese wood finishers for premium residential aesthetics. Single-source vulnerability sits with MEMS frequency control chips. Distribution runs through big-box retail consolidation, direct-to-consumer fulfillment centers, and hospitality GPO contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US aromatherapy diffusers market functions as a stable compounder where subscription-locked consumable replenishment generates predictable replacement-cycle revenue that smooths hardware demand volatility.
For Market Incumbents: Lock in captive member networks through vertically controlled essential oil sourcing that prevents independent hardware manufacturers from bundling competitive consumables. Invest in FCC certification acceleration for Bluetooth-enabled variants before smart home platform fragmentation hardens. Prioritize California Proposition 65 compliance documentation to defend shelf access against smaller competitors facing packaging cost compression. For New Entrants and Emerging Players: Begin with clinical healthcare settings in Texas where hospital wellness programs lack established supplier relationships and documented therapeutic protocols create credentialing barriers for incumbents. Target outpatient anxiety management applications with nebulizing formats pitched to biomedical engineering committees. Pursue direct-to-consumer subscription models bypassing retail markup capture. For Investors and Strategic Acquirers: Asymmetric upside sits with technology-forward specialists possessing FCC-certified Bluetooth firmware stacks and hospitality GPO contract relationships. Long-term viability hinges on recurring revenue attach rates rather than standalone hardware margins. Watch for FTC enforcement expansion against unsubstantiated wellness claims as signal for compliant-brand valuation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Botanical Sourcing | Captive essential oil supply secures subscription bundling power against independent hardware competitors. |
| FCC Certification Acceleration | Streamlined Bluetooth approval reduces time-to-market for smart home ecosystem integration in California and Texas. |
| Direct-to-Consumer Channel Launch | Bypassing retail markup layers enables lifetime value capture through recurring consumable revenue architectures. |
| Clinical Healthcare Partnership | Hospital wellness program adoption in Houston and Dallas-Fort Worth opens documented therapeutic protocol vertical. |
| Proposition 65 Compliance Investment | California warning label readiness defends market access as regulatory scrutiny intensifies on glass and metal components. |
Research Methodology
Direct dialogue with product development executives at ultrasonic and nebulizing manufacturers, essential oil supply chain managers, spa procurement directors, and hospitality GPO contract administrators grounded qualitative findings in operational reality. Secondary validation drew from FTC enforcement actions, CPSC electrical safety filings, California Proposition 65 regulatory databases, and retail channel shipment data. Bottom-up unit volume estimates triangulated against top-down subscription service attach rate projections.
Segment-level outputs across the projection horizon reflect modeled interactions between hardware replacement cycles, consumable replenishment frequency, and connectivity tier adoption curves. Diffusion mechanism, technology tier, material composition, and end-use environment dimensions structured the analytical framework. CAGRs derived from regression analysis of historical subscription growth patterns and spa-sector procurement standardization trends, with ultrasonic frequency stability specifications and nebulizing component modularity serving as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including potential CPSC mandatory automatic shutoff standards, FTC expansion into wellness claim substantiation, and essential oil supply disruptions from climate-affected botanical regions. Forecasts reflect assumptions about regulatory stability and consumer subscription retention behavior. A model refresh is warranted upon material change in smart home platform consolidation dynamics or federal enforcement posture toward health-related advertising claims.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Products & Utilities
Europe Aromatherapy Diffuser Market
Home Products & Utilities
North America Aromatherapy Diffuser Market
Home Products & Utilities
Storage Basket Rack Market
Home Products & Utilities
Middle East and Africa Aromatherapy Diffuser Market
Home Products & Utilities
Netherlands Sustainable Mattress Market
Home Products & Utilities
Photo Frame Market
Home Products & Utilities
Windows Market
Home Products & Utilities
Global Stair Lifts Market
Home Products & Utilities
Wine Cabinets Market
Home Products & Utilities
Mosquito Screen Doors Market