
 Europe Leather Goods Market | 2026-2036
Europe Leather Goods Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Leather Goods Market Foresight
Asset-light licensing and brand-operated leasing arrangements is rewriting competitive entry barriers across European leather goods. LVMH Moët Hennessy Louis Vuitton SE anchors its dominance through captive tannery partnerships and vertical control over raw material flows. Hermès International S.A. differentiates via extreme scarcity economics and in-house artisan training that spans generations. Kering S.A. navigates sustainability scrutiny by investing in regenerative agriculture for leather sourcing.
Europe leather goods encompass finished articles crafted from tanned animal hides or skins, typically measuring 0.5 to 5 millimeters in thickness after chromium or vegetable tanning processes, serving both functional carriage and conspicuous consumption purposes. Handbags occupy the largest value pool within product type segmentation, while genuine leather commands premium positioning against rising synthetic alternatives. Online retail channels accelerate fastest among distribution pathways, though specialty stores retain margin superiority through experiential service and authentication trust.
REACH enforcement by ECHA restricts chromium VI and certain azo dyes in leather finishing, compelling tanneries toward vegetable-tanning revival or closed-loop water systems. CE marking obligations under the EU's general product safety framework govern chemical exposure limits for skin-contact articles. The EU Green Deal's carbon border adjustments will soon penalize imported leather with high embedded emissions. Stakeholders must monitor regulatory tightening on traceability mandates and decide whether to absorb compliance costs or reposition toward certified circular leather streams.
Market Dynamics
REACH enforcement by ECHA and the EU Green Deal's carbon border adjustments are compressing tannery margins while accelerating consolidation around Italian and Spanish manufacturing clusters with closed-loop water systems and certified vegetable-tanning capabilities.
Growth Catalysts
- Regenerative agriculture mandates:The EU Green Deal's soil health requirements are creating certified leather supply pools that command premium positioning from French and Italian luxury houses.
- Florence-Milan corridor concentration:Artisan manufacturing clusters in Tuscany and Lombardy concentrate rare hand-stitching skills that mechanized competitors cannot replicate at scale.
- Blockchain traceability protocols:Distributed ledger systems are enabling batch-level hide provenance verification that satisfies emerging French consumer disclosure expectations.
Market Restraints
- Chromium VI compliance costs:ECHA's tightening limits on hexavalent chromium residues in finished leather are forcing small tanneries toward costly analytical testing or exit.
- Bovine hide supply concentration:European slaughterhouse consolidation leaves tanneries dependent on three dominant raw material aggregators across France, Germany, and Ireland.
- Mycelium leather substitution:Bolt Threads and Modern Meadow biomaterials are capturing vegan-positioned handbag share from entry-level genuine leather SKUs.
Strategic Opportunities
- Spanish underpenetration:Andalusian tanneries in Ubrique and Alicante offer untapped artisan capacity for mid-luxury brands seeking Italian alternative supply.
- Direct-to-consumer channel emergence:Owned digital flagships bypass wholesale margin stacking while capturing first-party data on German and Dutch purchasing patterns.
- CSRD disclosure requirements:Corporate Sustainability Reporting Directive mandates are creating advisory service demand for leather goods firms needing Scope 3 emissions accounting.
Industry Challenges
- Master craftsperson succession gaps:Italian leatherworking schools in Scandicci and Santa Croce sull'Arno report enrollment declines threatening generational knowledge transfer.
- CE marking timeline compression:General Product Safety Regulation updates demand accelerated chemical migration testing that bottlenecks small-batch production schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Leather Goods Market |
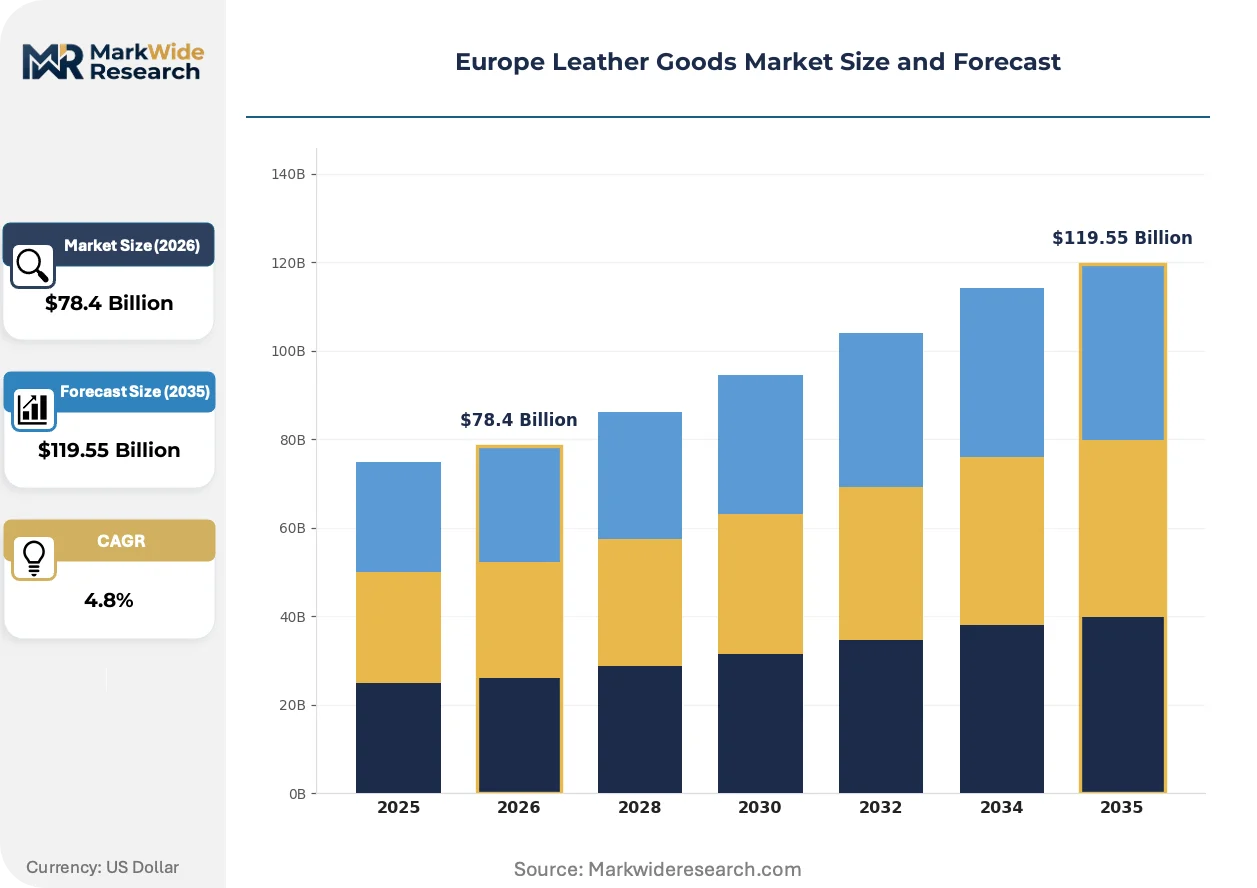
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $119.55 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handbags, Wallets, Belts, Footwear End User: Women, Men, Children, Businesses Distribution Channel: Online Retail, Specialty Stores, Department Stores, Outlets Material Type: Genuine Leather, Synthetic Leather, Suede, Nubuck |
| Companies Covered | Chanel SA, Prada S.p.A., LVMH Moët Hennessy Louis Vuitton SE, Samsonite IP Holdings S.A.R.L., Burberry Group, Kering S.A., Capri Holdings Limited, Ermenegildo Zegna Group, Hermès International S.A., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Leather Goods Market Shifts & Advancements
Digital product passports and regenerative sourcing credentials are redefining competitive differentiation in European leather goods, compressing the advantage window for legacy opacity while rewarding transparent supply chain investments.
Laser-cutting automation combined with robotic edge-finishing is rendering obsolete traditional die-cutting and manual burnishing workflows in high-volume Italian accessory production. Mid-tier manufacturers around Naples and Veneto are adopting these systems to maintain throughput despite rising labor costs. The technology is compressing batch minimums and enabling made-to-order economics previously reserved for artisan ateliers.
REACH Annex XVII restrictions on azo dyes and nickel release are forcing reformulation of finishing chemistries across Spanish and Portuguese tanneries. ECHA's 2024-2025 substance evaluation roadmap threatens additional restrictions on chromium tanning salts. Vegetable-tanned output from Tuscan consortiums is expanding to preempt regulatory displacement and capture positioning premiums.
Certification-driven purchasing is redirecting procurement toward Leather Working Group-rated tanneries, particularly among German corporate gifting programs and Dutch retail buyers. Specialty stores in Paris and London are demanding audited traceability documentation as table stakes for shelf placement. This behavior concentrates volume with vertically integrated houses while fragmenting spot-market demand for uncertified hides.
Europe Leather Goods Market Segmentation
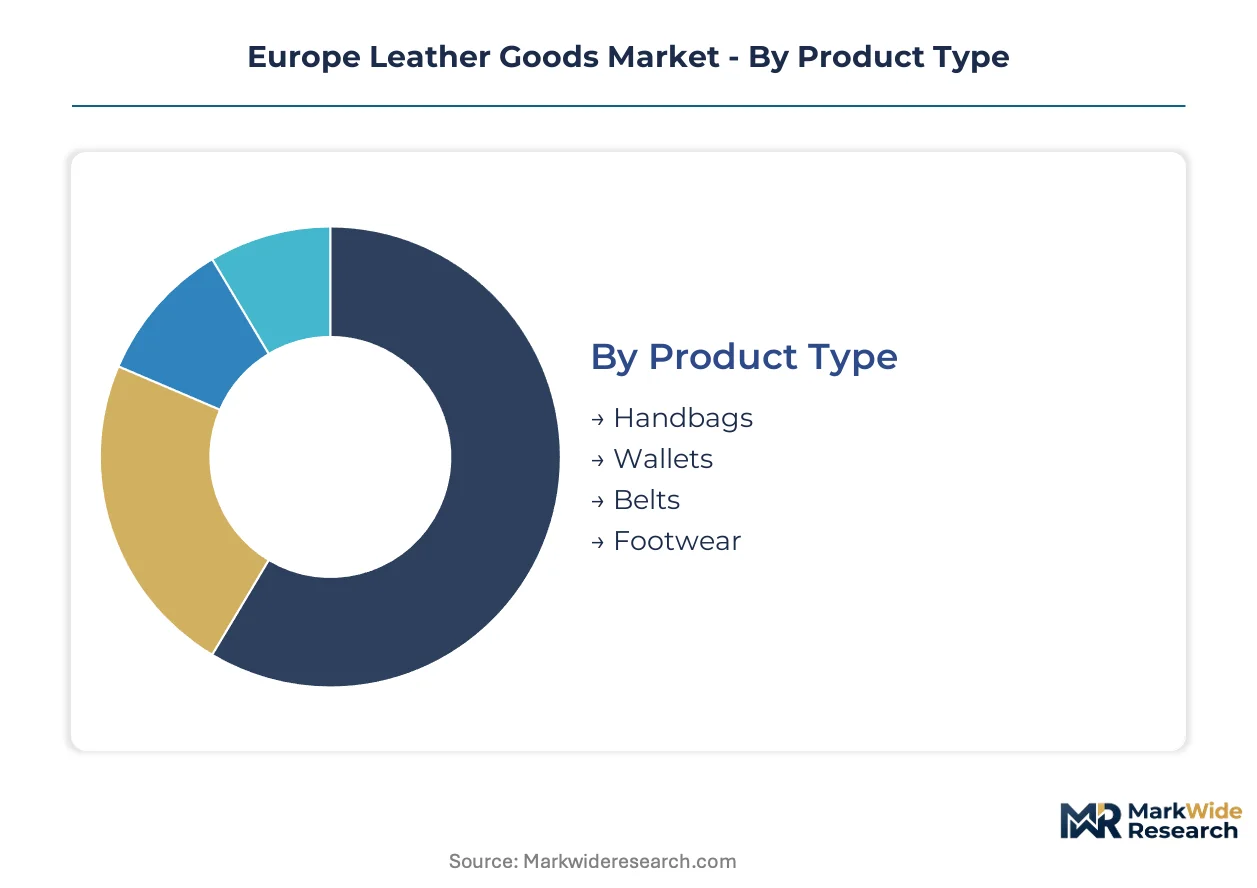
Leather goods segmentation in Europe maps purchasing behavior against craftsmanship intensity and regulatory exposure. Each dimension reveals distinct margin structures and compliance burdens that shape competitive positioning across Italian manufacturing clusters and German retail channels.
Product Type:
Functional carriage needs span daily utility through ceremonial display, with craftsmanship intensity determining price elasticity and brand loyalty.
- Handbags:Structured and soft-body designs in calf and exotic hides dominate conspicuous consumption occasions. Italian houses in Florence and Milan anchor artisan production for high-net-worth women, while mechanized Portuguese suppliers serve volume accessories.
- Wallets:Compact bi-fold and cardholder formats in vegetable-tanned leather command durability premiums. German and Dutch corporate gifting programs drive certified sourcing requirements.
- Belts:Reversible and single-layer constructions serve formal and casual dress codes with lower per-unit margin than bags.
- Footwear:Goodyear-welted and Blake-stitched leather shoes concentrate in Spanish and Italian manufacturing zones.
The dominant share belongs to Handbags, while Footwear is closing the gap fastest.
End User:
Customer archetypes differ sharply in purchase frequency, price tolerance, and sensitivity to provenance documentation.
- Women:Primary demand drivers for luxury handbags and small leather goods across French and Italian markets. Repeat purchase cycles align with seasonal collection drops.
- Men:Briefcases, wallets, and belts purchased on replacement cycles with lower frequency but higher per-transaction values in British and German markets.
- Children:School accessories and novelty items with price compression and synthetic leather substitution.
- Businesses:Corporate gifting and promotional leather goods with bulk pricing and customization requirements.
Women capture the largest value pool, with Men expanding most quickly in premium small leather goods.
Distribution Channel:
Channel selection determines authentication trust, margin retention, and customer data capture depth.
- Online Retail:Brand-owned flagships and multi-brand platforms accelerate fastest among German and Dutch consumers. First-party data enables personalized re-engagement.
- Specialty Stores:Curated assortments with trained sales staff and repair services retain margin superiority in Paris and London.
- Department Stores:Concession models with shared foot traffic but reduced brand control over presentation.
- Outlets:Off-price channels for past-season inventory with brand dilution risks.
Specialty Stores hold the dominant position, though Online Retail is gaining share fastest.
Material Type:
Substrate choice governs regulatory compliance burden, pricing tier placement, and end-use durability expectations.
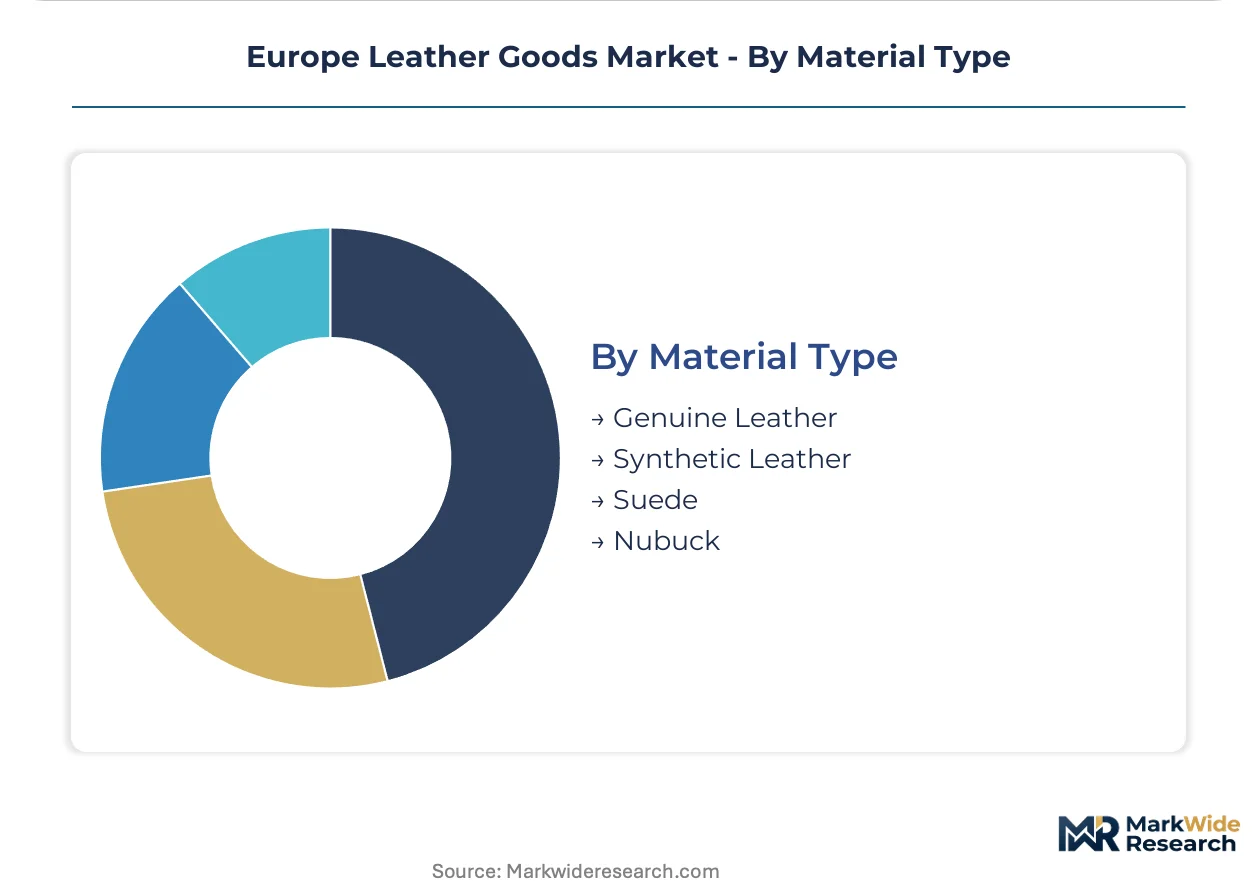
- Genuine Leather:Full-grain and top-grain hides from bovine and ovine sources command premium positioning. REACH chromium VI limits and EU Green Deal carbon border adjustments concentrate sourcing with Italian and Spanish certified tanneries.
- Synthetic Leather:Polyurethane and polyvinyl chloride alternatives capture vegan-positioned demand from younger French and British consumers.
- Suede:Split-hide constructions with napped surfaces requiring specialized cleaning protocols and moisture protection.
- Nubuck:Sanded grain surfaces with velvety handfeel and higher stain sensitivity than full-grain alternatives.
Genuine Leather maintains the dominant share, while Synthetic Leather is climbing the fastest on sustainability-positioned marketing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe's leather goods trade maintains a structural export surplus driven by Italian and French luxury houses, while import dependency concentrates in raw hide sourcing from Germany, Ireland, and France. Intra-European supply chains dominate finished goods circulation, with REACH compliance and EU Green Deal carbon border adjustments now differentiating competitive positioning across manufacturing clusters.
Italy
Florence and Milan anchor artisan production for high-net-worth women purchasing structured handbags in calf and exotic hides. REACH Annex XVII restrictions on chromium VI residues compel Tuscan tanneries toward vegetable-tanning revival and closed-loop water systems. The Scandicci leatherworking district reports enrollment declines at specialized schools, threatening generational knowledge transfer for hand-stitching techniques.
France
Parisian luxury houses command premium positioning through extreme scarcity economics and in-house artisan training spanning generations. ECHA substance evaluation roadmaps threaten additional restrictions on chromium tanning salts, accelerating reformulation investments. The Île-de-France region concentrates corporate headquarters and flagship retail, while blockchain traceability protocols satisfy emerging consumer disclosure expectations.
Spain
Andalusian tanneries in Ubrique and Alicante offer untapped artisan capacity for mid-luxury brands seeking Italian alternative supply. CE marking obligations under the EU's general product safety framework govern chemical exposure limits for skin-contact articles. The Valencia and Catalonia manufacturing zones adopt laser-cutting automation and robotic edge-finishing to maintain throughput despite rising labor costs.
Germany
Corporate gifting programs in Munich and Hamburg drive certified sourcing requirements for vegetable-tanned wallets and compact leather goods. CSRD disclosure mandates create advisory service demand for leather goods firms needing Scope 3 emissions accounting. The Baden-Württemberg industrial belt concentrates precision tooling suppliers serving automated cutting and finishing equipment.
United Kingdom
London specialty stores demand audited traceability documentation as table stakes for shelf placement, concentrating volume with vertically integrated houses. The EU Green Deal's carbon border adjustments penalize imported leather with high embedded emissions, reshaping procurement patterns. British men purchase briefcases, wallets, and belts on replacement cycles with higher per-transaction values than European averages.
Europe Leather Goods Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated luxury houses with captive tannery partnerships and closed-loop manufacturing capabilities. Three strategic archetypes dominate: heritage maisons with multi-generational artisan networks, conglomerate-owned portfolio brands leveraging shared raw material procurement, and mid-luxury specialists exploiting Spanish manufacturing alternatives. Competitive moves concentrate on regenerative agriculture investments for leather sourcing and direct-to-consumer digital flagships bypassing wholesale margin stacking.
Within the heritage maison tier, Hermès International S.A. and Chanel SA exemplify extreme scarcity economics and in-house craft preservation. Among conglomerate-structured players, LVMH Moët Hennessy Louis Vuitton SE and Kering S.A. occupy positions defined by portfolio diversification across price tiers and shared sustainability infrastructure. These named entities anchor archetype discussions without exhaustively mapping competitive dynamics.
| Leading Market Players |
|---|
| Chanel SA |
| Prada S.p.A. |
| LVMH Moët Hennessy Louis Vuitton SE |
| Samsonite IP Holdings S.A.R.L. |
| Burberry Group |
| Kering S.A. |
| Capri Holdings Limited |
| Ermenegildo Zegna Group |
| Hermès International S.A. |
| Others |
Supply & Pricing Matrix
Overcapacity in Portuguese mechanized tanneries is compressing spot-market hide prices while simultaneously pressuring artisan producers in Tuscany to defend premium positioning through certified vegetable-tanning credentials.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing stratification across premium, standard, and economy levels. Certification grade under Leather Working Group protocols and volume scale drive price differentiation, with bulk corporate gifting programs extracting steeper discounts than specialty retail procurement. Cost compression in standard-grade finished leather is intensifying because ECHA's tightening chromium VI limits force reformulation investments. German corporate buyers exhibit highest price sensitivity, while Parisian luxury houses demonstrate inelastic demand for exotic hide supply.
Supply Chain Analysis
Extended payment terms from Italian luxury houses now stretch 90-120 days, forcing tanneries toward supply-chain finance facilities anchored by raw material aggregators. Geographic supply concentrates in Italy, Spain, and France, with bovine hide sourcing drawing from slaughterhouse consolidation across Germany, Ireland, and France. Single-source vulnerability pervades exotic hide procurement from regulated wildlife trade channels. Distribution runs through vertically integrated flagship networks and wholesale concession models in department stores.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blockchain-enabled digital product passports are transforming European leather goods into a platform-economics arena where interoperability between traceability systems determines supplier inclusion.
For Market Incumbents: Entrench generational craft preservation through captive artisan training academies in Scandicci and Santa Croce sull'Arno. Secure backward integration into regenerative agriculture partnerships before EU Green Deal soil health mandates consolidate certified supply pools. Mycelium leather substitution from Bolt Threads and Modern Meadow threatens entry-level genuine leather positioning. For New Entrants and Emerging Players: Andalusian tanneries in Ubrique and Alicante represent the most penetrable entry point for mid-luxury brands seeking Italian alternative capacity with comparable artisan credentials. Direct-to-consumer digital flagships bypass wholesale margin stacking while capturing first-party data on German and Dutch purchasing patterns. Leather Working Group certification investment unlocks shelf placement in London and Paris specialty stores. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated heritage maisons with multi-generational artisan networks and captive retail footprints. Long-term viability across the analysis window favors acquisition targets with closed-loop water systems and vegetable-tanning capabilities that preempt REACH displacement. Monitor ECHA substance evaluation roadmap announcements for regulatory inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Regenerative Agriculture Partnership | Secures certified leather supply pools commanding premium positioning under EU Green Deal soil mandates. |
| Digital Product Passport Deployment | Enables batch-level hide provenance verification satisfying French consumer disclosure expectations. |
| Direct-to-Consumer Channel Launch | Bypasses wholesale margin stacking while capturing first-party data on German purchasing patterns. |
| Artisan Training Academy Investment | Addresses master craftsperson succession gaps threatening generational knowledge transfer in Tuscany. |
| Closed-Loop Water System Upgrade | Preempts REACH compliance displacement while reducing operational exposure to ECHA enforcement. |
Research Methodology
A standing panel of tannery operations directors, luxury house supply chain executives, specialty store buyers, and ECHA regulatory affairs specialists provided ongoing calibration across primary fieldwork. Secondary validation drew from customs trade databases, Leather Working Group audit disclosures, EU Green Deal implementation documents, and corporate sustainability filings. Bottom-up volume modeling triangulated against top-down value estimates from import-export flow analysis.
Scenario-bracketing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product type, material grade, distribution channel, and end-user archetype. CAGRs derived from elasticity-adjusted demand curves incorporating REACH compliance cost pass-through and carbon border adjustment exposure. Forecast inputs included artisan capacity utilization rates in Tuscan manufacturing clusters and mycelium leather substitution velocity in vegan-positioned segments.
Practitioners should monitor ECHA substance evaluation announcements, EU Green Deal carbon border implementation timelines, and artisan school enrollment trajectories for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Goods
United Kingdom Major Home Appliances Market
Consumer Goods
Brush Cleaner Market
Consumer Goods
UAE Consumer Electronics Market
Consumer Goods
Acrylic Marker Pen Market
Consumer Goods
Commercial Countertop Ranges Market
Consumer Goods
Household Refrigerators and Freezers Market
Consumer Goods
China Electric Face Cleanser Market
Consumer Goods
Popcorn Makers Market
Consumer Goods
Middle East and Africa Mobile Phone Accessories Market
Consumer Goods
Hair Serums Ingredient Market
Consumer Goods
Cat Food Toppers Market
Consumer Goods
Shaving Market
Consumer Goods
Baby Training Diaper Market
Consumer Goods
Integrated Smart Toilet Market
Consumer Goods
Earphones Market
Consumer Goods
Seamless Underwear for Men Market