
 Europe Charter Jet Services Market | 2026-2036
Europe Charter Jet Services Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Charter Jet Services Market Foresight
The Europe charter jet services sector is pivoting between ultra-premium managed-fleet offerings and price-sensitive on-demand brokerage. VistaJet Group Holding Limited anchors its position through a globally consistent heavy-jet fleet with guaranteed availability programs. NetJets Europe leverages fractional ownership structures to sustain recurring revenue from corporate accounts. PrivateFly Limited competes through digital-first booking platforms that reduce empty-leg positioning costs for price-aware travelers.
Europe charter jet services encompass the commercial provision of aircraft and crew for non-scheduled flights, typically operated under Part-NCC or Part-CAT rules with minimum equipment lists and crew duty-time limits calibrated to mission profiles. The primary purpose is time-critical passenger transport for entities where schedule control, privacy, or airport access outweighs scheduled airline economics. On-demand charter captures the largest transaction volume, though membership programs concentrate the highest per-client lifetime value through predictable utilization commitments. Heavy jets dominate transcontinental routes, while light jets and turboprops serve the intra-European short-haul segment where runway constraints at secondary airports create operational differentiation.
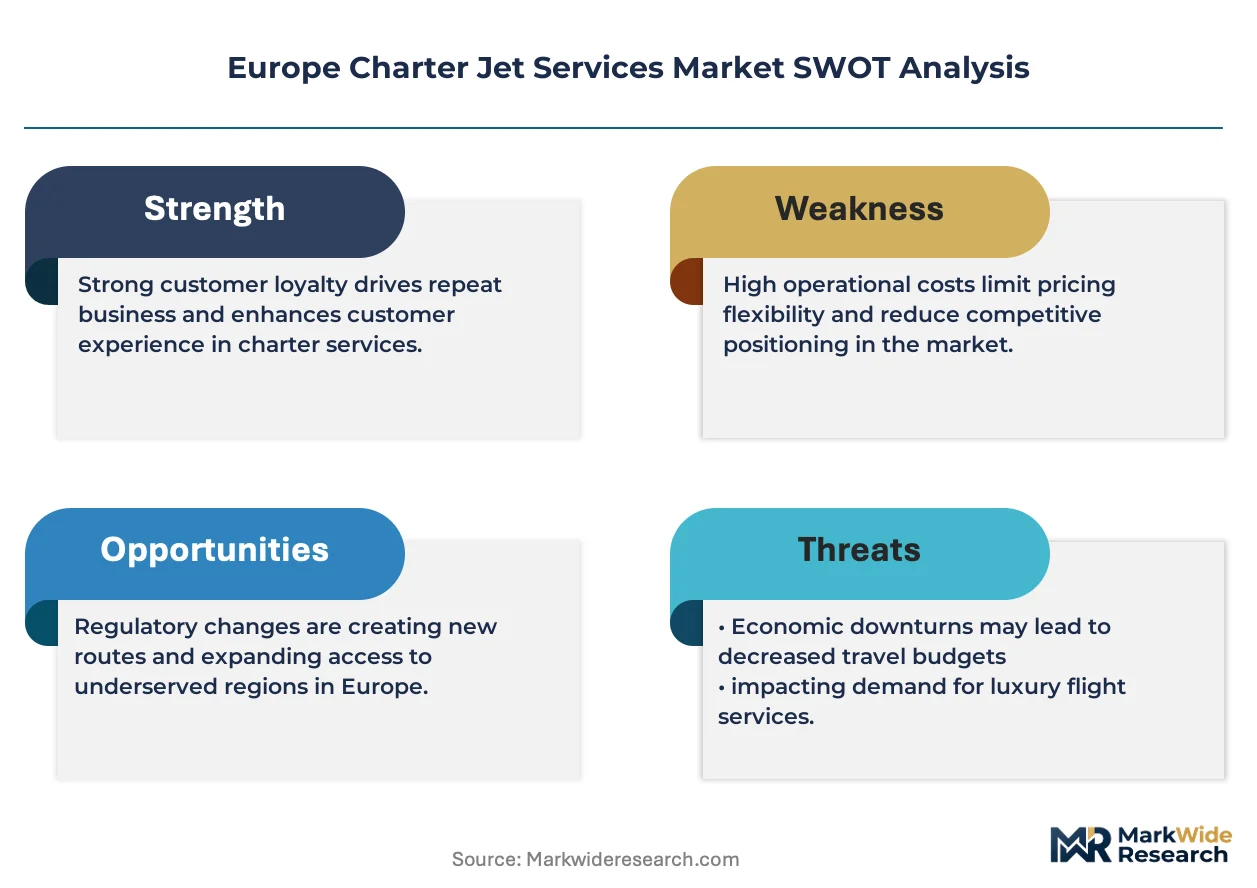
EASA mandates on emissions reporting and the EU Green Deal's sustainable aviation fuel targets are tightening operational compliance costs and accelerating fleet renewal timelines. REACH-aligned chemical handling standards for maintenance, repair, and overhaul activities further shape ground-handling economics across member states. Operators and investors must monitor SAF certificate pricing and bilateral air service negotiations, as these will determine route-level profitability and base-country selection for new charter certificates.
Market Dynamics
EASA's sustainable aviation fuel mandates and the EU Green Deal's emission targets are compressing fleet renewal cycles across European charter operators, forcing capital reallocation toward SAF-compatible aircraft and ground infrastructure upgrades.
Growth Catalysts
- EU Green Deal SAF targets:The EU Green Deal mandates progressive sustainable aviation fuel blending requirements, compelling operators to modernize fleets and attracting ESG-focused corporate flight departments seeking verified low-carbon travel options.
- Ultra-high-net-worth individual concentration:France, the United Kingdom, and Germany host dense clusters of wealth managers and family offices generating recurring demand for guaranteed-availability heavy-jet programs.
- Digital booking platforms:Real-time empty-leg matching algorithms reduce deadhead positioning costs, expanding price-accessible on-demand charter to mid-tier corporate travelers previously excluded from private aviation.
Market Restraints
- SAF supply scarcity:European sustainable aviation fuel production capacity remains concentrated at Rotterdam and Haldor Topsoe facilities, creating input cost volatility and certificate pricing uncertainty for operators outside direct supply agreements.
- Airport slot constraints:Secondary airports in the French Alps and Mediterranean coast face physical capacity limits during peak seasons, restricting fleet deployment flexibility for peak-demand routing.
- Pilot certification bottlenecks:EASA's Part-FCL training hour requirements and examiner availability shortages extend first-officer qualification timelines, constraining crew supply growth relative to aircraft deliveries.
Strategic Opportunities
- Central and Eastern Europe:Poland, Czechia, and Romania exhibit underdeveloped FBO infrastructure relative to Western European density, presenting first-mover advantages for base-country certificate establishment.
- CSRD-aligned carbon reporting:The Corporate Sustainability Reporting Directive creates procurement tailwinds for operators offering granular flight-level emissions data to corporate sustainability officers.
- Hybrid-electric propulsion convergence:Battery-electric and hydrogen fuel cell technologies are maturing for sub-500nm missions, positioning turboprop operators to capture intra-European short-haul segments with zero-emission claims.
Industry Challenges
- Maintenance technician specialization:Next-generation avionics and SAF-compatible engine architectures require skill sets scarce in legacy MRO workforces, extending AOG resolution times.
- Part-NCC to Part-CAT migration complexity:Operators expanding from non-commercial to commercial operations face air operator certificate conversion timelines and operational manual rewrites that delay revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Charter Jet Services Market |
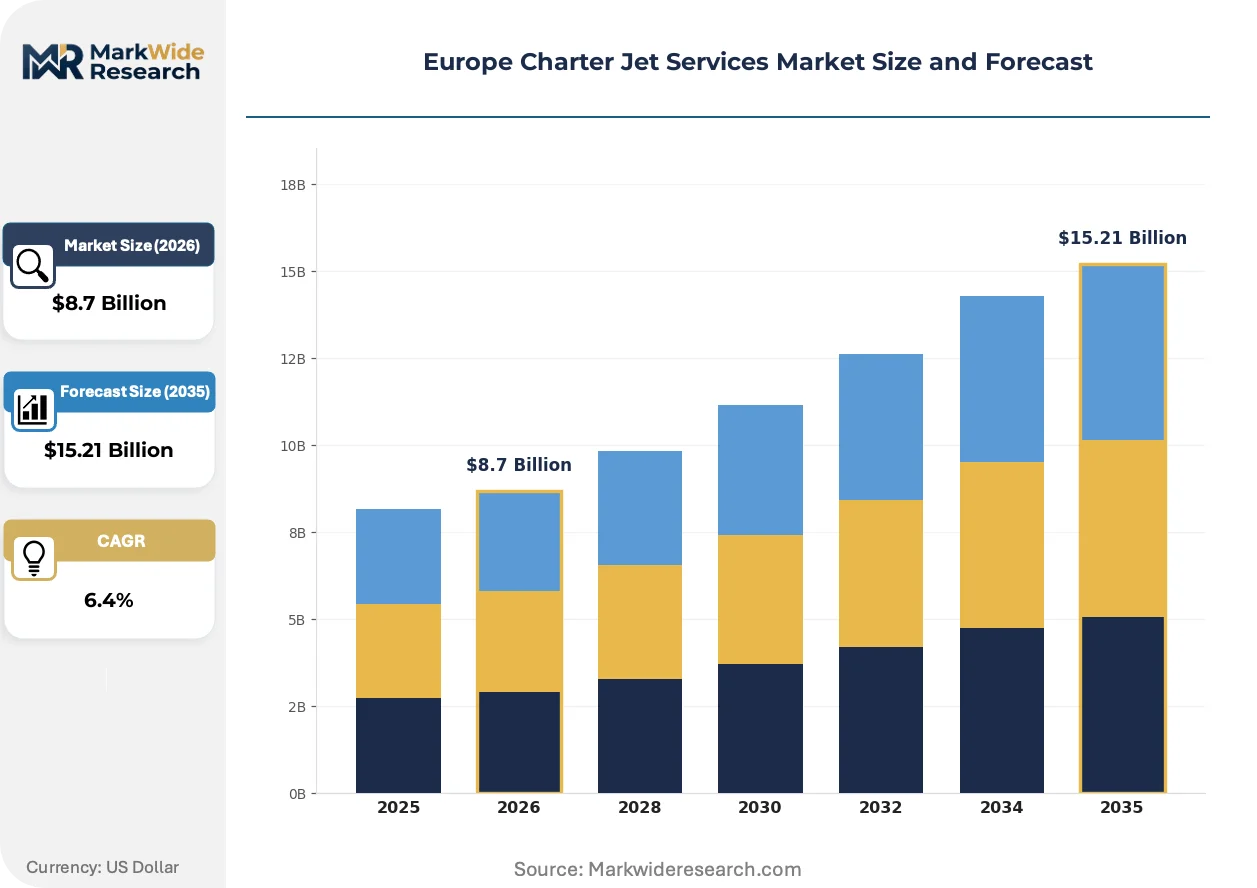
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: On-Demand, Fixed-Rate, Membership, Empty Leg Aircraft Type: Light Jet, Mid-Size Jet, Heavy Jet, Turboprop Booking Channel: Online, Travel Agent, Phone, Corporate Customer Type: Business, Leisure, Government, Sports |
| Companies Covered | Fly Victor Limited, Air Hamburg Luftverkehrs GmbH, VistaJet Group Holding Limited, Aero-Dienst, Hahn Air, Jet Aviation AG, PrivateFly Limited, NetJets Europe, Luxaviation Management Company, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Charter Jet Services Market Shifts & Advancements
European charter aviation is converging around three vectors: digital platform intermediation, regulatory-driven fleet transformation, and corporate procurement standardization demanding transparent sustainability credentials.
Artificial intelligence-powered demand forecasting is unifying aircraft positioning with customer booking patterns. VistaJet and NetJets Europe deploy machine learning models to pre-position heavy jets at London City, Le Bourget, and Geneva Cointrin before peak demand windows. This compression of empty-leg ratios is reducing per-flight-hour costs while maintaining guaranteed availability commitments for membership clients.
REACH-aligned chemical handling standards for MRO activities are tightening ground-handling economics. The European Chemicals Agency mandates for chrome-free pretreatments and solvent recovery systems increase facility capital requirements. Operators with in-house maintenance capabilities at Luton, Milan Malpensa, and Munich are absorbing compliance costs more efficiently than third-party-dependent competitors.
Corporate flight departments are consolidating supplier relationships around sustainability-verified operators. Procurement teams at headquartered multinationals in Frankfurt, Amsterdam, and Dublin now require SAF certificate documentation and Scope 3 emissions reporting as standard RFP criteria. This behavioral shift favors fleet-scale operators with integrated carbon accounting over fragmented brokerage models lacking audit trail depth.
Europe Charter Jet Services Market Segmentation
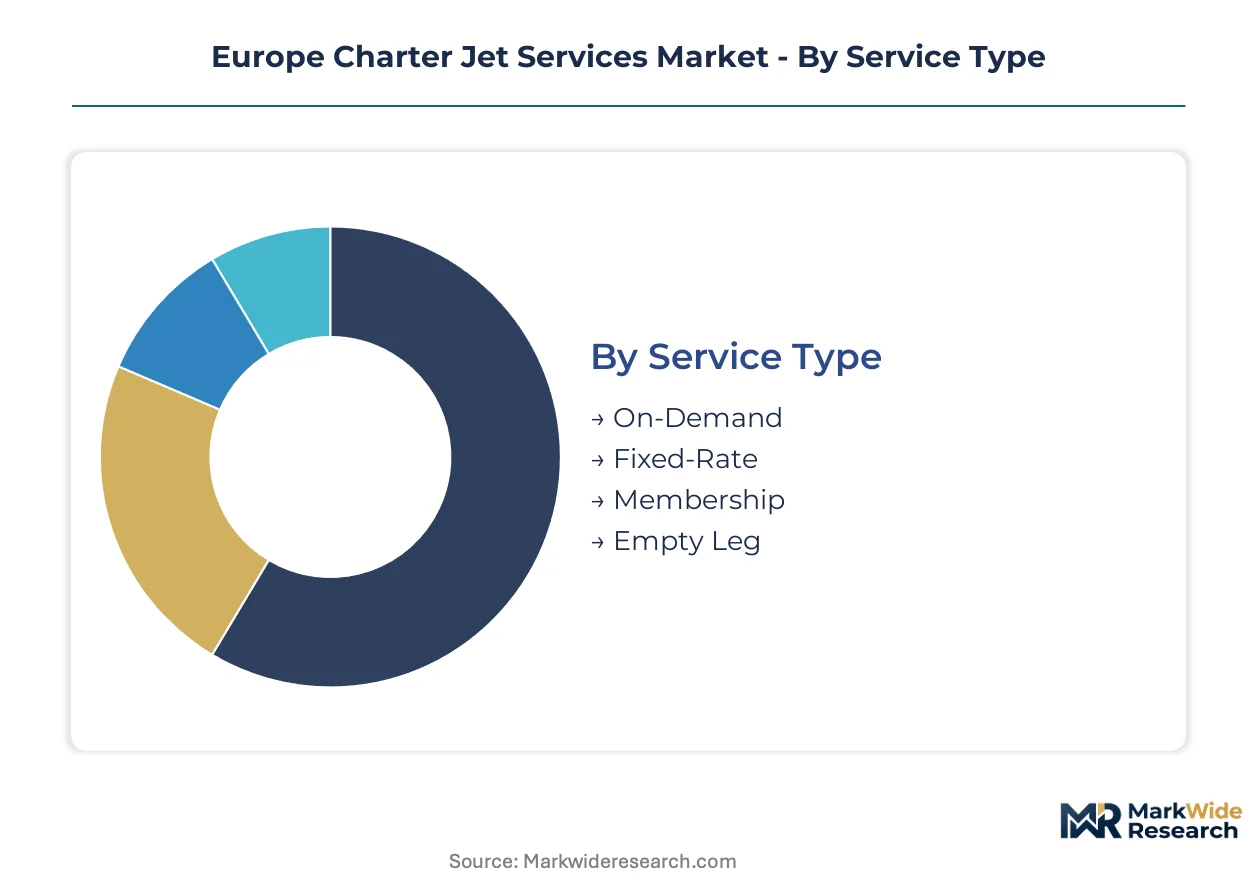
European charter operators structure service delivery around four distinct axes: mission flexibility, aircraft capability, procurement pathway, and traveler purpose. Each segmentation layer reveals divergent margin profiles and capital intensity requirements that shape operator portfolio decisions.
Service Type:
Standardized rate cards compete with bespoke mission pricing across this spectrum, with guaranteed availability programs commanding premium positioning against transactional spot markets.
- On-Demand:Ad-hoc charter transactions arranged per flight with dynamic pricing tied to aircraft positioning and peak-season slot scarcity. Demand concentrates among French and German corporate flight departments seeking airport-pair flexibility without recurring commitments. Price transparency platforms compress margins for operators lacking proprietary fleet scale.
- Membership:Prepaid hourly blocks or annual subscription models securing guaranteed aircraft access and fixed hourly rates. Ultra-high-net-worth individuals in the United Kingdom and Switzerland generate recurring revenue through VistaJet and NetJets Europe programs. ESG reporting requirements from corporate subscribers now mandate SAF certificate inclusion in membership tiers.
- Fixed-Rate:Published city-pair pricing for frequently traveled routes, typically London-Paris or Geneva-Nice corridors. Operators pre-position aircraft to honor rate commitments during demand surges.
- Empty Leg:Repositioning flights offered at discount to offset deadhead costs, captured through digital matching algorithms. Price-sensitive leisure travelers in Mediterranean markets drive transaction volume.
Most installed capacity flows through Membership programs. Expansion is steepest in On-Demand as digital platforms democratize access.
Aircraft Type:
Capital deployment intensity and crew specialization requirements separate short-haul turboprop operations from transcontinental heavy-jet fleets.
- Heavy Jet:Intercontinental-capable aircraft with 10-16 passenger capacity and 6,000+ nm range, configured for sleep-flat beds and full galleys. Transatlantic routes from London City and Le Bourget to Dubai and New York concentrate demand from family offices and private equity principals. EASA emissions mandates accelerate fleet renewal toward SAF-compatible engines.
- Light Jet:4-8 seat aircraft optimized for 1,500-2,000 nm missions with lower operating economics. Secondary airport access at Cannes Mandelieu and Sion drives adoption among Alpine leisure travelers and mid-market corporate users. Runway performance limitations exclude these aircraft from London City Airport's steep approach.
- Mid-Size Jet:Cross-continental range with stand-up cabins, serving the intra-European premium segment where heavy-jet economics prove excessive.
- Turboprop:Short-field performance for 500-800 nm missions, accessing runways at St. Moritz and Courchevel inaccessible to jets. Hybrid-electric propulsion prototypes target this segment for zero-emission claims.
Heavy Jet utilization generates the highest revenue per flight hour. Light Jet capacity is expanding most quickly as operators rebalance toward intra-European density.
Booking Channel:
Channel economics reflect customer acquisition cost structures and lifetime value differentiation between institutional procurement and individual transaction.
- Online:Platform-mediated bookings through PrivateFly and comparable digital intermediaries, reducing empty-leg friction through algorithmic matching. Corporate travel managers in Frankfurt and Amsterdam increasingly mandate online booking for policy compliance and emissions audit trails.
- Corporate:Direct contractual relationships between flight departments and operators, negotiated through RFP processes with sustainability scoring criteria. Multinational headquarters in Dublin and Luxembourg consolidate supplier panels around CSRD-aligned reporting capabilities.
- Travel Agent:High-touch concierge arrangements for ultra-high-net-worth leisure travelers, particularly Russian and Middle Eastern clientele accessing Mediterranean destinations.
- Phone:Legacy booking pathway retained for complex multi-leg missions and last-minute schedule changes.
Corporate channels concentrate the highest per-client lifetime value. Online penetration is climbing fastest as procurement digitization accelerates.
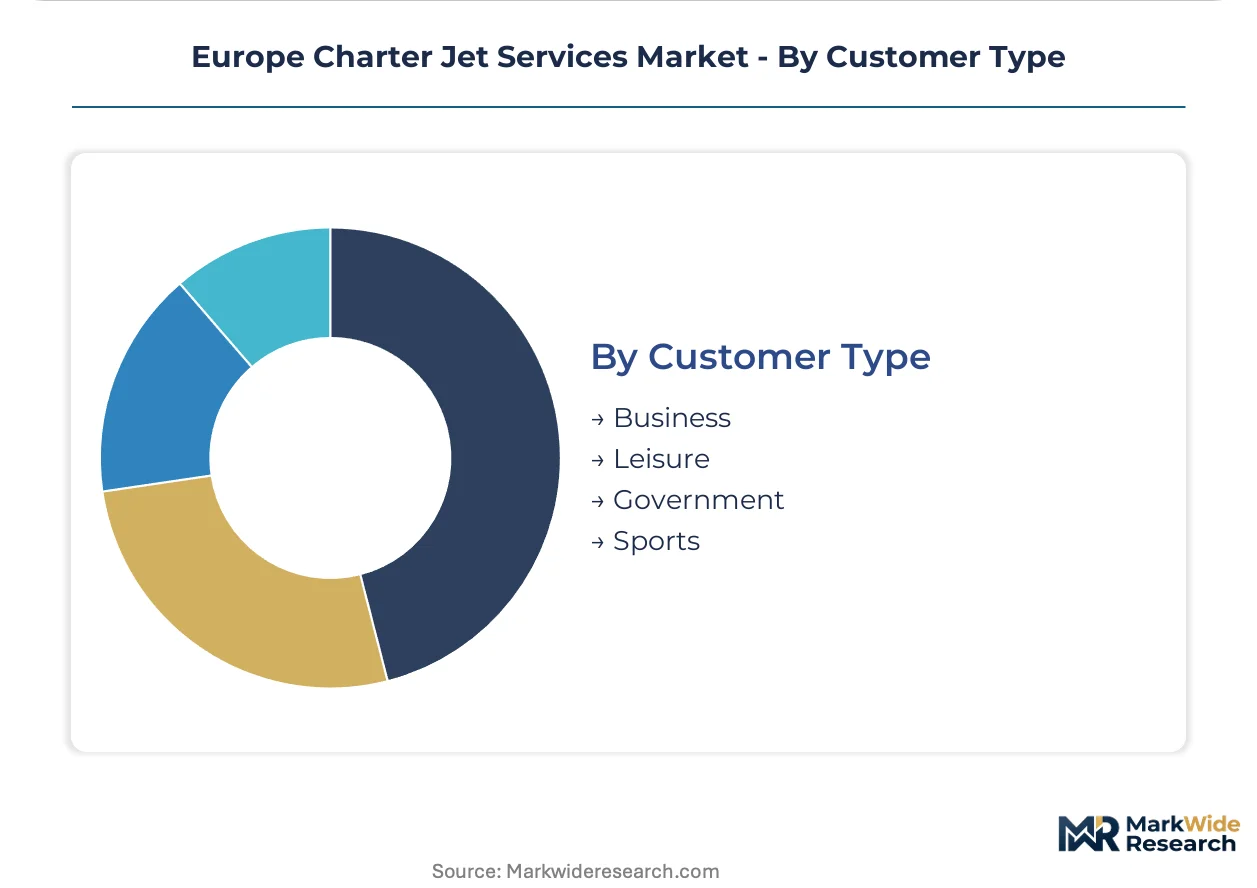
Customer Type:
Mission profiles and price sensitivity diverge sharply between time-critical business travel and discretionary leisure consumption.
- Business:Schedule-driven travel where opportunity cost of commercial airline delays exceeds charter premium. Financial services clusters in the City of London and Frankfurt's Bankenviertel sustain weekday peak demand with compressed booking windows.
- Leisure:Discretionary consumption concentrated in July-August and December-January windows, with French Riviera and Alpine ski destinations driving seasonal pricing power. Multi-generational family travel from the United Kingdom sustains heavy-jet utilization during holiday periods.
- Government:Diplomatic and head-of-state transport with security-cleared crews and specialized communications equipment.
- Sports:Team and athlete transport with equipment capacity requirements, particularly football clubs and Formula 1 operations.
Business travelers provide the foundation of year-round utilization. Leisure segment expansion is steepest as post-pandemic preferences shift toward private aviation for family travel.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France commands heavier jet utilization than Germany, yet both markets face tightening EASA emissions mandates that reshape fleet planning across Western Europe.
France
Family offices in Paris and the French Riviera sustain demand for guaranteed-availability heavy-jet programs. The EU Green Deal's SAF blending requirements pressure operators at Le Bourget to accelerate fleet renewal timelines. Alpine destinations like Courchevel and Megève concentrate seasonal turboprop activity where runway constraints exclude jet aircraft.
United Kingdom
Financial services clusters in the City of London and Canary Wharf generate compressed-booking business travel to Geneva and Frankfurt. CSRD-aligned carbon reporting mandates from the Corporate Sustainability Reporting Directive favor operators with integrated emissions audit trails. London City Airport's steep approach limitations restrict aircraft types, concentrating specialized fleet positioning.
Germany
Corporate flight departments in Frankfurt's Bankenviertel and Munich sustain recurring fractional ownership commitments. REACH-aligned chemical handling standards for MRO activities tighten ground-handling economics at Luton and Milan Malpensa. Bavaria's manufacturing headquarters generate mid-size jet demand for intra-European supplier network access.
Switzerland
Wealth management concentration in Geneva and Zürich drives membership program subscriptions with ESG verification requirements. Swissmedic-aligned operational standards exceed baseline EASA requirements for medical evacuation and diplomatic transport. The Sion and St. Moritz airports channel Alpine leisure demand through short-field-capable turboprops.
Italy
Milan Malpensa and Rome Ciampino anchor heavy-jet positioning for Middle Eastern and Russian leisure travelers accessing Mediterranean destinations. EASA Part-CAT certificate conversion timelines delay revenue recognition for operators expanding from non-commercial bases. The Amalfi Coast and Sardinia concentrate July-August peak pricing power for empty-leg matching platforms.
Europe Charter Jet Services Market Competitive Landscape
Top-tier vendors anchor globally consistent fleet operations, while regional specialists compete through airport-pair expertise and digital platform intermediation. The market structure splits between asset-heavy fractional ownership providers and asset-light brokerage models. Three archetypes dominate: managed-fleet operators with guaranteed availability programs, digital-first booking platforms with algorithmic empty-leg matching, and diversified aviation groups with integrated MRO capabilities. Competitive moves concentrate on SAF certificate procurement partnerships and CSRD-aligned carbon accounting integration.
Within the premium managed-fleet tier, VistaJet Group Holding Limited and NetJets Europe exemplify asset-heavy operators with recurring revenue structures. PrivateFly Limited occupies a position representing digital platform intermediation that reduces deadhead positioning costs through real-time matching algorithms. Air Hamburg Luftverkehrs GmbH anchors the specialized German market segment with Luftverkehrs GmbH corporate structure indicating regulated commercial air operator certification.
| Leading Market Players |
|---|
| Fly Victor Limited |
| Air Hamburg Luftverkehrs GmbH |
| VistaJet Group Holding Limited |
| Aero-Dienst |
| Hahn Air |
| Jet Aviation AG |
| PrivateFly Limited |
| NetJets Europe |
| Luxaviation Management Company |
| Others |
Supply & Pricing Matrix
Sustainable aviation fuel certificate costs cascade through operator rate cards, compressing margins on fixed-rate city-pair offerings while inflating premiums for ESG-verified membership tiers. Le Bourget and London City positioning expenses tether directly to Heathrow and Charles de Gaulle jet fuel differentials, forcing fleet managers to rebalance aircraft allocation between spot-market responsiveness and guaranteed-availability commitments.
Pricing Analysis
Capacity additions in Central and Eastern Europe are reshaping price floors for intra-European light-jet segments, eroding legacy operators' regional premiums. Three-tier pricing structure across premium, standard, and economy levels separates VistaJet's guaranteed-availability programs from PrivateFly's algorithmic empty-leg matching and transactional spot charters. Price differentiation stems from SAF certificate inclusion and crew duty-time flexibility. Cost compression in the on-demand tier intensifies because digital platforms democratize access. Leisure travelers accessing Mediterranean destinations exhibit highest price sensitivity; corporate flight departments in Frankfurt's Bankenviertel demonstrate lowest.
Supply Chain Analysis
Dual-sourcing requirements from corporate procurement teams now mandate SAF certificate verification from Rotterdam and Haldor Topsoe facilities alongside secondary Nordic suppliers. Aircraft manufacturing concentrates in France, the United States, and Brazil. Avionics suites and SAF-compatible engine architectures draw from German, British, and Israeli component specialists. Single-source vulnerability runs through concentrated MRO technician pools at Luton and Milan Malpensa. Distribution runs through FBO networks with direct operator relationships, bypassing traditional aviation fuel intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe charter jet services function as a regulatory compounder where EASA's progressive SAF blending mandates create procurement tailwinds for verified low-carbon operators. The EU Green Deal's emission targets lock in fleet renewal cycles that favor capital-rich incumbents with integrated carbon accounting.
For Market Incumbents: Acquire SAF offtake agreements and in-house MRO capabilities at certificate-heavy bases like Le Bourget and London City. Digital platform entrants threaten brokerage-dependent operators with algorithmic price transparency. Consolidation of Part-CAT certificates in Central and Eastern Europe defends positioning flexibility against slot-constrained Western airports.
For New Entrants and Emerging Players: Launch via digital-first booking platforms targeting price-aware mid-tier corporate travelers in Poland and Czechia. Empty-leg matching algorithms penetrate fastest where FBO density lags Western European saturation. White-space concentration in Romanian business aviation infrastructure offers first-mover certificate establishment. Partner with existing SAF suppliers for procurement credibility rather than building captive production.
For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented brokerage models lack audit trail depth for CSRD-aligned corporate procurement. Long-term viability favors fleet-scale operators with integrated sustainability verification over asset-light intermediaries. Acquisition target archetype: mid-size operators with Part-CAT certificates and established SAF supplier relationships. The signal to watch is corporate RFP standardization around granular flight-level emissions reporting.
| Strategic Initiative | Industry Significance |
|---|---|
| SAF Certificate Procurement Partnership | Secures supply agreements with Rotterdam and Haldor Topsoe facilities for ESG-verified operations. |
| Part-CAT Certificate Expansion | Enables commercial charter revenue recognition beyond non-commercial Part-NCC limitations. |
| Digital Platform Integration | Reduces empty-leg positioning costs through real-time algorithmic matching at Mediterranean destinations. |
| In-House MRO Capability Buildout | Absorbs REACH-aligned chemical handling compliance more efficiently than third-party-dependent competitors. |
| Hybrid-Electric Propulsion Investment | Positions turboprop operators for zero-emission claims on sub-500nm Alpine and intra-European routes. |
Research Methodology
Multiple input streams — operator fleet registries, EASA certificate databases, and corporate procurement survey responses — were reconciled through bottom-up and top-down triangulation. Primary interviews with charter operations directors, FBO facility managers, corporate flight department procurement leads, and SAF supply specialists were validated against secondary sources including EASA regulatory filings, EU Green Deal implementation documents, and REACH-aligned chemical handling standards. Customs data on aircraft imports and SEC filings from aviation lessors provided additional demand-side calibration.
Data-stream reconciliation across the projection horizon employed segmentation modeling across service type, aircraft category, booking channel, and customer purpose dimensions. CAGRs were derived from installed base evolution and utilization rate assumptions. Forecast inputs incorporated EASA SAF mandate phase-in schedules, pilot certification bottleneck timelines from Part-FCL requirements, and airport slot constraint severity at peak-season Mediterranean destinations.
Forecast precision tightens around the base case; tail outcomes carry wider variance under SAF supply disruption or accelerated hybrid-electric certification pathways. Forecasts reflect documented assumptions on corporate ESG procurement adoption rates and bilateral air service negotiation outcomes. Deviation in EU Green Deal enforcement intensity or REACH MRO compliance cost trajectories would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tourist Transport Services
Low-Cost Carrier (LCC) Market
Tourist Transport Services
Yacht Rental Market
Tourist Transport Services
Southeast Asia Charter Jet Services Market
Tourist Transport Services
Helicopter Tourism Market
Tourist Transport Services
UK Low Cost Airlines Market
Tourist Transport Services
Italy Car Rental Market
Tourist Transport Services
India International Express Service Market
Tourist Transport Services
Boat Rental Market
Tourist Transport Services
Airport Ground Transportation Market
Tourist Transport Services
Pre-Book Airport Transfer Market
Tourist Transport Services
Travel Transportation Market