
 Helicopter Tourism Market | 2026-2036
Helicopter Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
Helicopter Tourism Market Analysis
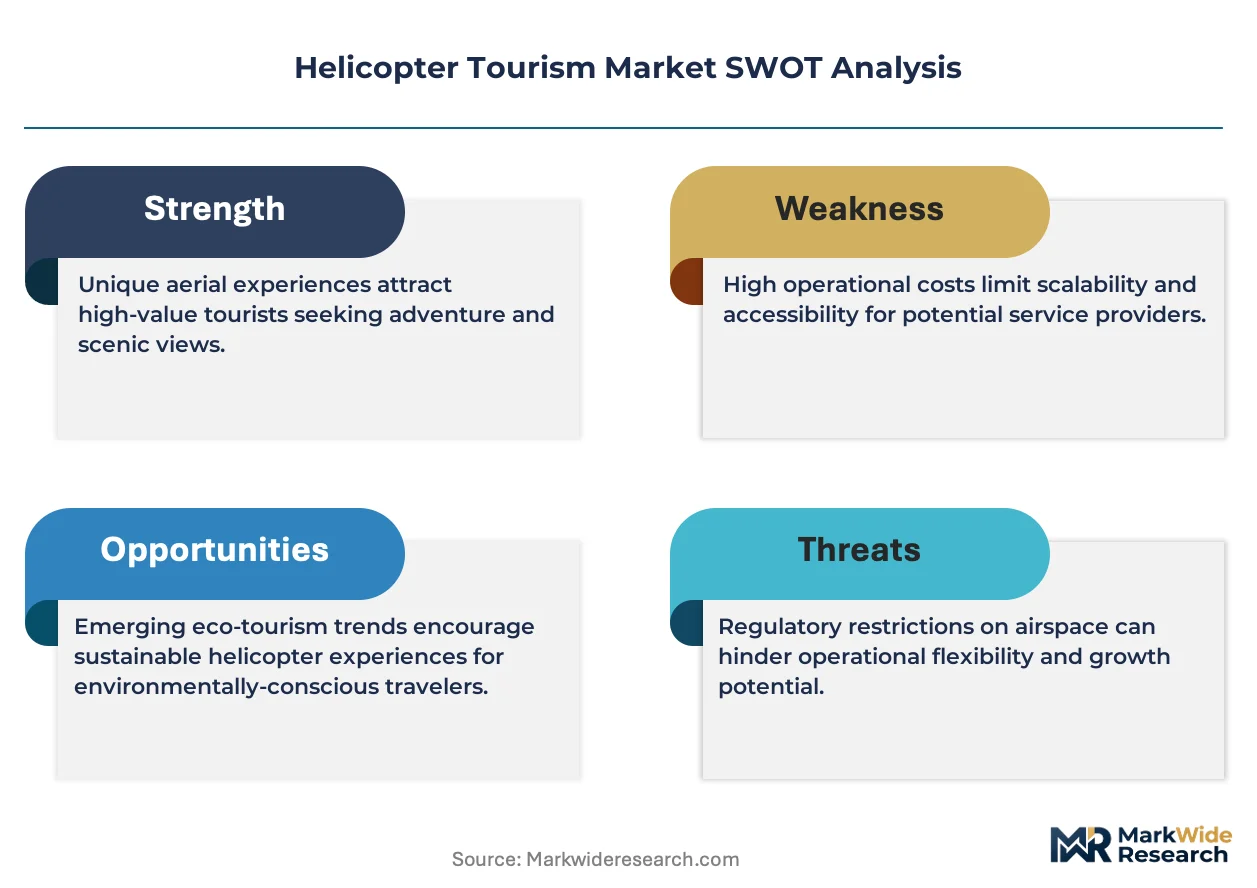
Modular tour packaging is shifting buyer choice across the helicopter tourism sector, as operators unbundle base flights from premium add-ons like private landings and extended routes. Maverick Aviation Group leverages its Las Vegas hub to anchor multi-destination bundles across the American Southwest. Blue Hawaiian Helicopters sustains its position through specialized volcano and waterfall circuits on the Big Island and Maui. Papillon Grand Canyon Helicopters dominates aerial access to the Grand Canyon corridor with extensive fleet scale and exclusive landing sites.
Helicopter tourism encompasses commercial passenger flights conducted in rotary-wing aircraft for non-scheduled recreational, scenic, or experiential purposes, typically operating at altitudes below 10,000 feet with turbine or piston-engine helicopters seating four to six passengers. The activity serves destination marketing, luxury hospitality, and adventure travel industries by providing access to terrain unreachable by surface transport. Sightseeing tours generate the largest revenue pool among service types, while charter services for high-net-worth individuals capture the widest margin spread. Natural landscapes attract the densest booking concentration among destination types, whereas urban destinations in Dubai and New York show the fastest route expansion.
FAA Part 135 regulations govern commercial charter operations in the United States, while EASA safety management requirements shape European fleet standards and pilot certification. The EU Green Deal's aviation emissions framework pressures operators toward sustainable aviation fuel adoption and noise abatement protocols. India's DGCA mandates increasingly align with ICAO standards for foreign-registered tourist helicopters. Stakeholders must monitor emerging urban air mobility zoning conflicts and evolving national park overflight restrictions that could redraw permissible routes.
Market Dynamics
Modular tour packaging is fragmenting traditional bundled offerings across the helicopter tourism sector, forcing operators to unbundle base flights from premium add-ons and rebuild revenue through à-la-carte pricing architectures.
Growth Catalysts
- EU Green Deal aviation emissions framework:The EU Green Deal's aviation emissions framework pressures operators toward sustainable aviation fuel adoption and noise abatement protocols, accelerating fleet modernization investments.
- Luxury hospitality cross-selling:High-end resorts in Hawaii and the Swiss Alps now embed helicopter transfers into villa packages, expanding addressable passenger pools beyond standalone adventure seekers.
- Urban air mobility infrastructure development:Dubai and New York are constructing dedicated heliport networks that reduce turnaround times and enable higher-frequency scheduling on premium routes.
Market Restraints
- Aviation turbine fuel price volatility:Jet fuel represents 25-35% of direct operating costs for turbine helicopter fleets, creating margin compression during supply disruptions.
- Pilot certification pipeline constraints:FAA Part 135 commercial pilot requirements and EASA safety management mandates extend training timelines, restricting qualified crew availability.
- National park overflight restrictions:Permissible routes over the Grand Canyon and Swiss Alps face tightening environmental noise limits that constrain capacity expansion.
Strategic Opportunities
- Indian DGCA regulatory alignment:India's DGCA mandates are converging with ICAO standards, opening foreign-registered tourist helicopter operations in underpenetrated Himalayan and coastal circuits.
- Electrification and hybrid propulsion:Battery-electric and hybrid-electric powertrains are converging with autonomous flight systems to enable lower-cost, lower-noise urban sightseeing products.
- Direct-to-consumer booking platforms:Operator-owned reservation systems are displacing traditional travel agency intermediaries, capturing 15-20 percentage points of margin previously lost to commissions.
Industry Challenges
- Airframe maintenance technician scarcity:Specialized turbine helicopter mechanics command premium wages, extending aircraft-on-ground periods during peak seasonal demand.
- FAA Part 135 certification timeline compression:New market entrants face 12-18 month approval cycles for commercial charter authority, delaying revenue generation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Helicopter Tourism Market |
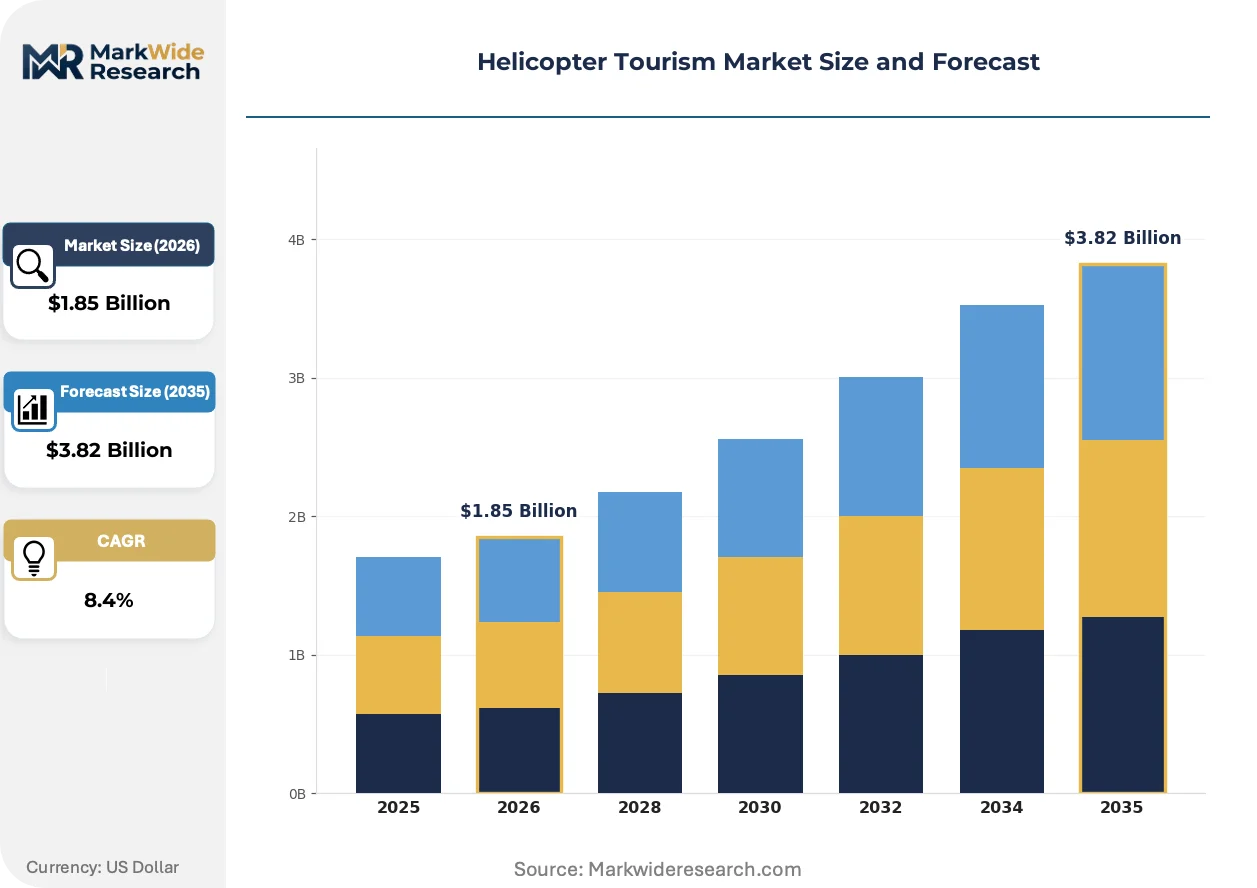
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.82 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Sightseeing Tours, Charter Services, Aerial Photography, Emergency Services End User: Adventure Seekers, Travel Agencies, Corporate Clients, Event Planners Flight Duration: Short Haul, Medium Haul, Long Haul, Scenic Flights Destination Type: Urban Destinations, Natural Landscapes, Heritage Sites, Custom Routes |
| Companies Covered | Liberty Helicopters, Air Maui Helicopters, Maverick Aviation Group, Accretion Aviation, Safari Helicopters, Papillon Grand Canyon Helicopters, Niagara Helicopters Limited, Alpine Helicopters, Blue Hawaiian Helicopters, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Helicopter Tourism Market Emerging Trajectories
Digital booking platforms and sustainable aviation technologies are converging to reshape how operators acquire passengers and manage environmental compliance. These shifts are compressing traditional intermediation layers while elevating operational transparency requirements.
Hybrid-electric propulsion systems are integrating into new-generation sightseeing helicopters, reducing fuel burn and noise signatures on sensitive routes. Operators serving the Grand Canyon and Swiss Alps are trialing these powertrains to preempt tightening environmental restrictions. The technology is integrating route access preservation with community acceptance, enabling expansion into noise-constrained corridors previously closed to conventional turbine aircraft.
EASA safety management requirements are mandating enhanced flight data monitoring and predictive maintenance protocols across European-registered fleets. Operators must now deploy real-time health monitoring on critical components, increasing upfront avionics investment but reducing unscheduled downtime. Charter services for high-net-worth individuals face the steepest compliance costs, driving consolidation among smaller independent operators unable to absorb certification burdens.
Experience unbundling is fragmenting traditional tour packages into componentized purchases across direct channels. Travelers now construct itineraries through operator websites, selecting base flights, private landings, and ground extensions separately. This pattern concentrates in the United States and UAE, where luxury consumers demonstrate willingness to pay premium markups for customization control rather than accepting standardized bundles.
Helicopter Tourism Market Segmentation
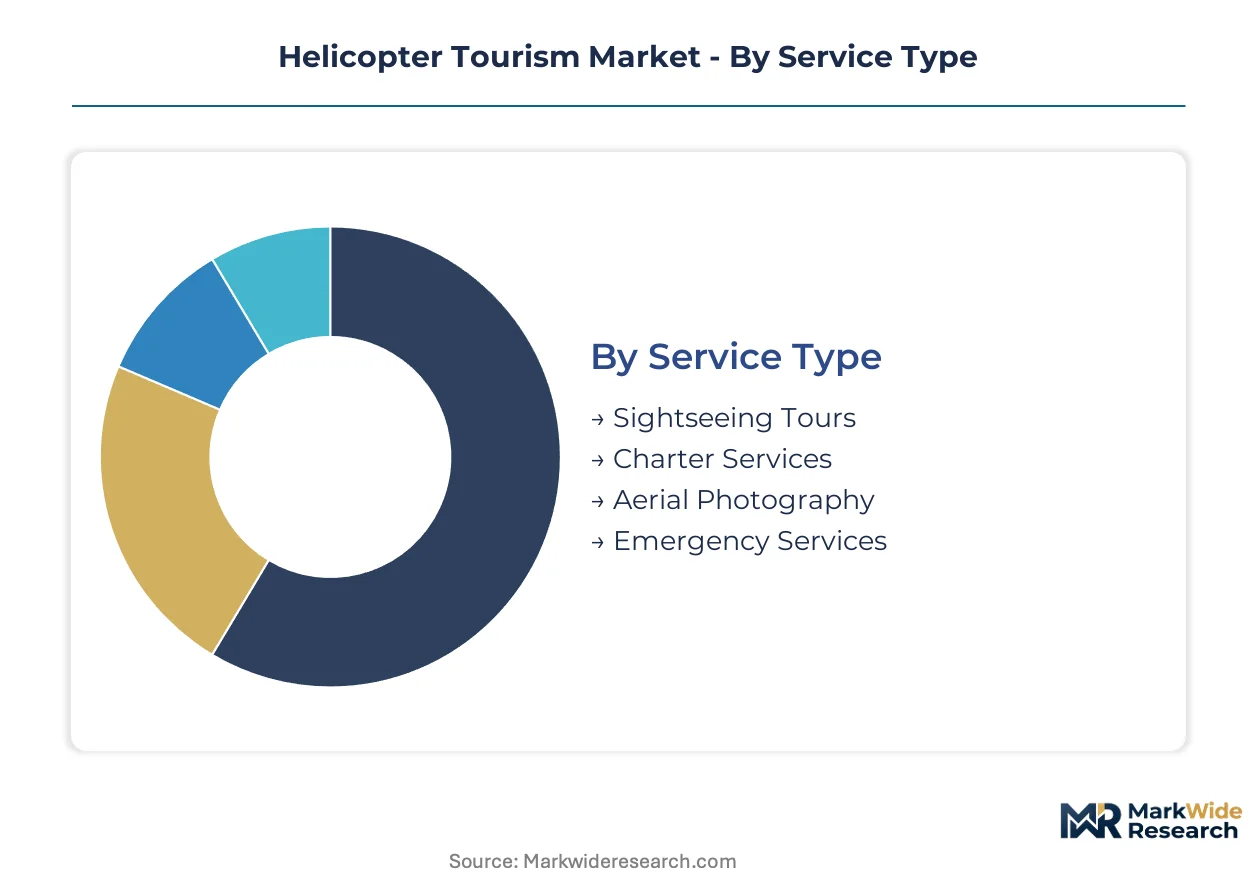
Helicopter tourism operators calibrate fleet deployment and pricing architectures against distinct demand profiles across service tiers, customer categories, and route characteristics. Segmentation discipline separates high-frequency scenic circuits from low-volume charter operations with divergent margin structures and regulatory burdens.
Service Type:
Supply concentrates in high-turnover sightseeing circuits while specialized aerial services command premium crew qualifications and equipment.
- Sightseeing Tours:Scheduled recreational flights over designated corridors with standardized routes and 4-6 passenger configurations. Demand clusters at the Grand Canyon, Hawaiian volcanoes, and Swiss Alpine passes where terrain inaccessibility drives aerial substitution. FAA Part 135 certification requirements and EASA safety mandates elevate operational compliance costs for scheduled service operators.
- Charter Services:On-demand rotary-wing transport for private parties with flexible routing and dedicated aircraft assignment. High-net-worth individuals in Dubai and New York generate the widest margin spreads through luxury hospitality cross-selling and exclusive landing site access. Pilot certification pipeline constraints restrict qualified crew availability, capping fleet expansion velocity.
- Aerial Photography:Specialized flights with stabilized camera mounts and door-off configurations for commercial and media clients.
- Emergency Services:Medical evacuation and search-rescue operations with night-vision and hoist-equipped aircraft.
Sightseeing tours absorb the bulk of installed capacity; charter services are expanding most quickly.
End User:
Customer acquisition economics diverge sharply between direct-to-consumer channels and intermediated corporate bookings.
- Adventure Seekers:Individual recreational travelers booking through operator websites or experience platforms with high price elasticity and seasonal concentration. Direct-to-consumer booking platforms are displacing traditional travel agency intermediaries, capturing margin previously lost to commissions. Modular tour packaging enables à-la-carte customization across base flights, private landings, and ground extensions.
- Travel Agencies:Luxury hospitality intermediaries bundling aerial excursions with villa packages and ground itineraries. High-end resorts in Hawaii and the Swiss Alps embed helicopter transfers into premium offerings, expanding addressable passenger pools beyond standalone adventure seekers.
- Corporate Clients:Business groups utilizing rotary transport for executive mobility and team-building events.
- Event Planners:Wedding and celebration coordinators arranging aerial arrivals and photography overflights.
Adventure seekers generate the highest transaction volume; travel agencies deliver the most predictable seasonal demand.
Flight Duration:
Route economics scale non-linearly with block time as fuel burn, crew duty limits, and turnaround logistics compound.
- Short Haul:Flights under 30 minutes connecting urban heliports with immediate periphery attractions. Dubai and New York are constructing dedicated heliport networks that reduce turnaround times and enable higher-frequency scheduling on these routes.
- Medium Haul:30-60 minute circuits covering multiple waypoints with intermediate landings. Papillon Grand Canyon Helicopters dominates this segment through extensive fleet scale and exclusive landing sites across the American Southwest corridor.
- Long Haul:Extended range operations exceeding 60 minutes with fuel stops or auxiliary tank configurations.
- Scenic Flights:Duration-flexible photography and observation missions with hover-capable routing.
Medium haul absorbs the bulk of installed capacity; short haul is climbing the fastest with urban air mobility infrastructure deployment.
Destination Type:
Route access permissions and community noise tolerance create divergent expansion headroom across geography categories.
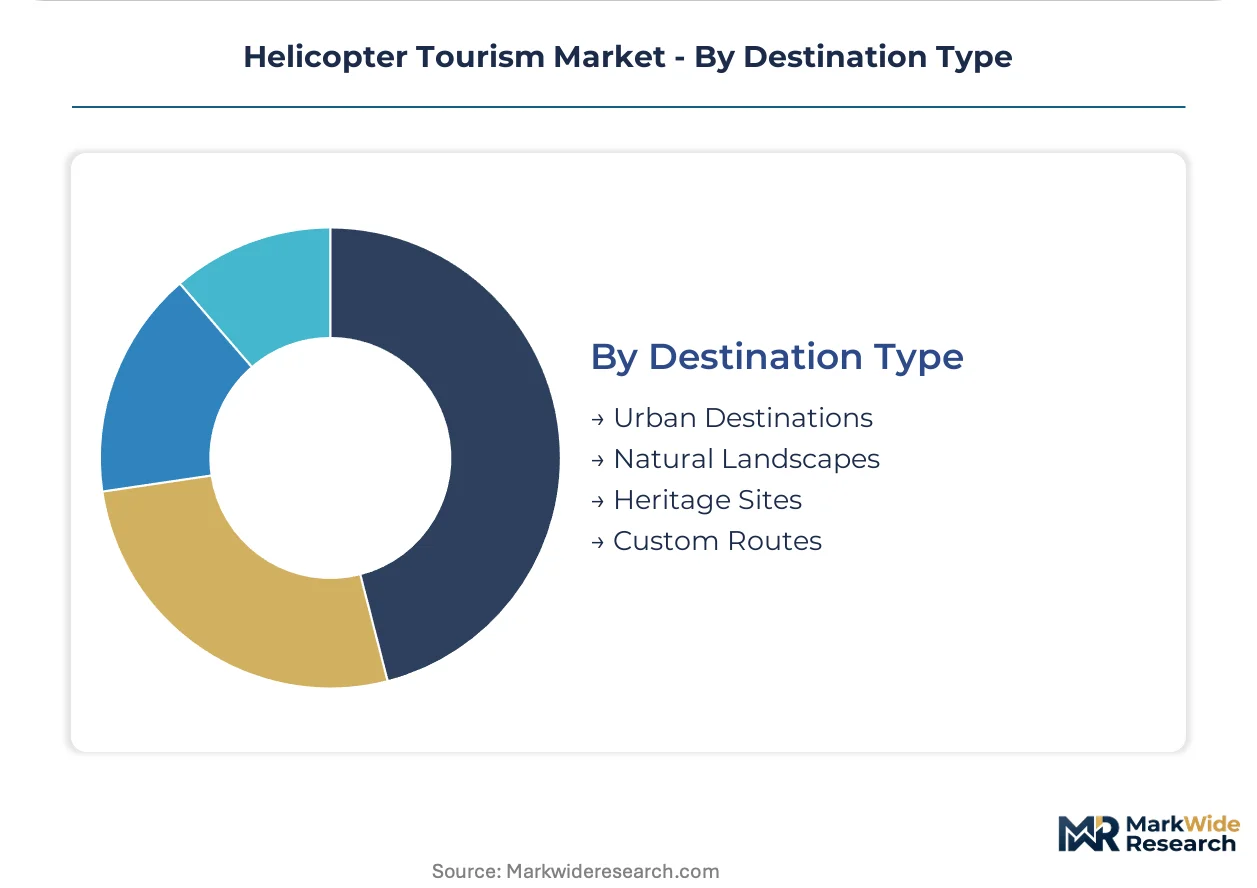
- Natural Landscapes:Terrain-defined corridors over mountains, canyons, and coastlines with limited surface access. National park overflight restrictions and tightening environmental noise limits constrain capacity expansion at the Grand Canyon and Swiss Alps. Hybrid-electric propulsion trials aim to preserve route access through reduced acoustic signatures.
- Urban Destinations:Metropolitan skylines and architectural landmarks with established heliport infrastructure. Dubai and New York show the steepest expansion trajectory as dedicated vertiport networks reduce regulatory friction and enable scheduled commuter-style service.
- Heritage Sites:Cultural and archaeological locations with restricted approach corridors and seasonal closures.
- Custom Routes:Bespoke itineraries negotiated for private clients with flexible waypoint selection.
Natural landscapes absorb the bulk of installed capacity; urban destinations are gaining share fastest with infrastructure investment acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Helicopter tourism clusters around coastal and mountainous tax-advantaged zones where luxury hospitality investment intersects with accessible terrain. The United States, Switzerland, UAE, India, and Australia concentrate distinct demand profiles shaped by local regulatory frameworks and infrastructure investment cycles.
United States
The Grand Canyon and Hawaiian volcanic corridors generate concentrated booking volume through luxury resort partnerships. FAA Part 135 certification requirements govern commercial charter operations, extending training timelines for pilots. Las Vegas anchors multi-destination bundling across the American Southwest, with operators leveraging exclusive landing site access to differentiate route portfolios.
Switzerland
Alpine passes and glacier access points attract high-net-worth adventure travelers through specialized mountain circuits. EASA safety management mandates shape fleet standards and predictive maintenance protocols across European-registered operators. The Swiss Alps region trials hybrid-electric powertrains to preempt tightening environmental noise restrictions on sensitive routes.
United Arab Emirates
Dubai's dedicated heliport network reduces turnaround times and enables higher-frequency scheduling on urban skyline routes. MOHAP aviation safety frameworks align with international standards for foreign-registered tourist helicopters. The emirate's luxury hospitality sector embeds helicopter transfers into villa packages, expanding addressable passenger pools beyond standalone bookings.
India
Himalayan and coastal circuits remain underpenetrated despite converging DGCA regulatory alignment with ICAO standards. The country's national aviation regulator mandates increasingly align with international benchmarks for foreign-registered tourist helicopters. Maharashtra and Karnataka host emerging clusters where operators test route viability before scaling fleet deployment.
Australia
Coastal reef and outback terrain drives demand for terrain-inaccessible aerial experiences. The national aviation safety authority enforces operational standards for commercial charter services across remote corridors. Queensland and New South Wales concentrate fleet deployment where tourism infrastructure intersects with natural landmark density.
Helicopter Tourism Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across the helicopter tourism sector, creating a tiered structure where scale-driven operators anchor high-frequency corridors and boutique providers capture premium customization margins. The market fragments across geographic clusters rather than consolidating nationally, with route access permissions and exclusive landing site leases serving as primary defensive moats. Two strategic archetypes dominate: integrated hospitality operators bundling air and ground experiences, and independent fleet specialists maximizing aircraft utilization through direct-to-consumer channels. Competitive moves center on exclusive landing site acquisition and vertical integration into reservation technology to displace travel agency intermediaries.
Among North American operators, Maverick Aviation Group and Papillon Grand Canyon Helicopters exemplify scale-driven corridor dominance through extensive fleet deployment and exclusive site access. Blue Hawaiian Helicopters occupies a specialist position in volcanic terrain circuits, representing the focused pure-play archetype against diversified competitors. These three companies anchor distinct geographic clusters where terrain inaccessibility and regulatory permissions create defensible market positions.
| Leading Market Players |
|---|
| Liberty Helicopters |
| Air Maui Helicopters |
| Maverick Aviation Group |
| Accretion Aviation |
| Safari Helicopters |
| Papillon Grand Canyon Helicopters |
| Niagara Helicopters Limited |
| Alpine Helicopters |
| Blue Hawaiian Helicopters |
| Others |
Supply Flow & Price Mechanics
Captive control over exclusive landing site leases anchors both supply positioning and pricing power across the helicopter tourism sector. Operators securing FAA Part 135 certification and EASA safety mandates command premium markups by restricting competitor access to high-demand corridors like the Grand Canyon and Swiss Alps.
Pricing Analysis
Short lead-time bookings command substantial premiums over advance reservations across scheduled sightseeing circuits. Three-tier pricing structure across premium, standard, and economy levels segments adventure seekers from corporate clients and high-net-worth individuals. Price differentiation rests on exclusive landing access and customization depth. Cost compression in base sightseeing tiers is intensifying because direct-to-consumer booking platforms displace travel agency commissions. Adventure seekers exhibit highest price sensitivity; charter clients demonstrate lowest elasticity.
Supply Chain Analysis
Domestic-content mandates for pilot certification and maintenance crew qualifications reshape sourcing patterns across operator networks. Fleet manufacturing concentrates in the United States, France, and Italy. Turbine engine supply draws from specialized aerospace foundries in the United Kingdom and Germany. Single-source vulnerability in avionics components creates exposure to semiconductor allocation disruptions. Distribution runs through operator-owned reservation platforms and luxury hospitality intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply constraints around certified pilots and airframe maintenance technicians prop pricing power across the helicopter tourism sector. This capacity bottleneck limits fleet expansion velocity and sustains margin structures for incumbent operators.
For Market Incumbents: Cement exclusive landing site portfolios through long-term lease extensions at the Grand Canyon, Hawaiian volcanoes, and Swiss Alpine corridors. Lock in captive maintenance technician pipelines via apprenticeship partnerships with FAA-approved training centers. Hybrid-electric propulsion trials represent the critical R&D lever for preempting noise-based route restrictions. For New Entrants and Emerging Players: Underpenetrated Himalayan circuits in India offer white-space entry with converging DGCA regulatory alignment. Coastal reef tourism in Queensland and New South Wales presents secondary expansion terrain. Direct-to-consumer booking platform development captures margin previously lost to travel agency intermediaries. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by integrated hospitality conglomerates seeking vertical control over guest experiences. Long-term viability hinges on route access preservation amid tightening environmental noise frameworks. Monitor EASA safety management mandate compliance costs as the inflection signal for distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| Exclusive Landing Site Acquisition | FAA Part 135 operators secure defensible corridor control against competitor encroachment. |
| Hybrid-Electric Fleet Transition | EASA noise compliance trials preserve Grand Canyon and Swiss Alps route permissions. |
| Direct-to-Consumer Platform Launch | Operator reservation systems displace travel agency intermediaries and recapture commission margins. |
| Pilot Certification Pipeline Investment | FAA-approved training partnerships reduce crew scarcity constraints on fleet utilization. |
| Luxury Hospitality Integration | High-end resorts in Hawaii and Dubai embed helicopter transfers into premium villa packages. |
Methodological Framework
Document review covered FAA regulatory filings, EASA safety management directives, and national aviation authority guidance documents, complemented by interviews with helicopter tour operators, fleet maintenance directors, luxury hospitality procurement managers, and pilot training center administrators. Secondary validation drew from customs trade data, SEC operator disclosures, and tourism infrastructure investment databases. Bottom-up route-level demand modeling triangulated against top-down market sizing across service type and destination categories.
Segmented outputs across service tier, customer archetype, flight duration band, and geography cluster fed into the projection framework. CAGRs were derived from regression analysis against historical booking velocity and fleet deployment patterns. Forecast inputs incorporated turbine fuel price trajectory assumptions and pilot certification pipeline constraints.
Revisions become necessary when national park overflight restrictions tighten, sustainable aviation fuel mandates accelerate, or urban air mobility zoning conflicts redraw heliport permissions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tourist Transport Services
UK Low Cost Airlines Market
Tourist Transport Services
Travel Transportation Market
Tourist Transport Services
Yacht Rental Market
Tourist Transport Services
India International Express Service Market
Tourist Transport Services
Low-Cost Carrier (LCC) Market
Tourist Transport Services
Boat Rental Market
Tourist Transport Services
Airport Ground Transportation Market
Tourist Transport Services
Europe Charter Jet Services Market
Tourist Transport Services
Southeast Asia Charter Jet Services Market
Tourist Transport Services
Pre-Book Airport Transfer Market
Tourist Transport Services
Italy Car Rental Market