
 Yacht Rental Market | 2026-2036
Yacht Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Yacht Rental Market Analysis
Asset-light fleet management through third-party vessel leasing is fragmenting capital requirements across the competitive landscape. Dream Yacht Charter leverages its distributed ownership model to sustain inventory breadth without direct hull acquisition costs. Fraser Yachts anchors its position through curated brokerage-to-charter pipelines that control premium client access. IYC (International Yacht Collection) differentiates via specialized superyacht placement across Caribbean and Mediterranean circuits.
A yacht rental denotes the short-term contractual use of a motorized or sailing vessel, typically spanning 12 to 24 meters in leisure configuration, for recreational cruising, corporate hospitality, or special-event staging without ownership transfer. Motor yachts dominate transaction volume due to operational simplicity and broader skipper certification compatibility, while catamarans represent the fastest-expanding yacht type as multihull stability attracts family-oriented charterers. Crewed charter services command premium pricing tiers, whereas bareboat arrangements appeal to certified sailors seeking cost-controlled autonomy.
French maritime authorities enforce strict safety-equipment mandates under the Division 240 regulatory framework, while the EU's MDR governs onboard medical-device compliance for extended voyages. The US Coast Guard and Bahamas Maritime Authority jointly shape flag-state inspection standards that determine fleet eligibility for Caribbean operations. Stakeholders must monitor evolving carbon-intensity thresholds for marine propulsion as regulatory bodies tighten environmental compliance across charter corridors.
Market Dynamics
Post-pandemic distributed workforces have transformed corporate retreat planners into the fastest-expanding end-user category, while the EU's F-Gas Regulation tightens refrigerant standards for onboard climate systems and forces fleet-wide retrofits.
Growth Catalysts
- Corporate Retreat Demand:Distributed workforce models sustain offsite venue requirements across Monaco, Cannes, and Nice charter corridors.
- Catamaran Stability Appeal:Multihull configurations attract family-oriented charterers seeking reduced seasickness risk and expanded deck space.
- EU F-Gas Regulation:Refrigerant phase-down mandates accelerate climate-system retrofit cycles and extend vessel upgrade revenue streams.
Market Restraints
- Flag-State Inspection Fragmentation:US Coast Guard and Bahamas Maritime Authority maintain divergent eligibility standards that complicate Caribbean fleet deployment.
- Skipper Certification Bottleneck:Bareboat charter growth faces constraint from limited availability of commercially endorsed skippers in Mediterranean hubs.
- Hull Acquisition Capital Intensity:Direct vessel ownership demands substantial balance-sheet commitment that excludes smaller regional operators.
Strategic Opportunities
- Third-Party Leasing Models:Distributed ownership structures reduce capital barriers and enable inventory breadth without direct hull exposure.
- Extended Voyage Medical Compliance:EU MDR device certification requirements create specialized outfitting demand for superyacht segments.
- Carbon-Intensity Threshold Preparation:Proactive propulsion upgrades position operators ahead of tightening marine environmental compliance.
Industry Challenges
- Division 240 Safety Mandates:French maritime authorities enforce equipment standards that demand continuous inventory monitoring and replacement cycles.
- Crewed Charter Talent Pipeline:Premium service tier expansion faces hospitality-staff scarcity in seasonal Mediterranean markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Yacht Rental Market |
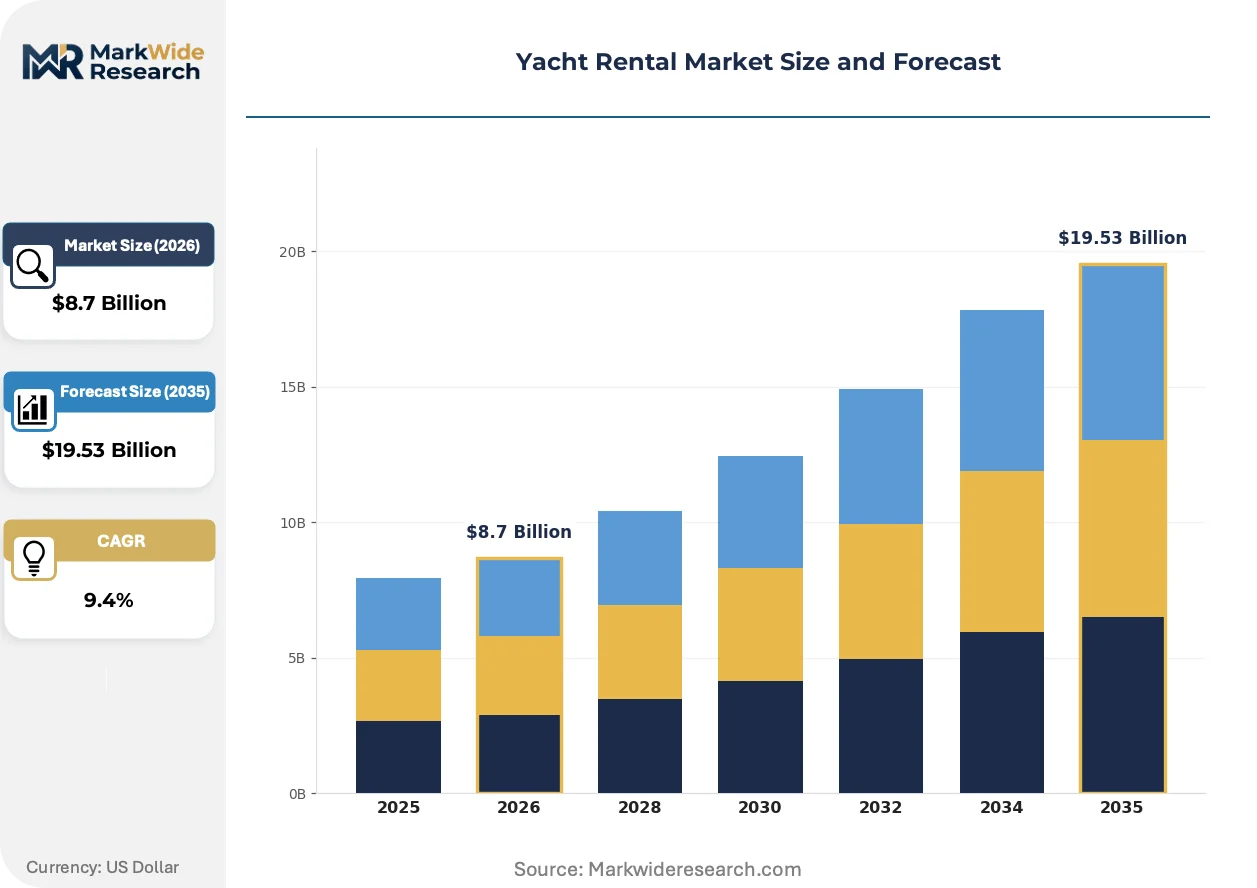
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Yacht Type: Sailing Yachts, Motor Yachts, Catamarans, Luxury Yachts End User: Tourists, Corporate Clients, Event Planners, Private Individuals Trip Duration: Daily Rentals, Weekly Charters, Monthly Charters, Special Event Rentals Service Type: Bareboat Charter, Crewed Charter, Corporate Events, Concierge Services |
| Companies Covered | Four Seasons Yachts, YachtCharterFleet, IYC (International Yacht Collection), Sanlorenzo, West Coast International, Dream Yacht Charter, CharterWorld, Feadship, Fraser Yachts, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Yacht Rental Market Emerging Trajectories
Hybrid-electric propulsion architectures and digital charter platforms are compressing traditional operational models while regulatory pressure on marine emissions accelerates fleet renewal decisions.
Hybrid-electric propulsion systems integrate battery-electric auxiliary power with conventional diesel prime movers. Charter operators in the French Riviera corridor adopt these configurations to meet anticipated port emission restrictions. The technology is collapsing the operational cost advantage previously held by legacy diesel-only fleets as fuel savings and maintenance reduction compound across high-utilization seasons.
The EU's F-Gas Regulation mandates refrigerant phase-down with GWP thresholds tightening through 2030. Onboard HVAC retrofit requirements now dominate vessel upgrade planning for Mediterranean-based operators. Superyacht segments face the steepest compliance cost exposure and are responding through centralized fleet-management contracts that bundle climate-system modernization.
Corporate retreat planners now bypass traditional brokerage intermediaries and contract directly with fleet operators through specialized procurement platforms. This channel disintermediation concentrates volume with asset-light operators capable of rapid itinerary customization. The shift is most visible across Monaco, Cannes, and Nice, where distributed ownership models align with corporate procurement velocity requirements.
Yacht Rental Market Segmentation
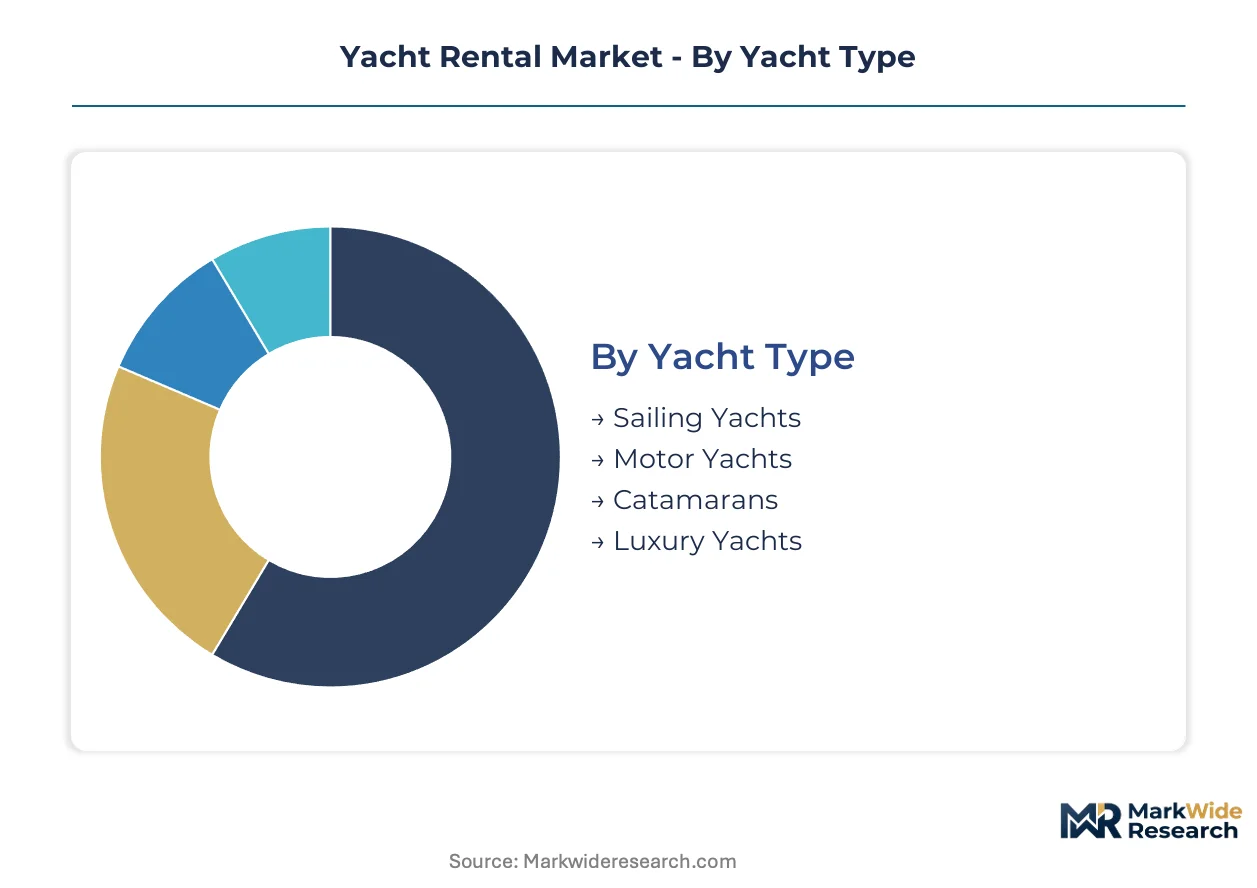
Yacht rental segmentation reveals distinct operational profiles across vessel configurations and client relationships. Fleet operators configure service tiers around technical complexity, regulatory exposure, and hospitality intensity rather than simple size classifications.
Yacht Type:
After-sales service intensity varies dramatically across hull architectures, with multihull and superyacht segments demanding specialized maintenance partnerships.
- Motor Yachts:Diesel or hybrid-electric propulsion systems dominate transaction volume through operational simplicity and broader skipper certification compatibility. Demand concentrates along the French Riviera corridor where Monaco, Cannes, and Nice anchor Mediterranean charter volume; fleet operators favor these configurations for high-utilization seasonal deployment.
- Catamarans:Twin-hull stability and expanded deck space attract family-oriented charterers seeking reduced seasickness risk. Demand concentrates in Caribbean circuits where shallow-draft access enables beach anchoring; multihull configurations are climbing the fastest as charterers prioritize onboard living space over raw speed.
- Sailing Yachts:Wind-powered vessels appeal to purist sailors and regatta participants; operational complexity limits commercial fleet penetration outside specialized brokerage portfolios.
- Luxury Yachts:Superyacht segments above 24 meters command premium positioning through crewed service mandates and concierge integration.
Motor yachts hold the largest share; momentum sits with catamarans.
End User:
Cost tier differentiation separates occasional leisure users from contracted corporate accounts with negotiated rate structures.
- Corporate Clients:Distributed workforce models sustain offsite venue requirements across Mediterranean charter corridors. Procurement platforms enable direct fleet contracting that bypasses traditional brokerage intermediaries; volume concentrates with asset-light operators capable of rapid itinerary customization.
- Event Planners:Wedding and celebration staging demands flexible vessel configurations with catering infrastructure and deck capacity for entertainment setup.
- Tourists:International visitors seek packaged experiences with pre-planned itineraries and shore excursion integration; seasonal concentration drives revenue volatility.
- Private Individuals:Ultra-high-net-worth households maintain recurring charter relationships for privacy-controlled leisure; loyalty programs and preferred vessel allocation sustain retention.
Corporate clients hold the largest share; momentum sits with event planners.
Trip Duration:
Application patterns range from impulse day trips to extended voyages requiring EU MDR medical device compliance and provisioning logistics.
- Weekly Charters:Seven-day itineraries represent the standard commercial unit across Mediterranean and Caribbean circuits; fleet scheduling optimizes around Saturday-to-Saturday turnover patterns.
- Daily Rentals:Short-duration excursions serve coastal tourism hubs with high passenger throughput and limited customization; operational intensity demands rapid vessel turnaround.
- Monthly Charters:Extended deployments require comprehensive provisioning, crew rotation protocols, and flag-state inspection coordination across multiple jurisdictions.
- Special Event Rentals:Single-day corporate hospitality and celebration staging commands premium pricing through exclusive venue positioning and catering integration.
Weekly charters hold the largest share; momentum sits with special event rentals.
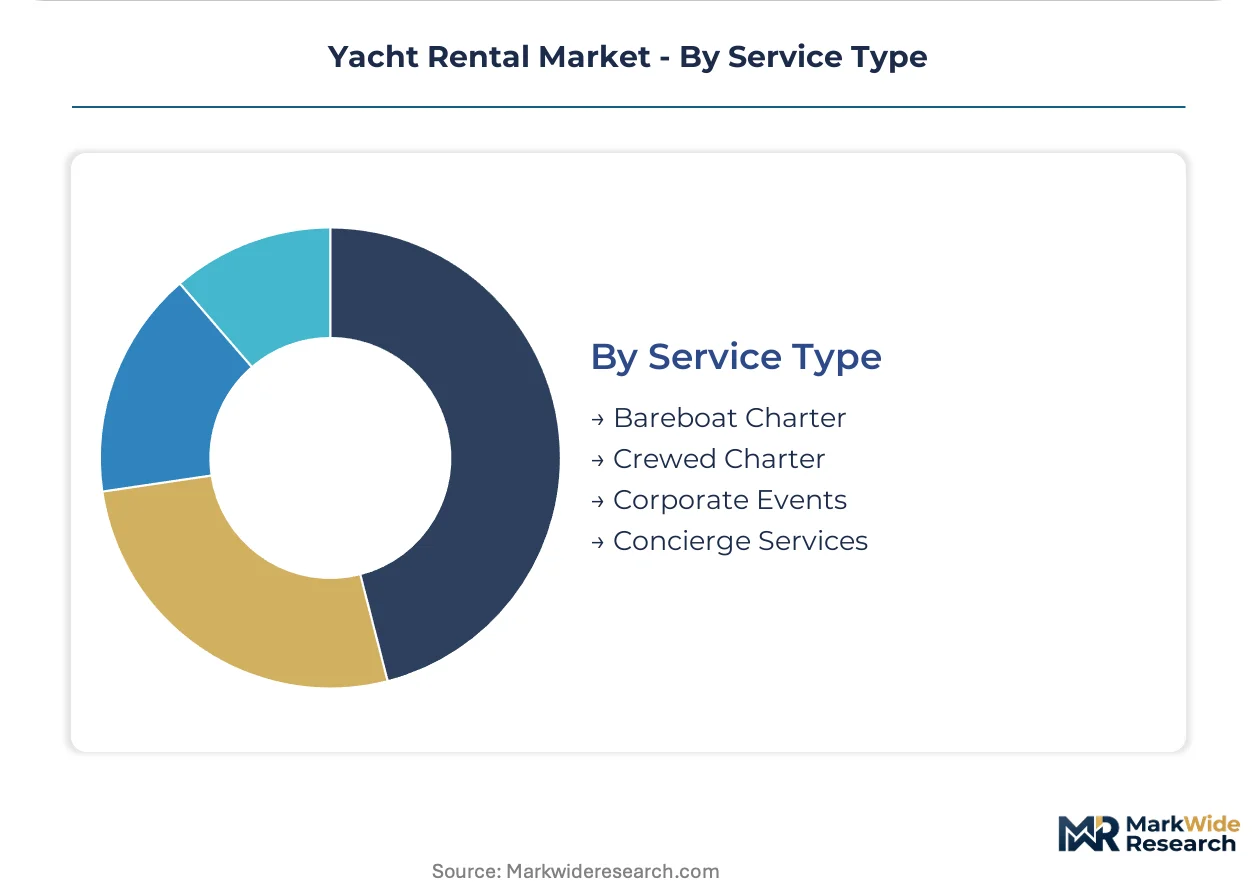
Service Type:
Customer type and margin structure diverge sharply between autonomy-focused bareboat arrangements and labor-intensive crewed operations.
- Crewed Charter:Professional hospitality staff and licensed deck crews command premium pricing tiers through service differentiation; talent scarcity in seasonal Mediterranean markets constrains expansion.
- Bareboat Charter:Certified sailors seek cost-controlled autonomy without crew overhead; skipper certification bottlenecks in Mediterranean hubs limit addressable market growth.
- Corporate Events:Specialized procurement platforms concentrate volume with operators capable of rapid itinerary customization and branded vessel staging.
- Concierge Services:Integrated shore excursion, provisioning, and transportation coordination extends charter value beyond vessel access; superyacht segments bundle these capabilities through centralized fleet-management contracts.
Crewed charter holds the largest share; momentum sits with concierge services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU's F-Gas Regulation is tightening refrigerant standards across Mediterranean charter corridors, while national maritime authorities enforce divergent safety mandates that reshape fleet deployment economics.
France
Corporate retreat planners drive demand concentration along the Côte d'Azur where Monaco, Cannes, and Nice anchor Mediterranean charter volume. French maritime authorities enforce strict safety-equipment mandates under the Division 240 regulatory framework. Fleet operators in Marseille and Antibes respond through accelerated climate-system retrofits to meet EU F-Gas phase-down timelines.
United States
Ultra-high-net-worth households sustain recurring charter relationships across Florida and Northeast coastal corridors. The US Coast Guard shapes flag-state inspection standards that determine fleet eligibility for Caribbean operations. Miami and Fort Lauderdale clusters concentrate bareboat inventory serving certified sailors seeking cost-controlled autonomy.
Italy
Event planners generate seasonal demand spikes for wedding and celebration staging across Sardinia and Amalfi Coast circuits. The EU's MDR governs onboard medical-device compliance for extended voyages departing from Italian ports. Genoa and Viareggio anchor superyacht outfitting activity where specialized maintenance partnerships sustain multihull segments.
Spain
International tourists seek packaged experiences with pre-planned itineraries across Balearic Islands charter corridors. Spanish maritime authorities align with EU refrigerant standards while maintaining distinct crew-certification requirements. Barcelona and Palma de Mallorca clusters concentrate fleet-management contracts bundling climate-system modernization.
Bahamas
Family-oriented charterers prioritize catamaran stability for shallow-draft beach anchoring across Exuma and Abaco circuits. The Bahamas Maritime Authority jointly shapes inspection standards with US regulators for Caribbean fleet deployment. Nassau anchors brokerage-to-charter pipelines controlling premium client access for extended voyages.
Yacht Rental Market Vendor Landscape
On the supply side, the industry is structurally tiered between asset-heavy hull owners and asset-light fleet operators leasing third-party vessels. Consolidation pressure concentrates among superyacht segments above 24 meters, while fragmentation persists in bareboat and day-charter tiers. Two strategic archetypes dominate: distributed ownership platforms reducing capital barriers, and curated brokerage pipelines controlling premium client access. Competitive moves center on fleet-management contract centralization and rapid itinerary customization capabilities.
Among distributed ownership specialists, Dream Yacht Charter exemplifies the asset-light archetype sustaining inventory breadth without direct hull acquisition costs. Fraser Yachts and IYC (International Yacht Collection) anchor the premium-tier vector through curated brokerage-to-charter pipelines that concentrate volume with operators capable of branded vessel staging and concierge integration.
| Leading Market Players |
|---|
| Four Seasons Yachts |
| YachtCharterFleet |
| IYC (International Yacht Collection) |
| Sanlorenzo |
| West Coast International |
| Dream Yacht Charter |
| CharterWorld |
| Feadship |
| Fraser Yachts |
| Others |
Supply Flow & Price Mechanics
Mediterranean-to-Caribbean repositioning corridors absorb seasonal fleet migration costs that concentrate pricing power with asset-light operators controlling vessel access without hull ownership. Supply concentration along the French Riviera and Florida brokerage clusters enables premium tier capture, while bareboat operators face margin compression from skipper certification scarcity and regulatory compliance burdens.
Pricing Analysis
Crew certification level creates the primary spread between premium crewed charters and cost-controlled bareboat arrangements. Three-tier pricing structure across luxury superyacht, standard motor yacht, and economy bareboat levels reflects hospitality intensity and regulatory exposure. Pricing pressure stems from EU F-Gas retrofit mandates that elevate fixed costs for climate-system compliance. Corporate retreat planners exhibit lowest price sensitivity through procurement platform direct contracting, while tourist segments face highest sensitivity to seasonal rate volatility.
Supply Chain Analysis
Extended payment terms from shipyard financing facilities enable fleet operators to defer hull acquisition capital without direct ownership exposure. Vessel supply concentrates in France, Italy, and Turkey where specialized shipyards and refit yards cluster. Raw material dependencies center on marine-grade aluminum, carbon fiber composites, and hybrid-electric propulsion systems. Single-source vulnerability runs through concentrated superyacht builder capacity for vessels above 40 meters. Distribution runs through curated brokerage pipelines and direct digital platforms that disintermediate traditional charter intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The yacht rental market sustains defensive moats through regulatory entrenchment, as flag-state inspection standards and EU environmental mandates create compliance barriers that favor established operators with centralized fleet-management capabilities.
For Market Incumbents: Insulate premium positioning through accelerated EU MDR medical device certification for extended voyage segments, countering emerging asset-light competitors lacking compliance infrastructure. Deepen backward integration into refit and maintenance partnerships across Marseille and Antibes clusters to capture retrofit revenue from F-Gas phase-down mandates.
For New Entrants and Emerging Players: Establish a beachhead in catamaran bareboat segments where family-oriented demand outpaces certified skipper supply, exploiting the stability appeal that reduces operational complexity. Target Caribbean circuits with shallow-draft vessel configurations, leveraging direct procurement platform relationships to bypass entrenched brokerage intermediaries controlling Mediterranean access.
For Investors and Strategic Acquirers: EU F-Gas Regulation phase-down timelines reshape the acquisition landscape toward operators with proactive climate-system modernization and centralized fleet-management contracts. Long-term viability favors asset-light platforms with distributed ownership structures over hull-heavy balance sheets. Monitor carbon-intensity threshold announcements from flag-state authorities as the critical inflection signal for propulsion upgrade investment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid-Electric Fleet Conversion | EU port emission restrictions in Monaco, Cannes, and Nice mandate propulsion modernization for market access retention. |
| Direct Procurement Platform Launch | Corporate retreat planners bypass traditional brokerage intermediaries, concentrating volume with rapid-customization operators. |
| Centralized Fleet-Management Contracting | Superyacht segments bundle climate-system retrofit, medical device compliance, and concierge services through unified agreements. |
| Caribbareboat Skipper Certification Pipeline | Mediterranean certification scarcity constrains bareboat growth; dedicated training partnerships unlock addressable market expansion. |
| Third-Party Vessel Leasing Expansion | Distributed ownership models reduce capital barriers and enable inventory breadth without direct hull acquisition exposure. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fleet managers, charter brokers, corporate procurement officers, and maritime regulatory consultants. Secondary validation drew from EU F-Gas Regulation filings, French Division 240 safety equipment mandates, Bahamas Maritime Authority inspection protocols, and customs data on vessel import flows. Bottom-up triangulation across individual charter transaction patterns converged with top-down fleet capacity estimates from shipyard delivery schedules.
Calibration against historical utilization rates and seasonal migration patterns anchored the analytical framework across the projection horizon. Segmentation dimensions modeled encompass yacht type, service tier, trip duration, and end-user category alongside regional regulatory cluster differentiation. CAGRs were derived from trend extrapolation moderated by compliance cost absorption capacity and fleet renewal cycle timing. Hybrid-electric propulsion adoption curves and corporate retreat procurement velocity served as industry-specific forecast inputs.
Stress conditions across fuel price volatility, flag-state inspection stringency, and skipper certification availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory phase-down timelines and fleet operator compliance investment capacity. Macroeconomic contraction, accelerated environmental mandate implementation, or breakthrough propulsion technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tourist Transport Services
Europe Charter Jet Services Market
Tourist Transport Services
Pre-Book Airport Transfer Market
Tourist Transport Services
Airport Ground Transportation Market
Tourist Transport Services
Boat Rental Market
Tourist Transport Services
Travel Transportation Market
Tourist Transport Services
Helicopter Tourism Market
Tourist Transport Services
UK Low Cost Airlines Market
Tourist Transport Services
Low-Cost Carrier (LCC) Market
Tourist Transport Services
India International Express Service Market
Tourist Transport Services
Italy Car Rental Market
Tourist Transport Services
Southeast Asia Charter Jet Services Market