
 UK Low Cost Airlines Market | 2026-2036
UK Low Cost Airlines Market Size, Share, and Industry Trends Forecast 2026-2036
UK Low Cost Airlines Market Insights
Unbundled ancillary pricing is pivoting how UK passengers configure their journeys, separating base fares from seat selection, baggage, and priority boarding. easyJet leverages its Gatwick and Luton bases to sustain high-frequency European coverage. Ryanair anchors ultra-low base fares across its UK network while competing aggressively on airport-pair costs. Jet2.com differentiates through bundled holiday packages that control seasonal capacity across Mediterranean and Canary Island routes.
UK low cost airlines operate narrow-body aircraft configured for high-density seating, typically 180-235 seats on single-aisle jets with turnaround targets below 30 minutes to maximize daily aircraft utilization. Their primary commercial purpose is delivering point-to-point air transport at fare levels below legacy network carriers by stripping included services and optimizing load factors. Single-aisle jets dominate fleet composition due to their unit economics on short-haul sectors, while point-to-point flights command the majority of sector capacity by eliminating connection costs and ground time. Direct website booking and mobile apps are capturing growing share of distribution as carriers reduce online travel agency commissions and capture first-party customer data.
The UK Civil Aviation Authority enforces safety and operational standards, while the Competition and Markets Authority monitors route-level competition and consumer protection compliance. EU-derived environmental regulations continue shaping emissions reporting requirements and sustainable aviation fuel blending mandates for UK-registered carriers. Stakeholders must monitor slot allocation reforms at congested London airports and the pace of airspace modernization to assess capacity expansion feasibility.
Market Dynamics
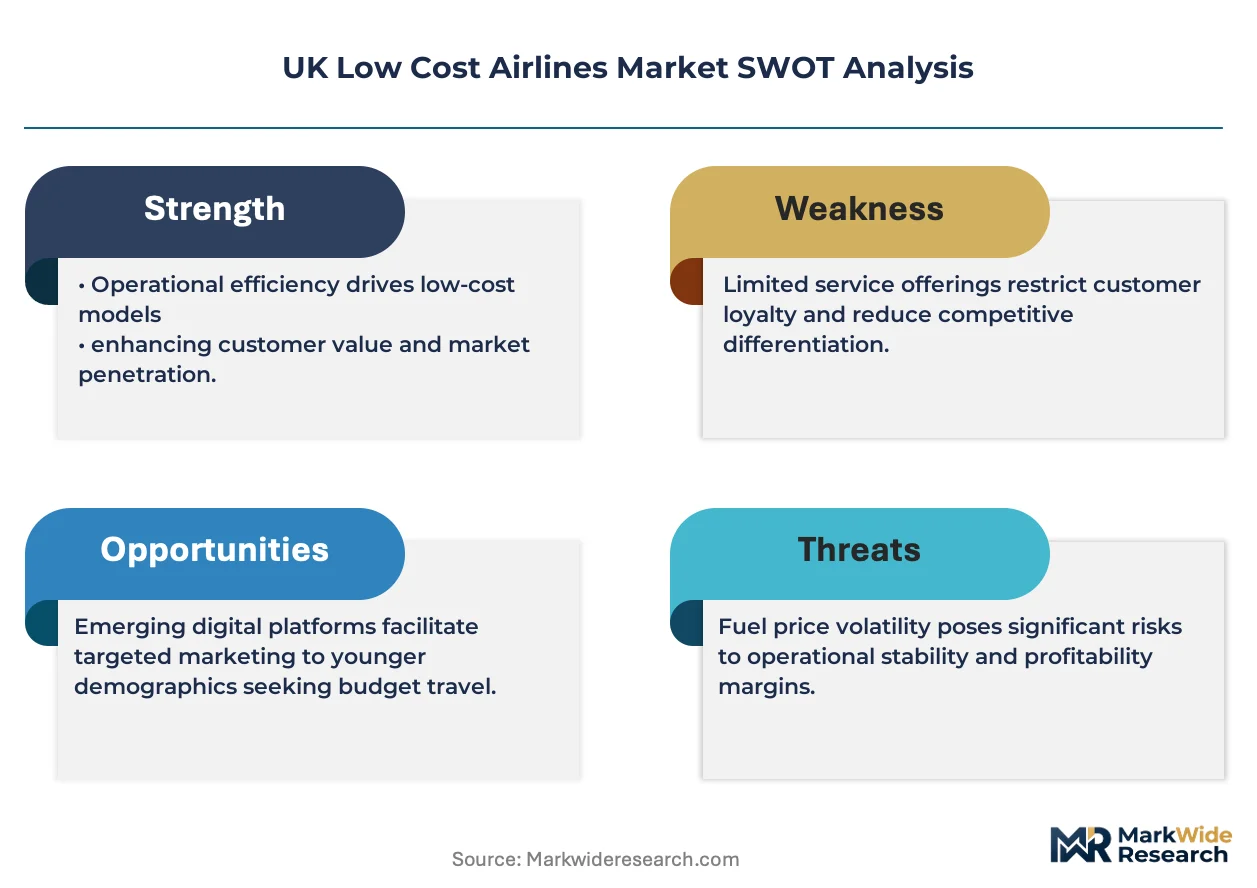
The UK Civil Aviation Authority's tightening environmental compliance frameworks are compressing operational margins while forcing fleet renewal cycles, fundamentally altering how carriers configure route economics and asset utilization across their networks.
Growth Catalysts
- Digital Distribution Channels:Direct website booking and mobile apps are capturing growing share of ticket sales, reducing online travel agency commissions and enabling first-party customer data capture for personalized ancillary offers.
- Jet Kerosene Price Volatility Hedging:Sophisticated fuel hedging instruments are stabilizing unit cost bases, allowing carriers to maintain fare competitiveness during crude oil price spikes.
- EU-derived SAF Mandates:Sustainable aviation fuel blending requirements are accelerating fleet modernization toward more fuel-efficient narrow-body aircraft with lower per-seat emissions profiles.
Market Restraints
- Slot Scarcity at London Airports:Heathrow and Gatwick slot allocation constraints limit frequency expansion on high-yield business routes, forcing reliance on secondary bases.
- Pilot Training Pipeline Bottlenecks:Cadet program capacity restrictions and type-rating cost burdens are extending crew recruitment timelines beyond fleet growth curves.
- Air Passenger Duty Escalation:Treasury tax policy on short-haul departures erodes the fare advantage over rail alternatives on domestic trunk routes.
Strategic Opportunities
- Scottish and Northern English Base Expansion:Edinburgh, Manchester, and Birmingham catchments show underpenetrated point-to-point connectivity to secondary European leisure destinations.
- Ancillary Revenue Unbundling:Dynamic pricing engines for seat selection, baggage tiers, and priority boarding are creating new margin pools detached from base fare competition.
- Domestic Route Rationalization:High-speed rail competition gaps on cross-country corridors present frequency-building potential where surface journey times exceed three hours.
Industry Challenges
- Air Traffic Management Modernization Delays:National Air Traffic Services infrastructure upgrade timelines are extending flight path inefficiencies and sector capacity constraints.
- Narrow-Body Aircraft Delivery Backlogs:Airbus and Boeing production rate limitations are stretching fleet replacement schedules and deferring unit cost improvements from next-generation engine technology.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Low Cost Airlines Market |
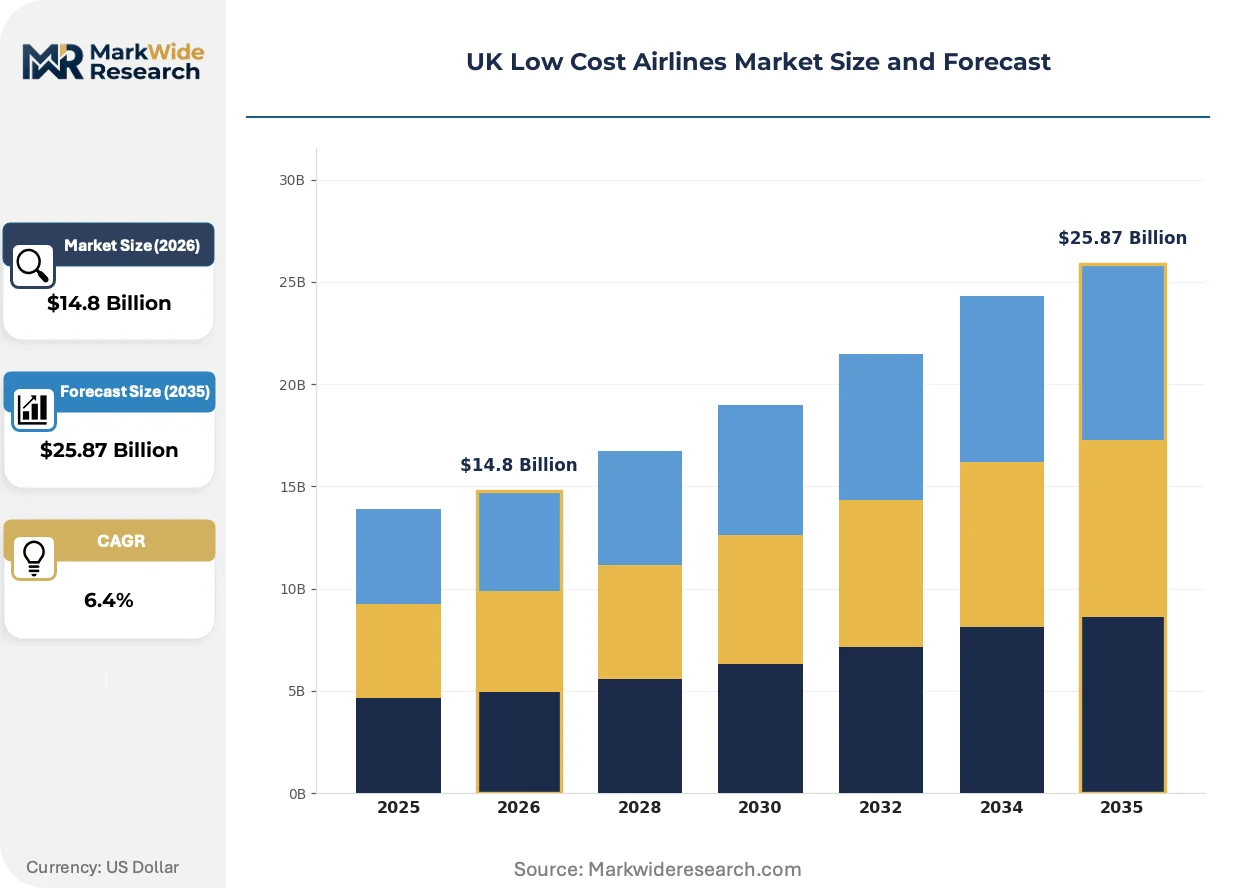
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Aisle Jets, Regional Aircraft, Turboprop Planes, Electric Planes Service Type: Point-to-Point Flights, Connecting Flights, Charter Services, Seasonal Routes Customer Type: Leisure Travelers, Business Flyers, Backpackers, Students, Retirees Distribution Channel: Online Travel Agencies, Direct Website Booking, Mobile Apps, Travel Agents |
| Companies Covered | easyJet, Ryanair, Jet2.com, Wizz Air UK, TUI Airways, Vueling, Ryanair UK, Norse Atlantic UK, Jet2holidays, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Low Cost Airlines Market Trends and Innovations
Data-centric revenue management systems are converging with behavioral analytics to transform how UK low cost carriers price inventory and configure ancillary bundles across booking channels.
Artificial intelligence-driven demand forecasting is converging with dynamic pricing algorithms to optimize load factors on thin European routes. Revenue management teams at carriers operating from London Stansted and Luton are deploying machine learning models that adjust fare buckets in real-time based on competitor pricing and search velocity. This technology convergence is compressing the revenue optimization cycle from weekly to hourly intervals.
The UK Civil Aviation Authority's carbon reporting mandates are tightening emissions disclosure requirements for all scheduled operators. Carriers must now submit verified CO2 per passenger-kilometer data across their networks, with non-compliance risking operational license reviews. Short-haul domestic and near-European routes face the steepest compliance cost escalation as older aircraft remain in service pending delivery slots.
Leisure travelers are fragmenting their booking behavior across multiple touchpoints before purchase completion. Mobile-first search and price comparison aggregators are displacing traditional travel agent channels for Mediterranean holiday routes. This pattern is most visible in Manchester and Birmingham catchments where package holiday bundling still dominates Canary Islands and Balearic demand.
UK Low Cost Airlines Market Segmentation
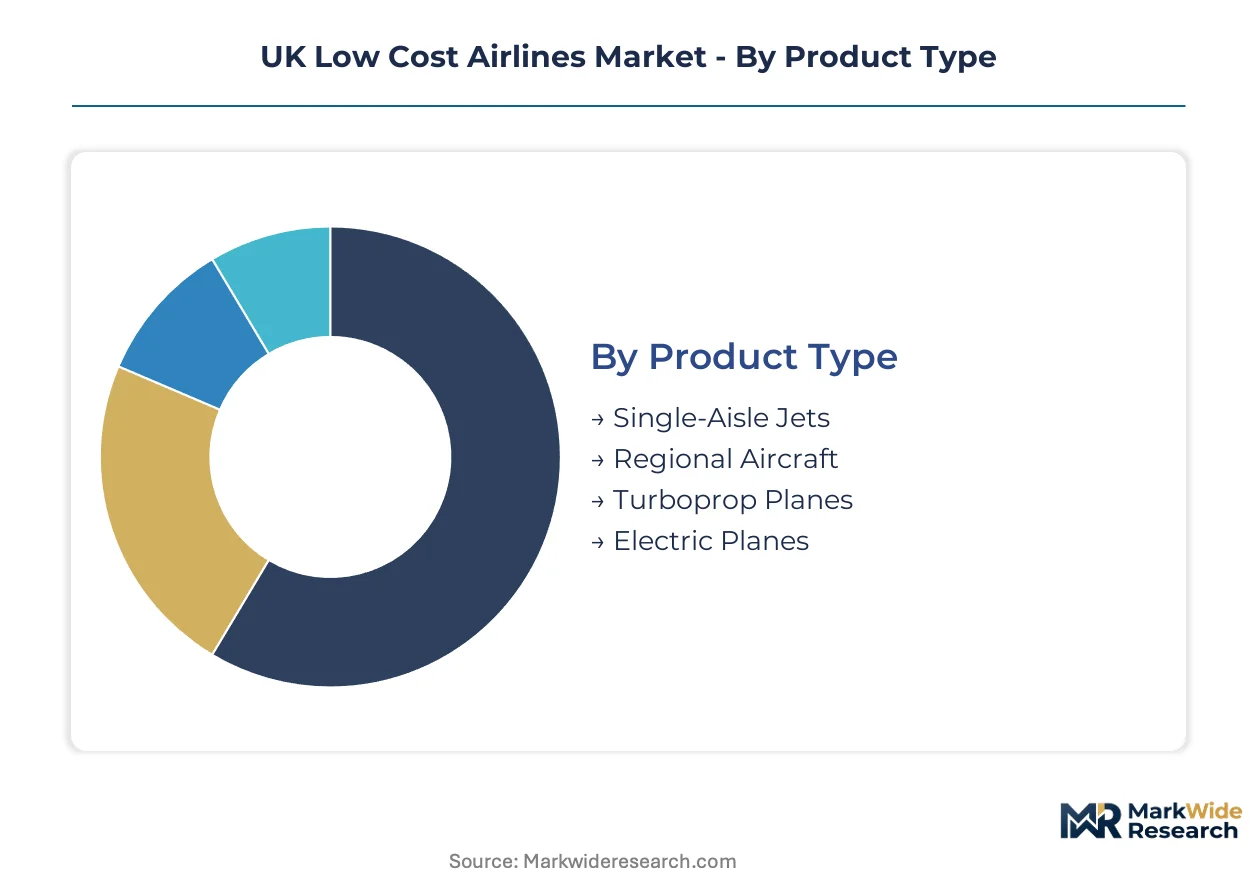
Segmentation reveals how UK low cost carriers allocate fleet assets and configure revenue systems across distinct operational layers. Each axis exposes different margin pressures and growth vectors within the market.
Product Type:
Airframe specifications determine seat density economics and turnaround feasibility across UK bases.
- Single-Aisle Jets:Narrow-body aircraft configured for 180-235 seats dominate fleet composition. easyJet and Ryanair deploy Airbus A320-family and Boeing 737-series aircraft from Gatwick, Luton, and Stansted to maximize daily utilization on sub-three-hour European sectors.
- Regional Aircraft:Smaller narrow-body variants serve thinner routes from Edinburgh and Birmingham where load factors cannot sustain larger gauge. Jet2.com utilizes these aircraft for seasonal capacity injection into Mediterranean leisure markets during peak summer demand windows.
- Turboprop Planes:Limited residual presence on domestic trunk routes where surface competition from rail operators constrains yield recovery.
- Electric Planes:Emerging technology constrained by battery energy density limitations and airworthiness certification timelines under UK Civil Aviation Authority oversight.
Mature deployment sits with Single-Aisle Jets. Newer deployment is concentrated in Electric Planes.
Service Type:
Route architecture choices separate asset-light operators from carriers carrying connection infrastructure costs.
- Point-to-Point Flights:Direct sector operation without hub-and-spoke connections defines the UK low cost model. Ryanair and easyJet schedule 6-8 daily frequencies on dense airport pairs to capture price-sensitive demand without ground handling complexity.
- Connecting Flights:Self-transfer products allow passengers to stitch itineraries across separate bookings. Some carriers now sell connection protection as an ancillary tier, though operational reliability constraints limit penetration.
- Charter Services:Wet-lease and ad-hoc capacity deployment for tour operators and sports event movements.
- Seasonal Routes:Capacity reallocation from winter domestic networks to summer Mediterranean and Canary Island markets.
Volume concentration favors Point-to-Point Flights. Margin expansion potential sits with Connecting Flights.
Customer Type:
Passenger mix shapes ancillary attachment rates and advance booking curves across distribution channels.
- Leisure Travelers:Price-elastic demand for beach and city-break destinations drives base fare minimization and high ancillary attachment on baggage and seat selection. Manchester and Birmingham catchments show dense concentration for package holiday bundling.
- Business Flyers:Time-sensitive demand on London-Edinburgh and London-Belfast corridors accepts premium tiers for flexibility and priority boarding. Frequency concentration at Gatwick and City Airport supports this segment.
- Backpackers:Extreme price sensitivity with minimal ancillary purchase and extended booking horizons.
- Students:Seasonal demand spikes aligned with academic calendars and holiday travel windows.
- Retirees:Flexible travel dates enable yield management optimization on off-peak departures to Mediterranean destinations.
Revenue scale anchors on Leisure Travelers. Yield improvement opportunity centers on Business Flyers.
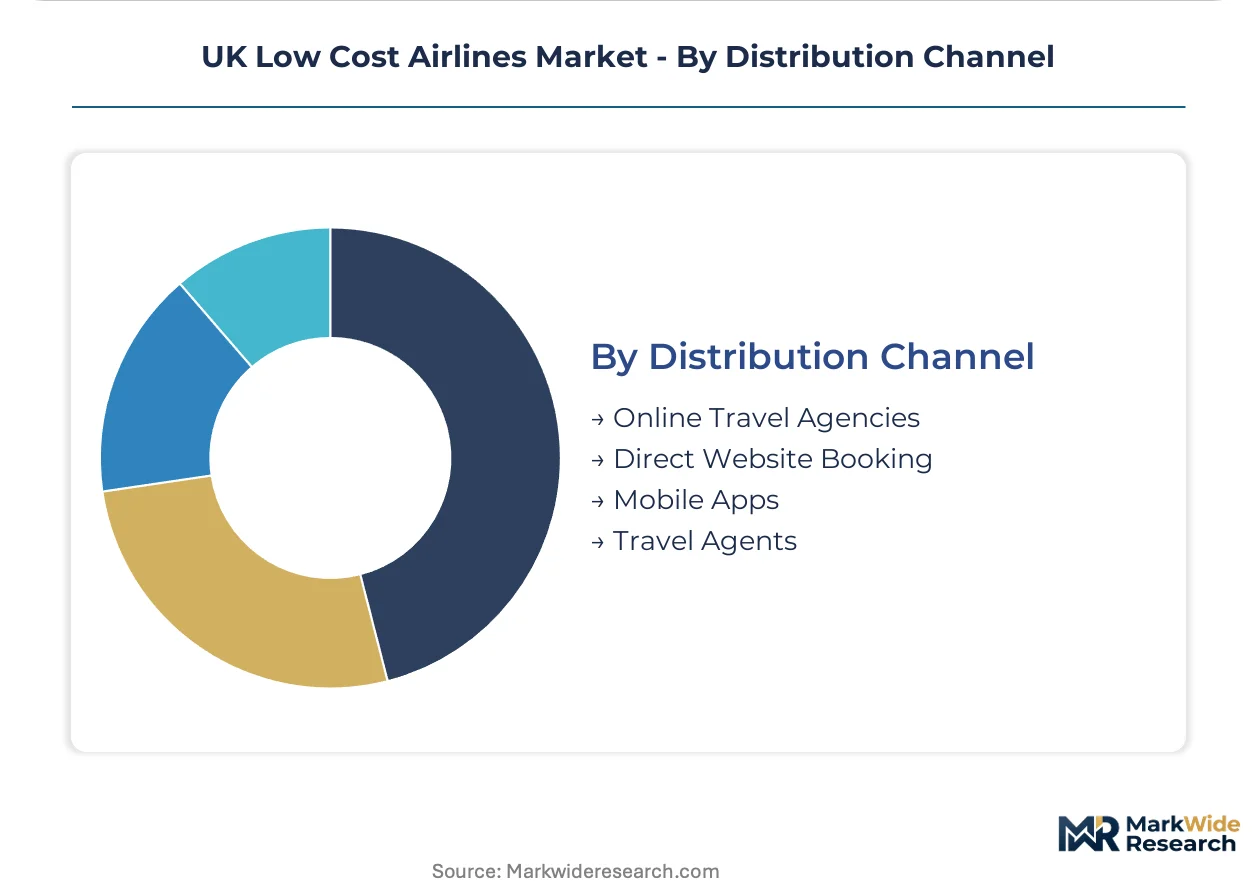
Distribution Channel:
Booking pathway economics determine customer acquisition cost and first-party data capture potential.
- Direct Website Booking:Proprietary platforms capture full fare value and enable personalized ancillary merchandising. easyJet and Jet2.com drive 70%+ of sales through owned channels to reduce commission leakage.
- Mobile Apps:Smartphone-native booking interfaces with push notification capabilities for price drop alerts and check-in prompts. Usage concentrates among under-35 demographics in London and Manchester catchments.
- Online Travel Agencies:Aggregator platforms deliver volume at 3-7% commission cost with limited customer relationship ownership.
- Travel Agents:Residual presence for package holiday bundling and complex multi-leg itineraries among older demographics.
Investment priority sits with Mobile Apps. Margin compression risk concentrates in Online Travel Agencies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise Zones across the UK Midlands and Northern Powerhouse regions are concentrating aerospace-related logistics infrastructure, drawing maintenance and crew training facilities away from London's saturated airport corridors.
London and Southeast England
Gatwick and Luton bases handle the densest European route frequencies, with easyJet and Ryanair scheduling 6-8 daily rotations to Mediterranean leisure markets. The UK Civil Aviation Authority's slot allocation reforms are tightening operational permissions at Heathrow, pushing low-cost capacity toward Stansted and Southend. The Thames Estuary logistics cluster supports rapid aircraft turnaround operations with consolidated ground handling services.
North England
Manchester Airport anchors point-to-point connectivity to secondary Spanish and Greek islands, with Jet2.com controlling seasonal capacity injection through owned holiday packaging. The Air Passenger Duty escalation on short-haul departures compresses yield recovery on domestic trunk routes to Scotland. The Trafford Park industrial zone hosts maintenance contractors serving the growing narrow-body fleet stationed at Manchester and Liverpool John Lennon.
Scotland
Edinburgh Airport captures business traffic on London corridors while expanding low-frequency summer routes to Canary Islands and Balearic destinations. Transport Scotland's route development funds are subsidizing connectivity to remote Highlands airports, though low-cost penetration remains limited by population density. The Turnhouse aerospace cluster supports line maintenance operations for carriers basing overnight aircraft.
Midlands
Birmingham Airport serves underpenetrated catchments for Eastern European city-break demand, with Wizz Air UK building frequency on Polish and Romanian routes. The West Midlands Enterprise Zone incentives are attracting aviation training academies to address pilot pipeline bottlenecks. The East Midlands Airport cargo corridor provides alternative belly-hold freight capacity when passenger load factors soften.
Wales and Northern Ireland
Cardiff and Belfast City airports operate as spoke stations with limited based aircraft, relying on seasonal charter deployment for holiday demand. The Welsh Government's aviation strategy targets aerospace manufacturing linkages rather than passenger airline growth. Belfast International maintains transatlantic narrow-body reach through Norse Atlantic UK's wet-lease operations during peak summer windows.
UK Low Cost Airlines Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the UK low-cost sector, creating a tiered structure where holiday packaging integration separates strategic archetypes. The market consolidates around three operational models: ultra-low base fare carriers stripping all included services, bundled package operators controlling vertical holiday supply chains, and hybrid players testing connection products on self-transfer itineraries. Capacity expansion through summer-only route licensing and strategic partnerships with airport authorities for long-term slot commitments dominate competitive maneuvering.
Among UK-based carriers, easyJet and Jet2.com exemplify divergent archetypes within the same regulatory environment. easyJet represents the frequency-driven, direct-distribution specialist with proprietary digital channels capturing seventy percent of sales. Jet2.com occupies the integrated tour operator position, bundling seat inventory with captive hotel supply to control margin pools across the Mediterranean. Ryanair UK, the Irish parent's British subsidiary, anchors the ultra-low-cost tier through aggressive airport-pair cost negotiations and unbundled ancillary pricing engines.
| Leading Market Players |
|---|
| easyJet |
| Ryanair |
| Jet2.com |
| Wizz Air UK |
| TUI Airways |
| Vueling |
| Ryanair UK |
| Norse Atlantic UK |
| Jet2holidays |
| Others |
Pricing and Supply Chain Analysis
Privately-owned fleet leasing specialists and sovereign wealth-backed aircraft financiers concentrate narrow-body supply channels, linking lease rate discipline to base fare floors and forcing carriers to unbundle ancillaries to recover margin.
Pricing Analysis
Margin tightening in the ultra-low base fare tier reflects Air Passenger Duty escalation on short-haul departures and jet kerosene hedging costs. Three-tier pricing structure across priority boarding, standard seat-only, and basic economy levels segments price-sensitive leisure travelers from time-sensitive business flyers. Cost-down pressure on domestic trunk routes accelerates as high-speed rail alternatives capture modal share. Backpackers and students show highest price elasticity, while corporate contract travelers on London-Edinburgh corridors accept premium tiers for flexibility.
Supply Chain Analysis
Aircraft returns and engine refurbishment flows concentrate at UK Civil Aviation Authority-approved maintenance facilities in Manchester and East Midlands, feeding secondary market lease channels. Narrow-body aircraft manufacturing draws from France, Germany, and the USA, with final assembly resting on Airbus Toulouse and Boeing Renton production lines. Engine supply sources from UK, USA, and Japan expose carriers to single-source vulnerability on next-generation powerplant availability. Distribution runs through direct carrier channels and mobile-native booking platforms to reduce online travel agency commission leakage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK Low Cost Airlines Market functions as a cost-of-compliance story where UK Civil Aviation Authority carbon reporting mandates and EU-derived SAF blending requirements create regulatory moats favoring carriers with capital reserves for fleet modernization.
For Market Incumbents: Cement slot control at London Stansted and Manchester through long-term airport use agreements before UK Civil Aviation Authority allocation reforms tighten access. Acquire captive maintenance capacity at East Midlands or Trafford Park to offset third-party MRO cost inflation. Defend against Wizz Air UK expansion on Eastern European routes by frequency-building on Polish and Romanian airport pairs. For New Entrants and Emerging Players: The price-point gap between Ryanair's ultra-low base fares and Jet2.com's bundled holiday packages opens white-space for hybrid positioning. Target Birmingham and Edinburgh catchments where point-to-point connectivity to secondary Spanish islands remains underpenetrated. Launch with self-transfer connection protection as a paid ancillary tier on thin Mediterranean routes. For Investors and Strategic Acquirers: Distressed-cycle entries favor narrow-body fleet lessors with UK AOC holdings and established slot portfolios at secondary London airports. Monitor UK Civil Aviation Authority enforcement actions on emissions non-compliance as early signals of carrier viability stress. Long-term viability hinges on sustainable aviation fuel offtake agreements and next-generation aircraft delivery positions.| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Modernization Program | Airbus A320neo and Boeing 737 MAX deliveries reduce per-seat emissions to meet UK Civil Aviation Authority mandates. |
| Direct Distribution Expansion | Mobile app investment captures first-party data from Manchester and Birmingham leisure travelers for ancillary merchandising. |
| SAF offtake Agreement | Long-term sustainable aviation fuel contracts secure compliance with EU-derived blending requirements for UK-registered carriers. |
| Secondary Base Development | Edinburgh and Belfast International capacity injection captures underserved Scottish and Northern Irish point-to-point demand. |
| Ancillary Unbundling | Dynamic pricing engines for seat selection and baggage tiers create margin pools detached from base fare competition. |
Research Methodology
Document review covered UK Civil Aviation Authority enforcement notices, Competition and Markets Authority route assessments, and airline regulatory filings, complemented by interviews with network planning directors, revenue management leads, airport slot coordinators, and sustainable aviation fuel procurement specialists. Secondary validation drew from UK Treasury Air Passenger Duty statistics, Eurocontrol delay databases, and fleet delivery tracking from manufacturer disclosure channels. Bottom-up route-level demand modeling and top-down market sizing triangulated volume estimates.
Segmentation outputs across product type, service architecture, customer segment, and distribution channel informed the analytical framework over the projection horizon. CAGRs were derived from passenger volume trajectories, fare elasticity coefficients, and ancillary attachment rate assumptions. Industry-specific inputs included jet kerosene forward curves, UK airport slot utilization rates, and sustainable aviation fuel production capacity forecasts.
Inputs from UK Civil Aviation Authority carbon disclosure registries and airline financial statements were available through the study window; gaps in real-time competitor yield data introduce uncertainty bands around fare optimization assumptions. Practitioners should monitor UK slot allocation reform timelines and National Air Traffic Services infrastructure upgrade progress for early signals of capacity constraint severity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tourist Transport Services
Travel Transportation Market
Tourist Transport Services
Yacht Rental Market
Tourist Transport Services
Airport Ground Transportation Market
Tourist Transport Services
Italy Car Rental Market
Tourist Transport Services
Southeast Asia Charter Jet Services Market
Tourist Transport Services
Helicopter Tourism Market
Tourist Transport Services
Europe Charter Jet Services Market
Tourist Transport Services
India International Express Service Market
Tourist Transport Services
Low-Cost Carrier (LCC) Market
Tourist Transport Services
Pre-Book Airport Transfer Market
Tourist Transport Services
Boat Rental Market