
 Italy Car Rental Market | 2026-2036
Italy Car Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Car Rental Market Foresight
Aftermarket fleet electrification services is reshaping competitive dynamics in the Italy car rental sector. Sixt leverages its premium positioning to capture high-margin corporate accounts in Milan and Rome. Enterprise anchors its Italian operations through extensive airport counter networks and long-term corporate partnerships. Sicily by Car specializes in regional tourism routes, dominating southern Italy's seasonal demand peaks.
Car rental denotes the short-term commercial provision of motorized vehicles to users who do not own the asset, with fleets typically comprising passenger vehicles meeting Euro 6 emissions standards and increasingly integrating battery-electric powertrains with minimum 300-kilometer range ratings. The primary purpose centers on substituting private vehicle ownership for intermittent mobility needs across tourism, business travel, and temporary transportation gaps. Economy and SUV rental types command the largest volume pools, though luxury segments extract disproportionate margin contribution from inbound tourism and executive corporate use. Online and mobile app booking channels are displacing traditional travel agency intermediation, concentrating customer acquisition investment in digital platforms and direct-to-consumer pricing control.
Italy's Ministry of Infrastructure and Transport enforces national vehicle registration and safety inspection protocols that dictate fleet turnover rates and maintenance compliance costs for rental operators. EU Green Deal emissions targets and the F-Gas Regulation on mobile air conditioning systems are accelerating fleet electrification mandates and refrigerant transition requirements. Stakeholders must monitor charging infrastructure density along major Italian highway corridors and assess whether captive fleet financing structures can absorb the capital intensity of battery-electric vehicle procurement.
Market Dynamics
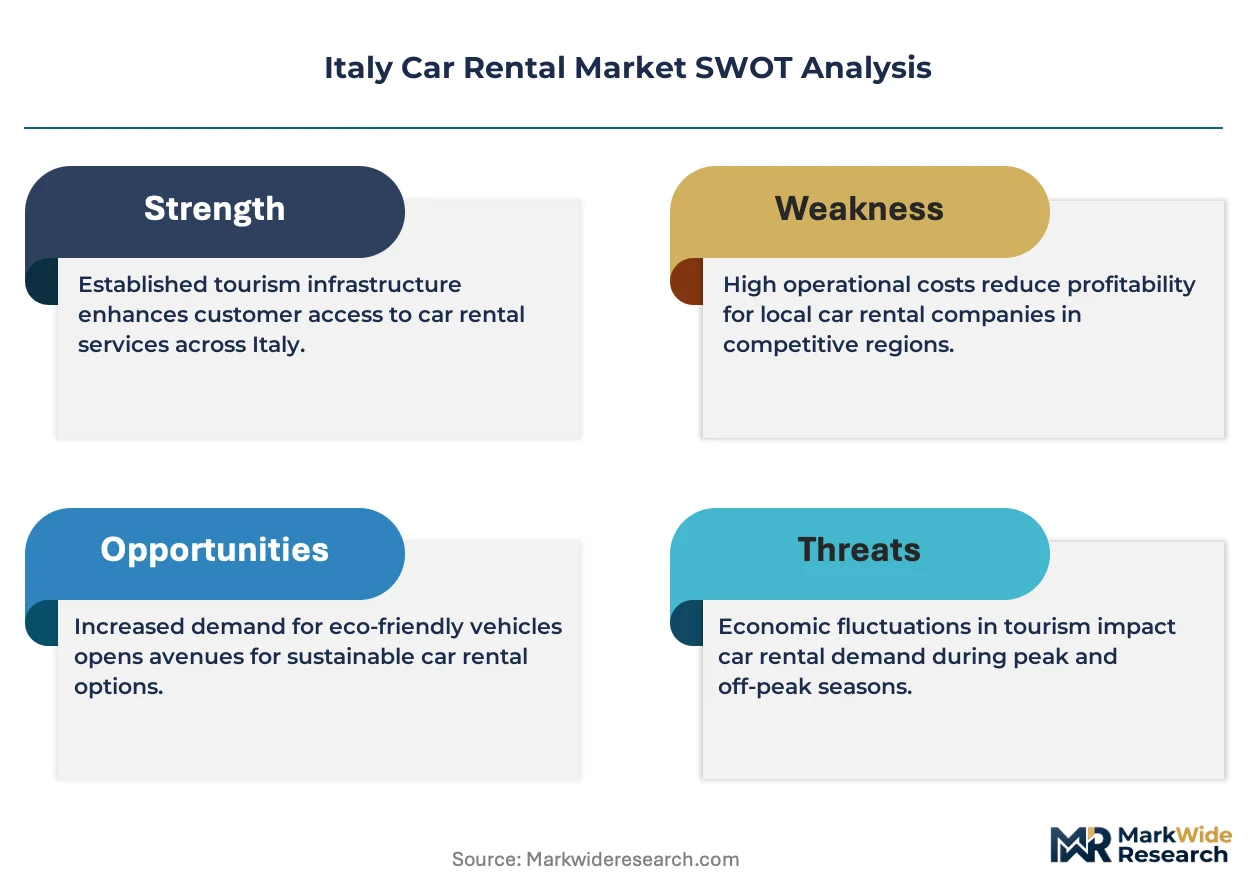
Electrification mandates under the EU Green Deal are compressing fleet turnover cycles while charging infrastructure gaps along Italian highway corridors force operators into capital-intensive asset reconfiguration decisions.
Growth Catalysts
- Mobility-as-a-Service Adoption:Italian corporate enterprises are outsourcing fleet management to rental operators, converting fixed vehicle ownership costs into variable operational expenditures.
- EU F-Gas Regulation:Mobile air conditioning refrigerant transition requirements are accelerating fleet renewal timelines and opening service revenue streams for compliant operators.
- Tourism Route Concentration:Seasonal demand peaks across Sicily, Tuscany, and the Amalfi Coast generate utilization premiums that offset winter capacity slack.
Market Restraints
- Battery-Electric Vehicle Capital Intensity:Procurement costs for 300-kilometer range EVs strain captive fleet financing structures and compress return on asset metrics.
- Charging Infrastructure Asymmetry:Northern Italy's dense fast-charging network contrasts with southern corridor gaps, constraining electrified fleet deployment flexibility.
- Ministry of Infrastructure Compliance:Safety inspection protocols and registration requirements impose fixed administrative burdens regardless of fleet size.
Strategic Opportunities
- Corporate Subscription Models:Long-term flexible leasing contracts for Milan and Rome headquartered enterprises capture recurring revenue outside volatile tourism cycles.
- High-Speed Rail Integration:Partnerships with Trenitalia at Rome Termini and Milan Centrale stations enable station-based vehicle pickup for intermodal travelers.
- EU CSRD Reporting Requirements:Scope 3 emissions disclosure mandates push enterprises toward rental partners with verified carbon accounting and electrified fleet options.
Industry Challenges
- Technician Certification Bottlenecks:High-voltage battery maintenance and diagnostics training lags behind EV fleet expansion timelines.
- Reservation System Integration:Legacy fleet management platforms require costly middleware development to sync with emerging mobility super-apps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Car Rental Market |
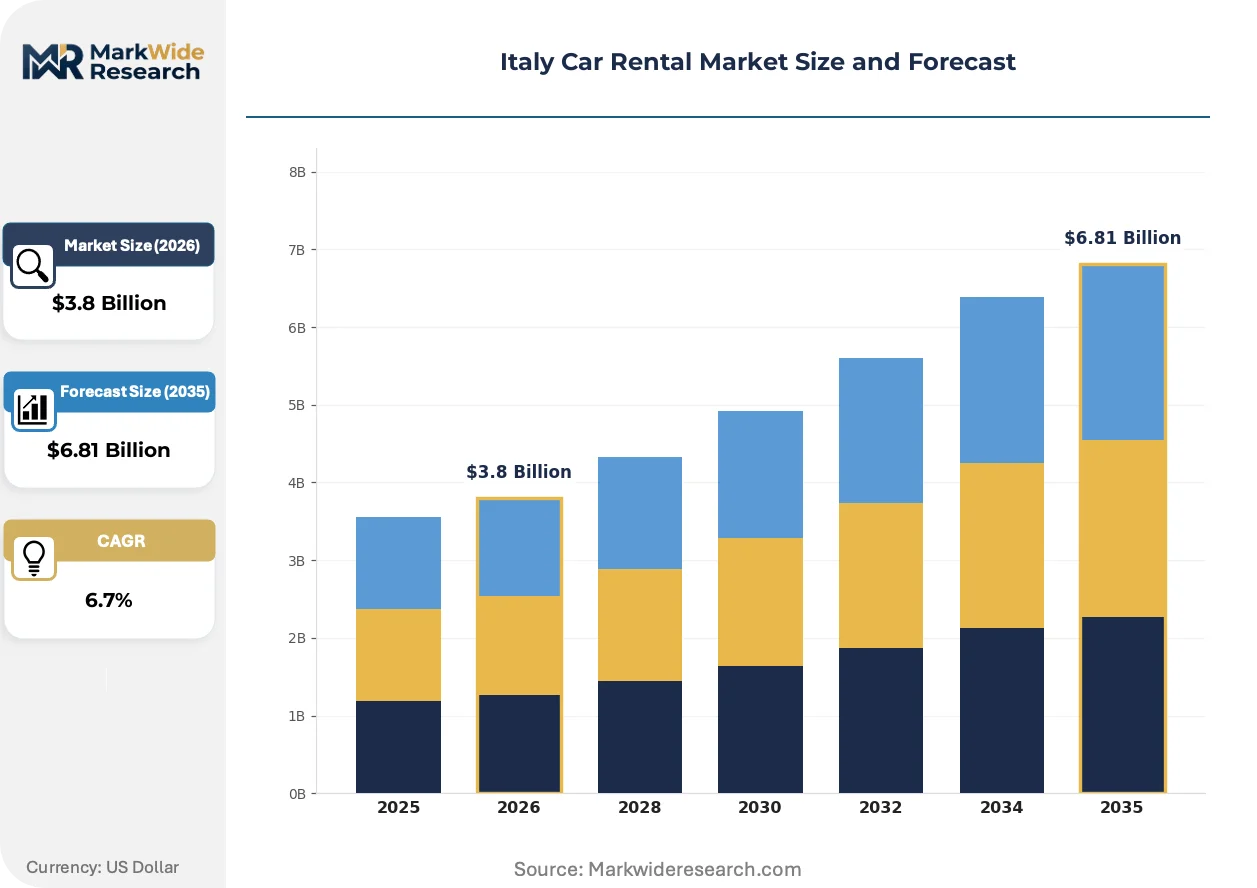
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Rental Type: Luxury, Economy, SUV, Van Booking Channel: Online, Travel Agency, Direct, Mobile App Customer Type: Tourists, Corporate, Locals, Government Duration: Short-term, Long-term, Daily, Weekly |
| Companies Covered | Sixt, Enterprise, Europcar, Sicily by Car, Maggiore, Avis, Budget, Locauto, Hertz, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Car Rental Market Shifts & Advancements
Digital booking channels are consolidating customer relationships while regulatory pressure and shifting corporate procurement norms restructure how fleet operators monetize vehicle access.
Telematics-enabled predictive maintenance is collapsing unplanned downtime costs for rental operators managing mixed ICE-EV fleets. Milan-based corporate accounts now demand real-time vehicle health dashboards as standard contract terms. This capability compression is eliminating the competitive advantage of traditional break-fix service models.
Italy's Ministry of Infrastructure enforces Euro 6 emissions standards with escalating inspection stringency that forces accelerated ICE fleet retirement. Rental operators face compressed depreciation schedules and residual value uncertainty for non-compliant vehicles. Southern Italy regional specialists are responding by front-loading EV procurement despite charging infrastructure constraints.
Corporate travel managers now mandate sustainability scoring in vendor selection criteria, displacing price-only procurement frameworks. Rental operators must document lifecycle emissions and renewable energy sourcing to retain Milan and Rome enterprise accounts. This behavioral shift is most visible in financial services and professional services verticals with public ESG commitments.
Italy Car Rental Market Segmentation
Segmentation in the Italy car rental market reveals how distinct mobility use-cases command specialized fleet configurations and pricing architectures. Operators optimize asset allocation across rental types, booking channels, customer profiles, and duration bands to capture margin premiums and minimize idle capacity.
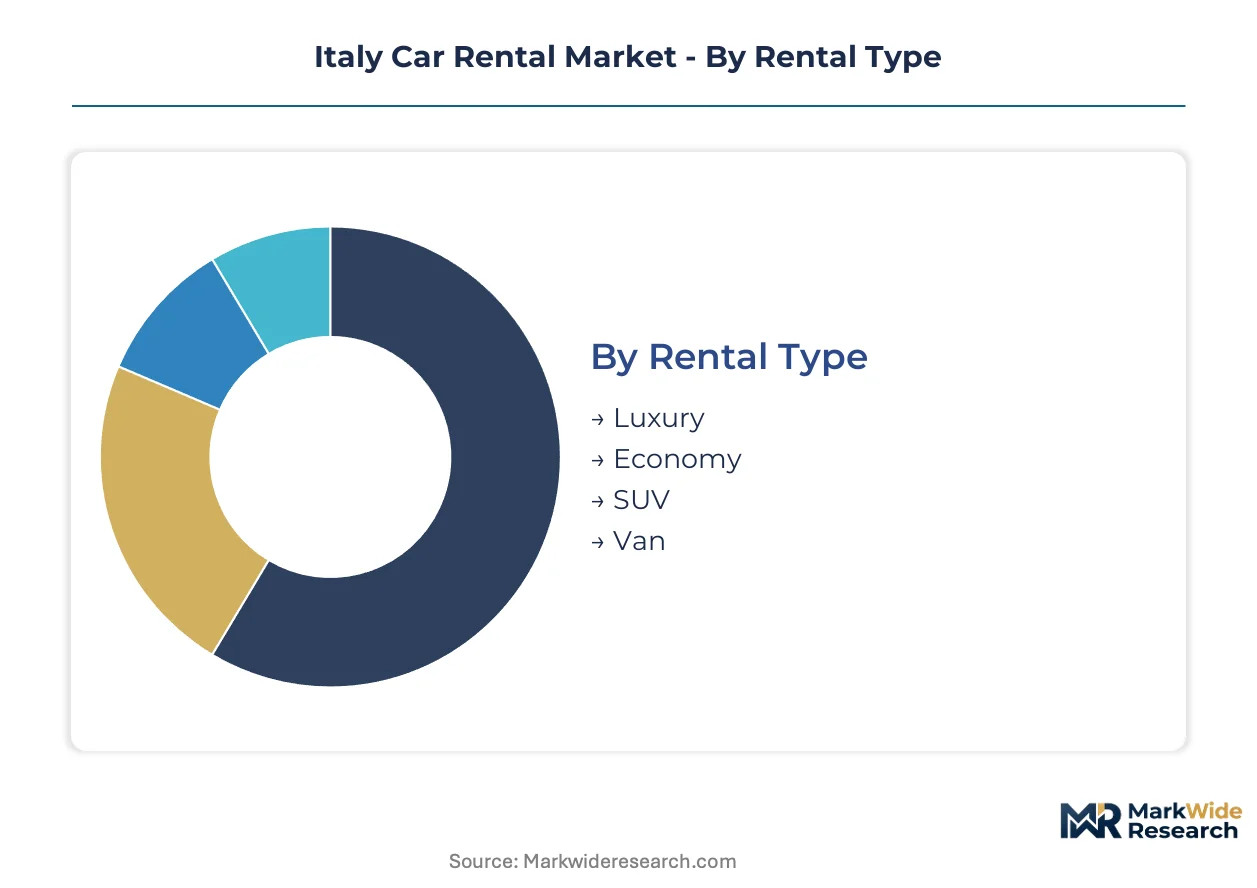
Rental Type:
Vehicle category selection tracks the full mobility spectrum from cost-conscious urban transit to premium experiential travel.
- Economy:Compact passenger vehicles with Euro 6 emissions compliance dominate urban circulation and budget tourism corridors. Rome and Milan airport counters process the highest transaction volumes in this tier, where price sensitivity from inbound European tourists compresses per-day rates.
- SUV:Elevated ride-height vehicles with expanded cargo capacity capture family tourism clusters across Tuscany and the Dolomites. Sicily by Car deploys disproportionate SUV allocation during summer peaks to serve coastal route demand where luggage capacity and all-weather capability justify rate premiums.
- Luxury:Premium marques with concierge delivery service target executive corporate accounts and high-net-worth inbound tourism. Milan's financial services district generates concentrated weekday demand for chauffeur-grade sedans with verified carbon accounting.
- Van:Multi-passenger and cargo configurations serve group tourism logistics and last-mile commercial mobility. Amalfi Coast operators utilize van fleets for wedding party transport and artisan goods distribution where road width constraints favor compact commercial vehicles.
Established volume favors Economy; emerging adoption favors SUV.
Booking Channel:
Customer acquisition pathways reflect divergent cost structures and relationship control dynamics across the Italian market.
- Online:Web-based reservation platforms with dynamic pricing engines now process the majority of leisure bookings. Direct-to-consumer interfaces enable operators to bypass travel agency commissions and capture first-party behavioral data for yield optimization.
- Mobile App:Smartphone-native booking with digital key integration and real-time fleet visibility is climbing the fastest among Milan and Rome corporate accounts. Sixt and Enterprise have prioritized app development to lock in subscription-based enterprise relationships.
- Direct:Counter and telephone reservations persist among government procurement channels and established corporate accounts with negotiated rate cards. Italy's Ministry of Infrastructure maintains direct booking protocols for official vehicle requirements.
- Travel Agency:Traditional intermediary channels retain relevance for packaged Italian tourism products targeting North American and Asian inbound markets. Commission structures here compress operator margins but deliver guaranteed volume commitments during shoulder seasons.
Volume concentrates in Online; margin protection concentrates in Direct.
Customer Type:
End-user identity determines fleet specification, contract structure, and compliance documentation requirements.
- Tourists:Inbound leisure travelers from Germany, France, and the United States generate seasonal demand spikes concentrated in Sicily, Tuscany, and Veneto. This segment accepts higher per-day rates during summer peaks but demands multilingual support and collision damage waiver clarity.
- Corporate:Enterprise fleet outsourcing contracts with Milan and Rome headquartered companies are expanding most quickly as mobility-as-a-service adoption accelerates. Financial services and professional services verticals now mandate Scope 3 emissions disclosure from rental partners.
- Locals:Domestic Italian users seeking temporary vehicle substitution during repair periods or relocation generate year-round baseline demand. This segment exhibits high price elasticity and switches between operators based on real-time availability signals.
- Government:Public administration procurement follows strict EU public tender regulations with emphasis on lifecycle cost calculations and environmental performance scoring. Fleet renewal timelines here align with EU Green Deal compliance milestones.
Revenue stability favors Corporate; rate elasticity favors Tourists.
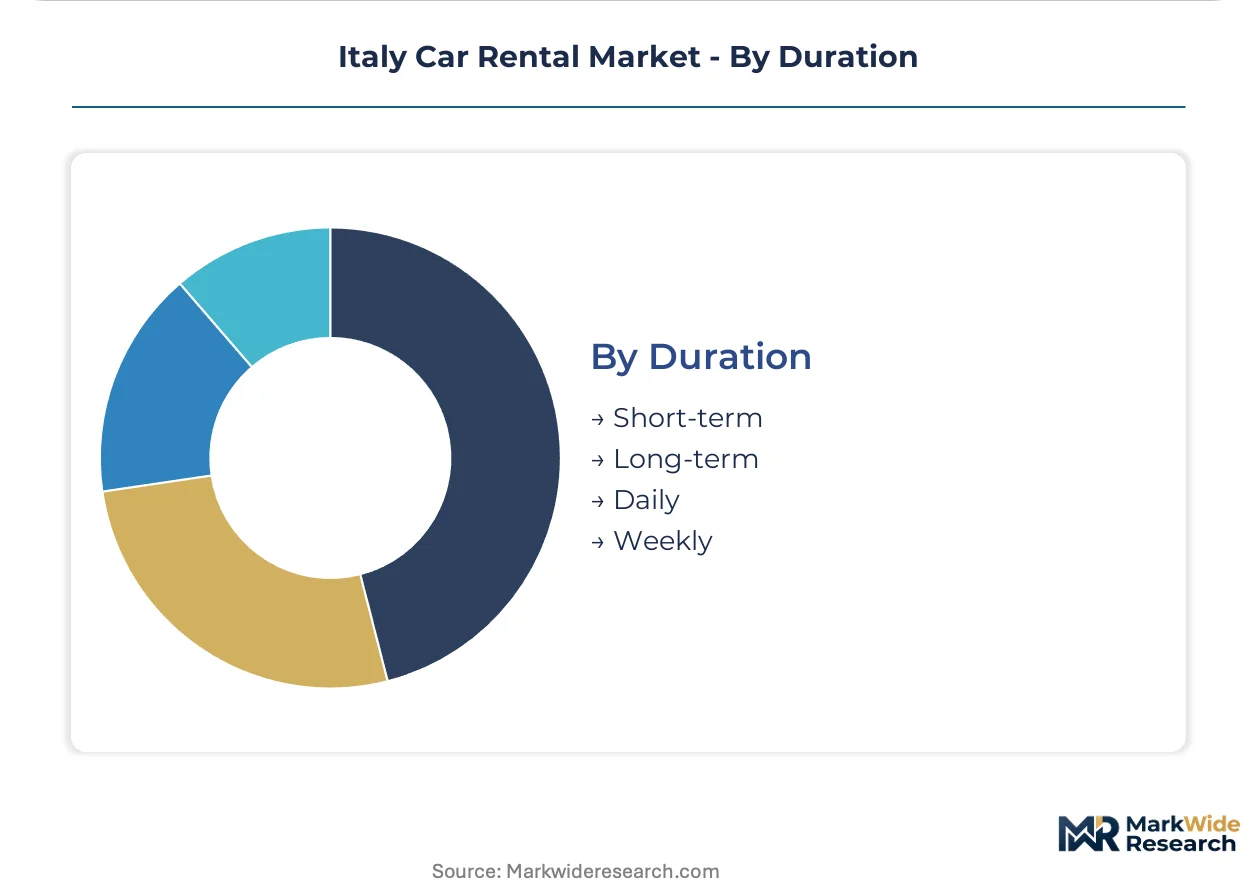
Duration:
Contract length structures capital recovery patterns and residual value risk allocation across the fleet.
- Short-term:Daily and multi-day rentals with immediate turnaround requirements dominate airport location economics. Rapid fleet rotation here demands intensive cleaning protocols and accelerated maintenance intervals to preserve asset condition.
- Long-term:Monthly and quarterly contracts with corporate subscribers provide predictable revenue streams that offset tourism seasonality. These arrangements increasingly incorporate battery-electric vehicles where charging infrastructure access can be pre-negotiated.
- Daily:Single-day urban rentals for business meetings and event logistics command premium location surcharges in Rome and Milan city centers. Operators position micro-fleets near high-speed rail terminals to capture Trenitalia intermodal travelers.
- Weekly:Seven-day blocks align with international tourism vacation patterns and offer operators yield management flexibility through bundled mileage packages. Coastal specialists in Puglia and Calabria structure weekly rates to maximize utilization during compressed summer windows.
Margin predictability favors Long-term; utilization velocity favors Daily.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Leisure tourists in southern Italy exhibit acute price sensitivity during off-peak months, while Milan corporate accounts absorb rate premiums for electrified fleet access without volume contraction.
Lombardy
Milan's financial services district drives sustained demand for luxury sedans with verified carbon accounting. EU CSRD reporting requirements push headquartered enterprises toward rental partners with Scope 3 disclosure capabilities. Bergamo and Brescia industrial zones generate mid-week corporate rotation needs.
Lazio
Rome Fiumicino airport processes the highest inbound tourism transaction volumes, concentrated in economy-class summer bookings. Italy's Ministry of Infrastructure enforces Euro 6 compliance timelines that accelerate fleet turnover for operators serving government procurement channels. Rome Termini station anchors intermodal pickup demand from Trenitalia business travelers.
Veneto
Venice Marco Polo and Verona airports capture German and Austrian leisure traffic seeking SUV configurations for Dolomite mountain routes. EU F-Gas Regulation refrigerant mandates compress maintenance intervals for operators managing mixed-age fleets. Padua's university corridor sustains academic-term long-term contracts.
Tuscany
Florence and Pisa airports serve concentrated American and British tourism clusters during April-October peaks. Charging infrastructure asymmetries constrain EV deployment flexibility along coastal routes between Livorno and Grosseto. Siena's wine tourism circuit commands premium weekly rates with bundled mileage structures.
Sicily
Palermo and Catania airports experience extreme seasonal utilization swings, with summer rates tripling winter baselines. Southern corridor charging gaps force operators into ICE fleet retention despite EU Green Deal electrification targets. Taormina and Siracusa coastal routes generate disproportionate SUV demand from family tourism segments.
Italy Car Rental Market Competitive Landscape
Premium-positioned specialists and volume-scale networks split the market into distinct competitive territories. International operators with centralized fleet procurement capabilities dominate northern Italy's corporate corridors, while regional specialists capture southern tourism peaks through localized route knowledge. Three archetypes define competitive positioning: airport-centric volume players, urban premium specialists, and seasonal regional operators. Consolidation activity concentrates on electrified fleet procurement partnerships and charging infrastructure joint ventures.
Within the premium-tier vector, Sixt occupies a position exemplifying high-margin corporate account capture through Milan and Rome city-center positioning. Enterprise anchors the airport-centric volume archetype, with extensive counter networks at Fiumicino and Malpensa supporting business travel procurement. Sicily by Car represents the seasonal regional specialist model, dominating southern Italy's compressed summer demand windows through localized fleet allocation.
| Leading Market Players |
|---|
| Sixt |
| Enterprise |
| Europcar |
| Sicily by Car |
| Maggiore |
| Avis |
| Budget |
| Locauto |
| Hertz |
| Others |
Supply & Pricing Matrix
German and Japanese OEM manufacturing concentration for premium fleet segments feeds directly into margin capture at Milan and Rome corporate counters, where verified carbon accounting commands rate premiums. Southern Italy operators absorb higher per-unit fleet costs through compressed summer pricing windows that triple winter baselines.
Pricing Analysis
After-sales revenue from collision damage waivers and fuel-service bundles drives lifetime value per rental transaction. Three-tier pricing structure across premium, standard, and economy levels stratifies by vehicle emissions certification and concierge delivery tiers. Pricing pressure stems from EV procurement cost absorption as operators front-load electrification despite residual value uncertainty. Tourist segments in Sicily and Puglia exhibit acute price sensitivity during off-peak months, while Milan financial services accounts absorb premiums without volume contraction.
Supply Chain Analysis
Contract manufacturing for telematics hardware concentrates in Taiwan and South Korea, with final vehicle assembly anchored in Germany, Spain, and Czechia. Lithium-ion battery cells draw from South Korean and Chinese suppliers, while semiconductor content for fleet management systems rests on Taiwanese foundry capacity. Single-source vulnerability in battery cell supply creates exposure to commodity price volatility for electrified fleet procurement. Distribution runs through airport counter networks and urban micro-depots with Trenitalia station integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Corporate subscription services and predictive maintenance contracts expand faster than per-day rental revenue, transforming fleet operators into mobility-as-a-service platforms with recurring revenue anchoring.
For Market Incumbents: Insulate core Milan and Rome corporate accounts by embedding real-time vehicle health dashboards as standard contract terms and accelerating technician certification for high-voltage battery diagnostics. Vertical integration into captive charging infrastructure at high-speed rail terminals defends against mobility super-app disintermediation. For New Entrants and Emerging Players: Southern Italy's seasonal tourism corridors with charging infrastructure gaps represent the most penetrable entry point for ICE fleet specialists capturing summer rate premiums. Government procurement channels following EU Green Deal compliance milestones offer contracted volume with environmental performance scoring as the go-to-market angle. For Investors and Strategic Acquirers: Capital is best deployed toward regional specialists with localized route knowledge and established seasonal utilization patterns across Sicily and Puglia. Long-term viability hinges on electrified fleet transition timelines aligned with EU CSRD disclosure mandates. Watch charging infrastructure density along A1 and A14 highway corridors as the inflection signal for EV deployment scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Charging Infrastructure Partnership | Trenitalia station integration at Rome Termini and Milan Centrale captures intermodal travelers. |
| Predictive Maintenance Platform | Telematics-enabled health dashboards collapse unplanned downtime for mixed ICE-EV fleets. |
| Corporate Subscription Model | Long-term flexible contracts with Milan financial services firms offset tourism seasonality. |
| Technician Certification Program | High-voltage battery diagnostics training closes the gap behind EV fleet expansion timelines. |
| Mobility Super-App Integration | API middleware development syncs legacy fleet management with emerging booking platforms. |
Research Methodology
A spread of perspectives from fleet operations directors, corporate travel procurement managers, charging infrastructure developers, and EU regulatory affairs specialists converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against Italy's Ministry of Infrastructure registration databases, EU F-Gas Regulation compliance filings, Trenitalia passenger flow statistics, and customs data on vehicle import volumes. Bottom-up fleet size estimates and top-down tourism expenditure patterns were triangulated to anchor market sizing.
Demand-supply balance modeling tracked vehicle deployment against utilization rates across the projection horizon. Segmentation dimensions included rental type, booking channel, customer profile, and contract duration band, with regional charging infrastructure density as an industry-specific overlay. CAGRs were derived from trend extrapolation of fleet turnover cycles and electrification mandate compliance timelines, incorporating corporate mobility-as-a-service adoption curves and seasonal tourism pattern shifts.
Stress conditions across battery cell supply disruptions, Euro 7 emissions standard acceleration, and charging infrastructure buildout delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about EU Green Deal implementation pacing and corporate ESG procurement behavioral shifts. Cross-checking against ISTAT tourism arrival statistics and ANFIA vehicle registration data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tourist Transport Services
Airport Ground Transportation Market
Tourist Transport Services
Pre-Book Airport Transfer Market
Tourist Transport Services
Europe Charter Jet Services Market
Tourist Transport Services
Low-Cost Carrier (LCC) Market
Tourist Transport Services
Southeast Asia Charter Jet Services Market
Tourist Transport Services
Travel Transportation Market
Tourist Transport Services
Helicopter Tourism Market
Tourist Transport Services
Boat Rental Market
Tourist Transport Services
Yacht Rental Market
Tourist Transport Services
UK Low Cost Airlines Market
Tourist Transport Services
India International Express Service Market