
 Travel Transportation Market | 2026-2036
Travel Transportation Market Size, Share, and Industry Trends Forecast 2026-2036
Travel Transportation Market Outlook
The Travel Transportation Market is pivoting between premium experiential offerings and commoditized point-to-point transit. Delta Air Lines Inc. dominates transatlantic premium cabin yields through its joint venture network control. Booking Holdings Inc. leverages its agency model to capture commission pools across independent hotel and alternative lodging inventory. Uber Technologies Inc. extends ground transport integration into airport-centric multimodal booking flows.
Travel transportation encompasses the commercial movement of passengers across air, rail, road, and waterborne modes utilizing scheduled and on-demand service architectures with capacity measured in available seat-miles or passenger-kilometers. The sector functions through yield management systems optimizing load factors against fixed route infrastructure and variable fuel or energy inputs. Airlines within the service type dimension sustain the largest revenue pool but face margin compression from crew and maintenance cost inflation. Online travel agencies in the booking channel dimension capture disproportionate growth as mobile-first booking behavior displaces legacy agent networks. The price tier dimension shows luxury and premium segments recovering faster than budget tiers in long-haul international markets.
The FAA governs U.S. air carrier certification and operational safety standards while the EU Green Deal's Fit for 55 package imposes sustainable aviation fuel blending mandates on European operators. China's MIIT coordinates high-speed rail capacity allocation with NMPA oversight of cross-border health protocols for international arrivals. Stakeholders must monitor regulatory divergence between carbon border adjustments and open-skies agreement renegotiations as these frameworks reshape route economics and fleet deployment priorities.
Market Dynamics
The EU Green Deal's emissions trading scheme is forcing aviation fleet renewal decisions while China's high-speed rail expansion captures intercity passenger volumes from regional carriers. These dual pressures are compressing route economics and reshaping multimodal investment priorities across operators.
Growth Catalysts
- Sustainable Aviation Fuel Mandates:The EU Green Deal's Fit for 55 package requires progressive SAF blending, driving refinery capacity expansion and long-term offtake agreements between carriers and biofuel producers.
- Corporate Travel Program Expansion:Post-pandemic normalization of business mobility is restoring managed travel volumes, particularly in transatlantic and Asia-Pacific corridors where premium cabin yields sustain network economics.
- High-Speed Rail Network Density:China's MIIT-coordinated rail expansion is creating integrated intercity transit options that compete directly with short-haul aviation on routes under 800 kilometers.
Market Restraints
- Jet Fuel Price Volatility:Crude oil input costs and refining capacity constraints create margin unpredictability for carriers lacking hedging sophistication or long-term supply contracts.
- Pilot and Maintenance Crew Scarcity:Training pipeline bottlenecks and demographic retirements are constraining fleet utilization rates, particularly for regional operators with limited training infrastructure.
- Airport Slot Concentration:Hub capacity limits at London Heathrow, Frankfurt, and Amsterdam Schiphol restrict network expansion for new market entrants and secondary carriers.
Strategic Opportunities
- India's Aviation Market Liberalization: DGFT export incentives and airport privatization are opening routes for low-cost carriers to capture first-time flyers in tier-two and tier-three cities.
- Multimodal Booking Integration:Ground transport operators are embedding rail, rideshare, and micro-mobility options into unified itinerary platforms, capturing ancillary revenue beyond core segments.
- Carbon Border Adjustment Mechanisms:The EU's CBAM framework for aviation is creating competitive advantage for carriers with early fleet renewal and verified emissions reporting capabilities.
Industry Challenges
- Aircraft Delivery Backlog Management:OEM production constraints and supply chain disruptions are extending fleet modernization timelines, forcing operators to retain less efficient older aircraft.
- Legacy Reservation System Migration:Mainframe-dependent carriers face integration complexity when adopting cloud-native retailing platforms and dynamic pricing engines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Travel Transportation Market |
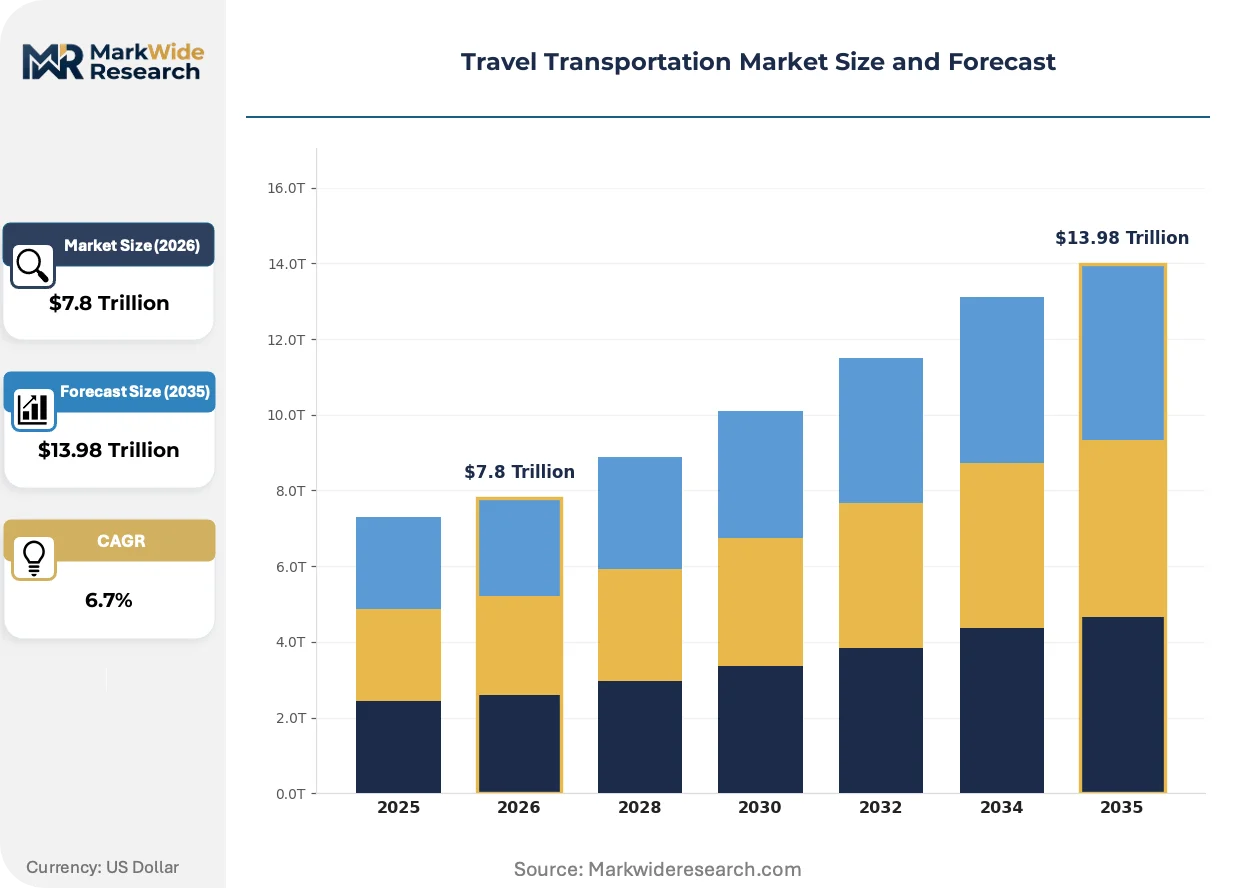
| Market Size in 2026 | $7.8 Trillion |
| Market Size in 2035 | $13.98 Trillion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Airlines, Railways, Bus Services, Car Rentals Customer Type: Business Travelers, Leisure Tourists, Group Travellers, Solo Adventurers Booking Channel: Online Travel Agencies, Direct Website Booking, Travel Agents, Mobile Apps Price Tier: Budget, Mid-Range, Luxury, Premium |
| Companies Covered | Booking Holdings Inc., Expedia Group Inc., Airbnb Inc., Trip.com Group, Uber Technologies Inc., Delta Air Lines Inc., United Airlines Holdings Inc., American Airlines Group Inc., Internova Travel Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Travel Transportation Market Strategic Shifts
Digitization of revenue management and propulsion technology diversification are compressing traditional competitive moats. Operators must now integrate real-time demand signals with sustainability compliance across multimodal networks.
Electric and hydrogen propulsion architectures are modularizing regional aircraft design, enabling swapable powertrain configurations that adapt to route-specific range and payload requirements. Scandinavian carriers and island-hopping operators in Greece and Indonesia are piloting these platforms for sub-500 kilometer sectors. This modularizing approach is compressing the traditional 20-year fleet replacement cycle into accelerated technology refresh timelines.
The EU Green Deal's Fit for 55 sustainable aviation fuel blending mandate is restructuring refinery investment across European energy majors. Industrial consequence includes binding offtake agreements that lock carriers into decade-long supply contracts at indexed pricing. Long-haul international operators with European hub exposure are responding by securing dedicated SAF production capacity through equity stakes in biorefinery projects.
Mobile-first itinerary management is displacing desktop-based corporate booking tools, with procurement authority shifting to individual travelers armed with real-time price transparency. Travel management companies are unbundling their service stacks to compete with direct supplier apps. This behavioral shift is most visible in the United States and United Kingdom, where corporate policy flexibility and expense automation adoption outpace continental European control frameworks.
Travel Transportation Market Segmentation
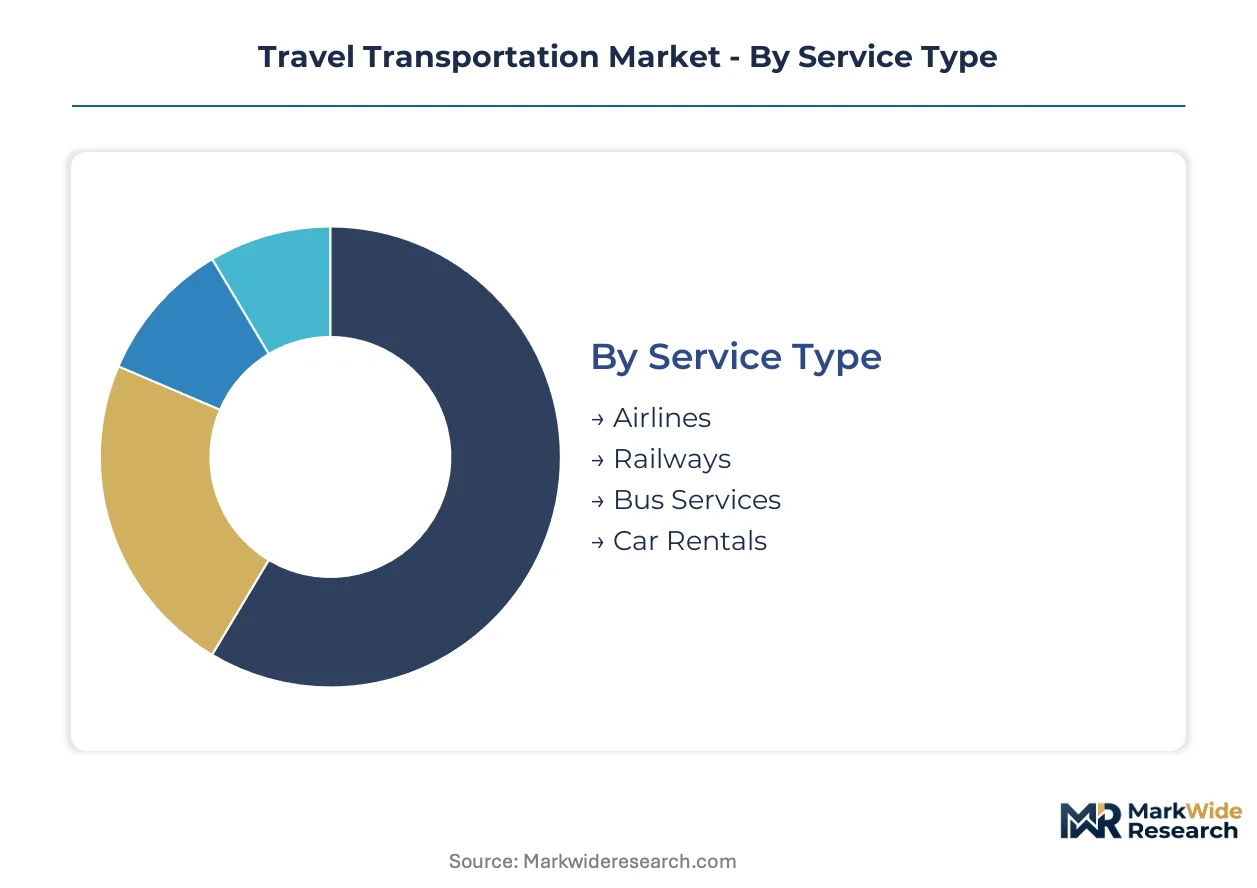
Travel transportation segmentation reveals how yield management systems, distribution economics, and passenger behavior patterns fragment across operational models. Understanding these dimensions exposes where margin pools concentrate and where technology disruption is reordering competitive hierarchies.
Service Type:
Propulsion architecture and infrastructure requirements create distinct capital intensity profiles across mobility modes.
- Airlines:Fixed-wing operators utilize jet and turboprop platforms with route economics governed by fuel hedging sophistication and slot-controlled hub access. Long-haul international carriers at London Heathrow and Frankfurt sustain premium cabin yields through joint venture network density, while regional operators face crew scarcity constraints on fleet utilization.
- Railways:Steel-wheel infrastructure delivers point-to-point capacity with electrification status determining carbon exposure under EU emissions trading schemes. China's MIIT-coordinated high-speed corridors capture intercity volumes under 800 kilometers through integrated station connectivity and frequency advantages.
- Bus Services:Intercity coach operators deploy variable-capacity fleets with lower fixed cost structures than rail or air competitors. Demand concentrates on price-sensitive corridors where highway density supports competitive journey times.
- Car Rentals:Asset-heavy fleet operators balance utilization rates against residual value risk on vehicle portfolios. Airport-centric location strategies capture inbound traveler volumes with ancillary insurance and fuel products padding transaction economics.
Mature deployment sits with Airlines. Newer deployment is concentrated in Railways.
Customer Type:
Trip purpose dictates booking lead times, cancellation flexibility requirements, and ancillary service attachment rates.
- Business Travelers:Corporate policy compliance and expense automation integration drive platform selection. Transatlantic and Asia-Pacific corridor demand restores premium cabin yields as managed travel programs normalize post-pandemic mobility.
- Leisure Tourists:Price elasticity and package bundling sensitivity characterize vacation passenger economics. Mobile-first itinerary management displaces desktop booking tools as individual travelers gain real-time price transparency.
- Group Travellers:Block booking negotiations and coordination complexity favor direct supplier relationships over intermediary channels. Educational and incentive segments show divergent seasonality patterns.
- Solo Adventurers:Experience-seeking behavior prioritizes destination authenticity over transport mode efficiency. Alternative lodging integration and micro-mobility connectivity shape platform loyalty.
Volume leadership rests with Leisure Tourists. Steepest expansion trajectory belongs to Solo Adventurers.
Booking Channel:
Distribution technology stacks determine customer acquisition costs and data ownership positions.
- Online Travel Agencies:Aggregator platforms capture commission pools across fragmented supplier bases through metasearch price transparency. Agency model economics favor inventory breadth over direct supplier rate parity.
- Direct Website Booking:Supplier-controlled channels eliminate intermediary fees while enabling loyalty program enrollment and ancillary upsell. Carriers with robust CRM infrastructure monetize repeat purchase behavior.
- Travel Agents:Human-advised booking retains relevance in complex multi-leg itineraries and corporate policy navigation. Legacy agent networks contract as mobile-first behavior displaces traditional intermediation.
- Mobile Apps:Native platform engagement enables push-notification pricing and real-time disruption management. Ground transport operators embed multimodal options into unified itinerary flows through API integration.
Platform investment concentrates in Mobile Apps. Infrastructure legacy burdens Travel Agents.
Price Tier:
Cabin class and service level stratification aligns with passenger willingness-to-pay and trip purpose segmentation.
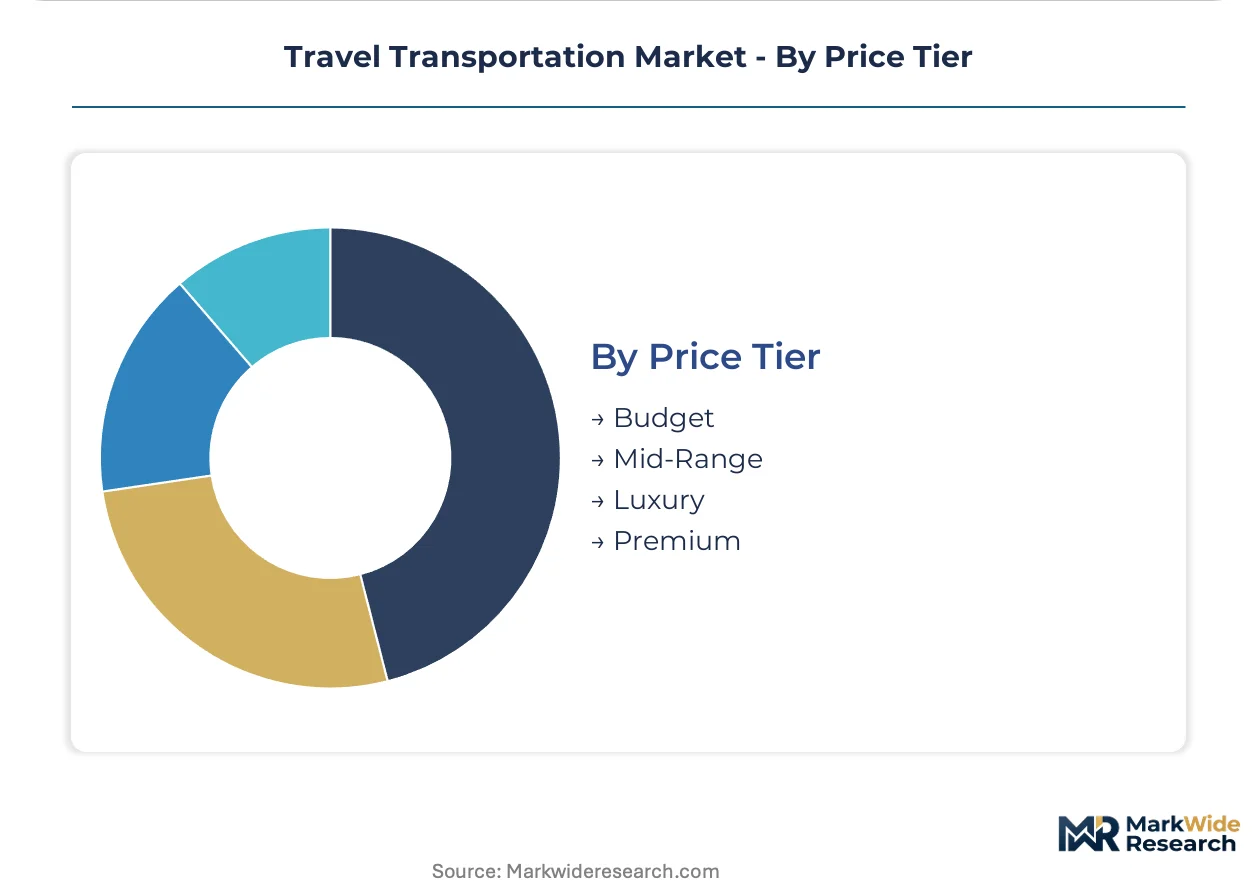
- Budget:Unbundled fare structures separate seat selection, baggage, and refreshments from base ticket prices. Low-cost carriers in India's tier-two and tier-three cities capture first-time flyers through DGFT export incentive-supported route expansion.
- Mid-Range:Partial service inclusion balances price sensitivity with predictable travel experience. This tier shows compression as premium economy products encroach from above and budget operators improve reliability from below.
- Luxury:Concierge-level service and exclusive lounge access command yield multiples over standard offerings. Long-haul international markets show faster recovery than budget tiers as experiential travel prioritization persists.
- Premium:Lie-flat seating and enhanced dining define competitive positioning on competitive routes. Joint venture network control at Delta sustains transatlantic yield premiums through coordinated capacity management.
Yield recovery leads in Premium. Volume concentration sits with Budget.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai anchors the densest multimodal transport corridor globally, where Pudong International Airport interfaces with China's high-speed rail spine to capture intercity passenger flows under 800 kilometers.
United States
Corporate travel normalization and premium cabin yield recovery drive transatlantic network economics. The FAA governs air carrier certification and operational safety standards for domestic and international operations. Dallas-Fort Worth and Atlanta Hartsfield-Jackson concentrate hub capacity where joint venture networks coordinate capacity management.
China
High-speed rail expansion captures regional aviation volumes through MIIT-coordinated corridor development and integrated station connectivity. NMPA oversight of cross-border health protocols shapes international arrival processing. The Yangtze River Delta cluster around Shanghai Hongqiao demonstrates multimodal integration between air and rail platforms.
Germany
EU Green Deal emissions trading accelerates fleet renewal investments across Lufthansa Group operations. The Fit for 55 package imposes sustainable aviation fuel blending mandates on European operators. Frankfurt Airport slot concentration restricts network expansion for secondary carriers competing on transatlantic routes.
India
DGFT export incentives and airport privatization open routes for low-cost carriers targeting first-time flyers in tier-two and tier-three cities. The PLI scheme supports aviation manufacturing and MRO infrastructure development. Mumbai and Delhi-NCR concentrate international gateway capacity where IndiGo and Air India compete for domestic market share.
United Kingdom
Heathrow slot scarcity constrains network growth for new market entrants competing against established joint venture alliances. The UK Civil Aviation Authority implements post-Brexit regulatory divergence from EU frameworks. London's five-airport system fragments demand across Gatwick, Stansted, Luton, and City alternatives to Heathrow's hub dominance.
Travel Transportation Market Competitive Environment
Premium-margin players sit above commodity-margin players across yield management sophistication and network control dimensions. The market structure consolidates around three carrier archetypes: full-service network airlines with joint venture dominance, low-cost point-to-point operators, and platform-based intermediaries capturing commission pools. Strategic moves concentrate on multimodal booking integration and sustainable aviation fuel offtake agreements securing decade-long supply contracts.
Among US-based network carriers, Delta Air Lines Inc. and United Airlines Holdings Inc. exemplify full-service operators leveraging joint venture structures for transatlantic yield premiums. Booking Holdings Inc. anchors the intermediary archetype through agency model economics capturing fragmented hotel and alternative lodging inventory. These three entities represent distinct competitive positions: network control through hub concentration, platform aggregation across supplier bases, and yield optimization through premium cabin segmentation.
| Leading Market Players |
|---|
| Booking Holdings Inc. |
| Expedia Group Inc. |
| Airbnb Inc. |
| Trip.com Group |
| Uber Technologies Inc. |
| Delta Air Lines Inc. |
| United Airlines Holdings Inc. |
| American Airlines Group Inc. |
| Internova Travel Group |
| Others |
Value Chain & Pricing Dynamics
Corporate travel managers consolidating managed travel program volumes command preferential contract rates through annual minimum spend commitments, anchoring negotiated yield structures across carrier networks. This buyer concentration reinforces value-based pricing tied to passenger throughput guarantees rather than spot-market seat availability.
Pricing Analysis
Yield-per-available-seat-mile serves as the dominant value-based pricing anchor across airline operations. Three-tier pricing structure across premium, standard, and economy levels segments passengers by willingness-to-pay and trip purpose flexibility. Price differentiation hinges on cabin class amenities and advance purchase commitment windows. Pricing pressure stems from low-cost carrier capacity additions on short-haul routes. Leisure tourists exhibit highest price sensitivity, while corporate travelers locked into managed travel contracts show lowest elasticity.
Supply Chain Analysis
India's PLI scheme and China's MIIT localization mandates are reshaping aircraft component sourcing toward domestic manufacturing hubs. Aerospace supply chains draw from the United States, France, and China for engines, avionics, and airframe assemblies. Jet fuel refining, lithium-ion battery cells, and composite materials constitute critical input dependencies. Single-source vulnerability concentrates in engine OEM duopoly structures. Distribution runs through hub-and-spoke airport networks with coordinated ground handling partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
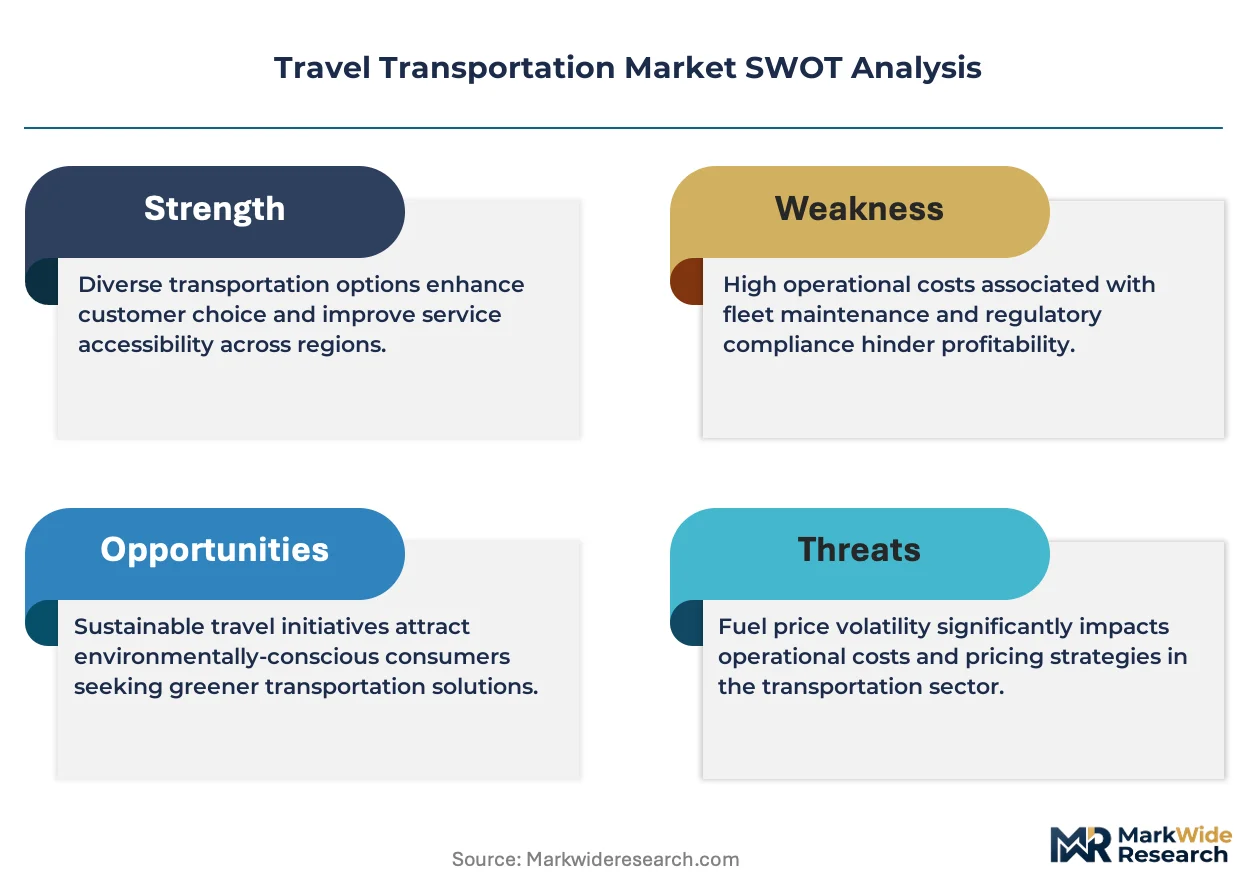
The EU Green Deal's Fit for 55 package functions as a cost-of-compliance moat, elevating capital requirements for sustainable aviation fuel infrastructure and carbon reporting systems that disadvantage undercapitalized competitors.
For Market Incumbents: Hedge fuel cost exposure through long-term sustainable aviation fuel offtake agreements with European biorefinery projects. Secure slot-controlled hub capacity at London Heathrow and Frankfurt against new entrant encroachment. Crew training pipeline investments address pilot scarcity constraining fleet utilization rates. For New Entrants and Emerging Players: Mobile-first booking platforms offer the lowest customer acquisition cost route for unbundled fare products targeting price-sensitive leisure segments. India's tier-two and tier-three city routes present penetrable white-space with DGFT export incentive support. Pursue asset-light partnership models with existing ground handlers to bypass airport slot concentration barriers. For Investors and Strategic Acquirers: The window for entry favors carriers with verified emissions reporting capabilities and early SAF supply contracts ahead of EU Green Deal enforcement acceleration. Long-term viability centers on fleet modernization trajectories aligned with propulsion technology diversification. Monitor aircraft delivery backlog resolution at OEMs as fleet renewal inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Sustainable Aviation Fuel Offtake Agreement | Binding decade-long contracts with European biorefineries lock in carbon-compliant supply under EU Green Deal mandates. |
| Multimodal Booking Platform Integration | API connectivity with high-speed rail and rideshare operators captures ancillary revenue beyond core air segments. |
| Hub Slot Portfolio Expansion | Concentrated capacity at Heathrow and Frankfurt sustains joint venture yield premiums through coordinated network control. |
| Electric-Hydrogen Propulsion Pilot Program | Scandinavian and Greek island route trials validate modular powertrain architectures for sub-500 kilometer sectors. |
| Corporate Travel Management Company Acquisition | Direct access to managed travel program volumes reduces intermediary commission burdens and improves yield visibility. |
Study Parameters
Document review covered carrier financial disclosures, EU ETS regulatory filings, and MIIT infrastructure planning documents, complemented by interviews with airline network planning executives, corporate travel procurement managers, sustainable aviation fuel procurement leads, and airport slot coordination officers. Secondary validation drew from FAA operational statistics, IEA energy transition databases, and customs trade flow records. Bottom-up route-level demand modeling triangulated against top-down macroeconomic travel elasticity assumptions.
Segmentation outputs across service type, customer type, booking channel, and price tier dimensions were projected across the analysis window using elasticity-adjusted passenger volume trajectories. CAGRs were derived from historical yield management system data and forward capacity deployment schedules. Forecast inputs incorporated jet fuel price scenarios, crew training pipeline throughput estimates, and high-speed rail corridor completion timelines.
The model holds under stable regulatory enforcement timelines and OEM delivery schedule normalization; deviation in carbon border adjustment acceleration or sustained supply chain disruptions would shift fleet renewal trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tourist Transport Services
India International Express Service Market
Tourist Transport Services
Europe Charter Jet Services Market
Tourist Transport Services
UK Low Cost Airlines Market
Tourist Transport Services
Pre-Book Airport Transfer Market
Tourist Transport Services
Italy Car Rental Market
Tourist Transport Services
Airport Ground Transportation Market
Tourist Transport Services
Boat Rental Market
Tourist Transport Services
Southeast Asia Charter Jet Services Market
Tourist Transport Services
Helicopter Tourism Market
Tourist Transport Services
Low-Cost Carrier (LCC) Market
Tourist Transport Services
Yacht Rental Market