
 India International Express Service Market | 2026-2036
India International Express Service Market Size, Share, and Industry Trends Forecast 2026-2036
India International Express Service Market Insights
Pharmaceutical and electronics exports from India is shifting toward time-definite international delivery, pulling express carriers into specialized cold-chain and high-value handling lanes. DHL Group leverages its Mumbai hub and temperature-controlled infrastructure to dominate pharmaceutical outbound flows. FedEx sustains competitive frequency on India-US lanes through its Delhi gateway operations. Blue Dart Express anchors domestic last-mile density that feeds international consolidation points in Bengaluru and Hyderabad.
India international express service encompasses time-definite cross-border parcel and document movement with customs brokerage, typically operating on 24-96 hour transit commitments with automated manifest filing and duty pre-payment mechanisms. The primary commercial purpose is enabling Indian manufacturers and digital merchants to meet delivery windows in distant markets without holding overseas inventory. Expedited shipping commands premium pricing on electronics and pharmaceutical lanes where stockout costs exceed freight multiples. B2C and e-commerce customer types are expanding fastest as direct-to-consumer platforms bypass traditional distributor networks. Door-to-door delivery models capture margin pools by embedding customs clearance and final-mile handoff within a single rate.
DGFT export documentation rules, RBI outward remittance frameworks, and BIS packaging standards collectively shape service design and cost structures for Indian express operators. CDSCO pharmaceutical export certifications and Customs ICEGATE digital filing mandates determine which carriers qualify for regulated product lanes. Stakeholders must monitor evolving FEMA remittance thresholds and emerging state-level logistics policies as these will determine hub location economics and cross-border compliance costs.
Market Dynamics
The Customs Automated Clearance System is compressing export documentation timelines from days to hours, forcing express carriers to reconfigure hub operations around pre-arrival manifest filing rather than post-arrival clearance workflows.
Growth Catalysts
- PLI scheme for logistics:Production-linked incentives for warehousing and cold-chain infrastructure are lowering capital barriers for temperature-controlled express lanes serving pharmaceutical exporters.
- E-commerce merchants:Tier-two Indian cities are generating cross-border parcel volumes through direct-to-consumer platforms that bypass traditional distributor networks entirely.
- CDSCO pharmaceutical export certifications:Streamlined drug regulator approvals for time-definite cold-chain shipments are opening regulated product lanes to qualified express operators.
Market Restraints
- Fuel cost volatility:Aviation turbine fuel represents 35-40% of operating costs for air express carriers, with rupee-dollar fluctuations amplifying pricing instability on international lanes.
- ICEGATE digital filing mandates:Mandatory pre-shipment data requirements create compliance friction for smaller freight forwarders lacking integrated ERP-to-customs connectivity.
- Road infrastructure gaps:Last-mile connectivity from Bengaluru and Hyderabad consolidation points to interior manufacturing clusters remains inconsistent, constraining pickup reliability.
Strategic Opportunities
- Delhi-NCR freight cluster expansion:Underutilized cargo capacity at Indira Gandhi International Airport's dedicated freight terminal offers landing rights for new international carriers.
- Electronics reverse logistics:Warranty return flows from Gulf Cooperation Council markets to Indian repair hubs represent an underserved lane with premium yield potential.
- DGFT export documentation automation:Integration of shipping bills with ICEGATE creates white space for carriers offering embedded customs brokerage as a bundled service.
Industry Challenges
- Temperature certification timelines:CDSCO validation of cold-chain packaging for pharmaceutical lanes requires 12-18 month qualification cycles that delay service launches.
- Legacy customs broker integration:Smaller exporters in the Mumbai-Pune corridor rely on paper-based documentation workflows that resist digitization without operational disruption.
- Specialized handling workforce scarcity:Qualified personnel for lithium battery classification and dangerous goods packaging remain concentrated with incumbent carriers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India International Express Service Market |
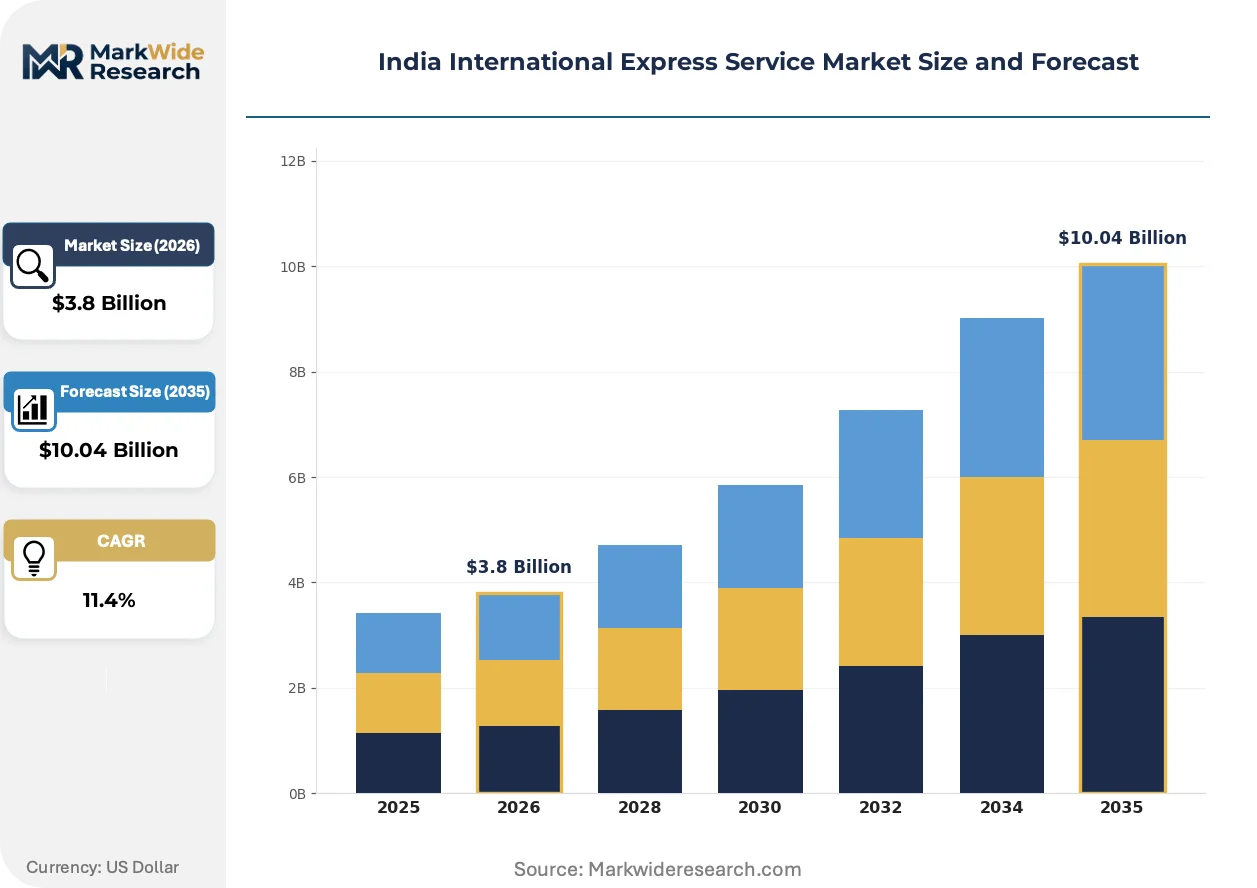
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Standard Shipping, Expedited Shipping, Same-Day Delivery, Cash on Delivery Customer Type: B2B, B2C, E-Commerce, Government Delivery Model: Door-to-Door, Hub-and-Spoke, Fulfillment Center, Cross-Border Weight Category: Documents, Light Packages, Heavy Packages, Oversized Items |
| Companies Covered | DHL Group, FedEx, United Parcel Service of America Inc (UPS), Blue Dart Express, Delhivery Limited, DTDC Express Limited, Gati Express & Supply Chain Private Limited, Transport Corporation of India Limited (TCI), Aramex, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India International Express Service Market Trends and Innovations
Express service architecture is fragmenting from monolithic hub-and-spoke models toward distributed micro-fulfillment networks that position inventory closer to export gateways before customs release.
Blockchain-enabled manifest sharing is modularizing the documentation chain between shippers, carriers, and customs authorities. Pharmaceutical exporters in Hyderabad are piloting distributed ledger integration for temperature integrity verification. This technology is modularizing compliance workflows into interoperable components that reduce single-point failure risk during multi-party handoffs.
BIS packaging standards for cross-border e-commerce are mandating QR-code traceability and dimensional weight accuracy. The regulation forces express operators to retrofit sorting equipment with automated dimensioning systems. Electronics exporters to Gulf markets face the tightest compliance windows, driving carrier investment in pre-sort verification tunnels at Bengaluru and Chennai gateways.
Direct-to-consumer platforms are compressing order-to-ship cycles from 48 hours to same-day pickup commitments. Merchants in Pune and Ahmedabad are bypassing traditional freight consolidators in favor of carrier-direct API integrations. This behavioral shift is most pronounced in apparel and accessories verticals, where inventory velocity outweighs freight cost minimization in supplier selection criteria.
India International Express Service Market Segmentation
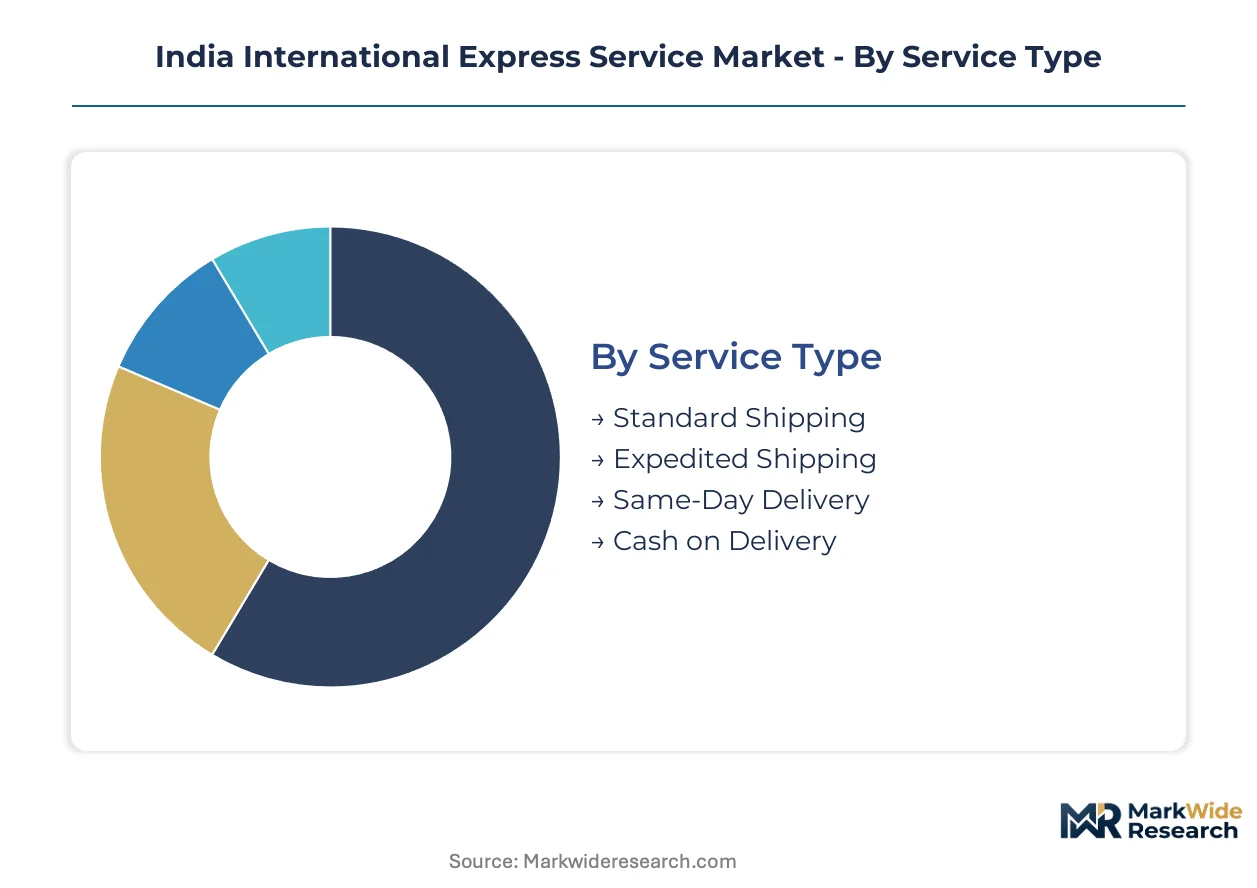
Express carriers in India calibrate network capacity and pricing architecture around distinct service tiers and customer workflows. Segmentation reveals where premium yield concentrates versus where volume scaling drives unit economics.
Service Type:
Volume flows concentrate in deferred lanes while premium capture sits with time-definite commitments.
- Standard Shipping:Deferred 4-7 day transit with consolidated manifest filing and deferred customs clearance. Demand clusters with apparel exporters in Tiruppur and Surat seeking cost-optimized ocean-air intermodal handoffs.
- Expedited Shipping:24-96 hour time-definite delivery with pre-arrival manifest filing and dedicated air freight capacity. Pharmaceutical exporters in Hyderabad and Mumbai-Pune corridor pay freight multiples to avoid stockout penalties in regulated markets.
- Same-Day Delivery:Intra-city emergency document and sample movement with motorcycle courier networks bridging airport gateways. Limited to Delhi-NCR and Mumbai metropolitan zones with sufficient courier density.
- Cash on Delivery:Payment-collection-embedded service for cross-border e-commerce merchants targeting Gulf Cooperation Council markets with low card penetration. RBI outward remittance frameworks govern settlement timelines.
Mature deployment sits with Standard Shipping. Newer deployment is concentrated in Expedited Shipping.
Customer Type:
Procurement patterns diverge sharply between contract-negotiated enterprise accounts and platform-aggregated individual merchants.
- B2B:Contractual volume commitments with annual rate negotiations and embedded customs brokerage. Manufacturing exporters in Bengaluru electronics clusters negotiate dedicated lane pricing.
- B2C:Individual shippers with spot pricing and retail service point access. Tier-two city adoption is climbing the fastest as direct-to-consumer platforms proliferate.
- E-Commerce:API-integrated platform merchants with real-time rate shopping and automated manifest generation. Pune and Ahmedabad merchant bases are expanding most quickly.
- Government:Tender-based procurement with DGFT compliance mandates and extended payment cycles. Public sector pharmaceutical and defense logistics dominate this tier.
Legacy revenue concentration remains with B2B. Margin expansion is concentrated in E-Commerce.
Delivery Model:
Network topology determines capital intensity and customs control points.
- Door-to-Door:Integrated pickup-to-final-mile service with embedded customs clearance and duty pre-payment. Captures premium pricing by eliminating handoff friction for SME exporters lacking in-house trade compliance.
- Hub-and-Spoke:Consolidation-driven model with Mumbai and Delhi international gateways feeding regional distribution. Incumbent carriers dominate through dedicated freighter capacity and landing rights.
- Fulfillment Center:Pre-positioned inventory at export gateways with customs-bonded storage and pick-pack-ship automation. Electronics verticals in Chennai are adopting this model fastest.
- Cross-Border:Partner-handoff model with last-mile delivery executed by foreign postal or courier networks. Cost-optimized for low-value apparel shipments to Southeast Asian markets.
Established infrastructure sits with Hub-and-Spoke. Investment flows are concentrating in Fulfillment Center.
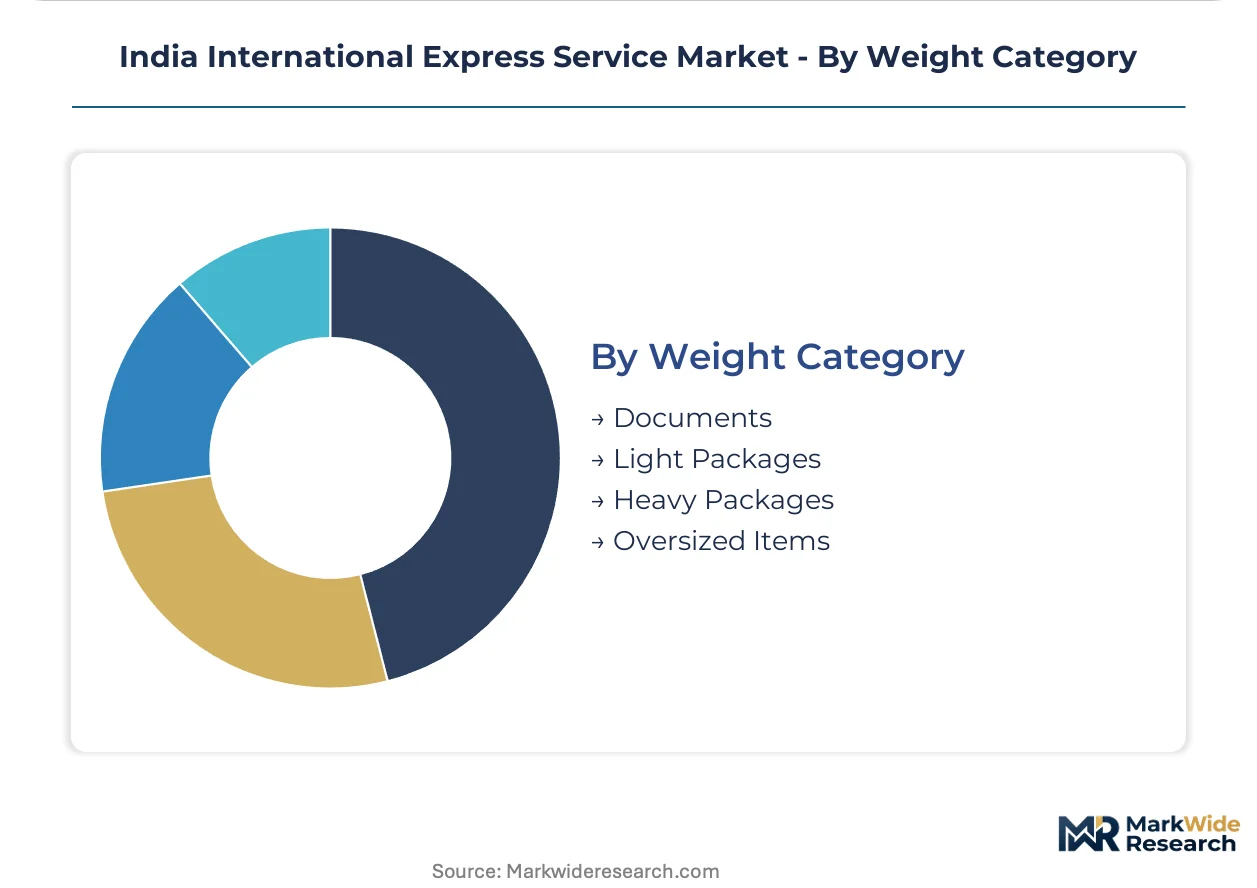
Weight Category:
Handling protocols and customs documentation intensity scale non-linearly with shipment density.
- Documents:Letter-class shipments with simplified customs declarations and diplomatic pouch equivalency for legal and financial sectors. Banking correspondent networks in Mumbai generate concentrated demand.
- Light Packages:Sub-2kg e-commerce parcels with automated sorting compatibility and dimensional weight pricing. Bengaluru and Hyderabad consolidation points process the highest volumes.
- Heavy Packages:10-70kg industrial components requiring manual handling and specialized lift equipment. Automotive parts exporters in Pune and Chennai dominate this segment.
- Oversized Items:Non-conveyable freight exceeding standard aircraft pallet dimensions with charter coordination and crating services. Project cargo for infrastructure exports operates on spot charter markets.
Operational maturity sits with Documents. Volume growth is concentrated in Light Packages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special Economic Zones in Gujarat and Maharashtra concentrate bonded warehousing capacity that feeds express consolidation networks. The Delhi-Mumbai Industrial Corridor anchors freight infrastructure investment. State-level logistics policies in Karnataka and Telangana accelerate hub development around Bengaluru and Hyderabad airports.
Maharashtra
Pharmaceutical exporters in the Mumbai-Pune corridor drive expedited shipping demand for temperature-controlled lanes. The state's logistics policy offers capital subsidies for cold-chain infrastructure at Chhatrapati Shivaji Maharaj International Airport. Mumbai's dedicated freight terminal processes the highest pharmaceutical outbound volumes in India.
Gujarat
Apparel manufacturers in Surat and diamond traders in Surat-Rajkot generate document and light parcel flows to Gulf markets. The Gujarat Logistics Policy incentivizes multi-modal parks at Mundra and Hazira ports. Ahmedabad merchants are adopting carrier-direct API integrations fastest among tier-two cities.
Karnataka
Electronics exporters in Bengaluru electronics clusters negotiate dedicated lane pricing for semiconductor components. The Karnataka Industrial Areas Development Board streamlines SEZ approvals for fulfillment centers near Kempegowda International Airport. Whitefield and Electronic City sub-clusters dominate high-value outbound flows.
Telangana
Pharmaceutical formulation exporters in Hyderabad require CDSCO-certified cold-chain packaging for regulated markets. The Telangana State Industrial Project Approval and Self-Certification System accelerates warehouse licensing. Genome Valley and Pashamylaram industrial zones anchor temperature-controlled express infrastructure.
Delhi-NCR
E-commerce merchants in Gurugram and Noida generate cross-border parcel volumes through direct-to-consumer platforms. The Delhi Freight Policy prioritizes dedicated cargo corridors linking Indira Gandhi International Airport to inland container depots. Tauru Road and Bilaspur logistics parks concentrate customs-bonded warehousing capacity.
India International Express Service Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated global carriers commanding premium lanes while domestic operators capture last-mile density. The market exhibits tiered concentration: three global integrators dominate pharmaceutical and electronics expedited shipping, while regional specialists fragment across B2C e-commerce and document services. Two strategic archetypes define competitive positioning: asset-heavy operators with dedicated freighter capacity and customs-bonded infrastructure, and asset-light platforms aggregating carrier capacity through API integrations. Capacity expansion at Delhi and Mumbai airport gateways and backward integration into fulfillment center operations represent the dominant competitive moves.
Among global integrators, DHL Group and FedEx occupy positions as infrastructure-heavy archetypes with temperature-controlled capabilities and dedicated landing rights. Blue Dart Express represents the domestic-last-mile specialist model, leveraging its Bengaluru and Hyderabad consolidation density to feed international handoffs. These three exemplify how carrier strategy diverges between global network control and domestic pickup reliability.
| Leading Market Players |
|---|
| DHL Group |
| FedEx |
| United Parcel Service of America Inc (UPS) |
| Blue Dart Express |
| Delhivery Limited |
| DTDC Express Limited |
| Gati Express & Supply Chain Private Limited |
| Transport Corporation of India Limited (TCI) |
| Aramex |
| Others |
Pricing and Supply Chain Analysis
Backward integration into captive air freight capacity anchors pricing power for incumbent carriers serving temperature-controlled pharmaceutical lanes from Hyderabad and Mumbai. Carriers owning dedicated freighter slots and customs-bonded cold storage at Chhatrapati Shivaji Maharaj International Airport command rate premiums that asset-light competitors cannot match.
Pricing Analysis
Lead-time-driven pricing separates expedited 24-96 hour commitments from deferred 4-7 day lanes, with pharmaceutical exporters absorbing freight multiples to avoid stockout penalties in regulated markets. Three-tier pricing structure across premium cold-chain, standard air freight, and deferred ocean-air intermodal segments reflects certification grade and handling complexity. Cost compression in standard deferred lanes is intensifying as tier-two e-commerce merchants prioritize inventory velocity over freight minimization. B2C platform merchants exhibit highest price sensitivity, while CDSCO-certified pharmaceutical exporters demonstrate lowest sensitivity due to compliance-driven carrier lock-in.
Supply Chain Analysis
Workforce availability for dangerous goods classification and lithium battery handling concentrates in Mumbai and Bengaluru, creating bottlenecks for carriers expanding specialized express lanes. Manufacturing inputs for express infrastructure draw from China for automated sorting equipment, Germany for temperature-controlled container technology, and domestic sources for last-mile motorcycle courier networks. Single-source vulnerability sits with aviation turbine fuel supply tied to dollar-denominated contracts and rupee volatility. Distribution runs through hub-and-spoke architectures anchored at Delhi-NCR and Mumbai-Pune freight clusters feeding international gateways.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
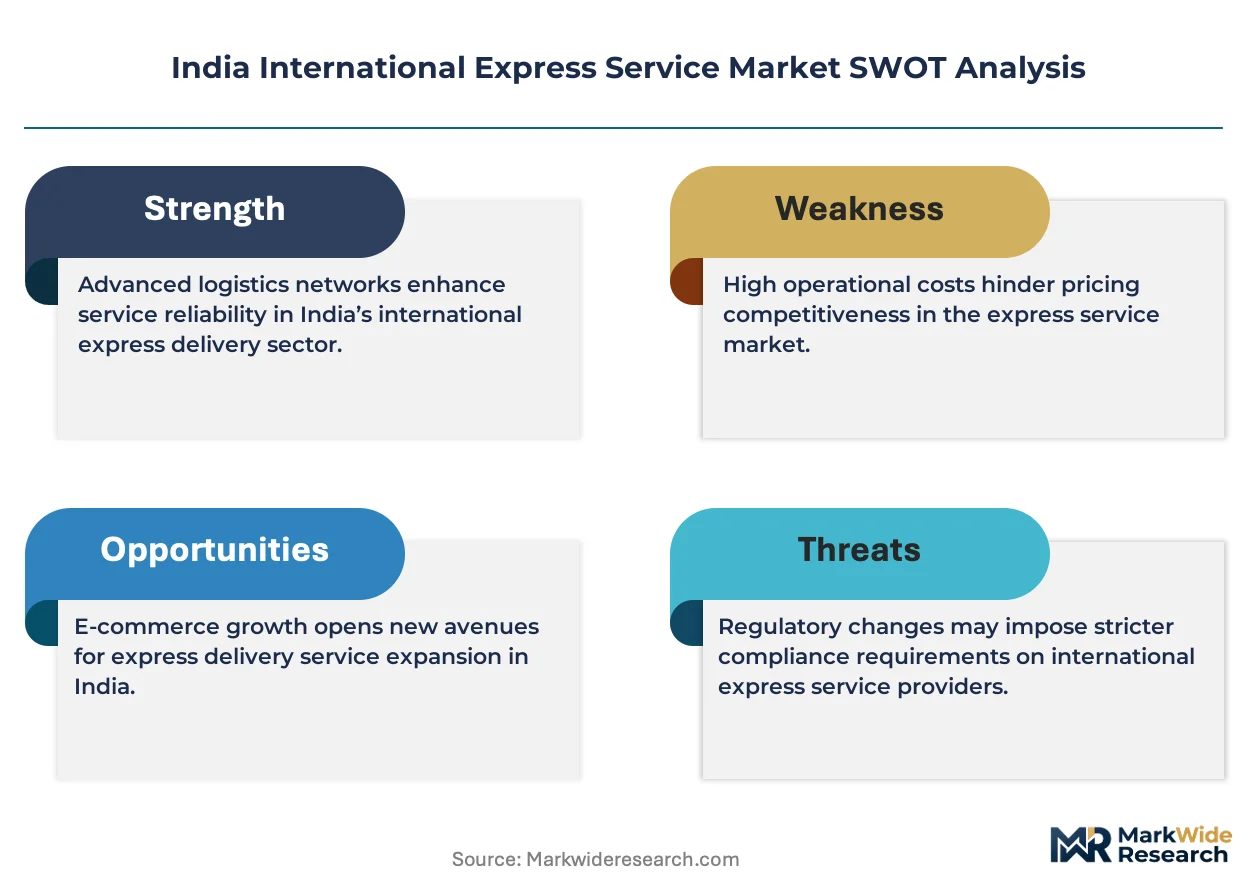
India's international express market reads as supply-constrained, with qualified cold-chain infrastructure scarcity propping rate premiums across pharmaceutical and electronics verticals.
For Market Incumbents: Deploy dedicated freighter capacity additions at underutilized Indira Gandhi International Airport cargo terminals to preempt competitor landing rights acquisition. Deepen captive control over temperature-certified packaging supply through CDSCO qualification partnerships, insulating against emerging regional specialists targeting Hyderabad pharmaceutical lanes. For New Entrants and Emerging Players: Enter via electronics reverse logistics from Gulf Cooperation Council warranty return flows, an underserved lane with premium yield potential and limited incumbent focus. Target Surat and Ahmedabad apparel merchant bases with API-integrated platform solutions, bypassing traditional freight consolidators through carrier-direct integrations. For Investors and Strategic Acquirers: Exit pathways concentrate in consolidation plays among domestic last-mile specialists with Bengaluru and Hyderabad density feeding international handoffs. Long-term viability hinges on regulatory compliance automation capabilities and ICEGATE integration depth. Watch CDSCO certification timeline compression as inflection signal for cold-chain service launch acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Expansion | CDSCO-qualified temperature-controlled capacity captures pharmaceutical export premiums from Genome Valley. |
| API-Integrated Platform Development | Direct merchant connectivity bypasses freight consolidators in Pune and Ahmedabad e-commerce clusters. |
| Customs Brokerage Automation | Embedded DGFT-ICEGATE integration creates bundled service differentiation for SME exporter segments. |
| Reverse Logistics Network Buildout | Gulf Cooperation Council warranty return lanes offer underserved premium yield for electronics verticals. |
| Multi-Modal Hub Development | Mundra and Hazira port connectivity under Gujarat Logistics Policy reduces air freight cost exposure. |
Research Methodology
Independent corroboration across express carrier operations executives, pharmaceutical export logistics managers, and customs brokerage specialists underwrites the qualitative findings. Primary fieldwork encompassed CDSCO regulatory affairs leads, DGFT compliance officers, and tier-two e-commerce platform operators. Secondary validation drew from DGFT export documentation databases, ICEGATE transaction filings, RBI outward remittance frameworks, and PLI scheme disbursement records. Bottom-up volume modeling across service tiers and customer segments triangulated against top-down freight terminal throughput data.
Comparable-period anchoring linked the projection horizon to historical PLI scheme implementation phases and CDSCO certification cycle timelines. Segmentation dimensions encompassed service type, customer archetype, delivery model topology, and weight category handling protocols. CAGRs were derived from shipment volume trajectories calibrated against air freight capacity additions at Delhi and Mumbai gateways. Forecast inputs incorporated e-commerce merchant adoption curves in tier-two cities and cold-chain infrastructure subsidy utilization rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under rupee-dollar volatility spikes and aviation turbine fuel price shocks. Forecasts reflect assumptions regarding PLI scheme continuity, CDSCO regulatory streamlining pace, and state logistics policy implementation fidelity. Material deviation in FEMA remittance threshold adjustments or customs automation rollout delays warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tourist Transport Services
Low-Cost Carrier (LCC) Market
Tourist Transport Services
Southeast Asia Charter Jet Services Market
Tourist Transport Services
Europe Charter Jet Services Market
Tourist Transport Services
Italy Car Rental Market
Tourist Transport Services
Helicopter Tourism Market
Tourist Transport Services
Airport Ground Transportation Market
Tourist Transport Services
Pre-Book Airport Transfer Market
Tourist Transport Services
Boat Rental Market
Tourist Transport Services
UK Low Cost Airlines Market
Tourist Transport Services
Travel Transportation Market
Tourist Transport Services
Yacht Rental Market