
 Low-Cost Carrier (LCC) Market | 2026-2036
Low-Cost Carrier (LCC) Market Size, Share, and Industry Trends Forecast 2026-2036
Low-Cost Carrier (LCC) Market Foresight
The fleet ownership gap between full-service legacy models and asset-light LCC structures is unwinding competitive economics across aviation. Southwest Airlines Co. leverages its entirely owned Boeing 737 fleet to sustain unit cost advantages on dense domestic US routes. Ryanair anchors European point-to-point density through uniform aircraft configuration and negotiated airport fee structures. Wizz Air Holdings plc competes in Central and Eastern Europe with aggressive base expansion into secondary cities underserved by flag carriers.
A low-cost carrier operates scheduled air passenger services through standardized narrow-body aircraft, high aircraft utilization rates exceeding twelve daily block hours, and direct point-to-point routing without hub-and-spoke complexity to minimize ground time and crew costs. Point-to-Point service dominates volume as it eliminates connection infrastructure and reduces turnaround intervals below thirty minutes at most bases. Ancillary Fees pricing captures expanding margin pools as unbundled baggage, seat selection, and onboard retail now constitute substantial revenue contributions separate from base fares. Short-Haul routes retain structural maturity across European and Asian LCC networks while Long-Haul experimentation with densified wide-body configurations represents emerging competitive territory.
The FAA governs US carrier certification and operational safety standards while the EU Green Deal imposes escalating sustainable aviation fuel blending requirements affecting European LCC fleet planning. EASA implements the EU Emissions Trading System for aviation with binding carbon caps that intensify pressure for next-generation engine adoption across Ryanair and Wizz Air route networks. Stakeholders must monitor evolving carbon border adjustments and SAF subsidy frameworks as these mechanisms determine which LCC business models retain cost parity against rail and conventional network carriers.
Market Dynamics
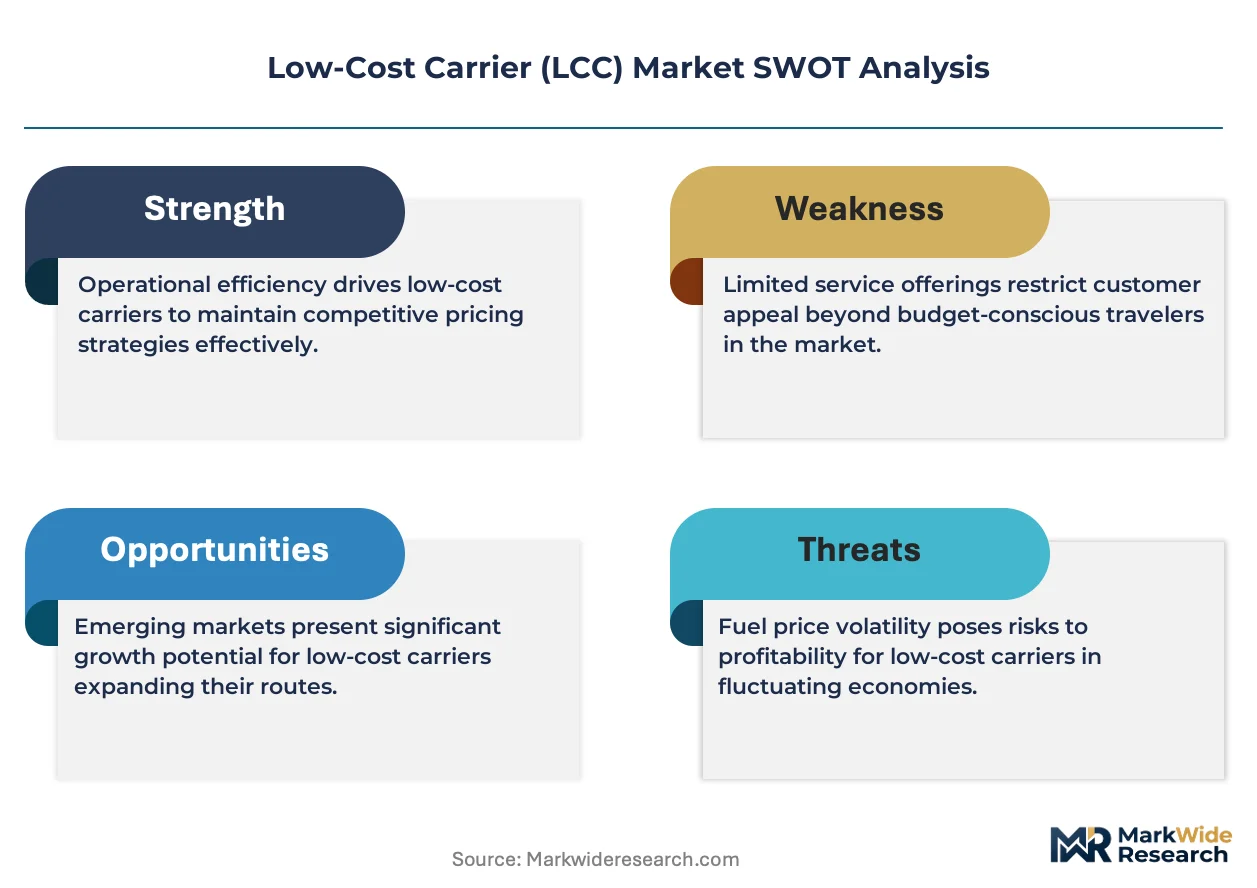
Fleet unbundling from ownership-heavy legacy structures toward asset-light operating models is compressing unit economics and redrawing competitive boundaries across short-haul aviation networks.
Growth Catalysts
- Open Skies Liberalization:Bilateral air service agreements across Southeast Asia and Latin America are dissolving route monopolies and enabling point-to-point network expansion into secondary cities previously served only by flag carriers.
- Sustainable Aviation Fuel Mandates:The EU Green Deal's escalating SAF blending requirements are accelerating fleet renewal cycles as older narrow-body aircraft face rising carbon compliance costs under ETS caps.
- Mobile-First Distribution:Direct booking platforms and app-based ancillary upselling are capturing margin pools previously ceded to global distribution systems and travel agency intermediaries.
Market Restraints
- Jet Fuel Price Volatility:Unhedged exposure to kerosene spot markets erodes the cost advantage that defines LCC unit economics during supply shock periods.
- Secondary Airport Slot Scarcity:Concentration of attractive point-to-point routes at capacity-constrained facilities in the UK, Germany, and Netherlands limits base expansion for new entrants.
- Rail Substitution on Dense Corridors:High-speed rail networks on routes under four hours—Paris-Lyon, Madrid-Barcelona, Milan-Rome—capture price-sensitive travelers with lower carbon footprints.
Strategic Opportunities
- Indian Domestic Market Expansion:Underpenetrated tier-2 and tier-3 city pairs offer unserved demand as India's middle-class air travel accelerates beyond metro hub saturation.
- Carbon Offset Premium Products:Voluntary passenger contributions toward verified emission reductions create ancillary revenue streams distinct from regulatory compliance costs.
- Single-Aisle Long-Haul Experimentation:Next-generation engine economics on extended-range narrow-bodies are opening thin transatlantic and Middle East-Southeast Asia routes previously requiring wide-body deployment.
Industry Challenges
- Pilot Training Pipeline Bottlenecks:Compressed captain upgrade timelines and simulator capacity constraints are extending crew recruitment cycles at expanding bases.
- Aircraft Delivery Backlog Management:OEM production rate limitations and pre-delivery payment schedules strain balance sheet flexibility for aggressive fleet growth plans.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low-Cost Carrier (LCC) Market |
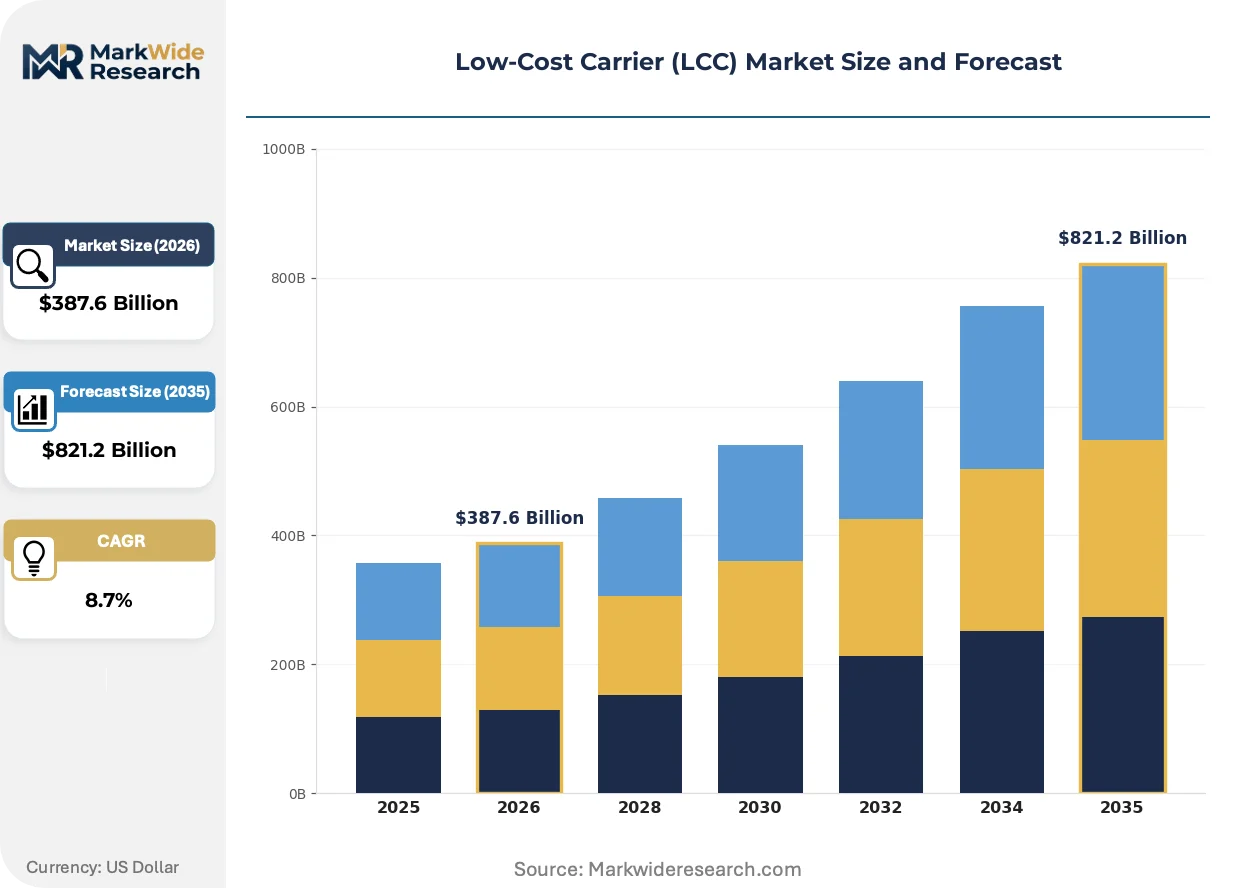
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $821.2 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Point-to-Point, Charter, Scheduled, Cargo Customer Type: Leisure Travelers, Business Travelers, Students, Families Route Type: Domestic, International, Short-Haul, Long-Haul Pricing Model: Dynamic Pricing, Flat Rate, Subscription, Ancillary Fees |
| Companies Covered | Southwest Airlines Co., Ryanair, easyJet plc, IndiGo, AirAsia Group Berhad, Wizz Air Holdings plc, Spirit Airlines, JetBlue Airways Corporation, Frontier Group Holdings Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low-Cost Carrier (LCC) Market Shifts & Advancements
Digital retail architecture and propulsion efficiency gains are converging to redefine how low-cost carriers extract value from passengers and optimize asset deployment across fragmented route networks.
Artificial intelligence-driven dynamic pricing is decomposing traditional fare class structures into micro-segmented willingness-to-pay tiers. LCC revenue management teams deploy machine learning models that adjust seat prices in fifteen-minute intervals based on search behavior and competitive positioning. This granularity compresses revenue leakage on high-demand departures while stimulating load factors on underbooked services through targeted flash promotions.
The EU Emissions Trading System is tightening aviation carbon caps through 2030, forcing accelerated adoption of next-generation engine technologies. Pratt & Whitney geared turbofan and CFM LEAP-1A powerplants deliver fifteen percent fuel efficiency gains over previous generation equipment. Ryanair and Wizz Air route networks face the steepest compliance cost exposure, driving negotiated fleet renewal commitments with Airbus and Boeing.
Travelers increasingly unbundle service expectations from base fare decisions, treating seat selection, baggage allowance, and onboard catering as separate purchase occasions. Mobile-native booking flows capture this behavioral shift through staged upsell presentations during reservation and pre-departure phases. Southeast Asian LCCs lead this monetization evolution, where ancillary revenue per passenger now approaches base fare contributions on competitive trunk routes.
Low-Cost Carrier (LCC) Market Segmentation
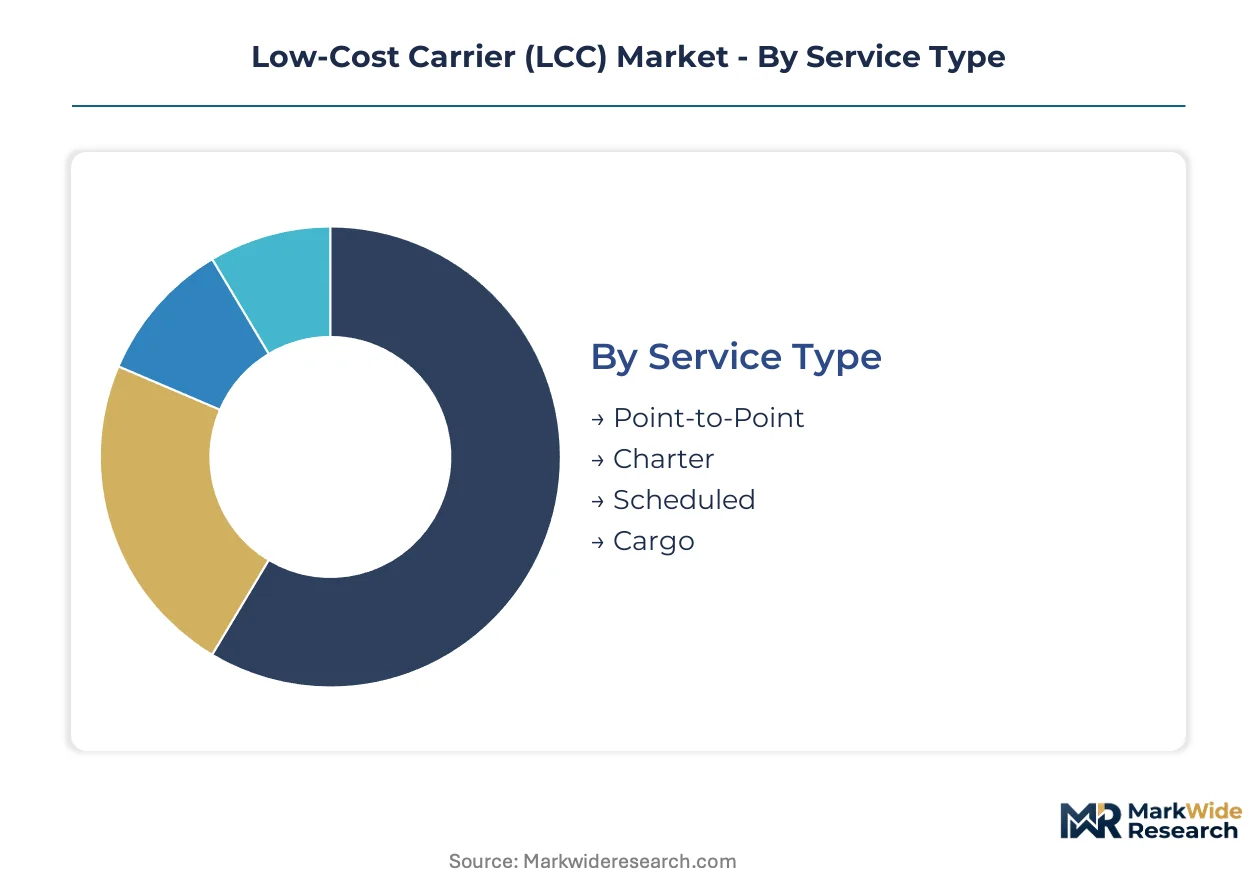
LCC segmentation reveals how operational architecture and passenger economics diverge across service configurations. Regulatory frameworks from the FAA, EASA, and national aviation authorities impose distinct compliance burdens on each segment, reshaping fleet deployment and revenue capture strategies.
Service Type:
EASA and FAA certification requirements diverge sharply between scheduled operations and non-scheduled alternatives, with carbon cap exposure concentrated on high-frequency point-to-point networks.
- Point-to-Point:Direct routing between origin and destination eliminates hub infrastructure and compresses turnaround times below thirty minutes at bases. Demand concentrates across Southeast Asian city pairs as Indonesia and Vietnam expand secondary airport capacity to accommodate densified narrow-body schedules.
- Scheduled:Fixed-frequency service with published timetables requires slot coordination at congested facilities and exposes operators to EU ETS compliance costs. European LCCs face the steepest regulatory pressure as SAF mandates escalate through the EU Green Deal implementation timeline.
- Charter:Ad-hoc capacity deployment for tour operators and seasonal demand spikes carries lighter regulatory overhead but irregular utilization patterns.
- Cargo:Belly-hold freight on passenger-configured narrow-bodies supplements yield on trunk routes with limited dedicated freighter competition.
Point-to-Point handles the majority of throughput; Scheduled is expanding most quickly as flag carrier retrenchment opens slot availability.
Customer Type:
Passenger willingness-to-pay variance determines ancillary revenue architecture and distribution channel investment priorities across LCC networks.
- Leisure Travelers:Price-elastic demand for vacation and VFR (visiting friends and relatives) traffic dominates volume on sun routes and emerging city pairs. India's middle-class expansion is driving tier-2 and tier-3 route development as metro hub saturation intensifies competition.
- Business Travelers:Time-sensitive passengers paying premium fares for schedule flexibility and airport proximity require frequency depth and business-friendly departure windows.
- Students:Seasonal mobility patterns around academic calendars create predictable demand troughs and peaks requiring yield management calibration.
- Families:Multi-passenger bookings with baggage and seat selection requirements generate higher ancillary capture per transaction than individual travelers.
Leisure Travelers account for the dominant share; Business Travelers are climbing the fastest as hybrid work patterns sustain midweek demand.
Route Type:
Stage length and border crossing complexity determine aircraft specification, crew complement, and regulatory jurisdiction overlap.
- Short-Haul:Sectors under four hours maximize daily aircraft utilization and minimize crew duty period constraints. High-speed rail substitution on dense European corridors—Paris-Lyon, Madrid-Barcelona—compresses addressable market on overlapping city pairs.
- Domestic:Single-jurisdiction operations avoid bilateral negotiation complexity and customs processing overhead while capturing deregulated market expansion.
- International:Cross-border services require air service agreement access and expose revenue to currency fluctuation on fare collection.
- Long-Haul:Extended-range narrow-body experimentation with densified configurations opens thin transatlantic and Middle East-Southeast Asia routes previously requiring wide-body economics.
Short-Haul carries the volume base; Long-Haul is gaining share fastest as next-generation engine efficiency enables unit cost parity on extended sectors.
Pricing Model:
Revenue management sophistication separates market leaders from capacity-dumpers as digital distribution disintermediates traditional sales channels.
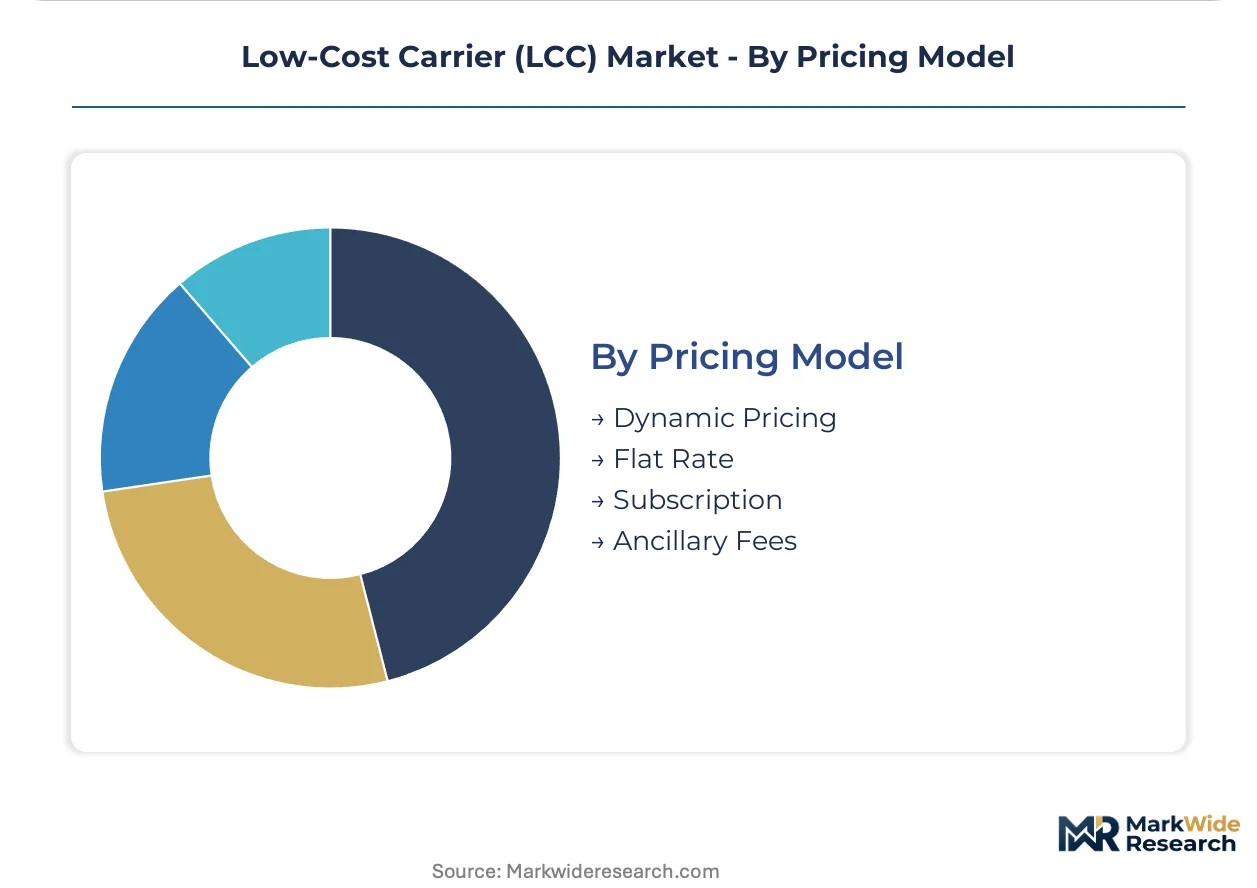
- Ancillary Fees:Unbundled baggage, seat selection, and onboard retail now constitute substantial revenue contributions separate from base fares. Southeast Asian operators lead monetization evolution where ancillary revenue per passenger approaches base fare contributions on competitive trunk routes.
- Dynamic Pricing:Machine learning models adjust seat prices in fifteen-minute intervals based on search behavior and competitive positioning, compressing revenue leakage on high-demand departures.
- Flat Rate:Simplified fare structures reduce comparison shopping friction but sacrifice yield optimization potential on peak demand services.
- Subscription:Recurring revenue models with fixed monthly fees for route-specific travel appeal to commuter segments and business travelers with predictable patterns.
Ancillary Fees dominates revenue composition; Dynamic Pricing is advancing fastest as AI deployment accelerates across major LCC revenue management teams.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European LCCs command superior yield premiums on dense city pairs while Southeast Asian operators compete on volume-driven unit economics across fragmented archipelago networks. Pricing power asymmetry reflects divergent airport slot scarcity, regulatory carbon exposure, and middle-class air travel penetration rates.
United States
Dense domestic route networks and deregulated airport access sustain Southwest Airlines Co.'s fleet ownership model. The FAA enforces operational safety standards while slot-constrained facilities at Newark and LaGuardia limit new entrant expansion. Dallas-Fort Worth and Chicago Midway anchor point-to-point density with sub-thirty-minute turnaround protocols.
Germany
High-speed rail substitution on corridors under four hours compresses addressable market for short-haul LCC operations. The EU Green Deal's SAF blending mandates accelerate fleet renewal pressures at Berlin and Frankfurt secondary bases. Bavaria's Munich Airport concentration forces yield competition against Lufthansa network frequency.
India
Tier-2 and tier-3 city pair underpenetration drives IndiGo's domestic expansion as metro hub saturation intensifies. The Directorate General of Civil Aviation (DGCA) regulates route dispersal obligations on trunk sectors. Mumbai-Delhi corridor density supports multiple daily frequencies with aggressive ancillary monetization.
Indonesia
Archipelago geography necessitates air connectivity where surface transport remains impractical across 17,000 islands. The Ministry of Transportation oversees bilateral air service negotiations affecting Jakarta-Singapore and Denpasar-Australia trunk routes. Surabaya and Makassar secondary bases unlock visiting friends and relatives traffic flows.
United Kingdom
London airport slot scarcity forces LCC concentration at Stansted, Luton, and Gatwick secondary facilities. The UK Emissions Trading Scheme mirrors EU carbon cap structures post-Brexit, affecting easyJet plc fleet planning. Manchester and Edinburgh bases capture regional business travel with business-friendly departure windows.
Low-Cost Carrier (LCC) Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the LCC sector. Fleet standardization and direct distribution platforms define the cost leadership tier, while ancillary revenue sophistication and dynamic pricing algorithms characterize the technology leadership segment. Three archetypes dominate: owned-fleet density operators, asset-light franchise expanders, and hybrid service differentiators. Capacity expansion through next-generation narrow-body orders and strategic partnerships with secondary airport authorities constitute the primary competitive moves reshaping network economics.
Among US-based owned-fleet specialists, Southwest Airlines Co. exemplifies the density-driven archetype through standardized Boeing 737 deployment. European point-to-point operators Ryanair and Wizz Air Holdings plc occupy positions within the aggressive expansion tier, leveraging uniform aircraft configuration and negotiated airport fee structures to compress unit costs. These three entities represent distinct geographic manifestations of the low-cost model, each anchored in regulatory environments that reward operational simplicity over network complexity.
| Leading Market Players |
|---|
| Southwest Airlines Co. |
| Ryanair |
| easyJet plc |
| IndiGo |
| AirAsia Group Berhad |
| Wizz Air Holdings plc |
| Spirit Airlines |
| JetBlue Airways Corporation |
| Frontier Group Holdings Inc. |
| Others |
Supply & Pricing Matrix
FAA certification requirements for pilot training and aircraft airworthiness simultaneously gate supplier qualification for LCC fleet orders and stratify pricing power between established OEMs and emerging lessors. The EU Green Deal's SAF mandates add parallel compliance layers that compress margins on older equipment while rewarding carriers with renewal flexibility.
Pricing Analysis
The customization-premium spread between configured-to-order narrow-body deliveries and standard specification spot purchases now exceeds fifteen percent at Airbus and Boeing. Pricing stratifies across premium engine selections, dense cabin configurations, and extended maintenance packages as carriers negotiate fleet packages. Cost compression in base fare tiers intensifies because unhedged fuel exposure erodes the unit economics that define LCC competitiveness. Leisure travelers on sun routes exhibit highest price sensitivity, while business travelers paying for schedule flexibility and airport proximity accept meaningful premiums.
Supply Chain Analysis
Pratt & Whitney GTF engine supply from the United States and CFM LEAP production split between France and the United States constitute critical chokepoints for fleet renewal timelines. Aircraft manufacturing draws from titanium forgings, avionics suites, and composite fuselage sections sourced across Japan, Germany, and Italy. Single-source vulnerability in engine MRO capacity strains turnaround reliability during peak summer scheduling. Distribution runs through direct OEM negotiations and sale-leaseback arrangements with Dublin and Singapore-based lessors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ancillary revenue streams from dynamic seat pricing and carbon offset contributions are expanding faster than base fare yield, reframing LCC valuation around service-attach depth rather than passenger volume alone.
For Market Incumbents: Consolidate gate access at slot-constrained facilities through long-term airport use agreements before regulatory carbon caps accelerate secondary base competition. Deepen backward integration into pilot training academies to relieve crew pipeline bottlenecks threatening expansion timelines. Lock in sustainable aviation fuel offtake contracts to hedge EU ETS exposure as compliance costs escalate.
For New Entrants and Emerging Players: Differentiate on underserved tier-2 city pairs in India and Indonesia where metro hub saturation leaves demand pockets unaddressed by established networks. Target visiting friends and relatives traffic flows with frequency depth on routes below four hours where rail substitution remains impractical. Deploy mobile-native booking platforms with staged upsell architecture to capture ancillary margin pools ceded to legacy distribution.
For Investors and Strategic Acquirers: Carve-out targets emerge from flag carrier subsidiaries and tour operator charter divisions seeking to divest non-core aviation assets amid balance sheet restructuring. Long-term viability hinges on fleet age profiles and SAF transition flexibility rather than current load factors alone. Monitor EU carbon border adjustment mechanisms as the inflection signal determining which LCC business models retain cost parity against conventional network carriers.
| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Standardization Program | Uniform aircraft configuration at Ryanair and Southwest compresses maintenance costs and crew training cycles. |
| Secondary Airport Base Expansion | Wizz Air's negotiated fee structures at Budapest and Krakow unlock point-to-point density underserved by flag carriers. |
| Dynamic Pricing Algorithm Deployment | Fifteen-minute fare adjustment intervals at IndiGo and AirAsia minimize revenue leakage on high-demand departures. |
| Sustainable Aviation Fuel Partnership | Long-term offtake agreements with Neste and World Energy hedge EU ETS compliance exposure for European operators. |
| Mobile-First Distribution Platform | Direct booking channels at Southeast Asian LCCs capture margin pools previously ceded to global distribution systems. |
Research Methodology
Cross-validation between executive interviews at fleet planning departments and secondary validation through FAA certification databases anchors the qualitative findings on operational economics. Primary fieldwork engaged route network strategists, aircraft procurement leads, airport slot coordinators, and ancillary revenue managers at carriers across the United States, Europe, and Southeast Asia. Secondary sources include EASA regulatory filings, EU ETS aviation sector data, IATA traffic statistics, and OEM delivery disclosures. Bottom-up passenger volume modeling and top-down market sizing triangulate segment-level outputs.
Sensitivity analysis around jet fuel price trajectories and carbon cap stringency frames the projection boundaries across the analysis window. Segmentation dimensions include service type, customer archetype, route length, and pricing model complexity alongside geographic regulatory cluster. CAGRs derive from fitted trend extrapolation calibrated to historical fleet deployment patterns and bilateral air service agreement expansion timelines. Forecast inputs incorporate engine efficiency curves and SAF blending mandate implementation schedules.
The analysis sits within stated boundaries; outcomes outside sustained open skies liberalization and middle-class air travel penetration rates would require recalibration. Forecasts reflect documented assumptions on OEM production rates and pilot training pipeline capacity. Practitioners should keep alternative scenarios live as EU Green Deal enforcement mechanisms and high-speed rail network extensions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tourist Transport Services
UK Low Cost Airlines Market
Tourist Transport Services
Helicopter Tourism Market
Tourist Transport Services
Southeast Asia Charter Jet Services Market
Tourist Transport Services
Travel Transportation Market
Tourist Transport Services
India International Express Service Market
Tourist Transport Services
Europe Charter Jet Services Market
Tourist Transport Services
Airport Ground Transportation Market
Tourist Transport Services
Boat Rental Market
Tourist Transport Services
Pre-Book Airport Transfer Market
Tourist Transport Services
Italy Car Rental Market
Tourist Transport Services
Yacht Rental Market