
 Southeast Asia Charter Jet Services Market | 2026-2036
Southeast Asia Charter Jet Services Market Size, Share, and Industry Trends Forecast 2026-2036
Southeast Asia Charter Jet Services Market Analytics
Multi-source fleet procurement is shifting as operators balance owned assets against wet-lease and dry-lease arrangements to manage capacity seasonality. OJets Pte Ltd. leverages Singapore's maintenance ecosystem to sustain operational reliability across its managed fleet. Berjaya Air Sdn. Bhd. anchors Malaysian domestic connectivity through its focus on secondary city pairs underserved by scheduled carriers. Thai Airways International Public Company Ltd. competes in the premium charter segment by extending its MRO capabilities and crew training infrastructure to private clients.
Southeast Asia charter jet services encompass on-demand aircraft rental with crew, fuel, and insurance included, typically utilizing jets with 4 to 19 passenger capacity and 2,000 to 7,500 nautical mile range depending on mission profile. These services serve time-sensitive travel, medical evacuation, and luxury tourism where scheduled airline networks prove inadequate or inefficient. The business service type captures the largest revenue pool due to recurring corporate contracts, while air ambulance operations command premium pricing through specialized medical fit-outs and rapid-response crew scheduling. Light jets lead transaction volume across island-hopping routes in Indonesia and the Philippines, though heavy jets concentrate margin pools on long-haul connections to the Middle East and Europe.
Civil aviation authorities in Indonesia, Thailand, and Singapore enforce divergent air operator certificate standards that fragment compliance costs for cross-border operators. The ASEAN Single Aviation Market framework and national regulations under each country's directorate general of civil aviation shape foreign ownership limits, cabotage rights, and safety audit protocols. Stakeholders must monitor pending harmonization of third-party liability insurance minimums and emissions disclosure requirements that will alter fleet renewal timelines and operating cost structures.
Market Dynamics
The ASEAN Single Aviation Market framework is fragmenting compliance architectures across Indonesia, Thailand, and Singapore, forcing operators to maintain parallel certification systems while national civil aviation authorities retain divergent safety audit protocols and foreign ownership limits.
Growth Catalysts
- Archipelagic Infrastructure Gaps:Indonesia's 17,000 islands lack surface connectivity, making charter aviation essential for executive mobility and medical evacuation across the archipelago.
- ASEAN Open Skies Agreements:The regional framework is expanding route permissions and reducing bilateral negotiation friction for cross-border charter operations.
- Medical Evacuation Networks:Specialized air ambulance fit-outs with rapid-response crew scheduling are commanding premium pricing from high-net-worth individuals and corporate risk managers.
Market Restraints
- Jet Fuel Price Volatility:Singapore jet kerosene benchmarks expose operators to input cost swings that compress margins on fixed-rate corporate contracts.
- Pilot Certification Fragmentation:Indonesia's Directorate General of Civil Aviation maintains distinct type-rating requirements that limit crew mobility across ASEAN borders.
- Scheduled Carrier Substitution:Low-cost carriers on trunk routes between Jakarta, Bangkok, and Singapore undercut charter pricing for non-time-sensitive travel.
Strategic Opportunities
- Philippine Resort Corridors:Secondary destinations like Palawan and Siargao lack adequate runway infrastructure for scheduled jets, creating white space for amphibious and short-field charter aircraft.
- Carbon Disclosure Mandates:Pending harmonization of emissions reporting requirements across ASEAN civil aviation authorities will reward operators with newer, more efficient fleets.
- Blockchain-Enabled Empty Leg Matching:Real-time repositioning algorithms are reducing deadhead costs and improving asset utilization for on-demand charter platforms.
Industry Challenges
- Maintenance Technician Shortage:Singapore's MRO ecosystem is absorbing regional talent, leaving Indonesian and Thai operators with extended airframe inspection backlogs.
- Third-Party Liability Insurance Harmonization:Divergent minimum coverage requirements across national aviation authorities complicate cross-border risk pooling and policy structuring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Southeast Asia Charter Jet Services Market |
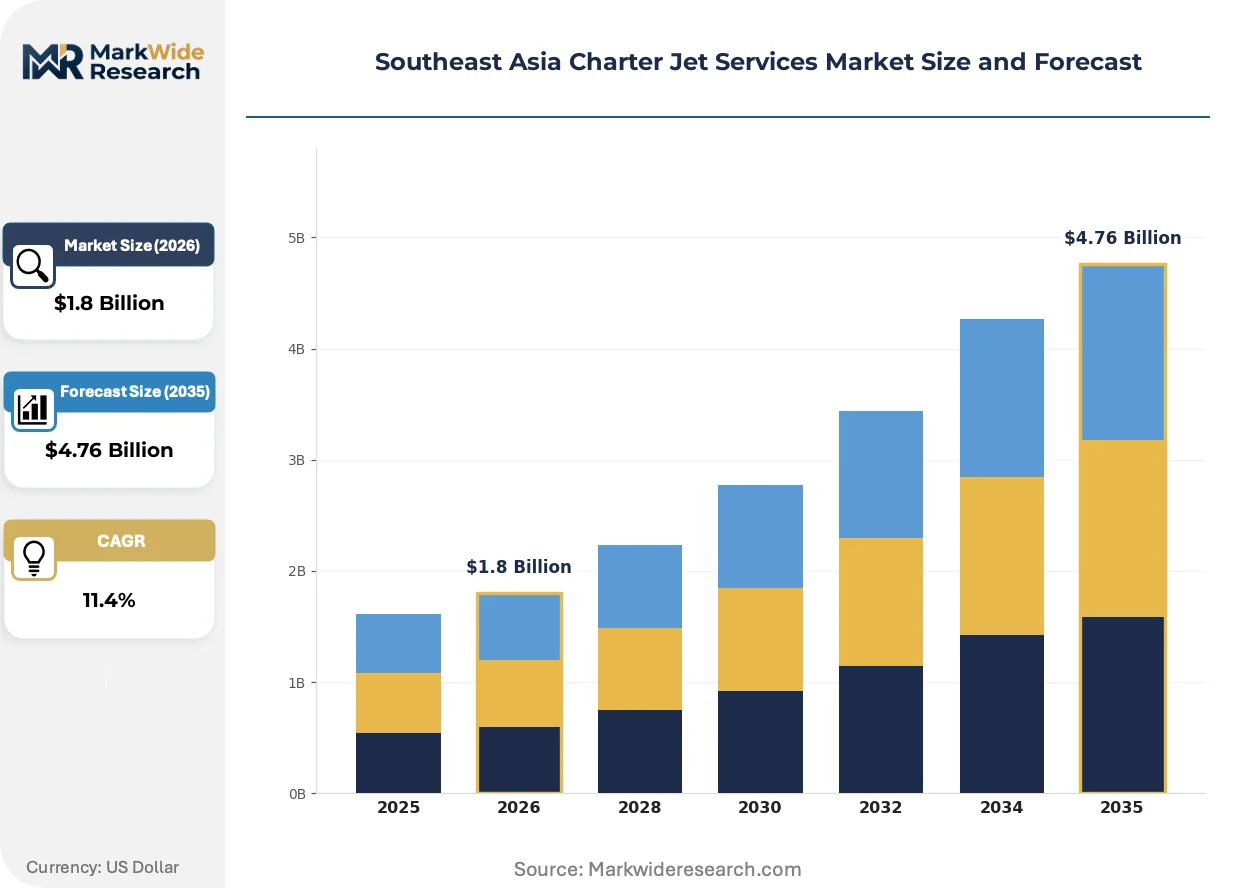
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: On-Demand, Air Ambulance, Business, Leisure End User: Corporate, Government, Tourists, VIPs Aircraft Type: Light Jets, Midsize Jets, Heavy Jets, Turboprops Booking Channel: Direct, Travel Agencies, Online Platforms, Brokers |
| Companies Covered | OJets Pte Ltd., Berjaya Air Sdn. Bhd., Thai Airways International Public Company Ltd. (THAI), PhilJets Aero Charter Corp., Phenix Jet, Singapore Air Charter Pte Ltd., EastIndo, MJets Limited, Advance Aviation Co., Ltd., Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Southeast Asia Charter Jet Services Market Evolving Landscape
Digital platforms and sustainable aviation technologies are compressing booking friction and emissions profiles simultaneously, while regulatory divergence forces operators into multi-jurisdictional compliance architectures.
Avionics suites with predictive maintenance algorithms are modularizing fleet management across Southeast Asian operators. Regional charter providers in Thailand and Indonesia are retrofitting legacy airframes with connected health-monitoring systems at accelerated timelines. This technology is modularizing maintenance scheduling, allowing operators to extend inspection intervals and reduce unscheduled downtime across dispersed island operations.
Indonesia's Directorate General of Civil Aviation is tightening foreign air operator certificate equivalency requirements for wet-lease arrangements. The regulation forces international lessors to establish local maintenance partnerships or face operational restrictions. Heavy jet operators serving long-haul Middle East routes are absorbing compliance costs through longer-term dry-lease structures rather than seasonal capacity augmentation.
Corporate travel managers are consolidating preferred operator relationships into annual minimum-commitment contracts rather than ad-hoc bookings. This concentration is displacing brokerage intermediaries in Singapore and Jakarta as direct operator-client agreements proliferate. The shift is most visible among Indonesian mining conglomerates and Thai hospitality groups requiring guaranteed lift for executive rotation schedules.
Southeast Asia Charter Jet Services Market Segmentation
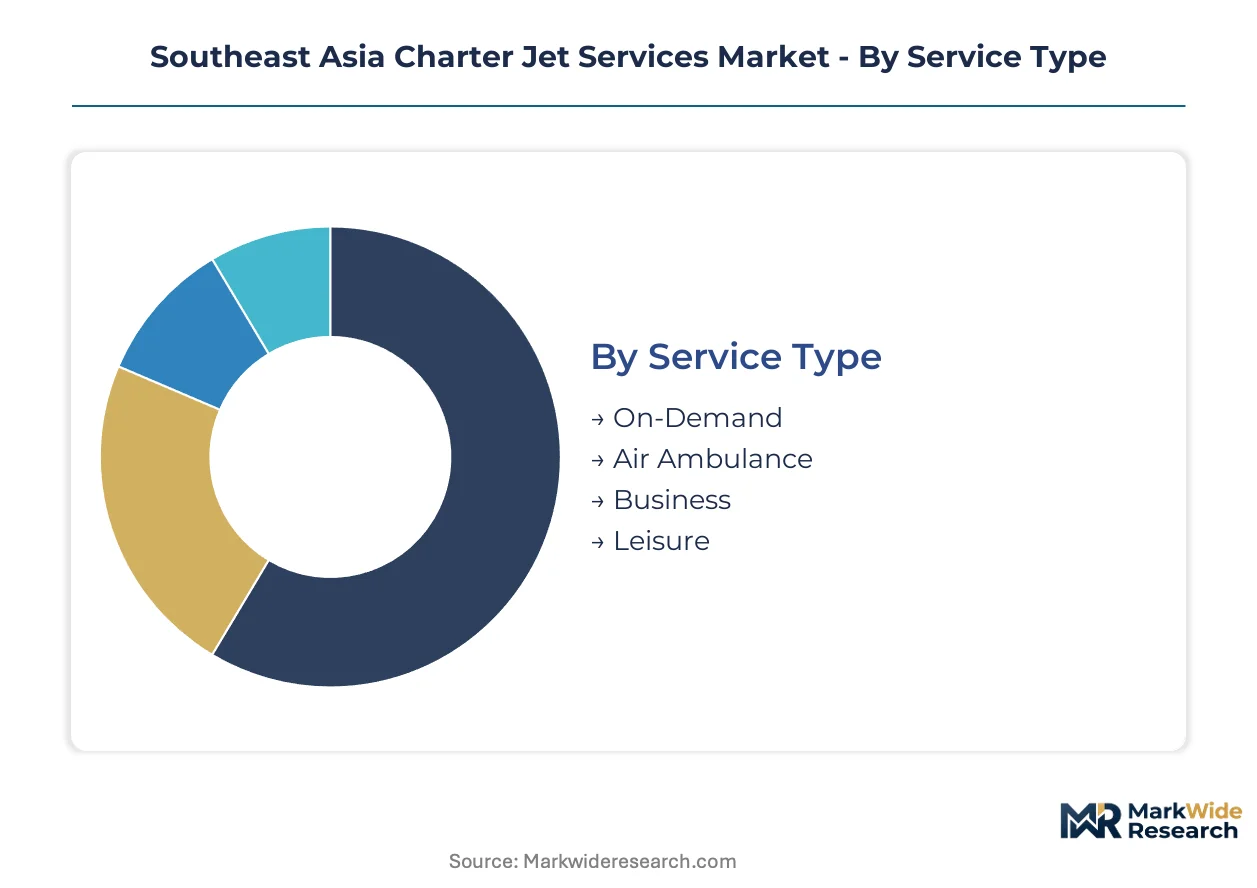
Segmentation in Southeast Asia charter jet services reflects divergent regulatory burdens across service types, aircraft categories, and booking channels. Each dimension carries distinct certification requirements from Indonesia's Directorate General of Civil Aviation, Singapore's Civil Aviation Authority, and Thailand's Department of Civil Aviation that shape operational economics.
Service Type:
Air operator certificate requirements vary sharply across service types, with medical evacuation demanding specialized equipment approvals and on-demand charter facing lighter operational specification burdens.
- On-Demand:Ad-hoc aircraft rental with crew, fuel, and insurance bundled into single-trip pricing. Demand concentrates in Indonesia's archipelagic corridors where surface infrastructure gaps make charter aviation essential for executive mobility between islands.
- Business:Recurring corporate contracts with guaranteed availability windows and fixed hourly rates. Singapore-based multinationals and Indonesian mining conglomerates drive volume through annual minimum-commitment agreements that displace brokerage intermediaries.
- Air Ambulance:Specialized medical fit-outs with rapid-response crew scheduling command premium pricing from high-net-worth individuals and corporate risk managers. Indonesia's DGCA enforces stringent airworthiness standards for intensive-care configurations that extend modification timelines.
- Leisure:Resort destination access for luxury tourism where scheduled airline networks prove inadequate. Thailand's hospitality groups and Philippine island destinations generate seasonal peaks requiring wet-lease capacity augmentation.
Leading the category by volume: Business. Growing fastest: Air Ambulance.
End User:
Customer type determines fleet configuration priorities, with VIPs and government clients demanding newer aircraft and corporate buyers optimizing for cost predictability.
- Corporate:Recurring executive mobility contracts with site access requirements across dispersed operations. Indonesian mining and energy conglomerates anchor volume through guaranteed lift for rotation schedules to remote facilities.
- VIPs:High-net-worth individuals requiring privacy, flexibility, and premium cabin configurations. Singapore's wealth concentration drives demand for heavy jets on long-haul connections to Europe and the Middle East.
- Government:Official travel and emergency response missions with sovereign immunity considerations. Thailand and Indonesia maintain dedicated fleets for head-of-state transport and disaster relief coordination.
- Tourists:Resort destination access for luxury leisure where surface infrastructure gaps eliminate scheduled alternatives. Philippine corridors like Palawan and Siargao lack adequate runway infrastructure for commercial jets.
Highest margin concentration: VIPs. Steepest expansion trajectory: Corporate.
Aircraft Type:
Airframe selection maps directly to mission range requirements and airfield infrastructure constraints across Southeast Asia's varied geography.
- Light Jets:Aircraft with 4-8 passenger capacity and 2,000-3,000 nautical mile range optimized for island-hopping routes. Indonesia and the Philippines dominate transaction volume where short runways and limited apron space restrict larger equipment.
- Heavy Jets:12-19 passenger capacity with 6,000-7,500 nautical mile range for intercontinental missions. Singapore and Bangkok concentrate margin pools on long-haul connections to the Middle East and Europe where fuel efficiency and cabin altitude specifications command premium pricing.
- Midsize Jets:Intermediate range and capacity for regional ASEAN connectivity. Cross-border charter operations within the ASEAN Single Aviation Market favor this category for flexibility across varying runway lengths.
- Turboprops:Short-field performance for remote airstrips and amphibious operations. Secondary Indonesian destinations and Philippine resort corridors with unimproved runways require this capability despite lower cruise speeds.
Dominant by transaction count: Light Jets. Gaining share fastest: Heavy Jets.
Booking Channel:
Channel selection reflects customer sophistication and contract scale, with direct relationships displacing intermediaries among large corporate accounts.
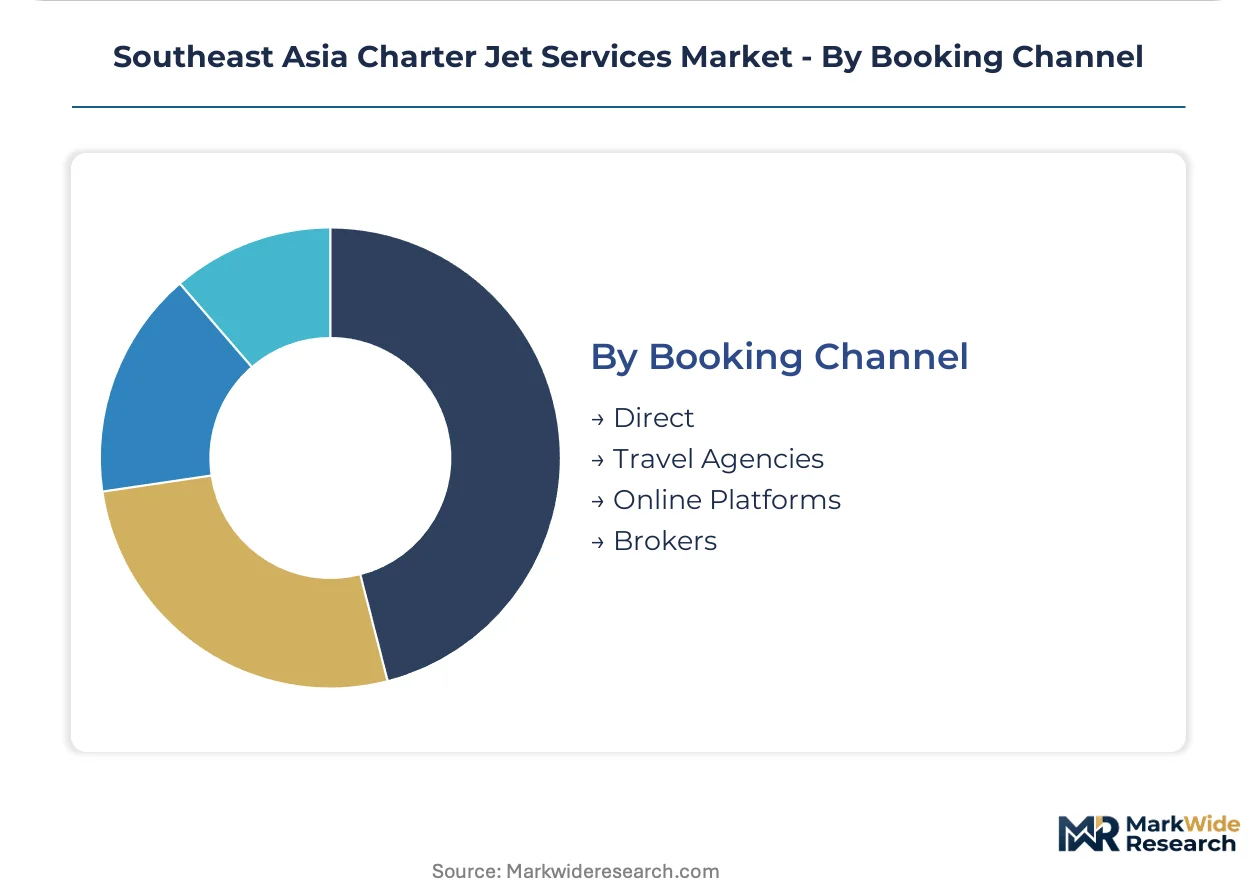
- Direct:Operator-client agreements eliminating brokerage fees and enabling customized service terms. Indonesian mining groups and Thai hospitality chains consolidate preferred operator relationships into annual contracts.
- Brokers:Intermediary networks sourcing capacity across multiple operators for ad-hoc requirements. Singapore maintains regional brokerage concentration though corporate consolidation erodes market share.
- Online Platforms:Digital booking interfaces with real-time availability and transparent pricing. Blockchain-enabled empty leg matching algorithms reduce deadhead costs and improve asset utilization.
- Travel Agencies:Traditional intermediaries packaging charter with ground services for leisure segments. Resort destinations in Thailand and the Philippines rely on this channel for tourist market access.
Largest volume flow: Direct. Expanding most quickly: Online Platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jet fuel refining capacity in Singapore anchors operational economics for charter operators across the archipelago. The city-state's storage and bunkering infrastructure supplies aviation kerosene to regional fleets while its maintenance ecosystem absorbs technical talent from neighboring markets.
Indonesia
Mining conglomerates and energy companies generate recurring demand for executive rotation schedules to remote facilities across the archipelago. The Directorate General of Civil Aviation enforces distinct type-rating requirements that limit crew mobility across ASEAN borders. Jakarta and Surabaya concentrate fleet management operations where operators coordinate island-hopping missions to secondary airstrips.
Singapore
Wealth concentration among high-net-worth individuals drives heavy jet demand for long-haul connections to Europe and the Middle East. The Civil Aviation Authority maintains stringent air operator certificate standards that shape foreign ownership limits and safety audit protocols. Seletar Aerospace Park anchors the regional MRO ecosystem, drawing maintenance technicians from Indonesian and Thai operators.
Thailand
Hospitality groups require guaranteed lift for executive access to resort destinations where surface infrastructure gaps eliminate scheduled alternatives. The Department of Civil Aviation regulates cabotage rights and cross-border charter permissions under evolving national frameworks. Bangkok concentrates premium charter operations while Phuket and Samui generate seasonal peaks requiring wet-lease capacity augmentation.
Philippines
Secondary destinations like Palawan and Siargao lack adequate runway infrastructure for scheduled jets, creating white space for amphibious and short-field charter aircraft. The Civil Aviation Authority of the Philippines oversees foreign operator access and airworthiness standards for medical evacuation configurations. Manila-based operators coordinate resort corridor access while Cebu serves as a hub for central island connectivity.
Malaysia
Secondary city pairs underserved by scheduled carriers sustain domestic charter demand for executive mobility and site access. The Civil Aviation Authority of Malaysia enforces air operator certificate standards that fragment compliance costs for cross-border operators. Kuala Lumpur and Penang concentrate fleet operations where Berjaya Air anchors connectivity to domestic destinations bypassed by trunk carriers.
Southeast Asia Charter Jet Services Market Competitive Landscape
Global majors compete with regional champions across wet-lease and dry-lease arrangements to manage capacity seasonality. The market fragments across national aviation authorities with divergent certification requirements, forcing operators to maintain parallel compliance systems. Three archetypes dominate: Singapore-based fleet managers leveraging maintenance ecosystems, Thai and Indonesian operators anchoring archipelagic connectivity, and legacy flag carriers extending MRO capabilities to private clients. Competitive moves concentrate on strategic partnerships with local maintenance providers and portfolio diversification into air ambulance configurations.
Within the fleet management tier, OJets Pte Ltd. exemplifies Singapore-based operators leveraging the city-state's technical infrastructure. Berjaya Air Sdn. Bhd. occupies a position among Malaysian operators focused on secondary domestic corridors. Thai Airways International Public Company Ltd. represents flag carrier incumbents extending crew training and maintenance capabilities to charter clients.
| Leading Market Players |
|---|
| OJets Pte Ltd. |
| Berjaya Air Sdn. Bhd. |
| Thai Airways International Public Company Ltd. (THAI) |
| PhilJets Aero Charter Corp. |
| Phenix Jet |
| Singapore Air Charter Pte Ltd. |
| EastIndo |
| MJets Limited |
| Advance Aviation Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Maintenance technician concentration in Singapore's Seletar Aerospace Park feeds labor-cost differentials that widen pricing-tier spreads between premium heavy-jet operations and economy turboprop services across the archipelago.
Pricing Analysis
All-inclusive crew-fuel-insurance bundling dominates transaction structures, with unbundled positioning fees and empty-leg repositioning costs creating price differentiation between guaranteed-availability corporate contracts and ad-hoc leisure bookings. Premium cabin configurations and newer airframes with lower cabin altitudes command spreads over standard interiors, while fuel price volatility compresses margins on fixed-rate annual commitments. Pricing pressure stems from Singapore jet kerosene benchmark swings that expose operators to input cost spikes. Corporate travel managers demonstrate lowest price sensitivity through locked-in annual minimums, while leisure tourists booking through travel agencies show highest elasticity to per-hour rate fluctuations.
Supply Chain Analysis
Freight costs for airframe components and avionics modules concentrate supply chain leverage in Singapore, Malaysia, and the United States where OEM distribution networks anchor parts availability. Jet engine turbines, flight control systems, and connected health-monitoring avionics draw from concentrated aerospace manufacturing clusters. Single-source vulnerability in specialized medical-fit-out certification from Indonesia's DGCA extends modification timelines and creates bottlenecks for air ambulance operators. Distribution runs through Singapore-based MRO hubs that coordinate spare parts logistics across dispersed island operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
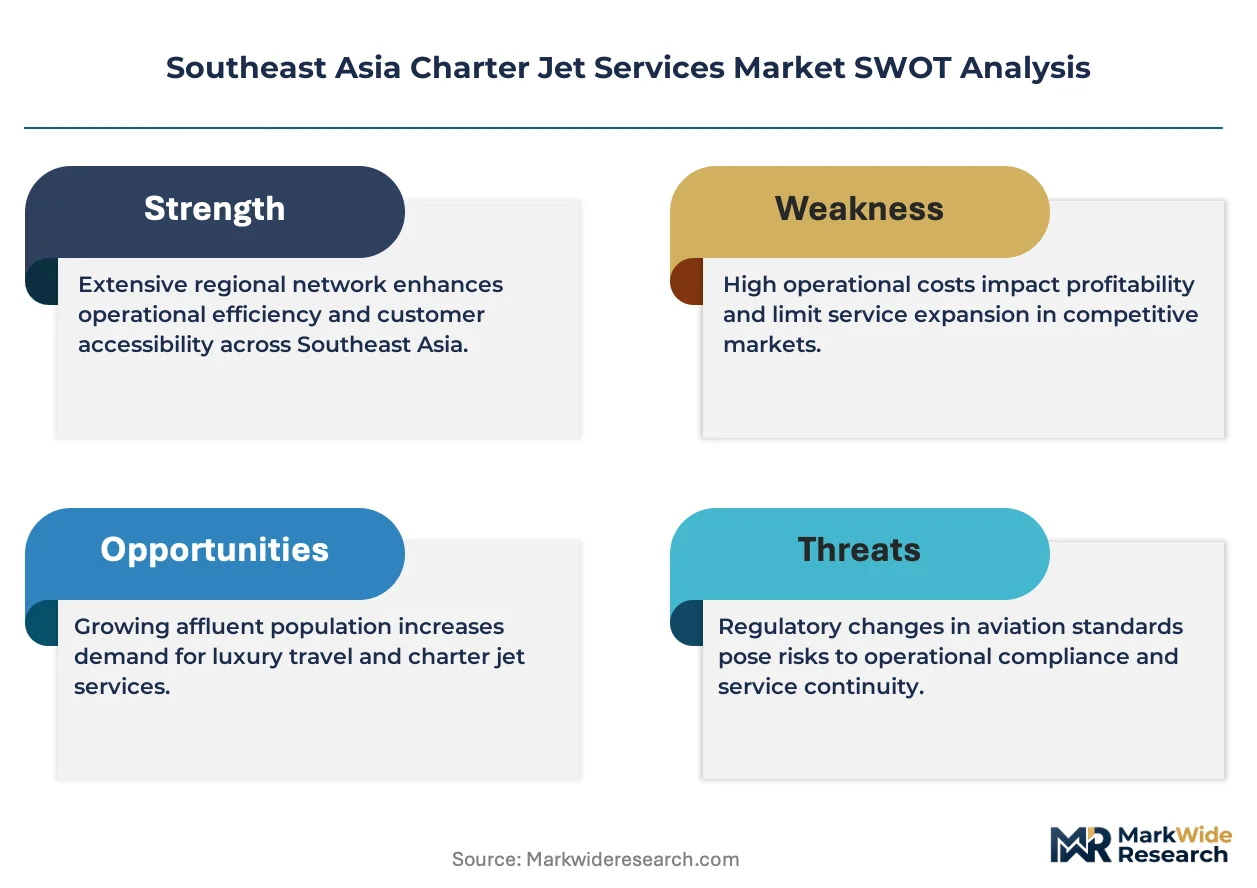
This market reads as a cost-of-compliance story where Indonesia's tightening foreign air operator certificate equivalency requirements erect barrier-to-entry moats favoring established players with local maintenance partnerships.
For Market Incumbents: Acquire wet-lease capacity agreements ahead of Indonesia's DGCA regulatory tightening to lock in cross-border operational flexibility before foreign lessors face restrictions. Consolidate preferred operator relationships with Indonesian mining conglomerates through longer-term dry-lease structures that displace brokerage intermediaries. Threat substitution from blockchain-enabled empty leg matching platforms demands defensive investment in proprietary digital booking interfaces. For New Entrants and Emerging Players: Begin with Philippine resort corridors like Palawan and Siargao where runway infrastructure gaps eliminate scheduled carrier competition and create white space for amphibious aircraft operations. Target medical evacuation networks in Indonesia's archipelagic corridors where specialized airworthiness certifications extend modification timelines and deter rapid competitive entry. Go-to-market angle should emphasize rapid-response crew scheduling partnerships with existing hospital networks. For Investors and Strategic Acquirers: Re-rating potential sits with Singapore-based fleet managers given carbon disclosure mandate harmonization across ASEAN civil aviation authorities that will reward newer, more efficient fleets with premium contract access. Long-term viability favors operators with backward integration into maintenance ecosystems rather than pure brokerage plays. Signal to watch is pending third-party liability insurance minimum harmonization that will alter capital requirements and consolidation timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Air Operator Certificate Investment | Indonesia's DGCA tightening creates compliance moats for early movers with local partnerships. |
| Maintenance Ecosystem Integration | Singapore's Seletar Aerospace Park anchors regional MRO talent absorption and technical reliability. |
| Digital Platform Development | Blockchain-enabled empty leg matching reduces deadhead costs and displaces traditional brokerage channels. |
| Air Ambulance Capability Expansion | Specialized medical fit-outs command premium pricing from corporate risk managers and high-net-worth individuals. |
| Fleet Renewal Acceleration | Pending ASEAN emissions disclosure harmonization rewards newer aircraft with preferential contract access. |
Research Methodology
Document review covered civil aviation authority regulatory filings, fleet registration databases, and corporate travel procurement disclosures, complemented by interviews with charter operations directors, aircraft maintenance engineers, and aviation insurance underwriters. Secondary validation drew from Indonesia's DGCA air operator certificate records, Singapore's CAAS safety audit protocols, and Thailand's Department of Civil Aviation cabotage rulings. Bottom-up transaction volume modeling triangulated against top-down market sizing from aviation kerosene consumption patterns and MRO labor statistics.
Historical fleet deployment patterns cross-referenced against executive mobility demand panels informed the projection framework across the analysis window. Segmentation dimensions modeled encompass service type, aircraft category, end-user archetype, and booking channel complexity. CAGRs derived from weighted average fleet expansion rates and corporate contract renewal trajectories. Forecast inputs incorporated ASEAN Single Aviation Market harmonization timelines and national civil aviation framework evolution.
Underlying measurement precision varies by segment; on-demand charter and business service types carry tighter precision than nascent air ambulance configurations where specialized equipment approvals create data sparsity. Forecasts reflect assumptions around regulatory harmonization pace and jet fuel price trajectory stability. Stakeholders should weight assumptions against their own operating context and monitor Indonesia's DGCA foreign operator equivalency enforcement as a critical revision trigger.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tourist Transport Services
Europe Charter Jet Services Market
Tourist Transport Services
UK Low Cost Airlines Market
Tourist Transport Services
Airport Ground Transportation Market
Tourist Transport Services
Yacht Rental Market
Tourist Transport Services
Boat Rental Market
Tourist Transport Services
Travel Transportation Market
Tourist Transport Services
Helicopter Tourism Market
Tourist Transport Services
India International Express Service Market
Tourist Transport Services
Pre-Book Airport Transfer Market
Tourist Transport Services
Low-Cost Carrier (LCC) Market
Tourist Transport Services
Italy Car Rental Market