
 Boat Rental Market | 2026-2036
Boat Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Boat Rental Market Analysis
Buyer fragmentation across leisure travelers is expanding the addressable base beyond traditional charter clients toward casual users seeking hourly and daily access. SamBoat leverages its peer-to-peer platform architecture to aggregate fragmented supply across European marinas. GetMyBoat anchors its position through geographic density in North American recreational boating corridors. Click&Boat competes on fleet breadth, spanning sailing yachts through jet skis.
Boat rental denotes the short-term commercial provision of watercraft—sailing yachts, motorboats, houseboats, and jet skis—typically governed by hull-length classifications, passenger capacity limits, and maritime safety certifications, serving leisure navigation, fishing, water sports, and event hosting. Hourly and daily service types command the transaction volume, while weekly and long-term rentals capture proportionally higher per-booking value with lower churn. Motorboats lead the type dimension on accessibility and license flexibility, whereas sailing yachts concentrate margin pools in premium coastal destinations.
The US Coast Guard enforces operator certification and vessel inspection standards that shape fleet eligibility and insurance underwriting. The EU's F-Gas Regulation and REACH framework constrain refrigerant and coating choices for operators maintaining vessels in European waters. Stakeholders must monitor regulatory divergence between jurisdictions to calibrate fleet deployment and compliance investment.
Market Dynamics
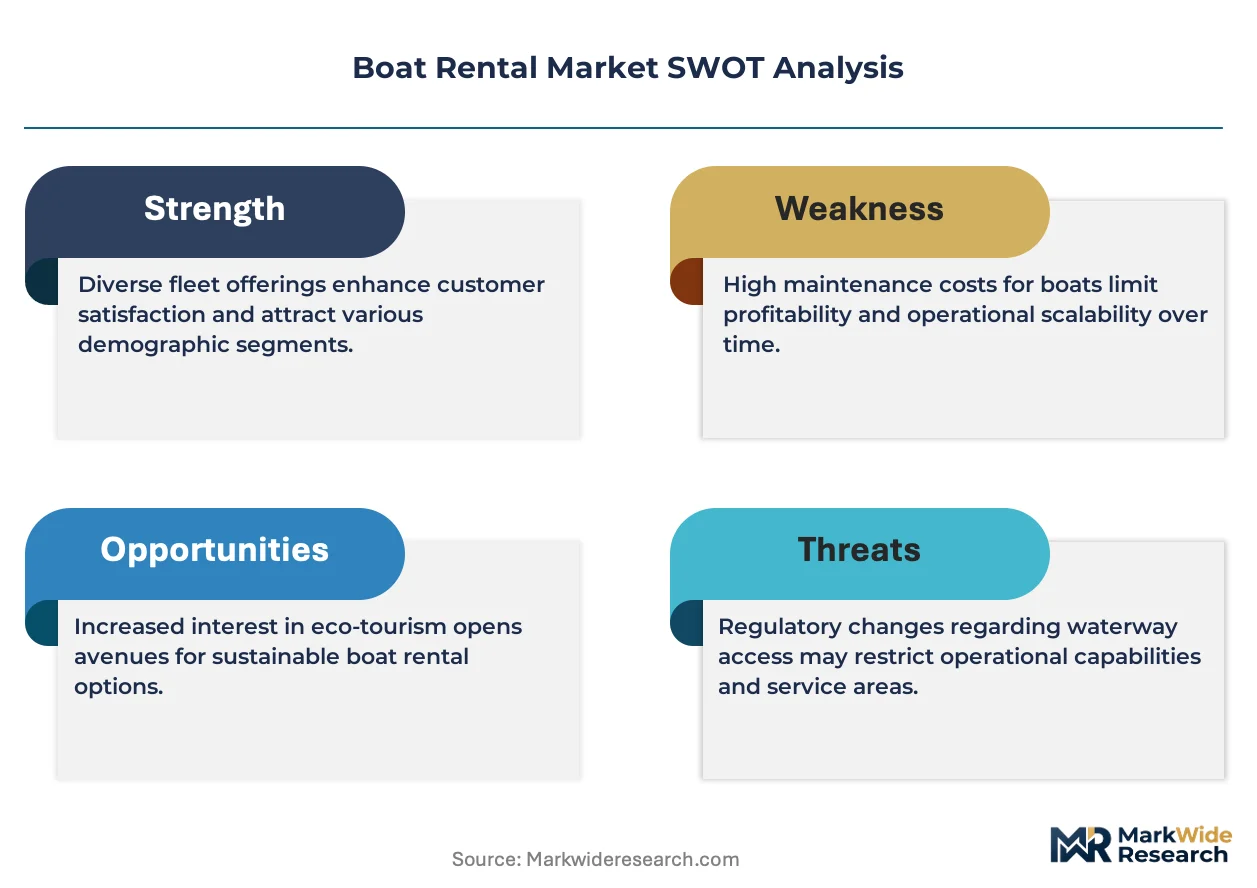
The boat rental market is experiencing structural pressure from the EU's F-Gas Regulation, which is forcing fleet operators to retrofit marine refrigeration systems and requalify vessels for European waters. This compliance burden is reshaping capital allocation across Mediterranean marinas and accelerating consolidation among smaller charter operators.
Growth Catalysts
- Peer-to-Peer Platform Architecture:Digital aggregation platforms are unlocking idle vessel capacity across European marinas. Hourly and daily booking granularity is expanding the addressable customer base beyond traditional week-long charter clients.
- REACH Framework Compliance Incentives:Operators investing in compliant coating and refrigerant systems gain preferential mooring access in Greek, Croatian, and Spanish ports. Early compliance is converting into fleet utilization premiums.
- License Flexibility for Motorboats:Reduced certification requirements for small-craft operation in coastal zones are lowering the skill barrier for casual users. Day-trip demand is concentrating in accessible motorboat categories.
Market Restraints
- Marine Refrigerant Input Volatility:F-Gas phasedown schedules are compressing supply windows for HFC alternatives. Fleet operators face unpredictable retrofit timing and stranded asset risk on older vessels.
- Marina Berth Concentration:Premium mooring capacity clusters in Greek islands and Croatian archipelagos. Supply bottlenecks in high-season corridors are capping fleet expansion for independent operators.
- Technical Limitation in Electrification:Battery energy density constraints are restricting electric propulsion to sub-10-meter day boats. Sailing yacht and houseboat segments remain tethered to diesel auxiliary systems.
Strategic Opportunities
- Underpenetrated Adriatic Secondary Ports:Montenegrin and Albanian coastal infrastructure is upgrading marina facilities. First-mover platforms can establish supply density ahead of demand maturation.
- Event Hosting Application Expansion:Corporate retreat and wedding charter demand is decoupling from traditional leisure seasonality. Specialized vessel configurations are capturing premium pricing in off-peak months.
- CSRD-Aligned Fleet Disclosure:Large European operators can leverage sustainability reporting mandates to differentiate carbon-transparent offerings. ESG-conscious corporate clients are prioritizing documented environmental performance.
Industry Challenges
- Maritime Safety Certification Backlogs:National maritime authorities in Spain and Italy are processing vessel inspections at extended lead times. Fleet readiness for peak season is degrading due to administrative bottlenecks.
- Insurance Underwriting Complexity:Peer-to-peer rental models are forcing carriers to recalibrate risk models for transient operator profiles. Premium volatility is compressing net margins for platform-mediated transactions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Boat Rental Market |
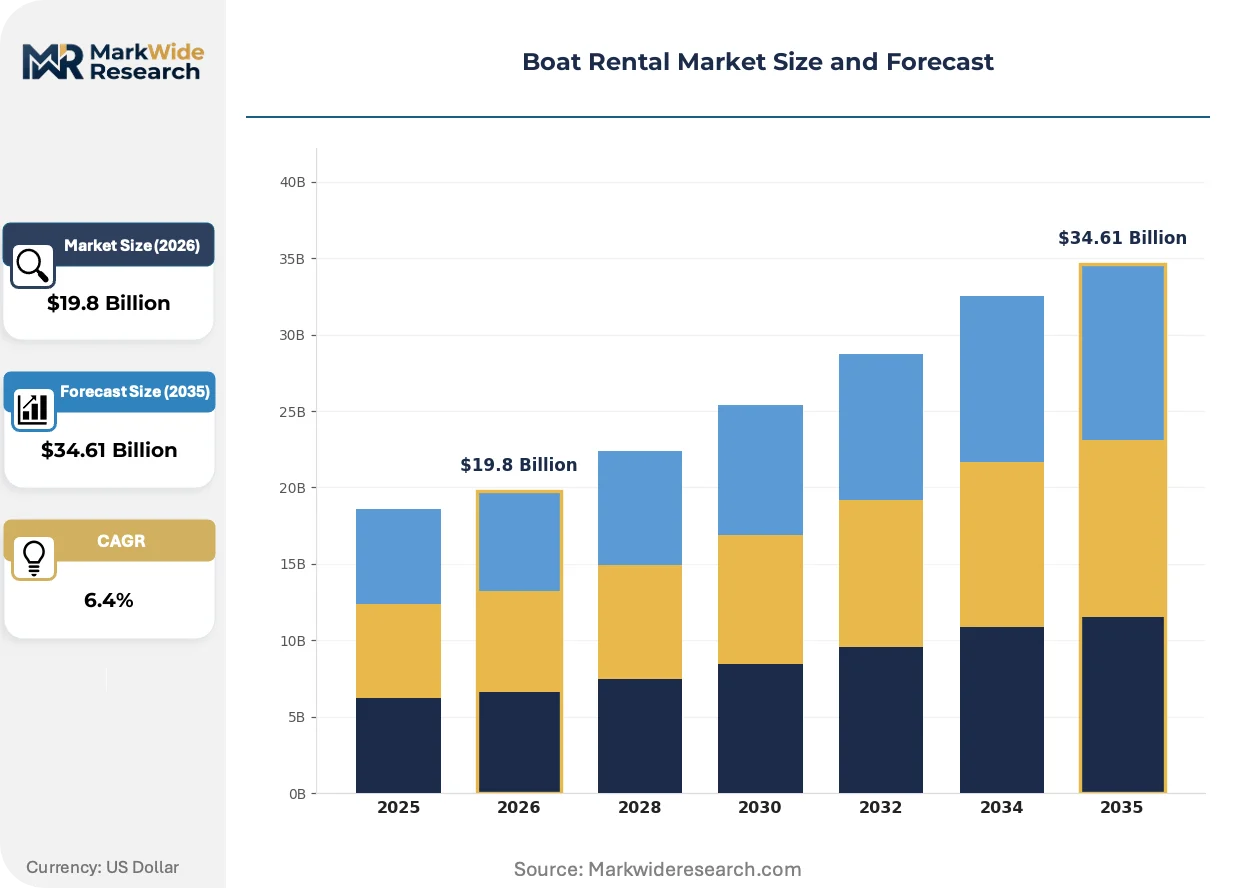
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $34.61 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Sailing Yachts, Motorboats, Houseboats, Jet Skis Customer Type: Tourists, Locals, Corporate Clients, Event Planners Service Type: Hourly Rentals, Daily Rentals, Weekly Rentals, Long-term Rentals End Use: Leisure Activities, Fishing Trips, Water Sports, Events |
| Companies Covered | SamBoat, Sailo, GetMyBoat, Boatbookings, Freedom Boat Club, Boatsetter, Dream Yacht Worldwide, Le Boat, Click&Boat, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Boat Rental Market Emerging Trajectories
Digital infrastructure is modularizing fleet management and customer acquisition in the boat rental sector. Platform intermediation is compressing search friction and enabling real-time availability matching across fragmented marina supply.
Telematics integration is modularizing vessel monitoring and predictive maintenance workflows. Fleet operators in Croatia and Greece are deploying IoT-enabled engine and hull sensors to reduce downtime and optimize turnaround intervals. The technology is modularizing operational oversight and enabling remote diagnostics that cut on-site technical labor requirements.
The EU F-Gas Regulation is tightening refrigerant phase-down schedules for marine air conditioning and cold storage systems. Operators maintaining vessels in Spanish, Italian, and Greek waters must transition to lower-GWP alternatives or face port access restrictions. The sailing yacht segment is absorbing disproportionate compliance costs due to integrated refrigeration system complexity.
Hourly booking granularity is displacing traditional week-long charter minimums among casual leisure travelers. Platform users in Mediterranean coastal economies are prioritizing spontaneous, short-duration access over advance-planned extended itineraries. Greek island-hopping corridors are emerged as the geography where this behavioral shift is most pronounced, with peak-day transaction volumes concentrating in sub-4-hour rental windows.
Boat Rental Market Segmentation
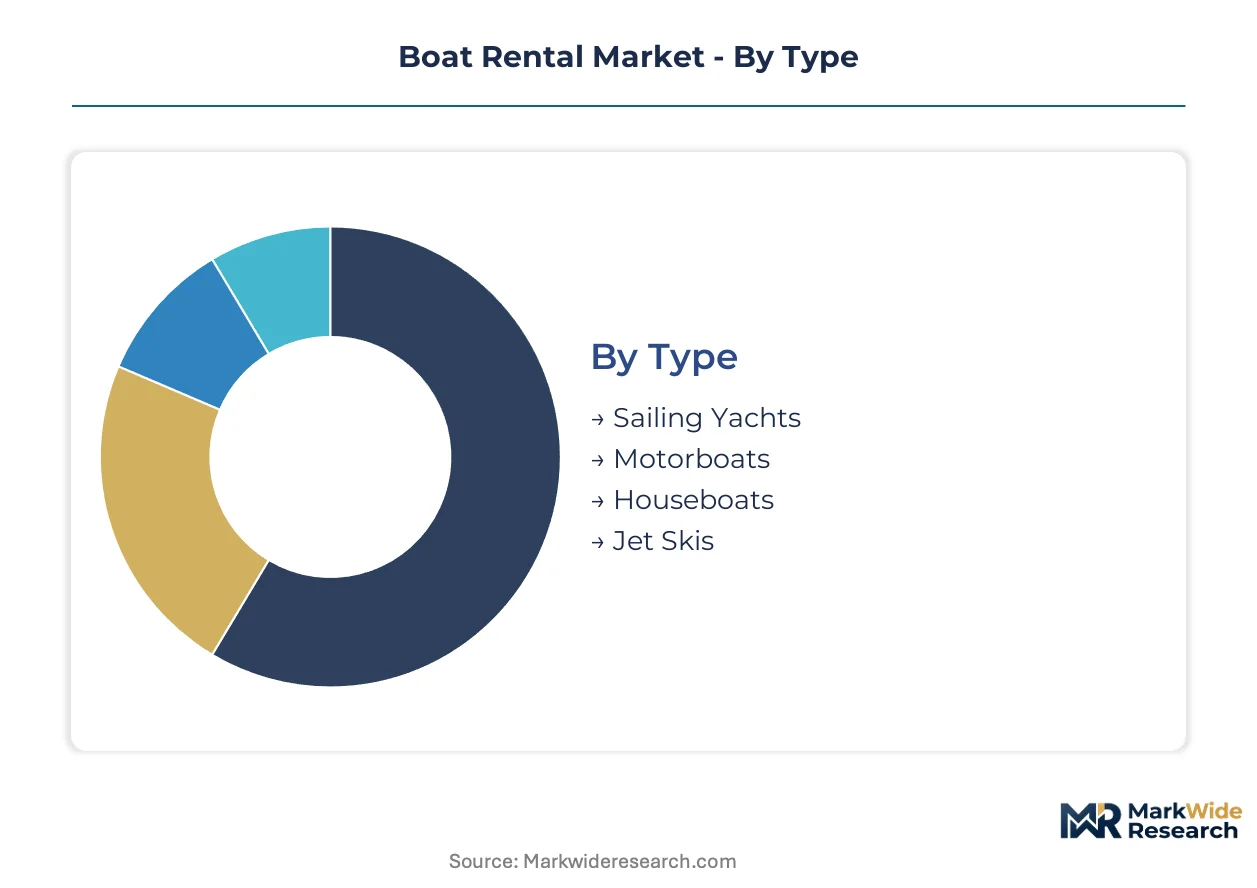
Segmentation in boat rental reveals how vessel configuration, booking duration, and customer profile dictate pricing power and utilization patterns. Operators calibrate fleet composition and marina deployment against these dimensions to capture margin in high-season corridors.
Type:
Buyer differentiation by watercraft category hinges on licensing requirements, operational complexity, and destination suitability across Mediterranean and North American recreational corridors.
- Sailing Yachts:These vessels integrate auxiliary diesel engines with sail propulsion systems, requiring certified skippers for most jurisdictions. Demand clusters in Greek island-hopping routes and Croatian archipelagos where multi-day itineraries dominate, though F-Gas Regulation compliance on integrated refrigeration systems elevates maintenance overhead.
- Motorboats:Open-deck and cabin cruisers with outboard or inboard engines dominate hourly and daily transaction volumes. Coastal Spain and Florida see concentrated day-trip demand from casual users benefiting from reduced certification thresholds for sub-10-meter craft.
- Houseboats:Self-contained living vessels with sleeping quarters and galley facilities cater to extended inland waterway cruising. Lake districts in Germany and the Netherlands anchor European demand.
- Jet Skis:Personal watercraft with two-stroke or four-stroke engines serve adrenaline-focused water sports segments. Beach resort zones in Portugal and California absorb peak seasonal volumes.
Motorboats lead volumes today; sailing yachts are gaining share fastest in premium coastal destinations.
Customer Type:
Revenue stability varies sharply by customer category, with corporate and event segments offering off-peak booking counterweights to seasonal leisure volatility.
- Tourists:International leisure travelers from Northern Europe and North America drive peak-season capacity absorption in Mediterranean marinas. Booking patterns concentrate in July and August with high advance-planning ratios.
- Locals:Resident recreational boaters in coastal Spain, Italy, and Greece provide year-round demand foundation with higher repeat rates and lower customer acquisition costs.
- Corporate Clients:Team-building retreats and executive entertainment charters operate outside traditional leisure seasonality. Specialized vessel configurations with AV equipment and catering infrastructure command premium pricing in shoulder months.
- Event Planners:Wedding and celebration charters require decorated vessels with photography-friendly layouts. Croatian and Greek operators report expanding inquiry volumes for multi-boat flotilla arrangements.
Tourists dominate transaction counts; corporate clients are expanding most quickly as operators target off-peak revenue diversification.
Service Type:
Duration-based segmentation determines fleet turnover economics and labor scheduling intensity across marina operations.
- Hourly Rentals:Sub-4-hour windows dominate jet ski and small motorboat transactions. Greek platforms report peak-day volumes concentrating in spontaneous booking corridors where digital availability matching reduces search friction.
- Daily Rentals:Full-day charters capture family and group leisure demand in Croatian coastal economies. Turnaround logistics require morning preparation and evening cleaning protocols that constrain fleet utilization ceilings.
- Weekly Rentals:Seven-day minimums concentrate in sailing yacht categories with skipper-inclusive packages. Italian and Spanish bareboat charter operators anchor revenue planning around these extended itineraries.
- Long-term Rentals:Monthly or seasonal contracts serve snowbird populations in Florida and resident expatriates in Portuguese Algarve. Reduced per-day rates trade off against guaranteed utilization and minimized marketing spend.
Hourly and daily rentals together lead volumes today; weekly rentals retain highest per-booking value with lowest churn characteristics.
End Use:
Application-driven demand shapes vessel specification requirements and seasonal timing across European and North American waterways.
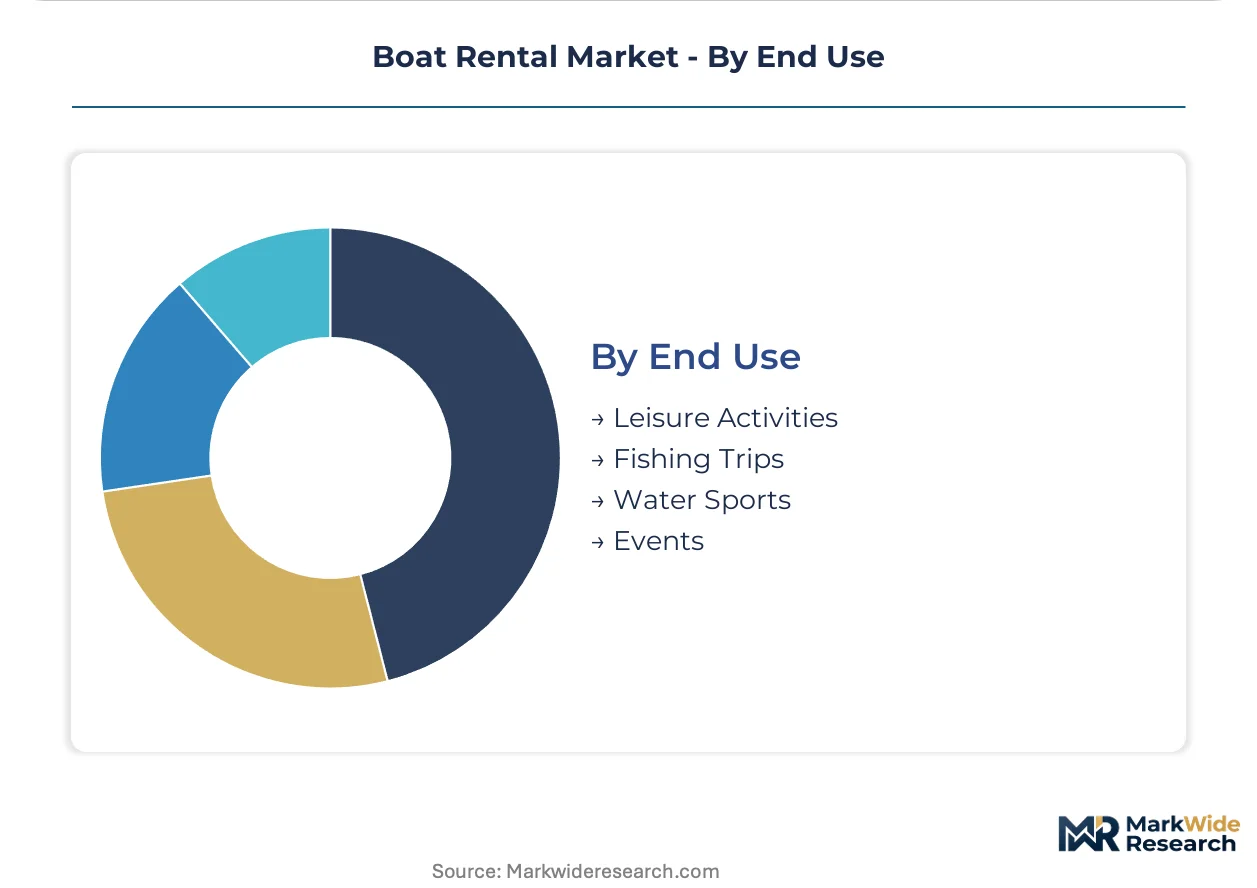
- Leisure Activities:General sightseeing and coastal cruising absorb the broadest vessel range. Mediterranean island circuits and Scandinavian fjord exploration represent distinct geographic demand poles.
- Fishing Trips:Specialized craft with rod holders, live wells, and fish-finding electronics serve angling communities. Chesapeake Bay and North Sea operators maintain dedicated sub-fleets for this segment.
- Water Sports:Wakeboarding, waterskiing, and tubing demand high-torque motorboats with towing equipment. Lake Tahoe and Lake Como see concentrated equipment rental bundling.
- Events:Corporate hospitality and private celebrations require catering-compatible galleys and passenger capacity optimization. Sunset cruise positioning in Santorini and Amalfi commands peak pricing premiums.
Leisure activities lead volumes today; events are climbing the fastest as operators monetize off-peak capacity through specialized configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Greece captures disproportionate Mediterranean transaction density while Croatia builds comparable marina infrastructure at lower operational cost bases. This divergence shapes fleet deployment strategies across Southern European waters.
United States
Florida's recreational boating corridors absorb peak seasonal demand from snowbird populations and domestic tourists. The US Coast Guard enforces operator certification standards that filter fleet eligibility and shape insurance underwriting requirements. Miami and Fort Lauderdale anchor the densest charter operator clusters, with hourly motorboat rentals dominating transaction volumes.
Greece
Island-hopping itineraries concentrate sailing yacht demand across the Cyclades and Ionian archipelagos. The EU's F-Gas Regulation imposes refrigerant compliance deadlines on vessels operating in Greek ports. Athens-based operators and Santorini marina clusters are retrofitting marine air conditioning systems to maintain mooring access.
Croatia
Adriatic coastline development is expanding marina capacity ahead of demand maturation in secondary ports. REACH framework compliance on marine coatings creates preferential access incentives for early-adopting fleet operators. Split and Dubrovnik anchor the core charter infrastructure, while Montenegrin border zones emerge as underpenetrated expansion corridors.
Spain
Balearic Islands and Costa del Sol corridors absorb international leisure demand with concentrated peak-season capacity constraints. Spanish maritime authorities are processing vessel inspection backlogs that degrade fleet readiness timelines. Barcelona and Palma de Mallorca clusters are investing in telematics-enabled fleet management to compress turnaround intervals.
France
Corsican and Côte d'Azur cruising grounds capture premium sailing yacht demand with extended itinerary preferences. The EU's CSRD disclosure mandates are pressuring large operators to document carbon-transparent fleet performance. Marseille and Nice anchor the primary charter infrastructure, with corporate event hosting applications expanding in shoulder months.
Boat Rental Market Vendor Landscape
Mediterranean platform operators anchor one tier; North American membership and rental specialists hold comparable scale with divergent monetization models. Market structure tilts toward platform-mediated fragmentation rather than consolidated fleet ownership, with digital intermediaries capturing transaction economics from dispersed vessel supply. Three archetypes dominate: peer-to-peer aggregation platforms, traditional fleet-owning charter operators, and membership-based boat clubs. Competitive moves concentrate on geographic density building and regulatory compliance differentiation rather than vertical integration.
Among platform-based intermediaries, SamBoat, GetMyBoat, and Click&Boat exemplify the peer-to-peer aggregation archetype. These operators occupy positions defined by digital infrastructure rather than captive vessel assets, with revenue models tied to transaction fees across fragmented supply bases. Their competitive positioning depends on marina network density and real-time availability matching algorithms rather than fleet ownership scale.
| Leading Market Players |
|---|
| SamBoat |
| Sailo |
| GetMyBoat |
| Boatbookings |
| Freedom Boat Club |
| Boatsetter |
| Dream Yacht Worldwide |
| Le Boat |
| Click&Boat |
| Others |
Supply Flow & Price Mechanics
The EU's F-Gas Regulation gates both qualified supply and premium-tier pricing access in European waters, as fleet operators must retrofit marine refrigeration systems to maintain port eligibility while compliant vessels command mooring premiums in Greek and Croatian marinas. This environmental mandate stratifies the market into certified and non-certified supply tiers, with early adopters capturing pricing power through preferential berth access and extended booking windows.
Pricing Analysis
Capacity additions in Montenegrin and Albanian marinas are reshaping price floors across the Adriatic corridor, compressing margins for established operators in Split and Dubrovnik while creating entry points for cost-optimized entrants. Three-tier pricing structure across premium, standard, and economy levels prevails, with F-Gas compliance status and skipper certification grade serving as primary differentiation drivers. Pricing pressure stems from platform-mediated commission structures that squeeze net margins on peer-to-peer transactions. Tourist segments exhibit highest price sensitivity, whereas corporate event clients absorb premium tiers with minimal elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Italian and Spanish maritime authorities processing vessel inspection certifications, creating administrative bottlenecks that degrade fleet readiness timelines ahead of peak season. Manufacturing concentration clusters in France, Germany, and Poland for marine propulsion systems, while hull fabrication draws from Turkish and Croatian shipyards. Supply chain risk centers on refrigerant input volatility under F-Gas phasedown schedules, compressing availability windows for HFC alternatives. Distribution runs through marina-based charter operators and digital aggregation platforms with divergent margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The boat rental market functions as a stable compounder, with peer-to-peer platform architecture driving steady supply aggregation and demand expansion across fragmented European marinas.
For Market Incumbents: Acquire underutilized vessel fleets in Montenegrin and Albanian coastal zones to preempt supply density building by emerging platforms. Consolidate inspection certification relationships with national maritime authorities in Spain and Italy to compress turnaround intervals. Defensive positioning against regulatory divergence requires parallel compliance investment across EU F-Gas and REACH frameworks. For New Entrants and Emerging Players: The price-point gap between premium skippered sailing yachts and economy self-drive motorboats creates white-space opportunity for mid-tier cabin cruisers with reduced certification thresholds. Montenegrin secondary ports offer the most penetrable geography, with infrastructure upgrading ahead of demand maturation. A telematics-enabled fleet management angle reduces operational overhead and accelerates turnaround economics. For Investors and Strategic Acquirers: Roll-up economics work for regional marina operators because fragmented supply bases concentrate transaction value in platform intermediaries rather than vessel assets. Long-term viability frames around 5-10 year digital infrastructure substitution for traditional fleet ownership. Acquisition targets should show berth concentration in high-season corridors. The signal to watch is F-Gas compliance cost absorption rates across sailing yacht sub-fleets.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Fleet Integration | IoT-enabled engine monitoring cuts downtime in Croatian and Greek marina operations. |
| F-Gas Compliance Retrofit | Refrigerant system upgrades secure preferential mooring access in EU ports. |
| Secondary Port Expansion | Montenegrin and Albanian berth investments capture demand ahead of maturity. |
| Corporate Event Specialization | AV-equipped vessels monetize off-peak capacity through wedding and retreat charters. |
| Platform Supply Aggregation | Digital intermediaries capture transaction economics from fragmented vessel owners. |
Methodological Framework
Direct dialogue with marina operators, fleet managers, platform engineers, and maritime authority inspectors grounded qualitative insights, cross-referenced against customs vessel registration data, EU regulatory filings, national tourism board statistics, and platform transaction disclosures. Bottom-up triangulation validated supply-side estimates against top-down demand absorption metrics across Mediterranean coastal economies.
Bottom-up modeling built from vessel inventory counts, berth capacity, and seasonal utilization rates, while top-down analysis calibrated against tourism expenditure flows and recreational boating participation surveys. Segmentation dimensions spanned watercraft type, service duration, customer archetype, and end-use application, with CAGRs derived from fitted trend extrapolation moderated by regulatory phase-in schedules. Forecast inputs incorporated F-Gas retrofit timelines and marina infrastructure investment pipelines.
Caveats apply where regulatory enforcement variance, refrigerant supply disruption, or platform commission structure shifts could materially shift the outlook. Forecasts embed assumptions about inspection processing efficiency and telematics adoption curves that may revise with administrative or technological change. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tourist Transport Services
Pre-Book Airport Transfer Market
Tourist Transport Services
Airport Ground Transportation Market
Tourist Transport Services
Travel Transportation Market
Tourist Transport Services
Yacht Rental Market
Tourist Transport Services
Italy Car Rental Market
Tourist Transport Services
Southeast Asia Charter Jet Services Market
Tourist Transport Services
Helicopter Tourism Market
Tourist Transport Services
Europe Charter Jet Services Market
Tourist Transport Services
India International Express Service Market
Tourist Transport Services
UK Low Cost Airlines Market
Tourist Transport Services
Low-Cost Carrier (LCC) Market