
 Pre-Book Airport Transfer Market | 2026-2036
Pre-Book Airport Transfer Market Size, Share, and Industry Trends Forecast 2026-2036
Pre-Book Airport Transfer Market Outlook
Market Context
App-based distribution is fragmenting across overlapping platforms and direct-to-consumer websites, eroding the dominance of traditional travel agency channels. Blacklane controls premium corporate accounts through guaranteed pricing and loyalty integrations. Jayride leverages aggregation technology to sustain volume across fragmented local operator networks. GetTransfer competes on price transparency with its bidding model for intercity and airport routes.
Technical Definition and Segment Structure
A pre-book airport transfer is a reserved ground transportation service between an airport terminal and a designated destination, typically confirmed hours or days in advance with fixed pricing, vehicle class allocation, and driver details provided prior to arrival. The service operates through centralized dispatch systems integrating flight tracking APIs, dynamic fleet allocation algorithms, and real-time traffic routing to minimize passenger wait times and missed connections. Private car bookings anchor revenue across most corridors due to reliability premiums, while shared shuttle services occupy the price-sensitive leisure segment with thinner margins. Luxury vehicle demand concentrates in corporate client portfolios where policy compliance and receipt automation outweigh cost considerations. Mobile app channels lead booking growth, displacing phone reservations as the default interface for younger demographics and repeat travelers.
Regulatory Environment and Outlook
The EU Green Deal and local emissions frameworks in Germany and France are mandating fleet electrification timelines that reshape operator capital deployment and vehicle procurement strategies. The U.S. Department of Transportation enforces accessibility standards under the Air Carrier Access Act, requiring equivalent service for passengers with disabilities across pre-book platforms. Stakeholders must monitor how evolving carbon reporting obligations under the Corporate Sustainability Reporting Directive alter corporate travel procurement criteria and supplier qualification thresholds.
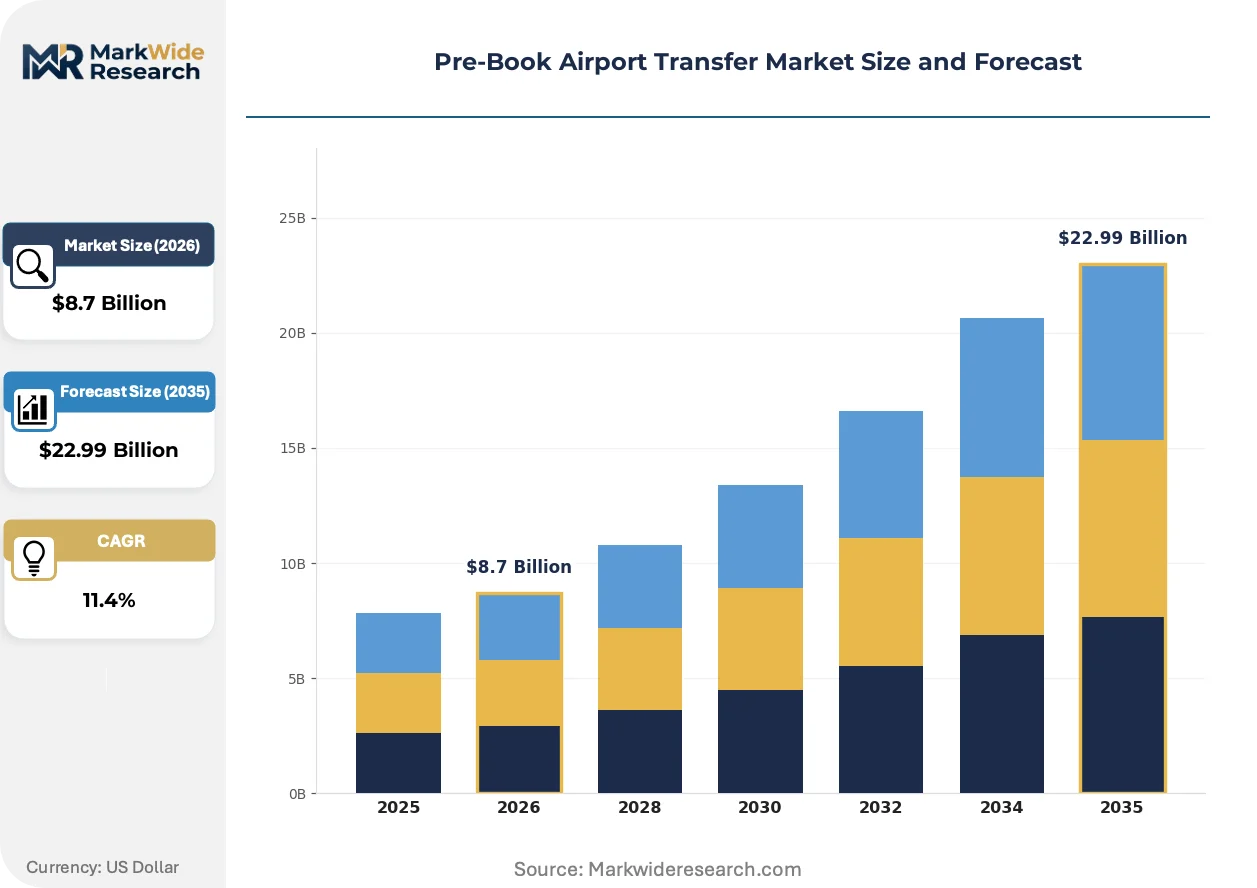
Market Dynamics
Fixed-rate pricing guarantees are displacing variable on-demand models across corporate travel corridors. Fleet operators now prioritize electric and hybrid vehicle procurement to satisfy tightening emissions frameworks while securing long-term contracts with enterprise accounts.
Growth Catalysts
- EU Green Deal mandates:Fleet electrification timelines in Germany and France accelerate operator capital deployment toward zero-emission vehicle procurement, creating procurement advantages for compliant suppliers.
- Corporate travel policy reform:Travel managers now mandate pre-booked ground transport with automated receipt generation, eliminating expense report friction and consolidating vendor relationships.
- Flight tracking API integration:Real-time arrival data synchronization reduces passenger wait times and missed connections, improving net promoter scores among frequent business travelers.
Market Restraints
- Vehicle procurement cost inflation:Electric and luxury fleet acquisition requires 40-60% higher capital outlay versus internal combustion equivalents, compressing operator margins during transition periods.
- Driver supply concentration:Licensed chauffeur availability clusters in metropolitan corridors like Dubai, Frankfurt, and New York, leaving secondary airports underserved during peak demand windows.
- Platform commission structures:Aggregator fees of 15-25% per booking erode profitability for small local operators dependent on third-party demand generation.
Strategic Opportunities
- Corporate Sustainability Reporting Directive compliance:European-headquartered enterprises now require Scope 3 emissions documentation from ground transport suppliers, creating qualification barriers for non-compliant competitors.
- Multi-modal itinerary bundling:Integration with rail and ride-hail APIs allows operators to capture door-to-door journey spend currently fragmented across separate booking channels.
- Accessibility service expansion:ADA and Air Carrier Access Act equivalent service mandates in the United States create dedicated vehicle demand for wheelchair-accessible and sensory-accommodated transport.
Industry Challenges
- Legacy dispatch system integration:Proprietary fleet management software from the 2010s lacks open API architecture, forcing expensive middleware development for real-time booking synchronization.
- Chauffeur certification pipeline gaps:Commercial driver licensing and hospitality training programs in the United Arab Emirates and Germany fail to match fleet expansion timelines, creating service quality variance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pre-Book Airport Transfer Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Private Car, Shared Shuttle, Luxury Vehicle, Minivan Customer Type: Business Travelers, Tourists, Families, Corporate Clients Booking Channel: Mobile App, Website, Travel Agency, Phone Reservation Vehicle Type: Sedan, SUV, Van, Coach |
| Companies Covered | SIXT Ride, GetTransfer, Transfeero, Jayride, MyTransfers, Blacklane, Holiday Taxis, Klook, AirportTransfer.com, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pre-Book Airport Transfer Market Strategic Shifts
Artificial intelligence and electrification are converging to reshape fleet operations and customer interface design. Operators now compete on predictive service delivery rather than price alone.
Dynamic pricing algorithms are migrating from revenue management systems into customer-facing booking interfaces. Corporate travel managers now encounter surge-adjusted quotes that conflict with fixed-rate policy requirements. Blacklane and similar premium platforms resist this migration, preserving guaranteed pricing as a competitive wedge against aggregator volatility.
The EU Green Deal's 2035 zero-emission vehicle mandate is forcing fleet replacement cycles to compress from seven years to four years. German operators face KBA certification requirements for commercial electric vehicle deployment that lag actual model availability. Premium corporate accounts in Frankfurt and Munich now specify electric vehicle class in procurement tenders, ahead of regulatory deadlines.
Mobile app channels are capturing booking share from phone reservations and travel agent intermediation. Business travelers under forty default to self-service interfaces with stored payment and preference profiles. This behavioral shift concentrates volume with platforms offering loyalty program integrations, particularly in United States corridors serving technology and finance sectors.
Pre-Book Airport Transfer Market Segmentation
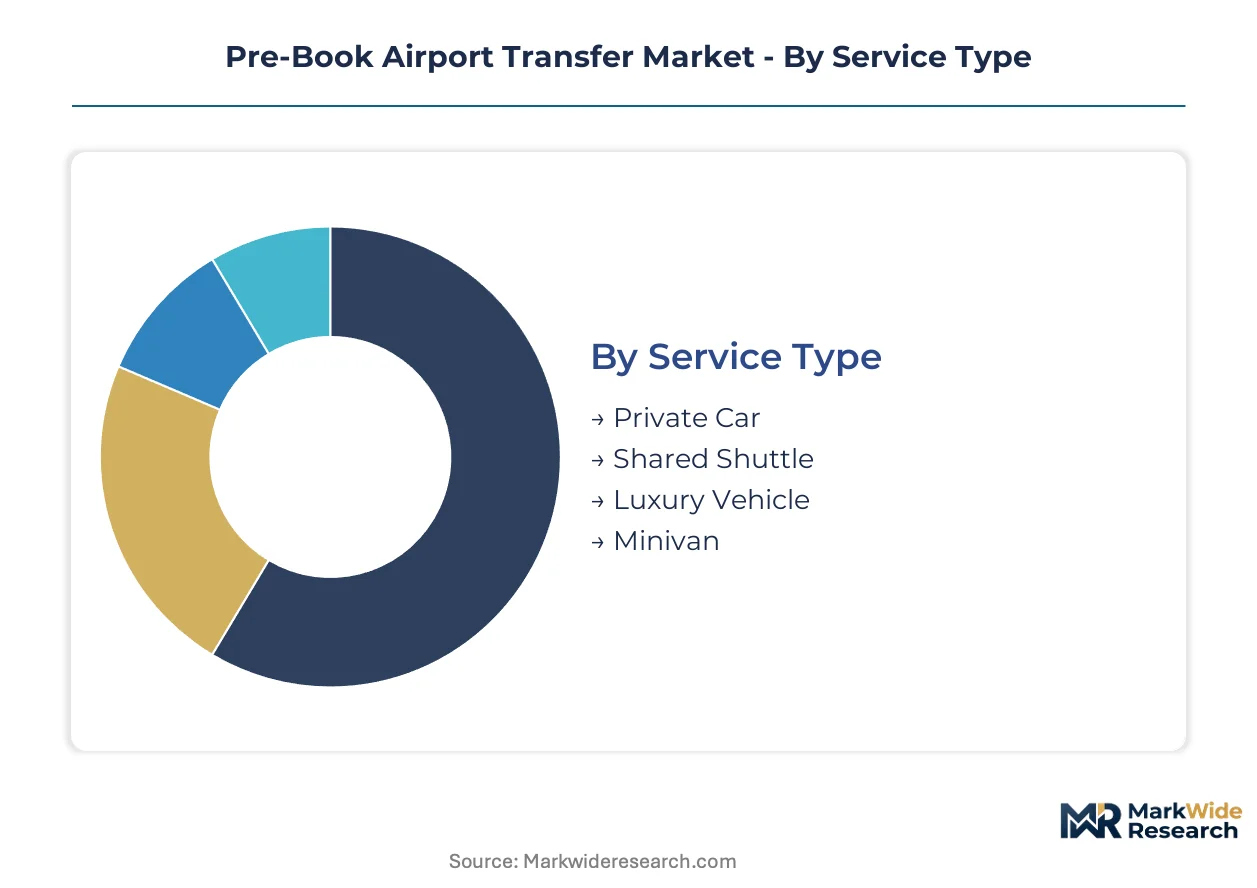
Segmentation in pre-book airport transfers reveals divergent margin profiles and booking cadences across service tiers and customer channels. Fleet operators calibrate vehicle allocation and pricing algorithms against these divisions to optimize yield per corridor.
Service Type:
Private car bookings cycle fastest with same-day confirmations dominating corporate corridors, while shared shuttles operate on longer lead times with fixed departure windows.
- Private Car:Reserved exclusively for individual or small-group transport with guaranteed pickup timing and direct routing. Demand clusters in Frankfurt, Dubai, and New York business corridors where travel managers mandate fixed-rate ground transport with automated receipt generation.
- Shared Shuttle:Scheduled multi-passenger service operating on fixed routes with consolidated pickup timing. Price-sensitive leisure travelers in United States and German secondary airports drive volume, though thinner margins constrain operator investment in fleet quality.
- Luxury Vehicle:Premium-class transport with chauffeur service and amenity specifications for executive clientele. Corporate procurement policies in the United Arab Emirates specify this tier for C-suite travel, ahead of regulatory sustainability mandates.
- Minivan:Mid-capacity vehicle allocation for family groups and luggage-intensive routes. Families transiting Orlando, London Heathrow, and Singapore Changi generate consistent demand during holiday peak windows.
Private car anchors the volume base while luxury vehicle gains share at the steepest rate.
Customer Type:
Cost tiers separate policy-compliant corporate accounts from discretionary leisure spenders with divergent sensitivity to price transparency and service guarantees.
- Business Travelers:Individual road warriors booking under employer travel policies with receipt automation requirements. United States technology and finance sectors concentrate demand through loyalty-integrated mobile platforms.
- Tourists:Leisure visitors prioritizing cost minimization over service consistency. German and French inbound tourism corridors show preference for aggregator price comparison before booking commitment.
- Families:Multi-passenger units requiring child safety seating and luggage capacity. Dubai and Orlando airport routes see peak concentration during school holiday periods with advance reservation patterns.
- Corporate Clients:Enterprise accounts negotiating annual contracts with guaranteed availability and consolidated billing. EU Green Deal compliance documentation now appears in German and French procurement tenders as a qualification threshold.
Corporate clients command the premium pricing tier while families expand most quickly as a booking volume source.
Booking Channel:
Volume concentration shifts toward self-service interfaces as younger demographics displace phone and agency intermediation.
- Mobile App:Smartphone-based booking with stored payment credentials and preference profiles. United States business travelers under forty default to this interface, concentrating volume with platforms offering airline loyalty integrations.
- Website:Desktop and mobile browser reservations for complex multi-leg itineraries. Corporate travel managers in Germany use web portals to enforce policy compliance before confirmation.
- Travel Agency:Intermediated booking through TMC and leisure agent channels. Legacy dependence persists in older demographics and packaged tour segments though share erodes steadily.
- Phone Reservation:Voice-based booking with human agent assistance. Accessibility requirements under the Air Carrier Access Act preserve this channel for passengers requiring accommodation coordination.
Mobile app captures the volume base while website bookings climb the fastest among corporate account segments.
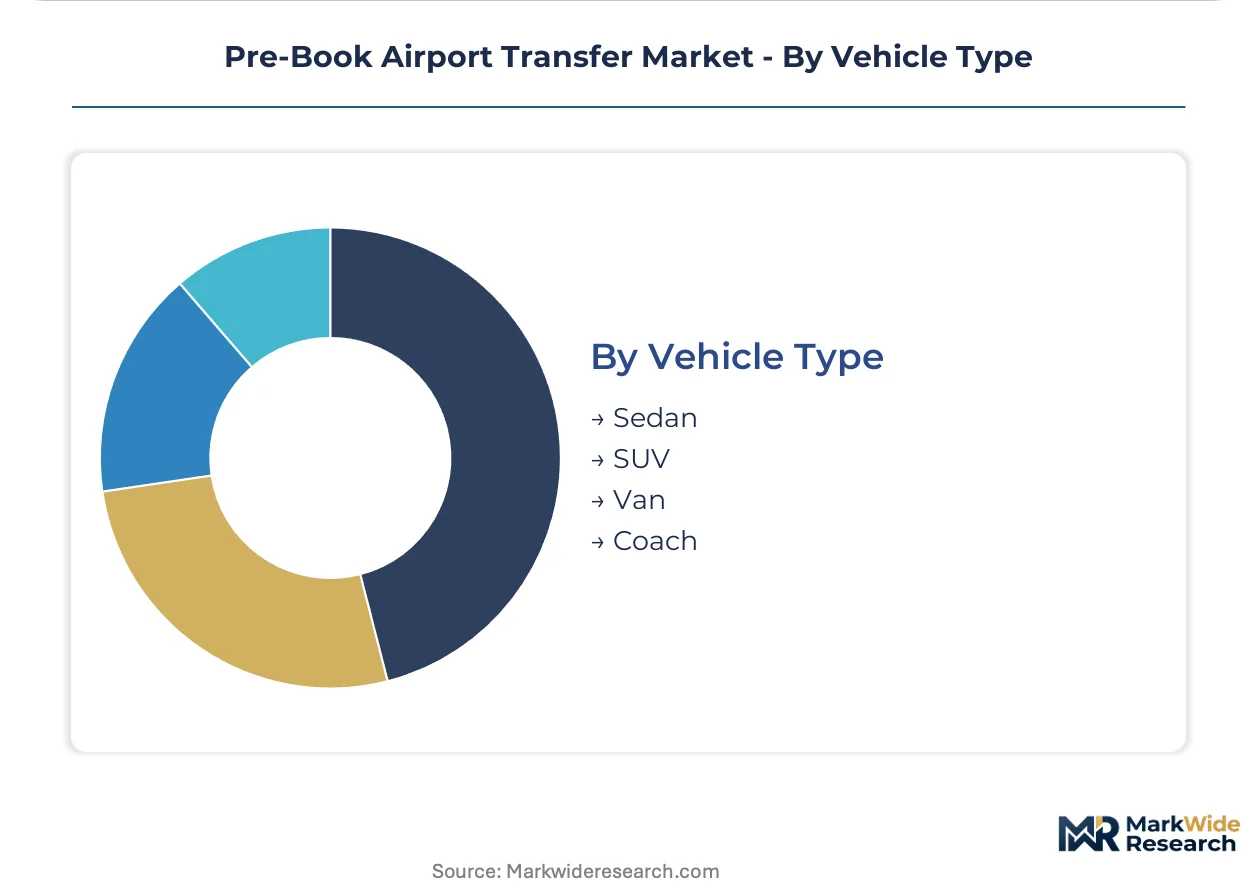
Vehicle Type:
Fleet procurement priorities track electrification timelines and corridor-specific capacity requirements across sedan, SUV, van, and coach configurations.
- Sedan:Standard four-door passenger vehicle for individual and dual-occupancy routes. German operators face KBA certification delays for electric sedan deployment that lag corporate tender specifications.
- SUV:Elevated-capacity vehicle with luggage and passenger volume advantages. United States corporate corridors show preference for this class during winter weather periods and executive transport.
- Van:Extended-capacity vehicle for group transport and equipment-intensive travel. Family and film production segments in Los Angeles and London generate specialized demand.
- Coach:Large-capacity bus configuration for event and group charter service. Airport-to-conference center routes in Dubai and Singapore deploy this class for technology sector gatherings.
Sedan retains the volume base while SUV expands most quickly as fleet operators respond to corporate preference shifts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Department of Transportation enforces accessibility standards under the Air Carrier Access Act that reshape operator service obligations across North American corridors. Corporate travel managers in Frankfurt and Dubai now mandate fixed-rate ground transport with automated receipt generation. Fleet electrification timelines in Germany and France compress replacement cycles from seven years to four years.
United States
Business travelers under forty default to mobile app interfaces with stored payment credentials and airline loyalty integrations. The Air Carrier Access Act requires equivalent service for passengers with disabilities across pre-book platforms. New York and San Francisco corridors concentrate premium corporate account volume where technology and finance sectors drive demand.
Germany
KBA certification requirements for commercial electric vehicle deployment lag actual model availability, creating procurement friction for operators. The EU Green Deal mandates zero-emission fleet deadlines that accelerate capital deployment toward electric sedan procurement. Frankfurt and Munich airports see corporate tenders specifying electric vehicle class ahead of regulatory deadlines.
United Arab Emirates
C-suite travel policies specify luxury vehicle tiers with chauffeur service and amenity specifications. Dubai's transport authority imposes commercial licensing standards that exceed regional benchmarks for service quality. Premium corridor volume concentrates at Dubai International Airport where technology sector gatherings generate group charter demand.
United Kingdom
Corporate sustainability reporting obligations under the Corporate Sustainability Reporting Directive alter procurement criteria for European-headquartered enterprises with UK operations. London Heathrow and Gatwick serve as aggregation points for price-sensitive leisure travelers comparing aggregator options before booking commitment. Family segments during school holiday periods drive advance reservation patterns for luggage-intensive routes.
France
Local emissions frameworks in Paris and Lyon mandate fleet electrification timelines that reshape operator vehicle procurement strategies. The EU Green Deal's 2035 zero-emission vehicle mandate forces compressed replacement cycles for sedan and van configurations. Charles de Gaulle and Orly airports concentrate inbound tourism corridor demand where German and French visitors prefer price comparison tools.
Pre-Book Airport Transfer Market Competitive Environment
Premium fixed-rate platforms and price-transparent aggregators split the market across divergent customer value propositions. The vendor base organizes around three strategic archetypes: guaranteed-pricing specialists serving corporate accounts, bidding-model platforms optimizing for leisure price sensitivity, and aggregation technology providers sustaining volume across fragmented local operator networks. Dominant competitive moves include loyalty program integrations with airline and hospitality partners, plus middleware development for real-time booking synchronization with legacy dispatch systems.
Within the premium corporate tier, Blacklane exemplifies guaranteed-pricing positioning through fixed-rate policies that resist dynamic surge adjustments. Jayride occupies the aggregation technology vector, sustaining volume across fragmented local operator networks through centralized demand generation. GetTransfer represents the price-transparency archetype, deploying bidding models that expose rate competition for intercity and airport routes. These three anchors illustrate how strategic differentiation around pricing mechanics, not vehicle assets alone, determines competitive position.
| Leading Market Players |
|---|
| SIXT Ride |
| GetTransfer |
| Transfeero |
| Jayride |
| MyTransfers |
| Blacklane |
| Holiday Taxis |
| Klook |
| AirportTransfer.com |
| Others |
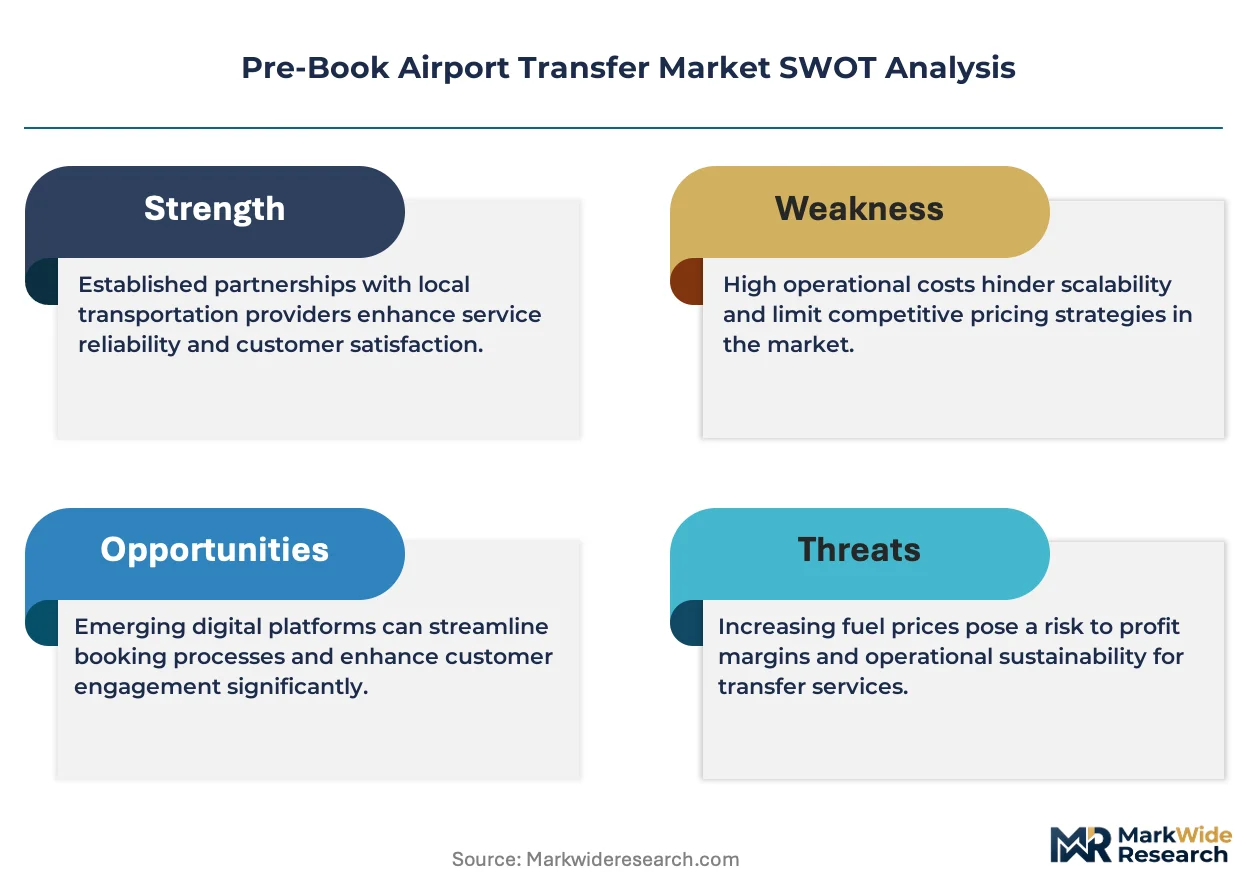
Value Chain & Pricing Dynamics
EU Green Deal fleet electrification mandates expose operators to single-source dependency on German KBA-certified electric vehicle supply, compressing replacement cycles from seven years to four years while widening spreads between compliant premium tiers and legacy internal-combustion economy offerings.
Pricing Analysis
The customization-premium spread separates guaranteed fixed-rate corporate contracts from dynamic aggregator bids. Three-tier pricing structure across premium, standard, and economy levels anchors on vehicle class and electrification compliance, with EU Green Deal documentation now qualifying tier access. Cost compression in the economy segment intensifies because platform commission structures of 15-25% erode small operator margins. Leisure tourists remain most price-sensitive, while corporate clients with automated receipt requirements show least sensitivity.
Supply Chain Analysis
Upstream feedstock for commercial electric vehicle fleets draws from Germany, China, and South Korea for battery cell supply, with sedan and van configurations dominating procurement volumes. Lithium-ion battery packs, electric drivetrain components, and KBA certification services constitute critical input dependencies. Single-source vulnerability concentrates in German KBA approval timelines that lag model availability. Distribution runs through centralized dispatch platforms integrating with legacy operator systems via middleware layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pre-book airport transfers sit in early-cycle expansion as corporate travel policy reform mandates fixed-rate ground transport with automated receipt generation, accelerating penetration beyond traditional travel agency channels.
For Market Incumbents: Harden fleet electrification compliance ahead of EU Green Deal deadlines to lock in enterprise contract renewals. Secure long-term battery supply agreements with South Korean and Chinese cell manufacturers to deflect procurement cost inflation. Invest in middleware development for real-time API synchronization with legacy dispatch systems to maintain platform integration advantages against aggregator encroachment.
For New Entrants and Emerging Players: Secondary airports in the United States Midwest and German regional hubs present whitespace corridors underserved by licensed chauffeur concentration. Target family segments with luggage-intensive minivan configurations during holiday peak windows. Launch through direct-to-consumer mobile interfaces with stored payment profiles to bypass incumbent loyalty program lock-in.
For Investors and Strategic Acquirers: EU Green Deal 2035 zero-emission mandates reshape the acquisition landscape toward compliant fleet operators with documented Scope 3 emissions tracking. Long-term viability favors vertically integrated platforms controlling both dispatch technology and captive vehicle supply. Watch corporate tender specifications requiring electric vehicle class as the inflection signal for qualification barriers tightening.
| Strategic Initiative | Industry Significance |
|---|---|
| Electric Fleet Procurement | KBA-certified vehicle deployment secures EU Green Deal compliance ahead of tender deadlines. |
| Flight Tracking API Integration | Real-time arrival synchronization reduces passenger wait times and missed connections. |
| Corporate Loyalty Integration | Airline and hospitality program tie-ins capture repeat business traveler volume. |
| Middleware Development | Legacy dispatch system connectivity enables real-time booking synchronization. |
| Accessibility Service Expansion | ADA-compliant vehicle deployment opens dedicated demand under Air Carrier Access Act. |
Study Parameters
A spread of perspectives from fleet operations directors, corporate travel managers, platform technology leads, and local operator owners converged on the working assumptions driving this analysis. Primary interviews with these stakeholders combined with secondary validation against customs vehicle import data, EU regulatory filings, SEC operator disclosures, and airport authority passenger statistics. Bottom-up corridor volume estimates and top-down market sizing triangulated to constrain projection variance.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation modeled across service type, customer archetype, booking channel, and vehicle electrification tier. CAGRs derived from corridor-level booking growth trajectories and fleet replacement cycle compression. Forecast inputs incorporated EU Green Deal compliance timelines and corporate procurement policy reform penetration curves.
The forecast holds incumbent behavior within observed patterns; aggressive electrification acceleration by German operators or platform commission restructuring would shift outcomes. Cross-checking against airport authority passenger throughput data and corporate travel spend surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tourist Transport Services
Helicopter Tourism Market
Tourist Transport Services
Airport Ground Transportation Market
Tourist Transport Services
Low-Cost Carrier (LCC) Market
Tourist Transport Services
Yacht Rental Market
Tourist Transport Services
UK Low Cost Airlines Market
Tourist Transport Services
Boat Rental Market
Tourist Transport Services
India International Express Service Market
Tourist Transport Services
Travel Transportation Market
Tourist Transport Services
Southeast Asia Charter Jet Services Market
Tourist Transport Services
Europe Charter Jet Services Market
Tourist Transport Services
Italy Car Rental Market