
 Airport Ground Transportation Market | 2026-2036
Airport Ground Transportation Market Size, Share, and Industry Trends Forecast 2026-2036
Airport Ground Transportation Market Outlook
Business traveler demand is shifting toward seamless multimodal connectivity as post-pandemic corporate travel patterns normalize. Uber Technologies Inc. leverages its global driver network and airport geofencing technology to capture premium ride-sharing volumes at major hubs. FirstGroup Plc anchors contracted bus and rail shuttle operations across UK airports through long-term service agreements. Didi Chuxing Technology Co dominates app-based dispatch in China's tier-one aviation gateways, integrating domestic flight data with ground transport scheduling.
Airport ground transportation encompasses the movement of passengers and crew between terminal facilities and external destinations via road-based vehicles operating under airport authority coordination. Fleet composition spans diesel, compressed natural gas, and battery-electric powertrains with passenger capacities ranging from four-seat sedans to sixty-seat articulated buses, governed by airside safety certifications and emissions protocols. Shuttle services and ride-sharing represent the fastest-expanding service type categories, with mobile app bookings displacing traditional taxi queues and travel agent reservations at hub airports. Sedans and vans command the highest utilization rates in private transfer segments, while electric buses gain share in employee and group transit contracts where charging infrastructure investment amortizes across fixed routes.
The Federal Aviation Administration coordinates with airport operators on curbside congestion management and commercial vehicle licensing, while the EPA's vehicle emissions standards directly affect fleet replacement cycles for contracted operators. The EU Green Deal and associated F-Gas Regulation pressure European ground transport providers to accelerate zero-emission fleet transitions ahead of terminal access restrictions. Stakeholders must monitor evolving airport authority sustainability mandates and digital platform integration requirements as these criteria increasingly determine concession renewal awards and exclusive operating agreements.
Market Dynamics
Airport ground transportation is undergoing a fundamental reconfiguration as fleet electrification mandates collide with charging infrastructure bottlenecks at hub airports. The European Union's Green Deal and California Air Resources Board zero-emission deadlines are forcing contracted operators into accelerated capital replacement cycles before terminal access restrictions take effect.
Growth Catalysts
- EU Green Deal Fleet Mandates:Terminal access restrictions for diesel vehicles in Frankfurt, Amsterdam, and Paris Charles de Gaulle are compelling ground transport operators to electrify shuttle and bus fleets ahead of statutory deadlines.
- Integrated Mobility Platforms:Business travelers now expect seamless multimodal booking where flight data automatically triggers ground transport scheduling, driving adoption of API-connected dispatch systems at major hubs.
- Hub Airport Expansions:Capacity additions at Denver International, Beijing Daxing, and Munich are generating contracted ground transport volumes through exclusive service agreements with incumbent operators.
Market Restraints
- Battery Supply Concentration:Lithium-ion cell production concentrates in China, exposing European and North American fleet operators to supply chain disruptions and tariff exposure during procurement cycles.
- Charging Infrastructure Capex:Depot fast-charging installations for electric bus fleets require electrical utility upgrades that amortize poorly across variable-route operations at smaller regional airports.
- Airside Certification Delays:FAA and EASA safety certifications for autonomous shuttle trials create extended approval timelines that compress deployment windows for pilot programs.
Strategic Opportunities
- Employee Transit Electrification:Fixed-route employee shuttles at Hartsfield-Jackson Atlanta and Dallas-Fort Worth offer predictable charging schedules that justify dedicated infrastructure investment.
- Carbon Credit Monetization:California's Low Carbon Fuel Standard and EU Emissions Trading System allow fleet operators to generate tradable credits from zero-emission vehicle deployment.
- First-Mile/Last-Mile Integration:Rail-air intermodal connectors at London Heathrow and Tokyo Haneda remain underdeveloped, creating white space for multimodal platform providers.
Industry Challenges
- Electrical Grid Coordination:Utility interconnection queues for high-capacity charging depots extend 18-24 months at congested airports, misaligning with fleet replacement deadlines.
- Legacy Dispatch System Migration:Proprietary taxi and shuttle scheduling software at incumbent operators resists API integration with modern mobility platforms, fragmenting booking data.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airport Ground Transportation Market |
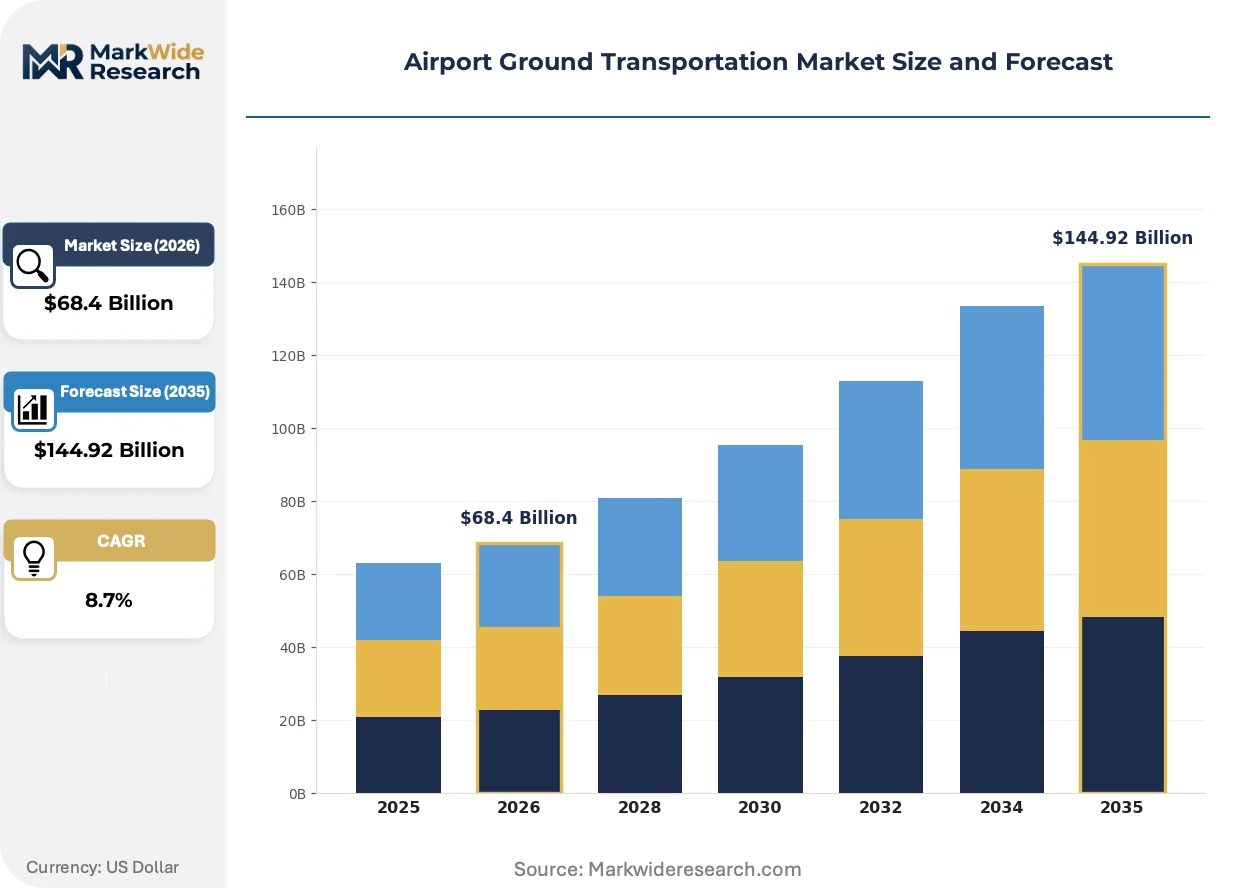
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $144.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Shuttle Services, Private Transfers, Taxi Services, Ride-Sharing Vehicle Type: Limousines, Vans, Buses, Sedans End User: Business Travelers, Tourists, Airport Staff, Groups Booking Channel: Mobile Apps, Websites, Travel Agents, Kiosks |
| Companies Covered | Keolis, Carey International, Uber Technologies Inc., AerCap Holdings N.V., Aena S.M.E., SA, Didi Chuxing Technology Co, FirstGroup Plc, Macquarie Infrastructure Holdings, LLC, GO Airport Shuttle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airport Ground Transportation Market Strategic Shifts
Digital platform integration is compressing traditional booking channels while powertrain electrification reshapes fleet economics. These forces are converging to redefine how ground transport services are procured, operated, and regulated at aviation gateways worldwide.
Battery-electric powertrains are electrifying airport shuttle and bus segments as operators confront terminal access restrictions. Hub airports in Germany and the Netherlands are mandating zero-emission zones that exclude diesel vehicles from curb and apron areas. This electrification is compressing total cost of ownership calculations that previously favored extended diesel fleet lifecycles.
REACH and F-Gas Regulation amendments are restricting fluorinated greenhouse gases in vehicle air conditioning systems across European airport fleets. The industrial consequence is accelerated refrigerant transition to CO2-based or hydrocarbon alternatives during scheduled maintenance intervals. Bus and coach segments operating cross-border routes face the most complex compliance burden as member state implementation timelines diverge.
Corporate travel managers are consolidating ground transport procurement through centralized sustainability dashboards that track scope-three emissions. Traditional taxi queues and travel agent bookings are losing share to API-integrated mobility platforms that aggregate ride-sharing, rail, and shuttle options. This consolidation is most visible in the United States and United Kingdom where enterprise travel spend has normalized post-pandemic.
Airport Ground Transportation Market Segmentation
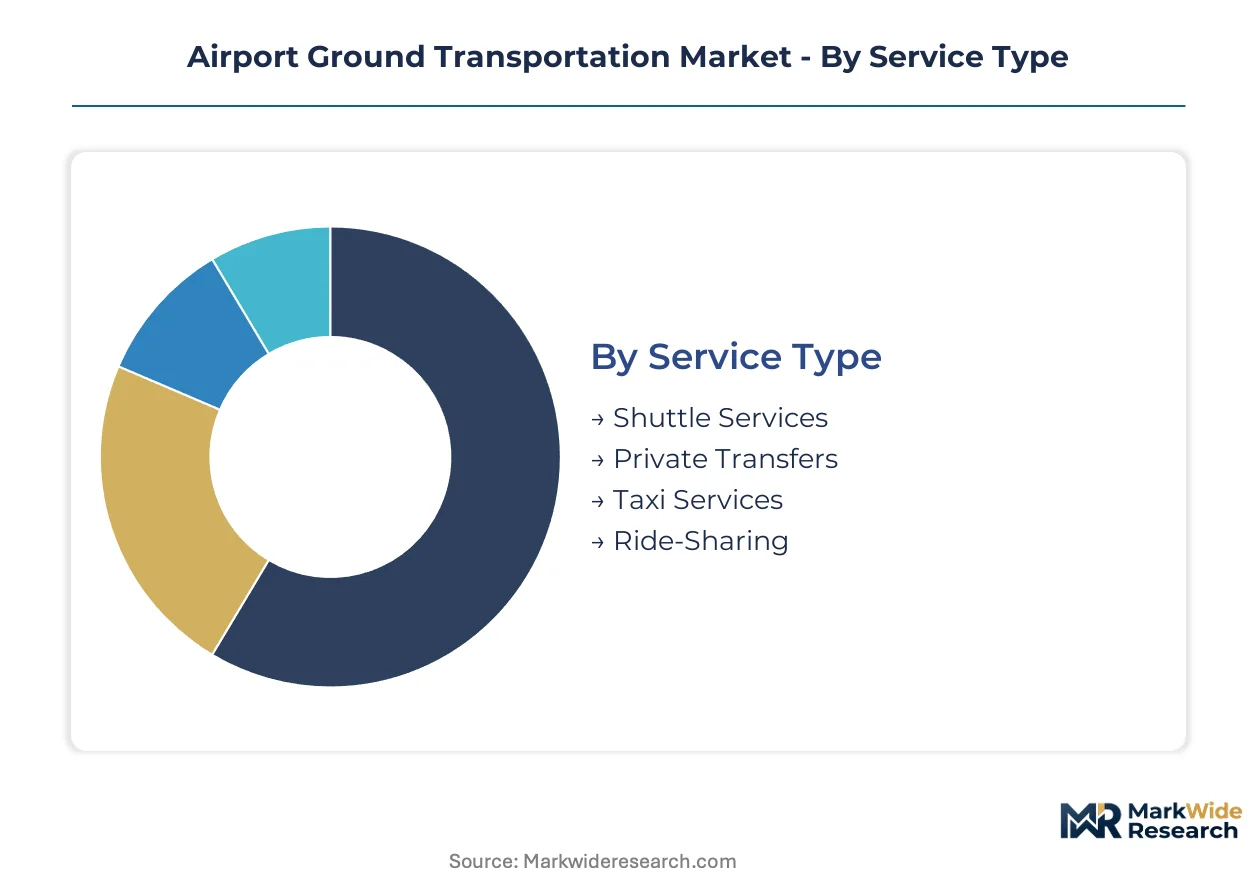
Airport ground transportation segmentation reflects divergent operational economics across fleet ownership models and passenger service tiers. Procurement patterns for contracted operators differ fundamentally from on-demand dispatch platforms, creating distinct margin structures within each category.
Service Type:
Supply concentration tilts toward operators holding exclusive airport authority agreements, with fragmentation increasing in open-access curb zones.
- Shuttle Services:Fixed-route operations using 15-60 seat vehicles under long-term airport contracts. Demand clusters at hub airports in the United States, Germany, and China where terminal expansion projects bundle ground transport concessions with construction financing.
- Ride-Sharing:App-based dispatch connecting arriving passengers with driver networks through geofenced pickup zones. Corporate travel managers in the United States and United Kingdom are consolidating spend through API-integrated platforms that displace traditional taxi queues.
- Private Transfers:Pre-booked sedan and van services targeting premium passengers. Operators maintain dedicated fleets with airside certification.
- Taxi Services:Licensed medallion or permit-holding vehicles operating from designated ranks. Regulatory fragmentation across municipal jurisdictions constrains scaling.
Today's leader: Shuttle Services. Tomorrow's challenger: Ride-Sharing.
Vehicle Type:
Cost tier stratification separates capital-intensive electric bus deployments from asset-light sedan networks.
- Buses:Articulated and standard coaches handling 40-120 passengers on fixed employee and group routes. Fleet operators in the Netherlands and Germany face EU Green Deal deadlines for zero-emission terminal access.
- Sedans:Four-door passenger vehicles dominating private transfer and ride-sharing dispatch. Utilization rates run highest in business traveler segments at Hartsfield-Jackson Atlanta and Dallas-Fort Worth.
- Vans:8-15 seat configurations serving group charters and hotel shuttles. California Air Resources Board mandates are accelerating electric powertrain adoption.
- Limousines:Premium stretched vehicles for executive transport. Volume concentrates in corporate travel accounts with sustainability reporting requirements.
Current procurement favors Buses for electrification subsidies; Sedans retain volume leadership through platform aggregation.
End User:
Application-specific requirements create divergent service specifications across passenger categories.
- Business Travelers:Time-sensitive passengers requiring seamless multimodal connectivity. Corporate travel policies in the United States and United Kingdom now mandate scope-three emissions tracking for ground transport bookings.
- Airport Staff:Employees on fixed schedules enabling predictable route planning and charging infrastructure utilization. Hartsfield-Jackson Atlanta and Dallas-Fort Worth are electrifying these routes first.
- Tourists:Price-sensitive leisure passengers booking shared shuttles and public transit connections. Volume fluctuates with seasonal aviation demand.
- Groups:Coordinated travelers requiring coordinated pickup for events and conventions. Procurement runs through destination management companies rather than individual booking.
Business Travelers command premium pricing; Airport Staff offers the clearest electrification payback.
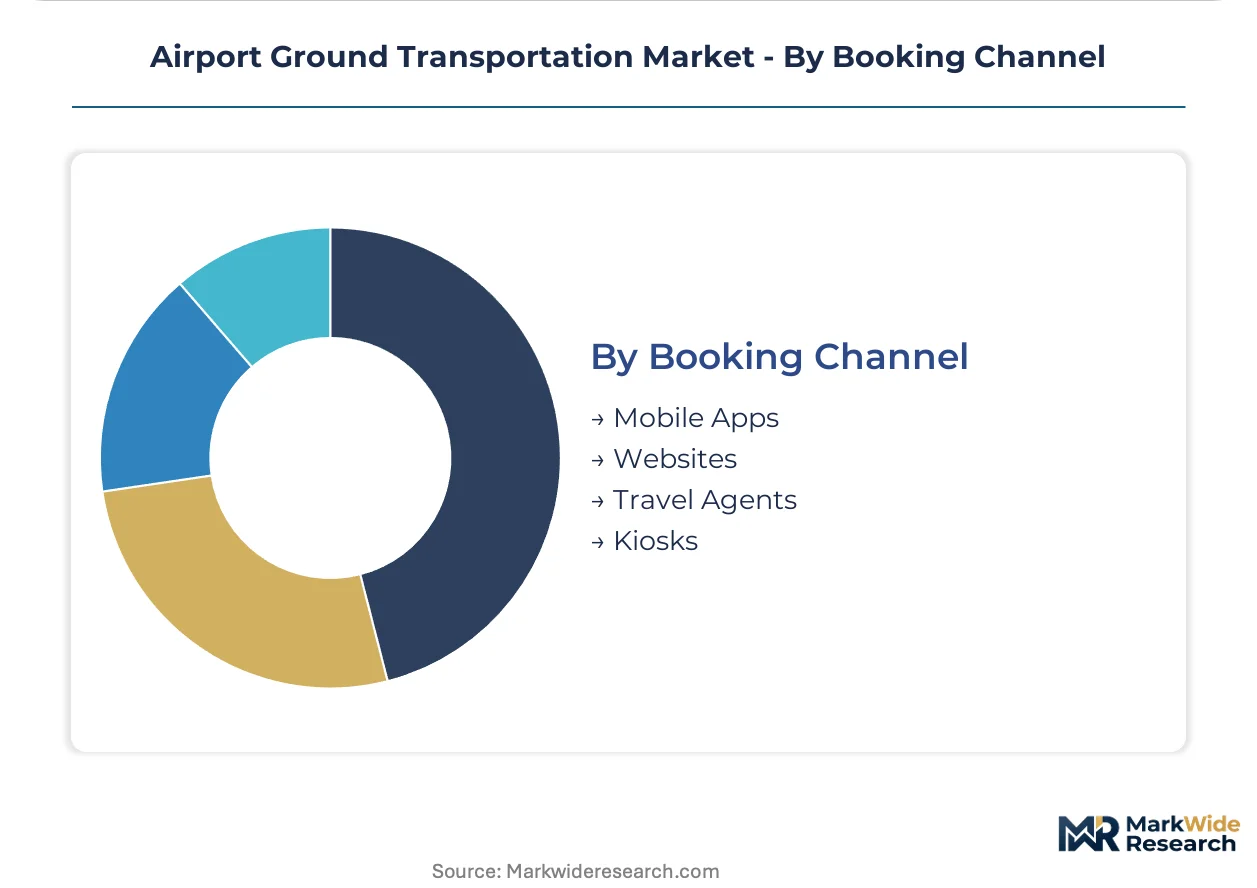
Booking Channel:
Customer type fragmentation separates enterprise procurement platforms from individual consumer apps.
- Mobile Apps:Real-time dispatch interfaces displacing traditional taxi queues at major hubs. API integration with flight data systems is becoming mandatory for airport concession renewals.
- Travel Agents:Traditional intermediaries losing share to direct platform bookings. Survival depends on corporate account management and sustainability reporting integration.
- Websites:Pre-booking portals for private transfers and group reservations. Conversion rates lag mobile for on-demand segments.
- Kiosks:Terminal-based self-service terminals for arriving passengers without smartphone access. Deployment concentrates in international arrival halls.
Mobile Apps capture volume growth; Travel Agents defend enterprise relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping fleet procurement as operators migrate investment toward jurisdictions with favorable electrification incentives and streamlined certification pathways. Compliance cost gaps between the European Union and North America are accelerating cross-border equipment sourcing strategies.
United States
Hartsfield-Jackson Atlanta and Dallas-Fort Worth anchor contracted ground transport volumes through hub expansion projects. The FAA coordinates curbside congestion management with airport authorities on commercial vehicle licensing. California's Air Resources Board zero-emission deadlines are forcing accelerated fleet replacement cycles in Los Angeles and San Francisco.
Germany
Frankfurt and Munich airports are mandating zero-emission zones that exclude diesel vehicles from terminal access areas. The EU Green Deal and F-Gas Regulation pressure operators to transition refrigerant systems in vehicle air conditioning. Fleet procurement concentrates in Baden-Württemberg and Bavaria where automotive supplier networks support electric powertrain integration.
China
Beijing Daxing and Shanghai Pudong drive contracted ground transport volumes through state-backed airport expansion financing. The Ministry of Ecology and Environment enforces dual carbon goals that shape fleet electrification timelines. Tier-one aviation gateways in Guangdong and Jiangsu provinces are integrating domestic flight data with ground transport scheduling platforms.
United Kingdom
Heathrow and Gatwick are modernizing passenger flow management through long-term service agreements with incumbent operators. The Department for Transport coordinates with airport authorities on airside safety certifications for commercial vehicles. London's congestion charging zone and ultra-low emission standards are compressing diesel fleet lifecycles.
Netherlands
Amsterdam Schiphol is implementing terminal access restrictions for conventional fuel vehicles ahead of statutory deadlines. The EU Green Deal mandates are reshaping fleet procurement decisions for shuttle and bus operators. Randstad region logistics clusters are deploying dedicated charging infrastructure for fixed-route employee transit contracts.
Airport Ground Transportation Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated mobility platforms capturing premium volumes while incumbent shuttle operators defend long-term airport concessions. The vendor base concentrates around operators holding exclusive authority agreements at hub locations, with fragmentation increasing in open-access curb zones. Three strategic archetypes dominate: global ride-sharing networks with geofencing capabilities, regional bus and rail operators with airside certification, and private transfer specialists maintaining dedicated premium fleets. Competitive moves center on API integration partnerships with flight data systems and exclusive concession renewals at expanding hub airports.
Within the integrated mobility tier, Uber Technologies Inc. and Didi Chuxing Technology Co occupy positions anchored by global driver networks and airport geofencing technology. Among European incumbent operators, Keolis and FirstGroup Plc exemplify the contracted shuttle archetype through long-term service agreements at major aviation gateways. Carey International represents the private transfer specialist model with dedicated fleet operations targeting premium passenger segments.
| Leading Market Players |
|---|
| Keolis |
| Carey International |
| Uber Technologies Inc. |
| AerCap Holdings N.V. |
| Aena S.M.E., SA |
| Didi Chuxing Technology Co |
| FirstGroup Plc |
| Macquarie Infrastructure Holdings, LLC |
| GO Airport Shuttle |
| Others |
Value Chain & Pricing Dynamics
Hub airport authorities in the United States, Germany, and China concentrate procurement power through exclusive concession agreements that compress margins for contracted shuttle operators while enabling premium pricing for private transfer specialists with airside certification.
Pricing Analysis
Direct-to-airport contract pricing dominates fleet procurement, with three-tier pricing structure across premium, standard, and economy levels differentiating by vehicle certification grade and after-sales service bundling. Price differentiation hinges on EU Green Deal compliance tier and battery-electric powertrain availability. Cost compression in shuttle segments is intensifying because lithium-ion cell supply bottlenecks extend replacement cycle negotiations. Tourists booking shared shuttles exhibit highest price sensitivity; corporate travel managers tracking scope-three emissions show lowest sensitivity to premium tiers.
Supply Chain Analysis
Dual-sourcing requirements from European and North American fleet operators mandate qualification of battery suppliers across China, South Korea, and Japan to mitigate tariff exposure. The supply chain draws from lithium carbonate, nickel sulfate, and semiconductor-grade silicon inputs. Single-source vulnerability concentrates in cathode active material production. Distribution runs through OEM-direct fleet sales and regional bus manufacturer networks serving airport authority tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Airport ground transportation operates as a geographic-arbitrage play where fleet operators can exploit the compliance cost gap between California Air Resources Board zero-emission deadlines and EU Green Deal terminal access restrictions to optimize procurement timing.
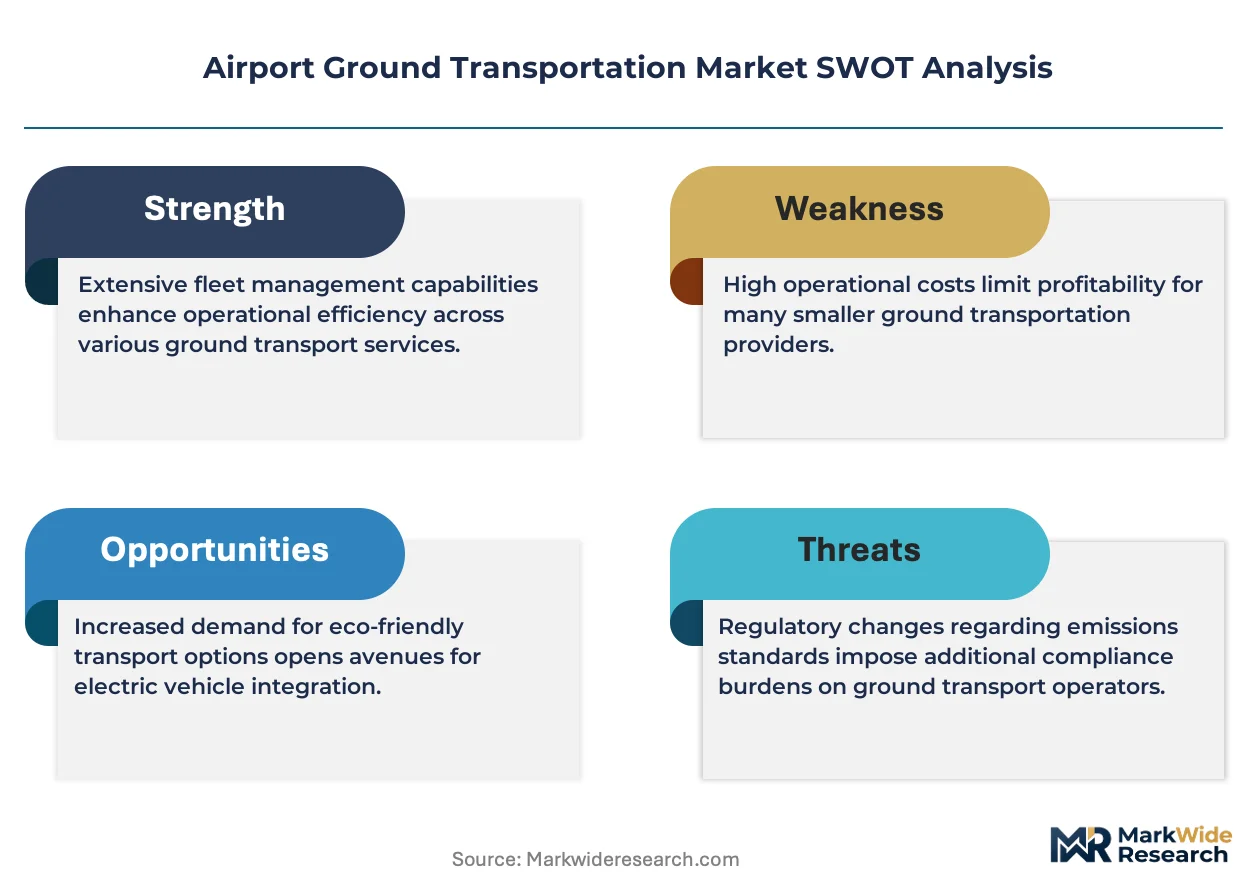
For Market Incumbents: Cement exclusive concession renewals at expanding hub airports before electrification mandates trigger competitive rebidding. Secure backward integration into charging infrastructure development to defend against mobility platform entrants. Prioritize API integration investments with flight data systems as the priority lever for corporate travel contract retention. For New Entrants and Emerging Players: Autonomous shuttle trials represent a technology-first wedge into employee transit contracts at Hartsfield-Jackson Atlanta and Dallas-Fort Worth where fixed routes justify infrastructure investment. Target underdeveloped rail-air intermodal connectors at London Heathrow and Tokyo Haneda. Pursue white-label platform partnerships with incumbent bus operators lacking digital dispatch capabilities. For Investors and Strategic Acquirers: Integrated mobility platforms are the most active acquirer in this space, consolidating regional shuttle operators to capture API-connected corporate travel spend. Long-term viability favors operators with airside certification and exclusive hub agreements over asset-light dispatch networks. Monitor California Low Carbon Fuel Standard credit pricing as the inflection indicator for electric fleet economics.| Strategic Initiative | Industry Significance |
|---|---|
| Charging Infrastructure Partnership | Secures depot fast-charging capacity ahead of utility interconnection queues at congested airports. |
| API Integration with Flight Data Systems | Enables automatic ground transport scheduling triggered by arrival information at major hubs. |
| Exclusive Concession Renewal | Locks in long-term service agreements bundled with terminal expansion project financing. |
| Zero-Emission Fleet Transition | Qualifies operators for EU Green Deal terminal access and California LCFS credit generation. |
| First-Mile/Last-Mile Rail Integration | Captures white space in underdeveloped intermodal connectors at Heathrow and Haneda. |
Study Parameters
Direct dialogue with fleet procurement managers at airport authorities, operations directors at contracted shuttle providers, sustainability officers at corporate travel programs, and charging infrastructure developers grounded the qualitative assessment. Secondary validation drew from FAA regulatory filings, EU Green Deal implementation documents, California Air Resources Board compliance databases, and airport concession tender records. Bottom-up and top-down triangulation cross-checked fleet deployment data against contracted service agreement values.
Bottom-up modeling built passenger volume projections from hub airport expansion timelines and corporate travel normalization patterns. Segmentation across service type, vehicle powertrain, end-user category, and booking channel shaped the analytical framework. CAGRs were derived from contracted ground transport volume growth at Denver International, Beijing Daxing, and Munich. Fleet electrification adoption curves and charging infrastructure deployment schedules served as industry-specific forecast inputs.
The model holds under stable regulatory enforcement timelines and lithium-ion supply continuity; deviation in EU terminal access restriction implementation or battery cell tariff regimes would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tourist Transport Services
Europe Charter Jet Services Market
Tourist Transport Services
Yacht Rental Market
Tourist Transport Services
Italy Car Rental Market
Tourist Transport Services
Travel Transportation Market
Tourist Transport Services
Low-Cost Carrier (LCC) Market
Tourist Transport Services
UK Low Cost Airlines Market
Tourist Transport Services
Southeast Asia Charter Jet Services Market
Tourist Transport Services
India International Express Service Market
Tourist Transport Services
Helicopter Tourism Market
Tourist Transport Services
Boat Rental Market
Tourist Transport Services
Pre-Book Airport Transfer Market