
 Anethole Market | 2026-2036
Anethole Market Size, Share, and Industry Trends Forecast 2026-2036
Anethole Market Outlook
Chinese anethole producers is restructuring capacity around fennel-derived natural extraction as feedstock volatility pressures synthetic routes. Jiangsu Jishui Natural Flavor Co. leverages its captive fennel cultivation base in Jiangsu province to secure raw material traceability. Merck KGaA sustains pharmaceutical-grade anethole supply through stringent European Pharmacopoeia certification protocols. Arora Aromatics Pvt. Ltd. anchors South Asian distribution with backward integration into star anise oil distillation in Uttar Pradesh.
Anethole is an aromatic organic compound with the molecular formula C10H12O, occurring naturally in fennel and anise seeds or synthesized via anisole propenylation, serving primarily as a flavoring agent and fragrance intermediate with characteristic sweet licorice odor profile. Natural anethole commands premium positioning in clean-label food and beverage formulations where EFSA flavoring regulations restrict synthetic additive declarations. Synthetic anethole occupies volume leadership in industrial fragrance applications where cost efficiency outweighs provenance requirements. Powder and crystal forms are gaining traction among pharmaceutical firms seeking precise dosing control in tablet and capsule manufacturing.
FDA food additive regulations under 21 CFR 182.60 and EU REACH chemical registration frameworks govern anethole purity thresholds, import documentation, and safety data sheet compliance for cross-border trade. China's SAMR national food safety standards and GB flavoring specifications create additional testing layers for anethole entering processed food supply chains. Stakeholders must monitor evolving pharmaceutical excipient monographs and biotech-derived fermentation alternatives that could displace traditional extraction methods.
Market Dynamics
Feedstock traceability mandates from EU REACH and FDA flavoring standards are compressing synthetic anethole margins while elevating natural extraction economics, restructuring procurement priorities across pharmaceutical and food-grade supply chains.
Growth Catalysts
- Pharmaceutical excipient demand:Tablet and capsule manufacturers in India and China are expanding anethole procurement for precise dosing control in solid-dose formulations, tightening purity specifications for active pharmaceutical ingredient synthesis.
- REACH compliance premium:EU importers are paying certification premiums for anethole meeting European Pharmacopoeia monographs, creating price differentiation between certified and uncertified supply streams.
- Gujarat cluster density:Downstream fragrance compounders concentrated in Gujarat's specialty chemical corridor are reducing logistics costs through port-proximate anethole processing infrastructure.
Market Restraints
- Fennel harvest volatility:Rainfall-dependent fennel cultivation in Jiangsu and Uttar Pradesh generates raw material price swings that destabilize natural anethole cost structures.
- Star anise supply concentration:Wild-harvested star anise dependency in specific Chinese provinces creates single-origin risk for natural extraction routes.
- Synthetic route feedstock pressure:Anisole propenylation depends on petrochemical-derived intermediates exposed to energy cost fluctuations and carbon pricing mechanisms.
Strategic Opportunities
- Fermentation-derived alternatives:Biotech platforms using engineered yeast strains are approaching commercial viability for anethole biosynthesis, potentially bypassing agricultural feedstock constraints.
- Clean-label beverage expansion:EFSA natural flavoring declarations are driving reformulation demand in European premium soft drinks and functional beverages.
- Pharmaceutical-grade certification gap:SAMR and CDSCO alignment with ICH quality guidelines creates first-mover advantage for suppliers achieving multi-jurisdictional pharmacopoeia compliance.
Industry Challenges
- Analytical chemistry talent scarcity:Chromatographic purity verification and chiral separation expertise required for pharmaceutical-grade production outpaces technical training pipeline output in producing regions.
- Dual-use export classification complexity:Anethole's precursor status for certain controlled substances triggers additional licensing layers under national chemical weapons convention implementations, extending order fulfillment timelines.
- Legacy distillation asset retrofit costs:Steam distillation facilities designed for essential oil batch processing require capital-intensive continuous-flow upgrades to meet volume pharmaceutical contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anethole Market |
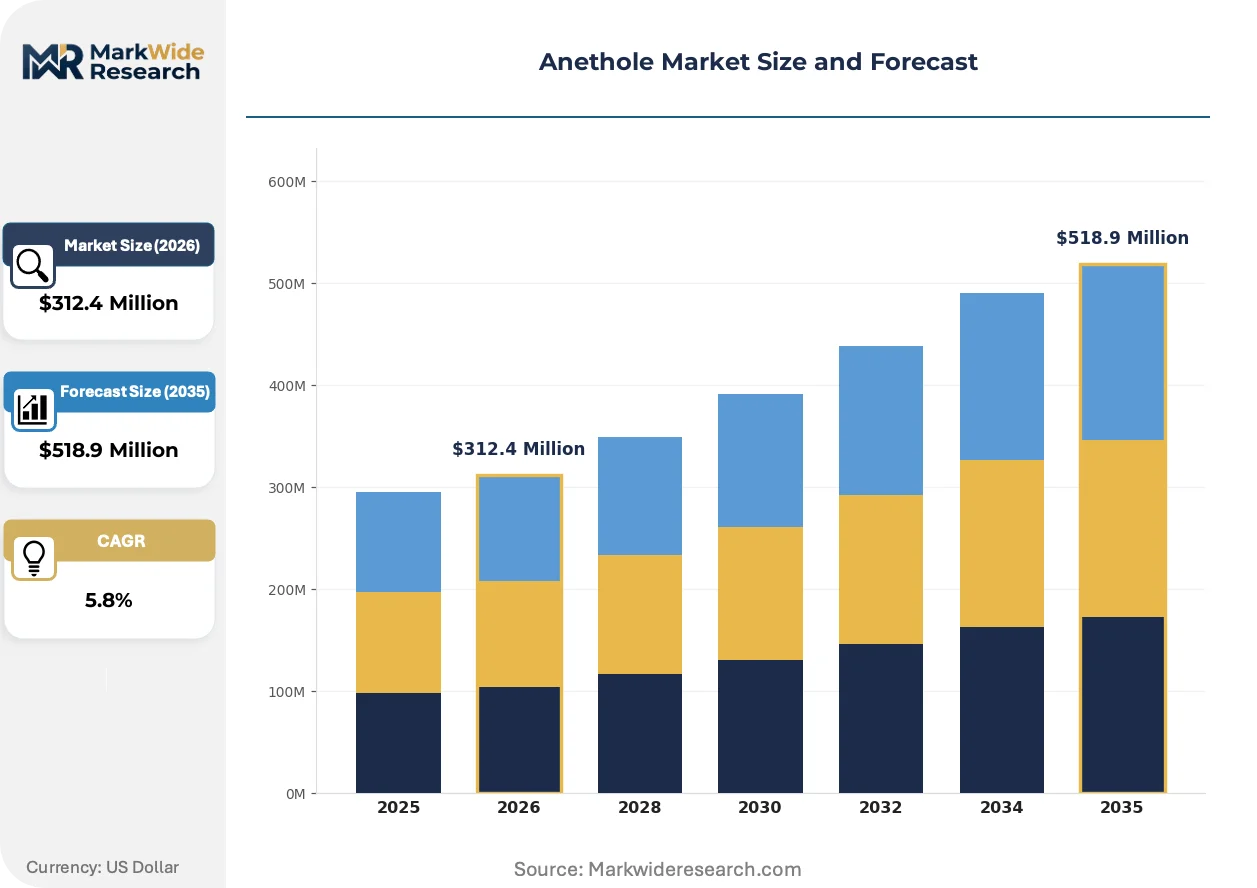
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Anethole, Synthetic Anethole, Essential Oils, Flavoring Agents Application: Food & Beverages, Cosmetics, Pharmaceuticals, Fragrances End User: Food Manufacturers, Cosmetic Companies, Pharmaceutical Firms, Perfume Producers Form: Liquid, Powder, Crystals, Emulsion |
| Companies Covered | Jiangsu Jishui Natural Flavor Co., Ltd., Thermo Fisher Scientific Inc., Sichuan Huiquan Co., Ltd., Arora Aromatics Pvt. Ltd., AOS Products Pvt. Ltd., Jiangxi Yisite Biotechnology Co., Ltd., Merck KGaA, Berje Inc., Guangxi Yulan Chemicals Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anethole Market Strategic Shifts
Supercritical CO2 extraction technology is rewriting competitive economics in natural anethole production, while regulatory data requirements and buyer procurement centralization are simultaneously reshaping market access patterns.
Supercritical CO2 extraction systems are replacing traditional steam distillation for fennel and star anise processing, delivering higher anethole concentrations with reduced thermal degradation. Pharmaceutical excipient manufacturers in Germany and Switzerland are adopting this technology fastest, demanding batch-level Certificates of Analysis. This extraction shift is rewriting the cost structure for natural anethole, compressing the historical premium over synthetic alternatives.
EU REACH Article 33 supply chain communication obligations now require full substance volume tracking from importer to downstream fragrance compounder. Industrial users must document safe-use scenarios in extended safety data sheets, adding compliance overhead that favors larger suppliers with dedicated regulatory affairs functions. Food-grade anethole importers are responding by consolidating vendor relationships to reduce audit burden.
Direct contracting between anethole distillers and pharmaceutical formulators is shortening traditional distributor layers in India and China. Large generic drug manufacturers are establishing approved supplier lists with backward traceability to cultivation plots, replacing spot-market purchasing. This channel compression is most visible in Gujarat and Jiangsu, where API producers now source anethole through qualified supplier programs rather than commodity brokers.
Anethole Market Segmentation
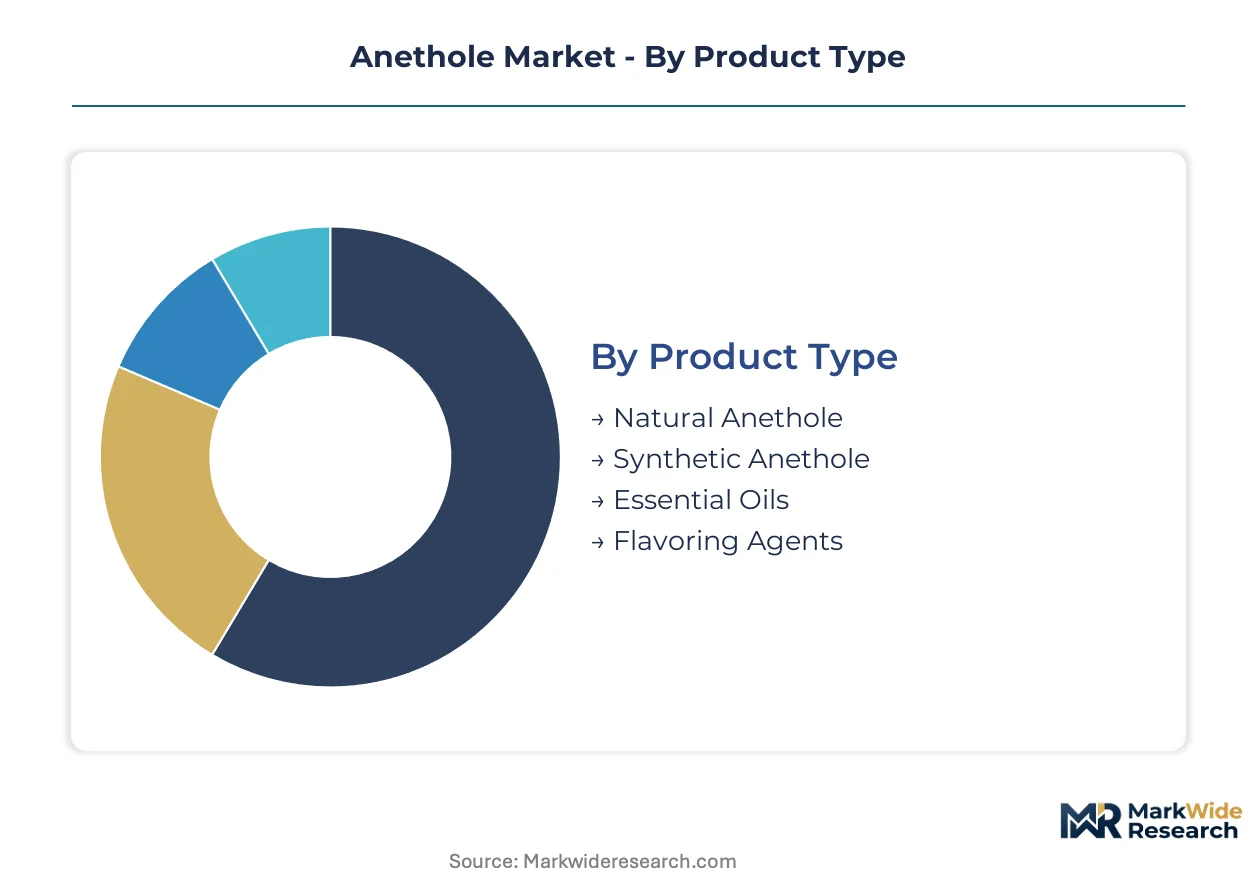
Anethole procurement patterns diverge sharply across product origins and end-use specifications, with pharmaceutical buyers prioritizing purity certification while food manufacturers weigh provenance against cost efficiency. Understanding these segment boundaries clarifies why suppliers maintain parallel production lines for natural extraction and synthetic synthesis despite overlapping technical specifications.
Product Type:
Buyers select anethole origin based on regulatory labeling requirements and end-use certification standards, with natural extraction commanding procurement premiums where EFSA or FDA flavoring declarations restrict synthetic additive claims.
- Natural Anethole:Derived from fennel and star anise through steam distillation or supercritical CO2 extraction, this form carries full traceability documentation required for European Pharmacopoeia compliance and clean-label food positioning. Pharmaceutical excipient manufacturers in Germany and Switzerland pay certification premiums for batch-level Certificates of Analysis verifying chiral purity and residual solvent limits.
- Synthetic Anethole:Manufactured via anisole propenylation using petrochemical intermediates, this route dominates industrial fragrance applications where cost efficiency outweighs provenance requirements. Fragrance compounders in Gujarat's specialty chemical corridor source synthetic material for bulk perfumery bases where regulatory labeling permits artificial flavor declarations.
- Essential Oils:Whole-plant distillates containing anethole alongside terpenoid co-constituents serve traditional medicine and aromatherapy channels requiring botanical integrity rather than isolated compound purity.
- Flavoring Agents:Pre-formulated anethole blends with carriers and stabilizers simplify manufacturing integration for mid-size food processors lacking in-house compounding capabilities.
Synthetic Anethole leads on scale; Natural Anethole leads on momentum.
Application:
Application selection correlates directly with purity tier requirements and regulatory exposure, with pharmaceutical and food-grade uses demanding pharmacopoeia-aligned specifications that cosmetic and fragrance applications often bypass.
- Food & Beverages:Licorice-flavored confectionery, alcoholic spirits, and functional beverages drive volume procurement, with EFSA natural flavoring regulations pushing European reformulation toward certified natural extraction routes. Premium soft drink manufacturers now require full supply chain documentation from cultivation plot to finished flavor.
- Pharmaceuticals:Tablet and capsule manufacturers utilize anethole as a flavor-masking excipient and active pharmaceutical ingredient precursor, with CDSCO and SAMR alignment to ICH quality guidelines tightening impurity profiling requirements for solid-dose formulations in India and China.
- Cosmetics:Toothpaste, mouthwash, and skincare applications employ anethole for sensory properties with less stringent purity thresholds than pharmaceutical uses, permitting broader supplier qualification.
- Fragrances:Fine perfumery and functional fragrance bases incorporate anethole for its sweet, warm odor profile, with synthetic material dominating volume contracts where cost transparency favors petrochemical-derived supply.
Food & Beverages leads on scale; Pharmaceuticals leads on momentum.
End User:
End-user category determines procurement sophistication, with pharmaceutical and food manufacturers implementing qualified supplier programs while perfume producers maintain spot-market flexibility for fragrance material sourcing.
- Food Manufacturers:Multinational beverage and confectionery corporations operate approved vendor lists with backward traceability to cultivation plots, replacing commodity brokers with direct distiller contracts. These buyers consolidate procurement to reduce REACH Article 33 audit burden across extended supply chains.
- Pharmaceutical Firms:Generic drug manufacturers in Gujarat and Jiangsu establish pharmacopoeia-compliant supply streams with dedicated regulatory affairs oversight, paying premiums for European Pharmacopoeia certification that accelerates formulation approval timelines.
- Cosmetic Companies:Personal care formulators prioritize sensory performance and cost stability over provenance documentation, maintaining dual sourcing across natural and synthetic origins.
- Perfume Producers:Fragrance houses blend anethole into complex accords where individual ingredient cost contribution diminishes, permitting flexible procurement from spot markets and distributor inventories.
Food Manufacturers leads on scale; Pharmaceutical Firms leads on momentum.
Form:
Form selection reflects manufacturing process integration requirements, with solid-dose pharmaceutical operations driving crystalline and powder specifications while liquid handling dominates flavor and fragrance compounding.
- Liquid:The standard presentation for flavor and fragrance compounding, liquid anethole integrates directly into solvent-based formulations without dissolution steps. Bulk tanker deliveries serve high-volume fragrance compounders in Gujarat's port-proximate processing infrastructure.
- Crystals:High-purity crystalline anethole enables precise gravimetric dosing in pharmaceutical tablet presses and capsule filling equipment, with particle size distribution specifications critical for content uniformity in solid-dose manufacturing.
- Powder:Spray-dried or milled crystalline material improves flow properties for automated pharmaceutical packaging lines, with excipient-grade specifications covering bulk density and moisture content parameters.
- Emulsion:Water-dispersible anethole preparations serve beverage applications requiring oil-in-water stability, simplifying formulation for processors lacking high-shear mixing equipment.
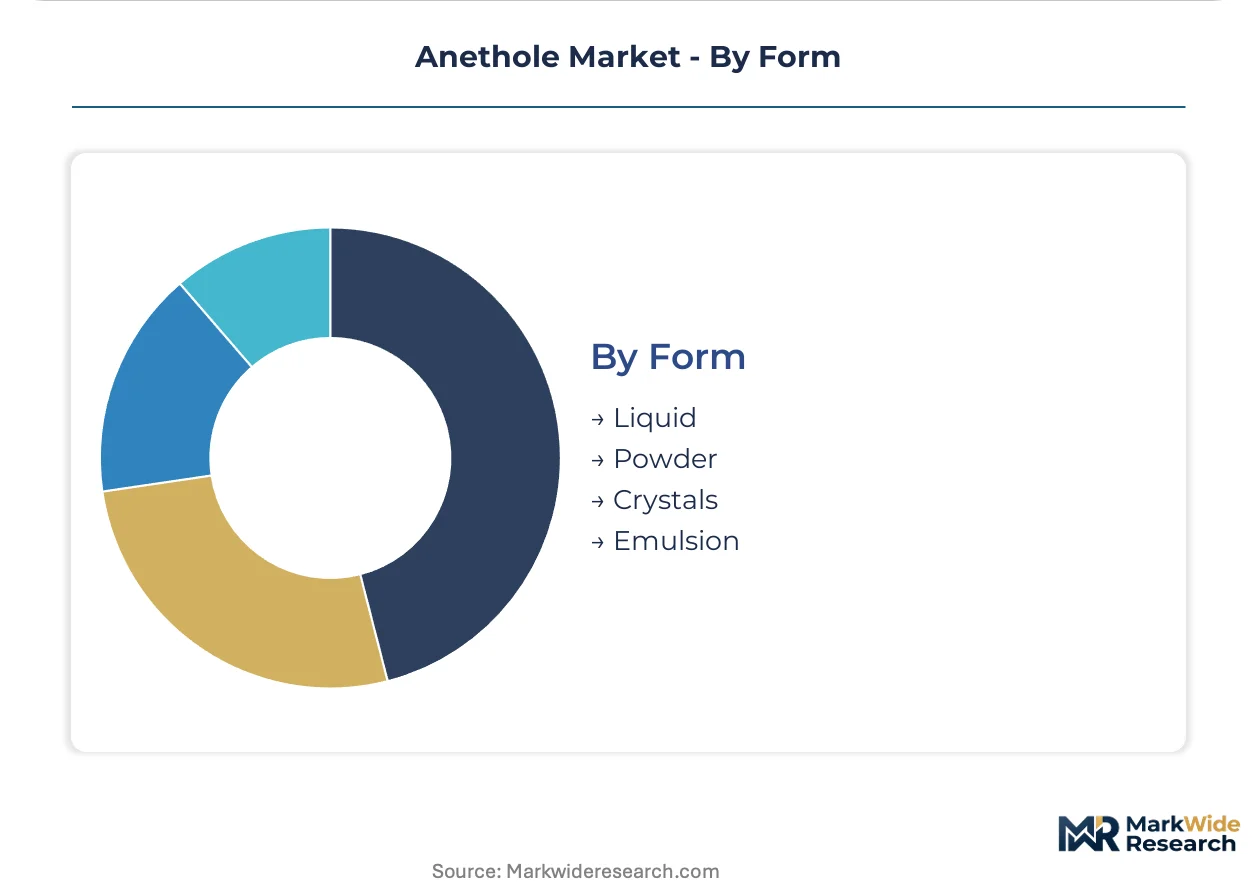
Liquid leads on scale; Crystals leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redrawing production maps as EU REACH compliance costs push natural extraction capacity toward India and China, where fennel cultivation clusters and lower certification overhead compress unit economics for export-oriented suppliers.
China
Jiangsu and Sichuan provinces dominate natural anethole output through captive fennel bases and star anise wild-harvesting networks. SAMR's GB flavoring standards and evolving food safety protocols create testing layers for domestic processors. Jiangsu Jishui Natural Flavor Co. leverages its provincial cultivation footprint to secure raw material traceability for pharmaceutical-grade exports.
India
Gujarat's specialty chemical corridor anchors South Asian fragrance compounding, with Uttar Pradesh's star anise oil distillation feeding backward-integrated suppliers. CDSCO alignment with ICH quality guidelines tightens impurity profiling for solid-dose pharmaceutical applications. Arora Aromatics Pvt. Ltd. maintains distribution reach through in-house distillation assets in Uttar Pradesh.
Germany
Pharmaceutical excipient demand from Merck KGaA and regional generic manufacturers drives premium pricing for European Pharmacopoeia-certified material. ECHA REACH Article 33 obligations require full substance volume tracking through extended safety data sheets. Supercritical CO2 extraction adoption concentrates in Baden-Württemberg and Bavaria processing facilities serving Swiss and German formulators.
United States
FDA 21 CFR 182.60 food additive regulations govern import purity thresholds for flavoring applications, with beverage manufacturers driving clean-label reformulation demand. EPA and OSHA frameworks overlay handling requirements for petrochemical-derived synthetic routes. New Jersey and Illinois fragrance compounders source through consolidated vendor relationships to reduce audit burden.
Switzerland
Swissmedic pharmaceutical excipient monographs and proximity to German chemical processing create premium-tier demand for batch-level Certificates of Analysis. Basel-area pharmaceutical formulators specify chiral purity verification that outpaces technical training pipeline output in traditional producing regions. Swiss buyers pay certification premiums that accelerate formulation approval timelines for multi-jurisdictional suppliers.
Anethole Market Competitive Environment
Chinese producers anchor the natural extraction tier through provincial cultivation control; German and Indian specialists hold pharmaceutical-grade certification advantages through pharmacopoeia alignment. The vendor base stratifies across three archetypes: captive-agriculture distillers with backward plantation integration, synthetic route operators with petrochemical feedstock access, and multi-jurisdictional traders with regulatory affairs infrastructure. Capacity expansion and strategic partnerships dominate competitive moves as REACH compliance costs favor larger suppliers with dedicated certification functions.
Within the captive-agriculture tier, Jiangsu Jishui Natural Flavor Co., Ltd. and Sichuan Huiquan Co., Ltd. exemplify Chinese provincial specialists leveraging in-province fennel bases for traceability documentation. Merck KGaA occupies a position on the premium-certification vector, representing European pharmaceutical-grade supply through European Pharmacopoeia protocols. Arora Aromatics Pvt. Ltd. anchors South Asian distribution reach through Uttar Pradesh distillation assets.
| Leading Market Players |
|---|
| Jiangsu Jishui Natural Flavor Co., Ltd. |
| Thermo Fisher Scientific Inc. |
| Sichuan Huiquan Co., Ltd. |
| Arora Aromatics Pvt. Ltd. |
| AOS Products Pvt. Ltd. |
| Jiangxi Yisite Biotechnology Co., Ltd. |
| Merck KGaA |
| Berje Inc. |
| Guangxi Yulan Chemicals Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Fennel seed procurement costs in Jiangsu and Uttar Pradesh cascade through three distinct pricing tiers before reaching pharmaceutical formulators in Gujarat and Baden-Württemberg, with each handoff adding certification premiums that widen spreads between natural extraction and synthetic alternatives. EU REACH documentation requirements and FDA flavoring substance standards compress margins at every node, forcing consolidation toward suppliers with captive cultivation bases and in-house regulatory affairs functions.
Pricing Analysis
Distributor margins for uncertified natural anethole range between certified pharmaceutical-grade supply and bulk synthetic material, with European Pharmacopoeia compliance adding substantial premiums at each channel layer. Three-tier pricing structure across premium, standard, and economy levels separates batch-tested excipient grade from food-grade natural and industrial synthetic origins. Cost compression in synthetic routes is intensifying because petrochemical feedstock volatility and carbon pricing mechanisms squeeze anisole propenylation economics. Fragrance compounders in Gujarat's specialty chemical corridor exhibit highest price sensitivity, while Swiss pharmaceutical formulators prioritize certification over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle pharmaceutical-grade demand from Merck KGaA and regional generic manufacturers, while distributor networks serve mid-size fragrance compounders lacking qualified supplier program infrastructure. Geographic supply concentration centers on China, India, and Germany, with Jiangsu and Sichuan provinces anchoring natural extraction capacity. Raw material dependencies draw from fennel cultivation plots, star anise wild-harvesting networks, and anisole petrochemical intermediates. Single-source vulnerability in star anise supply from specific Chinese provinces creates concentration risk for natural extraction routes. Distribution runs through port-proximate processing clusters in Gujarat and consolidated vendor relationships in New Jersey and Illinois.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Anethole procurement is shifting toward late-cycle quality specifications as pharmaceutical excipient demand hardens purity requirements beyond food-grade tolerances, with European Pharmacopoeia certification becoming the threshold for premium pricing.
For Market Incumbents: Anticipate fermentation-derived biosynthesis platforms approaching commercial viability by securing fennel cultivation contracts in Jiangsu and Uttar Pradesh before agricultural feedstock constraints tighten. Backward integration into supercritical CO2 extraction assets in Baden-Württemberg defends margin position against synthetic route competitors exposed to energy cost fluctuations. Certification investment in multi-jurisdictional pharmacopoeia alignment creates switching costs for pharmaceutical formulators in Gujarat and Basel. For New Entrants and Emerging Players: EU REACH Article 33 supply chain communication obligations in Europe open a window for regulatory-native entrants offering extended safety data sheet documentation that incumbent traders struggle to provision. Target pharmaceutical-grade crystal and powder specifications where analytical chemistry talent scarcity in producing regions delays incumbent capacity expansion. A go-to-market angle anchored in batch-level Certificate of Analysis transparency captures reformulation demand from premium beverage manufacturers requiring cultivation plot traceability. For Investors and Strategic Acquirers: Consolidation pressure builds where REACH compliance overhead exceeds standalone regulatory affairs infrastructure economics, favoring roll-up strategies around captive-agriculture distillers with provincial cultivation control. Long-term viability frames toward suppliers achieving SAMR, CDSCO, and ICH quality guideline alignment for multi-jurisdictional pharmaceutical contracts. The signal to watch is biotech platform announcements for anethole biosynthesis, which would revalue agricultural-dependent extraction assets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fennel Cultivation | Jiangsu Jishui-style provincial footprint secures raw material traceability for REACH documentation. |
| Supercritical CO2 Extraction Adoption | Baden-Württemberg processing facilities serve Swissmedic-tier pharmaceutical formulators demanding thermal degradation control. |
| Multi-Jurisdictional Pharmacopoeia Certification | European Pharmacopoeia alignment accelerates CDSCO and SAMR approval timelines for generic drug manufacturers. |
| Direct-to-OEM Channel Compression | Gujarat API producers bypass commodity brokers through qualified supplier programs with plot-level traceability. |
| Fermentation-Derived Biosynthesis R&D | Engineered yeast platforms potentially bypass rainfall-dependent fennel harvest volatility in Jiangsu and Uttar Pradesh. |
Study Parameters
Bottom-up pharmaceutical and food-grade demand modeling reconciled against top-down fennel cultivation and synthetic production capacity tracking forms the analytical core of this study. Primary interviews with fragrance compounder procurement leads, pharmaceutical excipient quality directors, essential oil distillation plant managers, and regulatory affairs specialists at import distributors combined with secondary validation from customs trade databases, European Pharmacopoeia monograph filings, SAMR GB standard publications, and SEC 10-K disclosures from listed chemical suppliers. Triangulation across these sources isolates volume flows by grade tier and end-use application.
Historical trendline analysis of natural extraction and synthetic route economics established baseline cost structures, with projection modeling extending across the analysis window through segmented demand growth curves. Segmentation dimensions include product origin, application purity requirements, end-user procurement sophistication, and physical form specifications. CAGRs derived from elasticity-adjusted demand projections incorporate pharmaceutical excipient expansion rates, clean-label beverage reformulation trends, and supercritical CO2 extraction adoption curves in German and Swiss processing facilities.
Revisions become necessary when biotech platform announcements for fermentation-derived anethole materialize, EU REACH substance volume thresholds tighten, or fennel harvest failures in Jiangsu or Uttar Pradesh disrupt natural extraction supply. Forecasts reflect assumptions regarding regulatory alignment timelines, cultivation yield stability, and synthetic feedstock cost trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavor and Fragrance Chemicals
India Essential Oils Market
Flavor and Fragrance Chemicals
Semiochemicals Market
Flavor and Fragrance Chemicals
Europe Deodorants Market
Flavor and Fragrance Chemicals
Musk Aroma Chemicals Market
Flavor and Fragrance Chemicals
Natural Fragrance Chemicals Market
Flavor and Fragrance Chemicals
Middle East and Africa Deodorants Market
Flavor and Fragrance Chemicals
Herbal Fragrance Ingredients Market
Flavor and Fragrance Chemicals
Tannic Acid Market
Flavor and Fragrance Chemicals
Essential Oil Blends Market
Flavor and Fragrance Chemicals
United States Aroma Chemicals Market
Flavor and Fragrance Chemicals
Asia-Pacific Aroma Chemicals Market
Flavor and Fragrance Chemicals
Synthetic Cinnamaldehyde Market
Flavor and Fragrance Chemicals
Guaiacwood Oil Market
Flavor and Fragrance Chemicals
Europe Aroma Chemicals Market
Flavor and Fragrance Chemicals
Natural Fragrance Ingredients Market
Flavor and Fragrance Chemicals
Fragrance Concentrates Market