
 Fragrance Concentrates Market | 2026-2036
Fragrance Concentrates Market Size, Share, and Industry Trends Forecast 2026-2036
Fragrance Concentrates Market Foresight
Multi-sourced raw material procurement is decoupling from traditional single-origin supply chains across the fragrance concentrates industry. Givaudan leverages captive cultivation networks in Grasse and Madagascar to secure botanical supply. Symrise anchors its competitiveness through biotechnology-driven fermentation of renewable feedstocks for aroma molecules. Firmenich differentiates via proprietary captive odorant molecules that downstream customers cannot replicate.
Fragrance concentrates are highly concentrated aromatic formulations, typically comprising 15-40% perfume oil dissolved in carrier solvents such as dipropylene glycol or isopropyl myristate, designed for dilution into finished consumer products. Their primary purpose is to deliver consistent scent performance and stability across diverse applications from eau de parfum to laundry detergents. Aroma chemicals command the largest value share among product types due to reproducibility and cost efficiency at scale, while natural extracts capture premium positioning despite supply volatility. Fine fragrances and personal care applications together absorb the majority of volume, though household care formulations are gaining formulation complexity as brands seek scent differentiation in commoditized categories.
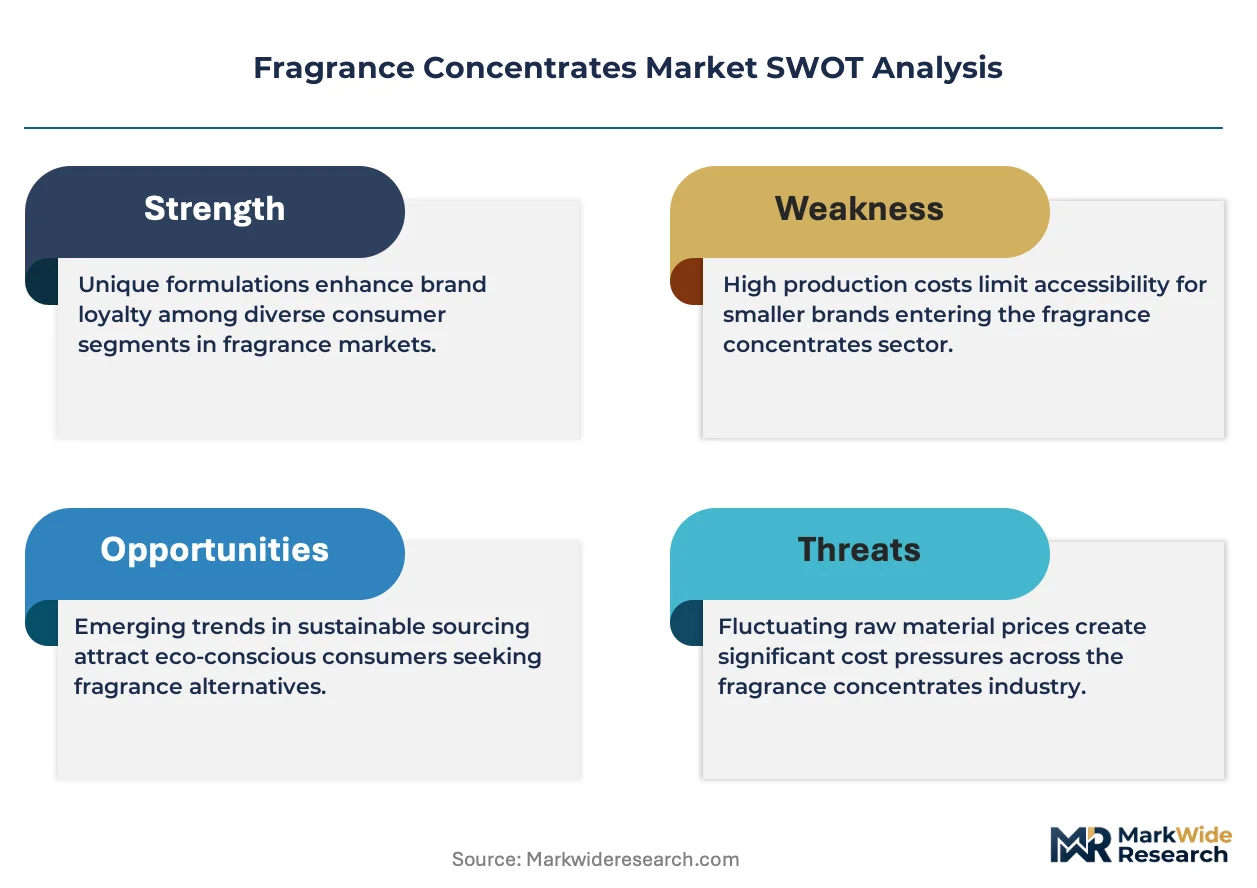
IFRA standards, REACH registration requirements, and FDA cosmetic ingredient regulations collectively constrain formulation freedom and elevate compliance costs for compounders and end users. ECHA's expanding restriction proposals on sensitizer-class fragrance materials are forcing reformulation cycles across European supply chains. Stakeholders must monitor regulatory divergence between Brussels and Washington while building flexible manufacturing architectures that accommodate ingredient substitution without consumer-perceptible quality degradation.
Market Dynamics
REACH registration deadlines and ECHA restriction proposals on sensitizer-class materials are compressing formulation freedom across European supply chains, forcing compounders into accelerated reformulation cycles without consumer-perceptible quality degradation.
Growth Catalysts
- IFRA Standards Expansion:Updated safety guidelines for fragrance materials are elevating compliance investments, creating competitive moats for certified compounders with established testing infrastructure.
- Fine Fragrance Premiumization:Niche perfumery brands are driving procurement of high-purity natural extracts and captive odorant molecules for differentiation in saturated consumer markets.
- Biotechnology Fermentation:Renewable feedstock conversion via microbial synthesis is reducing dependency on petrochemical precursors and volatile botanical harvests.
Market Restraints
- Natural Extract Supply Volatility:Climate-sensitive harvests in Madagascar and Grasse create input cost instability that synthetic alternatives cannot fully hedge.
- Regulatory Fragmentation:Divergence between REACH sensitizer restrictions and FDA cosmetic ingredient disclosure requirements elevates multi-jurisdiction compliance overhead.
- Substitution Pressure:Essential oil blends and plant-derived aroma chemicals face displacement from engineered biosynthetic molecules with reproducible odor profiles.
Strategic Opportunities
- India Formulation Hub Expansion:Converging consumer market scale and contract manufacturing capabilities position Mumbai and Bangalore as regional procurement centers.
- Household Care Scent Differentiation:Laundry detergent and surface cleaner brands are adopting complex fragrance architectures previously reserved for fine fragrances.
- EU Green Deal Chemistry:Bio-based content mandates and carbon border adjustments incentivize fermentation-derived aroma molecule investments with favorable lifecycle credentials.
Industry Challenges
- Perfumer Talent Scarcity:Traditional apprenticeship pipelines in France cannot match demand for compounders capable of navigating IFRA-compliant reformulation.
- Multi-Regulatory Certification Timelines:Parallel REACH registration and FDA fragrance allergen disclosure reviews extend product launch windows by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fragrance Concentrates Market |
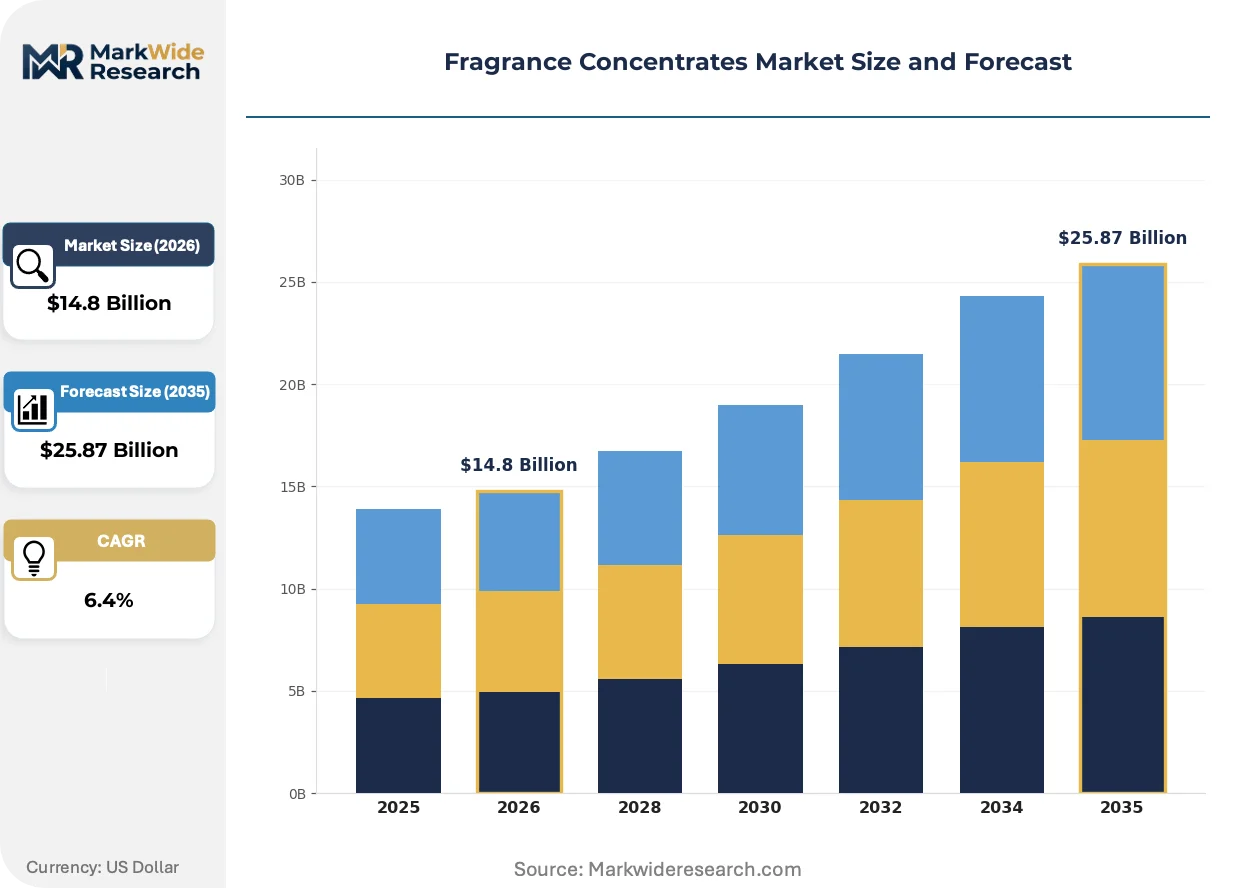
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Essential Oils, Aroma Chemicals, Natural Extracts, Synthetic Compounds Application: Personal Care, Household Care, Fine Fragrances, Air Fresheners, Candles End User: Cosmetic Manufacturers, Soap & Detergent Makers, Cleaning Product Producers, Candle Manufacturers Packaging Type: Glass Bottles, Plastic Containers, Metal Cans, Spray Bottles |
| Companies Covered | Symrise, Takasago, International Flavors & Fragrances (IFF), CPL Aromas, BMV Fragrances, Givaudan, Robertet, Sensient Technologies, Firmenich, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fragrance Concentrates Market Shifts & Advancements
Biotechnology-derived aroma molecules and digital scent formulation tools are compressing traditional development cycles. Regulatory disclosure requirements are tightening ingredient transparency. Procurement concentration among multinational personal care brands is reshaping supplier relationship structures.
Precision fermentation of terpenes and lactones is overtaking solvent extraction from botanical sources as the dominant production mode for high-volume aroma chemicals. Fine fragrance houses in France are adopting these biosynthetic materials for batch-to-batch consistency. This technology is overtaking geographic sourcing strategies that tied supply security to specific growing regions and harvest seasons.
ECHA's expanding restriction proposals on skin-sensitizing fragrance materials are forcing systematic ingredient substitution across European compounder portfolios. The industrial consequence is accelerated R&D allocation toward non-sensitizing molecular architectures with equivalent odor performance. Fine fragrance applications face the most acute pressure, with Grasse-based houses accelerating captive molecule development to preserve proprietary scent signatures.
Direct sourcing partnerships between personal care multinationals and biotechnology aroma producers are disintermediating traditional fragrance house distribution channels. Multinational brands with internal formulation capabilities are contracting directly with fermentation specialists for base notes and musks. This pattern is most visible in the United States, where Procter & Gamble and Unilever have established dedicated procurement teams for renewable aroma molecules.
Fragrance Concentrates Market Segmentation
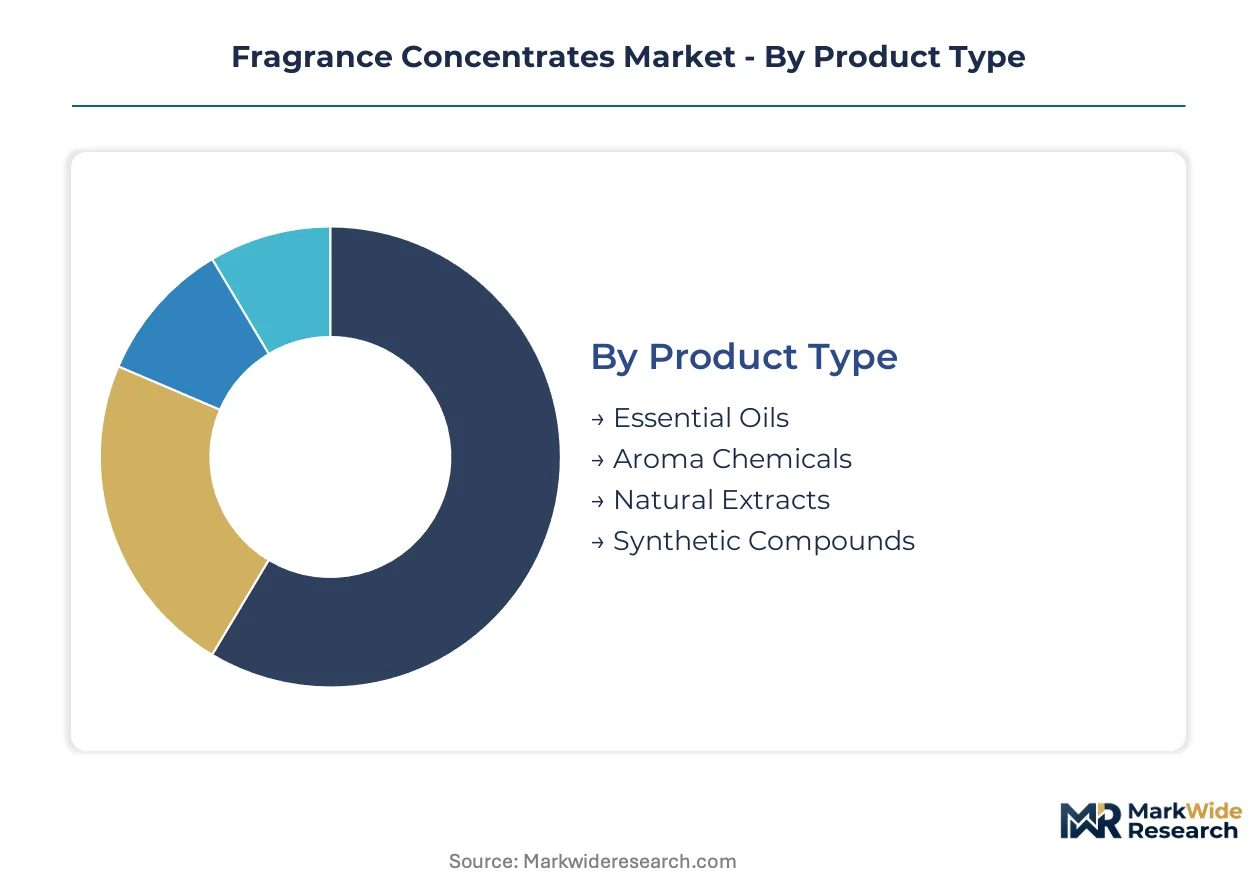
Segmentation in fragrance concentrates reveals divergent margin architectures across material purity grades and end-use sophistication levels. Procurement patterns split sharply between commodity-scale household applications and precision-formulated fine fragrance segments with captive molecule requirements.
Product Type:
Aroma chemicals dominate volume flows while natural extracts command premium positioning, creating a bifurcated supply structure with distinct sourcing protocols.
- Aroma Chemicals:Reproducible synthetic molecules manufactured via petrochemical or biotechnological routes deliver batch consistency at scale. Demand concentrates in mass-market personal care and household cleaning formulations where cost efficiency outweighs provenance claims.
- Natural Extracts:Botanical-derived materials from specific terroirs—Grasse jasmine, Madagascar ylang-ylang, Indian sandalwood—carry supply volatility premiums. Procurement from fine fragrance houses in France and niche perfumers in the United States prioritizes olfactory complexity over price stability.
- Essential Oils:Steam-distilled or cold-pressed plant essences serve mid-tier personal care and aromatherapy applications with moderate purity requirements.
- Synthetic Compounds:Engineered odorant molecules including proprietary captives provide fragrance houses with differentiation barriers against replication.
Mature deployment sits with aroma chemicals. Newer deployment is concentrated in biotechnology-derived natural extracts.
Application:
Formulation complexity escalates from functional scent masking in household products to layered architectural construction in luxury perfumery.
- Fine Fragrances:Eau de parfum and extrait formulations demand 15-40% perfume oil concentration with top-heart-base structure complexity. French and Italian houses drive procurement of high-purity captives and restricted natural materials.
- Personal Care:Skin-safe fragrance systems for lotions, shampoos, and deodorants require IFRA-compliant allergen management. United States and Indian cosmetic manufacturers prioritize stability across varying pH and temperature exposure.
- Household Care:Laundry detergents and surface cleaners incorporate simpler accords for functional malodor coverage rather than aesthetic experience.
- Air Fresheners:Aerosol and gel delivery systems favor cost-optimized aroma chemical blends with high volatility characteristics.
- Candles:Heat-stable fragrance loads compatible with soy and paraffin wax matrices require modified molecular structures to prevent thermal degradation.
Volume concentration centers on personal care. Steepest expansion trajectory belongs to fine fragrances.
End User:
Customer scale determines procurement leverage, with multinational personal care brands disintermediating traditional fragrance house channels through direct biotechnology contracts.
- Cosmetic Manufacturers:Skin care and color cosmetic brands in France, the United States, and India require dermatologically tested fragrance systems with documented safety profiles.
- Soap & Detergent Makers:Mass-market cleaning product producers prioritize cost-optimized aroma chemical procurement with supply security guarantees.
- Cleaning Product Producers:Industrial and institutional sanitation compounders demand functional scents compatible with active biocidal ingredients.
- Candle Manufacturers:Artisan and commercial wax product makers source heat-stable fragrance oils with optimized throw performance.
Established relationships dominate soap and detergent procurement. Direct contracting is expanding fastest among cosmetic manufacturers.
Packaging Type:
Material selection reflects end-use shelf stability requirements and regulatory compliance for chemical compatibility and transport safety.
- Glass Bottles:Inert borosilicate and amber glass containers preserve volatile top notes and prevent UV degradation for high-value natural extracts.
- Plastic Containers:HDPE and fluorinated polymer vessels serve cost-sensitive aroma chemical bulk distribution with permeation resistance.
- Metal Cans:Lacquer-lined aluminum packaging protects solvent-based concentrates from oxidation during extended storage.
- Spray Bottles:Trigger and aerosol systems with compatible propellants enable direct consumer dilution applications.
Glass retains dominance for premium extracts. Plastic containers are gaining share fastest in commodity chemical distribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for fragrance concentrates clusters in France, India, and the United States as formulation centers and consumer markets converge. Fine fragrance houses in Grasse drive procurement of high-purity natural extracts, while contract manufacturers in Mumbai and Bangalore scale output for personal care multinationals. REACH compliance in Europe and evolving IFRA standards are tightening ingredient disclosure requirements across all three markets.
France
Fine fragrance premiumization fuels demand for captive odorant molecules and restricted natural materials from Grasse jasmine fields. ANSM enforces REACH-derived sensitizer restrictions alongside IFRA compliance for dermatological safety. Grasse-based houses accelerate proprietary molecule development to preserve signature scents under regulatory pressure.
United States
Personal care multinationals with internal formulation capabilities contract directly with biotechnology aroma producers for base notes and musks. FDA cosmetic ingredient disclosure requirements create parallel compliance tracks with European standards. Procter & Gamble and Unilever procurement teams in Cincinnati and Englewood Cliffs source renewable aroma molecules through disintermediated channels.
India
Converging consumer market scale and contract manufacturing capabilities position Mumbai and Bangalore as regional procurement centers. BIS standards for cosmetic safety align with IFRA guidelines for fragrance allergen management. Karnataka-based formulation facilities supply IFRA-compliant compounds to domestic cosmetic brands and export markets.
Switzerland
Biotechnology-driven fermentation specialists anchor supply of renewable feedstock-derived aroma molecules. Swissmedic oversight of cosmetic ingredient safety runs parallel to REACH registration requirements for imported materials. Geneva-area innovation clusters develop microbial synthesis platforms for terpenes and lactones displacing botanical extraction.
Japan
Premium personal care brands drive demand for high-stability fragrance systems compatible with varying pH and temperature exposure. METI promotes bio-based chemistry investments through carbon neutrality targets for chemical industries. Osaka and Tokyo formulation centers adopt precision-fermented aroma materials for batch consistency in skin-safe applications.
Fragrance Concentrates Market Competitive Landscape
Strategic partnerships dominate the current landscape as compounders secure captive supply of biotechnology-derived molecules and botanical extracts. The vendor base concentrates around integrated fragrance houses with in-house cultivation networks, fermentation specialists with renewable feedstock platforms, and regional compounders serving price-sensitive household care segments. Three archetypes define competitive positioning: vertically integrated houses controlling upstream botanical supply, technology-driven biotech producers, and flexible regional formulators. M&A activity targets fermentation capabilities and natural extraction assets, while capacity expansion concentrates in India and biotechnology hubs.
Among integrated fragrance houses, Givaudan, Firmenich, and Symrise exemplify divergent supply security strategies. Givaudan leverages captive cultivation networks in specific terroirs to secure botanical inputs. Firmenich occupies a position defined by proprietary captive odorant molecules that downstream customers cannot replicate. Symrise anchors its competitiveness through biotechnology-driven fermentation platforms converting renewable feedstocks into reproducible aroma molecules at scale.
| Leading Market Players |
|---|
| Symrise |
| Takasago |
| International Flavors & Fragrances (IFF) |
| CPL Aromas |
| BMV Fragrances |
| Givaudan |
| Robertet |
| Sensient Technologies |
| Firmenich |
| Others |
Supply & Pricing Matrix
EU Green Deal chemistry mandates gate qualified supply and premium-tier pricing access for fragrance concentrate producers, with bio-based content thresholds determining which compounders capture formulation contracts from multinational personal care brands. REACH-registered molecules command price premiums over unregistered alternatives, while carbon border adjustments penalize petrochemical-derived inputs.
Pricing Analysis
Volume-margin splits separate commodity aroma chemicals from captive odorant molecules. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale differentiation. Price erosion runs through standard-tier aroma chemicals as biotechnology fermentation expands reproducible supply. Household care manufacturers exhibit highest price sensitivity; fine fragrance houses accept premiums for batch-consistent natural extracts.
Supply Chain Analysis
Dual-sourcing requirements from Procter & Gamble and Unilever mandate multi-supplier qualification for base notes and musks. Supply concentrates in France, India, and Switzerland, with Madagascar and Grasse providing botanical inputs. Raw material dependencies include jasmine absolutes, ylang-ylang oil, and fermentation-derived lactones. Single-source vulnerability from climate-sensitive harvests in Madagascar threatens input stability. Distribution runs through integrated fragrance houses and direct biotechnology contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragrance concentrate supply is tightening around qualified fermentation capacity, with bioreactor throughput bottlenecks propping pricing for renewable aroma molecules. Compounders without captive biotechnology platforms face margin compression.
For Market Incumbents: Anchor competitiveness through proprietary captive molecule development that preserves signature scent profiles under ECHA sensitizer restrictions. Accelerate backward integration into precision fermentation assets in Swiss and Indian biotechnology clusters. Biotechnology-driven entrants threaten replication of traditional odorant architectures; defend through exclusive supply agreements with personal care multinationals. For New Entrants and Emerging Players: EU Green Deal chemistry mandates in Europe open a window for fermentation specialists with favorable lifecycle credentials to capture share from petrochemical-dependent incumbents. Target household care scent differentiation as the most penetrable application segment, where complex fragrance architectures are displacing simple accords. Pursue direct contracting with multinational brands possessing internal formulation capabilities. For Investors and Strategic Acquirers: ECHA restriction proposals on sensitizer-class materials is the leading indicator that captive molecule portfolios will command acquisition premiums. Five-to-ten-year viability favors compounders with biotechnology platforms and established IFRA compliance infrastructure. Target fermentation specialists with scalable terpene and lactone production. Watch for accelerated R&D allocation toward non-sensitizing molecular architectures as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Biotechnology Capacity Expansion | Precision fermentation assets in Geneva-area clusters displace botanical extraction for batch consistency. |
| Captive Molecule Development | Proprietary odorant architectures preserve differentiation as ECHA restrictions force systematic substitution. |
| Direct Procurement Partnerships | Multinational brands with internal formulation capabilities contract fermentation specialists for renewable musks. |
| Regulatory Certification Investment | Parallel REACH registration and FDA fragrance allergen disclosure accelerates product launch timelines. |
| Backward Integration into Cultivation | Captive jasmine and ylang-ylang networks in Grasse and Madagascar hedge climate-sensitive harvest volatility. |
Research Methodology
Multi-period observation of formulation complexity indices and biotechnology patent filings anchored the trend analysis, supplemented by interviews with perfumers at Grasse-based houses, procurement directors at personal care multinationals, fermentation specialists in Swiss biotechnology clusters, and regulatory affairs leads navigating REACH compliance. Secondary validation drew from ECHA restriction proposals, IFRA standards updates, customs trade data for aroma chemical flows, and SEC filings from integrated fragrance houses. Bottom-up volume modeling triangulated against top-down value estimates across product type and application segments.
Segment-weighting approaches calibrated value distributions across aroma chemicals, natural extracts, essential oils, and synthetic compounds, with further stratification by fine fragrance, personal care, household care, air freshener, and candle applications. CAGRs derived from fitted growth curves incorporating biotechnology adoption rates, regulatory compliance cost trajectories, and procurement concentration patterns among multinational brands. Forecast inputs included bioreactor capacity expansion timelines and ECHA restriction implementation schedules.
The model assumes a particular technology adoption path; alternative pathways for precision fermentation of terpenes and lactones would alter the outlook for botanical extraction-dependent supply chains. Deviation in ECHA sensitizer restriction scope or REACH registration timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavor and Fragrance Chemicals
Synthetic Cinnamaldehyde Market
Flavor and Fragrance Chemicals
4-Allylanisole Market
Flavor and Fragrance Chemicals
Camphor Market
Flavor and Fragrance Chemicals
Synthetic Musk Market
Flavor and Fragrance Chemicals
Herbal Fragrance Ingredients Market
Flavor and Fragrance Chemicals
Peel Oil Market
Flavor and Fragrance Chemicals
Linalool Market
Flavor and Fragrance Chemicals
Phenethyl Alcohol Market
Flavor and Fragrance Chemicals
Deodorization Systems Market
Flavor and Fragrance Chemicals
Smoke Ingredients Market
Flavor and Fragrance Chemicals
Fragrance Wax Melts Market
Flavor and Fragrance Chemicals
Musk Aroma Chemicals Market
Flavor and Fragrance Chemicals
Bio-Based Flavors and Fragrances Market
Flavor and Fragrance Chemicals
Tangerine Oil Market
Flavor and Fragrance Chemicals
Ethyl Vanillin Market
Flavor and Fragrance Chemicals
Europe Essential Oils Market