
 Smoke Ingredients Market | 2026-2036
Smoke Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Smoke Ingredients Market Analytics
Asset-light contract manufacturing and third-party flavor formulation leasing is tilting competitive dynamics toward specialists who avoid capital-heavy smoke generation infrastructure. Kerry Group leverages captive smoke technology development across European culinary applications. Red Arrow Products Company anchors North American meat processing supply through concentrated liquid smoke platforms. Besmoke specializes in traditional cold-smoke replication for premium cured meat channels.
Smoke ingredients comprise condensed natural smoke vapors, pyroligneous acid fractions, and controlled-combustion particulates standardized for flavor, color, and antimicrobial functionality in food systems. Manufacturing employs fractional condensation at 80-120°C followed by pH adjustment and tar removal to achieve food-grade specifications. Liquid formulations lead ingredient type demand due to dosing precision and extended shelf stability in industrial meat processing, while granule and powder forms sustain growth in dry seasoning blends and snack applications. Distribution through wholesale distributors dominates volume flows, though specialty stores capture margin concentration in artisan smoke ingredient sales.
EFSA additive safety protocols, FDA GRAS self-affirmation requirements, and EU Flavouring Regulation 1334/2008 collectively constrain synthetic smoke analog introduction while privileging verified natural smoke derivatives. Compliance documentation demands now shape supplier qualification timelines and reformulation costs across export-oriented processors. Stakeholders must monitor evolving pyrolysate characterization standards and preemptive regulatory engagement in target jurisdictions.
Market Dynamics
EFSA's tightening additive safety assessments are forcing meat processors across Western Europe to abandon synthetic smoke analogs and validate natural pyrolysate documentation, compressing supplier qualification timelines and reshaping procurement hierarchies toward certified natural smoke specialists.
Growth Catalysts
- Clean-label mandates:EFSA's revised pyrolysate characterization standards are compelling Dutch and German meat processors to reformulate with verified natural smoke derivatives, privileging suppliers with compliant documentation pipelines.
- Liquid smoke precision dosing:Industrial meat facilities are adopting concentrated liquid platforms for antimicrobial functionality and color consistency, displacing traditional smokehouse infrastructure in high-volume operations.
- Snack seasoning diversification:Granule and powder smoke formats are penetrating dry seasoning blends as flavor houses seek shelf-stable alternatives to oil-based carriers in extruded snack applications.
Market Restraints
- Hardwood feedstock volatility:Regional sawmill capacity constraints in the US Southeast and Scandinavian timber belts are compressing pyroligneous acid feedstock availability for fractional condensation facilities.
- Tar removal capex intensity:Food-grade smoke production requires pH adjustment and tar filtration systems that demand sustained capital deployment, disadvantaging smaller regional compounders.
- Natural smoke cost premium:Synthetic smoke analogs retain price advantages in price-sensitive processed meat segments, particularly in export markets with less stringent labeling requirements.
Strategic Opportunities
- Artisan retail channel expansion:Specialty stores and direct-to-consumer platforms are capturing margin concentration in cold-smoke replication products for premium cured meat enthusiasts.
- Plant-based protein convergence:Smoke ingredient suppliers are developing tailored pyrolysate formulations for extruded pea and soy protein matrices, opening adjacent demand in meat-alternative manufacturing.
- EU Flavouring Regulation 1334/2008 compliance services:Documentation and verification consulting for natural smoke derivatives represents a high-margin service layer beyond commodity ingredient sales.
Industry Challenges
- Pyrolysate characterization expertise scarcity:Analytical chemists capable of executing EFSA-mandated polycyclic aromatic hydrocarbon testing and batch consistency verification command premium compensation, constraining quality control scaling.
- Legacy smokehouse integration friction:Industrial meat processors with embedded traditional smoking infrastructure face operational disruption when retrofitting liquid smoke dosing systems into continuous production lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smoke Ingredients Market |
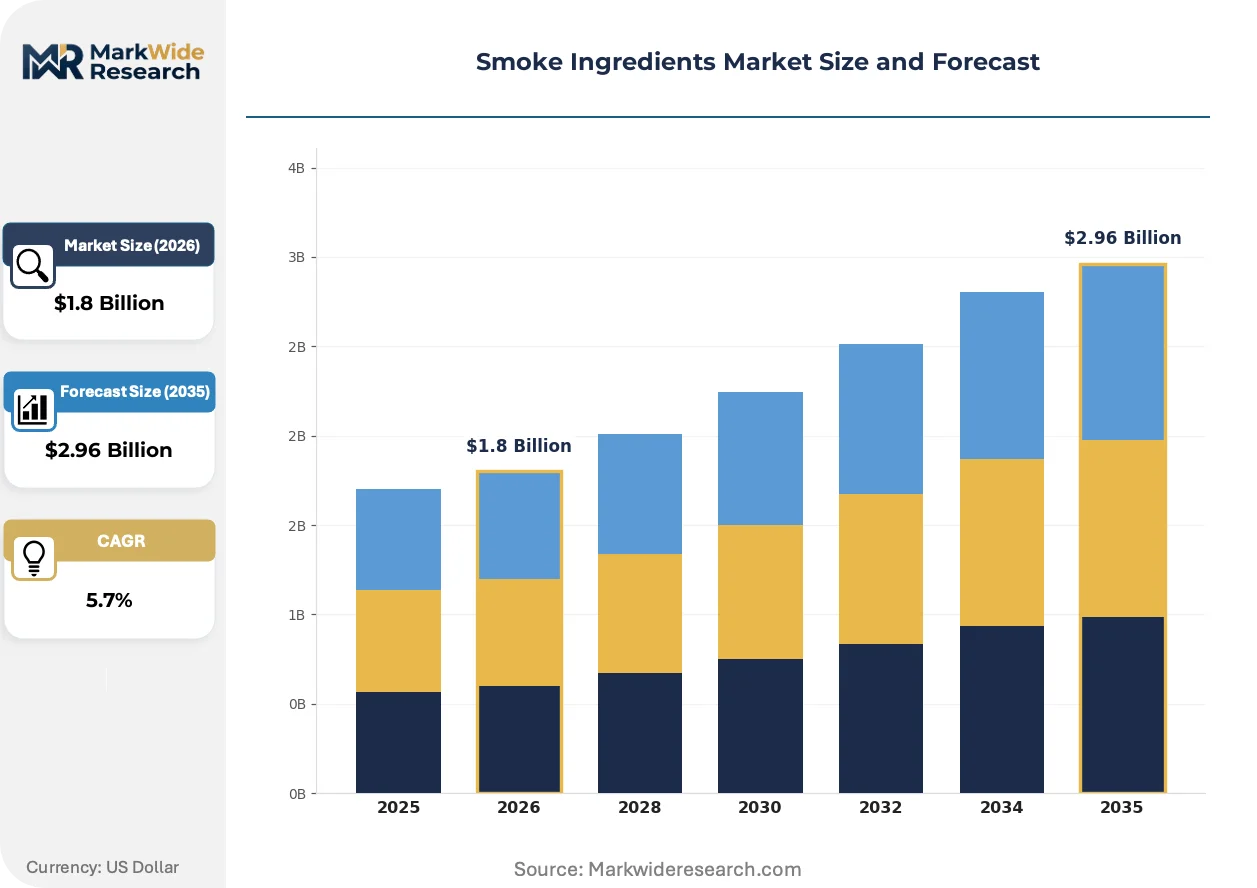
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ingredient Type: Wood Chips, Natural Herbs, Spices, Seasoning Blends Form: Granules, Powders, Liquids, Pellets Application: Meat Processing, Culinary, Food Preservation, Beverage Flavoring Distribution Channel: Online Retail, Specialty Stores, Wholesale Distributors, Supermarkets |
| Companies Covered | Kerry Group, Azelis Holdings, International Flavors & Fragrances, Essentia Protein Solutions, Sensient Technologies, Red Arrow Products Company, Besmoke, B&G Foods, Symrise, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smoke Ingredients Market Evolving Landscape
Smoke ingredient manufacturing is bifurcating between precision-controlled pyrolysis systems and artisan replication techniques, with regulatory documentation capabilities becoming the decisive competitive differentiator across both paths.
Membrane filtration technology is collapsing the traditional multi-stage tar removal and pH adjustment sequence into integrated continuous processing. German equipment suppliers are deploying ceramic membrane systems that simultaneously separate particulates, condense vapors, and standardize acid fractions. This compression is enabling mid-scale processors to achieve food-grade specifications without the capital footprint previously reserved for multinational suppliers.
EU Flavouring Regulation 1334/2008 is tightening natural smoke derivative labeling requirements, mandating detailed pyrolysate source documentation and combustion parameter disclosure. Dutch and German meat processors are now requiring suppliers to submit batch-level hardwood species verification and temperature regime logs. Small compounders without integrated analytics partnerships are exiting the verified natural segment, concentrating compliant supply among documentation-capable specialists.
Buyer concentration among contract meat processors is compressing procurement cycles and unbundling flavor formulation from ingredient supply. Large European ready-meal manufacturers are engaging smoke ingredient suppliers for captive formulation development rather than accepting standard catalog concentrates. This service-layer attachment is most visible in the Netherlands, where private-label prepared food brands demand application-specific smoke profiles with exclusive sensory mapping.
Smoke Ingredients Market Segmentation
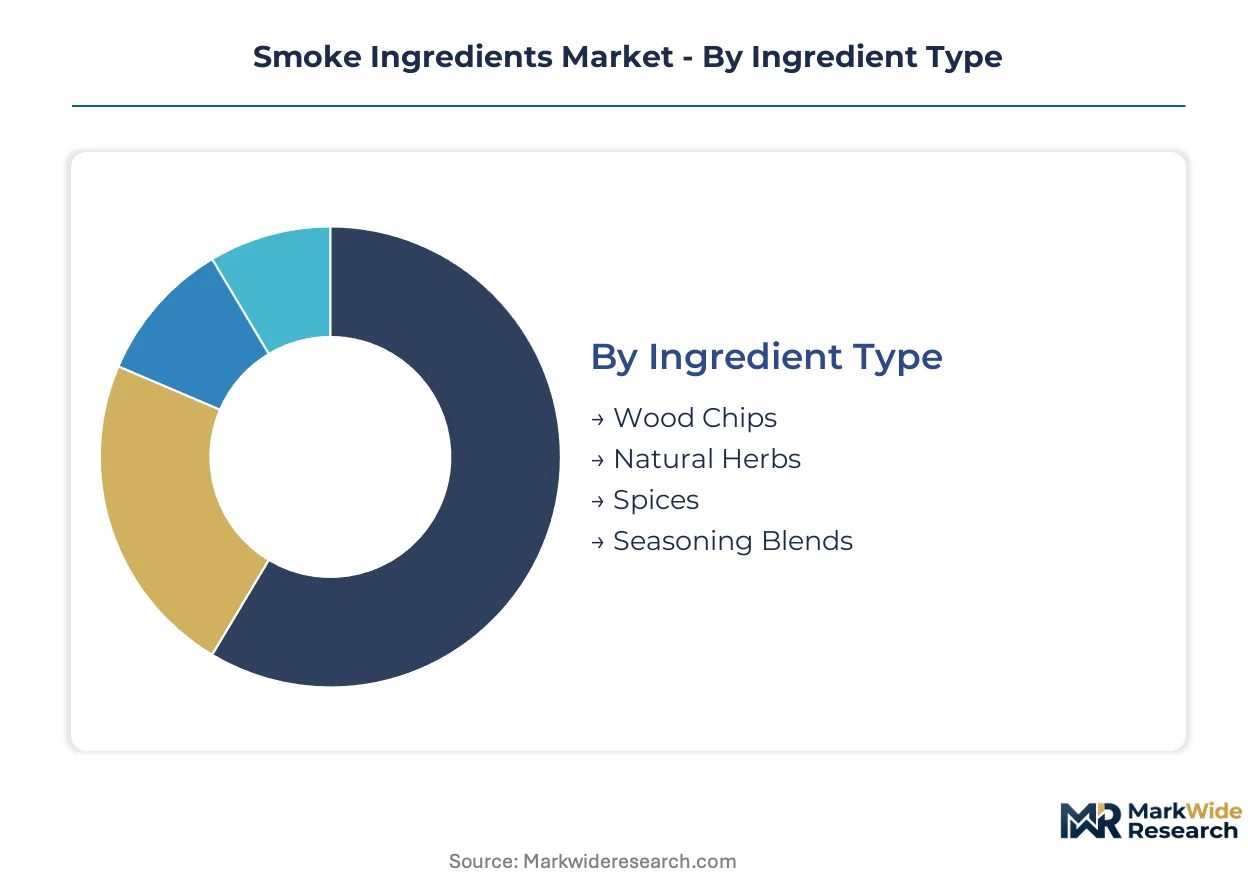
Smoke ingredient procurement diverges sharply across industrial versus artisan use cases, with form factor and distribution channel choices reflecting fundamentally different compliance burdens and margin structures. Segmentation clarity enables suppliers to match documentation capabilities against buyer sophistication tiers.
Ingredient Type:
Mature commodity categories dominate volume flows while emerging botanical segments capture reformulation attention from clean-label processors.
- Wood Chips:Hardwood species—hickory, oak, mesquite, and apple—provide the foundational pyrolysate feedstock for fractional condensation systems. German meat processors favor beech and oak chip derivatives for EFSA-compliant natural smoke documentation, though US Southeast sawmill capacity constraints are compressing regional hickory availability.
- Natural Herbs:Rosemary, thyme, and sage smoke fractions are penetrating premium cured meat channels as processors seek differentiated flavor profiles beyond traditional hardwood bases. Dutch specialty sausage manufacturers are piloting herb-smoke hybrids to satisfy retailer clean-label mandates without synthetic additive exposure.
- Spices:Smoked paprika, chipotle, and black pepper derivatives serve dual flavor-color functions in dry seasoning applications.
- Seasoning Blends:Pre-compounded smoke-herb-spice matrices target small-scale processors lacking in-house formulation capabilities.
Wood chips handle the majority of throughput; natural herbs are gaining share fastest among reformulation-active processors.
Form:
Cost tier stratification separates precision-dosing liquid platforms from commodity dry formats, with capital intensity determining supplier participation thresholds.
- Liquids:Concentrated liquid smoke concentrates enable antimicrobial functionality and color consistency through precision dosing systems. Industrial meat facilities in the Netherlands are displacing traditional smokehouse infrastructure with continuous liquid dosing lines, though tar removal and pH adjustment capex requirements disadvantage smaller compounders.
- Granules:Spray-dried smoke particulates offer shelf stability in dry seasoning blends for snack applications. Flavor houses are adopting granule formats to eliminate oil-based carrier dependencies in extruded protein matrices.
- Powders:Fine-milled smoke derivatives integrate into dry rubs and coating systems for poultry and seafood processors.
- Pellets:Compressed smoke-impregnated hardwood pellets serve traditional smokehouse operators seeking consistent combustion parameters.
Liquids command the premium tier on functionality; granules are expanding most quickly in snack seasoning diversification.
Application:
Customer type concentration varies dramatically across application segments, with contract manufacturers driving standardization versus artisan producers demanding customization.
- Meat Processing:Industrial bacon, ham, and sausage production represents the dominant demand sink for antimicrobial smoke functionality. German and Dutch facilities are mandating batch-level hardwood verification and temperature regime logs under EU Flavouring Regulation 1334/2008, disqualifying suppliers without integrated analytics partnerships.
- Culinary:Restaurant and foodservice channels are adopting liquid smoke for sauce and marinade applications where traditional smoking is operationally impractical.
- Food Preservation:Smoke-derived antimicrobial compounds are penetrating prepared meal and ready-to-eat categories for shelf-life extension.
- Beverage Flavoring:Smoked malt derivatives and pyrolysate infusions are emerging in craft spirits and non-alcoholic beverage innovation pipelines.
Meat processing anchors volume demand; beverage flavoring is climbing the fastest on adjacent category expansion.
Distribution Channel:
Supply concentration patterns separate high-volume wholesale flows from margin-capturing specialty retail, with digital channels fragmenting traditional intermediary structures.
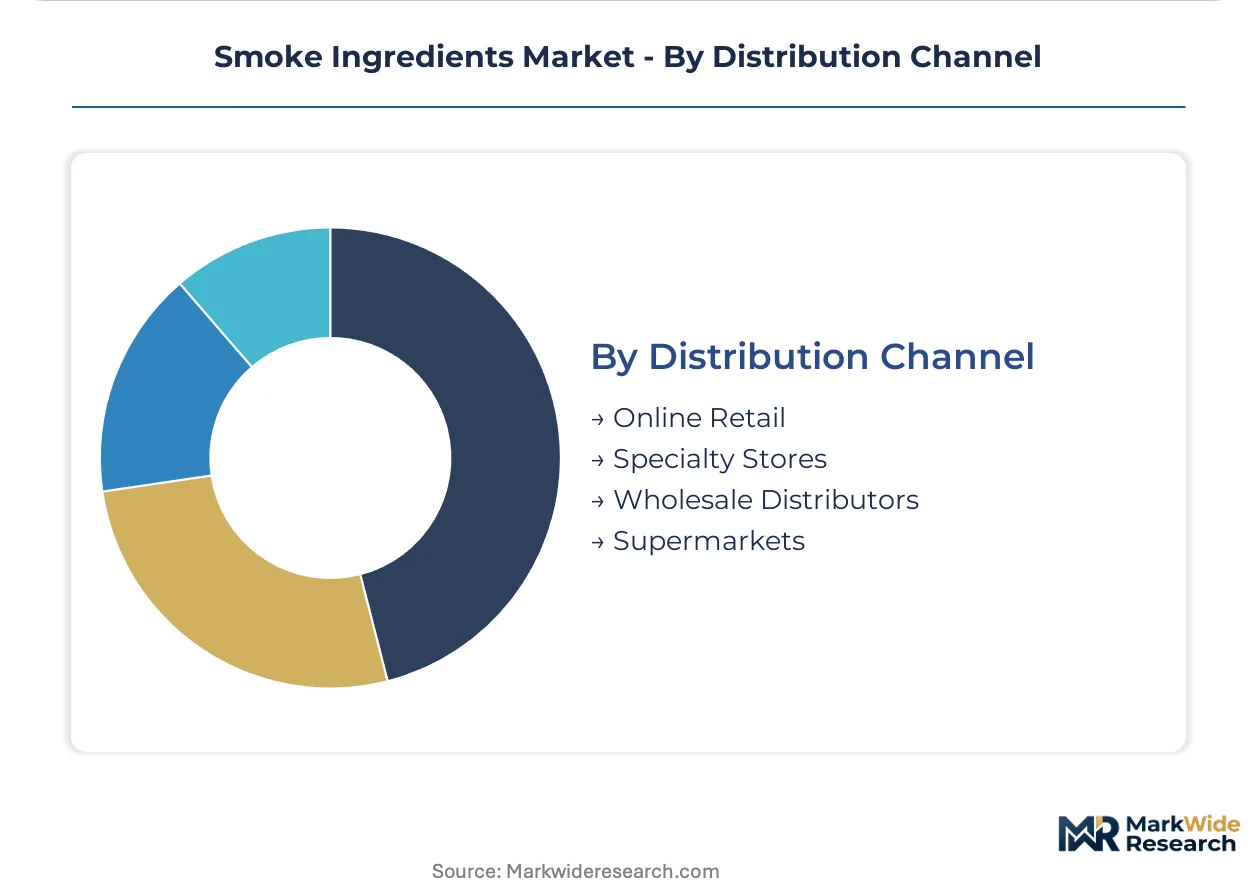
- Wholesale Distributors:Industrial ingredient distributors dominate volume flows to meat processing facilities and flavor houses, bundling smoke derivatives with broader additive portfolios. Procurement cycles are compressing as buyer concentration among contract manufacturers enables direct supplier negotiation.
- Specialty Stores:Artisan retail channels capture margin concentration in cold-smoke replication products for premium cured meat enthusiasts and home smoking hobbyists.
- Online Retail:Direct-to-consumer platforms are disintermediating traditional specialty store relationships for small-batch smoke ingredient producers.
- Supermarkets:Mass retail smoke ingredient placement remains limited to condiment-adjacent positioning rather than standalone ingredient merchandising.
Wholesale distributors move the dominant share; online retail is expanding most quickly on platform-enabled artisan producer access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented processors in Germany and the Netherlands currently dominate intra-European smoke ingredient trade flows, while tariff uncertainties and hardwood feedstock constraints are reshaping transatlantic sourcing patterns for North American meat facilities.
Germany
Industrial bacon and sausage manufacturers in Lower Saxony and Bavaria are mandating batch-level hardwood verification under EU Flavouring Regulation 1334/2008. EFSA's tightened pyrolysate characterization standards have compressed supplier qualification timelines to under six months. The Emsland meat processing cluster is displacing traditional smokehouse infrastructure with continuous liquid smoke dosing lines.
Netherlands
Private-label prepared food brands in the Randstad region demand application-specific smoke profiles with exclusive sensory mapping. Dutch specialty sausage manufacturers are piloting herb-smoke hybrids using rosemary and thyme fractions to satisfy retailer clean-label mandates. The country's central European distribution position enables rapid re-export to Belgian and French processors.
United States
Southeast sawmill capacity constraints in Georgia and Alabama are compressing hickory chip availability for fractional condensation facilities. FDA GRAS self-affirmation requirements privilege suppliers with documented natural smoke derivative portfolios over synthetic analog producers. Chicago-area meat processing facilities are adopting concentrated liquid platforms for antimicrobial functionality in high-volume bacon production.
United Kingdom
Artisan cured meat producers in Yorkshire and the Scottish Highlands are driving demand for cold-smoke replication products through specialty retail channels. Post-Brexit regulatory divergence from EU Flavouring Regulation 1334/2008 is creating documentation complexity for cross-border suppliers. London-based flavor houses are developing tailored pyrolysate formulations for plant-based protein matrices.
China
Domestic meat processors in Shandong and Henan provinces are importing liquid smoke concentrates for sausage and ham production as local hardwood pyrolysis capacity remains underdeveloped. SAMR food additive registration requirements for imported smoke derivatives extend qualification timelines. Yangtze River Delta ready-meal manufacturers are experimenting with smoke-derived antimicrobial compounds for shelf-life extension.
Smoke Ingredients Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in feedstock and fractional condensation. The vendor base separates into multinational flavor houses with captive smoke technology development, mid-scale regional compounders with membrane filtration investments, and artisan specialists focused on cold-smoke replication. Three archetypes dominate: documentation-capable natural smoke specialists, asset-light contract formulators, and vertically integrated hardwood processors. Competitive dynamics center on M&A activity targeting regional compounders with compliant analytics pipelines, and strategic partnerships between equipment suppliers and mid-scale processors seeking membrane filtration deployment.
Within the multinational flavor house tier, Kerry Group and International Flavors & Fragrances occupy positions anchored by broad culinary application portfolios and captive technology development capabilities. Among North American specialists, Red Arrow Products Company exemplifies the concentrated liquid smoke platform archetype serving industrial meat processing supply chains. Besmoke represents the artisan replication specialist segment, focusing on traditional cold-smoke methodologies for premium cured meat channels.
| Leading Market Players |
|---|
| Kerry Group |
| Azelis Holdings |
| International Flavors & Fragrances |
| Essentia Protein Solutions |
| Sensient Technologies |
| Red Arrow Products Company |
| Besmoke |
| B&G Foods |
| Symrise |
| Others |
Value Network & Pricing Analysis
Scandinavian timber belt hardwood availability and US Southeast sawmill capacity constraints concentrate pyroligneous acid feedstock control among fractional condensation specialists, pushing margin pools toward documentation-capable natural smoke derivative suppliers serving EFSA-compliant meat processors.
Pricing Analysis
Industrial meat processing facilities anchor a contract-based long-term offtake pricing structure, with three-tier pricing stratification across premium certified-natural, standard food-grade, and economy synthetic-analog tiers. Price differentiation hinges on EFSA batch-verification documentation and volume scale commitments. Cost compression in the economy tier is intensifying because synthetic smoke analogs retain cost advantages in export markets with weaker labeling requirements. Contract manufacturers exhibit the highest price sensitivity, while artisan cured meat channels absorb premium natural smoke cost premiums without volume negotiation leverage.
Supply Chain Analysis
EU Flavouring Regulation 1334/2008 documentation requirements function as export-control-style restrictions limiting unverified natural smoke derivative flows to compliant buyers. Geographic supply concentrates in Germany, the Netherlands, and the United States, with pyroligneous acid feedstock drawing from Scandinavian beech, US Southeast hickory, and German oak hardwood streams. Single-source vulnerability pervades the hardwood chip tier where regional sawmill capacity constraints create feedstock chokepoints. Distribution runs through wholesale industrial ingredient distributors bundling smoke derivatives with broader additive portfolios to meat processing facilities and flavor houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smoke ingredients market sits in a cyclical recovery phase as EFSA-mandated reformulation waves force processor procurement cycle renewal and supplier qualification pipeline rebuilding across Western European meat facilities.
For Market Incumbents: Insulate compliant documentation capabilities through captive analytics partnerships and preemptive hardwood species verification investments before EFSA pyrolysate characterization standards tighten further. Secure backward integration into Scandinavian and US Southeast sawmill relationships to hedge feedstock volatility threatening margin stability in liquid smoke concentrate production. For New Entrants and Emerging Players: Artisan retail channels and direct-to-consumer platforms for cold-smoke replication products represent the most penetrable entry point, given documentation expertise scarcity disqualifies most regional compounders from verified natural segment participation. Plant-based protein matrix tailored pyrolysate formulations offer a second white-space target where incumbent flavor houses lack application-specific sensory mapping capabilities. A formulation-leasing go-to-market angle bypasses capital-heavy smoke generation infrastructure requirements. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale regional compounders with membrane filtration technology investments and compliant analytics pipelines, positioned for documentation-capable natural smoke segment consolidation. Long-term viability over a multi-year window depends on regulatory divergence resilience between EU and post-Brexit UK frameworks. Watch for hardwood feedstock price spike inflection signals indicating sawmill capacity constraint intensification.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Technology Deployment | Ceramic membrane systems from German equipment suppliers compress tar removal capex for mid-scale processors. |
| Captive Hardwood Feedstock Integration | Backward integration into Scandinavian beech and US Southeast hickory sawmill relationships secures pyroligneous acid supply continuity. |
| EFSA Compliance Documentation Services | Batch-level hardwood verification and temperature regime logging creates high-margin service layers beyond commodity sales. |
| Plant-Based Protein Matrix Formulation Development | Tailored pyrolysate formulations for extruded pea and soy proteins open adjacent demand in meat-alternative manufacturing. |
| Artisan Retail Channel Expansion | Specialty store and direct-to-consumer positioning captures margin concentration in cold-smoke replication for premium cured meat enthusiasts. |
Research Methodology
Cross-validation between primary interviews with meat processing procurement directors, flavor house technical R&D leads, and regulatory affairs specialists and secondary sources including EFSA safety assessment databases, EU Flavouring Regulation 1334/2008 compliance filings, and hardwood trade flow customs records anchors the qualitative findings. Bottom-up segmentation modeling triangulates against top-down macroeconomic drivers across the analysis window.
Calibration against historical price point trajectories and documented supplier qualification timeline compressions shapes the analytical framework. Segmentation dimensions include ingredient type, form factor, application end-use, and distribution channel, with CAGRs derived from volume-weighted growth rate aggregation. Hardwood feedstock availability indices and EFSA regulatory amendment pipelines serve as industry-specific forecast inputs.
Practitioners should monitor EFSA pyrolysate characterization standard amendments and Scandinavian sawmill capacity utilization rates for early signals of forecast revision triggers. Forecasts reflect assumptions about regulatory compliance timeline stability and hardwood supply continuity. Material shifts in EU-UK regulatory divergence trajectories or US Southeast timber harvest policy would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavor and Fragrance Chemicals
Sage Essential Oil Market
Flavor and Fragrance Chemicals
Asia-Pacific Deodorants Market
Flavor and Fragrance Chemicals
Allyl Heptanoate Market
Flavor and Fragrance Chemicals
Nonanal Market
Flavor and Fragrance Chemicals
Flavor and Fragrance Market
Flavor and Fragrance Chemicals
Estragole Market
Flavor and Fragrance Chemicals
Scent Eliminators Market
Flavor and Fragrance Chemicals
Camphor Market
Flavor and Fragrance Chemicals
Flavors for Pharmaceutical and Healthcare Applications Market
Flavor and Fragrance Chemicals
Spearmint Oil Market
Flavor and Fragrance Chemicals
Limonene Market
Flavor and Fragrance Chemicals
Fragrance Ingredients Market
Flavor and Fragrance Chemicals
Synthetic Cinnamaldehyde Market
Flavor and Fragrance Chemicals
Essential Oil Blends Market
Flavor and Fragrance Chemicals
Europe Essential Oils Market
Flavor and Fragrance Chemicals
Global Terpene Market