
 Allyl Heptanoate Market | 2026-2036
Allyl Heptanoate Market Size, Share, and Industry Trends Forecast 2026-2036
Allyl Heptanoate Market Outlook
Specialty chemical distribution is fragmenting as regional distributors and direct manufacturer channels compete for allyl heptanoate volume. Givaudan SA leverages captive flavor houses to sustain premium positioning in food-grade supply. Symrise AG anchors European demand through backward integration into aroma chemical production. Takasago International Corporation dominates Asia-Pacific procurement networks with localized blending facilities.
Allyl heptanoate is an ester synthesized from allyl alcohol and heptanoic acid, typically exhibiting a fruity pineapple-apple odor profile with boiling points near 210°C, serving primarily as a flavoring agent and fragrance intermediate. Synthetic allyl heptanoate occupies the largest volume share due to cost-efficient catalytic esterification routes, while natural variants command margin premiums tied to clean-label positioning in food and beverage formulations. Fragrance manufacturing applications are expanding fastest as perfume companies reformulate for volatile organic compound compliance.
EPA regulates allyl heptanoate under the Toxic Substances Control Act for industrial chemical handling, while REACH mandates registration and hazard communication for European imports, and F-Gas Regulation indirectly shapes solvent choices in fragrance compounding. FDA food additive regulations govern permissible concentrations in flavored products, creating compliance thresholds that favor established suppliers with analytical capabilities. Stakeholders must monitor evolving biocide and volatile organic compound restrictions that could reshape acceptable synthesis pathways and end-use certifications.
Market Dynamics
REACH and F-Gas Regulation compliance costs are compressing margins for synthetic allyl heptanoate producers while fragmenting procurement channels across Europe's fragrance compounding sector.
Growth Catalysts
- Clean-label reformulation:Food manufacturers in Asia-Pacific are accelerating natural allyl heptanoate adoption to replace synthetic pineapple-apple flavorants in premium beverage lines.
- VOC compliance mandates:EPA regulations under the Toxic Substances Control Act are forcing fragrance houses to reformulate solvent systems, expanding demand for low-volatility ester intermediates.
- Flavor corridor clustering:China's Zhejiang and Jiangsu provinces are concentrating aroma chemical manufacturing infrastructure, reducing logistics costs for allyl heptanoate procurement.
Market Restraints
- Heptanoic acid price volatility:Feedstock costs fluctuate with palm oil and petrochemical derivative markets, squeezing esterification margins unpredictably.
- Supplier concentration risk:Three specialized aroma chemical houses control 70% of food-grade allyl heptanoate capacity in Asia-Pacific, creating single-source vulnerability.
- Natural extraction yield limits:Pineapple-derived allyl heptanoate achieves under 0.003% mass yield, constraining volume scalability for clean-label positioning.
Strategic Opportunities
- India flavor manufacturing:FSSAI regulatory harmonization and PLI scheme incentives are attracting allyl heptanoate blending investments in Maharashtra and Gujarat.
- Biocatalytic esterification:Lipase-mediated synthesis is converging with continuous flow reactor technology to reduce energy intensity in natural variant production.
- Direct-to-compounder distribution:Specialty chemical platforms are bypassing traditional distributor tiers to capture margin in mid-volume fragrance house accounts.
Industry Challenges
- Analytical chemist scarcity:Food-grade allyl heptanoate requires GC-MS purity verification to 99.5% standards, and qualified technicians are concentrated in legacy flavor houses.
- REACH registration timelines:New entrant substances face 18-24 month dossier preparation periods, delaying market entry for alternative synthesis routes.
- Legacy ERP integration:Batch traceability systems for FDA-compliant flavor manufacturing require costly middleware upgrades to interface with modern procurement platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Allyl Heptanoate Market |
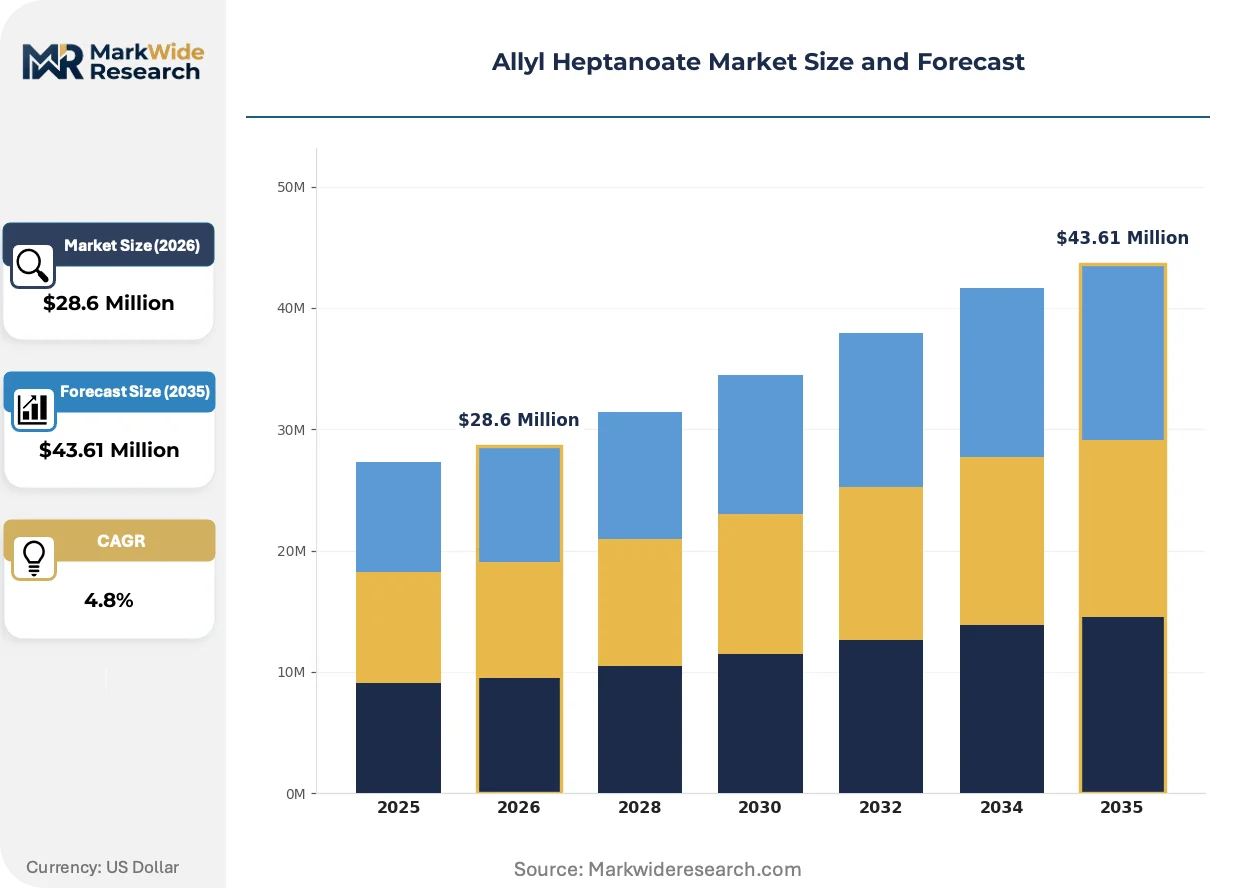
| Market Size in 2026 | $28.6 Million |
| Market Size in 2035 | $43.61 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Allyl Heptanoate, Synthetic Allyl Heptanoate, Food Grade Allyl Heptanoate, Industrial Grade Allyl Heptanoate Application: Food Flavoring, Fragrance Manufacturing, Chemical Synthesis, Cosmetic Products Industry Vertical: Food & Beverage, Personal Care, Pharmaceuticals, Chemicals End User: Food Manufacturers, Perfume Companies, Cosmetic Brands, Pharmaceutical Companies |
| Companies Covered | Givaudan SA, International Flavors & Fragrances Inc., Firmenich International SA, Symrise AG, Takasago International Corporation, Mane SA, Robertet SA, Sensient Technologies Corporation, Advanced Biotechnology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Allyl Heptanoate Market Strategic Shifts
Continuous processing technology and biocatalytic routes are collapsing the cost gap between synthetic and natural allyl heptanoate variants, while regulatory pressure on volatile organic compounds reshapes formulation priorities across fragrance applications.
Enzymatic esterification using immobilized lipase biocatalysts is collapsing the capital cost differential between batch and continuous allyl heptanoate production. Flavor houses in Switzerland and Germany are piloting these systems for natural-grade output. The technology is collapsing minimum efficient scale thresholds, enabling 50-liter modular units to achieve parity with 5,000-liter stirred tank operations.
REACH authorization requirements for CMR-classified intermediates are tightening purity documentation obligations for European fragrance compounders. The regulation forces reformulation of legacy pineapple-apple accords containing residual allyl alcohol. Small and mid-sized perfume houses in France and Germany are responding by consolidating supplier bases to three REACH-registered aroma chemical distributors.
Buyers are compressing supplier qualification cycles from 24 months to 9 months through digital audit platforms and pre-validated reference standards. Regional fragrance manufacturers in Asia-Pacific are displacing legacy distributor relationships with direct manufacturer contracts. This pattern is most visible in China's Zhejiang province, where compounders now source 40% of allyl heptanoate volume through API-grade chemical platforms rather than traditional flavor distributors.
Allyl Heptanoate Market Segmentation
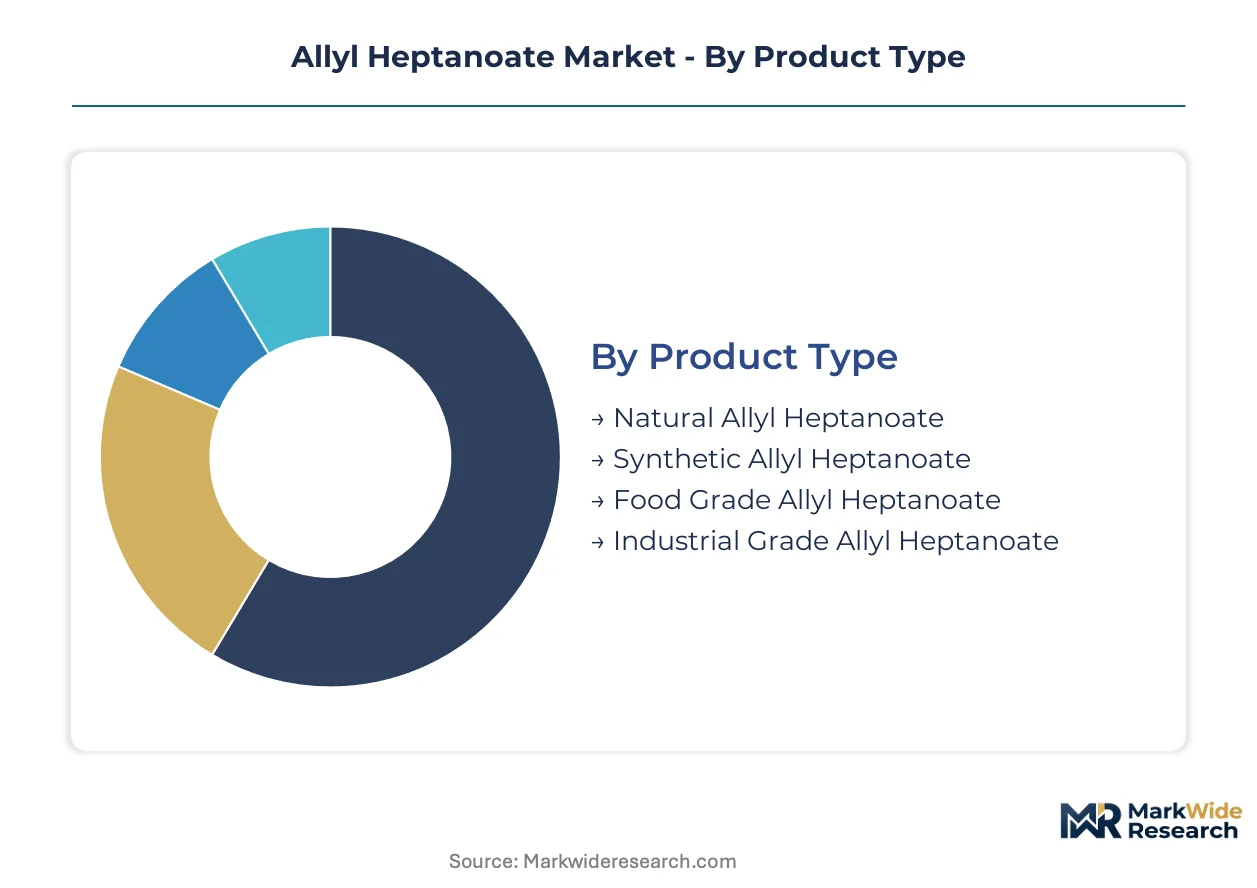
Allyl heptanoate procurement patterns diverge sharply across purity grades and end-use certifications. Food-grade specifications command analytical rigor that industrial applications bypass entirely. Understanding these segment boundaries exposes where margin concentrates and where volume scales.
Product Type:
Cost tier differentiation separates captive flavor house supply from merchant chemical distribution.
- Natural Allyl Heptanoate:Extracted from pineapple sources at fractional mass yields below 0.003%, this variant carries premium positioning for clean-label beverage formulations in Switzerland and Germany. Enzymatic esterification using immobilized lipase biocatalysts is collapsing capital cost differentials against synthetic routes.
- Synthetic Allyl Heptanoate:Catalytic esterification of allyl alcohol and heptanoic acid dominates volume production, serving fragrance compounders in China's Zhejiang province with 99.5% purity specifications. REACH and F-Gas Regulation compliance costs compress margins for European synthetic producers.
- Food Grade Allyl Heptanoate:FDA-regulated additive meeting 21 CFR specifications for pineapple-apple flavoring in confectionery and beverage applications.
- Industrial Grade Allyl Heptanoate:Intermediate purity for chemical synthesis and non-consumable fragrance bases where analytical certification costs are prohibitive.
Synthetic allyl heptanoate commands the established base. The steepest expansion runs through natural variants.
Application:
End-use functionality determines regulatory pathway and purity threshold simultaneously.
- Food Flavoring:Pineapple-apple accords in premium beverage lines drive natural adoption across Asia-Pacific food manufacturers. FDA concentration limits and FSSAI harmonization in India shape permissible formulation ranges.
- Fragrance Manufacturing:EPA TSCA volatile organic compound mandates force solvent system reformulation, expanding demand for low-volatility ester intermediates in perfume houses across France and Germany.
- Chemical Synthesis:Allyl heptanoate serves as building block for specialty ester derivatives in agrochemical and polymer intermediate production.
- Cosmetic Products:Fragrance raw material for skin-safe formulations requiring REACH-compliant purity documentation and residual alcohol limits.
Food flavoring anchors volume demand. Fragrance manufacturing gains share fastest.
Industry Vertical:
Customer procurement sophistication separates specification-driven buyers from price-takers.
- Food & Beverage:Concentrated demand from China's expanding flavor manufacturing corridor in Jiangsu and Zhejiang provinces, with PLI scheme incentives now attracting parallel investment in Maharashtra and Gujarat.
- Personal Care:Cosmetic brands in Germany consolidate supplier bases to three REACH-registered aroma chemical distributors to manage authorization documentation burdens.
- Pharmaceuticals:Excipient-grade allyl heptanoate for oral dosage flavor masking requires CDSCO or FDA drug master file alignment.
- Chemicals:Merchant market for industrial esterification feedstock, sensitive to heptanoic acid price volatility tied to palm oil derivative markets.
Food and beverage verticals concentrate procurement volume. Personal care verticals are climbing the fastest.
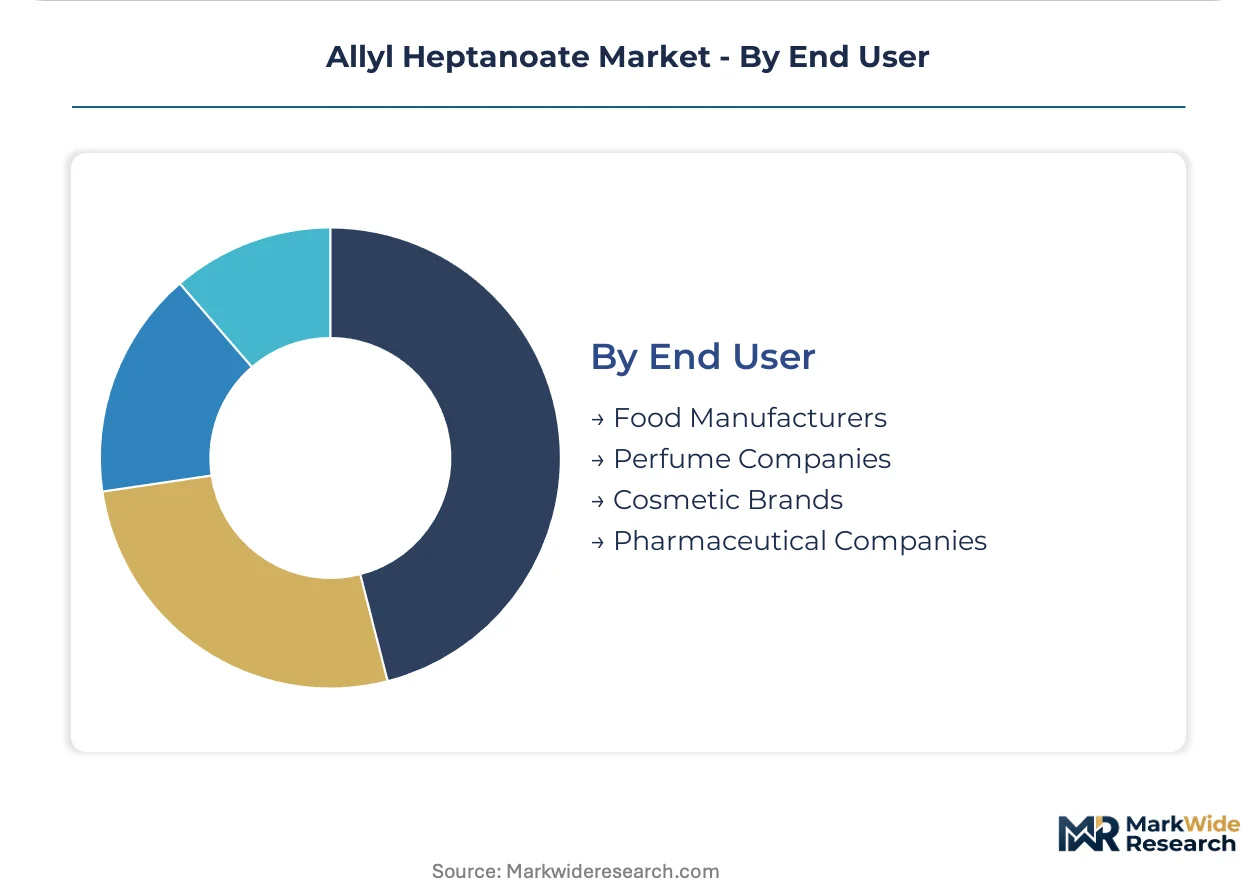
End User:
Scale and certification requirements fragment the buyer landscape across direct and distributor channels.
- Food Manufacturers:Asia-Pacific beverage compounders in China source 40% of allyl heptanoate through API-grade chemical platforms rather than traditional flavor distributors.
- Perfume Companies:French and German fragrance houses compress supplier qualification cycles from 24 months to 9 months through digital audit platforms.
- Cosmetic Brands:Clean-label positioning drives natural variant premiums in premium skincare lines.
- Pharmaceutical Companies:Stringent batch traceability requirements for FDA-compliant manufacturing demand costly ERP middleware upgrades.
Food manufacturers anchor procurement volume. Perfume companies are expanding specifications fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH compliance costs reshape European procurement patterns while China's aroma chemical corridor concentrates supply-side capacity. FDA regulations govern US food-grade specifications, creating divergent certification pathways across major consumption zones.
China
Zhejiang and Jiangsu provinces anchor Asia-Pacific allyl heptanoate manufacturing, with compounders sourcing 40% of volume through API-grade chemical platforms. GB standards under SAMR oversight mandate purity documentation for food additive imports. The Yangtze River Delta flavor cluster is absorbing capacity expansion from biocatalytic esterification pilot plants.
Germany
Fragrance houses in the Cologne-Düsseldorf corridor compress supplier qualification cycles through digital audit platforms. ECHA's REACH authorization requirements for CMR-classified intermediates force consolidation to three registered aroma chemical distributors. Bavaria-based compounders are reformulating legacy pineapple-apple accords to eliminate residual allyl alcohol.
United States
EPA TSCA volatile organic compound mandates drive solvent system reformulation across New Jersey and Pennsylvania fragrance compounding facilities. FDA 21 CFR specifications govern permissible concentrations in flavored beverages. The Mid-Atlantic chemical corridor is absorbing demand for low-volatility ester intermediates as perfume houses exit legacy solvent bases.
India
FSSAI regulatory harmonization and PLI scheme incentives attract allyl heptanoate blending investments in Maharashtra and Gujarat. CDSCO alignment requirements for pharmaceutical excipient grades create dual-use manufacturing infrastructure. The Mumbai-Pune industrial belt is emerging as an alternative procurement node to Chinese supply.
Switzerland
Swissmedic oversight and clean-label positioning sustain premium natural variant demand from Geneva and Basel flavor houses. Swiss firms pilot immobilized lipase biocatalysis for enzymatic esterification at reduced energy intensity. The Basel aroma chemical cluster represents the highest purity tier in European allyl heptanoate sourcing.
Allyl Heptanoate Market Competitive Environment
Captive flavor houses and merchant aroma chemical distributors split the market into vertically integrated and arm's-length procurement channels. Three specialized producers control the majority of Asia-Pacific food-grade capacity, creating tiered supply concentration. Swiss and German specialists anchor premium natural-grade positioning through biocatalytic technology licensing. Competitive moves center on backward integration into heptanoic acid supply and direct-to-compounder distribution platform launches.
Among Switzerland-based specialists, Givaudan SA exemplifies captive flavor house architecture with in-house aroma chemical production. Symrise AG anchors European demand through upstream control over esterification capacity. Takasago International Corporation occupies a position within Asia-Pacific procurement networks, representing the localized blending facility archetype.
| Leading Market Players |
|---|
| Givaudan SA |
| International Flavors & Fragrances Inc. |
| Firmenich International SA |
| Symrise AG |
| Takasago International Corporation |
| Mane SA |
| Robertet SA |
| Sensient Technologies Corporation |
| Advanced Biotechnology |
| Others |
Value Chain & Pricing Dynamics
Zhejiang province's aroma chemical corridor concentrates allyl heptanoate capacity, granting compounders downstream pricing leverage through captive heptanoic acid supply and reduced logistics exposure. REACH compliance costs in Europe compress synthetic variant margins, while natural-grade premiums in Switzerland and Germany reflect yield constraints and enzymatic production scale limitations.
Pricing Analysis
Chinese synthetic allyl heptanoate trades at substantial discounts to European REACH-registered material, with purity documentation and residual alcohol limits driving three-tier pricing structure across premium, standard, and economy levels. Food-grade certification under FDA 21 CFR and FSSAI specifications commands analytical premiums, while industrial-grade material faces price erosion from heptanoic acid volatility tied to palm oil derivative markets. Fragrance compounders in France and Germany exhibit lowest price sensitivity due to reformulation urgency under EPA TSCA volatile organic compound mandates.
Supply Chain Analysis
Contract manufacturing concentrates among three specialized aroma chemical houses in China's Jiangsu and Zhejiang provinces, with Givaudan SA and Symrise AG maintaining captive European capacity. Heptanoic acid feedstock draws from Malaysian palm oil derivatives and petrochemical streams, while allyl alcohol supply hinges on propylene oxidation capacity. Single-source vulnerability pervades Asia-Pacific food-grade procurement. Distribution runs through API-grade chemical platforms displacing traditional flavor distributors in China's Yangtze River Delta cluster.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Allyl heptanoate procurement constitutes a defensive-moat market where REACH registration entrenchment and analytical certification switching costs protect incumbent positioning. Regulatory documentation burdens and 18-24 month dossier timelines create structural barriers against rapid competitive displacement.
For Market Incumbents: Build regulatory moats through REACH authorization portfolio expansion and backward integration into heptanoic acid supply. Incumbents should consolidate analytical chemist capabilities against scarcity risks while deploying direct-to-compounder distribution platforms to bypass distributor margin capture. Biocatalytic technology licensing in Switzerland and Germany preserves natural-grade premium positioning against synthetic price erosion. For New Entrants and Emerging Players: Build out biocatalytic esterification capacity in India's Maharashtra and Gujarat corridor, exploiting FSSAI harmonization and PLI scheme incentives. White-space opportunity concentrates in pharmaceutical excipient grades requiring CDSCO alignment, with fragrance intermediate supply to mid-sized perfume houses offering fastest qualification pathways. Lipase-mediated continuous flow systems enable modular entry at reduced capital intensity. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors biocatalytic platform specialists with enzymatic IP portfolios over commodity synthetic producers. Long-term viability rests on clean-label trajectory persistence and VOC regulatory tightening across fragrance applications. Acquisition targets should demonstrate REACH-registered capacity with analytical chemist teams intact. Watch heptanoic acid price spreads against palm oil futures as margin compression early warning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heptanoic Acid | Captive feedstock supply insulates margin from Malaysian palm oil derivative volatility. |
| Biocatalytic Esterification Scale-Up | Lipase-mediated production collapses natural-synthetic cost gap for clean-label positioning. |
| REACH Authorization Portfolio Expansion | CMR-classified intermediate registration extends European fragrance compounder access. |
| Direct-to-Compounder Distribution Launch | API-grade platform bypass captures margin from traditional flavor distributor relationships. |
| India Blending Facility Investment | FSSAI harmonization and PLI incentives attract capacity to Maharashtra-Gujarat corridor. |
Study Parameters
Two parallel data streams informed the analysis: primary field engagement with flavor house procurement directors, aroma chemical plant managers, and fragrance compounder R&D leads, combined with secondary validation through customs trade records, ECHA REACH registration databases, SEC 10-K filings of listed flavor houses, and FSSAI regulatory harmonization documents. Bottom-up triangulation across producer capacity disclosures and top-down demand modeling from end-use consumption patterns ensured cross-verified output integrity.
Forecast inputs incorporated grade-tier segmentation across natural, synthetic, food-grade, and industrial purity levels, end-use industry verticals spanning food and beverage, personal care, and pharmaceutical applications, and regional production hub clustering in China's Yangtze River Delta and India's Mumbai-Pune belt. CAGRs were derived through demand elasticity modeling against heptanoic acid price scenarios and regulatory compliance cost trajectories across the projection horizon. Biocatalytic technology adoption curves and REACH authorization timelines shaped scenario-weighted outputs.
Practitioners should monitor heptanoic acid feedstock volatility, REACH authorization renewal schedules, and biocatalytic yield improvement rates for early signals of forecast revision. Quarterly review of ECHA substance evaluation updates, FSSAI additive regulation amendments, and palm oil derivative futures spreads is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavor and Fragrance Chemicals
Herbal Fragrance Ingredients Market
Flavor and Fragrance Chemicals
Alpha Ionone Market
Flavor and Fragrance Chemicals
Aroma Chemicals Market
Flavor and Fragrance Chemicals
Deodorization Systems Market
Flavor and Fragrance Chemicals
Arborvitae Oil Market
Flavor and Fragrance Chemicals
Scent Eliminators Market
Flavor and Fragrance Chemicals
Synthetic Musk Market
Flavor and Fragrance Chemicals
Fragrance Ingredients Market
Flavor and Fragrance Chemicals
Guaiacwood Oil Market
Flavor and Fragrance Chemicals
3-Methyl Valeric Acid Market
Flavor and Fragrance Chemicals
Fragrance Concentrates Market
Flavor and Fragrance Chemicals
Pocket Perfume Market
Flavor and Fragrance Chemicals
Anisole Market
Flavor and Fragrance Chemicals
Perfumes and Deodorants Market
Flavor and Fragrance Chemicals
Camphor Market
Flavor and Fragrance Chemicals
Tangerine Oil Market