
 Dry Pet Food Market | 2026-2036
Dry Pet Food Market Size, Share, and Industry Trends Forecast 2026-2036
Dry Pet Food Market Analysis
Multi-format bundling is expanding across retail channels as manufacturers combine kibble with freeze-dried toppers and functional supplements in single SKUs. Mars, Incorporated leverages its veterinary clinic network to anchor prescription dry diets within professional channels. Nestlé S.A. sustains broad manufacturing scale across multiple protein-source formulations. Blue Buffalo Co., Ltd. specializes in grain-free positioning that commands premium placement in pet specialty stores.
Dry pet food comprises extruded or baked formulations with moisture content below ten percent, typically manufactured through high-temperature extrusion followed by drying and fat coating to ensure shelf stability and nutrient density. Kibble dominates volume production due to extrusion efficiency and packaging economics, while freeze-dried segments capture disproportionate margin pools through minimal processing claims and raw nutrition positioning. Natural and organic ingredient quality tiers are expanding fastest as label-conscious owners scrutinize supply chain provenance.
The FDA Center for Veterinary Medicine governs ingredient safety and labeling claims in the United States, while the EU's FEDIAF nutritional guidelines shape formulation standards across European markets. The EU Green Deal's packaging waste directives are pressing manufacturers toward recyclable mono-material bags and reduced plastic content. Stakeholders must monitor evolving state-level extended producer responsibility laws and protein-source sustainability certifications as these frameworks increasingly determine market access and brand positioning.
Market Dynamics
Pet humanization is restructuring manufacturer portfolios as urban households demand clinical-grade nutrition transparency and protein-source traceability previously reserved for human food categories.
Growth Catalysts
- EU Green Deal packaging directives:Recyclable mono-material mandates are accelerating R&D investment in barrier-coated paper alternatives to multi-layer plastic laminates.
- Freeze-dried toppers:Functional meal-enhancement formats are capturing margin pools through minimal processing claims that justify 3-4x kibble pricing.
- Veterinary clinic networks:Professional channel anchoring of prescription diets is creating switching costs that lock households into single-brand ecosystems.
Market Restraints
- Animal protein input volatility:Chicken meal and fish meal prices fluctuate with livestock epidemiology and marine catch quotas, compressing gross margins unpredictably.
- Extrusion equipment concentration:High-capacity twin-screw extruders are manufactured by a narrow German and Italian supplier base, creating 18-24 month lead time bottlenecks.
- FDA ingredient approval timelines:Novel protein sources and fermentation-derived nutrients face 24-36 month evaluation windows that delay formulation launches.
Strategic Opportunities
- Insect protein regulatory tailwinds:EFSA novel food approvals for black soldier fly larvae are opening formulation pathways with 90% lower land use than conventional livestock.
- Direct-to-subscription channels:Customized kibble blends delivered on 4-week cycles are bypassing retail slotting fees and capturing lifetime value data.
- Cell-cultured meat convergence:Bioreactor technology paired with extrusion expertise is positioning early movers for post-2030 commercialization of slaughter-free protein.
Industry Challenges
- Pet food safety certification complexity:FSSC 22000 and Safe Quality Food audits require dedicated quality teams that strain mid-tier manufacturer overhead structures.
- Legacy ERP integration with traceability platforms:Blockchain-enabled ingredient tracking demands API overhauls that disrupt production scheduling systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dry Pet Food Market |
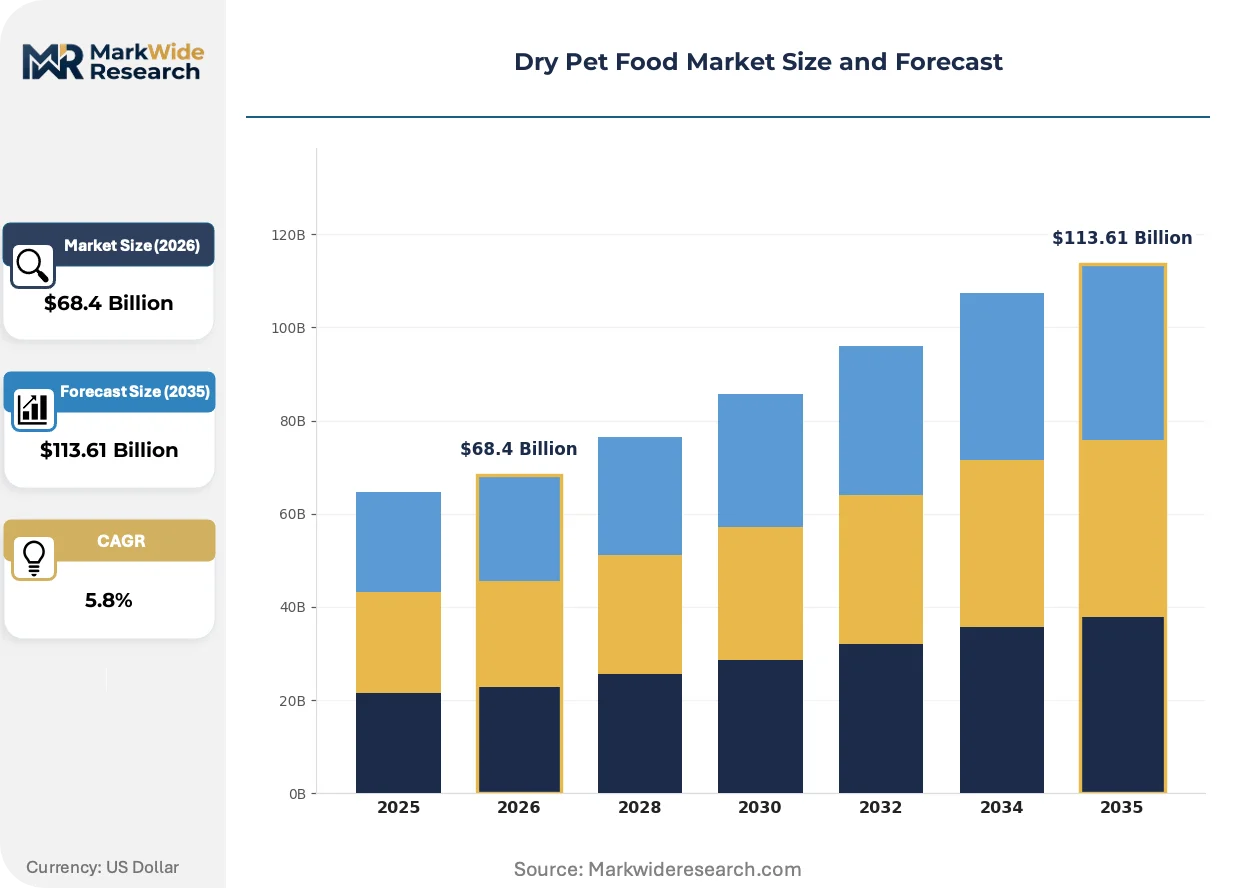
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $113.61 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Kibble, Pellets, Freeze-Dried, Dehydrated Ingredient Quality: Premium, Natural, Organic, Grain-Free Packaging Type: Bags, Tins, Pouches, Bulk Distribution Channel: Online Retail, Supermarkets, Pet Stores, Wholesalers |
| Companies Covered | Colgate-Palmolive Company, Hill's Pet Nutrition, Mars, Incorporated, Royal Canin SAS, Blue Buffalo Co., Ltd., Nestlé S.A., General Mills Inc., Spectrum Brands Holdings Inc., J.M. Smucker Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dry Pet Food Market Emerging Trajectories
Formulation science is converging with precision fermentation and alternative protein engineering to redefine nutritional density benchmarks and sustainability credentials simultaneously.
Cold-pressed extrusion technology preserves heat-sensitive amino acids and probiotics that conventional high-temperature processing degrades. Premium and super-premium manufacturers are retrofitting production lines to capture the raw nutrition positioning that commands shelf space in pet specialty retail. This equipment transition is modularizing plant configurations, allowing facilities to toggle between kibble, baked, and air-dried formats within single production cycles.
The EU Green Deal's packaging waste directives are mandating 70% recyclable content by 2030 for consumer goods sold in member states. Manufacturers are trialing metallized paper laminates and water-based barrier coatings to replace aluminum oxide layers. Wet pet food and dry formats with high fat content face the steepest technical hurdles, driving joint development programs between film suppliers and major brand owners.
Subscription-based replenishment is displacing bulk warehouse purchasing among millennial and Gen Z pet owners who prioritize convenience over per-pound economy. Chewy and Amazon's recurring delivery models are capturing household data that enables predictive formulation and personalized supplement bundling. This behavioral shift is most pronounced in coastal United States metropolitan areas where same-day delivery infrastructure is densest.
Dry Pet Food Market Segmentation
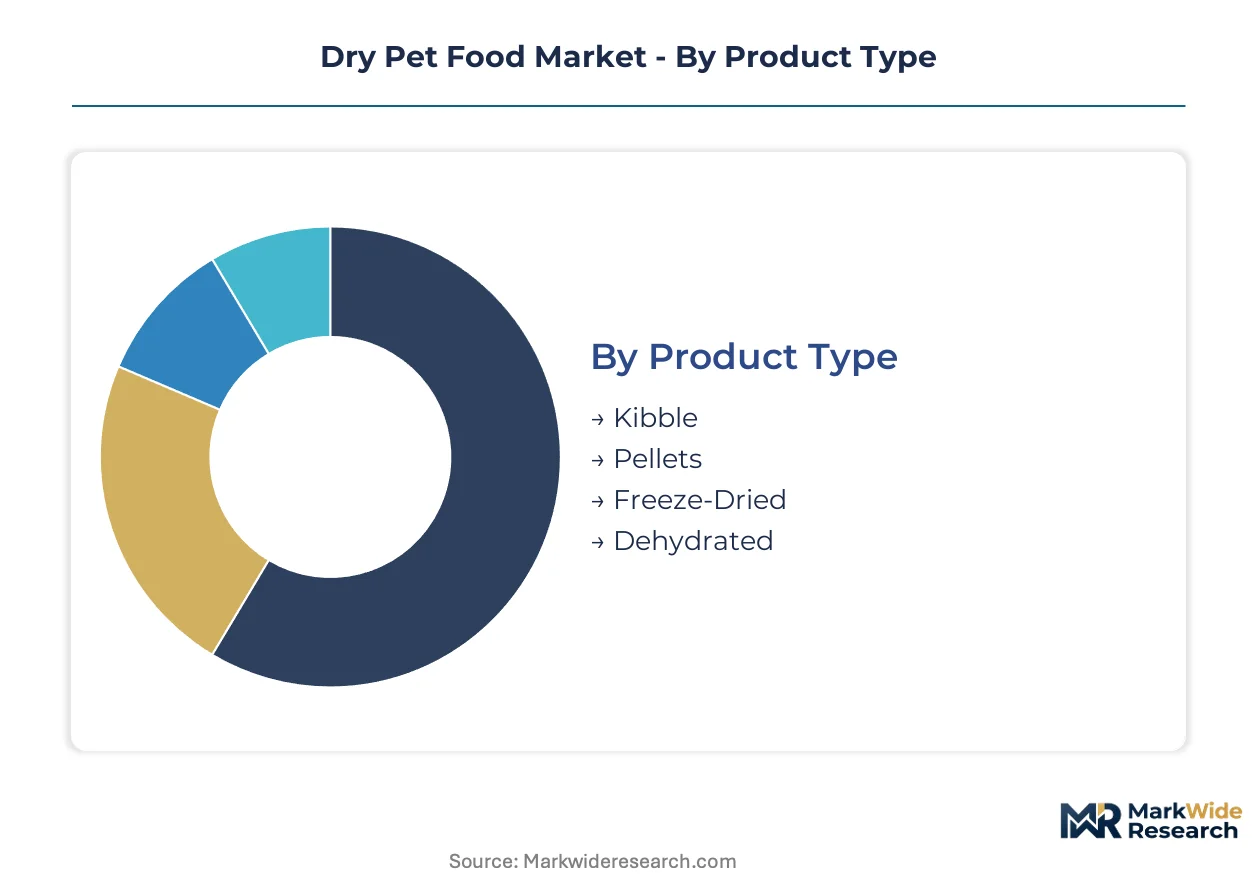
Segmentation in dry pet food reveals how manufacturing scale, ingredient sourcing, and channel economics partition value capture. Each dimension exposes distinct margin structures and competitive moats that determine portfolio allocation decisions.
Product Type:
Extrusion capacity concentrates among high-volume kibble producers while freeze-dried specialists command premium positioning through capital-light batch processing.
- Kibble:Extruded formulations dominate volume production through continuous high-temperature processing that yields shelf-stable products with moisture below ten percent. United States households in metropolitan corridors sustain the bulk of demand as veterinary endorsement and bulk purchasing economics reinforce brand loyalty.
- Freeze-Dried:Minimal thermal exposure preserves raw nutritional integrity and justifies substantial price premiums over conventional formats. Coastal urban markets in California and New York exhibit strongest uptake among millennial owners prioritizing biologically appropriate feeding claims.
- Pellets:Compressed feed formats serve large-breed and working dog segments with higher caloric density per volume.
- Dehydrated:Gentle air-drying retains enzyme activity while achieving shelf stability without synthetic preservatives.
Today's leader: Kibble. Tomorrow's challenger: Freeze-Dried.
Ingredient Quality:
Cost tier stratification separates commodity formulations from certified supply chains that command retail price multiples.
- Premium:Named meat meals as first ingredients with guaranteed analysis exceeding AAFCO minimums by substantial margins. Veterinary clinic networks in the United States anchor prescription-grade positioning that locks households into recurring purchase cycles.
- Grain-Free:Legume and tuber carbohydrate substitutes address perceived gluten sensitivity concerns among companion animal owners. Pet specialty retailers in Texas and Florida allocate disproportionate shelf space to these formulations despite ongoing FDA investigation into dilated cardiomyopathy correlations.
- Natural:Absence of artificial colors, flavors, and preservatives meets baseline clean-label expectations.
- Organic:USDA-certified ingredient provenance satisfies regulatory compliance for export markets and domestic premium positioning.
Grain-Free formulations face regulatory headwinds. Natural tiers gain share fastest.
Packaging Type:
Volume scale and perishability risk determine format selection across retail and institutional channels.
- Bags:Multi-wall paper and plastic laminates constitute the standard for retail kibble distribution. EU Green Deal mandates are accelerating mono-material recyclable alternatives with water-based barrier coatings.
- Bulk:Institutional purchasers and multi-pet households favor loose-fill dispensing that eliminates unit packaging costs. Warehouse club channels in the United States sustain this format despite limited shelf-life guarantees.
- Pouches:Stand-up flexible formats with resealable closures serve trial-size and premium positioning needs.
- Tins:Metal canisters preserve ultra-premium and prescription formulations against oxidation and moisture ingress.
Bags dominate tonnage. Bulk formats climb fastest in subscription channels.
Distribution Channel:
Customer acquisition economics and data capture capabilities separate channel strategies.
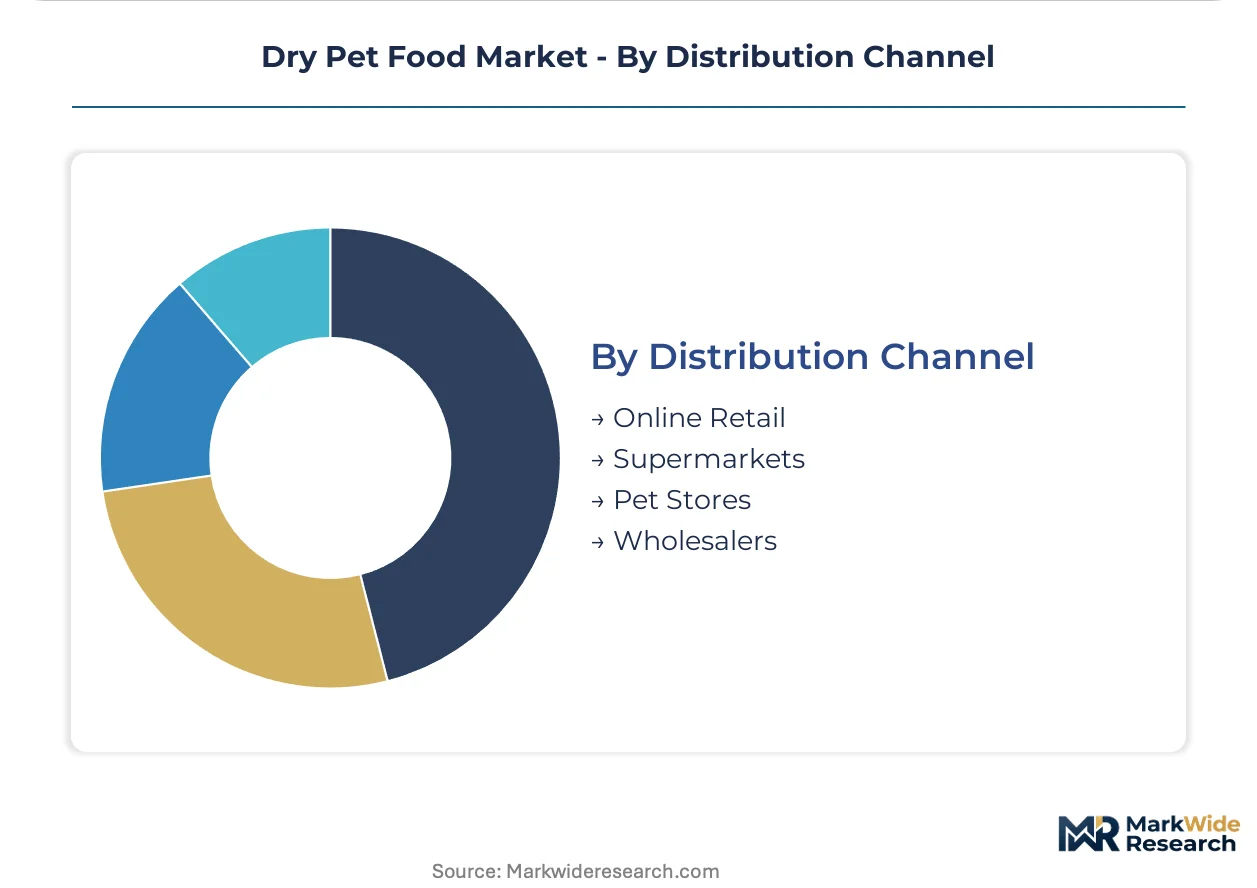
- Online Retail:Chewy and Amazon subscription models capture lifetime value through predictive replenishment algorithms. Same-day delivery infrastructure in United States metropolitan areas enables 4-week customized kibble cycles that bypass retail slotting fees.
- Pet Stores:Specialty retailers provide tactile brand experiences and staff consultation that convert first-time purchasers. Independent chains in Colorado and Washington state curate local and regional formulations that differentiate against mass-market alternatives.
- Supermarkets:Mass-market penetration depends on trade promotion spending and shelf-space negotiations with consolidated retail buyers.
- Wholesalers:Distributor networks serve rural veterinary clinics and independent pet retailers with consolidated logistics.
Online Retail leads growth trajectory. Pet Stores defend margin through experience differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States pioneered commercial pet food manufacturing in the 1950s, establishing extrusion technology standards that spread to European and Asian markets. Veterinary-endorsed prescription diets and premium grain-free formulations first scaled in American metropolitan corridors before diffusing internationally. Today's demand geography reflects this lineage, with formulation innovation and regulatory frameworks propagating from established Western markets toward emerging pet-keeping economies.
United States
Coastal metropolitan households in California and New York drive freeze-dried and subscription-format uptake as pet humanization reaches clinical-grade nutrition expectations. The FDA Center for Veterinary Medicine governs ingredient safety and novel protein approvals, creating 24-36 month evaluation windows that delay formulation launches. Kansas and Iowa host concentrated extrusion manufacturing clusters where high-capacity twin-screw equipment processes bulk commodity kibble for domestic distribution and export.
Germany
Discerning pet owners in Bavaria and North Rhine-Westphalia prioritize FEDIAF-compliant nutritional formulations with transparent supply chain documentation. The EU Green Deal's packaging waste directives mandate 70% recyclable content by 2030, accelerating metallized paper laminate trials among major brand owners. Hamburg anchors northern European distribution logistics, with regional manufacturers retrofitting production lines for cold-pressed extrusion technology that preserves heat-sensitive nutrients.
China
Urban middle-class households in Shanghai and Beijing are adopting premium dry formats as companion animal ownership restrictions ease in major municipalities. The National Medical Products Administration and Ministry of Agriculture and Rural Affairs jointly supervise imported pet food registration, requiring foreign manufacturers to establish domestic legal entities for market access. Shandong Province concentrates domestic manufacturing capacity, where local producers scale extrusion operations to serve both domestic demand and Southeast Asian export markets.
Brazil
São Paulo and Rio de Janeiro metropolitan areas sustain the bulk of South American premium dry pet food consumption as veterinary clinic networks expand prescription diet availability. ANVISA regulates product registration and labeling claims, with import dependency creating price volatility for specialized formulations. The São Paulo state industrial corridor hosts multinational manufacturing facilities that leverage Mercosur trade preferences to distribute throughout Latin America.
United Kingdom
London and Southeast England concentrate demand for natural and organic ingredient tiers as label-conscious owners scrutinize provenance claims. Post-Brexit regulatory divergence from EU FEDIAF guidelines has created dual compliance burdens for manufacturers serving both markets. The Midlands manufacturing belt retains extrusion capacity serving domestic retailers and Irish export channels, with regional players emphasizing British-sourced protein meals for differentiation.
Dry Pet Food Market Vendor Landscape
Premium-margin players sit above commodity-margin players across ingredient quality and channel access dimensions, with veterinary endorsement and subscription data capture creating divergent moat structures. The market exhibits consolidated leadership at the top tier alongside fragmented mid-tier competition. Three archetypes dominate: multinational CPG conglomerates leveraging veterinary clinic networks, pet-specialty pure-plays commanding shelf space through grain-free positioning, and private-label manufacturers serving mass-market retail price points. Capacity expansion and strategic portfolio diversification represent the dominant competitive moves, with players retrofitting extrusion lines for cold-pressed and freeze-dried formats.
Within the multinational CPG tier, Mars, Incorporated and Nestlé S.A. occupy positions that exemplify scale-driven manufacturing and broad protein-source formulation capabilities. Blue Buffalo Co., Ltd. represents the pet-specialty pure-play archetype, anchoring grain-free premium positioning within independent retail channels. These three entities collectively illustrate how divergent channel strategies—veterinary professional anchoring versus pet-specialty experience differentiation versus mass-market manufacturing scale—can coexist within expanding market value pools.
| Leading Market Players |
|---|
| Colgate-Palmolive Company |
| Hill's Pet Nutrition |
| Mars, Incorporated |
| Royal Canin SAS |
| Blue Buffalo Co., Ltd. |
| Nestlé S.A. |
| General Mills Inc. |
| Spectrum Brands Holdings Inc. |
| J.M. Smucker Company |
| Others |
Supply Flow & Price Mechanics
The EU Green Deal's packaging waste directives function as a dual gatekeeper, restricting qualified supply to manufacturers with recyclable mono-material capabilities while segmenting premium-tier pricing access around sustainability credentials. This environmental mandate reshapes procurement economics as barrier-coated paper alternatives command substantial cost premiums over conventional multi-layer laminates.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by ingredient quality tier and veterinary endorsement status. Price differentiation rests on named meat meal provenance and FSSC 22000 certification grade, with prescription diets capturing the least price-sensitive households through clinic network lock-in. Cost compression in commodity kibble is intensifying because animal protein input volatility compresses gross margins unpredictably. Mass-market retail buyers exhibit highest price sensitivity, while veterinary channel purchasers accept substantial premiums for clinical-grade formulations.
Supply Chain Analysis
FSSC 22000 and Safe Quality Food audits gate supplier participation, concentrating qualified ingredient sourcing among established manufacturers with dedicated quality infrastructure. Manufacturing capacity clusters in the United States, Germany, and China, with Kansas and Iowa anchoring North American extrusion operations. Raw material dependencies center on chicken meal, fish meal, and legume carbohydrate substitutes. Single-source vulnerability runs through the narrow German and Italian supplier base for high-capacity twin-screw extruders. Distribution runs through veterinary clinic networks, pet specialty retailers, and direct-to-subscription channels with divergent margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dry pet food market functions as a stable compounder, with pet humanization driving recurring revenue through subscription replenishment and veterinary prescription lock-in.
For Market Incumbents: To counter insect protein regulatory tailwinds from EFSA novel food approvals, anchor defensive positioning through backward integration into alternative protein fermentation capacity and accelerate cold-pressed extrusion retrofit programs. Certification investment in EU Green Deal-compliant packaging formats preserves shelf access as mono-material mandates tighten.
For New Entrants and Emerging Players: Direct-to-subscription channels offer the most penetrable entry vector, targeting coastal United States metropolitan areas where same-day delivery infrastructure enables 4-week customized kibble cycles. Freeze-dried toppers represent an underserved white-space segment with 3-4x kibble pricing headroom. A precision-formulation go-to-market angle, leveraging predictive replenishment algorithms, bypasses retail slotting fee barriers.
For Investors and Strategic Acquirers: Roll-up economics work for regional cold-pressed specialists because equipment modularity allows single facilities to toggle between kibble, baked, and air-dried formats, generating operational leverage across format proliferation. Mid-tier manufacturers with existing FSSC 22000 infrastructure and veterinary channel relationships present acquisition targets with defensive moat potential. EFSA novel protein approvals for black soldier fly larvae serve as the inflection signal to watch for alternative protein formulation viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Pressed Extrusion Retrofit | Preserves heat-sensitive amino acids that conventional high-temperature processing degrades, commanding pet specialty shelf premiums. |
| Direct-to-Subscription Channel Launch | Captures lifetime value data through Chewy and Amazon recurring delivery models in dense metropolitan corridors. |
| Insect Protein Formulation Development | Positions early movers for EFSA-approved black soldier fly larvae recipes with substantially lower land use profiles. |
| Recyclable Packaging Transition | Ensures EU market access under Green Deal mandates through metallized paper laminate and water-based barrier coating adoption. |
| Veterinary Clinic Network Expansion | Creates prescription diet switching costs that lock households into single-brand ecosystems with recurring purchase cycles. |
Methodological Framework
Bottom-up companion animal ownership modeling reconciled against top-down extrusion capacity tracking forms the analytical core of this study. Primary interviews with veterinary nutritionists, pet specialty retail category buyers, extrusion equipment engineers, and subscription platform operations managers combined with secondary validation from FDA Center for Veterinary Medicine filings, EU FEDIAF nutritional guideline publications, and Nielsen retail audit data. Trade customs records and SEC 10-K manufacturing disclosures provided supply-side triangulation against demand-side household penetration estimates.
Input-output matrices mapped protein source availability, packaging material cost structures, and channel economics across product type, ingredient quality tier, and distribution format segmentation dimensions. CAGRs were derived through iterative reconciliation of volume uptake trajectories with pricing elasticity assumptions. Forecast inputs incorporated pet humanization intensity indices and regulatory approval timelines for novel protein sources.
The model assumes a particular technology adoption path; alternative pathways for cell-cultured meat bioreactor convergence would alter the outlook through accelerated slaughter-free protein commercialization. Forecasts reflect assumptions around EFSA novel food approval pacing and EU packaging directive enforcement timelines. A model refresh is warranted upon material change in FDA ingredient evaluation windows or state-level extended producer responsibility law adoption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Pet Tick and Flea Prevention Market
Pet Care Products
Dog Food for Small Breeds Dogs Market
Pet Care Products
Gcc Pet Food Market
Pet Care Products
South Korea Dog Food Market
Pet Care Products
Europe Farrier Products Market
Pet Care Products
Cat Shampoo Market
Pet Care Products
UK Pet Treats Market
Pet Care Products
India Pet Food Market
Pet Care Products
Dog Crate Furniture Market
Pet Care Products
South America Dog Food Market
Pet Care Products
UAE Pet Food Market
Pet Care Products
Animal-Based Pet Protein Market
Pet Care Products
Saudi Arabia Dog Food Market
Pet Care Products
Kitten Milk Replacer and Formula Market
Pet Care Products
Thunder Jacket for Dogs Market
Pet Care Products
Dog Harness Market