
 Pet Furniture Market | 2026-2036
Pet Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Furniture Market Analysis
Specialty pet retail and direct-to-consumer digital storefronts is rewriting how pet furniture reaches households, bypassing traditional big-box intermediaries. Petmate leverages its manufacturing scale to dominate mass-market distribution across North American retail chains. Chewy, Inc. competes through subscription-driven replenishment and curated furniture assortments. Trixie Heimtierbedarf anchors European demand with design-forward, safety-certified product lines.
Pet furniture comprises purpose-built resting, climbing, and enrichment structures for domestic animals, typically constructed from engineered wood, woven sisal, high-density foam, and pet-safe textiles rated for scratch resistance and non-toxic off-gassing. These products serve to support animal orthopedic health, territorial behavior, and household integration within residential environments. Dog beds and cat trees lead volume, while eco-friendly and multi-functional feature segments capture expanding margin pools as sustainability premiums and space constraints reshape buyer priorities. Fabric and wood materials sustain the largest share, though adjustable and stylish feature variants are gaining fastest among urban apartment dwellers seeking aesthetic coherence with interior design.
The United States Consumer Product Safety Commission and state-level flammability regulators enforce textile safety standards that constrain foam and fabric sourcing for pet sofas and beds. The European Union REACH regulation and ECHA chemical restrictions limit certain adhesives and flame retardants, compelling reformulation of coated fabrics and pressed-wood substrates. Stakeholders must monitor evolving chemical disclosure requirements and circular economy mandates that will determine which material portfolios retain market access across major economies.
Market Dynamics
Multi-family residential developers now mandate pet amenity packages as lease differentiators, forcing furniture suppliers to reconfigure production lines for bulk modular systems rather than individual retail SKUs. This shift from consumer pull to institutional procurement is compressing margins while expanding volume throughput.
Growth Catalysts
- REACH chemical disclosure mandates:European ECHA enforcement is accelerating reformulation of adhesives and flame retardants, creating first-mover advantage for compliant suppliers in cross-border trade.
- Urban household densification:Compact living spaces in Chinese metropolitan clusters are generating demand for vertical, multi-functional cat furniture that integrates storage and climbing surfaces.
- Orthopedic foam certification standards:Veterinary endorsement protocols for pressure-relief dog beds are opening premium price tiers previously occupied by human mattress brands.
Market Restraints
- Sisal rope supply concentration:Brazilian sisal fiber harvest volatility constrains scratching post manufacturers dependent on single-origin natural materials.
- State-level flammability standard fragmentation:California TB 117-2013, New York State regulations, and emerging Massachusetts rules create compliance patchwork for upholstered pet sofas sold across US markets.
- Engineered wood tariff exposure:Import duties on Chinese-manufactured particleboard substrates inflate landed costs for price-sensitive mass-market cat trees.
Strategic Opportunities
- EU circular economy mandates:Extended producer responsibility frameworks for textile waste are incentivizing take-back programs and recyclable pet bed designs ahead of 2030 enforcement deadlines.
- Veterinary clinic channel expansion:Post-surgical recovery furniture represents an underdeveloped prescription-adjacent category with recurring replacement cycles.
- Smart home integration convergence:Embedded sensors for activity monitoring and climate control are merging pet furniture with connected home ecosystems.
Industry Challenges
- Certification timeline compression:Third-party safety testing for non-toxic off-gassing and structural load-bearing capacity extends new product introduction cycles by four to six months.
- Specialized upholstery skill scarcity:Industrial sewing technicians capable of handling pet-grade reinforced seams and concealed zipper systems command wage premiums that strain contract manufacturer margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Furniture Market |
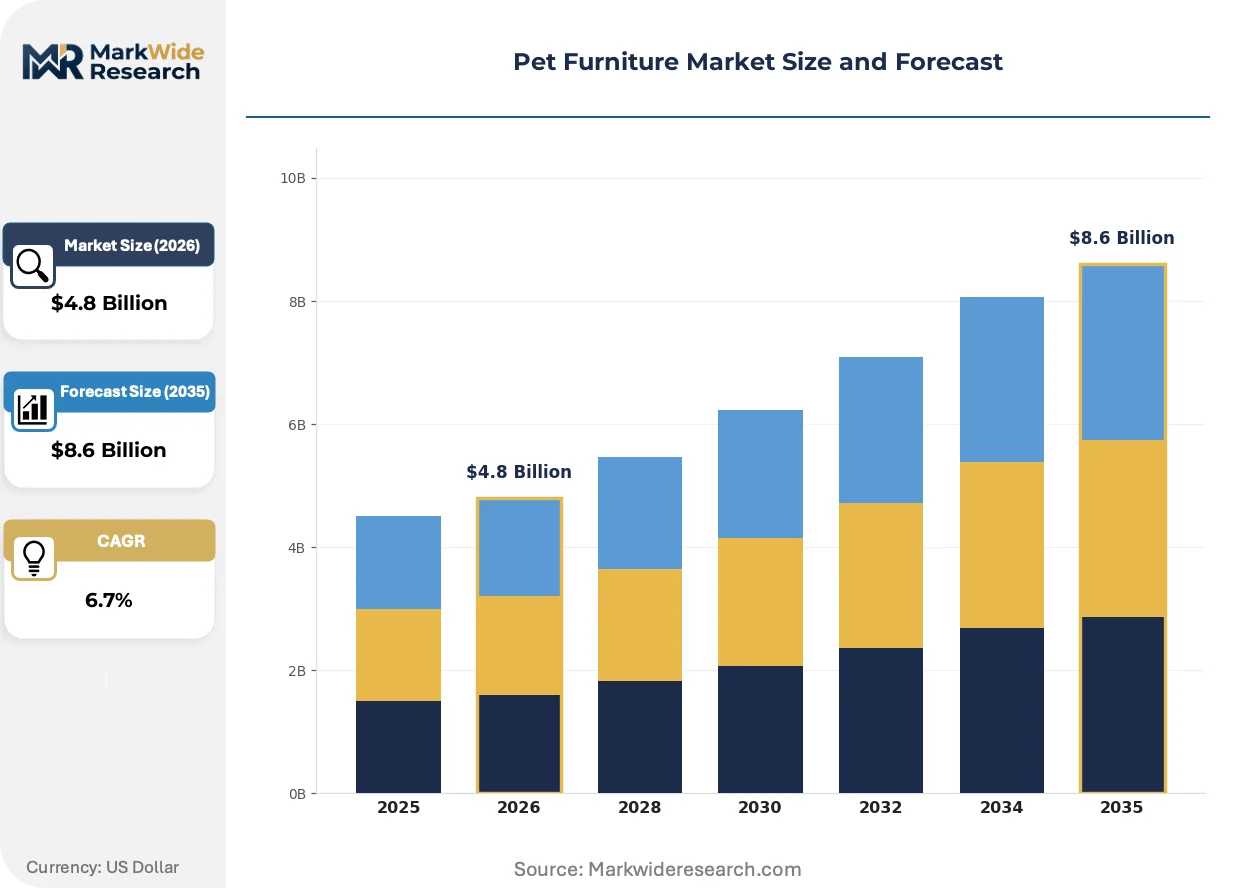
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cat Trees, Dog Beds, Pet Sofas, Scratching Posts Material: Wood, Fabric, Plastic, Metal Feature: Eco-Friendly, Multi-Functional, Stylish, Adjustable Customer Type: Pet Owners, Retailers, Online Shoppers, Distributors |
| Companies Covered | Petmate, Inter IKEA Group, Go Pet Club, PetPals Group, Inc., North American Pet Products, MidWest Homes for Pets, Chewy, Inc., Trixie Heimtierbedarf, Central Garden and Pet Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Furniture Market Emerging Trajectories
Material science breakthroughs and regulatory disclosure requirements are converging to redefine acceptable performance benchmarks across the pet furniture category. Suppliers must now validate sustainability claims with chain-of-custody documentation while maintaining price accessibility.
Biodegradable mycelium-based foam alternatives are collapsing the traditional petroleum-polyurethane supply chain for cushion cores. Premium dog bed manufacturers in Germany and the Netherlands are adopting mycelium substrates at pilot scale, compressing raw material lead times from twelve weeks to four while eliminating volatile organic compound emissions during production. This substitution is collapsing the cost barrier between eco-certified and conventional foam tiers.
REACH SVHC candidate list expansions are forcing systematic substitution of brominated flame retardants in coated fabrics destined for European markets. Upholstery suppliers must now maintain dual inventory streams—compliant and legacy formulations—or abandon EU market access entirely. Small-batch manufacturers without reformulation chemistry partnerships are exiting the segment rather than absorbing compliance costs.
Subscription-based replenishment models are displacing one-time retail purchases for consumable furniture components like replaceable scratching surfaces and washable bed covers. Chewy and specialized DTC platforms capture recurring revenue while locking in household brand loyalty. This shift is most pronounced among millennial pet owners in US coastal metropolitan areas who prioritize convenience over showroom browsing.
Pet Furniture Market Segmentation
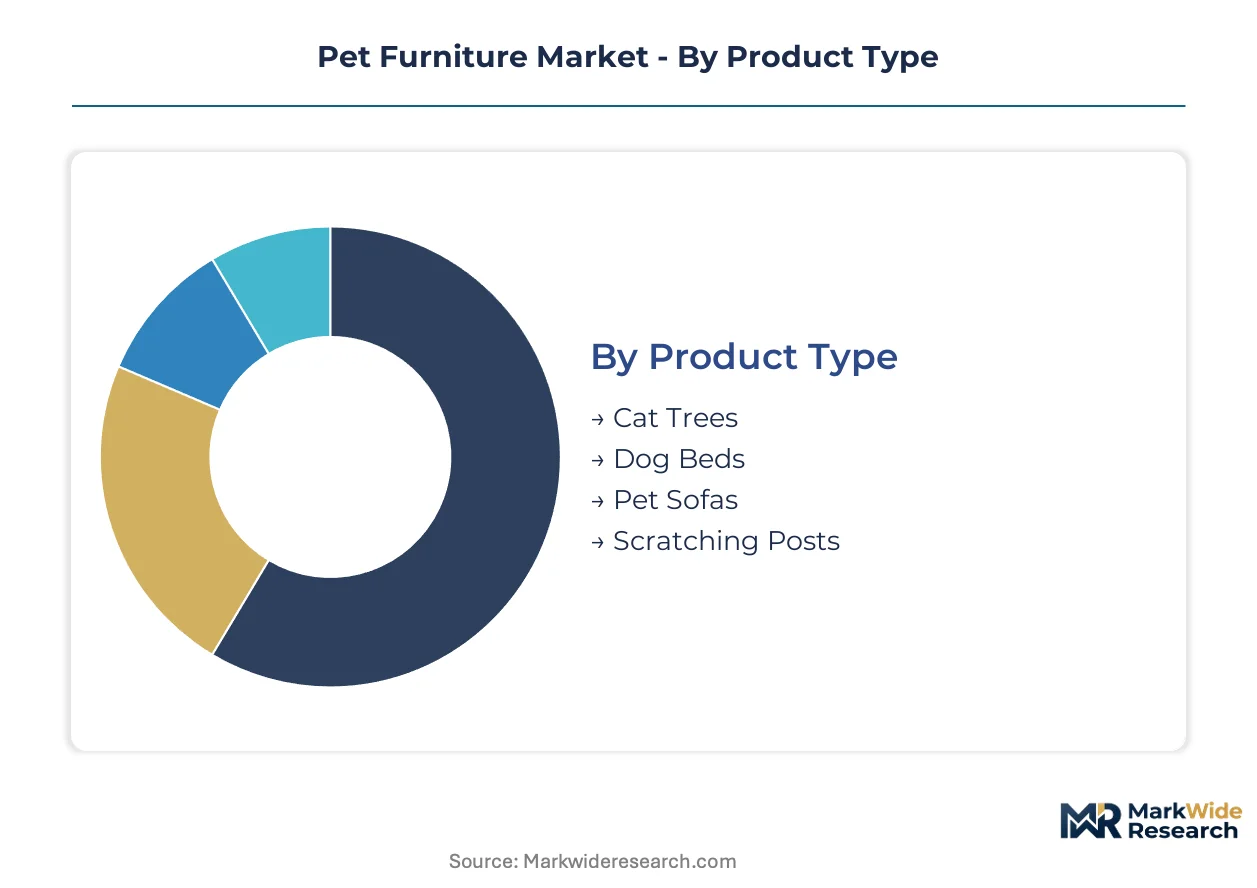
Pet furniture segmentation reflects divergent sourcing logic across consumer, institutional, and digital channels. Product architecture, material certification, and feature premiums each command distinct procurement workflows and margin structures that suppliers must navigate simultaneously.
Product Type:
Mature volume categories dominate procurement budgets while emerging formats reshape production line configurations.
- Dog Beds:Orthopedic foam cores with pressure-relief certification command premium placement in veterinary clinic channels. Urban Chinese households driving demand for compact, washable designs in tier-one metropolitan clusters.
- Cat Trees:Modular vertical systems with sisal-wrapped posts and engineered wood platforms anchor multi-family residential amenity packages. Bulk procurement from developers in Shanghai, Beijing, and Shenzhen compresses per-unit margins while locking in volume throughput.
- Pet Sofas:Upholstered resting furniture with reinforced seams and concealed zippers targets aesthetic-conscious millennial owners in US coastal cities.
- Scratching Posts:Single-function vertical and horizontal sisal surfaces serve as entry-price acquisition tools for first-time cat adopters.
Dog beds handle the majority of throughput; cat trees are expanding most quickly on share as institutional procurement scales.
Material:
Cost tier stratification separates certified sustainable inputs from commodity substrates.
- Fabric:Scratch-resistant textiles rated for non-toxic off-gassing per REACH SVHC mandates dominate European market access. German and Dutch manufacturers piloting mycelium-foam cores are collapsing lead times from twelve weeks to four while eliminating volatile organic compound emissions.
- Wood:Engineered particleboard and solid timber substrates face tariff exposure on Chinese imports into US markets. California TB 117-2013 and emerging Massachusetts flammability rules constrain adhesive selection for pressed-wood cat tree platforms.
- Plastic:Molded polymer bases and connectors serve mass-market price points with limited durability expectations.
- Metal:Powder-coated steel frames for elevated feeding stations and industrial-grade dog beds target commercial kennel and veterinary applications.
Fabric commands the widest margin spread; wood remains the volume anchor despite regulatory headwinds.
Feature:
Application-driven feature sets separate replacement-cycle purchases from durable goods investments.
- Eco-Friendly:Biodegradable mycelium foam, FSC-certified timber, and recycled textile fills capture sustainability premiums. EU circular economy mandates for extended producer responsibility are accelerating take-back program development ahead of 2030 deadlines.
- Multi-Functional:Vertical storage-integrated cat furniture and convertible dog bed-sofa hybrids address space constraints in compact urban apartments across Chinese metropolitan clusters.
- Stylish:Designer collaborations and interior design coherence specifications target millennial owners in US and European premium segments.
- Adjustable:Modular height and configuration systems extend product lifecycles across multiple pet life stages.
Multi-functional designs are gaining share fastest as urban household densification intensifies; eco-friendly certifications command the steepest price premiums.
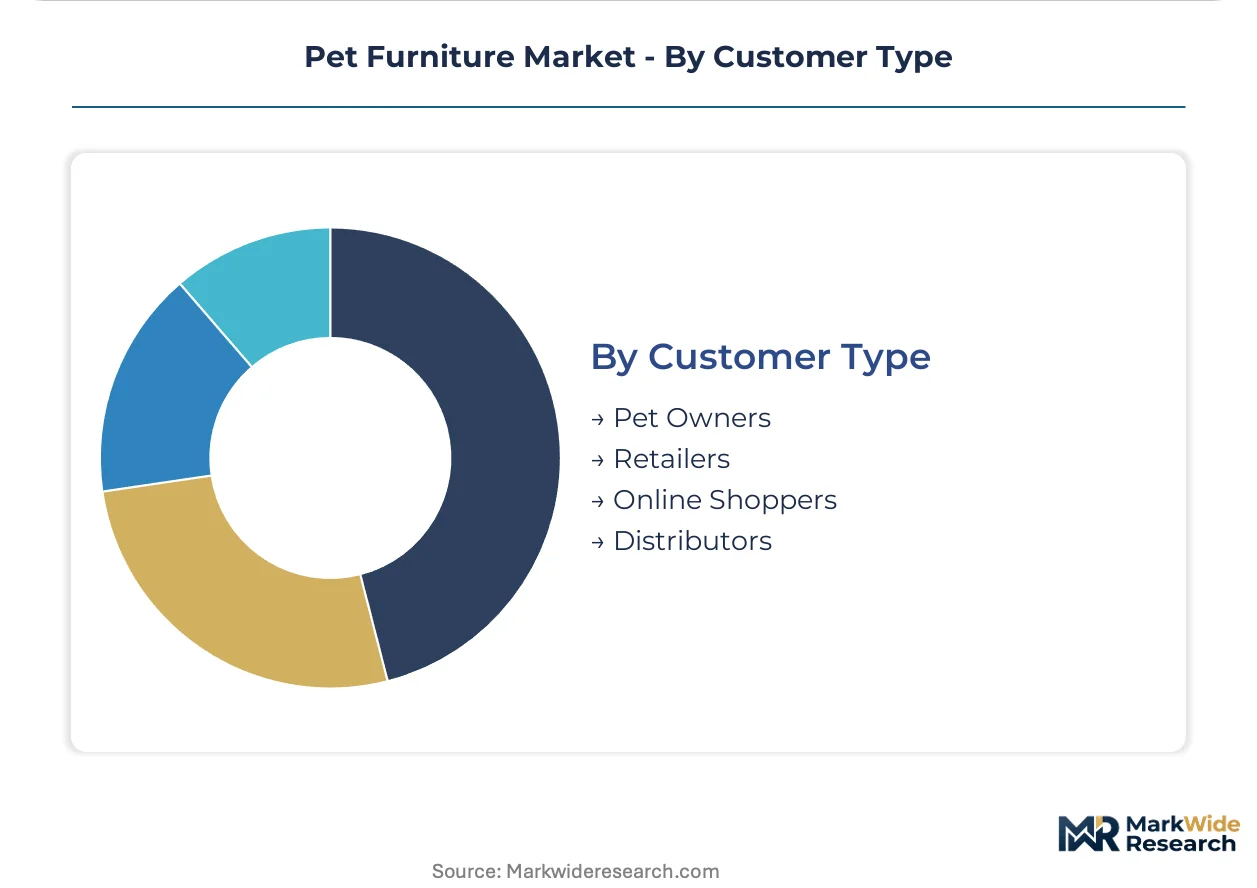
Customer Type:
Distribution channel concentration determines pricing architecture and inventory risk allocation.
- Pet Owners:Direct purchasers prioritize convenience and subscription replenishment for consumable components like replaceable scratching surfaces. Millennial cohorts in US coastal metropolitan areas favor curated digital storefronts over showroom browsing.
- Retailers:Specialty pet retail chains and big-box intermediaries negotiate volume commitments with tiered pricing structures across premium, standard, and economy assortments.
- Online Shoppers:Digital-native consumers drive subscription-based replenishment models for washable bed covers and modular replacement parts.
- Distributors:Institutional procurement agents for multi-family residential developers mandate bulk modular systems rather than individual retail SKUs.
Retailers move the bulk of physical volume; distributors are climbing the fastest as institutional procurement scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's integrated logistics corridor underwrites European pet furniture distribution into hinterland markets. Container throughput from Asian manufacturing clusters feeds regional fulfillment networks serving dense urban pet ownership zones.
United States
Multi-family residential developers in Austin, Denver, and Seattle now mandate pet amenity packages as lease differentiators. California TB 117-2013 and emerging Massachusetts flammability rules constrain adhesive selection for upholstered pet sofas. The Dallas-Fort Worth metroplex anchors bulk procurement consolidation for institutional developer accounts.
Germany
Veterinary endorsement protocols for orthopedic pressure-relief dog beds open premium price tiers previously occupied by human mattress brands. ECHA enforcement of REACH SVHC candidate list expansions forces systematic substitution of brominated flame retardants in coated fabrics. The North Rhine-Westphalia industrial corridor concentrates mycelium-foam pilot production for biodegradable cushion cores.
China
Compact living spaces in Shanghai, Beijing, and Shenzhen generate demand for vertical, multi-functional cat furniture integrating storage and climbing surfaces. GB standards on formaldehyde emissions from engineered wood substrates constrain pressed-wood cat tree manufacturing. The Yangtze River Delta manufacturing cluster dominates export-oriented production despite tariff exposure on particleboard substrates.
Netherlands
EU circular economy mandates for extended producer responsibility incentivize take-back programs and recyclable pet bed designs ahead of 2030 enforcement deadlines. Rotterdam's port infrastructure enables just-in-time raw material sourcing for mycelium-foam alternatives collapsing lead times from twelve weeks to four. The Randstad urban corridor concentrates design-forward, safety-certified product development for European market access.
United Kingdom
Millennial pet owners in London and Manchester favor curated digital storefronts over showroom browsing for subscription-based replenishment models. The UK government's evolving product safety standards post-EU exit create parallel compliance pathways for foam and fabric sourcing. The Midlands manufacturing belt retains specialized upholstery capacity for pet-grade reinforced seams and concealed zipper systems.
Pet Furniture Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in materials and modular sub-assemblies. The vendor base stratifies across three tiers: mass-market manufacturers with North American retail chain penetration, design-forward European specialists with safety-certified product lines, and digital-native platforms capturing subscription-driven replenishment revenue. Two dominant competitive moves reshape positioning: bulk modular system reconfiguration for institutional developer procurement, and backward integration into mycelium-foam substrate production to compress raw material lead times.
Within the mass-market manufacturing tier, Petmate exemplifies scale-driven distribution across retail chain networks. Trixie Heimtierbedarf occupies a position representing European design-forward, safety-certified specialization. Chewy, Inc. anchors the digital-native platform archetype through subscription-driven replenishment and curated furniture assortments.
| Leading Market Players |
|---|
| Petmate |
| Inter IKEA Group |
| Go Pet Club |
| PetPals Group, Inc. |
| North American Pet Products |
| MidWest Homes for Pets |
| Chewy, Inc. |
| Trixie Heimtierbedarf |
| Central Garden and Pet Co. |
| Others |
Supply Flow & Price Mechanics
The Port of Rotterdam's integrated logistics corridor compresses inbound freight costs for engineered wood substrates and mycelium-foam alternatives, enabling European manufacturers to sustain premium pricing tiers while mass-market producers in the Yangtze River Delta absorb tariff-inflated particleboard costs that compress margins on entry-level cat trees.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates veterinary-endorsed orthopedic dog beds with pressure-relief certification from modular cat trees sold in bulk to institutional developers and disposable scratching posts for first-time adopters. Price differentiation rests on REACH compliance status and volume procurement scale, with certified sustainable materials commanding substantial premiums. Cost compression in the mass-market tier is intensifying because engineered wood tariff exposure inflates landed costs for Chinese-manufactured substrates. Institutional distributors exhibit the lowest price sensitivity due to lease-differentiation budgets, while entry-level pet owners in tier-two Chinese cities remain highly price-conscious.
Supply Chain Analysis
Contract manufacturing concentration sits with Yangtze River Delta facilities for pressed-wood platforms, North Rhine-Westphalia pilot plants for mycelium-foam cores, and specialized upholstery workshops in the UK Midlands for reinforced seam construction. Raw material sourcing draws from Brazilian sisal fiber harvests, FSC-certified timber streams, and petroleum-polyurethane foam alternatives. Single-source vulnerability in sisal rope supply constrains scratching post production during harvest volatility periods. Distribution runs through Rotterdam's port infrastructure for European hinterland markets, Dallas-Fort Worth consolidation nodes for North American institutional accounts, and direct-to-consumer digital storefronts for subscription replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-driven replenishment platforms are consolidating household loyalty into recurring revenue ecosystems, with embedded sensor integration for activity monitoring creating interoperability lock-in that favors first movers with connected-home partnerships.
For Market Incumbents: Entrench bulk modular system capabilities through dedicated production lines serving multi-family residential developers, insulating against margin compression by capturing volume throughput commitments. Deepen captive supply of mycelium-foam substrates to compress raw material lead times and neutralize the cost barrier between eco-certified and conventional tiers. Certification investment in REACH SVHC compliance creates defensive moats as small-batch competitors exit rather than absorb reformulation chemistry costs.
For New Entrants and Emerging Players: Veterinary clinic channel penetration in post-surgical recovery furniture represents underdeveloped white-space with recurring replacement cycles and prescription-adjacent credibility. Tier-two Chinese metropolitan clusters offer penetrable geography for compact multi-functional designs addressing space constraints without competing against established Yangtze River Delta exporters. Go-to-market execution should prioritize digital-native subscription models with replaceable component replenishment to lock in millennial household loyalty.
For Investors and Strategic Acquirers: Design-forward European specialists with ECHA-compliant safety certifications and established Rotterdam distribution access represent priority acquisition archetypes as REACH enforcement accelerates competitive exits. Long-term viability over the next decade hinges on circular economy readiness for extended producer responsibility mandates. Monitor EU textile waste take-back program development as the inflection signal for material portfolio winners.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mycelium Substrates | North Rhine-Westphalia pilot production collapses lead times and eliminates volatile organic compound emissions. |
| Bulk Modular System Reconfiguration | Dedicated production lines for institutional developers lock in volume throughput despite compressed per-unit margins. |
| REACH SVHC Compliance Investment | ECHA-aligned reformulation partnerships secure cross-border market access as competitors exit. |
| Veterinary Clinic Channel Expansion | Post-surgical recovery furniture opens prescription-adjacent category with recurring replacement cycles. |
| Smart Home Integration Development | Embedded sensors for activity monitoring merge pet furniture with connected home ecosystems. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with multi-family residential developers, specialty pet retail category buyers, contract manufacturing plant managers, and veterinary clinic procurement coordinators. Secondary validation drew from ECHA chemical restriction databases, US state-level flammability regulatory filings, customs trade records for engineered wood substrates, and circular economy mandate documentation. Bottom-up volume estimates from SKU-level production data were triangulated against top-down macroeconomic indicators across the analysis window.
Calibration against historical volume trajectories and regulatory implementation timelines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, material certification tier, feature premium category, and distribution channel concentration. CAGRs were derived from regression analysis of correlated demand drivers including urban household densification indices and pet ownership penetration rates. Industry-specific forecast inputs incorporated REACH SVHC candidate list expansion schedules and EU extended producer responsibility enforcement milestones.
The forecast holds incumbent behavior within observed patterns; aggressive moves by digital-native subscription platforms or mycelium-foam substrate pioneers would shift outcomes beyond modeled ranges. Quarterly review of ECHA regulatory disclosure requirements, Brazilian sisal harvest yield reports, and multi-family residential development permit issuances is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Natural Pet Food Market
Pet Care Products
Cat Accessories Market
Pet Care Products
Asia Pacific Dog Food Market
Pet Care Products
Cat Bed Market
Pet Care Products
Pet Food Nutraceutical Market
Pet Care Products
North America Cat Food Market
Pet Care Products
Smart Cat Eye Market
Pet Care Products
Pet Odor Absorber Market
Pet Care Products
Parrot Cage Market
Pet Care Products
Dog Boot for Winters Market
Pet Care Products
Netherlands Pet Boarding Market
Pet Care Products
Bird Toy Market
Pet Care Products
Dehydrated Pet Food Market
Pet Care Products
Vegan Dog Food Market
Pet Care Products
GCC Dog Food Market
Pet Care Products
Pet Smart Tracker Market