
 Dog Bowl Market | 2026-2036
Dog Bowl Market Size, Share, and Industry Trends Forecast 2026-2036
Dog Bowl Market Analysis
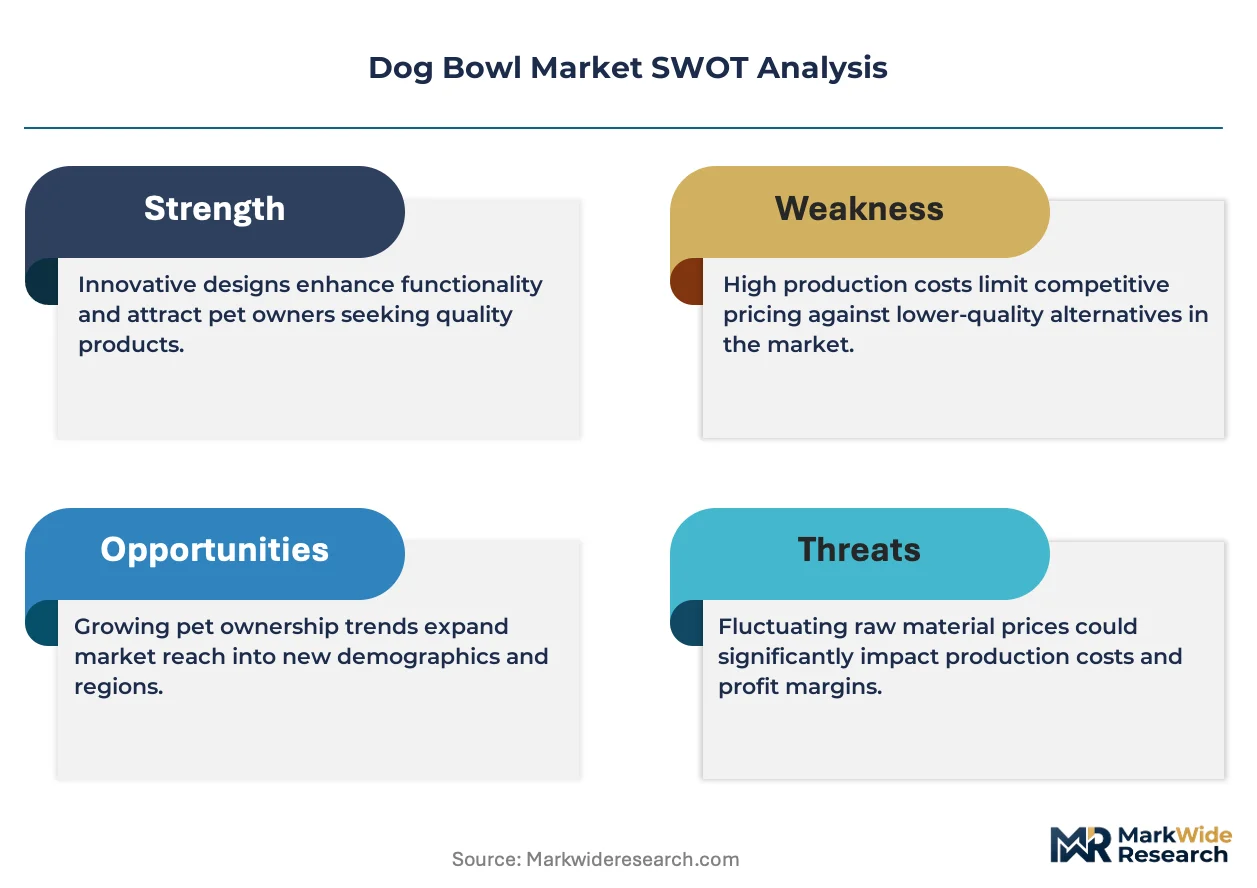
EU REACH restrictions on phthalates and heavy metals in food-contact articles is expanding compliance burdens for imported petware. Everich leverages in-house stainless steel forging to bypass third-party coating vendors. PetFusion sustains direct-to-consumer margins through proprietary elevated-frame designs. Neater Pet Brands anchors its position with splash-proof engineering patents.
A dog bowl is a purpose-built feeding vessel, typically fabricated from stamped stainless steel, injection-molded polypropylene, slip-cast ceramic, or borosilicate glass, with capacity ratings from 8 fluid ounces to 2 gallons and stability features including weighted bases or silicone gaskets. Its commercial function centers on hygienic food and water delivery for domestic canines across household, veterinary, and boarding environments. Stainless steel dominates volume due to corrosion resistance and dishwasher compatibility, while elevated and automatic feeder styles command margin premiums as veterinarians link joint health to feeding posture. Ceramic and glass segments occupy artisan and toxin-averse niches where buyer willingness-to-pay exceeds mass-market thresholds.
FDA food-contact notification requirements govern plastic resin selection for US-bound inventory, while California Proposition 65 drives labeling obligations for lead and cadmium in ceramic glazes. The EU F-Gas Regulation indirectly affects insulated bowl cooling systems, though its primary impact sits with refrigerated pet food logistics. China's GB standards for food-contact plastics create parallel testing regimes for OEM suppliers serving multiple export markets. Stakeholders must monitor diverging chemical compliance calendars across FDA, REACH, and GB frameworks to avoid port-of-entry detention and retailer delisting.
Market Dynamics
Veterinary-endorsed feeding posture guidelines are reshaping product development priorities across material categories, elevating joint-health engineering from niche premium to mass-market expectation.
Growth Catalysts
- Elevated Feeder Engineering:Veterinary orthopedic associations now link feeding posture to long-term joint health, creating pull-through demand for raised-platform designs in specialty retail channels.
- FDA Food-Contact Compliance:Tightened notification requirements for plastic resins are filtering out low-grade imported inventory, clearing shelf space for compliant domestic and premium offshore suppliers.
- Stainless Steel Forging:In-house metalworking capabilities bypass coating vendor dependencies, shortening lead times for corrosion-resistant product lines.
Market Restraints
- Raw Material Volatility:Nickel and chromium price swings in stainless steel feedstock compress margin predictability for volume producers.
- REACH Chemical Burdens:EU phthalate and heavy metal restrictions on food-contact articles impose parallel testing regimes that detain non-compliant shipments at Rotterdam and Hamburg.
- Ceramic Glaze Substitution Risk:Lead-free glass and uncoated metal alternatives capture toxin-averse buyers unwilling to verify third-party glaze certifications.
Strategic Opportunities
- Smart Feeder Convergence:Integration of portion-control sensors with mobile application interfaces opens subscription revenue streams in the connected pet hardware ecosystem.
- Veterinary Channel Direct:Clinic-endorsed dispensing creates pull-through for prescription-compatible feeding systems bypassing retail markup.
- India Urban Pet Ownership:Metropolitan household formation and nuclear family structures expand addressable demand for branded feeding accessories in Mumbai, Bangalore, and Delhi NCR.
Industry Challenges
- Multi-Jurisdiction Certification Lag:Simultaneous FDA, REACH, and GB standard compliance extends product launch timelines by 8-14 months for cross-border suppliers.
- Silicone Gasket Supply Concentration:Dependence on concentrated Southeast Asian molded-rubber specialists creates vulnerability to port congestion and customs inspection backlogs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dog Bowl Market |
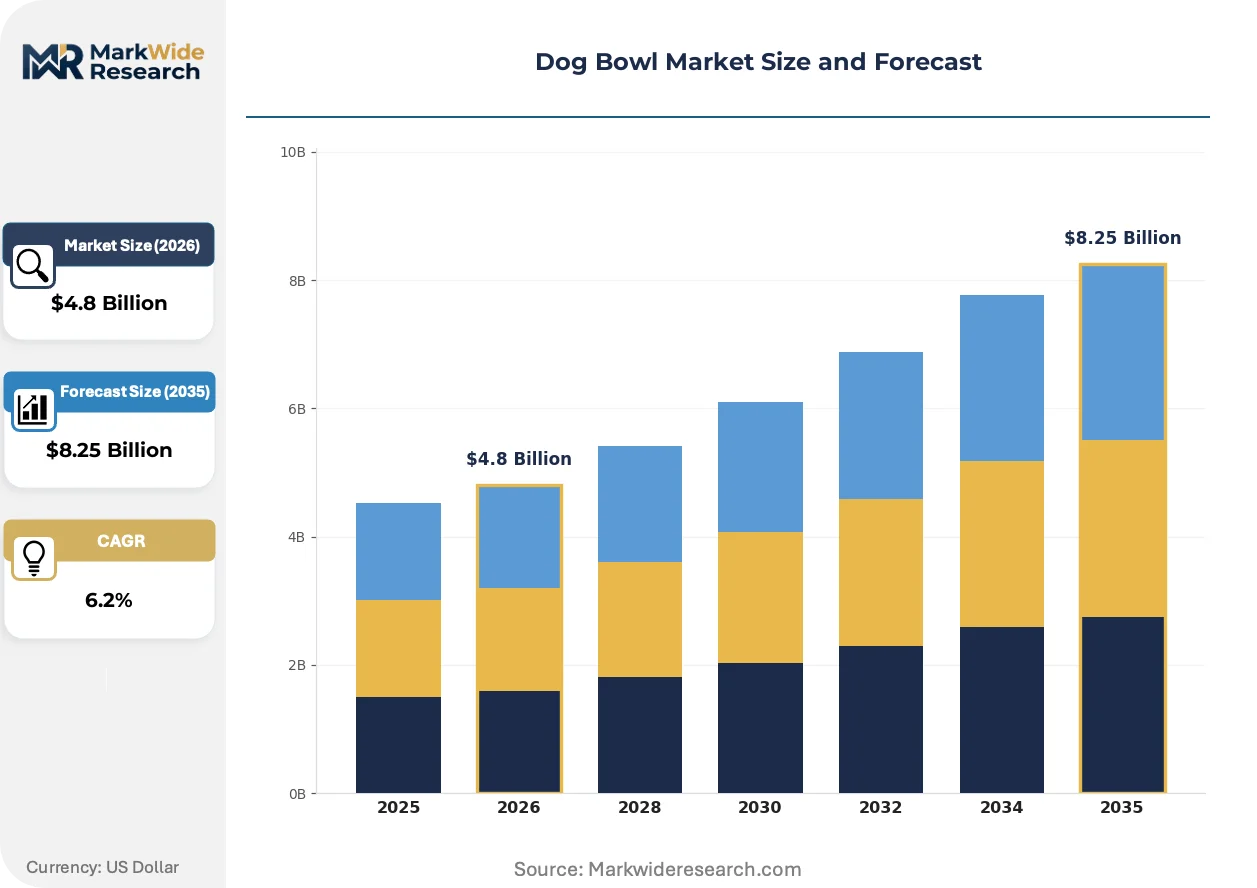
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.25 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Stainless Steel, Plastic, Ceramic, Glass Size: Small, Medium, Large, Extra Large Style: Elevated, Non-Slip, Travel, Standard Feature: Self-Watering, Automatic Feeder, Dishwasher Safe, Non-Tip |
| Companies Covered | Strobigo, Amazon Basics, Everich, Neater Pet Brands, PetFusion, Nicety, Sumplast, Basis Pet, KingStar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dog Bowl Market Emerging Trajectories
Product engineering is absorbing biometric monitoring capabilities while regulatory divergence forces parallel compliance investments. Distribution channels fragment between veterinary endorsement and direct-to-consumer subscription models.
Antimicrobial copper-ion infusion in stainless steel surfaces is absorbing veterinary clinic demand for reduced pathogen transmission in multi-patient boarding environments. High-volume kennel operators specify these alloys in procurement tenders, compressing price premiums for standard uncoated bowls. The technology is absorbing share from chemical disinfectant protocols by embedding hygiene directly into material substrate.
California Proposition 65 enforcement against ceramic lead content is forcing glaze reformulation across Mexican and Chinese export ceramics. Retailers now require third-party heavy metal testing documentation before shelf placement. Specialty pet chains in Los Angeles and San Francisco markets have delisted non-compliant artisan suppliers, redirecting volume toward verified stainless and borosilicate alternatives.
Subscription-based automatic feeder replenishment is consolidating buyer relationships around hardware-software bundles. Direct-to-consumer brands bypass retail slotting fees by capturing recurring kibble and bowl replacement revenue through mobile-integrated dispensers. This pattern concentrates in United States metropolitan markets where Amazon Prime penetration and veterinary telehealth adoption overlap.
Dog Bowl Market Segmentation
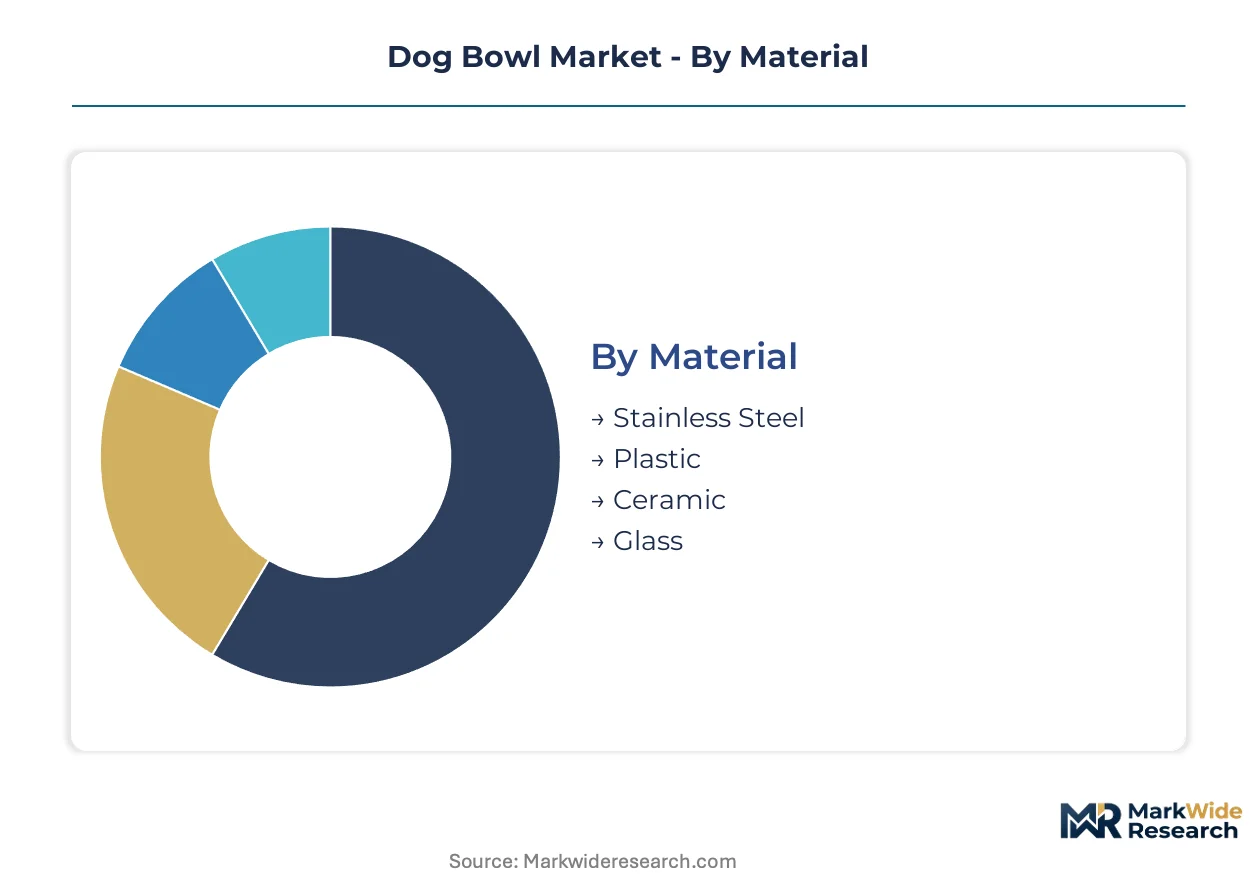
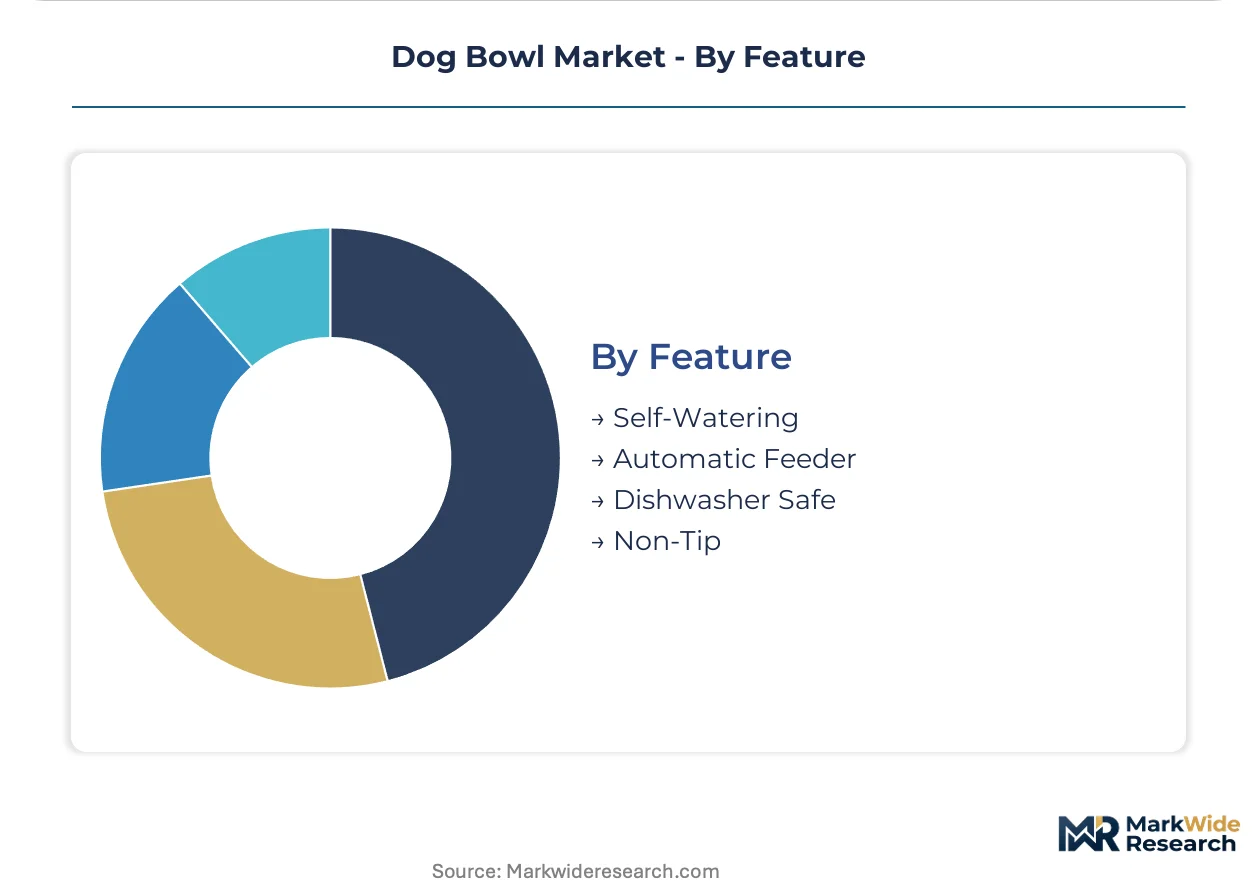
Segmentation in the dog bowl market determines compliance pathways, margin structures, and channel access. Material selection governs FDA notification and REACH testing burdens. Style and feature differentiation command veterinary endorsement premiums in specialty retail.
Material:
Certification requirements diverge sharply by substrate. Stainless steel faces ASTM corrosion testing and nickel release protocols under REACH. Plastic resins trigger FDA food-contact notification and California Proposition 65 labeling. Ceramic glazes demand third-party heavy metal verification. Glass compositions require borosilicate thermal shock certification.
- Stainless Steel:Forged 304 and 316 alloys deliver corrosion resistance and dishwasher compatibility. Demand concentrates in United States veterinary clinics and high-volume kennel operations where pathogen control protocols mandate non-porous surfaces. Nickel price volatility compresses margin predictability for volume producers.
- Plastic:Injection-molded polypropylene and copolyester formulations dominate mass-market retail through cost efficiency. FDA food-contact compliance filters out low-grade imported inventory, clearing shelf space for domestic and premium offshore suppliers with validated resin documentation.
- Ceramic:Slip-cast stoneware with lead-free glazes occupies artisan and toxin-averse niches. California Proposition 65 enforcement has delisted non-compliant Mexican and Chinese exports from Los Angeles and San Francisco specialty chains.
- Glass:Borosilicate compositions target buyers seeking chemical inertness without glaze verification burden. Limited volume due to breakage risk in multi-dog households and commercial boarding environments.
Leading the category by volume: Stainless Steel. Growing fastest: Plastic with FDA-validated resins.
Size:
Capacity specifications align with breed weight classes and feeding regimen requirements. Small-format bowls serve toy breeds and portion-controlled diets. Extra-large designs target working breeds and multi-dog households with elevated consumption profiles.
- Small:8-16 fluid ounce capacity for dogs under 15 pounds. Concentrates in urban apartment markets with space constraints and veterinary-prescribed restricted feeding protocols.
- Medium:24-32 fluid ounce standard for breeds 15-50 pounds. Anchors mass-market retail assortments with the broadest breed coverage and replacement cycle frequency.
- Large:48-64 fluid ounce for breeds 50-90 pounds. Demand correlates with large-breed puppy acquisition trends and veterinary joint-health feeding recommendations requiring elevated platforms.
- Extra Large:1-2 gallon capacity for giant breeds and multi-dog households. Limited SKU penetration due to storage footprint and shipping cost disadvantages in e-commerce channels.
Volume leadership sits with Medium. Steepest expansion trajectory: Large, driven by elevated feeder attachment rates for joint-health positioning.
Style:
Engineering differentiation determines price tier placement and channel access. Elevated designs capture veterinary endorsement premiums. Travel formats address mobility trends in remote work and pet-inclusive tourism.
- Elevated:Raised-platform designs with adjustable leg systems. Veterinary orthopedic associations link feeding posture to long-term joint health, creating pull-through demand in specialty retail and clinic dispensing channels.
- Non-Slip:Silicone gasket or weighted base configurations. Concentrates in hardwood and tile flooring households where spillage and bowl migration drive replacement purchases.
- Travel:Collapsible silicone or nesting stainless designs. Expands with remote work mobility and pet-inclusive travel accommodation growth in United States metropolitan corridors.
- Standard:Basic floor-level bowls without stability or elevation features. Dominates dollar-store and mass-market entry-price tiers with compressed margins and high inventory velocity.
Elevated commands the highest average selling price. Travel formats are gaining share fastest among style variants.
Feature:
Functional integration determines subscription revenue potential and smart hardware convergence. Automatic feeding systems capture recurring kibble revenue. Self-watering designs address multi-day absence scenarios in single-owner households.
- Self-Watering:Gravity-fed reservoir systems maintaining constant water level. Targets working households with extended absence periods and regions with intermittent water service reliability concerns.
- Automatic Feeder:Programmable portion control with mobile application integration. Direct-to-consumer brands bypass retail slotting fees through hardware-software bundle subscriptions in Amazon Prime penetration markets.
- Dishwasher Safe:Material and construction compatibility with commercial and residential sanitization cycles. Baseline expectation in stainless and premium plastic tiers, with ceramic glaze durability varying by firing temperature.
- Non-Tip:Wide-base geometry and weighted bottom configurations. Concentrates in enthusiastic eater profiles and outdoor feeding environments subject to wind and surface irregularity.
Dishwasher Safe represents the baseline volume leader. Automatic Feeder features are climbing the fastest as connected pet hardware ecosystems mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in Chinese forging clusters and Southeast Asian molding centers, while consumption tilts toward United States veterinary channels and European premium retail. This geographic split shapes compliance investments and distribution strategies differently across origin and destination markets.
United States
Veterinary clinic dispensing and Amazon Prime penetration drive replacement cycles for elevated and smart feeder designs. FDA food-contact notification requirements for plastic resins filter low-grade imports, clearing shelf space for compliant domestic suppliers. Los Angeles and San Francisco specialty chains have delisted non-compliant ceramic suppliers under California Proposition 65 enforcement.
China
Zhejiang and Guangdong provinces host stainless steel forging and injection molding clusters serving export markets. GB standards for food-contact plastics create parallel testing regimes alongside FDA and REACH requirements. Shenzhen and Ningbo export hubs face extended certification timelines as multi-jurisdiction compliance extends product launches.
Germany
EU REACH phthalate and heavy metal restrictions on food-contact articles detain non-compliant shipments at Rotterdam and Hamburg ports. Pet specialty retailers in Munich and Berlin expand premium bowl assortments as pet humanization deepens. ECHA enforcement drives substitution toward verified stainless steel and borosilicate alternatives.
United Kingdom
Post-Brexit divergence from EU chemical standards creates dual compliance burdens for imported petware. London and Manchester veterinary channels pull through elevated feeder demand linked to orthopedic association feeding posture guidelines. Retailers navigate separate UK REACH and retained EU regulation frameworks.
India
Metropolitan household formation in Mumbai, Bangalore, and Delhi NCR expands addressable demand for branded feeding accessories. BIS certification requirements for food-contact plastics remain less stringent than export markets, creating price-tier segmentation. Domestic molding specialists serve mass-market entry segments while premium imports capture toxin-averse urban buyers.
Dog Bowl Market Vendor Landscape
The competitive structure tilts toward material-specialist fabricators with in-house forging or molding capabilities. Stainless steel volume producers and injection-molded plastic specialists occupy distinct tiers, with elevated-engineering and smart-hardware entrants capturing margin premiums. Three archetypes dominate: integrated metalworkers, resin-validated molders, and connected-device platforms. Capacity expansion in Zhejiang forging clusters and strategic partnerships between hardware brands and veterinary clinic networks represent the dominant competitive moves.
Among stainless steel specialists, Everich and KingStar exemplify integrated forging capabilities that bypass third-party coating dependencies. PetFusion occupies a position within the elevated-design tier, while Neater Pet Brands anchors the splash-proof engineering segment. These fabricators represent how compliance investments and veterinary channel access separate premium positioning from mass-market commodity supply.
| Leading Market Players |
|---|
| Strobigo |
| Amazon Basics |
| Everich |
| Neater Pet Brands |
| PetFusion |
| Nicety |
| Sumplast |
| Basis Pet |
| KingStar |
| Others |
Supply Flow & Price Mechanics
Antimicrobial copper-ion infusion in stainless steel surfaces is compressing price premiums across veterinary clinic procurement tiers while simultaneously concentrating forging expertise in Zhejiang province clusters. This metallurgical transition simultaneously elevates material cost structures and locks in supply relationships with in-house alloy specialists capable of embedding hygiene directly into substrate.
Pricing Analysis
Margin tightening in mass-market plastic tiers reflects FDA food-contact notification compliance costs that filter out low-grade imported inventory. Three-tier pricing structure across premium, standard, and economy levels separates veterinary-endorsed elevated designs from commodity floor-level bowls, with certification grade and volume scale as primary differentiation drivers. Pricing pressure intensifies in ceramic segments as California Proposition 65 enforcement forces third-party heavy metal testing documentation. Mass-market retail buyers exhibit highest price sensitivity, while veterinary clinic dispensing channels tolerate premium positioning for joint-health engineering.
Supply Chain Analysis
Single-source vulnerability sits with concentrated Southeast Asian molded-rubber specialists supplying silicone gasket components for non-slip configurations. Manufacturing draws from Zhejiang and Guangdong provinces in China for stainless steel forging and injection molding, with secondary capacity in Vietnam for cost-sensitive plastic tiers. Raw material dependencies rest on nickel and chromium feedstock for corrosion-resistant alloys, polypropylene resins for mass-market formats, and borosilicate glass compositions for toxin-averse segments. Tariff exposure on Chinese-origin metalware creates inventory detention risk at Rotterdam and Hamburg ports. Distribution runs through Amazon Prime-enabled direct-to-consumer channels and veterinary clinic networks in United States metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive forging capabilities and resin validation documentation determine shelf access. Players are pursuing upstream control over alloy production and coating processes to bypass third-party vendor dependencies.
For Market Incumbents: Deploy in-house stainless steel forging investments to eliminate coating vendor lead time variability and capture veterinary clinic procurement tenders specifying pathogen-resistant substrates. Consolidate position by acquiring FDA-validated resin documentation portfolios from distressed offshore suppliers facing notification compliance failures. Smart feeder hardware-software bundles represent the primary substitution threat to passive bowl formats. For New Entrants and Emerging Players: Veterinary clinic dispensing networks offer the most penetrable channel architecture for prescription-compatible feeding systems bypassing retail slotting fees. Target metropolitan India household formation in Mumbai, Bangalore, and Delhi NCR where branded accessory penetration remains below saturation thresholds. Pursue direct-to-consumer subscription models with automatic feeder replenishment to capture recurring revenue streams in Amazon Prime penetration markets. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by pet specialty retailers seeking captive supply of elevated-engineering and splash-proof patented designs. Long-term viability hinges on compliance infrastructure capable of simultaneous FDA, REACH, and GB standard navigation without launch timeline extension. Monitor ECHA enforcement intensity against phthalate residues as inflection indicator for ceramic-to-metal substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Forging | In-house 304 and 316 alloy production eliminates third-party coating dependencies and shortens lead times for corrosion-resistant veterinary clinic specifications. |
| FDA Food-Contact Notification Investment | Validated resin documentation clears shelf space at specialty retailers filtering out non-compliant imported inventory under tightened notification requirements. |
| Veterinary Clinic Network Partnership | Direct dispensing channels bypass retail markup and capture pull-through demand linked to orthopedic association feeding posture guidelines. |
| Smart Feeder Hardware-Software Bundle Launch | Mobile-integrated automatic dispensers consolidate buyer relationships around subscription kibble replenishment in connected pet hardware ecosystems. |
| Antimicrobial Copper-Ion Alloy Certification | Veterinary clinic procurement tenders for reduced pathogen transmission embed hygiene directly into material substrate, displacing chemical disinfectant protocols. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs while primary interviews with veterinary procurement officers, pet specialty retail category managers, stainless steel forging plant supervisors, and FDA regulatory affairs consultants provided demand-side validation. Bottom-up triangulation across material-specific volume estimates and top-down reconciliation against aggregate pet accessory expenditure patterns ensured cross-verification. Secondary sources included FDA food-contact notification databases, ECHA REACH substance restriction updates, California Proposition 65 enforcement actions, and Chinese GB standard revision calendars.
Data-stream reconciliation across shipment manifests, production capacity surveys, and channel inventory audits informed the analytical framework. Segmentation dimensions modeled include material substrate, capacity tier, style engineering, feature integration, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand projections and replacement cycle frequency analysis across the projection horizon. Forecast inputs incorporated veterinary endorsement penetration rates, e-commerce pet supply adoption curves, and multi-jurisdiction compliance timeline extensions.
Caveats apply where nickel and chromium commodity volatility, port congestion at Southeast Asian rubber molding centers, or divergent chemical standard enforcement calendars could materially shift the outlook. Forecasts reflect documented assumptions regarding pet humanization trajectory and telehealth veterinary adoption patterns. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Vegan Dog Food Market
Pet Care Products
Pet Furniture Market
Pet Care Products
Europe Pet Clothing Market
Pet Care Products
Dog Carrier Bags Market
Pet Care Products
Pet Snacks and Treats Market
Pet Care Products
Pet Dental Health Market
Pet Care Products
Philippines Pet Food Market
Pet Care Products
Cat Diets Market
Pet Care Products
GCC Organic and Natural Pet Food Market
Pet Care Products
US Pet Treats Market
Pet Care Products
Outdoor Pet Backpack Market
Pet Care Products
Pet Rugs Market
Pet Care Products
Pet Oral Care Market
Pet Care Products
Vegan Pet Food Market
Pet Care Products
South Korea Pet Food Market
Pet Care Products
UK Dog Food Market